
 Smart Electric Heater Market | 2026-2036
Smart Electric Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Electric Heater Market Analytics
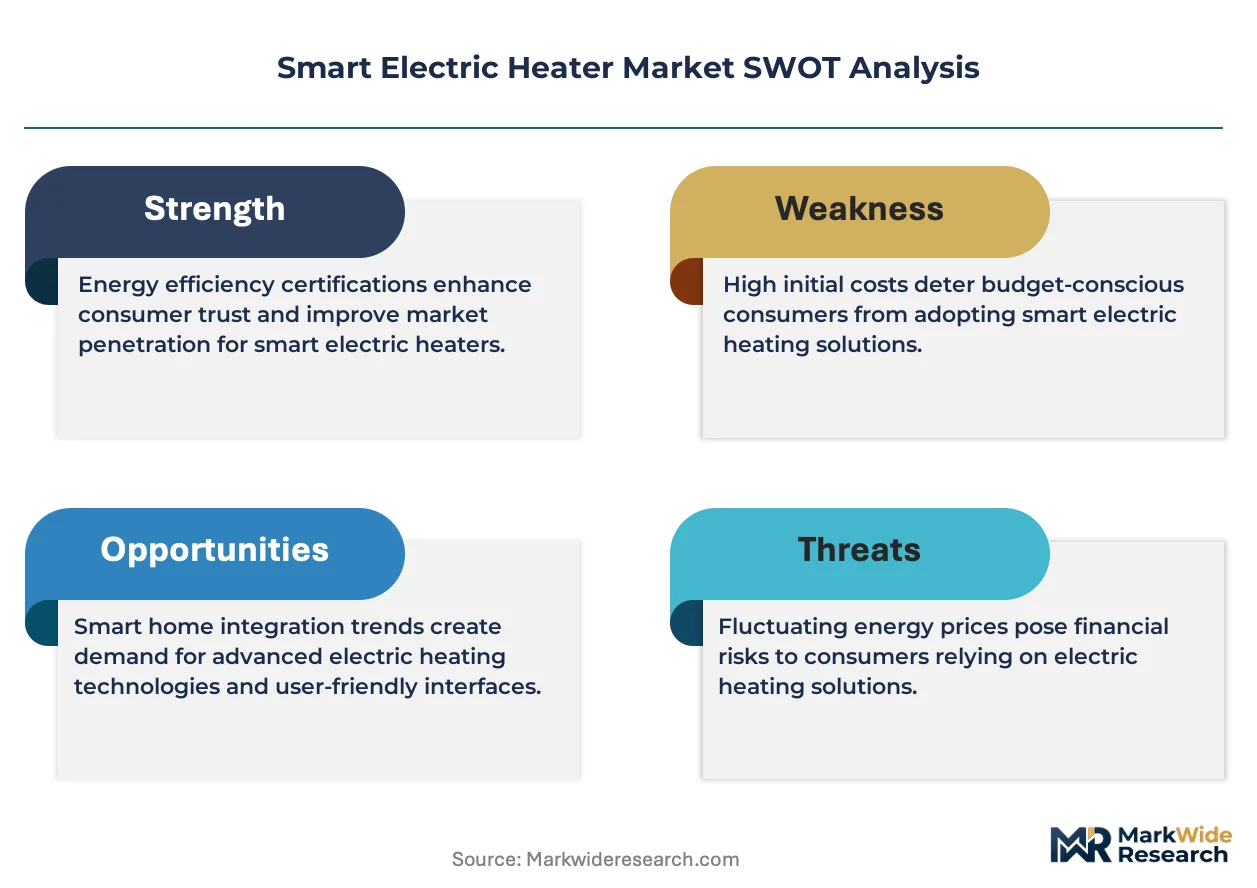
Subscription-based equipment leasing and energy-as-a-service models is tilting competitive dynamics toward capital-light entrants. Honeywell International Inc. leverages its building automation heritage to bundle smart heating with enterprise energy management platforms. Haier Electronics Group Co., Ltd. anchors its position through backward integration into compressor and sensor manufacturing. Dyson Ltd. differentiates via acoustic engineering and air-multiplier thermal distribution patents that command premium positioning.
A smart electric heater integrates resistive or infrared heating elements with embedded sensors, microprocessors, and wireless connectivity protocols to enable remote scheduling, occupancy-based climate control, and grid-responsive load modulation, typically operating at 1,500–4,000 watts with efficiency ratings governed by seasonal performance metrics. Infrared heaters lead product type margins due to targeted radiant delivery and lower thermal lag, while smart thermostats within the technology segment capture recurring software revenue streams through utility demand-response partnerships. Fan heaters compete on entry pricing but face margin compression as energy efficiency regulations tighten minimum performance thresholds.
The EU Green Deal and F-Gas Regulation drive phase-out of fossil-fuel heating in European buildings, while the U.S. EPA and state-level Public Utility Commissions shape electrification incentives and grid-interconnection standards for connected thermal loads. China's GB standards and dual carbon goals enforce efficiency tiers that filter import eligibility and domestic manufacturing compliance. Stakeholders must monitor evolving interoperability mandates between utility platforms and residential device ecosystems to secure long-term placement in utility-sponsored rebate programs.
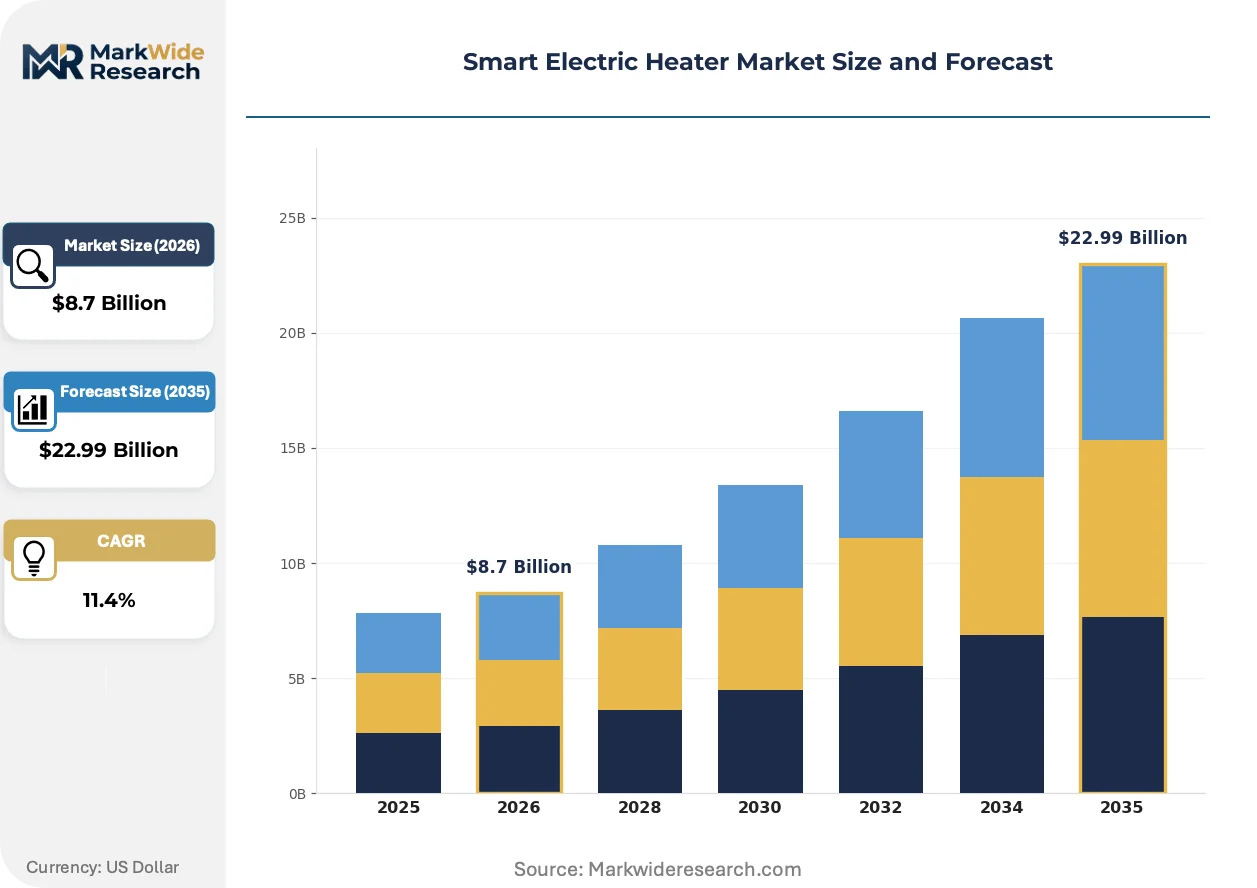
Market Dynamics
Electrification mandates under the EU Green Deal and parallel decarbonization frameworks are forcing wholesale replacement of fossil-fuel heating infrastructure, creating structural demand pull for connected thermal systems that can modulate load in response to grid signals.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants and combustion heating bans in new buildings across Germany, France, and the Netherlands is accelerating electric heat pump and smart heater retrofits.
- Residential smart home adoption:Homeowners integrating Alexa, Google Home, and Apple HomeKit ecosystems are demanding climate devices with open API connectivity and occupancy-based automation.
- Silicon carbide power electronics:Wider bandgap semiconductors are enabling more compact inverter designs that improve part-load efficiency in variable-output heating elements.
Market Restraints
- Copper and rare earth magnet costs:Volatility in Chilean copper concentrate and Chinese neodymium processing is compressing margins on motor-driven fan heaters and heat pump compressors.
- Grid interconnection standards fragmentation:Incompatible utility demand-response protocols between ISO New England, CAISO, and European TSOs force redundant hardware certification cycles.
- Natural gas price arbitrage:Persistent differentials in US Henry Hub versus European TTF pricing slow electrification economics in shale-rich North American markets.
Strategic Opportunities
- India building energy code enforcement:State-level adoption of ECBC-R standards in Maharashtra and Gujarat creates first-mover positioning for connected heating in high-rise residential construction.
- Heat-as-a-service contracting:Energy retailers in Denmark and Sweden are bundling equipment installation, maintenance, and electricity supply into fixed monthly tariffs.
- AI-driven predictive maintenance:Machine learning models trained on thermal sensor telemetry are enabling proactive element replacement before failure, opening recurring software revenue streams.
Industry Challenges
- Cybersecurity certification delays:ETSI EN 303 645 compliance for IoT devices and IEC 62443 industrial security standards are extending product launch timelines by 6-12 months.
- Legacy HVAC installer training gaps:The transition from bimetallic thermostat wiring to low-voltage digital bus architectures requires reskilling of contractor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Electric Heater Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Heaters, Convection Heaters, Radiant Heaters, Fan Heaters Application: Residential Use, Commercial Use, Industrial Use, Outdoor Heating Technology: Wi-Fi Enabled, Smart Thermostats, Voice Control, Mobile App Integration Energy Efficiency: High Efficiency, Medium Efficiency, Low Efficiency, Smart Regulation |
| Companies Covered | Honeywell International Inc., Zehnder Group, Haier Electronics Group Co., Ltd., Mitsubishi Electric Corporation, DAIKIN INDUSTRIES Ltd., Dyson Ltd., Siemens AG, De’Longhi Appliances S.r.l., LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Electric Heater Market Evolving Landscape
Product architecture is converging around edge-computing thermal controllers that process occupancy and weather data locally while maintaining cloud connectivity for utility demand-response programs. This shift is compressing the traditional separation between HVAC hardware and building management software layers.
Far-infrared carbon crystal heating elements are hybridizing with conventional resistive wire designs to combine rapid radiant response with convective air distribution. Residential developers in Nordic markets are specifying these dual-mode units for passive house projects where thermal lag minimization is critical. The technology is hybridizing product categories that previously required separate ceiling panels and floor-mounted convection units.
The EU Green Deal's Renovation Wave strategy and EPBD recast are mandating smart readiness indicators for all new heating installations in member states. Equipment manufacturers must embed interoperable communication interfaces to qualify for national subsidy programs in Germany, France, and Italy. The regulation is compressing time-to-market for proprietary control ecosystems that cannot demonstrate open protocol compliance.
Buyers in multi-family housing are consolidating vendor relationships through master service agreements with property management platforms rather than individual unit purchases. Greystar, AvalonBay, and comparable institutional landlords are specifying fleet-wide heating standardization to simplify maintenance logistics. The pattern is most visible in US Sun Belt markets where build-to-rent construction volume exceeds traditional for-sale development.
Smart Electric Heater Market Segmentation
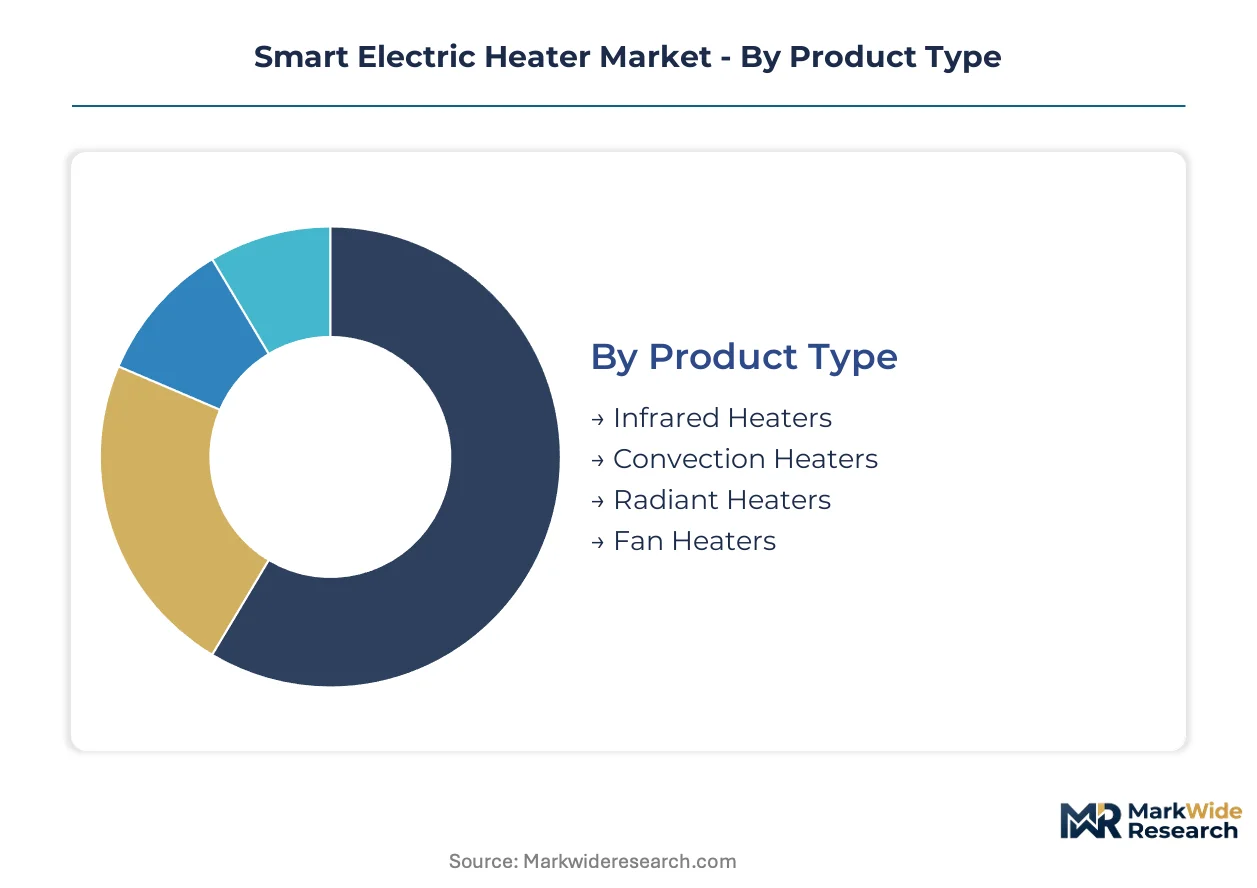
Segmentation in the smart electric heater market reveals divergent service intensity requirements across product architectures. Infrared and radiant systems demand minimal field maintenance, while connected fan heaters and smart thermostat ecosystems generate recurring software support obligations that reshape vendor profitability models.
Product Type:
After-sales service intensity varies dramatically across heating element architectures, with connected convection systems requiring firmware update cycles and sensor calibration that infrared panels simply do not.
- Infrared Heaters:Carbon crystal and quartz tube elements deliver targeted radiant heat without convective air movement. Passive house developers in Germany and Austria specify these units for thermal lag minimization in deep renovation projects where wall-mounted installation reduces floor space consumption.
- Convection Heaters:Oil-filled or ceramic core systems with integrated fans distribute heated air through room volumes. Apartment operators in Denmark favor these for whole-unit coverage in build-to-rent portfolios where centralized fleet management justifies higher capital outlay.
- Radiant Heaters:Metal-sheath or quartz elements provide directional warmth for spot heating applications. Warehouses in northern China deploy these for workstation-level comfort without building-wide HVAC retrofit costs.
- Fan Heaters:Compact resistive elements with forced-air delivery dominate entry-price positioning. Retail channels in India move high volumes of these units despite margin compression from copper motor cost volatility.
Infrared heaters hold the largest share; momentum sits with convection systems as property management platforms consolidate around whole-room climate control.
Application:
Cost tier stratification separates residential subscription models from industrial capital expenditure cycles, with commercial landlords occupying a hybrid procurement position.
- Residential Use:Single-family homeowners and apartment dwellers prioritize smartphone integration and utility demand-response compatibility. Swedish energy retailers bundle these installations with fixed monthly heat-as-a-service tariffs that transfer ownership risk from occupant to supplier.
- Commercial Use:Office buildings and retail spaces require zonal control with building management system integration. French commercial property mandates under the EU Green Deal's smart readiness indicators drive replacement cycles in Paris and Lyon office stock.
- Industrial Use:Manufacturing facilities and logistics centers demand ruggedized housings with extended duty cycles. German automotive suppliers specify these for production line comfort heating where downtime tolerance approaches zero.
- Outdoor Heating:Hospitality terraces and event venues require weather-resistant enclosures with rapid startup response. Italian restaurant operators in Milan and Rome deploy these to extend outdoor dining seasons through regulatory restrictions on fossil-fuel patio heaters.
Residential applications dominate volume; commercial use is climbing fastest as institutional landlords standardize fleet-wide heating specifications.
Technology:
Customer type fragmentation splits between utility-integrated demand-response participants and standalone smart home enthusiasts with divergent interoperability requirements.
- Wi-Fi Enabled:Direct cloud connectivity without hub dependencies appeals to retrofit markets. US consumers in Texas and California favor these for rapid installation without electrician involvement.
- Smart Thermostats:Dedicated climate controllers with learning algorithms and occupancy sensing generate recurring software revenue through utility partnership programs. These systems capture the steepest expansion trajectory as grid operators seek dispatchable thermal loads.
- Voice Control:Native Alexa, Google Assistant, or Siri integration targets smart home ecosystem adherents. Younger demographics in UK urban centers treat voice activation as a baseline purchase criterion.
- Mobile App Integration:Proprietary or open-API smartphone interfaces enable remote scheduling and geofencing. Japanese consumers prioritize these features for energy-conscious commuting patterns.
Smart thermostats command premium positioning; Wi-Fi enabled units gain share fastest through retail channel accessibility.
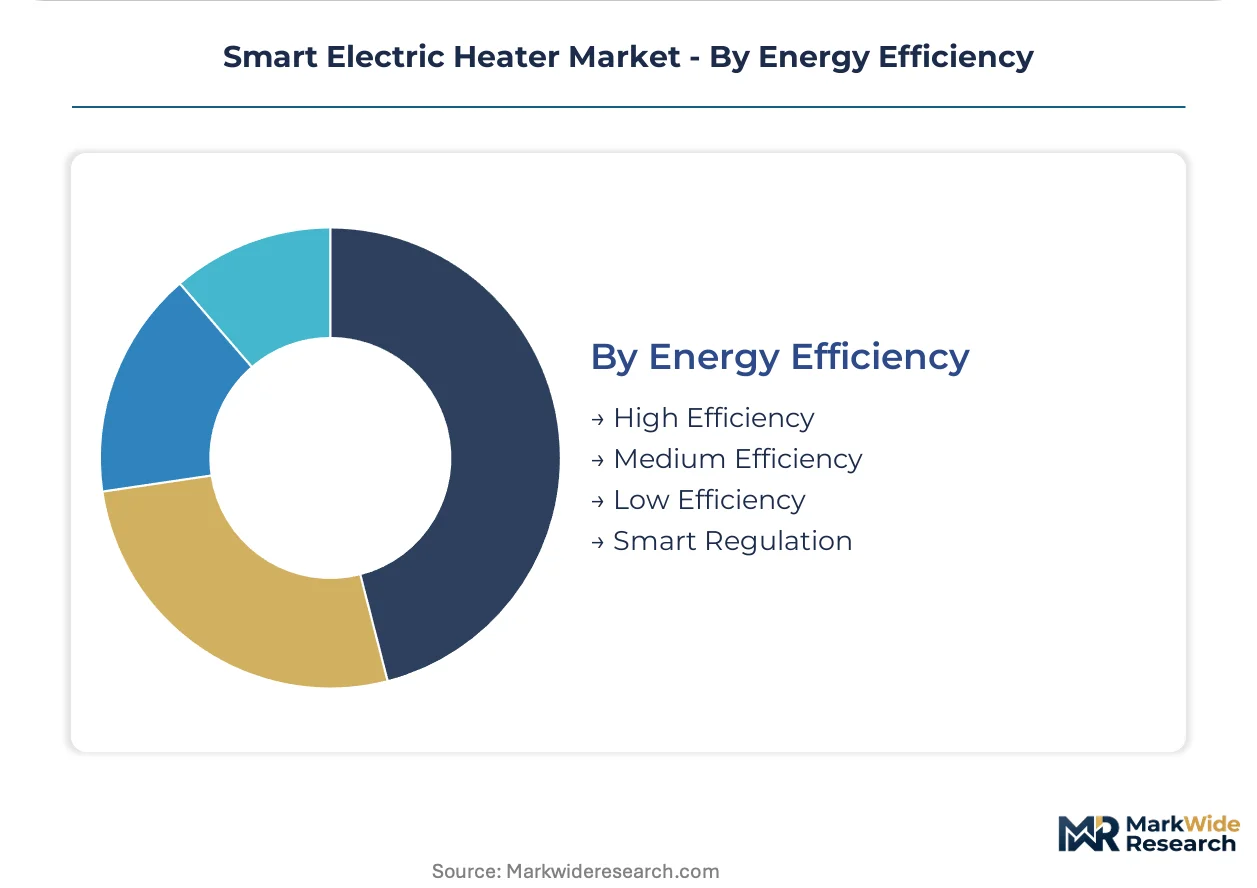
Energy Efficiency:
Regulatory tier enforcement under EU Ecodesign and comparable frameworks creates mandatory segmentation that overrides consumer preference in covered jurisdictions.
- High Efficiency:Seasonal performance coefficients exceeding baseline thresholds qualify for national subsidy programs. These products dominate new construction specifications in the Netherlands where building codes mandate maximum thermal energy intensity.
- Medium Efficiency:Mid-tier performance meets minimum regulatory requirements without premium component costs. These units fill replacement demand in existing building stock where full electrification economics remain marginal.
- Low Efficiency:Basic resistive heating without modulation or connectivity occupies declining market position. Regulatory phase-out timelines in France and Germany compress remaining commercial viability to price-sensitive emergency replacement scenarios.
- Smart Regulation:Dynamic load modulation responding to real-time pricing or grid signals optimizes operational cost without hardware efficiency gains. Danish district heating integration and German virtual power plant participation drive specialized demand for this capability tier.
High efficiency products hold the largest share; smart regulation capabilities are expanding most quickly as grid interconnection standards mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing in Germany and the Netherlands sits roughly 40% above entry-level products in India, creating arbitrage opportunities for manufacturers with modular platform architectures. This asymmetry reflects divergent regulatory enforcement and subsidy availability rather than raw material cost differentials.
Germany
The EU Green Deal's building renovation wave and F-Gas Regulation phase-out drive wholesale replacement of fossil-fuel heating in residential stock. KBA and federal building codes under the EPBD recast mandate smart readiness indicators for all new installations. Bavaria and North Rhine-Westphalia concentrate demand through deep renovation clusters in Munich and Cologne metropolitan areas.
United States
State-level Public Utility Commissions in California and Texas shape electrification incentives and grid-interconnection standards for connected thermal loads. The EPA's evolving appliance efficiency standards and IRA tax credits accelerate uptake in new construction. Sun Belt build-to-rent markets in Phoenix and Dallas standardize fleet-wide heating specifications for institutional landlords.
China
GB standards and dual carbon goals enforce efficiency tiers that filter import eligibility and domestic manufacturing compliance. MIIT's smart home integration mandates accelerate connected device penetration in high-rise residential construction. Yangtze River Delta manufacturing clusters around Shanghai supply carbon crystal heating elements for both domestic and export markets.
India
State-level adoption of ECBC-R building energy codes in Maharashtra and Gujarat creates first-mover positioning for connected heating in high-rise residential construction. BIS efficiency labeling and PLI scheme incentives for domestic manufacturing reshape procurement patterns. Mumbai and Ahmedabad metropolitan areas concentrate early deployment through green building certification requirements.
Sweden
Heat-as-a-service contracting models bundle equipment installation, maintenance, and electricity supply into fixed monthly tariffs for residential subscribers. The country's national energy regulator oversees demand-response integration with district heating networks. Stockholm and Gothenburg urban cores lead deployment through municipal building retrofit programs.
Smart Electric Heater Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in heating elements and sensor modules. The vendor base clusters around three strategic archetypes: diversified conglomerates with building automation heritage, pure-play climate equipment manufacturers, and consumer electronics brands leveraging acoustic or air-handling engineering. Competitive moves concentrate on backward integration into compressor and sensor manufacturing, plus strategic partnerships with utility demand-response platforms.
Among diversified technology conglomerates, Honeywell International Inc., Siemens AG, and Mitsubishi Electric Corporation exemplify platform integrators that bundle smart heating with enterprise energy management and building automation ecosystems. These players occupy positions where software recurring revenue and utility partnership programs offset hardware margin compression. Their geographic footprints span multiple regulatory jurisdictions, requiring compliance with ETSI EN 303 645, IEC 62443, and divergent grid interconnection standards simultaneously.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Zehnder Group |
| Haier Electronics Group Co., Ltd. |
| Mitsubishi Electric Corporation |
| DAIKIN INDUSTRIES Ltd. |
| Dyson Ltd. |
| Siemens AG |
| De’Longhi Appliances S.r.l. |
| LG Electronics |
| Others |
Value Network & Pricing Analysis
Copper concentrate volatility from Chilean mining disruptions and Chinese neodymium processing bottlenecks compress margins simultaneously across motor-driven fan heaters and infrared element assemblies, forcing three-tier pricing stratification across premium smart-thermostat bundles, standard Wi-Fi-enabled units, and entry-level resistive models while reshaping supplier geography toward Yangtze River Delta manufacturing clusters.
Pricing Analysis
Industrial OEM buyers anchor pricing stratification across premium, standard, and economy tiers. Certification under IEC 62443 cybersecurity standards and ETSI EN 303 645 IoT compliance commands substantial premiums over uncertified alternatives. Cost compression in entry-level fan heaters intensifies because copper motor windings face sustained commodity pressure. Residential retrofit consumers in Germany and Sweden exhibit lowest price sensitivity due to heat-as-a-service subscription bundling, while Indian retail channel buyers prioritize unit acquisition cost above efficiency ratings.
Supply Chain Analysis
Carbon crystal heating elements and silicon carbide power semiconductors draw from concentrated manufacturing bases in China, Germany, and Japan. Rare earth magnet supply for high-efficiency fan motors rests on Chinese neodymium processing and Malaysian separation facilities. Single-source vulnerability in advanced ceramic substrates for infrared emitters threatens production continuity for European OEMs. Distribution runs through building automation integrators in commercial segments and big-box retail chains in residential markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through institutional landlord fleet-standardization agreements at Greystar and AvalonBay, compressing vendor count per property management platform and tilting procurement toward master service contracting.
For Market Incumbents: Harden software recurring revenue streams through utility demand-response platform certification before hardware margin compression accelerates. Deepen backward integration into sensor module production to offset Chinese component tariff exposure. Lock in installer network training partnerships now, as legacy HVAC contractor reskilling gaps widen competitive moats for early movers. For New Entrants and Emerging Players: Mid-market commercial buildings in India's Maharashtra and Gujarat state clusters represent the most penetrable entry point before ECBC-R code enforcement matures. Heat-as-a-service contracting white space in Nordic markets offers SaaS-margin structures unavailable in transactional hardware sales. Pursue white-label partnerships with energy retailers rather than direct consumer brand building. For Investors and Strategic Acquirers: Specialist firms with captive carbon crystal element production and embedded AI thermal control firmware present the strongest acquisition target profile. Long-term viability hinges on regulatory interoperability certification depth rather than unit volume scale. Watch for German KBA smart-readiness indicator enforcement acceleration as the inflection signal for premium-tier demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of occupancy detection modules secures margin control against Taiwanese component suppliers. |
| Utility Demand-Response Platform Certification | Qualification for California CAISO and Germany virtual power plant programs unlocks recurring software revenue. |
| AI-Driven Predictive Maintenance Launch | Machine learning on thermal telemetry enables proactive element replacement before failure. |
| Heat-as-a-Service Contracting Model | Danish and Swedish energy retailers bundle installation, maintenance, and electricity into fixed tariffs. |
| Open-API Ecosystem Integration | Native Alexa, Google Home, and Apple HomeKit connectivity meets residential smart home ecosystem demands. |
Research Methodology
Initial hypotheses were tested against primary input from HVAC contractor network heads, utility demand-response program managers, smart home platform engineers, and residential property management procurement leads, and refined through secondary validation against SEC filings from building automation conglomerates, EIA residential energy consumption surveys, EU Ecodesign directive implementation reports, and IEA building electrification roadmaps. Bottom-up unit shipment estimates by product architecture and top-down energy consumption modeling were triangulated for convergence.
Demand-supply balance across the projection horizon was assessed through analysis window segmentation by heating element type, connectivity protocol, application end-use, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to electrification policy implementation timelines and building renovation cycle data. Forecast inputs incorporated utility rebate program budget allocations and smart home device penetration trajectories by income demographic.
Stress conditions across copper and rare earth magnet price volatility, grid interconnection standard fragmentation, and cybersecurity certification timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and subsidy program continuity. Cross-checking against IEA national building stock electrification benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Europe Alternating Current (AC) Drive Market
Electrical Power Equipment
Copper Ground Rod Market
Electrical Power Equipment
Nuclear Cables Sales Market
Electrical Power Equipment
Magnetic Optical Current Transformer Market
Electrical Power Equipment
Electric Insulator Market
Electrical Power Equipment
Electrical Steel for Electric Vehicle Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
Skid Mounted Unit Substations Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
AV Power Conditioners Market
Electrical Power Equipment
Alternate Current (AC) Drives Market
Electrical Power Equipment
High Voltage Oil Insulated Switchgear Market
Electrical Power Equipment
Recloser Market
Electrical Power Equipment
Alternator Regulator Market