
 Marine Switchboard Market | 2026-2036
Marine Switchboard Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Switchboard Market Analytics
Offshore support vessels is expanding their share of marine switchboard procurement as deepwater exploration extends into harsher environments. ABB leverages its automation integration to dominate the high-specification segment for dynamic positioning systems. Siemens anchors its position through in-house production of digital control modules that reduce commissioning time at shipyards. Hyundai Electric & Energy competes aggressively on Korean newbuild programs where local content requirements favor domestic suppliers.
A marine switchboard is an electrical distribution assembly engineered to manage power flow across vessel generation, propulsion, and auxiliary loads, typically rated for low-voltage applications up to 1,000V AC with busbar configurations designed to withstand salt-laden atmospheres and vessel motion stresses. Its primary function centers on isolating fault conditions, enabling load shedding, and integrating multiple power sources including shore connection, diesel generators, and emerging battery storage. Power distribution boards occupy the largest installed base across cargo fleets where standardization drives economies of scale. Smart switchboards represent the fastest-growing technology segment as remote diagnostics and condition-based monitoring reduce unplanned downtime in commercial operations. Retrofits constitute a concentrated margin pool for specialized integrators serving aging naval and commercial fleets with legacy electromechanical systems.
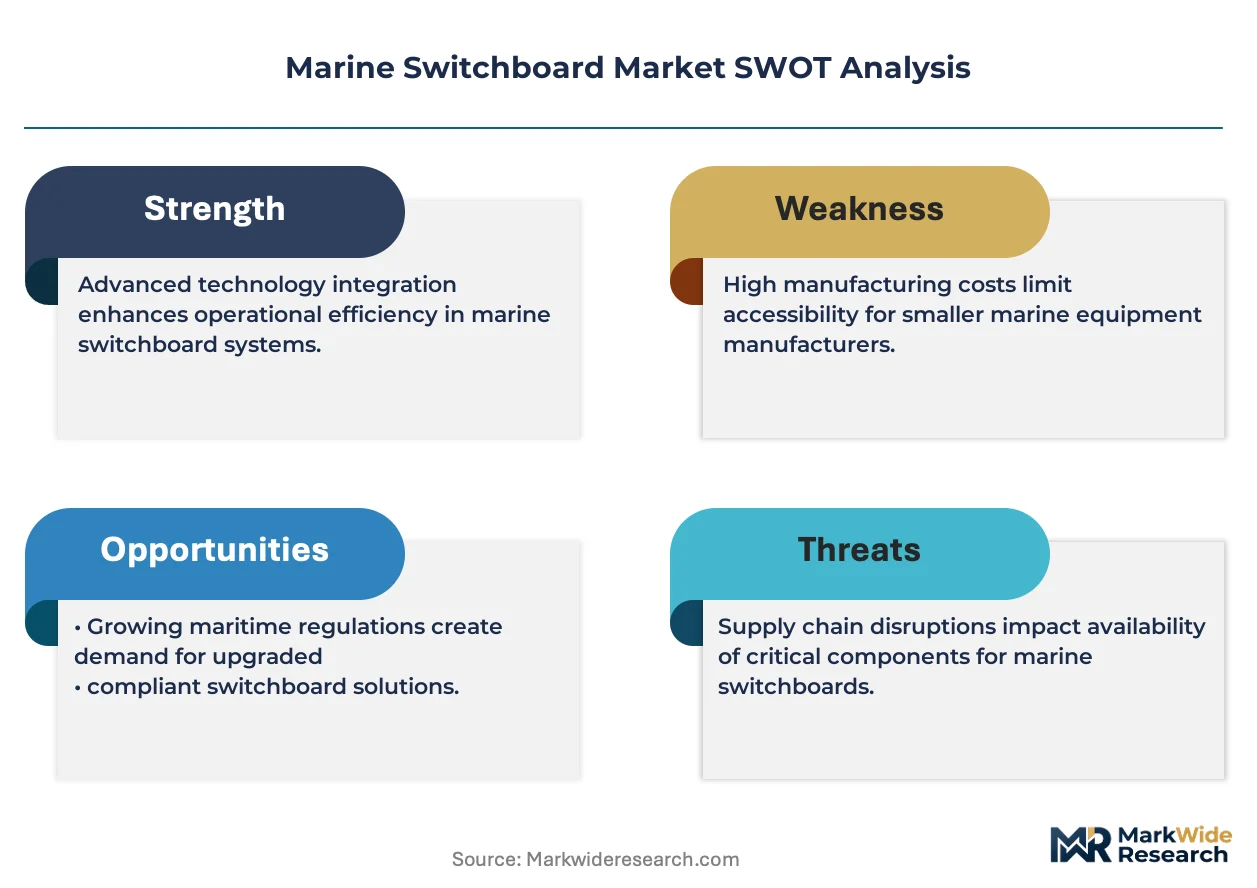
The International Maritime Organization enforces carbon intensity indicator compliance that compels fleet operators to replace obsolete switchgear with intelligent power management systems. Lloyd's Register and DNV classification societies mandate type-approved assemblies for vessel safety certification, creating barrier conditions for uncertified manufacturers. The EU Green Deal's Fit for 55 framework extends emissions trading to maritime transport, accelerating investment in hybrid-compatible switchboard architectures. Stakeholders must monitor how evolving cybersecurity standards for connected ship systems reshape supplier qualification criteria and procurement protocols.
Market Dynamics
Deepwater exploration expansion and IMO carbon intensity regulations are forcing fleet operators to replace legacy electromechanical switchgear with intelligent power management systems, restructuring procurement around automation integration and hybrid-compatible architectures.
Growth Catalysts
- IMO Carbon Intensity Indicator:Fleet operators must upgrade power distribution systems to comply with mandatory emissions tracking, accelerating replacement cycles for obsolete switchgear across commercial fleets.
- Dynamic Positioning Systems:Offshore support vessels operating in harsher deepwater environments require high-specification switchboards with integrated automation for station-keeping precision.
- Korean Shipyard Concentration:Newbuild activity at Ulsan and Geoje anchors sustained demand for marine electrical infrastructure with local content requirements favoring domestic supply chains.
Market Restraints
- Copper and Silver Price Volatility:Busbar fabrication depends on these conductive metals, exposing manufacturers to commodity swings that compress margin predictability on fixed-price contracts.
- South Korean Supply Concentration:Hyundai Heavy Industries and Samsung Heavy Industries control a disproportionate share of newbuild orders, creating customer dependency risk for switchboard suppliers.
- Classification Society Approval Bottlenecks:Lloyd's Register and DNV type-approval processes extend lead times for design modifications, freezing product iteration cycles.
Strategic Opportunities
- Battery-Hybrid Retrofits:Aging cargo fleets with legacy diesel-electric systems present conversion opportunities for integrators capable of engineering shore-connection and energy storage integration.
- EU Emissions Trading Extension:The Fit for 55 framework's inclusion of maritime transport creates compliance-driven demand for hybrid-compatible switchboard architectures in European-flagged vessels.
- Remote Diagnostics Convergence:Integration of IoT sensors with cloud-based fleet management platforms enables condition-based monitoring services as recurring revenue streams.
Industry Challenges
- Marine Electrical Engineering Talent Scarcity:Specialized expertise in salt-atmosphere electrical design and vessel motion stress analysis remains concentrated among retiring workforce cohorts.
- Cybersecurity Certification Complexity:Evolving IEC 62443 standards for connected ship systems require suppliers to requalify products under new threat-modeling protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Switchboard Market |
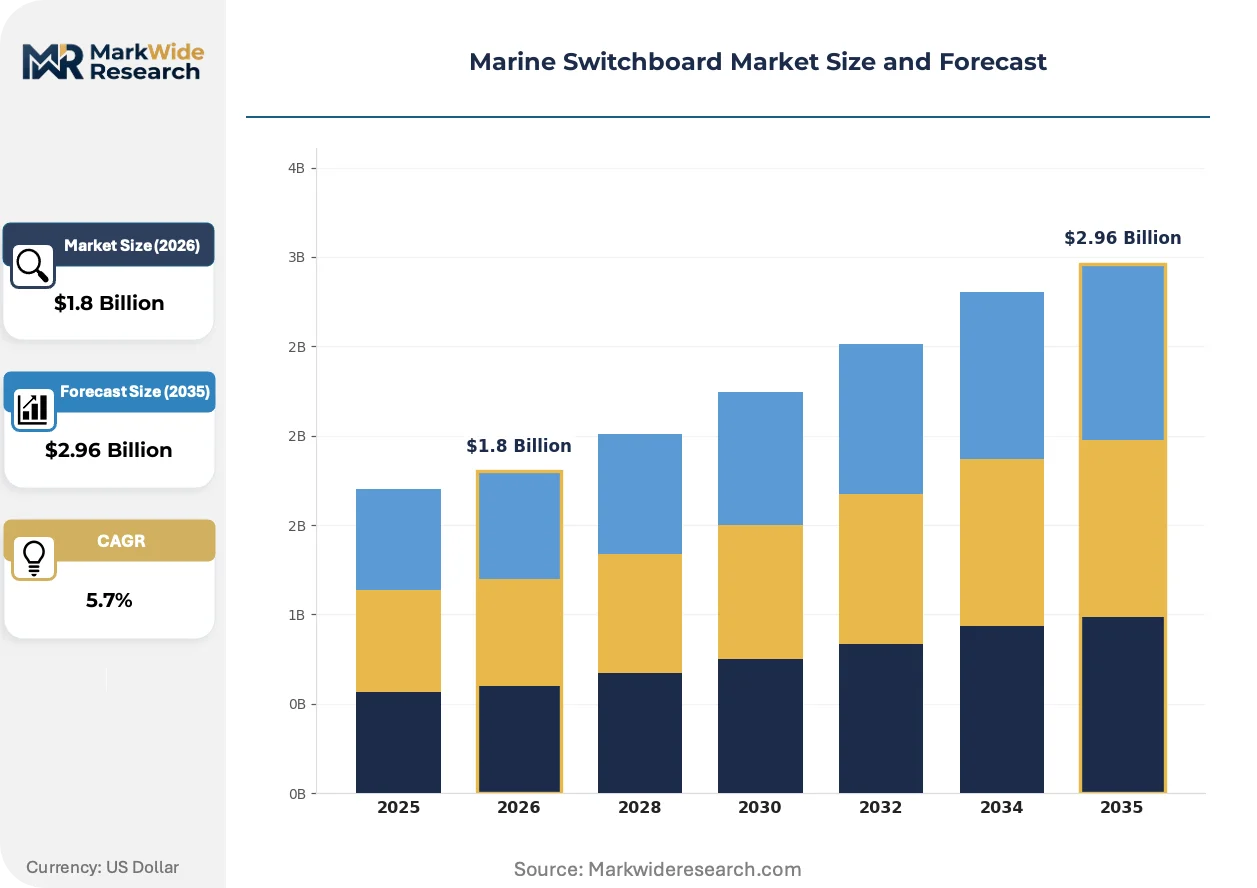
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Distribution Boards, Control Panels, Circuit Breaker Boards, Automation Panels End User: Commercial Vessels, Cargo Ships, Yachts, Naval Ships Installation Type: Onboard Installation, Retrofits, Custom Builds, Modular Systems Technology: Digital Control Systems, Hybrid Systems, Smart Switchboards, Manual Switchboards |
| Companies Covered | Atlas Marine Systems, General Electric, ABB, TERASAKI, Kongsberg, Schneider Electric, Eaton, Hyundai Electric & Energy, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Switchboard Market Evolving Landscape
Switchboard architecture is pivoting from fixed electromechanical assemblies toward software-defined power distribution, with remote monitoring capabilities and modular hardware configurations displacing traditional commissioning models.
Intelligent switchboard technology is modularizing power distribution around standardized, hot-swappable drawer units that reduce vessel downtime during maintenance windows. Offshore support vessel operators are adopting these configurations fastest due to operational continuity requirements in remote locations. This shift is compressing the traditional switchboard replacement cycle from decades to years as upgrade paths become incremental rather than capital-intensive.
EU Green Deal implementation through the Fit for 55 framework is extending emissions trading to maritime transport, compelling fleet operators to document power consumption at the circuit level. Switchboard suppliers must now engineer measurement and verification capabilities into baseline product designs. European short-sea shipping routes are responding first, with North Sea and Baltic operators piloting integrated power management systems ahead of compliance deadlines.
Buyer consolidation among integrated shipowners is consolidating procurement authority at fleet headquarters rather than dispersed at individual shipyards. Engineering specifications now centralize through technical departments in Oslo, Hamburg, and Singapore, displacing traditional shipyard-driven vendor selection. This pattern concentrates contract values with suppliers capable of global service networks and multi-vessel program pricing.
Marine Switchboard Market Segmentation
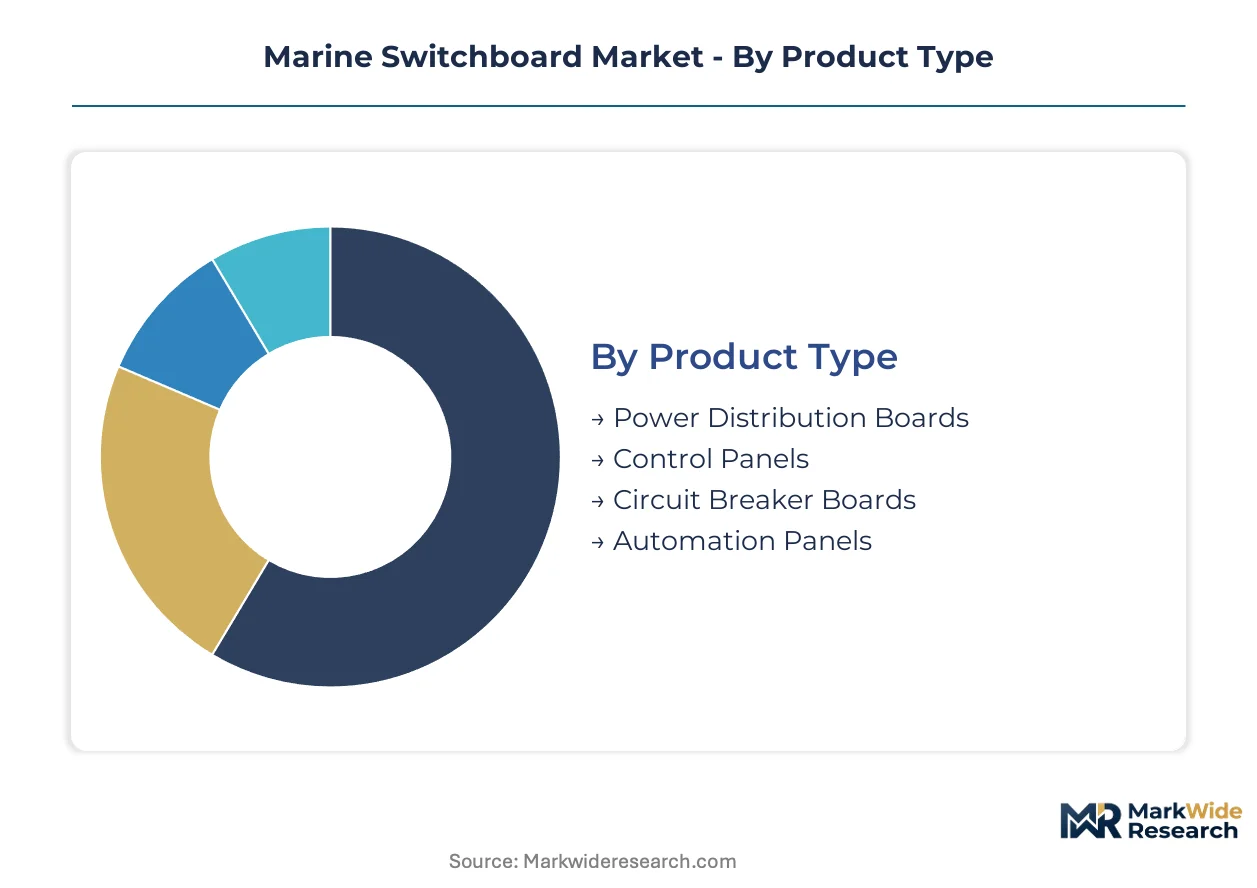
Marine switchboard procurement patterns diverge sharply across vessel types and operational profiles. Upgrade cycles and regulatory compliance windows create distinct demand rhythms that suppliers must align against.
Product Type:
Replacement intensity varies by assembly complexity, with simpler units cycling faster than integrated systems.
- Power Distribution Boards:These assemblies route primary power from generators to propulsion and auxiliary loads through copper busbar configurations rated for marine voltage classes. Cargo fleet operators in South Korea and Germany drive procurement volume as standardization permits economies of scale across series-built vessels.
- Control Panels:Enclosures housing monitoring instrumentation, protective relays, and operator interfaces for real-time power system oversight. Offshore support vessels operating in the North Sea and Gulf of Mexico concentrate demand for these units as dynamic positioning precision requirements tighten.
- Circuit Breaker Boards:Dedicated fault isolation assemblies with molded-case and air-break configurations for selective coordination.
- Automation Panels:Integration platforms connecting switchgear to vessel-wide power management systems.
Power Distribution Boards sits at the top of the volume ranking, with Automation Panels climbing the fastest.
End User:
Customer procurement authority concentrates differently across vessel ownership structures, from dispersed shipyard selection to centralized fleet technical departments.
- Commercial Vessels:Ferries, tugs, and workboats with standardized electrical requirements and shorter capital planning horizons. Operators in the EU and Japan dominate this segment as emissions trading schemes and domestic route electrification mandates accelerate replacement schedules.
- Cargo Ships:Container, bulk, and tanker fleets with massive installed bases and extended depreciation cycles. Shipowners headquartered in Hamburg, Oslo, and Singapore are consolidating procurement authority at fleet level, displacing yard-driven vendor selection.
- Yachts:Superyacht and recreational craft with bespoke electrical specifications and owner-driven customization.
- Naval Ships:Military vessels with classified requirements and extended qualification protocols.
Cargo Ships command the greatest absolute demand, while Commercial Vessels are gaining share fastest under regulatory pressure.
Installation Type:
Project economics shift dramatically between greenfield integration and brownfield modification, with margin structures inverting across these modes.
- Onboard Installation:Factory-integrated assemblies delivered to shipyards for hull-in mounting during new construction. Korean yards at Ulsan and Geoje anchor this demand as Hyundai Heavy Industries and Samsung Heavy Industries execute contracted orderbooks.
- Retrofits:Replacement of legacy electromechanical switchgear in operating vessels without drydock extension. Aging European short-sea fleets and US inland waterway operators concentrate this demand as IMO carbon intensity deadlines approach.
- Custom Builds:Engineered-to-order assemblies for specialized vessel types with non-standard power architectures.
- Modular Systems:Standardized, hot-swappable drawer configurations enabling incremental upgrade paths.
Onboard Installation retains volume leadership, though Retrofits are expanding most quickly as compliance windows narrow.
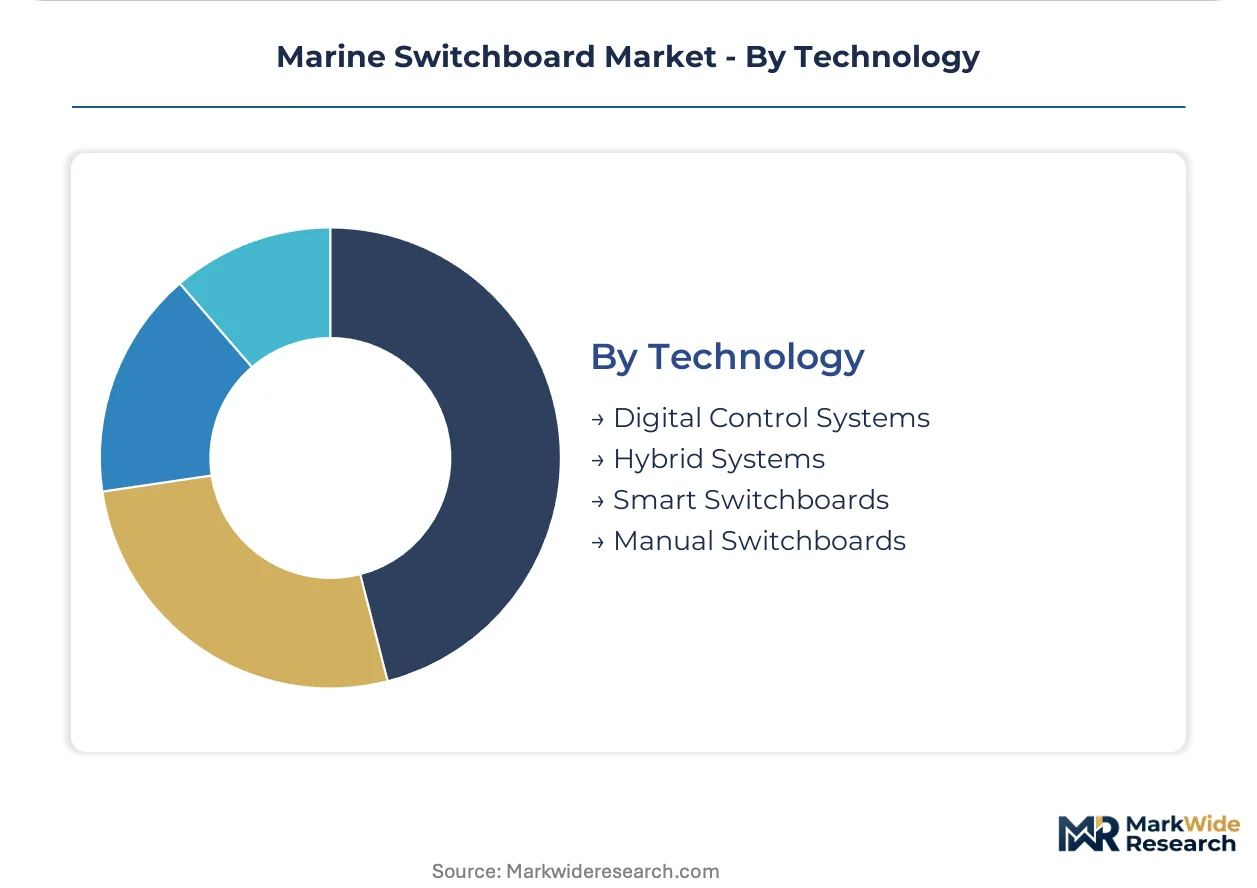
Technology:
Technology selection increasingly determines lifecycle cost rather than capital outlay alone, shifting procurement evaluation criteria.
- Digital Control Systems:Microprocessor-based protection and monitoring with programmable logic for automated load shedding and source transfer. DNV and Lloyd's Register classification requirements in European-flagged fleets are accelerating displacement of analog alternatives.
- Smart Switchboards:IoT-enabled assemblies with cloud-connected diagnostics and predictive maintenance algorithms. North Sea offshore operators are piloting these systems ahead of broader fleet rollout to reduce unplanned downtime in remote locations.
- Hybrid Systems:Architectures integrating diesel generation with battery storage and shore connection capability.
- Manual Switchboards:Electromechanical assemblies with direct operator control, now confined to legacy installations and cost-sensitive segments.
Digital Control Systems hold the largest installed base, with Smart Switchboards tracing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting switchboard procurement toward jurisdictions with streamlined classification approval processes and concentrated shipyard capacity. South Korea and China leverage faster type-certification timelines to capture retrofit and newbuild contracts that European yards cannot execute within IMO compliance windows.
South Korea
Ulsan and Geoje shipyards execute the majority of global offshore support vessel newbuilds, driving concentrated demand for marine electrical infrastructure. The Korea Register of Shipping maintains accelerated approval pathways for digital control systems that DNV and Lloyd's Register process more slowly. Hyundai Heavy Industries and Samsung Heavy Industries anchor procurement authority, favoring domestic suppliers such as Hyundai Electric & Energy under local content requirements.
China
State-owned shipyards in Shanghai and Dalian are expanding into high-specification offshore vessels previously dominated by Korean builders. The China Classification Society has harmonized its rules with IMO carbon intensity protocols, reducing re-certification costs for export-bound vessels. Jiangnan Shipyard and COSCO Shipping Heavy Industry are integrating intelligent power management systems into series-built container vessels for European charterers.
Germany
Hamburg-headquartered shipowners are consolidating procurement authority at fleet technical departments, displacing yard-driven vendor selection. The EU Green Deal's Fit for 55 framework extends emissions trading to maritime transport, compelling North Sea short-sea operators to document power consumption at the circuit level. Flensburger Schiffbau-Gesellschaft and Meyer Werft in Papenburg are retrofitting legacy fleets with hybrid-compatible switchboard architectures ahead of compliance deadlines.
Norway
Oslo-based integrated shipowners are piloting smart switchboard systems with remote diagnostics for offshore support vessels operating in the North Sea. The Norwegian Maritime Authority enforces stringent cybersecurity standards for connected ship systems under evolving IEC 62443 protocols. Ulstein Verft and Vard Group in Ålesund are engineering battery-hybrid retrofits for aging platform supply vessels.
United States
Gulf of Mexico offshore operators are replacing obsolete switchgear to meet Bureau of Safety and Environmental Enforcement electrical safety mandates. The Jones Act preserves domestic build requirements for coastwise trade, sustaining demand at Ingalls Shipbuilding in Mississippi and General Dynamics NASSCO in California. US inland waterway operators are accelerating retrofit schedules as EPA marine diesel emissions rules tighten.
Marine Switchboard Market Competitive Landscape
Automation integration dominates the current landscape as suppliers compete to embed power management software within switchboard hardware. The vendor base separates into three distinct tiers: diversified electrical conglomerates with marine divisions, specialized marine electrical integrators, and shipyard-captive fabricators serving local newbuild programs. Consolidation pressure is mounting as fleet operators reduce approved vendor lists to simplify global service coverage. Strategic partnerships between switchboard manufacturers and battery system suppliers are displacing standalone hardware procurement.
Among diversified industrial electrification groups, ABB, Siemens, and Schneider Electric occupy positions defined by in-house production of digital control modules and automation platforms. These conglomerates exemplify the automation-integration archetype, leveraging software-defined power distribution to differentiate from commodity hardware fabricators. Hyundai Electric & Energy represents the shipyard-captive model, anchoring supply relationships with Korean newbuild programs where local content requirements create structural advantages. Specialized marine electrical integrators such as Atlas Marine Systems and TERASAKI sit within a middle tier, competing on retrofit expertise and legacy system compatibility where classification society approval bottlenecks protect incumbent positions.
| Leading Market Players |
|---|
| Atlas Marine Systems |
| General Electric |
| ABB |
| TERASAKI |
| Kongsberg |
| Schneider Electric |
| Eaton |
| Hyundai Electric & Energy |
| Siemens |
| Others |
Value Network & Pricing Analysis
Korean shipyard concentration around Hyundai Heavy Industries and Samsung Heavy Industries enforces project-based contract pricing with fixed-price terms that transfer commodity volatility risk to switchboard manufacturers. This buyer archetype dominance compresses margin predictability when copper and silver busbar costs swing.
Pricing Analysis
Direct-to-shipyard contracts carry thin distributor margins with pricing stratifying across Lloyd's Register certification grade, automation integration depth, and volume scale. Price differentiation hinges on DNV type-approval tier and after-sales service bundling. Cost compression in standard power distribution boards is intensifying because Korean yards consolidate procurement authority at fleet technical departments. Cargo fleet operators prove most price-sensitive while offshore support vessel charterers prioritize specification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with South Korean copper busbar fabrication and German digital control module production. Manufacturing draws from Chilean copper concentrate, Chinese silver refining, and Japanese semiconductor components for protection relays. Tariff exposure runs through EU carbon border adjustments on imported electrical assemblies. Distribution runs through shipyard-integrated procurement channels with limited aftermarket parts availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine switchboard procurement functions as a regulatory compounder where IMO carbon intensity indicator deadlines force fleet-wide replacement cycles regardless of underlying vessel economics.
For Market Incumbents: Extend automation platform integration into battery-hybrid power management systems to defend against pure-play battery integrators entering switchboard retrofit contracts. Anchor capacity in Ulsan and Geoje shipyard clusters to capture Korean newbuild volume under local content requirements. Deepen in-house production of IEC 62443-compliant cybersecurity modules as classification societies tighten connected-system standards. For New Entrants and Emerging Players: Smart switchboard remote diagnostics capability offers a technology-first wedge into European short-sea retrofit programs where incumbent suppliers lack cloud-native fleet management integration. Target aging North Sea platform supply vessels with modular drawer configurations that reduce drydock downtime. Lead with condition-based monitoring subscriptions rather than hardware margin capture. For Investors and Strategic Acquirers: Diversified industrial electrification conglomerates are the most active acquirer in this space as they seek marine-automation capabilities to complement shore-side power portfolios. Five-to-ten year viability rests on hybrid-architecture engineering depth rather than legacy electromechanical fabrication. Watch Korean shipyard orderbook cancellations as the lead inflection signal for demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Hybrid Retrofit Engineering | Captures IMO compliance-driven replacement demand in aging European short-sea fleets. |
| IEC 62443 Cybersecurity Certification | Unlocks procurement eligibility under Norwegian Maritime Authority connected-ship mandates. |
| Remote Diagnostics Platform Launch | Converts hardware sales into recurring revenue from North Sea offshore operators. |
| Shipyard-Captive Supply Agreement | Secures volume allocation at Ulsan and Geoje under Hyundai and Samsung programs. |
| Copper Busbar Backward Integration | Insulates margin from London Metal Exchange price swings on fixed-price contracts. |
Research Methodology
Multiple input streams — shipyard procurement director interviews, classification society type-approval databases, and copper commodity futures data — were reconciled to construct demand estimates. Primary fieldwork captured perspectives from marine electrical engineers, fleet technical managers at Hamburg and Oslo headquarters, and aftermarket service heads at specialized integrators. Secondary validation drew from Lloyd's Register and DNV certification records, Korea Register of Shipping approval timelines, and EU MRV emissions monitoring disclosures. Bottom-up vessel-by-vessel retrofit pipeline analysis was cross-checked against top-down shipyard orderbook aggregation.
Data-stream reconciliation anchored volume projections across the analysis window through segmented modeling of vessel type, installation mode, and technology tier. The analytical framework incorporated propulsion architecture evolution, regulatory compliance window clustering, and regional shipyard capacity utilization. CAGRs were derived from replacement cycle compression rates and newbuild specification trajectories. Forecast inputs included IMO carbon intensity implementation schedules and EU Green Deal maritime extension timelines.
The model holds under steady regulatory enforcement timelines; deviation in IMO compliance deadline extensions or Korean shipyard labor disruptions would shift replacement intensity. Forecasts reflect assumptions around classification society approval velocity and copper price band stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Global Electrical SCADA Market
Electrical Power Equipment
Global Hazardous Location Motor Starters Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
United States Electric Space Heaters Market
Electrical Power Equipment
Utility Equipment Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
Bucket Water Heater Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
Carbon Brush Market
Electrical Power Equipment
Overhead Aluminium Conductors Market
Electrical Power Equipment
North America Gas Insulated Switchgear Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
Utility Poles Market
Electrical Power Equipment
Digital Fault Recorder (DFR) Market
Electrical Power Equipment
Magneto Optic Current Transformer Market
Electrical Power Equipment
AV Power Conditioners Market