
 Electric Parking Brake Market | 2026-2036
Electric Parking Brake Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Parking Brake Market Intelligence
A shift from single-sourcing to multi-sourcing by major automotive OEMs is rebalancing the competitive landscape for electric parking brake suppliers. Continental AG leverages its extensive electronics and software expertise to offer integrated chassis control solutions. ZF Friedrichshafen competes with a broad portfolio of mechatronic systems for both passenger and commercial vehicles. Robert Bosch specializes in advanced braking systems that are foundational for automated driving functions.
An electric parking brake replaces the conventional mechanical handbrake with an electronic system, typically activated by a button or switch. The system utilizes an electronic control unit (ECU) and an actuator mechanism to apply braking force to the rear wheels, holding the vehicle stationary. Integrated systems are displacing older cable-pulled designs, especially within the passenger vehicles segment where space optimization is critical. Demand from the autonomous vehicles application is centered on fail-safe mechanisms and sensor-based control for redundant safety.
Automotive safety standards, including Federal Motor Vehicle Safety Standards (FMVSS) in the United States and ECE regulations in Europe, mandate specific performance criteria for braking systems. China's GB standards for electric vehicles are also influencing EPB design, particularly regarding integration with regenerative braking systems. Component suppliers must now navigate these divergent regional requirements while developing platforms that support automated and electric vehicle architectures.
Market Dynamics
The integration of fail-safe braking into autonomous driving systems is the central force shaping the market. This requires EPBs to evolve from convenience features into critical components of a vehicle's redundant safety architecture.
Growth Catalysts
- ADAS Integration:Advanced driver-assistance systems require automated brake engagement for functions like stop-and-go cruise control, driving EPB adoption for safety.
- China's EV Market:China's expanding electric vehicle sector, governed by GB standards, necessitates EPBs that integrate with regenerative braking systems.
- Safety Mandates:European ECE regulations mandate braking performance criteria that favor the electronically controlled nature of EPBs over mechanical alternatives.
Market Restraints
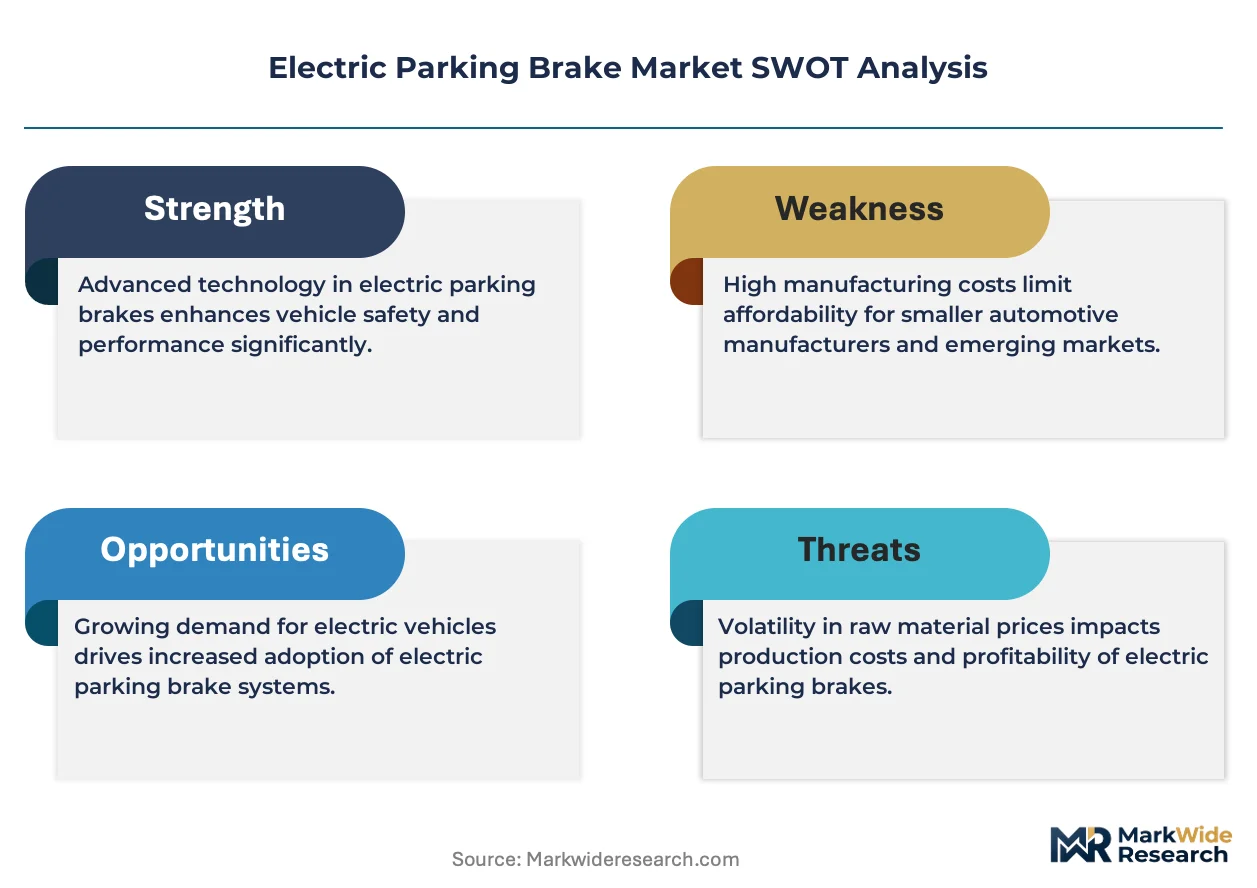
- Cost Sensitivity:Higher EPB system cost compared to traditional handbrakes remains a barrier in budget vehicle segments.
- ECU Supply Concentration:Reliance on a few firms for automotive-grade ECUs creates supply chain bottlenecks and price volatility for EPB manufacturers.
- Technical Hurdles:Ensuring functional safety across diverse vehicle architectures is a complex challenge that increases development and validation costs.
Strategic Opportunities
- Commercial Vehicle Expansion:Adapting EPB technology for light and heavy commercial vehicles is a key opportunity due to low current penetration.
- Predictive Maintenance:EPBs with integrated sensors for condition monitoring can create new service revenue by predicting wear and preventing failures.
- Aftermarket Upgrades:Certified aftermarket EPB conversion kits for older vehicles represent a growth avenue targeting enthusiasts and fleet owners.
Industry Challenges
- Software Integration Burden:Suppliers face challenges ensuring flawless interoperability between the EPB's ECU and a growing number of other vehicle control systems, complicating software validation.
- Regulatory and Talent Hurdles:Navigating disparate regional safety standards while facing a shortage of engineers with expertise in functional safety like ISO 26262 increases costs and slows development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Parking Brake Market |
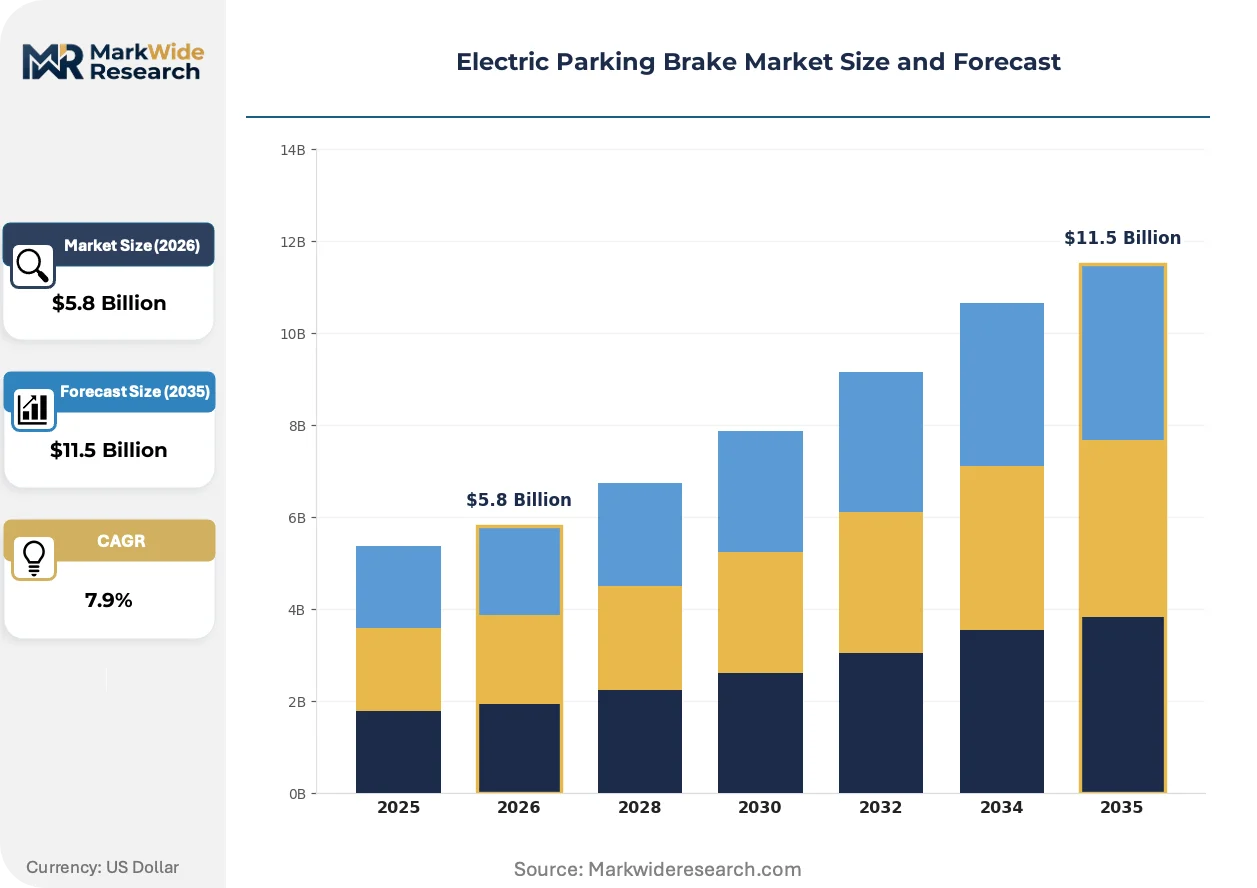
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cable-Pulled, Electronic, Electro-Mechanical, Hydraulic, Integrated Systems Application: Passenger Vehicles, Commercial Trucks, Specialty Vehicles, Off-Road Equipment, Autonomous Vehicles End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Fleet Operators, Aftermarket Providers Technology: Button Activated, Lever Activated, Sensor-Based Control, Automated Parking Brake, Fail-Safe Mechanisms |
| Companies Covered | Aisin Seiki, Hyundai Mobis, ZF Friedrichshafen, Mando, Brembo, Continental AG, Hitachi Astemo, Wuhu Bethel, Robert Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Parking Brake Market Strategic Shifts & Innovations
The electric parking brake's evolution from a simple mechanical replacement to a core node in the vehicle's central nervous system is a defining theme. This transition is driven by software-defined vehicle architectures and the push for higher levels of automation.
Brake-by-wire technology eliminates the direct mechanical link for braking, relying entirely on electronic signals for actuation. Premium electric vehicles and platforms designed for autonomous driving are the primary adopters, seeking its precise control capabilities. This architecture is absorbing the standalone EPB function into a unified chassis control domain, simplifying hardware but elevating software's role.
Updated ECE regulations in Europe are imposing stricter requirements for the cybersecurity of vehicle electronic systems, including braking controls. This forces suppliers to implement robust protection against remote unauthorized access and manipulation, adding a new layer of software and hardware validation. The passenger car segment is most affected by these new mandates.
A notable shift in OEM procurement involves unbundling software from hardware in sourcing decisions for mechatronic systems. This model disrupts the traditional Tier 1 supplier role by allowing automakers to source actuators from one vendor and develop control software separately. This demand-side change is most visible among new EV manufacturers in China.
Electric Parking Brake Market Segmentation
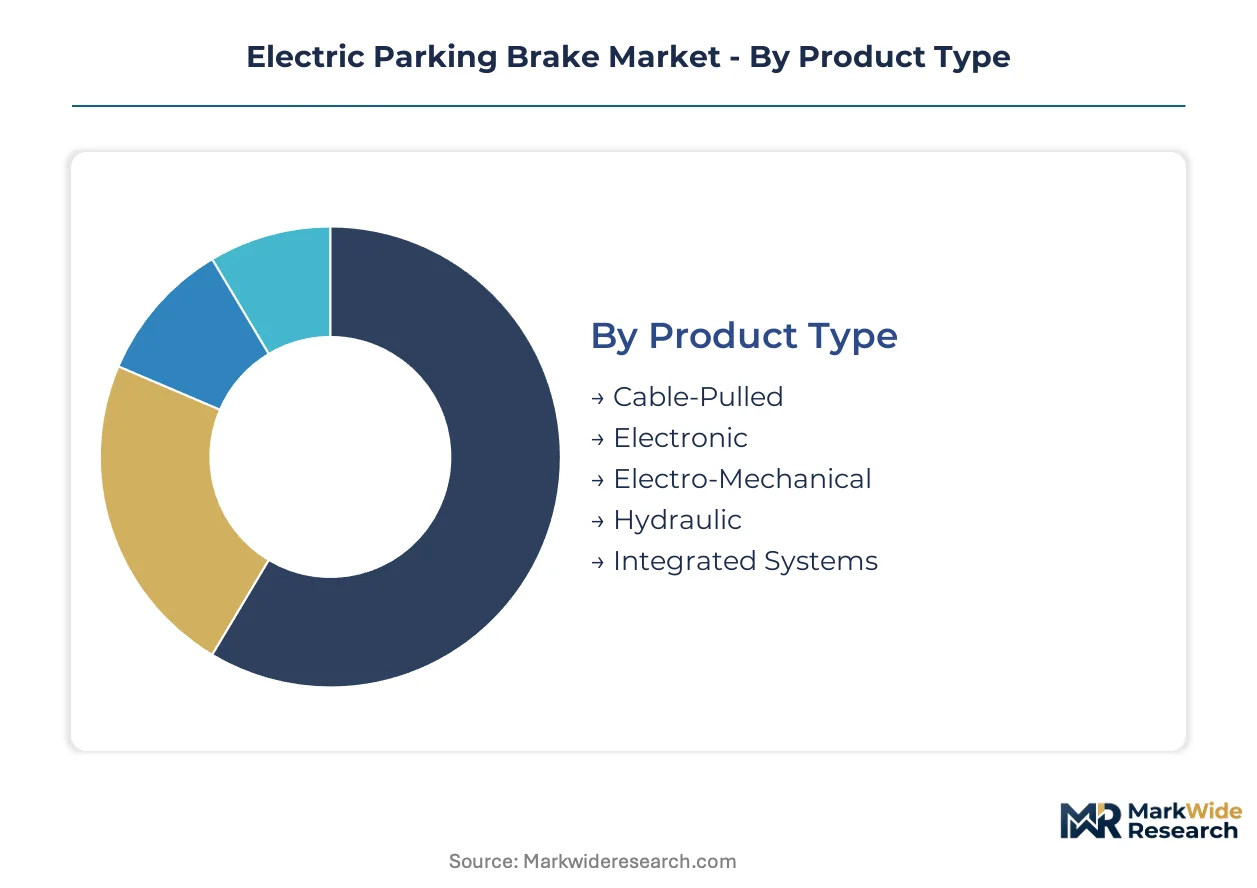
Understanding the Electric Parking Brake market's segmentation is critical for identifying specific demand patterns and technological adoption trajectories. The diverse requirements across vehicle types and end-user demands shape product development and market penetration strategies for suppliers.
Product Type:
The customization versus standardization spectrum significantly influences product type offerings, ranging from basic mechanical replacements to highly integrated electronic modules.
- Integrated Systems:These advanced EPB solutions combine braking functions with other vehicle control units, reducing hardware complexity and enhancing software-defined vehicle architectures. Demand concentrates within premium electric vehicles in Germany, driven by the need for precise control and space optimization.
- Electro-Mechanical:This system uses an electric motor to actuate the parking brake calipers, offering a balance of electronic control and mechanical robustness. Adoption is accelerating in mid-range passenger vehicles across China, where manufacturers seek improved safety and convenience features.
- Cable-Pulled:Traditional cable-actuated systems represent an older generation of parking brakes, characterized by their mechanical simplicity.
- Electronic:These systems utilize an electronic control unit to manage a separate actuator, providing electronic activation without full integration into the main braking system.
- Hydraulic:Hydraulic EPBs integrate with the vehicle's hydraulic braking circuit, offering high clamping forces suitable for heavier vehicles.
Most installed capacity flows through Electro-Mechanical systems. Expansion is steepest in Integrated Systems.
Application:
The breadth of application for electric parking brakes spans various vehicle categories, each with distinct performance and safety requirements.
- Passenger Vehicles:This segment represents the largest volume market, driven by consumer demand for convenience features and safety enhancements in daily driving. Automakers in Japan prioritize EPB integration for advanced driver-assistance systems.
- Autonomous Vehicles:EPBs serve as critical fail-safe components within autonomous driving stacks, requiring redundant safety mechanisms and highly reliable sensor-based control. Development efforts focus on these systems for future mobility solutions in the United States.
- Commercial Trucks:EPB technology is being adapted for heavier loads and more demanding operational cycles in the commercial vehicle sector.
- Specialty Vehicles:This category includes niche applications like recreational vehicles and emergency services vehicles, where specific braking requirements apply.
- Off-Road Equipment:EPBs for off-road machinery must withstand harsh environmental conditions and provide robust holding power on uneven terrains.
Passenger Vehicles command the largest share of EPB deployments. Autonomous Vehicles are climbing the fastest in terms of adoption rates.
End User:
The primary customer types for electric parking brake systems reflect the automotive supply chain's structure, from initial manufacturing to post-sales support.
- OEMs:Original Equipment Manufacturers are the largest direct purchasers, integrating EPB systems into new vehicle designs during the production phase. Vehicle manufacturers in Europe dictate specifications for functional safety and cybersecurity compliance.
- Tier-1 Suppliers:These companies develop and supply complete EPB modules or sub-systems directly to OEMs, often undertaking significant R&D. German Tier-1 suppliers focus on advanced mechatronic integration for global automotive platforms.
- Vehicle Assemblers:Firms that assemble vehicles using components from various suppliers also procure EPB systems for their production lines.
- Fleet Operators:Companies managing large vehicle fleets require reliable and maintainable EPB systems for operational efficiency and driver safety.
- Aftermarket Providers:These entities supply replacement parts and upgrade kits for EPBs in vehicles already on the road.
OEMs represent the dominant procurement channel for EPB components. Tier-1 Suppliers are gaining share as system integrators.
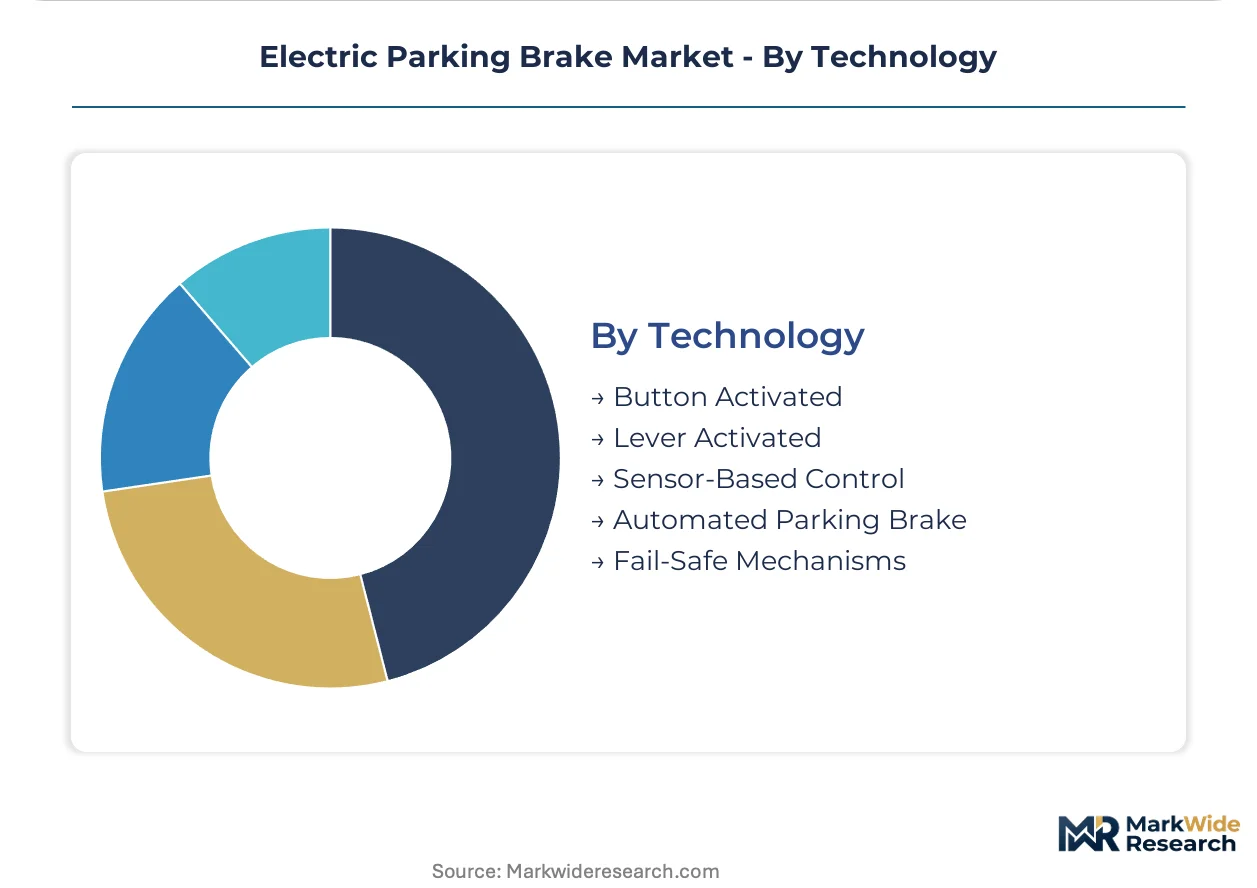
Technology:
Technological advancements are transforming EPBs from simple activation mechanisms to sophisticated control systems, particularly for automated driving.
- Sensor-Based Control:These EPB systems utilize various sensors to detect vehicle conditions, enabling automatic engagement or disengagement based on factors like incline or driver presence. This technology is critical for advanced driver-assistance systems in North America.
- Fail-Safe Mechanisms:Essential for autonomous vehicles, fail-safe EPBs ensure braking functionality even in the event of primary system failure, providing a crucial layer of redundancy. Development in China focuses on robust fail-safe designs to meet stringent EV safety standards.
- Button Activated:The most common interface, where a driver presses a button to engage or release the parking brake.
- Lever Activated:Less common in modern EPBs, this involves a lever-style switch for activation, often found in older designs.
- Automated Parking Brake:This feature automatically engages the parking brake when the vehicle is stopped or the ignition is turned off, enhancing convenience.
Button Activated EPBs currently hold the largest installed base. Fail-Safe Mechanisms are seeing the most rapid technological development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta, a significant automotive manufacturing hub, drives much of the global electric parking brake demand. This region, along with other key automotive clusters worldwide, dictates the pace of technological adoption and market expansion. Diverse regional requirements and safety standards influence EPB design and integration across various vehicle platforms.
China
China's expanding electric vehicle sector generates substantial demand for electric parking brakes. GB standards for electric vehicles influence EPB design, particularly concerning integration with regenerative braking systems. The Yangtze River Delta region, a major center for new energy vehicle production, sees high adoption of advanced EPB solutions.
Germany
German automotive OEMs prioritize integrated EPB systems for premium electric vehicles, demanding precise control and space optimization. ECE regulations impose strict performance criteria for braking systems, favoring electronically controlled EPBs. The Stuttgart region, home to several major automotive manufacturers, leads in the development of sophisticated mechatronic systems.
United States
United States demand for EPBs stems from the integration of fail-safe braking into autonomous driving systems. Federal Motor Vehicle Safety Standards (FMVSS) mandate specific performance criteria for all braking systems. Michigan's automotive corridor focuses on research and development for autonomous vehicle applications, driving demand for redundant safety mechanisms.
Japan
Japanese automakers integrate electric parking brakes into passenger vehicles for advanced driver-assistance systems and enhanced convenience. JIS standards for automotive components guide the design and manufacturing of these systems. Toyota City and surrounding prefectures remain a key hub for automotive manufacturing and technology development, including EPB integration.
India
India's automotive market sees growing adoption of EPBs in mid-range passenger vehicles, driven by consumer demand for improved safety and convenience features. BIS standards for automotive components are increasingly relevant for EPB manufacturers entering the market. The Chennai and Pune automotive clusters attract investments in manufacturing facilities for advanced vehicle technologies.
Electric Parking Brake Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue integrated chassis control solutions. The competitive landscape for electric parking brake suppliers shifts due to major automotive OEMs moving from single-sourcing to multi-sourcing. This rebalancing creates opportunities for specialized players and integrated system providers. Strategic partnerships and extensive research and development in software integration define key competitive moves.
Specialists in advanced braking systems, such as Robert Bosch GmbH, exemplify innovation in foundational technologies for automated driving functions. Continental AG leverages extensive electronics and software expertise to offer integrated chassis control solutions. ZF Friedrichshafen AG occupies a position among broad portfolio providers of mechatronic systems for both passenger and commercial vehicles, adapting to evolving vehicle architectures.
| Leading Market Players |
|---|
| Aisin Seiki |
| Hyundai Mobis |
| ZF Friedrichshafen |
| Mando |
| Brembo |
| Continental AG |
| Hitachi Astemo |
| Wuhu Bethel |
| Robert Bosch |
| Others |
Cost & Logistics Intelligence
Electronic Control Units (ECUs) represent a significant cost component for electric parking brakes, with their pricing influencing the final system cost passed downstream to automotive OEMs. This critical component's availability and cost directly impact the overall market's pricing tiers and supplier margins.
Pricing Analysis
Input-cost pass-through remains a critical factor, particularly for specialized electronic components and software development. The dominant pricing model involves contract-based long-term offtake agreements between Tier-1 suppliers and OEMs. Price differentiation stems from functional safety certification, customization levels for specific vehicle platforms, and order volume scale. Pricing pressure intensifies due to OEM multi-sourcing strategies and cost sensitivity within the mid-range passenger vehicle segment. Premium electric vehicle and autonomous vehicle applications exhibit the least price sensitivity, prioritizing advanced features and redundancy.
Supply Chain Analysis
Dual-sourcing requirements from major automotive OEMs are reshaping the EPB supply chain, reducing single-supplier dependency. Geographic supply concentration includes China for EV-related components, Germany for advanced mechatronics, and Japan for established automotive manufacturing. The supply chain depends on critical raw materials and components such as ECUs, microcontrollers, and specialized sensors. ECU supply concentration creates a structural risk, leading to potential bottlenecks and price volatility. Distribution directly flows from Tier-1 suppliers to OEMs and vehicle assemblers for integration into new vehicle production lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric parking brake market is transforming into a late-cycle quality story, driven by the escalating demand for fail-safe mechanisms in autonomous vehicles. This shift necessitates a focus on robust engineering and software integrity across all product lines.
For Market Incumbents:
Lock in core competencies in software integration and mechatronics engineering to counter emerging threats from brake-by-wire technology. Invest heavily in research and development for ISO 26262 compliance and advanced functional safety features. Deepen relationships with leading OEMs by offering integrated chassis control solutions that simplify vehicle architecture. Consolidate market share through strategic partnerships that enhance component supply security.
For New Entrants and Emerging Players:
Software-defined vehicle architecture offers a technology-first wedge for specialized firms focusing on EPB control algorithms and cybersecurity. Target underpenetrated segments like light and heavy commercial vehicles where current EPB adoption is low. Develop predictive maintenance solutions with integrated sensors as a unique value proposition and go-to-market angle. Focus on modular, scalable solutions that can integrate seamlessly with diverse vehicle platforms.
For Investors and Strategic Acquirers:
Consolidation pressure builds where functional safety expertise and integrated system capabilities are paramount for next-generation mobility. The long-term viability of the EPB market is strong, given its critical role in autonomous driving systems. Identify acquisition targets with proven track records in advanced mechatronics integration or specialized software for braking controls. The signal to watch is the increasing OEM unbundling of software from hardware in procurement decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Advances EPB integration into unified chassis control for autonomous platforms. |
| Functional Safety Certification | Meets stringent ECE and FMVSS requirements for critical braking systems. |
| Commercial Vehicle Adaptation | Expands market reach into underpenetrated heavy-duty transport segments. |
| Predictive Maintenance Platform | Creates new service revenue streams through sensor-based condition monitoring. |
| Global Regulatory Compliance | Navigates diverse GB, ECE, and FMVSS standards for broader market access. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, ensuring a comprehensive view of the electric parking brake market. Primary data collection involved conversations with automotive OEM engineers, Tier-1 procurement leads, functional safety specialists, and EV platform architects. Secondary validation drew from industry association reports, vehicle production databases, regulatory body publications such as FMVSS, ECE, and GB standards, and academic research, triangulating findings from both bottom-up and top-down approaches.
Segment-weighting across product type, application, and end-user dimensions informed the market forecast across the modeling period. The analytical framework also incorporated technology trends and regional adoption patterns to project market trajectories. Compound annual growth rates were derived from historical trend analysis and future adoption projections, considering key industry-specific forecast inputs like electric vehicle production forecasts and advanced driver-assistance system penetration rates.
The model holds under current regulatory stability and anticipated technology roadmap progression; deviation in unexpected supply chain disruptions or rapid shifts in autonomous vehicle deployment would shift market outcomes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
UAE Automotive Lubricants Market
Automotive Parts
Auto Parts Manufacturing Market
Automotive Parts
Wiper Blade Market
Automotive Parts
Global Automotive Parts Remanufacturing Market
Automotive Parts
Malaysia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Singapore Passenger Vehicles Lubricants Market
Automotive Parts
External Combustion Engine Market
Automotive Parts
France Automotive Airfilters Market
Automotive Parts
Automatic Gearbox Valves Market
Automotive Parts
Automotive Differential Housing Market
Automotive Parts
Mexico Passenger Vehicles Lubricants Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Ignition Coil Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Automotive Air Flow Meter Market