
 Electric Utility-Terrain Vehicle (UTV) Market | 2026-2036
Electric Utility-Terrain Vehicle (UTV) Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Utility-Terrain Vehicle (UTV) Market Insights
Recreational buyers are reorganizing demand patterns as commercial and agricultural fleets expand electric UTV procurement. Polaris Inc. leverages its established off-road dealer network to anchor North American distribution. John Deere competes through agricultural channel control and farm-equipment brand equity. Volcon specializes in pure-electric powertrains for rugged terrain applications.
An electric utility-terrain vehicle is a battery-electric or hybrid-powered off-highway vehicle designed for hauling, towing, and terrain traversal across unpaved surfaces, typically featuring all-wheel drive, payload capacities exceeding 450 kg, and sealed electrical enclosures rated for mud and water ingress. Its primary commercial purpose centers on replacing internal-combustion utility vehicles in noise-sensitive or emission-restricted work environments. Battery electric configurations command the dominant share of new product development investment, while hybrid architectures retain relevance in remote deployment scenarios lacking charging infrastructure. The 20-40 HP power rating band captures the bulk of agricultural and industrial utility applications where torque demands intersect with battery cost constraints.
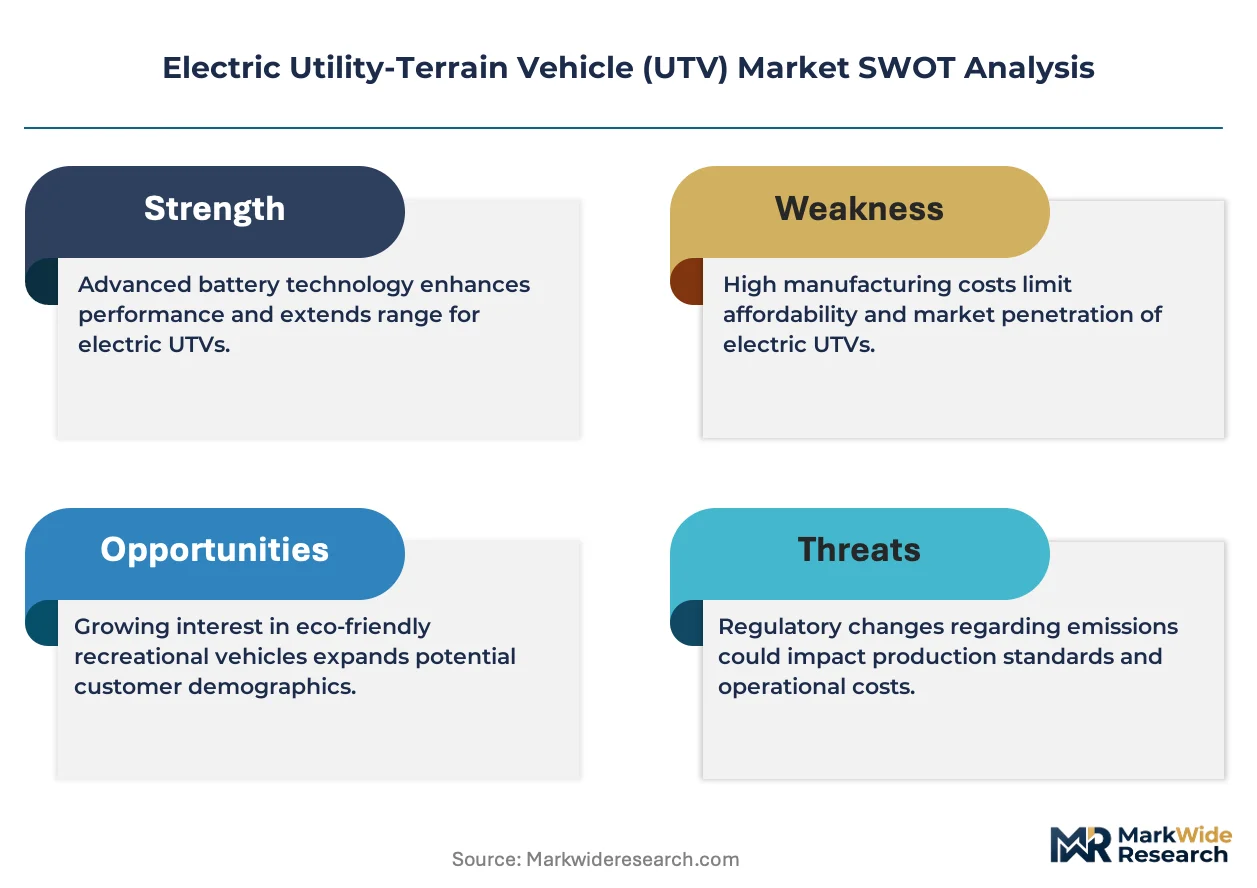
The EPA enforces emission standards that effectively bar new gasoline-powered utility vehicles from certain federal land management contracts, while OSHA guidelines influence vehicle stability and rollover protection requirements for workplace deployment. The EU Green Deal and F-Gas Regulation accelerate diesel displacement across European agricultural and municipal fleets. Stakeholders must monitor evolving battery safety certification protocols and charging interoperability standards as procurement shifts from early-adopter pilots to fleet-scale replacement cycles.
Market Dynamics
Agricultural fleet electrification is compressing replacement cycles for diesel utility vehicles as lithium-ion battery costs decline and torque performance matches combustion equivalents. This structural shift is reordering procurement priorities across commercial operators who previously deferred electric adoption due to range anxiety.
Growth Catalysts
- US Federal Clean Vehicle Incentives:Tax credits under the Inflation Reduction Act reduce effective acquisition costs for commercial electric UTV fleets operating on federal grazing lands and national forest contracts.
- EU F-Gas Regulation:Diesel phase-out mandates across European agricultural zones are accelerating municipal and cooperative fleet turnover toward zero-emission alternatives.
- Lithium Iron Phosphate Chemistry:Improved thermal stability and cycle life in LFP battery packs are extending field operational hours for livestock management and crop monitoring applications.
Market Restraints
- Cobalt and Lithium Price Volatility:Raw material cost swings in battery metal markets compress manufacturer margins and create pricing uncertainty for fleet procurement committees.
- Charging Infrastructure Gaps:Remote agricultural deployment zones in Australia and Brazil lack grid connectivity sufficient for overnight fleet charging without diesel generator backup.
- OSHA Rollover Certification Delays:Extended testing timelines for electric platform stability compliance slow new model introductions and freeze fleet replacement decisions.
Strategic Opportunities
- Swappable Battery Architectures:Standardized pack formats enable continuous operation in vineyard and orchard settings where downtime carries seasonal harvest penalties.
- India Agricultural Electrification:State-level subsidies for farm mechanization create first-mover positioning for electric UTV distribution through cooperative networks.
- Autonomous Guidance Convergence:Integration of RTK-GPS steering with electric powertrains opens precision agriculture contracts previously served by manned diesel equipment.
Industry Challenges
- High-Voltage Technician Scarcity:Rural dealership networks lack certified personnel for battery system diagnostics and thermal runaway containment protocols.
- Legacy PTO Interface Compatibility:Electric motor torque curves require redesigned implement couplings, forcing aftermarket attachment manufacturers into costly redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Utility-Terrain Vehicle (UTV) Market |
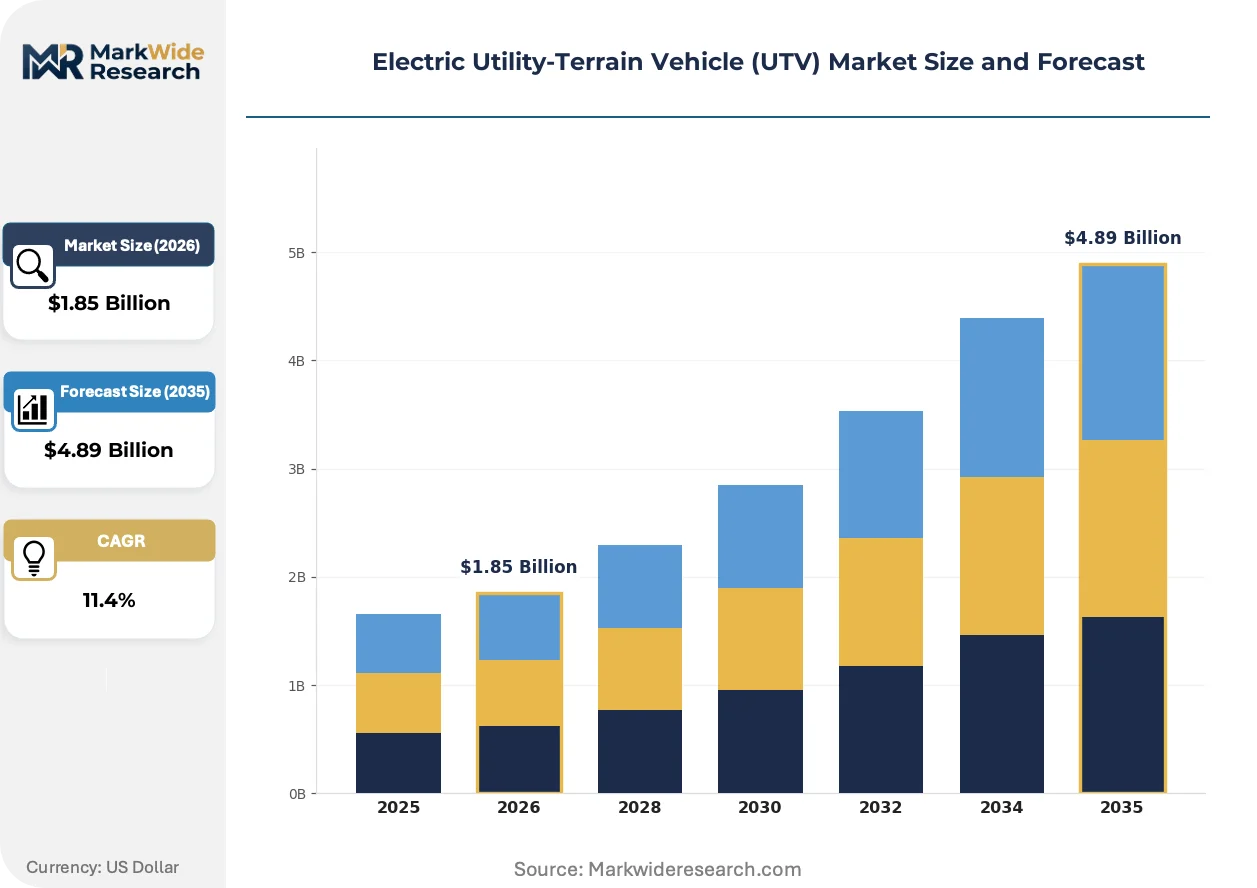
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Battery Electric, Hybrid, Fuel Cell, Plug-in Hybrid End User: Agriculture, Construction, Industrial, Recreation Power Rating: Below 20 HP, 20-40 HP, 40-60 HP, Above 60 HP Application: Material Handling, Terrain Management, Maintenance, Utility Services |
| Companies Covered | Polaris Inc., John Deere, Club Car, Textron Specialized Vehicles, Volcon, TUATARA VEHICLES, Kaxa Motos, Milbay Australia, TRACKER OFF ROAD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Utility-Terrain Vehicle (UTV) Market Trends and Innovations
Power electronics integration is compressing drivetrain packaging and enabling new chassis architectures that depart from combustion-engine legacy layouts. These developments are reshaping competitive positioning around thermal management and software-defined vehicle control.
Silicon carbide inverter technology is miniaturizing high-voltage switching components while reducing switching losses. Agricultural OEMs are adopting SiC modules for 48V and 800V architectures in premium utility platforms. This miniaturization is enabling under-hood packaging densities that accommodate larger battery packs without extending wheelbase.
The EPA's updated emission standards for off-highway vehicles are disqualifying gasoline-powered utility vehicles from federal land management contracts. Equipment lessors are responding by accelerating electric UTV procurement for Bureau of Land Management and National Park Service applications. Western US states with concentrated federal land exposure are showing the steepest diesel-to-electric transition rates.
Fleet managers are consolidating vendor relationships around full-service lease structures that bundle vehicles, charging infrastructure, and predictive maintenance. Traditional equipment financing channels are losing share to captive finance arms of major OEMs. This consolidation is most pronounced among large-scale row-crop operations in the Corn Belt and Central Valley regions.
Electric Utility-Terrain Vehicle (UTV) Market Segmentation
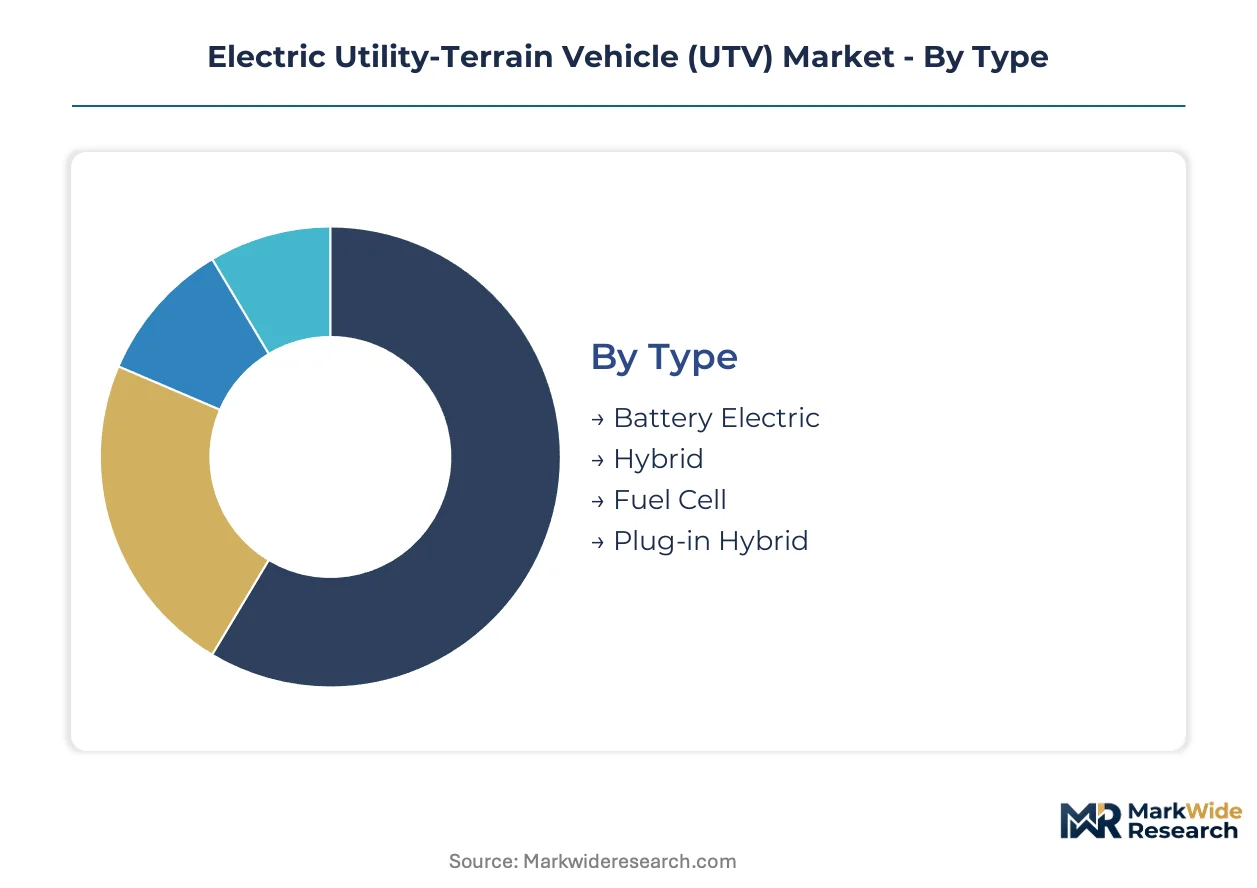
Electric UTV procurement patterns diverge sharply across powertrain architectures and duty cycles. Fleet managers prioritize total cost of ownership calculations that favor specific configurations for agricultural hauling versus recreational trail riding. Understanding these segment boundaries clarifies where lithium-ion pack sizing and motor torque calibration create competitive differentiation.
Type:
Battery electric configurations concentrate margin pools through software-defined thermal management and energy density premiums, while hybrid variants capture value in charging-constrained deployment zones.
- Battery Electric:Pure-electric architectures employ lithium iron phosphate or nickel manganese cobalt cell chemistries in sealed enclosures rated for IP67 ingress protection. Demand clusters in California's Central Valley and Iowa's corn belt where federal clean vehicle incentives intersect with large-scale row-crop operations requiring zero-emission compliance for federal land access.
- Hybrid:Series-parallel hybrid systems combine compact internal combustion range extenders with electric traction motors for remote vineyard and ranch applications lacking grid infrastructure. Australian cattle stations and Brazilian soy operations favor this architecture where diesel generator backup remains necessary for overnight charging.
- Fuel Cell:Proton exchange membrane fuel cell variants utilize compressed hydrogen storage for extended range in sub-zero temperature environments where battery performance degrades.
- Plug-in Hybrid:Larger battery packs than conventional hybrids enable 40-60 kilometer electric-only range for mixed-use fleets transitioning toward full electrification.
Battery electric holds installed capacity. Hybrid is rotating up the share rankings in remote deployment corridors.
End User:
Volume concentration follows agricultural mechanization subsidies and federal grazing land contract specifications, with construction and industrial segments trailing in electrification timelines.
- Agriculture:Crop monitoring, livestock management, and implement towing dominate procurement volumes across cooperative fleets and large-scale family operations. The USDA's Environmental Quality Incentives Program accelerates diesel displacement in the Corn Belt and Pacific Northwest orchard districts.
- Construction:Emission-restricted urban job sites and noise-sensitive residential developments drive electric UTV adoption for material transport and supervisor mobility. OSHA rollover certification requirements slow new model introductions relative to agricultural channels.
- Industrial:Manufacturing facilities and warehouse complexes deploy electric utility vehicles for indoor logistics where exhaust emissions are prohibited.
- Recreation:Trail riding and hunting applications favor electric powertrains for reduced noise signature in wildlife management areas and private reserves.
Agriculture commands current fleet penetration. Construction is climbing the fastest as municipal emission zones expand.
Power Rating:
Cost tier stratification centers on battery pack sizing and motor controller specifications, with mid-range ratings capturing the bulk of commercial utility applications.
- Below 20 HP:Compact lithium-ion packs power light-duty vineyard transport and golf course maintenance where payload requirements stay under 300 kilograms. California's wine country and Florida's resort corridors concentrate demand for these configurations.
- 20-40 HP:Permanent magnet synchronous motors deliver torque curves matching diesel equivalents for tillage implement towing and hay bale transport. This band captures the majority of Midwestern grain operation procurement and European cooperative fleet turnover under F-Gas Regulation mandates.
- 40-60 HP:Larger battery enclosures and liquid-cooled inverters support heavy tillage and loader attachment operations in commercial dairy and feedlot environments.
- Above 60 HP:Premium silicon carbide power electronics and 800V architectures serve specialized applications requiring sustained high-load performance.
20-40 HP holds installed capacity. Below 20 HP is gaining share fastest through precision agriculture specialization.
Application:
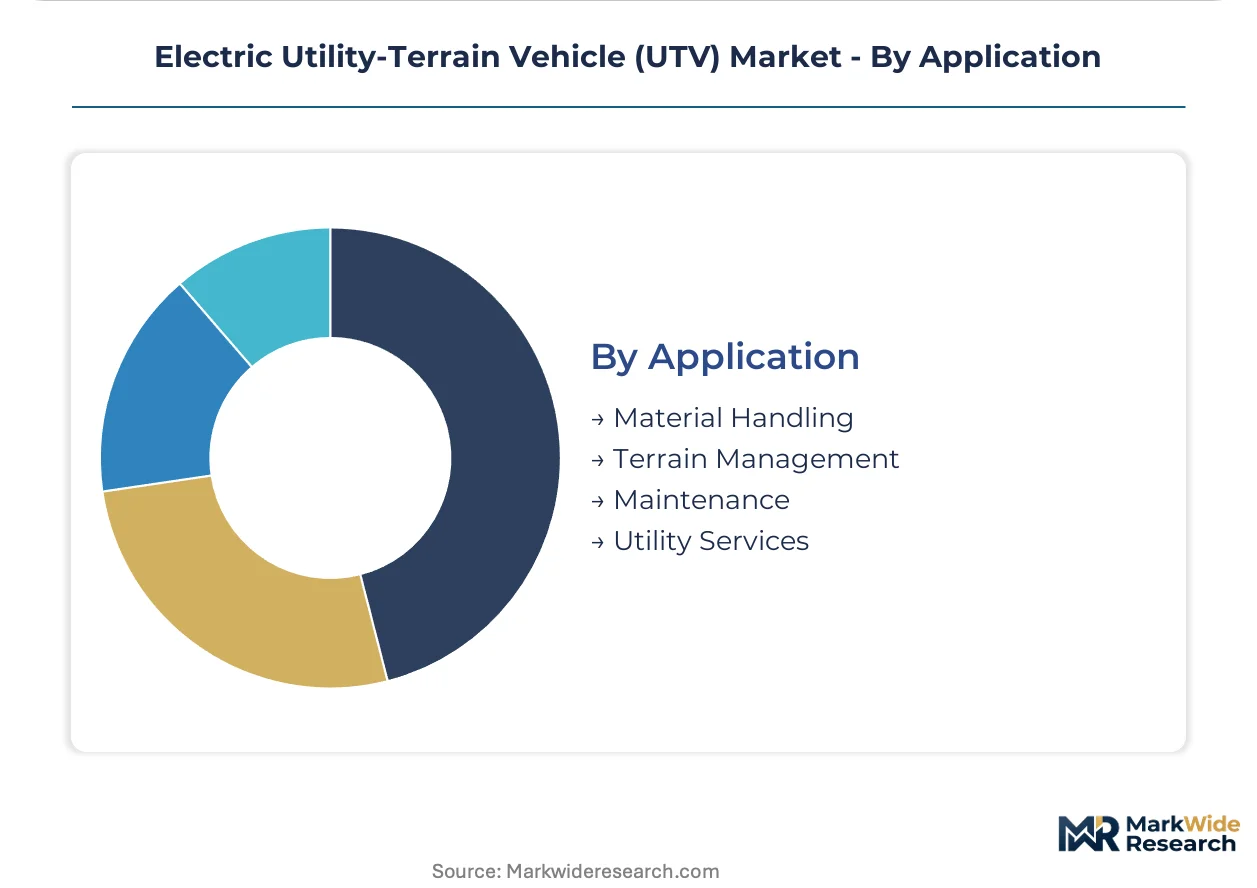
Customer type differentiation separates scheduled maintenance contracts from seasonal harvest intensity, reshaping uptime requirements and battery swap protocol adoption.
- Material Handling:Pallet transport, bulk feed movement, and harvested crop relocation require reinforced cargo beds and hydraulic lift compatibility. Distribution centers in Texas and Illinois prioritize swappable battery architectures for continuous shift operation.
- Terrain Management:Firebreak maintenance, invasive species control, and trail grooming demand aggressive tread patterns and sealed drivetrains for mud and water traversal. US Forest Service contracts in Montana and Idaho specify electric platforms for wilderness area access.
- Maintenance:Facility upkeep and groundskeeping applications favor compact turning radius and reduced noise for campus and estate environments.
- Utility Services:Electrical cooperative line inspection and water district valve maintenance require insulated platforms and tool mounting compatibility.
Material handling holds installed capacity. Terrain management is rotating up the share rankings through federal land contract specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge system and intermodal rail terminals at Chicago and Memphis anchor North American agricultural equipment distribution networks. These transport arteries enable just-in-time battery pack delivery from Midwestern gigafactories to Corn Belt equipment dealers.
United States
USDA Environmental Quality Incentives Program subsidies accelerate diesel displacement across Iowa and Illinois grain operations. The EPA's updated off-highway emission standards bar gasoline UTVs from Bureau of Land Management contracts. California's Central Valley and Pacific Northwest orchard districts concentrate procurement where federal clean vehicle incentives intersect with state-level zero-emission mandates.
Germany
EU F-Gas Regulation diesel phase-out mandates drive cooperative fleet turnover in Bavarian dairy regions. The country's national agricultural regulator enforces strict stability certification for electric platforms used in steep vineyard terrain. Baden-Württemberg's precision agriculture clusters near Stuttgart deploy electric UTVs for autonomous crop monitoring trials.
Australia
Remote cattle stations in Queensland and Western Australia favor hybrid architectures where diesel generator backup remains necessary for overnight charging. The national energy regulator oversees grid connectivity standards for agricultural electrification programs. New South Wales wine country near Hunter Valley pilots swappable battery protocols for continuous harvest operations.
India
State-level farm mechanization subsidies in Maharashtra and Gujarat create first-mover positioning for electric UTV distribution through cooperative networks. The Bureau of Indian Standards develops battery safety certification protocols for tropical operating conditions. Karnataka's precision agriculture technology corridor near Bangalore integrates RTK-GPS steering with electric powertrains for smallholder contract farming.
Brazil
Soy operations in Mato Grosso and Paraná states adopt hybrid systems where grid infrastructure gaps persist across remote plantation zones. The national agricultural regulator monitors rollover protection compliance for electric platforms in hilly coffee regions. São Paulo state's sugarcane mechanization cooperatives trial fuel cell variants for extended-range field applications.
Electric Utility-Terrain Vehicle (UTV) Market Competitive Landscape
Concentration sits with diversified off-road equipment conglomerates and pure-electric specialists. Three structural tiers separate established powersports manufacturers, agricultural machinery incumbents, and venture-backed electric entrants. Tier-one players leverage captive dealer networks and captive finance arms. Tier-two specialists compete on powertrain architecture differentiation. Dominant competitive moves include strategic partnerships for battery supply security and geographic expansion through distributor acquisition.
Among North American-based powersports manufacturers, Polaris Inc. and Textron Specialized Vehicles exemplify the diversified conglomerate archetype with established off-road dealer networks. John Deere anchors the agricultural machinery incumbent tier through farm-equipment brand equity and channel control. Volcon occupies a position within the pure-electric specialist tier focused on rugged terrain powertrain architectures.
| Leading Market Players |
|---|
| Polaris Inc. |
| John Deere |
| Club Car |
| Textron Specialized Vehicles |
| Volcon |
| TUATARA VEHICLES |
| Kaxa Motos |
| Milbay Australia |
| TRACKER OFF ROAD |
| Others |
Pricing and Supply Chain Analysis
Ninety-day battery pack lead times from Midwestern gigafactories concentrate pricing power with OEMs possessing captive cell supply agreements, while spot-market purchasers absorb cobalt and lithium volatility through quarterly contract renegotiations. Fleet procurement committees face divergent total-cost-of-ownership calculations depending on whether their supplier relationships anchor in long-term offtake or transactional spot purchasing.
Pricing Analysis
Volume-discount tiering structures separate enterprise fleet commitments above fifty units from cooperative orders and individual agricultural operators. Pricing stratifies across premium silicon-carbide configurations, standard LFP architectures, and economy-tier lead-acid conversions for light-duty applications. Cost compression in the standard tier intensifies as Chinese cell manufacturers expand into North American distribution. Cooperative fleets in the Corn Belt exhibit highest price sensitivity due to thin operating margins, while federal contractors demonstrate lowest sensitivity given IRA tax credit absorption.
Supply Chain Analysis
Inventory buffers of thirty to forty-five days for power electronics modules reflect just-in-time coordination between Taiwanese semiconductor foundries and Midwestern inverter assembly plants. Cell manufacturing concentrates in China, South Korea, and Nevada's expanding gigafactory corridor. Raw material feeds draw from Chilean lithium brine, Indonesian nickel processing, and Congolese cobalt concentrate. Single-source vulnerability sits with silicon carbide wafer supply from Wolfspeed's New York facility. Distribution runs through John Deere's agricultural dealer network and Polaris's powersports channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as agricultural electrification splits demand between precision-agriculture specialists and commodity haulage operators. The disaggregation of traditional farm-equipment bundling opens white-space for pure-electric powertrain specialists.
For Market Incumbents: Secure captive lithium supply through offtake agreements with Nevada and Australian hard-rock miners before cell cost volatility destabilizes margin structures. Defend dealer channel control by embedding certified high-voltage technicians within rural service networks, countering emerging entrants lacking field-service density.
For New Entrants and Emerging Players: Lead with swappable battery architectures targeting vineyard and orchard operators where seasonal downtime penalties exceed purchase price sensitivity. Penetrate Australian cattle station and Brazilian soy frontier markets through hybrid range-extender configurations that circumvent grid infrastructure gaps. Partner with agricultural cooperative financing arms for equipment-lease bundling.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core off-road vehicle divisions amid electrification capital demands. Long-term viability hinges on software-defined thermal management IP and RTK-GPS integration capabilities rather than legacy manufacturing footprints. Monitor EPA off-highway emission standard enforcement intensity as inflection indicator for federal contract eligibility shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locking in LFP cell supply from Nevada gigafactories secures cost predictability for Corn Belt fleet contracts. |
| Swappable Battery Architecture | Standardized pack formats enable continuous operation in California Central Valley harvest windows. |
| High-Voltage Technician Certification | Rural dealership networks with OSHA-compliant training capture service revenue from electric platform rollouts. |
| RTK-GPS Autonomous Integration | Precision agriculture contracts previously served by manned diesel equipment shift to electric autonomous platforms. |
| Cooperative Finance Partnership | Equipment-lease bundling through Iowa and Illinois agricultural credit unions accelerates fleet turnover. |
Research Methodology
The analysis maps battery electric, hybrid, fuel cell, and plug-in hybrid architectures, each validated through fleet procurement directors, agricultural cooperative managers, OEM platform engineers, and aftermarket service heads. Primary fieldwork combined with secondary validation from EPA off-highway emission filings, USDA Environmental Quality Incentives Program disbursement records, SEC 10-K equipment manufacturer disclosures, and EU F-Gas Regulation implementation tracking. Bottom-up unit shipment estimates triangulated against top-down addressable fleet calculations.
Consistency checks against Bureau of Land Management contract award databases and state-level agricultural electrification subsidy registries validated volume outputs across the projection horizon. Segmentation modeling incorporated powertrain architecture, power rating tier, end-use application, and regional regulatory cluster dimensions. CAGRs derived from fitted adoption curves weighted by incentive program sunset schedules and diesel phase-out mandate timelines. Forecast inputs included lithium carbonate price trajectories and silicon carbide inverter cost-down curves.
Forecasts assume regulatory continuity in EPA off-highway standards and EU F-Gas diesel displacement mandates; material policy reversals would require re-modeling. Battery metal price shocks, grid infrastructure buildout delays, or OSHA certification timeline extensions represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Mining Vehicle Attachments Market
Off Road Vehicles
Off Highway Vehicles Brake Systems Market
Off Road Vehicles
Off-Highway Vehicle Engine Market
Off Road Vehicles
Global Electric Off-Highway Equipment Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market
Off Road Vehicles
Off-Highway Vehicle Market
Off Road Vehicles
Four-Wheel Drive Vehicles Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Off-Highway Vehicle HVAC Market
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
All-Terrain Vehicle Market
Off Road Vehicles
Off Highway Vehicle Lighting Market