
 Automotive Ignition Coil Market | 2026-2036
Automotive Ignition Coil Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Ignition Coil Market Analysis
ISO 26262 functional safety certification is redrawing competitive boundaries in automotive ignition coil supply. Robert Bosch GmbH leverages captive semiconductor and winding capabilities to control high-voltage subsystem integration. DENSO Corporation anchors Asian OEM supply through in-house ferrite core production and thermal management IP. NGK Spark Plug Co. Ltd specializes in precious-metal spark interface technologies that extend coil durability under lean-burn conditions.
An automotive ignition coil is a pulse transformer that converts low-voltage battery current into 15,000–45,000 volts to ionize the air-fuel mixture in combustion chambers, typically wound with copper magnet wire around laminated iron or ferrite cores and impregnated with epoxy for dielectric strength and thermal dissipation. Coil-on-plug configurations now dominate OEM fitment by eliminating spark plug wires and reducing electromagnetic interference, while the aftermarket channel sustains demand for conventional and inductive replacement units across aging vehicle parcs. Inductive ignition leads gasoline applications by volume, though capacitive discharge architectures compete in high-performance and flex-fuel segments where faster spark rise times improve combustion stability.
EPA tailpipe standards and Euro 7 proposals from the European Commission are forcing ignition coil suppliers to demonstrate misfire rates below 0.5% under extended dilute-burn operation, while China's MIIT fuel consumption mandates push domestic OEMs toward higher-energy coil designs. NHTSA defect investigation protocols in the United States create recall exposure that prioritizes traceable manufacturing records and thermal cycle validation. Stakeholders must monitor how electrification timelines in key production jurisdictions reshape the addressable base for spark-ignition components.
Market Dynamics
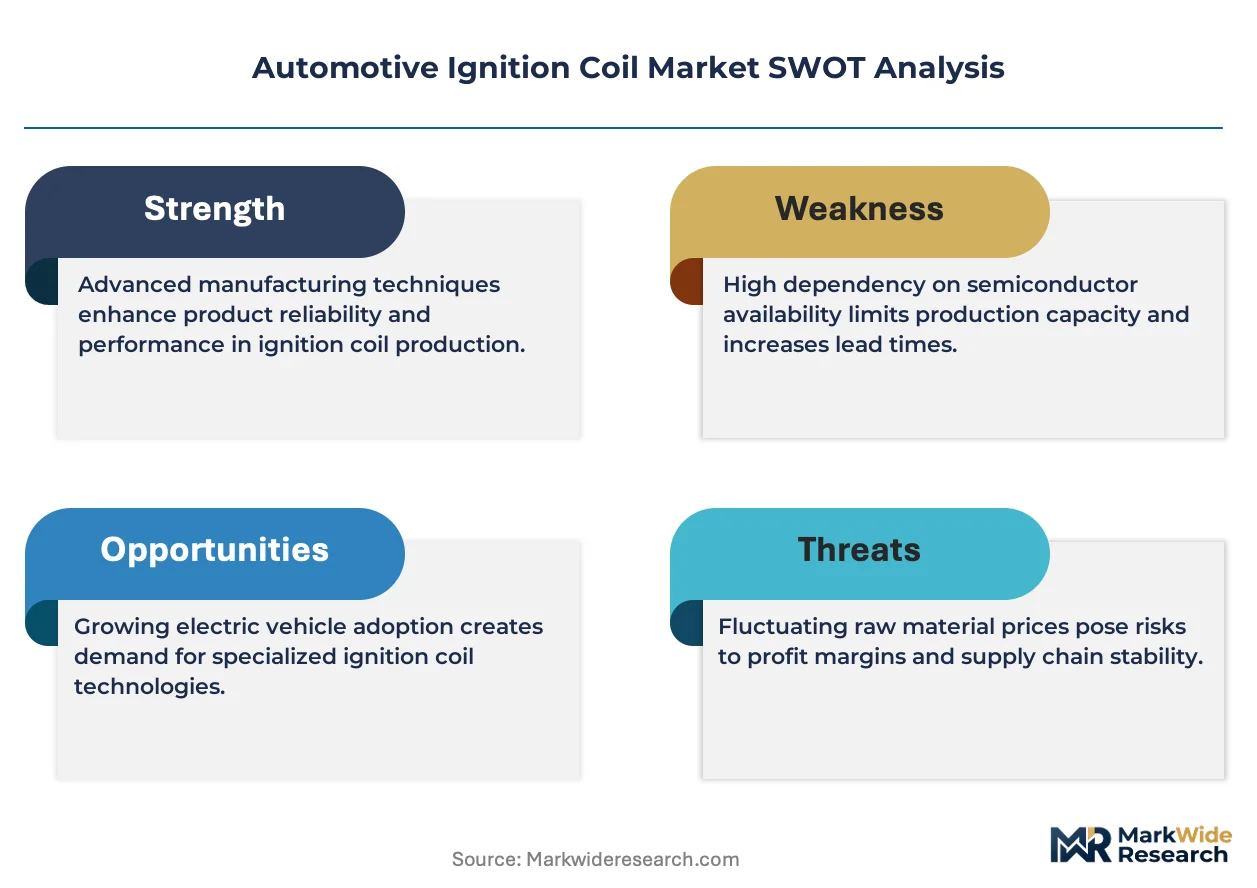
Powertrain electrification timelines are compressing the addressable window for spark-ignition components while simultaneously intensifying performance requirements for remaining internal combustion applications. Suppliers must now optimize coil designs for extended lean-burn operation and higher cylinder pressures without the volume economics of historical mass production.
Growth Catalysts
- EPA Tier 3 and Euro 7 emissions benchmarks:These tightening standards force gasoline engine manufacturers to demand higher spark energy and more precise ignition timing, directly expanding the specification envelope for advanced coil architectures.
- China's sustained ICE production base:Domestic OEMs under MIIT fuel consumption mandates continue to source high-energy coil designs for their large-volume gasoline vehicle programs, sustaining procurement volumes that offset declines elsewhere.
- Ferrite core material advances:Improved magnetic permeability and thermal stability in ceramic ferrite formulations enable smaller coil packages without energy density loss, supporting engine-downsizing trends.
Market Restraints
- Copper magnet wire cost volatility:Raw material price swings in refined copper directly compress manufacturing margins and complicate long-term supply agreements with tier-1 automotive suppliers.
- Powertrain electrification substitution:Battery electric vehicles eliminate spark-ignition systems entirely, eroding the installed base of addressable vehicles in premium European and North American markets.
- Concentrated OEM buyer power:Procurement consolidation among Volkswagen Group, Toyota Motor, and Stellantis NV squeezes component pricing and extends payment terms for ignition coil suppliers.
Strategic Opportunities
- Aftermarket channel digitization:E-commerce platforms and direct-to-installer distribution models bypass traditional parts wholesalers, capturing margin and improving demand visibility for replacement coil inventory.
- Flex-fuel and ethanol-compatible designs:Brazilian ANVISA biofuel mandates and US EPA renewable fuel standards create specification pull for coils engineered to withstand corrosive combustion byproducts in high-ethanol blends.
- India's expanding vehicle parc:BIS automotive safety standards and rising gasoline vehicle ownership in second-tier cities generate replacement demand for conventional inductive ignition systems.
Industry Challenges
- ISO 26262 functional safety certification:Achieving ASIL-D ratings for coil driver electronics demands specialized firmware validation and fault-injection testing capabilities that stretch mid-tier engineering resources.
- Thermal cycle validation infrastructure:Extended durability testing under combined temperature, vibration, and humidity profiles requires capital-intensive environmental chambers that smaller suppliers struggle to fund.
- Legacy vehicle data access:Decoding proprietary engine control unit communication protocols for diagnostic-equipped replacement coils requires reverse-engineering investments with uncertain IP exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Ignition Coil Market |
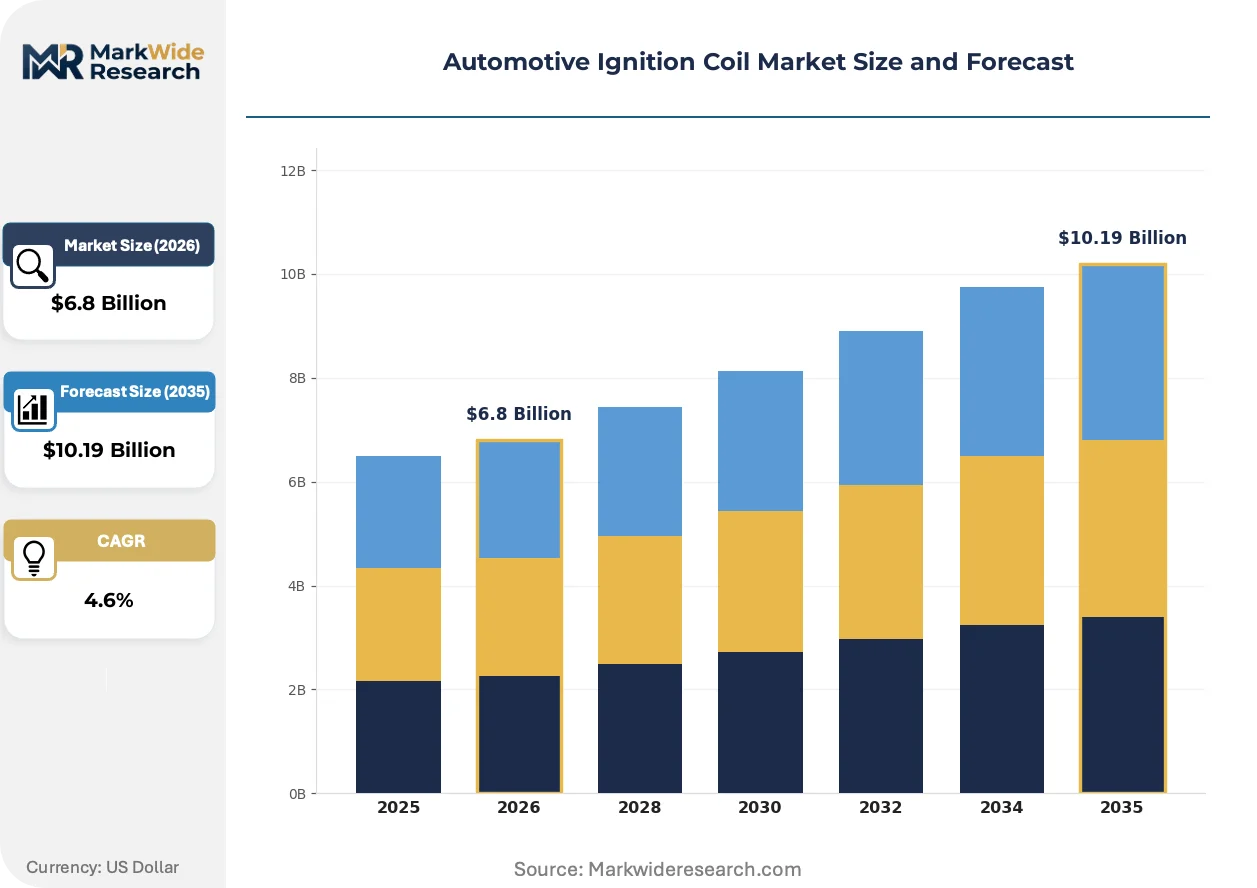
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Capacitive Discharge, Inductive, Coil-On-Plug End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Fuel Type: Gasoline, Diesel, Flex-Fuel, Ethanol Installation Type: Retail, Workshop, Mobile Service, DIY |
| Companies Covered | NGK Spark Plug Co. Ltd, Mitsubishi Electric Corporation, Robert Bosch GmbH, Valeo S.A., HELLA GmbH & Co. KGaA, DENSO Corporation, Hitachi Astemo Ltd, Standard Motor Products Inc., BorgWarner Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Ignition Coil Market Emerging Trajectories
Ignition coil technology is bifurcating between premium integrated designs for downsized turbocharged engines and cost-optimized units for emerging market vehicle programs. Material science and embedded electronics are converging to redefine performance benchmarks.
Multi-spark discharge technology is displacing single-event ignition in high-compression gasoline direct injection engines. BMW Group and Mercedes-Benz AG have adopted these systems for their M and AMG performance divisions. This architecture is displacing conventional inductive coils in the premium segment by enabling multiple spark events per combustion cycle, improving flame kernel development under dilute mixture conditions.
REACH substance restrictions on hexavalent chromium and certain epoxy hardeners are forcing reformulation of coil encapsulation compounds. European coil manufacturers must now qualify alternative dielectric resins that maintain thermal conductivity and moisture resistance without restricted chemical content. The aftermarket segment faces particular disruption as existing inventory must clear compliance deadlines while new formulations undergo revalidation.
Fleet operators and independent repair chains now demand predictive failure diagnostics from replacement ignition components. These buyers specify coils with integrated ion-sensing feedback circuits that communicate misfire detection data to onboard diagnostic systems. North American commercial vehicle fleets and German independent workshop networks are driving this specification shift, prioritizing total cost of ownership over lowest unit price in procurement decisions.
Automotive Ignition Coil Market Segmentation
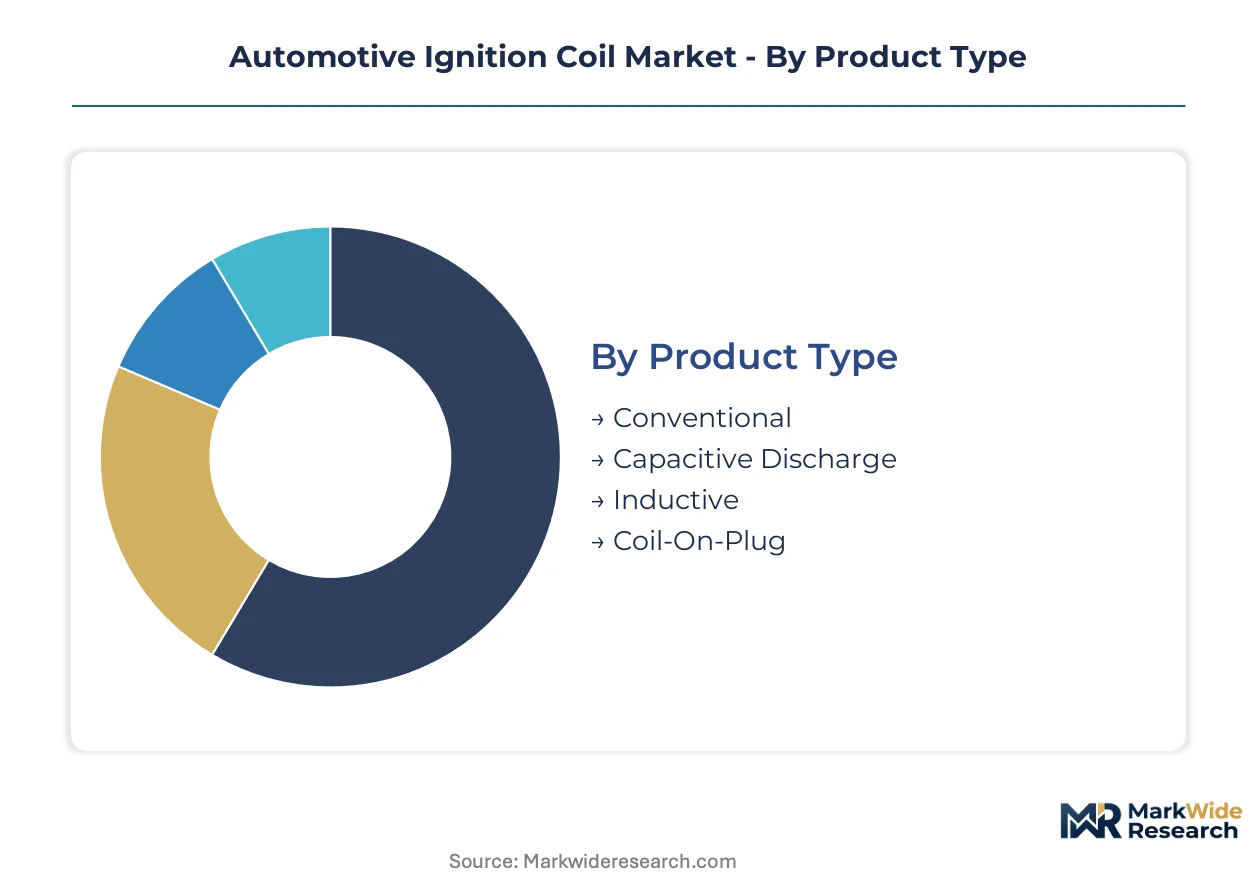
Ignition coil procurement flows through sharply divergent channels depending on segment characteristics. OEMs demand integrated coil-on-plug architectures validated to ISO 26262 standards, while aftermarket channels sustain conventional inductive replacement demand across aging vehicle parcs with shorter specification cycles.
Product Type:
OEM channels favor integrated designs that eliminate spark plug wires, while aftermarket distribution sustains legacy architectures for repair applications.
- Conventional:Wound copper magnet wire around laminated iron cores with epoxy impregnation delivers 15,000–25,000 volt output for distributor-based ignition systems. Demand concentrates in India's BIS-regulated aftermarket and Latin American repair networks where vehicle parc aging outpaces electrification timelines.
- Capacitive Discharge:Rapid voltage rise times of 50–100 nanoseconds improve combustion stability in high-compression engines through stored-energy release mechanisms. Brazilian ANVISA biofuel mandates and US EPA renewable fuel standards pull specification demand for ethanol-tolerant variants in flex-fuel applications.
- Inductive:Standard pulse-transformer architecture dominates gasoline volume through electromagnetic induction in primary and secondary windings.
- Coil-On-Plug:Direct-mount designs eliminate high-tension leads and reduce electromagnetic interference through integrated driver electronics.
By volume, Inductive leads. By growth pace, Coil-On-Plug is expanding most quickly.
End User:
Cost tier stratification separates specification-heavy OEM procurement from price-sensitive independent distribution.
- OEMs:Volkswagen Group, Toyota Motor, and Stellantis NV consolidate procurement through multi-year supply agreements demanding ASIL-D functional safety certification and thermal cycle validation documentation. NHTSA defect investigation exposure prioritizes traceable manufacturing records and lot-level quality data retention.
- Aftermarket Providers:E-commerce platforms and direct-to-installer distribution models bypass traditional parts wholesalers, capturing margin and improving demand visibility for replacement coil inventory across North American and European digital channels.
- Vehicle Assemblers:Contract manufacturers and kit builders source validated subassemblies for specialty and low-volume production programs.
- Repair Shops:German independent workshop networks and North American commercial fleet operators now specify diagnostic-equipped coils with integrated ion-sensing feedback circuits.
By revenue contribution, OEMs dominate. By margin expansion, Aftermarket Providers are gaining share fastest.
Fuel Type:
Application severity determines material specification, with corrosive combustion environments demanding enhanced encapsulation chemistries.
- Gasoline:EPA Tier 3 and Euro 7 emissions benchmarks force manufacturers to demand higher spark energy and more precise ignition timing, directly expanding the specification envelope for advanced coil architectures in direct-injection turbocharged engines.
- Diesel:Compression-ignition architectures require glow plug systems rather than spark ignition, limiting addressable coil demand to dual-fuel and pilot-ignition variants in heavy-duty applications.
- Flex-Fuel:Ethanol-compatible designs withstand corrosive combustion byproducts through reformulated epoxy compounds and precious-metal spark interface technologies.
- Ethanol:High-blend specifications above E85 require enhanced dielectric strength and moisture resistance in coil encapsulation systems.
By installed base, Gasoline leads. By specification intensity, Flex-Fuel shows the steepest expansion trajectory.
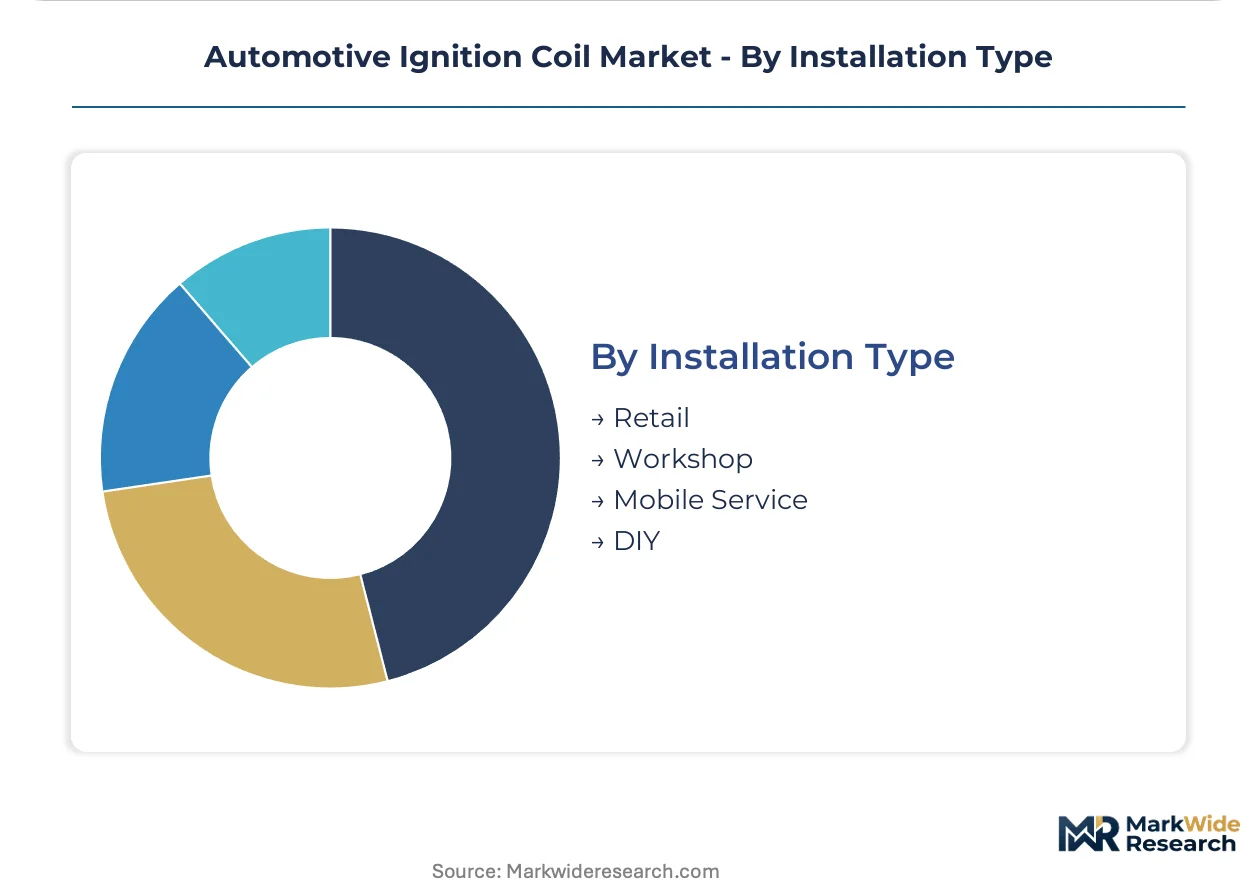
Installation Type:
Customer capability segmentation separates professional workshop demand from consumer-direct procurement channels.
- Retail:Auto parts chains and e-commerce platforms stock replacement coils with standardized connector configurations for consumer pickup, requiring clear interchange data and vehicle identification number matching systems.
- Workshop:EPA-certified repair facilities and Euro 7-compliant service centers demand diagnostic-equipped coils with onboard communication protocols for misfire detection integration.
- Mobile Service:Fleet maintenance operators and roadside assistance providers carry compact inventory ranges covering high-frequency failure applications.
- DIY:Enthusiast segments purchase through specialty retailers with detailed installation documentation and technical support access.
By transaction volume, Workshop leads. By channel growth, Mobile Service is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 3 tailpipe standards and China's MIIT fuel consumption mandates are redirecting procurement flows toward high-energy coil architectures in key production jurisdictions. Germany, China, the United States, Japan, and India sustain the largest addressable bases for spark-ignition components through divergent electrification timelines.
China
Domestic OEMs under MIIT fuel consumption mandates continue sourcing high-energy coil designs for large-volume gasoline vehicle programs. The country's national automotive safety regulator enforces GB standards for electromagnetic compatibility in ignition subsystems. Shanghai and the Yangtze River Delta concentrate captive ferrite core production and thermal management IP development for regional supply chains.
Germany
Volkswagen Group and Mercedes-Benz AG procurement consolidations demand ASIL-D functional safety certification for coil-on-plug architectures. The KBA enforces type approval protocols for spark-ignition components under Euro 7 proposals from the European Commission. Stuttgart and Baden-Württemberg anchor precision winding capabilities and high-voltage subsystem integration for premium powertrain programs.
United States
North American commercial vehicle fleets specify diagnostic-equipped coils with integrated ion-sensing feedback circuits for total cost of ownership optimization. NHTSA defect investigation protocols create recall exposure prioritizing traceable manufacturing records and thermal cycle validation. Detroit and the Midwest manufacturing corridor sustain tier-1 supplier concentration for OEM and aftermarket channels.
Japan
METI industrial policy supports domestic coil suppliers maintaining in-house ferrite core production and precious-metal spark interface technologies. JIS standards govern dielectric strength and moisture resistance specifications for high-compression gasoline direct injection applications. Nagoya and the Chubu region concentrate electromagnetic component manufacturing for Asian OEM supply.
India
Rising gasoline vehicle ownership in second-tier cities generates replacement demand for conventional inductive ignition systems. BIS automotive safety standards regulate coil interchangeability and connector configurations for the aftermarket channel. Maharashtra and the Pune-Nashik industrial belt host contract manufacturers serving domestic and export vehicle programs.
Automotive Ignition Coil Market Vendor Landscape
Listed leaders compete with private specialists across functional safety certification and thermal management IP dimensions. The supplier base concentrates around tier-1 automotive procurement channels with consolidated buyer power extending payment terms. Three archetypes dominate: integrated subsystem specialists with captive semiconductor capabilities, ferrite core manufacturers with in-house winding operations, and aftermarket-focused distributors with diagnostic-equipped replacement portfolios. Competitive moves center on ISO 26262 compliance investments and direct-to-installer channel digitization.
Within the integrated subsystem tier, Robert Bosch GmbH and DENSO Corporation exemplify vertical control over high-voltage electronics and magnetic component manufacturing. NGK Spark Plug Co. Ltd occupies a specialist position anchored in precious-metal technologies for extended durability applications. These three entities represent divergent strategic postures: German engineering-system integration, Japanese materials-science depth, and spark-interface specialization.
| Leading Market Players |
|---|
| NGK Spark Plug Co. Ltd |
| Mitsubishi Electric Corporation |
| Robert Bosch GmbH |
| Valeo S.A. |
| HELLA GmbH & Co. KGaA |
| DENSO Corporation |
| Hitachi Astemo Ltd |
| Standard Motor Products Inc. |
| BorgWarner Inc. |
| Others |
Supply Flow & Price Mechanics
ISO 26262 functional safety certification gates both supplier qualification and price differentiation in the automotive ignition coil market, separating ASIL-D validated coil-on-plug architectures from commodity replacement units. OEM procurement teams at Volkswagen Group and Toyota Motor extend payment terms while demanding thermal cycle documentation, compressing margins for uncertified competitors and concentrating pricing power among integrated subsystem specialists.
Pricing Analysis
Certification level creates the primary spread across the automotive ignition coil market, with ASIL-D validated coil-on-plug designs commanding premium positioning against conventional inductive units. Three-tier pricing structure separates premium integrated architectures from standard OEM replacement coils and economy aftermarket units, with differentiation anchored in thermal management IP and precious-metal spark interface technologies. Pricing pressure stems from copper magnet wire cost volatility and consolidated buyer power among Stellantis NV and other volume purchasers. Fleet operators and German independent workshop networks exhibit lowest price sensitivity, prioritizing diagnostic-equipped coils with ion-sensing feedback circuits over unit cost.
Supply Chain Analysis
Inventory buffers for ferrite core materials and copper magnet wire now stretch to twelve-to-sixteen-week lead times as automotive semiconductor allocation prioritizes powertrain electrification programs. Manufacturing concentrates in China, Germany, and Japan, with Shanghai and the Yangtze River Delta anchoring captive ferrite production and Nagoya concentrating electromagnetic component manufacturing. Raw material dependencies center on refined copper, ceramic ferrite formulations, and epoxy encapsulation compounds. Single-source vulnerability in high-voltage semiconductor drivers for coil-on-plug electronics threatens supply continuity. Distribution runs through tier-1 automotive supplier channels for OEM fitment and direct-to-installer platforms for aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of ASIL-D firmware validation capabilities and thermal cycle testing infrastructure defines competitive boundaries in this market, favoring suppliers with capital-intensive environmental chamber investments and specialized fault-injection engineering teams.
For Market Incumbents: Compound defensive positioning by deepening backward integration into ferrite core production and captive semiconductor winding capabilities, matching Robert Bosch GmbH's high-voltage subsystem control. Extend thermal management IP moats through precision winding investments in Stuttgart and Baden-Württemberg clusters. Prioritize channel digitization to capture aftermarket margin from e-commerce platforms and direct-to-installer networks before emerging distributors consolidate repair shop relationships. For New Entrants and Emerging Players: Aftermarket diagnostic-equipped coil gaps where incumbents under-serve independent repair chains present the most penetrable entry vector. Target North American commercial fleet operators and German workshop networks with ion-sensing feedback circuit specifications that prioritize total cost of ownership over lowest unit price. Pursue flex-fuel and ethanol-compatible design certifications under Brazilian ANVISA mandates and US EPA renewable fuel standards as a differentiated go-to-market anchor. For Investors and Strategic Acquirers: Euro 7 finalization and EPA Tier 3 enforcement timelines reshape the acquisition landscape toward suppliers with validated lean-burn combustion expertise and traceable manufacturing records. Long-term viability favors integrated subsystem specialists with in-house ferrite production and ASIL-D certification completion. Monitor NHTSA defect investigation frequency as an inflection indicator for recall exposure that prioritizes lot-level quality data retention capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | ISO 26262 functional safety validation opens Volkswagen Group and Toyota Motor procurement channels. |
| Ferrite Core Backward Integration | In-house ceramic ferrite production secures magnetic permeability advantages and thermal stability IP. |
| Aftermarket Channel Digitization | Direct-to-installer platforms bypass traditional wholesalers and capture replacement coil margin expansion. |
| Flex-Fuel Design Qualification | Ethanol-tolerant epoxy formulations meet Brazilian ANVISA biofuel mandates and US EPA renewable standards. |
| Thermal Cycle Validation Infrastructure | Capital-intensive environmental chambers differentiate suppliers under NHTSA defect investigation protocols. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and thermal management R&D directors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation from vehicle production databases, IHS Markit registration data, EPA certification filings, and KBA type approval records. Bottom-up coil shipment estimates by product architecture triangulated against top-down gasoline vehicle production forecasts across the analysis window.
Sensitivity analysis tested forecast robustness across electrification acceleration scenarios and copper price volatility bands. The analytical framework modeled segmentation dimensions including propulsion architecture, coil design type, OEM tier positioning, and regional production cluster throughout the forecast period. CAGRs derived from production volume trajectories and content-per-vehicle assumptions for downsized turbocharged engines. Key inputs included MIIT fuel consumption mandate compliance timelines and Euro 7 spark-energy efficiency requirements.
Underlying assumptions cover sustained ICE production in China, India, and select European premium segments, with deviation risk concentrated in battery electric vehicle substitution rates and semiconductor allocation shifts away from ignition electronics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
External Combustion Engine Market
Automotive Parts
Two Speed Gearbox Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
Singapore Passenger Vehicles Lubricants Market
Automotive Parts
Struts System Market
Automotive Parts
Brake Lathe Machine Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
North America Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Coolant Market
Automotive Parts
Global Automotive Timing Belt Market
Automotive Parts
South Korea Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Washer System Market
Automotive Parts
Electromagnetic Clutch System Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market