
 Europe Commercial Vehicles Lubricants Market | 2026-2036
Europe Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Commercial Vehicles Lubricants Market Foresight
Fleet operator consolidation across Central Europe is repositioning procurement power toward large transport networks with centralized lubricant purchasing. TotalEnergies leverages its refinery integration to secure feedstock cost advantages for heavy-duty engine oils. FUCHS anchors its position through specialized mining and construction vehicle lubricants with extended-drain formulations. BP PLC (Castrol) competes by controlling premium distribution channels tied to OEM service networks.
Europe commercial vehicles lubricants are formulated blends of base oils and additive packages engineered to reduce friction, dissipate heat, and protect powertrain components under severe-duty cycles, with viscosities typically ranging from SAE 10W-40 to 15W-40 for heavy-duty diesel engines. Synthetic formulations lead value generation due to longer drain intervals and thermal stability demanded by Euro VI powertrains, while mineral oils retain volume dominance in price-sensitive aftermarket channels. Engine oil commands the largest application share, though hydraulic oil for construction and municipal fleets represents the fastest-growing margin pool as equipment electrification reshapes fluid requirements.
REACH chemicals registration and the EU F-Gas Regulation shape additive chemistry choices and base oil sourcing across European blending plants. ECHA substance restrictions on boron and certain friction modifiers are forcing reformulation investments ahead of sunset dates. ACEA oil sequences and OEM-specific approvals create tiered market access barriers that concentrate premium supply among accredited blenders. Stakeholders must monitor how the EU Green Deal's transport decarbonization targets redirect R&D spending from internal combustion fluids toward e-axle and thermal management lubricants.
Market Dynamics
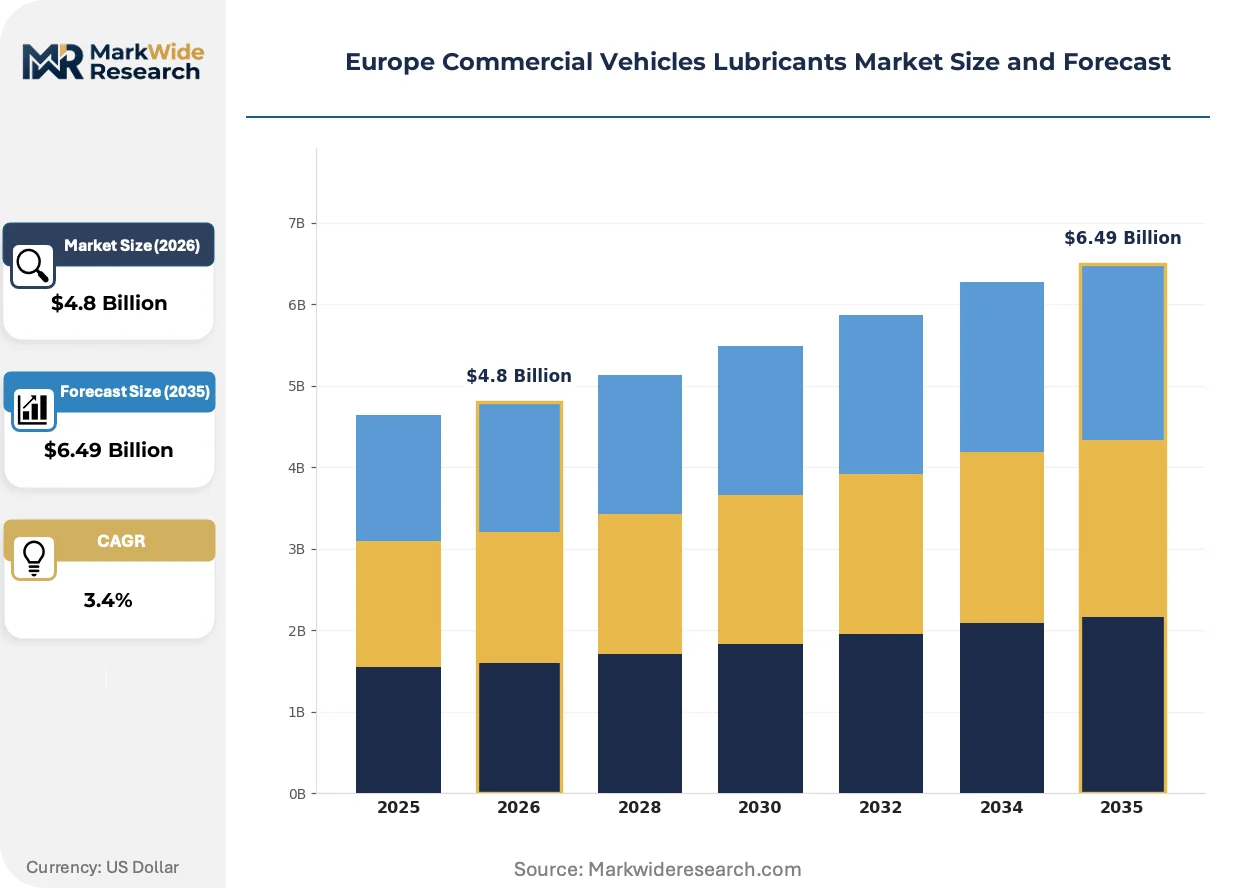
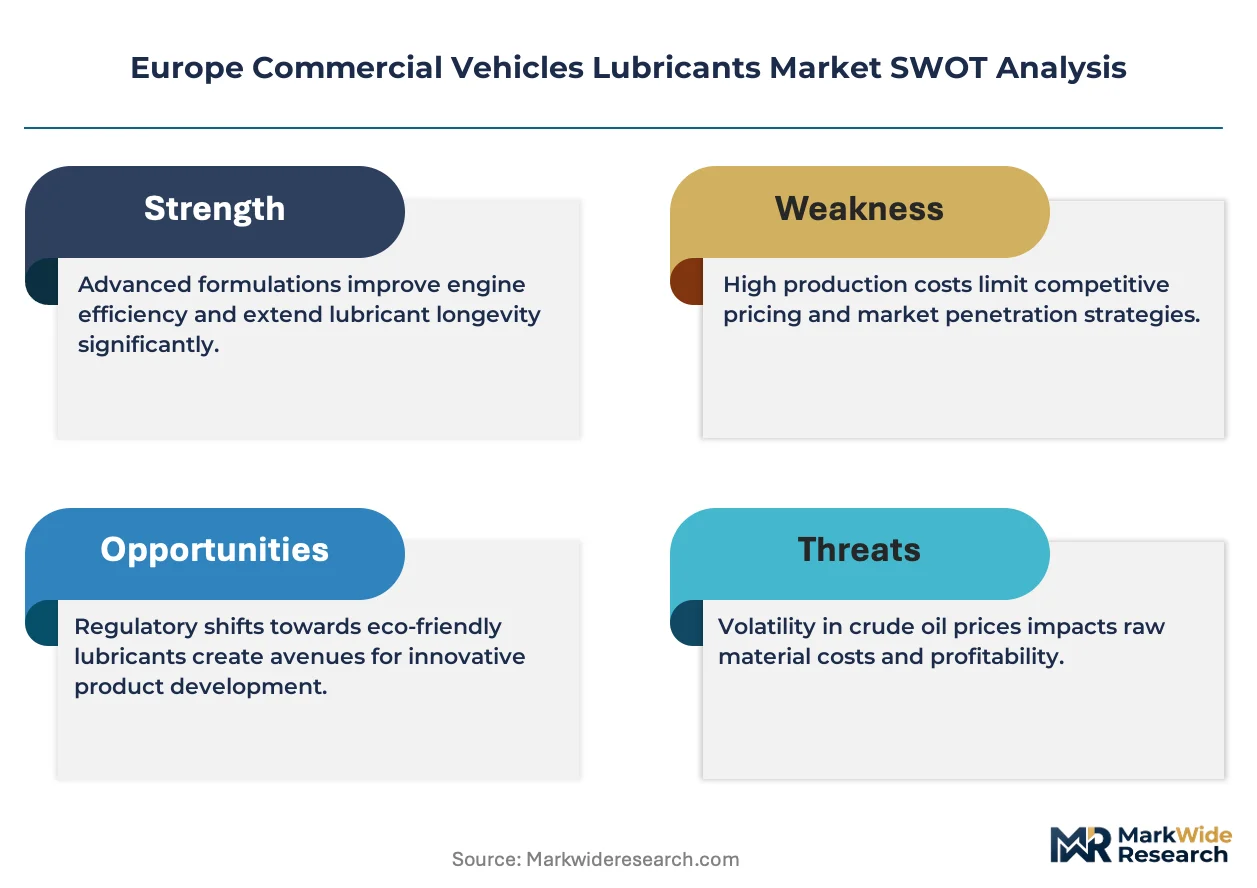
Fleet consolidation across Central Europe is concentrating purchasing power into fewer hands while the EU Green Deal forces accelerated reformulation of additive chemistry. These dual pressures are compressing margins for independent blenders and rewarding integrated suppliers with captive base oil access.
Growth Catalysts
- Extended drain intervals:Fleet operators in Germany and Poland are pushing oil-drain cycles beyond 100,000 kilometers to reduce downtime and labor costs. This drives demand for synthetic formulations with enhanced thermal stability.
- Euro VI powertrain proliferation:Stricter emissions standards require low-SAPS (sulfated ash, phosphorus, sulfur) lubricants compatible with exhaust after-treatment systems. ACEA E6 and E9 sequences now dominate OEM approvals.
- Construction equipment electrification:Hybrid and electric municipal fleets in the Netherlands and Belgium are creating demand for specialized hydraulic fluids and e-axle lubricants with dielectric properties.
Market Restraints
- Base oil supply concentration:European Group II and III base oil production concentrates among integrated refiners in Rotterdam and Antwerp, exposing independent blenders to feedstock cost volatility and allocation constraints.
- ECHA substance restrictions:REACH sunset dates for boron-based friction modifiers and certain zinc dithiophosphates are forcing costly reformulation cycles before alternative chemistries achieve equivalent performance validation.
- Mineral oil price floor:Price-sensitive aftermarket channels in Eastern Europe retain volume preference for mineral formulations, limiting synthetic penetration rates and margin expansion in value-tier segments.
Strategic Opportunities
- Polish freight hub expansion:Silesian logistics corridors are attracting German and Dutch fleet operators seeking lower operating costs, creating demand for localized blending capacity and technical service presence.
- E-axle thermal management fluids:Electric commercial vehicle powertrains require new lubricant categories managing both gear protection and battery thermal regulation, opening formulation white space beyond traditional engine oils.
- CSRD disclosure requirements:The EU Corporate Sustainability Reporting Directive mandates supply chain carbon transparency, creating premium positioning for blenders with certified renewable base oil sourcing and lifecycle documentation.
Industry Challenges
- OEM approval timeline compression:Accelerated Euro VII development schedules are compressing lubricant validation cycles, requiring simultaneous bench testing, field trials, and documentation submission to maintain service-fill positioning.
- Additive package complexity:Reformulation to meet ECHA restrictions while retaining ACEA performance claims demands rare tribochemistry expertise, with qualified formulators concentrated among a handful of European technical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Commercial Vehicles Lubricants Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.49 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Mineral, Bio-Based End User: Fleet Operators, OEMs, Aftermarket Providers, Workshops Application: Engine Oil, Transmission Fluid, Hydraulic Oil, Grease Formulation: Additive Packages, Base Oils, Detergents, Viscosity Enhancers |
| Companies Covered | TotalEnergies, FUCHS, BP PLC (Castrol), Eni SpA, Chevron Corporation, ExxonMobil Corporation, LUKOIL, Repsol, Royal Dutch Shell Plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Commercial Vehicles Lubricants Market Shifts & Advancements
Additive technology convergence and regulatory chemistry restrictions are forcing simultaneous evolution across formulation science, supply chain transparency, and fleet procurement models. Three developments are restructuring competitive advantage.
Multi-functional additive packages are unifying dispersant, antioxidant, and anti-wear functions into single-molecule architectures. Blenders serving Volvo and Scania service networks are adopting these chemistries fastest, compressing the traditional four-to-six additive component slate into two-to-three core building blocks that simplify blending logistics and reduce batch variability.
REACH authorization procedures are tightening scrutiny of persistent, bioaccumulative, and toxic substances in lubricant formulations. The industrial consequence is accelerated substitution of traditional extreme-pressure additives with ionic liquid alternatives, particularly affecting gear oils for mining and construction equipment where load-carrying capacity cannot degrade during transition.
Centralized fleet procurement departments are consolidating lubricant purchasing across multi-country networks, displacing decentralized garage-level ordering. Large German and Polish transport operators now negotiate framework agreements directly with blenders, bypassing traditional distributor channels and demanding integrated fluid analysis services as contract inclusions.
Europe Commercial Vehicles Lubricants Market Segmentation
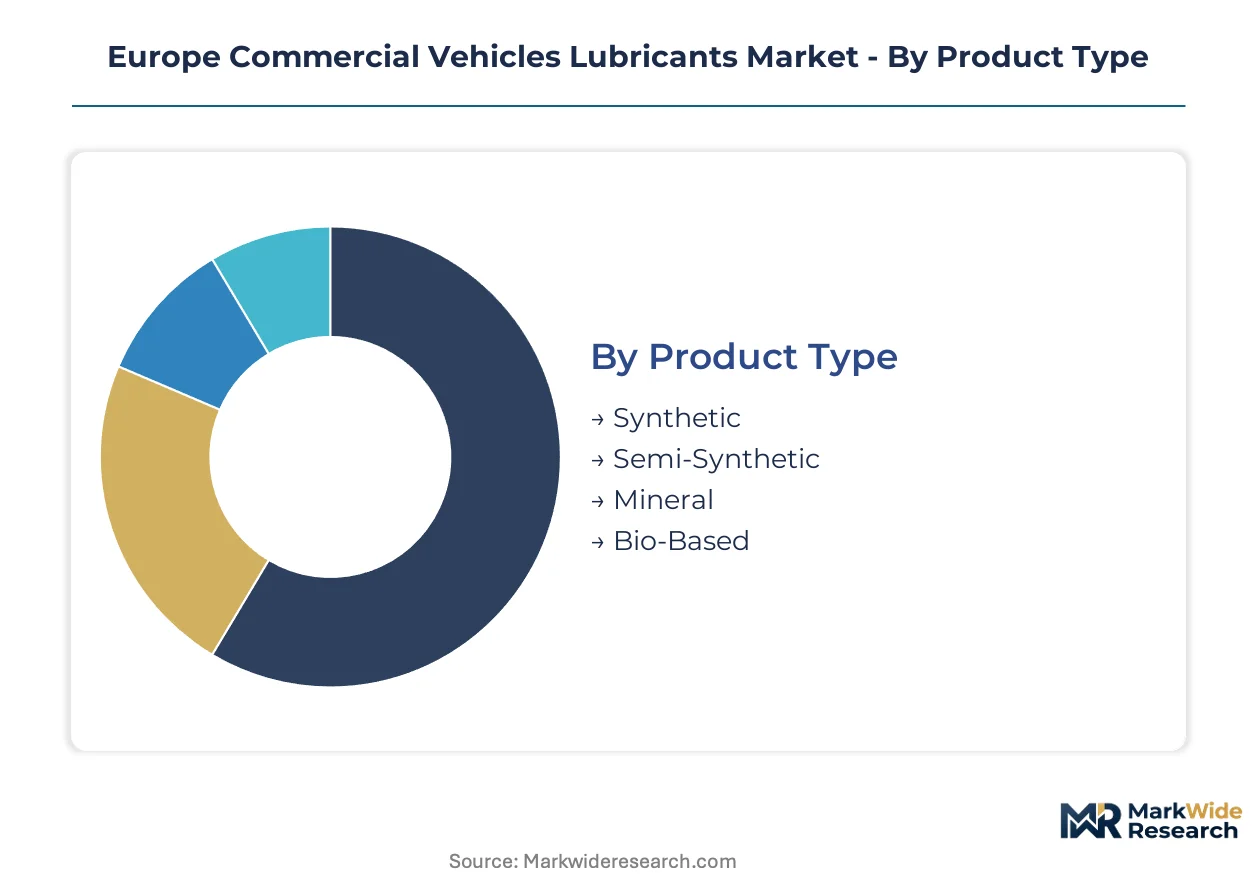
Segmentation in Europe's commercial vehicles lubricants market reveals how procurement power, regulatory compliance, and equipment electrification reshape product positioning. Understanding these divides exposes where margin concentrates and where volume defends.
Product Type:
Cost tier determines access to extended-drain formulations and OEM approval pathways across European fleet procurement.
- Synthetic:Formulated from Group III and PAO base stocks with engineered additive architectures delivering thermal stability beyond 150°C. German long-haul operators running Euro VI powertrains concentrate demand here, driven by 100,000+ kilometer drain intervals that compress total cost of ownership despite 40-60% price premiums over mineral alternatives.
- Semi-Synthetic:Blends Group I/II mineral bases with 20-30% synthetic content, occupying the value-performance midpoint. Polish and Czech regional fleet operators favor this tier where OEM warranty compliance matters but full synthetic economics fail to justify.
- Mineral:Refined petroleum distillates with conventional additive packages dominate Eastern European aftermarket channels where price sensitivity overrides drain-interval optimization.
- Bio-Based:Estolide and vegetable-derived formulations meeting EU Ecolabel criteria serve municipal contracts in the Netherlands and Belgium with mandatory renewable content thresholds.
Synthetic leads on scale; bio-based climbs the fastest on regulatory procurement mandates.
End User:
Procurement centralization restructures how lubricant suppliers access commercial vehicle operators across the value chain.
- Fleet Operators:Consolidated transport networks with 500+ vehicle fleets now negotiate direct framework agreements, displacing traditional distributor relationships. Rhine-Ruhr and Silesian logistics corridors concentrate this buyer power, with technical service and fluid analysis bundled as contract requirements.
- OEMs:Volvo, Scania, and MAN service-fill positioning demands simultaneous ACEA sequence compliance and proprietary factory-fill approvals, creating accreditation barriers that filter supplier pools.
- Aftermarket Providers:Independent distributors and parts retailers serve fragmented owner-operator segments across Southern and Eastern Europe where garage-level purchasing persists.
- Workshops:Authorized service networks and independent repair facilities represent the final consumption node, with technician training and bulk storage infrastructure determining brand loyalty.
Fleet operators lead on scale; OEMs lead on margin capture through captive service networks.
Application:
Equipment electrification redraws fluid demand profiles beyond traditional engine-centric formulations.
- Engine Oil:Heavy-duty diesel formulations commanding 60-70% of market value, with ACEA E6/E9 low-SAPS specifications now mandatory for Euro VI compliance and exhaust after-treatment protection across German and Polish long-haul operations.
- Hydraulic Oil:Construction and municipal equipment fluids represent the steepest expansion trajectory as hybrid excavators and electric refuse trucks in Belgium and the Netherlands demand dielectric properties combined with wear protection.
- Transmission Fluid:Automated manual and dual-clutch transmissions require friction-modified formulations with extended oxidation stability, particularly in Scania and MAN powertrain service networks.
- Grease:Lithium complex and calcium sulfonate thickeners serve chassis, wheel bearing, and fifth-wheel applications where water resistance and mechanical stability outweigh thermal demands.
Engine oil leads on scale; hydraulic oil leads on momentum from construction electrification.
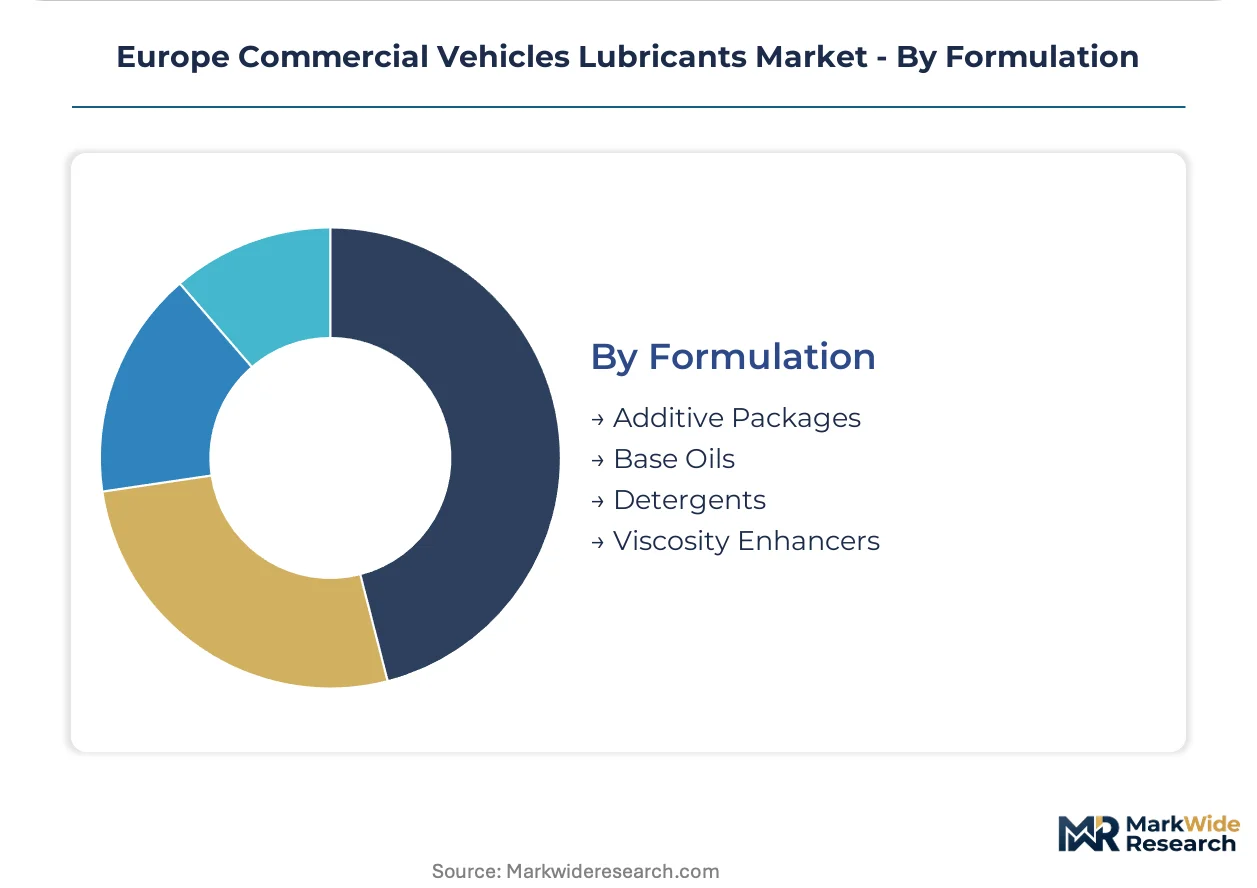
Formulation:
REACH authorization deadlines and ACEA performance evolution force simultaneous chemistry substitution and performance retention.
- Additive Packages:Multi-functional single-molecule architectures unifying dispersant, antioxidant, and anti-wear roles reduce blending complexity. ECHA sunset dates for boron-based friction modifiers and certain ZDDP variants accelerate reformulation investment among European technical centers.
- Base Oils:Group II and III supplies concentrate among integrated refiners in Rotterdam and Antwerp, with Group III+ commanding premium positioning for synthetic formulations serving OEM service-fill contracts.
- Detergents:Calcium and magnesium sulfonate overbased complexes neutralize combustion acids in extended-drain applications, with low-ash variants required for diesel particulate filter compatibility.
- Viscosity Enhancers:Olefin copolymer and polymethacrylate modifiers enable SAE 10W-40 and 5W-30 multigrade performance for cold-start protection across Nordic operations.
Base oils lead on scale; additive packages lead on technical differentiation through regulatory-driven reformulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany generates higher synthetic lubricant demand per fleet vehicle than Poland, yet Polish freight corridors are expanding blending capacity faster to capture cross-border logistics migration.
Germany
Long-haul operators along the Rhine-Ruhr corridor push drain intervals past 100,000 kilometers to minimize downtime. The EU Green Deal mandates transport decarbonization timelines that accelerate low-SAPS formulation adoption. Stuttgart-based OEM service networks concentrate factory-fill approvals for ACEA E6/E9 sequences.
Poland
Silesian logistics hubs attract German and Dutch fleet operators seeking lower operating costs. REACH authorization deadlines for boron-based friction modifiers force reformulation investments at local blending facilities. Warsaw and Łódź distribution centers are adding bulk storage infrastructure for centralized procurement contracts.
Netherlands
Hybrid municipal fleets in Rotterdam and Amsterdam demand dielectric hydraulic fluids for electric refuse trucks. The CSRD mandates supply chain carbon transparency that favors blenders with renewable base oil certification. Port of Rotterdam refining clusters control Group II and III base oil allocation across Northwest Europe.
Belgium
Construction equipment electrification in Flanders drives specialized e-axle lubricant testing programs. The EU F-Gas Regulation shapes thermal management fluid chemistry choices for battery-powered commercial vehicles. Antwerp petrochemical complexes supply feedstock to accredited blenders serving OEM service networks.
France
Regional fleet operators in Île-de-France negotiate framework agreements that bundle fluid analysis with lubricant supply. ECHA substance restrictions on zinc dithiophosphates accelerate additive package substitution at Lyon technical centers. Marseille logistics corridors are upgrading to synthetic formulations for Mediterranean cross-border routes.
Europe Commercial Vehicles Lubricants Market Competitive Landscape
French and German producers anchor the integrated refiner tier; independent specialists in Central Europe hold formulation flexibility advantages. The market structures around three player categories: integrated majors with captive base oil supply, independent blenders with technical service differentiation, and regional distributors serving fragmented aftermarket channels. Strategic moves concentrate on refinery integration into base oil production and direct framework agreements with consolidated fleet operators.
Within the integrated major tier, TotalEnergies and Royal Dutch Shell Plc exemplify players leveraging Rotterdam and Antwerp refining positions to secure feedstock cost structures. BP PLC (Castrol) occupies a position emphasizing premium distribution channels tied to OEM service networks. These three represent distinct archetypes: refinery-integrated supply security, premium channel control, and service-network captive positioning.
| Leading Market Players |
|---|
| TotalEnergies |
| FUCHS |
| BP PLC (Castrol) |
| Eni SpA |
| Chevron Corporation |
| ExxonMobil Corporation |
| LUKOIL |
| Repsol |
| Royal Dutch Shell Plc |
| Others |
Supply & Pricing Matrix
Rotterdam Brent crude differentials and Group III base oil spot indices cascade through European blending economics, compressing margin structures for independent formulators while rewarding integrated refiners with captive feedstock access. ACEA sequence certification costs and REACH reformulation investments layer onto raw material volatility, stratifying pricing power across synthetic, semi-synthetic, and mineral tiers.
Pricing Analysis
Capacity additions in Antwerp and Rotterdam refining clusters are reshaping price floors for Group II and III base oils, easing feedstock pressure on synthetic formulations while mineral alternatives face margin compression from Eastern European aftermarket competition. Three-tier pricing structure across premium, standard, and economy levels separates OEM-approved synthetics with extended-drain warranties from semi-synthetics serving Polish regional fleets and mineral oils dominating price-sensitive garage channels. Pricing pressure stems from fleet procurement centralization demanding bundled fluid analysis services at contract rates. Owner-operators across Southern Europe exhibit highest price sensitivity; German long-haul networks with total-cost-of-ownership modeling show lowest.
Supply Chain Analysis
ACEA E6/E9 and OEM-specific factory-fill approvals function as qualification gates that filter supplier pools to accredited blenders with validated test protocols and field trial documentation. Geographic supply concentrates in Netherlands, Belgium, and Germany where Rotterdam-Antwerp refining corridors control Group II and III base oil allocation. Raw material dependencies span PAO feedstocks, calcium sulfonate detergents, and zinc dithiophosphate anti-wear chemistries facing ECHA sunset constraints. Single-source vulnerability runs through boron-based friction modifier substitution timelines. Distribution runs through direct framework agreements with consolidated fleet operators, displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polish freight corridor expansion against German operating cost differentials creates geographic-arbitrage positioning for blending capacity and technical service investment.
For Market Incumbents: Cement refinery integration advantages by securing Group III+ base oil allocation for OEM service-fill contracts while accelerating REACH-compliant additive package validation ahead of ECHA sunset dates. Threat from centralized fleet procurement demanding price transparency compresses distributor margins; lever fluid analysis bundling and lifecycle documentation to defend contract positioning. For New Entrants and Emerging Players: EU Green Deal transport decarbonization targets in Netherlands and Belgium open a window for e-axle thermal management fluid development beyond traditional engine oil categories. Most penetrable white space sits in dielectric hydraulic oils for hybrid municipal fleets; target construction equipment electrification programs in Flanders with specialized formulation partnerships. For Investors and Strategic Acquirers: Consolidation pressure builds where independent blenders lack captive base oil supply and face simultaneous REACH reformulation and ACEA validation cost burdens. Long-term viability favors technical-service-differentiated regional specialists with accredited laboratory infrastructure and existing OEM relationships. Signal to watch: framework agreement announcement velocity from Silesian logistics operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive Group III supply secures cost structures against Rotterdam spot volatility for ACEA-accredited blenders. |
| E-Axle Lubricant Formulation Development | Dielectric thermal management fluids address Volvo and Scania electric powertrain service-fill requirements. |
| REACH-Compliant Additive Package Investment | Ionic liquid substitution for boron friction modifiers maintains mining equipment load capacity through regulatory transition. |
| Direct Fleet Framework Agreements | Centralized procurement contracts with Rhine-Ruhr operators displace distributor channels and capture volume commitments. |
| CSRD-Aligned Lifecycle Documentation | Certified renewable base oil sourcing meets EU Corporate Sustainability Reporting Directive supply chain transparency mandates. |
Research Methodology
Multiple input streams — blending plant technical directors, fleet procurement managers at consolidated transport networks, OEM lubricant specification engineers, and aftermarket distribution channel partners — were reconciled against customs trade data, ACEA oil sequence documentation, ECHA substance restriction filings, and refinery capacity disclosures. Secondary validation drew from SEC filings of integrated majors, European base oil trade flow databases, and municipal fleet electrification procurement records. Bottom-up volume modeling across product tiers and end-user segments was cross-checked against top-down market sizing from feedstock demand indicators.
Historical pricing trajectories for Group II and III base oils were cross-referenced against panel input from procurement leads to anchor volume and value projections across the analysis window. Segmentation dimensions modeled include product type tier, end-user procurement centralization level, application fluid category, and formulation chemistry compliance status. CAGRs were derived from trend extrapolation of drain interval extension rates and synthetic penetration curves, calibrated against Euro VI and emerging Euro VII powertrain adoption timelines.
Revisions become necessary when ECHA accelerates substance restriction timelines, ACEA introduces new oil sequences ahead of Euro VII implementation, or base oil refinery outages disrupt Rotterdam-Antwerp supply allocation. Forecasts reflect assumptions about fleet consolidation velocity and electrification penetration in municipal segments. A model refresh is warranted upon material change in EU Green Deal transport decarbonization enforcement schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
United States Passenger Vehicles Lubricants Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
France Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Propeller Shaft Market
Automotive Parts
North America Automotive Parts Die Casting Market
Automotive Parts
Global Automotive Hydraulics System Market
Automotive Parts
Bumper Beam Market
Automotive Parts
Automotive Viscosity Index Improvers Market
Automotive Parts
Tow Bar Market
Automotive Parts
Automotive Proportioning Valves Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
Tappet Market
Automotive Parts
Global Automotive Nitrous Oxide System Market
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Automotive Wheel Speed Sensor Tone Ring Market
Automotive Parts
Automotive Electric Water Pump Market