
 Automotive Differential Housing Market | 2026-2036
Automotive Differential Housing Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Differential Housing Market Analysis
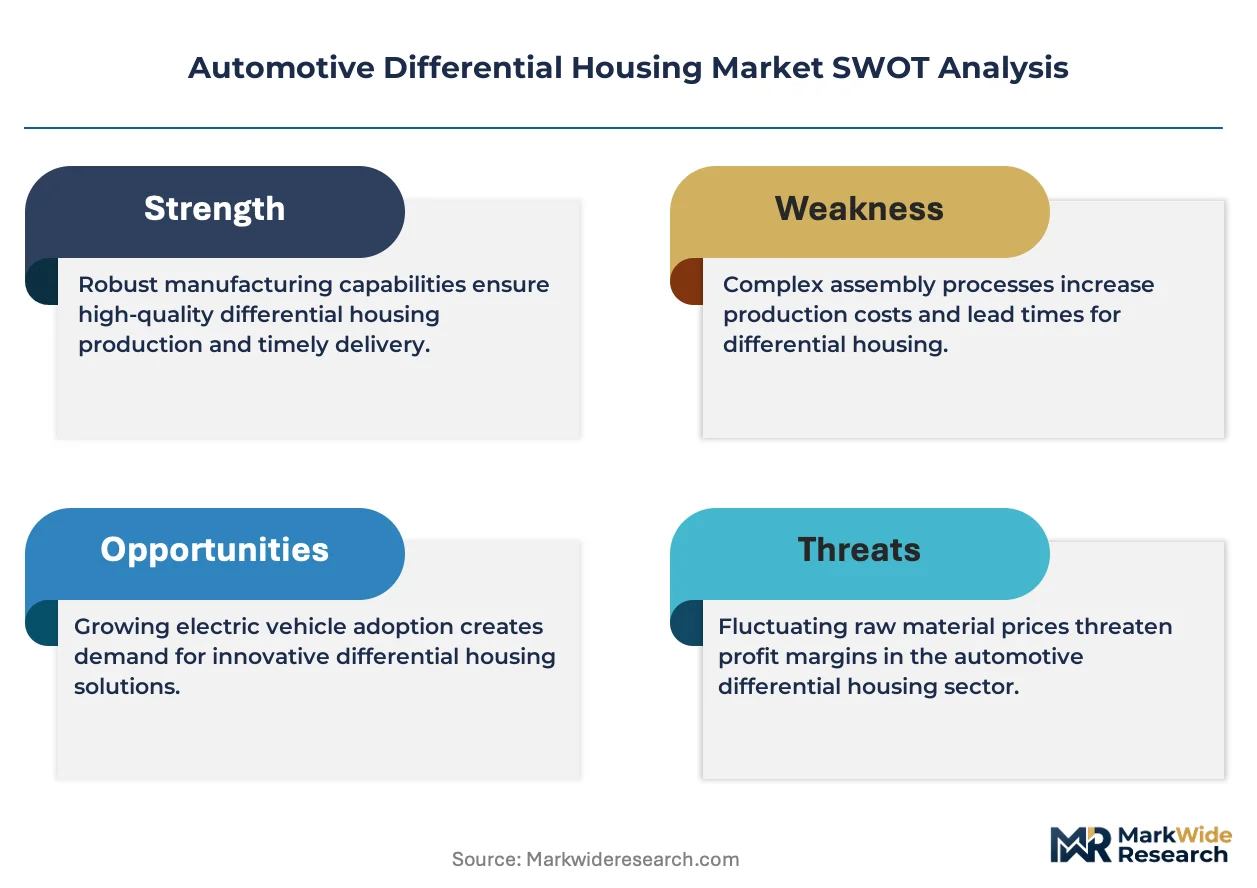
High-strength aluminum alloy specifications for electric vehicle differential housings is collapsing the cost gap with traditional steel castings. Dana Incorporated leverages captive foundry capacity in North America to secure OEM contracts for lightweight axle modules. GKN Automotive Limited anchors European supply through its powder-forging expertise in torque-vectoring housings. ZF Friedrichshafen competes on integrated e-axle systems where the differential housing merges with the electric motor casing.
An automotive differential housing is a structural enclosure that contains the gear set distributing torque between drive wheels, typically cast from aluminum A356-T6 or ductile iron GGG-50 with wall thicknesses of 4-8 mm and fatigue life targets exceeding 500,000 cycles. Its primary purpose is to protect precision-machined hypoid or planetary gears from contamination while maintaining rigid alignment under torsional loads up to 10,000 Nm. Limited-slip and torque-vectoring differentials command premium pricing due to complex housing geometries that accommodate clutch packs and multi-pinion gear sets. Electric vehicle applications favor aluminum and magnesium material segments for mass reduction, while steel retains dominance in heavy commercial vehicles where impact resistance governs specification.
NHTSA Corporate Average Fuel Economy rules and EPA greenhouse gas standards in the United States penalize drivetrain weight, directly accelerating aluminum and magnesium substitution in differential housings. The EU Green Deal and REACH restrictions on heavy metals constrain coating and surface treatment processes for European-sourced castings. Stakeholders must monitor how battery-electric platform architectures eliminate mechanical differentials entirely in favor of dual-motor torque distribution, reshaping long-term housing demand.
Market Dynamics
The electric vehicle platform transition is compressing mechanical differential demand while simultaneously elevating material specifications for remaining housings, as dual-motor torque distribution eliminates the component entirely from some axle architectures.
Growth Catalysts
- Aluminum A356-T6 specification:High-strength aluminum alloy castings satisfy NHTSA Corporate Average Fuel Economy weight penalties while maintaining fatigue life targets exceeding 500,000 cycles for electric vehicle axle modules.
- EU Green Deal industrial policy:REACH restrictions on heavy metals accelerate coating process innovation for European-sourced differential housings, favoring suppliers with advanced surface treatment capabilities.
- Germany:Precision casting and forging clusters anchored by ZF Friedrichshafen AG, GKN Automotive, and Dana Incorporated concentrate OEM supply chain access for torque-vectoring and limited-slip differential architectures.
Market Restraints
- Primary aluminum price volatility:London Metal Exchange aluminum pricing fluctuations compress foundry margins on fixed-price OEM contracts for A356-T6 alloy castings.
- Supply concentration in Baden-Württemberg:German automotive component clusters create geographic risk exposure for European OEMs dependent on single-region forging and precision casting capacity.
- Battery-electric platform substitution:Dual-motor electric vehicle architectures eliminate mechanical differentials entirely, threatening long-term housing demand in passenger vehicle segments.
Strategic Opportunities
- Commercial vehicle steel retention:Heavy truck and off-highway segments where impact resistance governs specification offer durable demand for ductile iron GGG-50 housings resistant to aluminum substitution.
- Integrated e-axle housing convergence:Merging differential enclosures with electric motor casings creates design white space for suppliers with multi-material joining and thermal management expertise.
- India automotive production expansion:PLI scheme incentives for electric vehicle manufacturing attract housing suppliers capable of localized aluminum casting capacity.
Industry Challenges
- Powder-forging talent scarcity:Torque-vectoring housing geometries requiring clutch pack accommodation demand specialized metallurgists and process engineers concentrated at limited European and North American facilities.
- Multi-material joining certification:Integrated e-axle designs combining aluminum housings with steel gear carriers extend OEM validation timelines and testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Differential Housing Market |
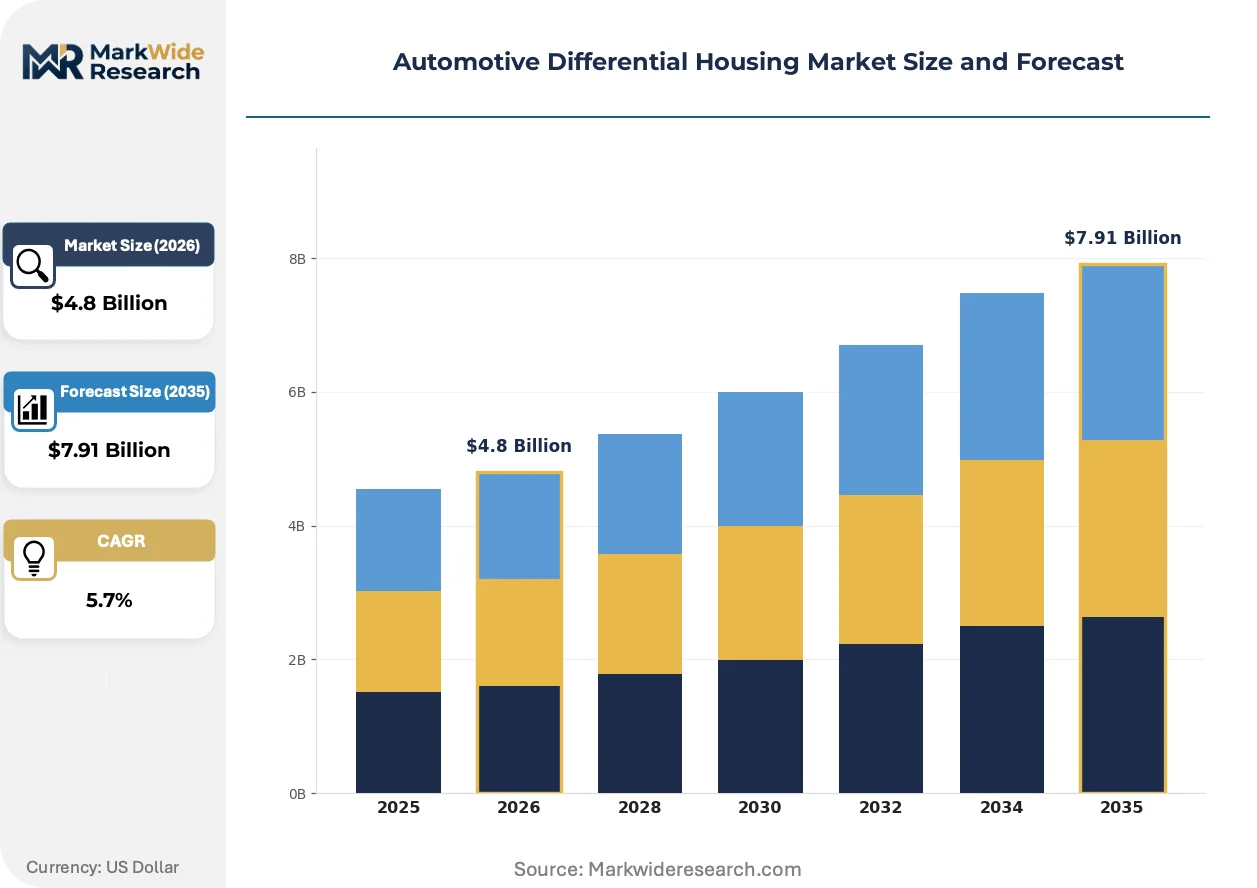
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Differential, Limited-Slip Differential, Torque-Vectoring Differential, Electronic Differential Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, SUVs Material: Aluminum, Steel, Composite, Magnesium Manufacturing Process: Casting, Machining, Forging, Additive Manufacturing |
| Companies Covered | ZF Friedrichshafen AG, Dana Incorporated, GKN Automotive Limited, Eaton Corporation plc, American Axle & Manufacturing, Inc., BorgWarner Inc., Linamar Corporation, JTEKT Corporation, Meritor, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Differential Housing Market Emerging Trajectories
Material science advances and regulatory weight mandates are actively restructuring differential housing specifications, with aluminum alloys displacing traditional ferrous castings in passenger applications while manufacturing processes adapt to integrated electric drivetrain architectures.
High-pressure die-cast aluminum A356-T6 is bifurcating the passenger vehicle differential housing market from heavy commercial segments. Electric vehicle manufacturers specify this alloy for axle modules where mass reduction directly extends range, while steel retains specification in heavy trucks where impact resistance governs procurement decisions. This material split is compressing foundry investment into aluminum-dominant capacity for light vehicle supply and ferrous-specialized capacity for commercial applications.
EPA greenhouse gas standards and NHTSA fuel economy rules are tightening material and weight requirements for drivetrain components in the United States. These regulations penalize mass directly, accelerating aluminum and magnesium substitution in differential housings for light-duty vehicles. OEMs respond by consolidating supplier relationships with foundries capable of thin-wall casting at 4-8 mm thicknesses while maintaining torsional rigidity under loads up to 10,000 Nm.
Buyer specifications now prioritize integrated thermal management and electromagnetic shielding in housing designs for electric vehicle applications. Procurement teams at battery-electric platform developers specify multi-functional enclosures that combine differential gearing with inverter mounting and cooling circuit integration. This specification evolution is most visible in German and South Korean OEM supply chains where e-axle architectures are standardizing fastest.
Automotive Differential Housing Market Segmentation
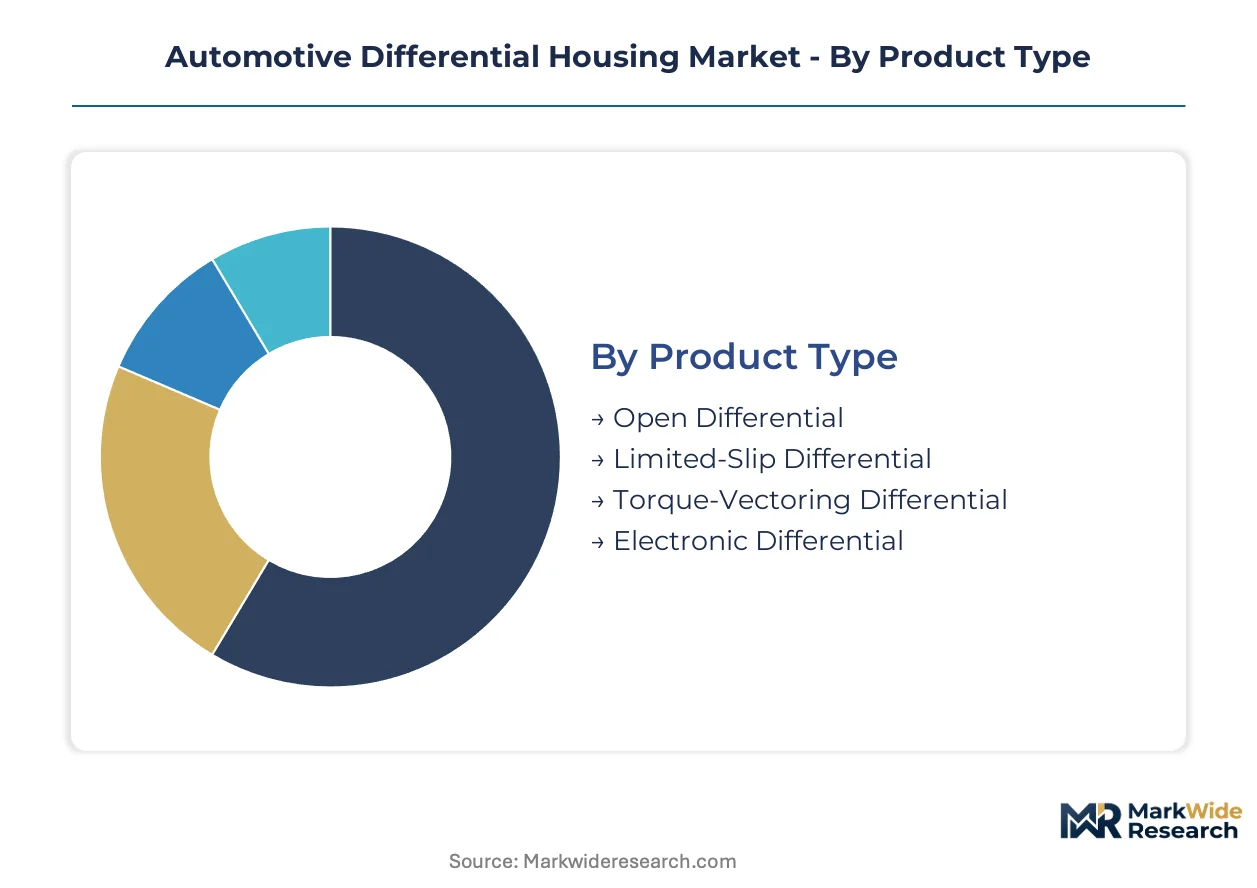
Differential housing procurement patterns diverge sharply across vehicle architectures, with electric platforms favoring aluminum precision castings while commercial fleets retain ductile iron specifications. Material selection and manufacturing process choices now determine supplier qualification timelines more than geometric complexity alone.
Product Type:
Open differential specifications dominate domestic OEM supply chains in North America and Europe, while torque-vectoring and electronic variants concentrate in export-led premium vehicle programs from Germany and Japan.
- Open Differential:Conventional bevel gear enclosures serve mass-market front-wheel-drive and rear-wheel-drive axles with standardized hypoid gear interfaces. Procurement concentrates at Detroit Three and Volkswagen Group assembly plants where cost-per-unit targets override performance differentiation.
- Torque-Vectoring Differential:Multi-pinion gear sets with integrated clutch packs demand complex housing geometries accommodating hydraulic actuators and position sensors. BMW, Porsche, and Lexus source these primarily from Baden-Württemberg forging clusters for all-wheel-drive performance platforms.
- Limited-Slip Differential:Friction plate integration requires machined seal surfaces and thermal expansion management in housing bore specifications.
- Electronic Differential:Sensor mounting bosses and wiring harness routing channels add geometric complexity without mechanical clutch hardware.
Open differential holds the largest share; momentum sits with torque-vectoring differential.
Vehicle Type:
Passenger car and SUV segments drive aluminum casting volume through tier-one foundries, while commercial vehicle demand stabilizes ductile iron capacity utilization at ferrous-specialized suppliers.
- Electric Vehicles:Dual-motor architectures eliminate mechanical differentials entirely from some axle designs, compressing addressable housing volume while elevating material specifications for remaining units. Tesla, BYD, and Hyundai-Kia specify A356-T6 castings for single-motor rear axles where mass reduction extends range certification.
- Commercial Vehicles:Heavy truck and off-highway applications specify ductile iron GGG-50 housings resistant to stone impact and curb loading. Daimler Truck, Volvo Group, and PACCAR anchor demand at foundries with ferritic-pearlitic microstructure control capabilities.
- Passenger Cars:Compact and mid-size sedans standardize open differential aluminum castings across front-wheel-drive transaxles.
- SUVs:All-wheel-drive system penetration elevates limited-slip and torque-vectoring attachment rates in unibody platforms.
Commercial vehicle commands durable demand; electric vehicle represents the fastest-growing trajectory.
Material:
Cost tier separation between aluminum and steel specifications determines foundry investment allocation, with magnesium and composite alternatives confined to technology demonstration programs.
- Aluminum:A356-T6 alloy dominates light-vehicle specifications through high-pressure die-casting and squeeze-casting processes. NHTSA fuel economy penalties accelerate substitution at Ford, General Motors, and Stellantis powertrain operations.
- Steel:Ductile iron GGG-50 retains specification where impact resistance and fatigue life under overload conditions govern procurement. Navistar, Scania, and Tata Motors commercial divisions specify ferrous castings for frame-mounted axle housings.
- Magnesium:AZ91D alloy trials continue at BMW and Mercedes-Benz for secondary mass reduction beyond aluminum baselines.
- Composite:Carbon fiber-reinforced polymer prototypes remain confined to motorsport and hypercar validation programs without production scaling.
Steel retains the largest installed base; aluminum gains share fastest.
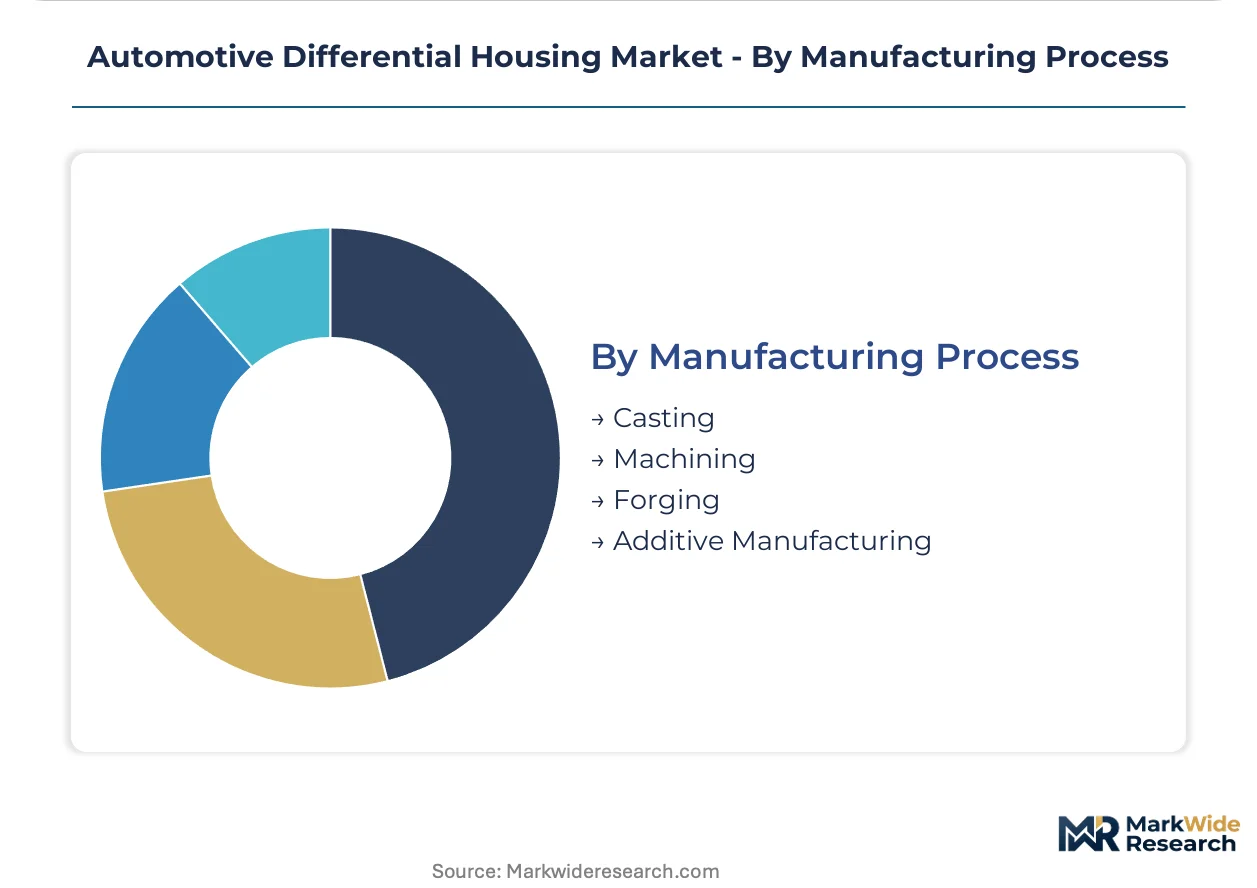
Manufacturing Process:
Process maturity and capital intensity stratify supplier tiers, with casting and machining commanding volume leadership while additive manufacturing attracts development funding for topology-optimized prototypes.
- Casting:High-pressure die-casting and gravity permanent mold processes produce near-net-shape housings requiring minimal finish machining for bearing bores and sealing surfaces. Cosma, Nemak, and Ryobi supply aluminum castings to Toyota, Honda, and Nissan assembly plants across multiple continents.
- Forging:Powder-forged preforms achieve full density in torque-vectoring housing geometries with complex internal features. GKN Automotive anchors European powder-forging capacity for clutch pack accommodation.
- Machining:CNC finishing operations establish final gear mesh alignment and surface finish specifications on cast or forged blanks.
- Additive Manufacturing:Laser powder bed fusion produces prototype housings for thermal management integration studies without tooling investment.
Casting holds the largest share; forging delivers the steepest expansion trajectory in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor net exporters with precision casting capabilities, while import-dependent markets accelerate localized capacity under industrial policy incentives. Regional supply chains fragment around regulatory compliance clusters and raw material access.
United States
Domestic OEM procurement concentrates at Detroit Three assembly plants where NHTSA Corporate Average Fuel Economy penalties accelerate aluminum substitution. EPA greenhouse gas standards tighten material specifications for light-duty drivetrain components. Foundry capacity clusters in Michigan and Ohio supply high-pressure die-cast housings for electric vehicle axle modules.
Germany
Premium vehicle export demand anchors torque-vectoring differential housing specifications for BMW, Porsche, and Mercedes-Benz platforms. EU Green Deal REACH restrictions on heavy metals constrain coating processes for European-sourced castings. Baden-Württemberg forging clusters concentrate powder-forging expertise for clutch pack accommodation.
China
Domestic electric vehicle production volume from BYD and Tesla Shanghai compresses mechanical differential demand while elevating integrated e-axle specifications. MIIT dual carbon goals accelerate lightweight material substitution in passenger vehicle drivetrains. Yangtze River Delta casting capacity serves both local OEMs and export markets.
India
PLI scheme incentives for electric vehicle manufacturing attract housing suppliers capable of localized aluminum casting capacity. BIS standards govern material specifications for domestic commercial vehicle applications. Tamil Nadu and Gujarat automotive clusters concentrate tier-one foundry investment for Maruti Suzuki and Hyundai-Kia supply chains.
Japan
Hybrid platform persistence sustains mechanical differential demand longer than battery-electric markets. METI industrial policy supports next-generation casting process development for multi-material joining. Aichi Prefecture and Kanto region machining clusters finish precision housings for Toyota and Honda transaxle programs.
Automotive Differential Housing Market Vendor Landscape
Concentration sits with diversified automotive suppliers possessing captive foundry capacity and OEM direct relationships. The vendor base stratifies into three tiers: integrated drivetrain system suppliers, independent casting specialists, and regional machining houses. Strategic moves center on backward integration into aluminum smelting partnerships and geographic expansion into PLI-subsidized manufacturing zones.
Among European-anchored system integrators, ZF Friedrichshafen AG and GKN Automotive Limited exemplify the integrated e-axle convergence archetype where differential housing design merges with electric motor casing engineering. Dana Incorporated represents North American capacity concentration through captive foundry operations serving Detroit Three electric vehicle programs. These three entities anchor supplier qualification timelines for premium torque-vectoring architectures.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Dana Incorporated |
| GKN Automotive Limited |
| Eaton Corporation plc |
| American Axle & Manufacturing, Inc. |
| BorgWarner Inc. |
| Linamar Corporation |
| JTEKT Corporation |
| Meritor, Inc. |
| Others |
Supply Flow & Price Mechanics
NHTSA Corporate Average Fuel Economy certification gates supplier qualification and price differentiation simultaneously, as OEMs demand A356-T6 alloy documentation and fatigue test data before contract award while penalizing overweight designs through compliance penalties. This regulatory threshold stratifies foundries into qualified premium suppliers versus commodity casting houses unable to absorb validation costs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across premium, standard, and economy tiers based on certification grade and volume scale. Price differentiation reflects NHTSA documentation completeness and geometric complexity for torque-vectoring geometries. Cost compression in standard open differential castings is intensifying because London Metal Exchange aluminum volatility squeezes fixed-price contracts. Fleet procurement teams at commercial vehicle divisions exhibit highest price sensitivity, while electric vehicle platform engineers prioritize mass reduction over unit cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites primary aluminum flow to Asian casting operations, though German precision forging clusters and North American high-pressure die-casting capacity serve regional OEM assembly networks. Raw material dependencies center on A356-T6 alloy ingots, rare earth elements for clutch pack actuators, and specialized coating chemistries compliant with REACH restrictions. Single-source vulnerability concentrates in Baden-Württemberg powder-forging expertise for torque-vectoring housings. Distribution runs through tier-one system integrators with captive foundry capacity rather than merchant casting houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as electric vehicle platform proliferation accelerates aluminum housing adoption before dual-motor architectures eliminate mechanical differentials entirely.
For Market Incumbents: Compound captive foundry advantages through backward integration into aluminum smelting partnerships that lock in A356-T6 alloy supply against London Metal Exchange volatility. Add squeeze-casting capacity in Michigan or Ohio to defend against Baden-Württemberg cluster concentration risk. Prioritize NHTSA documentation investment as battery-electric platform qualification timelines compress. For New Entrants and Emerging Players: Aftermarket remanufacturing services for commercial vehicle ductile iron housings represent an underserved layer where incumbent system integrators cede ground to independent rebuilders. Target heavy truck fleet maintenance operations in North America with refurbished GGG-50 housings certified to OEM dimensional specifications. Pursue direct fleet relationships bypassing traditional tier-one distribution channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive component roll-ups possessing aluminum casting capacity but lacking electric vehicle platform engineering relationships. Five-to-ten-year viability hinges on successful e-axle housing convergence execution. Monitor Tesla and BYD dual-motor architecture penetration as the signal indicating mechanical differential displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Smelting | Captive A356-T6 supply secures margin against London Metal Exchange price swings for Detroit Three contracts. |
| E-Axle Housing Convergence R&D | Multi-material joining expertise qualifies suppliers for integrated motor-differential enclosures at BMW and Hyundai-Kia. |
| PLI Scheme Manufacturing Footprint | Tamil Nadu casting capacity captures Maruti Suzuki and Hyundai-Kia localized procurement under Indian electric vehicle incentives. |
| Powder-Forging Talent Acquisition | Specialized metallurgists from GKN Automotive or ZF Friedrichshafen clusters unlock torque-vectoring housing qualification. |
| REACH-Compliant Coating Process Development | Advanced surface treatment capabilities preserve European OEM supply access under EU Green Deal heavy metal restrictions. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, tier-one supplier procurement directors, foundry operations managers, and aftermarket distribution heads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, IHS Markit vehicle production databases, EPA certification records, and EU REACH compliance registries. Bottom-up housing volume estimates triangulated with top-down drivetrain content analysis.
Sensitivity analysis tested forecast robustness across aluminum price scenarios, electric vehicle penetration trajectories, and dual-motor architecture adoption curves over the projection horizon. Segmentation dimensions modeled include vehicle propulsion architecture, differential type complexity, material specification tier, manufacturing process maturity, and regional production cluster. CAGRs derived from regression against historical content-per-vehicle trends and OEM platform launch calendars, with battery-electric transition velocity and commercial vehicle replacement cycles as key forecast inputs.
Underlying assumptions cover NHTSA fuel economy penalty continuity, REACH restriction stability, and primary aluminum supply chain integrity, with deviation risk concentrated in battery-electric platform architecture shifts that eliminate mechanical differentials faster than modeled. Practitioners should keep alternative scenarios live as dual-motor torque distribution penetration and integrated e-axle standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Fuel Nozzle Market
Automotive Parts
Mexico Automotive Actuators Market
Automotive Parts
VVT Actuators Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
India Automotive Coolant Market
Automotive Parts
Automotive Viscosity Index Improvers Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
Center and Drag Link Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
Qatar Passenger Vehicles Lubricants Market
Automotive Parts
Automotive OEM Brake Friction Material Market
Automotive Parts
Powerglide Shifter Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Argentina Automotive Actuators Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Electric Vehicle Brake Pad Market