
 Malaysia Passenger Vehicles Lubricants Market | 2026-2036
Malaysia Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Passenger Vehicles Lubricants Market Foresight
Aftermarket service revenue is narrowing as manufacturers tighten warranty-linked servicing protocols and direct-channel lubricant sales expand. PETRONAS Lubricants International anchors its position through captive supply relationships with national vehicle assemblers and an extensive domestic blending network. ExxonMobil Corporation leverages its synthetic formulation leadership to capture premium segments among Malaysian car owners upgrading from mineral oils. Royal Dutch Shell Plc competes through retail service station dominance and integrated loyalty programs that lock in repeat purchase behavior.
Malaysia passenger vehicles lubricants encompass refined petroleum-based and synthetic formulations engineered to reduce friction, dissipate heat, and prevent wear in internal combustion engines and drivetrain components, with viscosity grades typically ranging from 0W-20 to 15W-40 depending on operating temperature and engine architecture. These products serve the essential commercial purpose of extending engine life, maintaining fuel efficiency, and ensuring compliance with manufacturer warranty conditions across tropical climates with high humidity and stop-and-go traffic patterns. Engine oil occupies the largest value pool given mandatory drain intervals and high per-vehicle consumption volumes, while synthetic formulations within this category command widening margin premiums as OEM specifications tighten. Workshop channels sustain disproportionate influence over formulation selection despite online retail growth, since Malaysian fleet operators and individual car owners rely heavily on mechanic recommendations for brand and grade decisions.
Malaysia's Department of Environment enforces emission standards aligned with Euro 5 protocols, compelling lubricant producers to reformulate for lower sulfated ash, phosphorus, and sulfur content to protect exhaust after-treatment systems. BIS-equivalent specifications through the Department of Standards Malaysia and Energy Commission regulations on fuel economy labeling create layered compliance obligations that favor larger blenders with in-house testing laboratories. Stakeholders must monitor how the country's national automotive policy and proposed electric vehicle transition timelines recalibrate lubricant demand curves, since hybrid powertrains introduce divergent thermal management fluid requirements that reshape product development priorities.
Market Dynamics
Euro 5 emission standards are forcing lubricant reformulation across Malaysia's passenger vehicle fleet, tightening specifications for sulfated ash, phosphorus, and sulfur content while accelerating synthetic oil penetration in the Klang Valley corridor.
Growth Catalysts
- Department of Environment Enforcement:Euro 5 alignment mandates lower SAPS formulations, creating mandatory upgrade cycles for workshop inventories nationwide.
- Fleet Operator Professionalization:Commercial vehicle pools in Selangor and Kuala Lumpur are adopting scheduled maintenance protocols that standardize synthetic lubricant procurement.
- Hybrid Powertrain Fluid Complexity:Thermal management requirements for hybrid engines are expanding the addressable product portfolio beyond conventional engine oils.
Market Restraints
- Base Oil Import Dependency:Malaysia lacks domestic Group III/IV base oil production, exposing blenders to freight and currency volatility from Middle Eastern and Singaporean suppliers.
- Warranty-Locked Distribution:National vehicle assemblers specify captive lubricant supply chains that freeze out independent brands during warranty periods.
- Extended Drain Intervals:Synthetic formulations with 15,000-kilometer service cycles are compressing per-vehicle volume consumption in the premium segment.
Strategic Opportunities
- Johor Bahru Corridor Expansion:Vehicle density growth in southern Malaysia remains underserved by premium synthetic distribution relative to the Klang Valley.
- Energy Commission Fuel Economy Labeling:Regulatory pressure on fuel efficiency creates co-marketing openings for lubricant brands aligned with OEM certification programs.
- Direct-to-Fleet Digital Platforms:B2B procurement portals bypass traditional workshop markups for logistics and ride-hailing fleet operators.
Industry Challenges
- Formulation Chemist Scarcity:Malaysia's technical talent pool for low-SAPS additive package development trails regional demand from Thailand and Indonesia.
- Blending Asset Utilization:Domestic facilities face margin pressure from underutilized capacity during periods of base oil price volatility.
- Cross-Border Specification Divergence:Singaporean and Indonesian regulatory misalignment complicates regional product harmonization for multinational blenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Passenger Vehicles Lubricants Market |
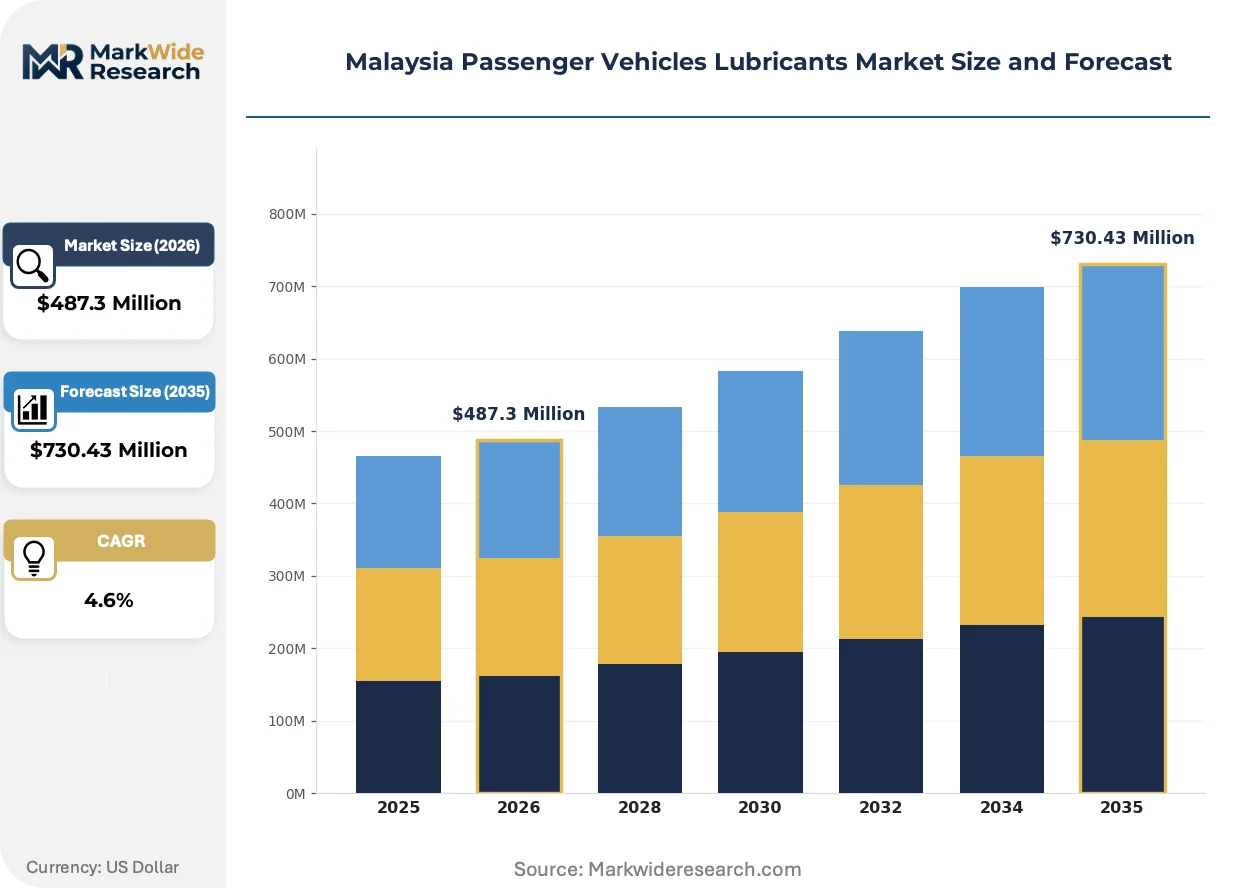
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lubricant Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease Formulation: Synthetic, Semi-Synthetic, Mineral, Bio-Based End User: Car Owners, Vehicle Assemblers, Workshops, Fleet Operators Distribution Channel: Retail, Online, Wholesalers, Service Stations |
| Companies Covered | BP Plc (Castrol), ExxonMobil Corporation, PETRONAS Lubricants International, Royal Dutch Shell Plc, TotalEnergies, Chevron Corporation, Feoso Oil (Malaysia) SDN BHD, LIQUI MOLY, Petron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Passenger Vehicles Lubricants Market Shifts & Advancements
Synthetic lubricant technology is collapsing traditional grade hierarchies while regulatory tightening and channel fragmentation reshape how Malaysian vehicle owners access maintenance products.
Low-viscosity 0W-20 and 0W-16 synthetic formulations engineered for turbocharged direct-injection engines are collapsing the historical dominance of 5W-30 and 10W-40 mineral blends in Malaysian workshops. Japanese and Korean OEM assembly plants in Shah Alam and Kulim are specifying these grades for new vehicle fills, compressing the upgrade window for owners of older vehicles. The technology shift is collapsing aftermarket mineral oil shelf space in Selangor retail channels.
Malaysia's Department of Standards Malaysia is enforcing BIS-equivalent specifications that layer atop Euro 5 protocols, requiring in-house testing laboratory investments that smaller blenders cannot sustain. The industrial consequence is accelerated consolidation of formulation certification capabilities among domestic producers. Workshop channels in Kuala Lumpur are responding by consolidating supplier relationships with blenders holding dual Euro 5 and BIS credentials.
Malaysian fleet operators are unbundling lubricant procurement from mechanical labor, negotiating direct supply contracts with blenders while outsourcing installation to independent workshops. This behavior is disrupting the traditional bundled service model where workshops captured margin on both product and labor. The shift is most visible among logistics fleets operating along the North-South Expressway corridor between Kuala Lumpur and Johor Bahru.
Malaysia Passenger Vehicles Lubricants Market Segmentation
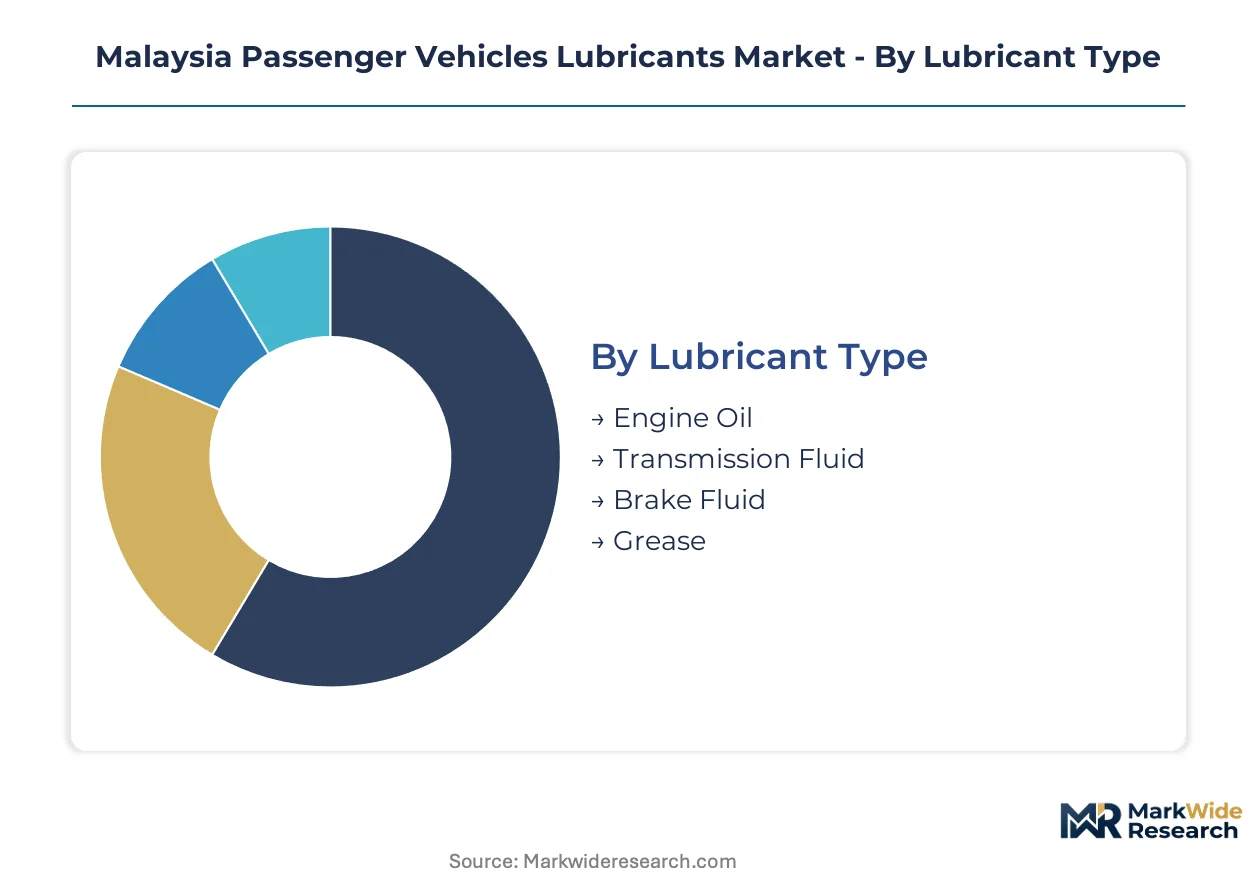
Segmentation in Malaysia's passenger vehicle lubricants market reveals divergent profit pools tied to service intensity, formulation complexity, and channel control. Workshop-dependent categories command premium positioning through technical recommendation power, while direct-channel segments compete on price transparency.
Lubricant Type:
After-sales service intensity varies dramatically by lubricant type, with mandatory drain intervals and diagnostic requirements shaping channel economics.
- Engine Oil:Formulated from Group II/III base stocks with ACEA or API certification, engine oil dominates consumption volumes through 5,000 to 15,000-kilometer drain intervals. Demand concentrates in Klang Valley workshops where turbocharged direct-injection engines from Proton and Perodua assembly plants specify low-viscosity synthetics.
- Transmission Fluid:Specialized ATF and CVT formulations with precise friction modification requirements command technical specification loyalty. Fleet operators along the North-South Expressway corridor are consolidating procurement around OEM-certified grades to avoid warranty disputes.
- Brake Fluid:DOT 3 and DOT 4 hygroscopic formulations require two-year replacement cycles in Malaysia's humid tropical climate. Service stations capture recurring revenue through safety-critical positioning.
- Grease:Lithium and calcium soap-based chassis lubricants serve older vehicle parc and commercial applications with extended service intervals. Rural workshops in Pahang and Kelantan maintain steady demand for multi-purpose grades.
By volume, Engine Oil leads. By growth pace, Transmission Fluid is ahead.
Formulation:
Cost tier stratification separates premium synthetic positioning from commodity mineral competition, with semi-synthetic occupying the contested middle ground.
- Synthetic:Group III/IV base oils with engineered additive packages deliver extended drain intervals and fuel economy compliance. Euro 5 enforcement through Malaysia's Department of Environment is accelerating synthetic penetration in Selangor and Kuala Lumpur.
- Semi-Synthetic:Blended formulations balance performance upgrade cost against mineral baseline pricing. Johor Bahru corridor workshops promote these grades for vehicles exiting manufacturer warranty periods.
- Mineral:Conventional Group I base oil products serve price-sensitive segments and older engine architectures. Rural markets in Sabah and Sarawak sustain volume through established distribution networks.
- Bio-Based:Ester and vegetable-derived formulations address sustainability positioning in corporate fleet procurement policies. Penang-based logistics operators are piloting these products for carbon reporting compliance.
Synthetic formulations capture the highest margin per liter. Semi-synthetic volumes are expanding most quickly among upgrade-seeking car owners.
End User:
Customer type segmentation exposes divergent procurement behaviors, from individual price sensitivity to institutional contract negotiation.
- Car Owners:Individual purchasers rely heavily on mechanic recommendations for brand and grade selection, creating workshop channel dependency. Klang Valley vehicle density supports fragmented retail competition.
- Vehicle Assemblers:National manufacturers specify captive first-fill and warranty-service lubricant supply chains. Proton and Perodua assembly relationships lock in multi-year blending contracts.
- Workshops:Independent service providers capture margin on both product and labor, though fleet unbundling is compressing this model. Kuala Lumpur mechanical clusters consolidate around preferred supplier relationships.
- Fleet Operators:Commercial vehicle pools professionalize maintenance scheduling and negotiate direct blender contracts. Ride-hailing and logistics fleets in Selangor are driving synthetic standardization.
Workshops handle the largest transaction volume. Fleet Operators are gaining share fastest through procurement centralization.
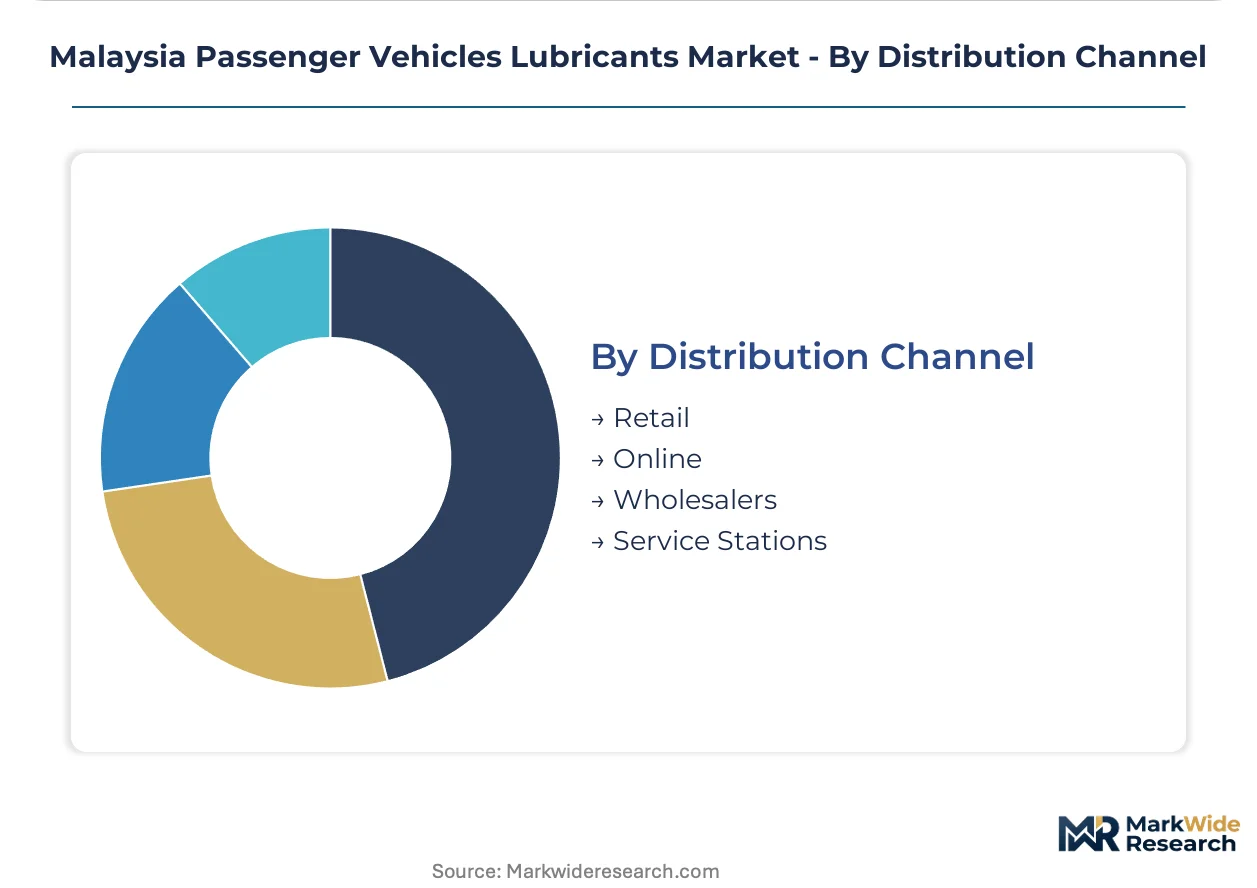
Distribution Channel:
Geographic concentration of Malaysia's vehicle population shapes channel viability, with urban density enabling scale economics unavailable in dispersed rural markets.
- Retail:Hypermarket and automotive specialty stores serve DIY enthusiasts and emergency purchasers. Selangor retail shelf space is compressing mineral oil SKUs in favor of synthetic grades.
- Online:E-commerce platforms and direct-to-consumer portals bypass workshop markups for price-transparent buyers. Urban millennials in Kuala Lumpur are driving digital lubricant purchases.
- Wholesalers:Regional distributors supply workshop networks with inventory financing and technical support. Southern Malaysia distribution infrastructure remains underdeveloped relative to Klang Valley.
- Service Stations:Integrated fuel-and-lube retail captures convenience-driven demand through loyalty program lock-in. PETRONAS and Shell station networks dominate the forecourt segment.
Service Stations lead by transaction frequency. Online channels are climbing the fastest as digital procurement penetrates fleet segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Malaysia's lubricant landscape, with Klang Valley buyers accepting synthetic premiums while rural Sabah and Sarawak markets remain anchored to mineral formulations. Fleet operators in Selangor negotiate bulk contracts that compress per-liter margins, contrasting with individual car owners in Johor Bahru who respond to mechanic recommendations rather than price signals.
Selangor
Vehicle density in the Klang Valley corridor generates the nation's highest per-capita lubricant consumption, with Shah Alam and Petaling Jaya hosting concentrated workshop networks. Malaysia's Department of Environment enforces Euro 5 emission standards that mandate low-SAPS synthetic formulations for newer vehicle registrations. Proton and Perodua assembly plants in this state lock in captive first-fill supply contracts that shape downstream distribution patterns.
Kuala Lumpur
Urban stop-and-go traffic patterns accelerate engine oil degradation, compressing drain intervals for ride-hailing fleets operating across the capital. The Energy Commission's fuel economy labeling regulations create co-marketing opportunities for lubricant brands aligned with OEM certification programs. Bukit Bintang and Mont Kiara service clusters exhibit the strongest synthetic penetration rates as premium vehicle ownership concentrates.
Johor Bahru
Southern Malaysia's vehicle population growth outpaces premium synthetic distribution infrastructure, leaving price-sensitive segments underserved relative to the Klang Valley. The Iskandar Malaysia economic corridor attracts logistics fleet investment that professionalizes maintenance scheduling. Pasir Gudang industrial zones generate commercial vehicle demand that blends workshop loyalty with emerging direct-procurement channels.
Penang
Electronics manufacturing clusters in Bayan Lepas sustain corporate fleet procurement policies that pilot bio-based lubricants for carbon reporting compliance. The state's higher average income levels support faster synthetic upgrade cycles among individual car owners. Georgetown workshop networks retain strong mechanic influence over brand selection despite e-commerce penetration.
Sabah and Sarawak
Rural distribution networks in East Malaysia sustain mineral oil volumes through established supply chains serving older vehicle parc. Long-distance highway driving patterns between Kuching and Miri extend drain intervals, partially offsetting lower synthetic penetration. Local workshops in Kota Kinabalu and Kuching maintain multi-purpose grease demand for commercial applications with limited access to specialized formulations.
Malaysia Passenger Vehicles Lubricants Market Competitive Landscape
National oil companies and multinational lubricant specialists split the market between captive supply relationships and retail channel dominance. PETRONAS Lubricants International anchors its position through vertical integration into domestic blending infrastructure and assembler partnerships. ExxonMobil Corporation and Royal Dutch Shell Plc compete through synthetic formulation leadership and service station network density. Competitive moves concentrate on warranty-locked distribution expansion and fleet direct-procurement platform development.
Within the multinational tier, BP Plc (Castrol) and TotalEnergies represent premium-positioned archetypes competing for upgrade-seeking car owners transitioning from mineral baselines. PETRONAS Lubricants International occupies a distinctive position as the national champion with captive supply relationships and domestic production assets. Among specialty importers, LIQUI MOLY exemplifies the technical-positioning archetype targeting enthusiast segments with additive-focused marketing. Feoso Oil (Malaysia) SDN BHD and Petron Corporation sit within the regional distributor tier, leveraging Southeast Asian supply chain proximity to serve price-sensitive volume segments.
| Leading Market Players |
|---|
| BP Plc (Castrol) |
| ExxonMobil Corporation |
| PETRONAS Lubricants International |
| Royal Dutch Shell Plc |
| TotalEnergies |
| Chevron Corporation |
| Feoso Oil (Malaysia) SDN BHD |
| LIQUI MOLY |
| Petron Corporation |
| Others |
Supply & Pricing Matrix
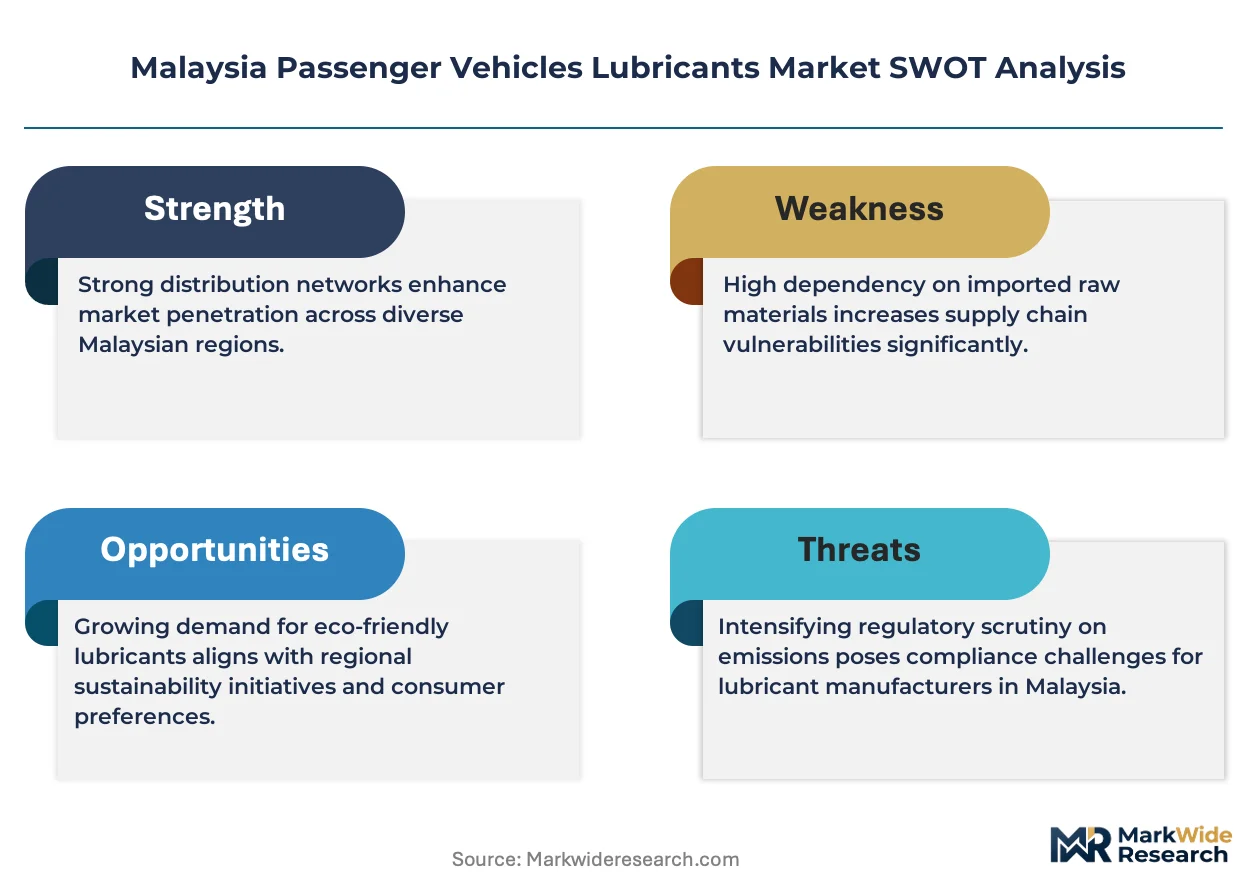
Base oil import dependency from Middle Eastern and Singaporean suppliers exposes Malaysian blenders to freight and currency volatility, compressing margin spreads between premium synthetic tiers and commodity mineral grades while forcing supply chain restructuring toward regional inventory buffers.
Pricing Analysis
After-sales service revenue from workshop labor and bundled maintenance packages drives lifetime value capture across the Malaysian passenger vehicle lubricants market. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral levels stratifies according to ACEA/API certification tier and volume procurement scale. Pricing pressure stems from fleet operator unbundling of lubricant procurement from mechanical labor, which exposes blenders to direct contract negotiation. Individual car owners in Klang Valley workshops exhibit lowest price sensitivity due to mechanic recommendation dependency, while rural Sabah and Sarawak buyers anchor to mineral baselines.
Supply Chain Analysis
Export-control regimes on advanced additive packages and Group IV base oil technologies limit technology transfer into Malaysian blending facilities, constraining domestic low-SAPS formulation capability. Supply concentrates in Singapore, South Korea, and Japan for Group III/IV base oils and friction modifier additives. Raw material dependencies span polyalphaolefin base stocks, molybdenum disulfide friction modifiers, and calcium sulfonate detergent packages. Single-source vulnerability runs through Singaporean port congestion affecting just-in-time base oil deliveries. Distribution runs through wholesaler networks with inventory financing support, though direct-to-fleet digital platforms are bypassing traditional markup layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's passenger vehicle lubricants market operates as a substitution defense against electric vehicle powertrain fluid displacement, where hybrid thermal management requirements offer partial demand offset but full electrification timelines threaten long-term volume erosion.
For Market Incumbents: Pre-empt fleet operator procurement centralization by developing direct-to-fleet digital platforms with integrated technical support and drain interval optimization tools. Lock in captive supply relationships with national vehicle assemblers through multi-year blending contracts that extend beyond warranty periods. Invest in in-house testing laboratory capacity to maintain dual Euro 5 and BIS-equivalent certification credentials as smaller blenders exit.
For New Entrants and Emerging Players: Build out distribution infrastructure in the Johor Bahru corridor where vehicle density growth outpaces premium synthetic supply penetration relative to Klang Valley saturation. Target logistics fleet operators along the North-South Expressway with bio-based lubricant pilots aligned to corporate carbon reporting requirements. Establish technical positioning through additive-focused marketing to enthusiast segments before expanding to mainstream workshop channels.
For Investors and Strategic Acquirers: Euro 5 enforcement through Malaysia's Department of Environment reshapes the acquisition landscape toward blenders with demonstrated low-SAPS formulation capability and in-house certification infrastructure. Long-term viability hinges on exposure to hybrid powertrain fluid complexity rather than pure internal combustion engine dependence. Acquisition target archetypes include regional distributors with underutilized blending assets and technical talent pools. Monitor electric vehicle transition timeline announcements from national automotive policy bodies as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Mitigates currency volatility exposure from Singaporean and Middle Eastern import dependency. |
| Direct-to-Fleet Digital Platform Launch | Bypasses workshop markup capture and locks in ride-hailing and logistics procurement centralization. |
| Dual Certification Laboratory Investment | Secures Euro 5 and BIS-equivalent credentials that smaller domestic blenders cannot sustain. |
| Hybrid Powertrain Fluid Portfolio Expansion | Captures thermal management demand offset as electric vehicle transition compresses engine oil volumes. |
| Johor Bahru Distribution Infrastructure Buildout | Addresses underserved southern Malaysia vehicle density growth relative to Klang Valley saturation. |
Research Methodology
Operator-level perspectives from lubricant blending plant managers, fleet procurement officers at logistics and ride-hailing operators, workshop owners in Klang Valley mechanical clusters, and technical R&D directors at additive suppliers anchored the qualitative base. Secondary validation drew from Department of Environment emission standard filings, Department of Standards Malaysia BIS-equivalent specifications, Energy Commission fuel economy labeling regulations, and customs trade data on base oil imports. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Scenario-bracketing framed demand projections under varying electric vehicle penetration assumptions and hybrid powertrain adoption curves. Segmentation dimensions modeled included lubricant type, formulation grade, end-user archetype, and distribution channel structure. CAGRs were derived from trend extrapolation of synthetic penetration rates, fleet operator procurement professionalization, and regulatory compliance upgrade cycles. Industry-specific forecast inputs encompassed Proton and Perodua assembly plant production schedules and national automotive policy transition timelines.
The forecast holds incumbent behavior within observed patterns; aggressive direct-procurement platform investments by multinational blenders or accelerated electric vehicle subsidies would shift outcomes. Material shifts in Department of Environment emission standard enforcement timing or national electric vehicle transition mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Racing Vehicles Market
Automotive Parts
Industrial V Belt Market
Automotive Parts
Automatic Bus Door System Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Global Automotive Motor Oil Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
Electric Coolant Pump Market
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Mobile Diesel Heaters Market
Automotive Parts
Colombia Passenger Vehicles Lubricants Market
Automotive Parts
Wind Shield Washer Market
Automotive Parts
Global Automotive Auxiliary Brake Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Heavy Duty Engines Market