
 Automatic Gearbox Valves Market | 2026-2036
Automatic Gearbox Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Gearbox Valves Market Outlook
The EU Green Deal is consolidating procurement standards across European automotive supply chains, favoring suppliers with certified low-carbon manufacturing processes. Bosch GmbH leverages its electromechanical valve portfolio to anchor long-term contracts with German premium OEMs. BorgWarner competes through integrated transmission module development that bundles valve systems with clutch packs. Aisin Seiki dominates Asian supply networks with manufacturing scale across multiple transmission platforms.
Automatic gearbox valves are precision-actuated fluid control devices, typically machined from hardened steel alloys with tolerances below 5 microns, that modulate hydraulic pressure to execute gear shifts in planetary and dual-clutch transmissions. Their primary purpose is enabling smooth, millisecond-accurate ratio changes while protecting clutch packs from thermal damage. Solenoid valves currently occupy the largest product category due to their proven reliability in mass-market torque-converter automatics, while smart valves integrating pressure sensors and diagnostic feedback represent the fastest-expanding technology segment. Among end users, automotive OEMs sustain the deepest margin pools as they specify custom valve calibration maps tied to proprietary transmission control software.
FDA standards for medical device fluidics do not apply here, but EPA tailpipe regulations, NHTSA fuel economy mandates, and EU REACH substance restrictions directly shape valve material selection and sealing technology requirements. China's MIIT dual carbon goals and GB standards for vehicle energy consumption are accelerating local sourcing requirements for transmission components. Stakeholders must monitor how software-defined vehicle architectures redistribute control authority between centralized compute units and distributed valve actuators.
Market Dynamics
Passenger vehicle electrification is forcing transmission suppliers to reengineer hydraulic architectures for hybrid and electric drivetrains, compressing development cycles while demanding higher precision from valve actuation systems.
Growth Catalysts
- Euro 7 tailpipe standards:European OEMs are redesigning transmission control modules to optimize shift efficiency, directly expanding demand for precision pressure-modulating valves.
- Dual-clutch transmission proliferation:Performance-oriented passenger vehicles require faster-acting solenoid arrays to manage clutch engagement sequences under thermal stress.
- China MIIT dual carbon goals:Local content mandates are accelerating domestic valve production capacity expansion for transmission assembly plants in Jiangsu and Zhejiang provinces.
Market Restraints
- Hardened steel alloy supply:Specialized martensitic stainless grades face pricing volatility from nickel and chromium spot markets, squeezing foundry margins.
- German supplier concentration:Precision machining capacity clusters disproportionately around Stuttgart and Munich, creating geographic vulnerability to regional energy cost spikes.
- Sub-5 micron tolerance limits:Current grinding and honing equipment reaches physical thresholds for cost-effective mass production of next-generation smart valve bodies.
Strategic Opportunities
- India automotive assembly expansion:Tamil Nadu and Gujarat transmission plants lack qualified local valve suppliers, opening import-substitution partnerships for established tier-1s.
- Sensor-integrated smart valves:Convergence of MEMS pressure sensing with proportional solenoid control enables predictive maintenance revenue streams for aftermarket channels.
- EU Green Deal procurement standards:Certified low-carbon manufacturing processes unlock preferential supplier status with premium German and Swedish OEMs.
Industry Challenges
- Mechatronics systems integration:Transmission control software calibration requires valve suppliers to maintain embedded engineering teams at OEM development centers.
- Functional safety certification:ISO 26262 ASIL-D compliance timelines for new valve designs extend 18-24 months, delaying program launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Gearbox Valves Market |
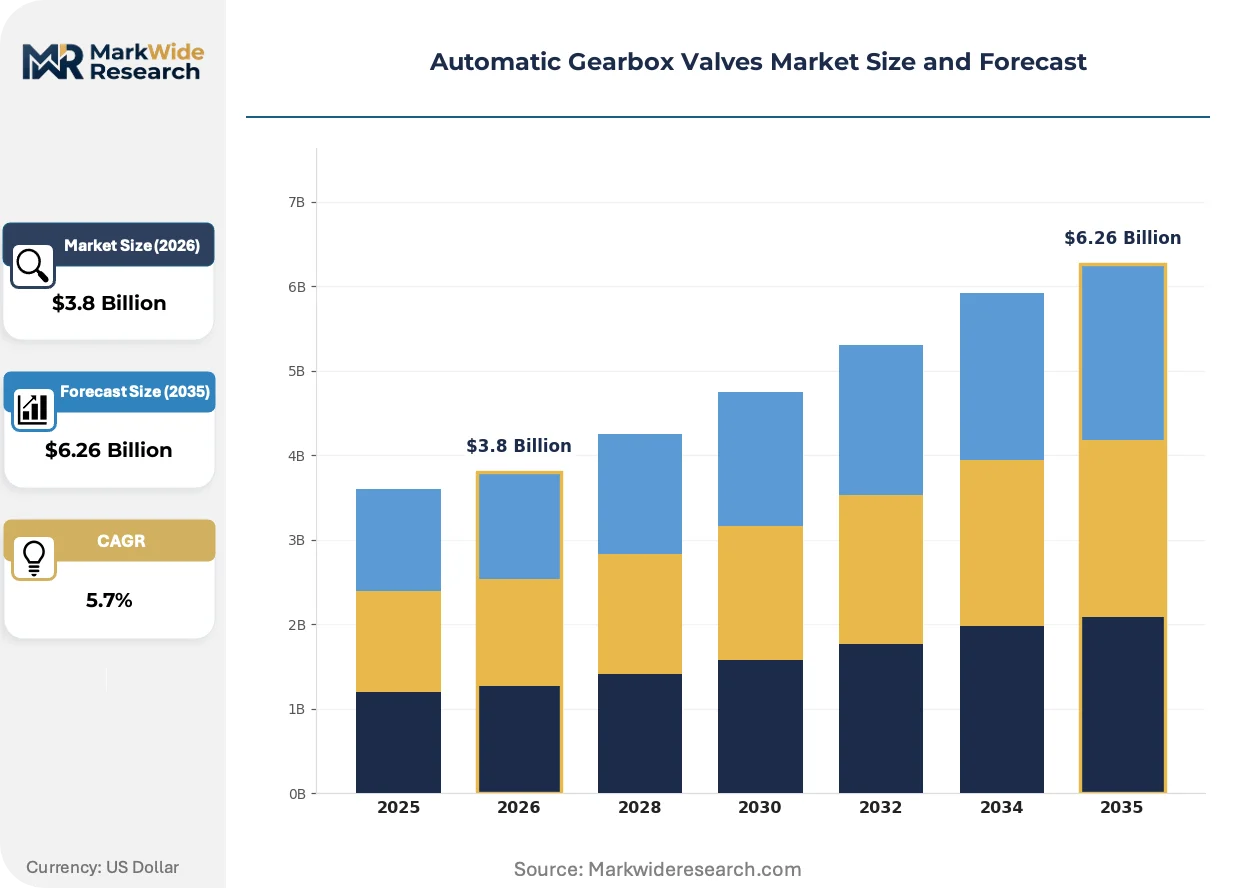
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Valves, Pneumatic Valves, Electric Valves, Solenoid Valves End User: Automotive OEMs, Aftermarket Providers, Fleet Operators, Industrial Manufacturers Technology: Electromechanical, Electrohydraulic, Fluidic Control, Smart Valves Application: Transmission Control, Engine Management, Fuel Control, Fluid Handling |
| Companies Covered | Aisin Seiki, Avex, BorgWarner, Eaton, Hikari Seiko, Bosch GmbH, Atsumitec, Mahle GmbH, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Gearbox Valves Market Strategic Shifts
Software-defined vehicle architectures are redistributing control authority from distributed transmission modules toward centralized domain controllers, forcing valve suppliers to develop digital-ready actuation platforms.
Electromechanical valve actuation is overtaking traditional hydraulically-piloted designs in next-generation hybrid transmissions. Premium German OEMs are specifying direct-acting solenoids for their P2 hybrid architectures to enable millisecond-ratio changes under electric motor torque fill. This technology compression is eliminating intermediate hydraulic relay stages, reducing valve count per transmission by 30-40%.
EPA fuel economy mandates and NHTSA Corporate Average Fuel Economy standards are tightening enforcement timelines for 2027-2031 model years. Transmission suppliers must submit validated shift-energy consumption data, forcing valve manufacturers to instrument production units with flow sensors for regulatory traceability. Dual-clutch platforms for the US light-truck segment are absorbing the bulk of compliance engineering resources.
Long-term service contracts are displacing transactional component sales for fleet operators managing electric-hybrid commercial vehicles. Valve suppliers in North America are bundling predictive replacement schedules with telematics integration, capturing aftermarket revenue through subscription models rather than spare-part margins. Municipal bus fleets in California represent the most advanced adoption of this consumption-pattern shift.
Automatic Gearbox Valves Market Segmentation
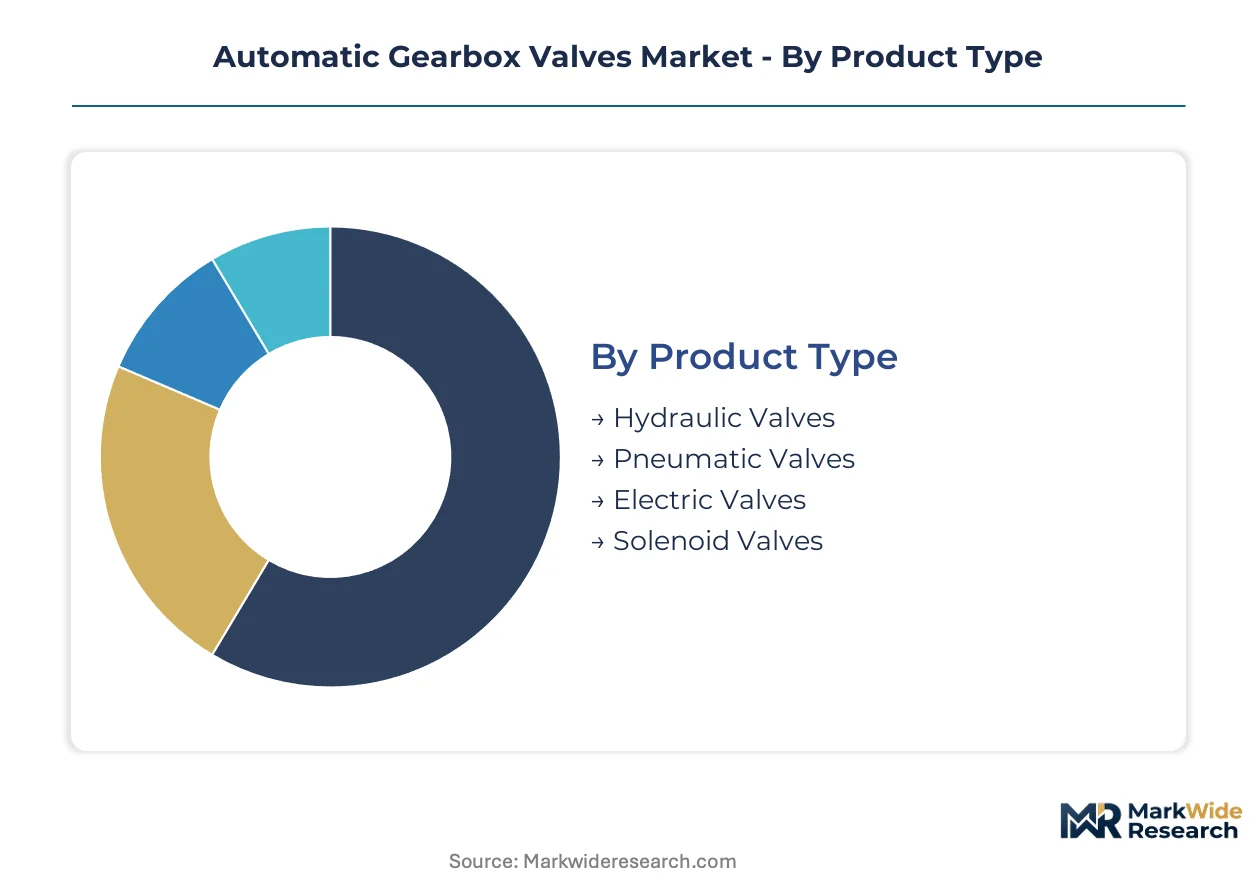
Automatic gearbox valve procurement splits across four distinct dimensions, each reflecting divergent technical requirements and margin structures. Product type determines machining precision standards, while end-user category dictates whether suppliers compete on volume contracts or service bundling.
Product Type:
Upgrade cycles for transmission architectures are shortening as electrification forces hydraulic system redesigns, with each valve category facing distinct replacement timelines and qualification burdens.
- Solenoid Valves:Proportional electromagnetic actuators with copper-wound coils and hardened steel armatures deliver millisecond response times for torque-converter automatics. Demand concentrates in German premium OEM assembly plants, where EPA fuel economy mandates for light-truck platforms are accelerating specification updates for shift-energy optimization.
- Electric Valves:Brushless DC motor-driven valve bodies eliminate hydraulic pilot stages entirely, enabling direct software control from domain controllers. Chinese transmission plants in Jiangsu province are absorbing capacity expansion here, driven by MIIT dual carbon goals and local content requirements for hybrid drivetrain production.
- Hydraulic Valves:Pressure-modulating spool valves machined from martensitic stainless alloys with sub-5 micron tolerances.
- Pneumatic Valves:Compressed-air actuated designs with limited adoption in passenger vehicle applications.
Solenoid valves sit at the top of the volume ranking, with electric valves climbing the fastest as P2 hybrid architectures displace pure hydraulic control.
End User:
Customer type determines whether valve suppliers optimize for production-line scale or aftermarket service intensity, with contract structures diverging sharply between these modes.
- Automotive OEMs:Direct procurement relationships with transmission assemblers specify custom calibration maps and embedded engineering support. German and US OEMs dominate this tier, leveraging proprietary transmission control software to lock in multi-year supply agreements with ISO 26262 ASIL-D compliance requirements.
- Fleet Operators:Municipal and commercial vehicle fleets in California are pioneering subscription-based predictive maintenance models. These contracts bundle telematics-integrated valve replacement schedules with long-term service agreements, displacing traditional spare-part transactions.
- Aftermarket Providers:Independent distributors serving repair networks with standardized valve replacements.
- Industrial Manufacturers:Non-automotive fluid power applications with distinct specification requirements.
Automotive OEMs capture the deepest margin pools, while fleet operators are gaining share fastest through outcome-based contracting structures.
Technology:
Control architecture choices are fragmenting as software-defined vehicle platforms redistribute authority between centralized compute and distributed actuation.
- Smart Valves:MEMS pressure sensors integrated with proportional solenoid bodies enable real-time diagnostic feedback and predictive maintenance algorithms. US light-truck dual-clutch platforms are absorbing the bulk of development engineering here, driven by NHTSA Corporate Average Fuel Economy validation requirements for shift-energy traceability.
- Electromechanical:Direct-acting solenoid designs eliminating intermediate hydraulic relay stages are specified by German premium OEMs for P2 hybrid architectures. These systems enable torque-fill coordination with electric motors, cutting valve count per transmission by 30-40%.
- Electrohydraulic:Traditional pilot-operated designs with proven reliability in mass-market applications.
- Fluidic Control:Laminar flow-based microvalve architectures with limited current deployment.
Electromechanical technology holds the largest installed base, with smart valves expanding most quickly through sensor integration roadmaps.
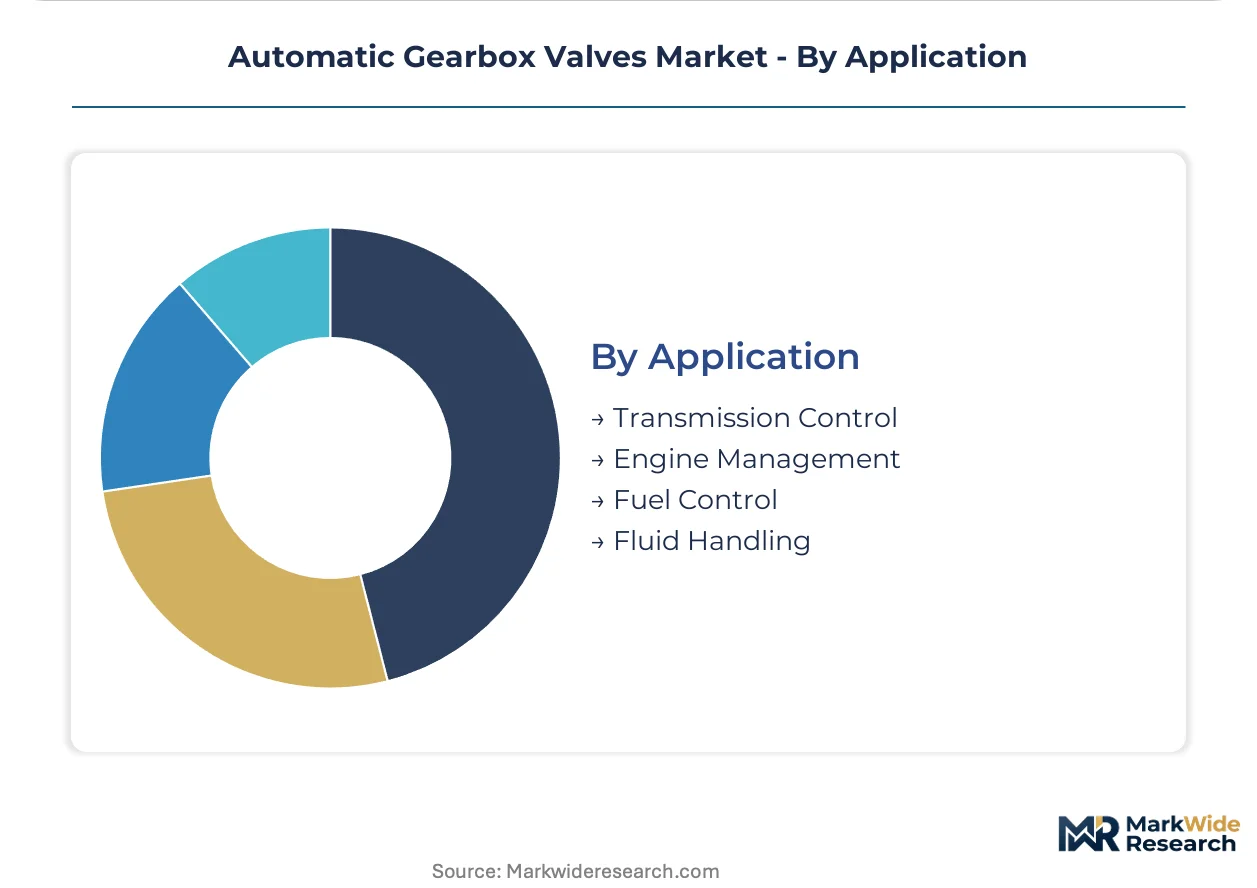
Application:
Functional deployment of valve systems spans powertrain domains beyond transmission control, with each application carrying distinct thermal and precision requirements.
- Transmission Control:Multi-clutch sequencing valves and pressure modulators govern ratio changes in planetary and dual-clutch architectures. Chinese assembly plants in Zhejiang province are driving volume concentration here, supported by domestic capacity expansion for automatic transmission production.
- Engine Management:Variable valve timing oil control valves and cam phaser actuators manage internal combustion efficiency. Euro 7 tailpipe standards are forcing redesigns of these systems for residual ICE applications in European hybrid platforms.
- Fuel Control:High-pressure direct injection valve systems with precision metering requirements.
- Fluid Handling:Thermal management and lubrication circuit valves supporting auxiliary powertrain functions.
Transmission control dominates current procurement volumes, with engine management applications gaining share fastest as hybrid architectures extend ICE relevance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision transmission component manufacturing during the 1980s expansion of automated manual gearboxes, establishing machining expertise that still defines tolerance standards for sub-5 micron valve bodies today.
Germany
Stuttgart and Munich host the densest clusters of automatic transmission assembly capacity in Europe, with Bosch GmbH leveraging electromechanical valve portfolios to anchor long-term contracts with premium OEMs. KBA vehicle certification requirements under Euro 7 tailpipe standards are forcing redesigns of transmission control modules. Baden-Württemberg precision machining foundries are expanding capacity for martensitic stainless alloy valve bodies serving hybrid drivetrain programs.
China
Jiangsu and Zhejiang provinces are absorbing capacity expansion for electric valve production driven by MIIT dual carbon goals and local content mandates. GB standards for vehicle energy consumption are accelerating domestic sourcing requirements for transmission components. Shanghai-based transmission assembly plants are integrating smart valves with MEMS pressure sensing for predictive maintenance algorithms in fleet applications.
United States
EPA fuel economy mandates and NHTSA Corporate Average Fuel Economy standards for 2027-2031 model years are tightening enforcement timelines for shift-energy consumption validation. Detroit-area transmission engineering centers are specifying direct-acting solenoids for light-truck dual-clutch platforms. Michigan and Ohio valve suppliers are instrumenting production units with flow sensors for regulatory traceability.
Japan
Aisin Seiki dominates Asian supply networks with manufacturing scale across multiple transmission platforms serving both domestic and export markets. METI energy efficiency regulations are pushing hybrid drivetrain adoption requiring faster-acting valve actuation systems. Nagoya-area precision component clusters are retooling for electromechanical valve architectures that eliminate hydraulic pilot stages.
India
Tamil Nadu and Gujarat transmission plants lack qualified local valve suppliers, creating import-substitution opportunities for established tier-1 partnerships. BIS automotive component standards are gradually tightening quality certification requirements for transmission subsystems. Chennai-based assembly operations are sourcing solenoid valves for emerging dual-clutch platforms in compact passenger vehicles.
Automatic Gearbox Valves Market Competitive Environment
Premium-margin players sit above commodity-margin players across calibration complexity and embedded software integration, with the market consolidating around three distinct capability tiers. Tier-1 transmission specialists with captive valve manufacturing command the deepest OEM relationships through multi-year supply agreements. Tier-2 precision machining houses compete on volume contracts for standardized solenoid bodies. Tier-3 regional fabricators serve aftermarket replacement demand with reverse-engineered specifications. Dominant competitive moves include strategic partnerships for mechatronics systems integration and geographic expansion into underpenetrated assembly regions.
Among Germany-based precision engineering groups, Bosch GmbH and Mahle GmbH exemplify the premium-tier archetype through their electromechanical and engine management positioning. BorgWarner represents the integrated systems approach, bundling valve systems with clutch packs for transmission module development. Aisin Seiki anchors the scale-driven Asian supply network with manufacturing presence across multiple transmission platforms.
| Leading Market Players |
|---|
| Aisin Seiki |
| Avex |
| BorgWarner |
| Eaton |
| Hikari Seiko |
| Bosch GmbH |
| Atsumitec |
| Mahle GmbH |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Martensitic stainless steel alloy costs cascade from nickel and chromium spot markets through Stuttgart foundries into tiered valve pricing for German premium OEMs, compressing margins for precision machining houses while elevating procurement leverage for transmission assemblers with multi-year contract locks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262 ASIL-D certified electromechanical valves from mass-market solenoid bodies and unbranded aftermarket replacements. Price differentiation hinges on certification grade and embedded software integration depth. Cost compression in standard-tier solenoid arrays is intensifying because Chinese domestic capacity expansion under MIIT dual carbon goals is flooding mid-grade supply. Fleet operators managing electric-hybrid commercial vehicles exhibit lowest price sensitivity due to subscription-based predictive maintenance contracts, while independent aftermarket distributors face acute margin pressure from reverse-engineered imports.
Supply Chain Analysis
Skilled precision grinding and honing technician availability constrains output expansion in Baden-Württemberg and Nagoya manufacturing clusters, forcing valve suppliers into automation capital deployment. Geographic supply concentration centers on Germany, China, and Japan for sub-5 micron tolerance machining. Raw material dependencies draw from nickel-chromium alloy feedstock, copper coil winding, and MEMS sensor substrates. Single-source vulnerability permeates specialized martensitic stainless grades from European foundries. Distribution runs through captive Tier 1 transmission module assembly plants rather than open merchant markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Valve suppliers can arbitrage cost differentials between energy-intensive European precision foundries and expanding Chinese electric valve capacity under MIIT local content mandates, capturing margin expansion through geographic sourcing optimization.
For Market Incumbents: Anticipate displacement pressure from sensor-integrated smart valve architectures by deepening backward integration into MEMS pressure sensing substrates. Prioritize certification investment for ISO 26262 ASIL-D compliance to defend OEM contract renewals against emerging Chinese competitors with cost advantages but immature functional safety track records.
For New Entrants and Emerging Players: Launch via import-substitution partnerships with Tamil Nadu and Gujarat transmission plants lacking qualified local valve suppliers. Target India's emerging dual-clutch platform segment through technical licensing arrangements with established precision machining houses, leveraging BIS automotive component standard tightening as qualification barrier against unorganized competitors.
For Investors and Strategic Acquirers: Consolidation pressure builds where mechatronics systems integration capabilities fragment across Tier 2 precision machining houses unable to sustain embedded engineering teams at OEM development centers. Target acquisition archetypes are German mid-cap specialists with captive electromechanical valve portfolios and existing ASIL-D certification infrastructure. Watch for inflection where EPA fuel economy mandate enforcement timelines accelerate shift-energy validation requirements, favoring suppliers with flow-sensor instrumented production traceability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Sensing | Smart valve roadmaps require captive pressure sensor supply chains to secure predictive maintenance revenue streams. |
| Geographic Manufacturing Footprint Expansion | Jiangsu province capacity additions satisfy MIIT dual carbon local content mandates for hybrid drivetrain programs. |
| Software-Defined Vehicle Investment | Domain controller compatibility demands digital-ready actuation platforms with direct software control interfaces. |
| Functional Safety Certification Program | ASIL-D compliance timelines extend 18-24 months, creating qualification moats against unproven competitors. |
| Long-Term Supply Agreement Structuring | Subscription-based fleet service contracts displace transactional spare-part margins in California municipal bus applications. |
Study Parameters
Multiple input streams — transmission platform engineering directors, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and precision machining foundry managers — were reconciled against vehicle production databases, IHS Markit registration data, EPA fuel economy compliance filings, and MIIT dual carbon policy documentation. Primary fieldwork across German, Chinese, and US automotive engineering centers was validated through secondary triangulation. Bottom-up valve unit demand estimates and top-down transmission assembly forecasts were cross-referenced for convergence.
Data-stream reconciliation anchored volume projections across the analysis window through segmented modeling of product type, end user category, technology architecture, and application domain. CAGRs were derived from fitted growth curves calibrated to electrification penetration rates and regulatory enforcement timelines. Industry-specific forecast inputs included shift-energy optimization engineering resource allocation and dual-clutch platform proliferation trajectories for US light-truck segments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA mandate acceleration or nickel-chromium commodity price spikes. Forecasts reflect assumptions regarding transmission architecture electrification pacing and functional safety certification timeline stability. Material deviation in Euro 7 implementation schedules or China MIIT local content enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Thin-Section Ball Bearings Market
Automotive Parts
Vietnam Commercial Vehicles Lubricants Market
Automotive Parts
South Africa Commercial Vehicles Lubricants Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Automotive Fuel Supply System Market
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Engine Fogging Oil Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
Brake Pad Market
Automotive Parts
Automotive Brake Friction Materials Market
Automotive Parts
External Combustion Engine Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Germany Automotive Hydraulic Actuators Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Automotive Pinion Gear Market
Automotive Parts
Bearing Steel Balls for New Energy Vehicles Market