
 Mexico Passenger Vehicles Lubricants Market | 2026-2036
Mexico Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Passenger Vehicles Lubricants Market Foresight
The capability gap between integrated blenders and import-dependent distributors is redrawing competitive boundaries in Mexico's passenger vehicle lubricants sector. Roshfrans leverages captive base-oil refining and domestic additive compounding to sustain margin control across central Mexico. Royal Dutch Shell Plc anchors premium synthetic positioning through its service-station network, while Mexicana de Lubricantes S A de C V competes on regional distribution density in northern border states.
Passenger vehicle lubricants comprise formulated fluids engineered from Group I through Group III base stocks combined with detergent, dispersant, anti-wear, and viscosity-index improver packages, typically meeting SAE viscosity grades from 0W-16 to 15W-40 for gasoline and light-duty diesel engines. These formulations reduce friction, dissipate heat, and suspend combustion byproducts to extend powertrain operational life in consumer automobiles. Engine oil occupies the dominant value share given mandatory drain-interval compliance, while synthetic formulations capture expanding margin pools as OEM fill specifications shift toward lower-viscosity grades. The application split tilts toward passenger cars and SUVs, which together absorb the majority of volume through both aftermarket replacement and dealer service channels.
SEMARNAT enforces NOM-085-ECOL-2011 emission thresholds that directly influence lubricant ash-content and phosphorus limits for gasoline engines sold in Mexico. PROFECO monitors labeling and performance claims through periodic market surveillance, while the national oil regulator shapes base-stock availability through supply-chain oversight of domestic refining capacity. Stakeholders must track how impending updates to Mexican emission harmonization with EPA Tier 3 equivalents will recalibrate additive chemistry requirements and reformulation timelines.
Market Dynamics
SEMARNAT's tightening enforcement of NOM-085-ECOL-2011 emission thresholds is compressing additive chemistry timelines and forcing reformulation cycles across Mexico's passenger vehicle lubricants supply base. The regulation's phosphorus and sulfated ash limits are redrawing product viability boundaries faster than blenders can recertify existing portfolios.
Growth Catalysts
- Fleet electrification preparation:Hybrid-compatible lubricants are capturing service-bay attention as Mexico City ride-hailing operators pre-position for powertrain diversification. Drain-interval extension programs are accelerating semi-synthetic uptake among Uber and Didi vehicle owners.
- Bajío manufacturing corridor expansion:OEM assembly plants in Guanajuato and Querétaro are mandating lower-viscosity factory-fill specifications. This specification pull is cascading into aftermarket replacement demand.
- NOM-085-ECOL-2011:The emission standard's lubricant-performance requirements are creating compliance-driven replacement cycles. Ash-content restrictions are disqualifying legacy formulations and opening specification windows for reformulated products.
Market Restraints
- Base-stock import dependency:Mexico's domestic refining capacity concentrates Group I output, forcing blenders to import Group II and III stocks through Veracruz and Lázaro Cárdenas terminals. Currency volatility directly transmits into formulation cost instability.
- Additive package concentration:Four global suppliers control the majority of detergent-dispersant chemistry licensed for Mexican emission compliance. This supplier concentration limits negotiating leverage for mid-tier blenders.
- Extended drain-interval validation:Fleet operators lack OEM warranty coverage for interval extension beyond manufacturer specifications. This technical limitation caps semi-synthetic penetration in commercial passenger applications.
Strategic Opportunities
- Northern border states channel innovation:Cross-border e-commerce platforms are enabling direct-to-garage lubricant distribution in Baja California and Tamaulipas. This bypasses traditional distributor markups and captures price-sensitive independent repair shops.
- Lower-viscosity grade convergence:0W-16 and 0W-20 formulations are intersecting with hybrid engine thermal-management requirements. Blenders with pre-approved OEM specifications can capture premium positioning before commoditization accelerates.
- PROFECO performance-claim enforcement:Stricter labeling surveillance is creating compliance moats for laboratories with in-house testing infrastructure. Verified performance data is becoming a differentiable asset in retail channels.
Industry Challenges
- Additive chemist scarcity:Formulation expertise for low-SAPS (sulfated ash, phosphorus, sulfur) packages is concentrated among retiring specialists. Knowledge transfer gaps are delaying reformulation timelines for smaller blenders.
- Dual-certification complexity:Products must simultaneously satisfy API SP and ILSAC GF-6 standards while adapting to Mexican emission harmonization. Testing protocol overlap is extending product-launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Passenger Vehicles Lubricants Market |
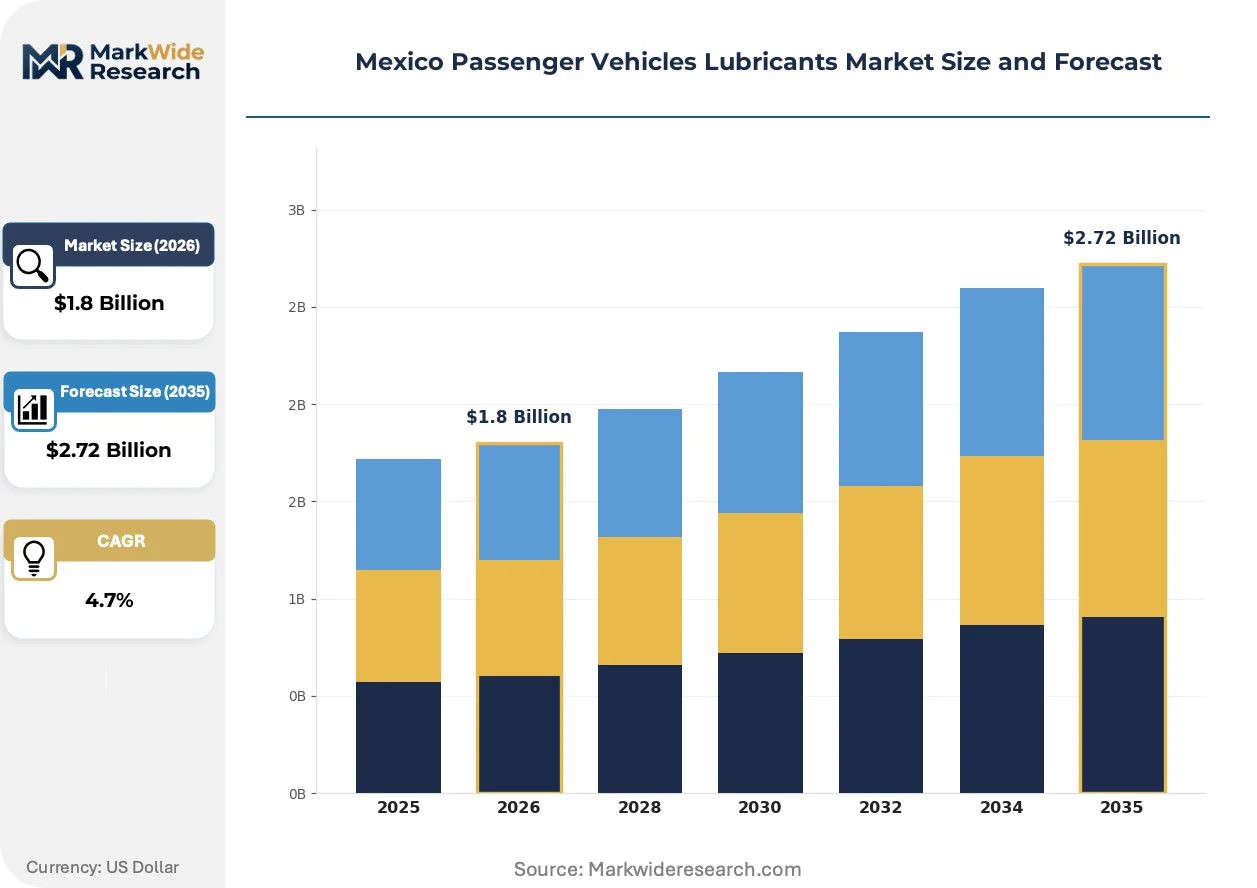
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease Application: Passenger Cars, SUVs, Light Trucks, Vans Formulation: Synthetic, Semi-Synthetic, Mineral, Bio-Based Distribution Channel: Retail Stores, Online Platforms, OEMs, Service Stations |
| Companies Covered | Roshfrans, Mexicana de Lubricantes S A de C V, Bardahl, TotalEnergies, Motul, BP PLC (Castrol), Royal Dutch Shell Plc, Valvoline Inc, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Passenger Vehicles Lubricants Market Shifts & Advancements
Reformulation velocity is overtaking traditional product-lifecycle patterns as emission standards compress development windows. Three concurrent shifts are restructuring how lubricants are engineered, certified, and distributed across Mexican passenger vehicle applications.
Polymer-based viscosity-index improvers are miniaturizing molecular architecture to maintain film strength across wider temperature ranges. Ride-hailing fleets in Mexico City are adopting these advanced formulations to protect engines during stop-start congestion cycles. The technology is miniaturizing the performance gap between mineral and synthetic base stocks, enabling semi-synthetic products to capture synthetic-adjacent pricing.
SEMARNAT is accelerating NOM-085-ECOL-2011 harmonization with EPA Tier 3 sulfur and particulate thresholds. This regulatory convergence is forcing additive suppliers to redesign detergent chemistry for gasoline direct-injection engines. Light-duty SUV segments are experiencing the fastest specification turnover as these powertrains dominate new-vehicle sales in the Bajío corridor.
Independent repair shops are consolidating procurement through cooperative buying groups to counter distributor pricing power. These collectives are displacing traditional jobber relationships in Guadalajara and Monterrey metropolitan zones. Digital platforms are capturing order flow by aggregating demand and negotiating direct blender relationships, compressing channel margins across central Mexico.
Mexico Passenger Vehicles Lubricants Market Segmentation
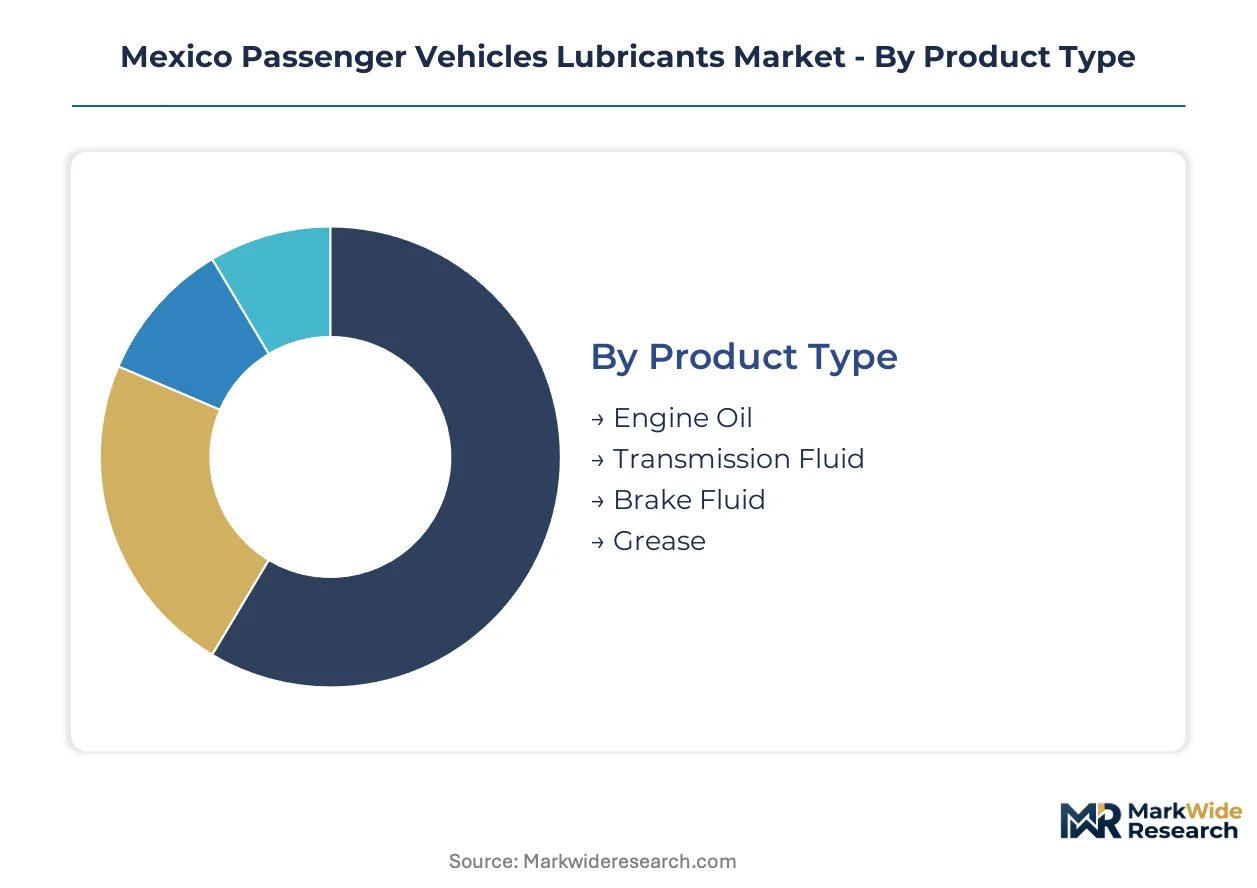
Product and channel configurations in Mexico's passenger vehicle lubricants sector determine margin capture and reformulation urgency. Specification divergence across OEM factory-fill and aftermarket replacement channels forces blenders to maintain parallel certification portfolios.
Product Type:
Retail stores and service stations dominate Engine Oil and Grease volumes, while OEMs and online platforms concentrate Transmission Fluid and Brake Fluid demand through technical specification channels.
- Engine Oil:Formulated from Group I through Group III base stocks with detergent-dispersant packages meeting SAE 0W-16 to 15W-40 grades. Demand concentrates in the Bajío corridor's dealer service bays as Guanajuato and Querétaro assembly plants mandate lower-viscosity factory-fill specifications. NOM-085-ECOL-2011 ash-content limits are disqualifying legacy formulations and accelerating reformulation cycles.
- Transmission Fluid:ATF and CVT-specific formulations with friction-modifier packages calibrated for dual-clutch and continuously variable architectures. Mexico City ride-hailing fleets are extending drain intervals through semi-synthetic ATF adoption, though OEM warranty coverage gaps cap penetration in commercial applications.
- Brake Fluid:Glycol-ether and silicone-based formulations meeting DOT 3, DOT 4, and DOT 5.1 specifications for hydraulic brake and clutch systems.
- Grease:Lithium-complex and calcium-sulfonate thickened lubricants for chassis, wheel bearing, and universal joint applications.
By volume, Engine Oil leads. By growth pace, Transmission Fluid is expanding most quickly.
Application:
Cost tier stratification separates premium synthetic positioning in SUVs from economy mineral formulations in aging passenger car fleets.
- Passenger Cars:Sedan and hatchback segments absorb the majority of aftermarket volume through independent repair shops in Guadalajara and Monterrey metropolitan zones. Semi-synthetic formulations are gaining traction among Uber and Didi vehicle owners pursuing drain-interval extension programs.
- SUVs:Light-duty SUV powertrains dominate new-vehicle sales in the Bajío corridor and command premium synthetic factory-fill specifications. These specifications cascade into aftermarket replacement demand through dealer service channels.
- Light Trucks:Pickup configurations for commercial and personal use requiring 5W-30 and 5W-40 formulations with enhanced soot-handling capacity.
- Vans:Passenger and cargo van segments with extended drain-interval requirements for fleet operators.
Passenger Cars command the largest volume share. SUVs generate the steepest margin expansion.
Formulation:
Supply concentration in additive chemistry limits negotiating leverage for mid-tier blenders pursuing low-SAPS certification.
- Synthetic:Group III and PAO-based formulations with polymer viscosity-index improvers for extreme temperature stability. Royal Dutch Shell Plc anchors premium positioning through its service-station network as OEM fill specifications shift toward 0W-16 and 0W-20 grades.
- Semi-Synthetic:Group II/III blends capturing synthetic-adjacent pricing through advanced polymer technology. Ride-hailing fleets in Mexico City are adopting these formulations to protect engines during stop-start congestion cycles without full synthetic cost exposure.
- Mineral:Group I base-stock formulations concentrated in price-sensitive independent repair shop channels.
- Bio-Based:Vegetable oil-derived formulations with biodegradable additive packages for environmentally regulated fleet applications.
Mineral formulations retain volume leadership. Semi-Synthetic is climbing the fastest on ride-hailing fleet conversion.
Distribution Channel:
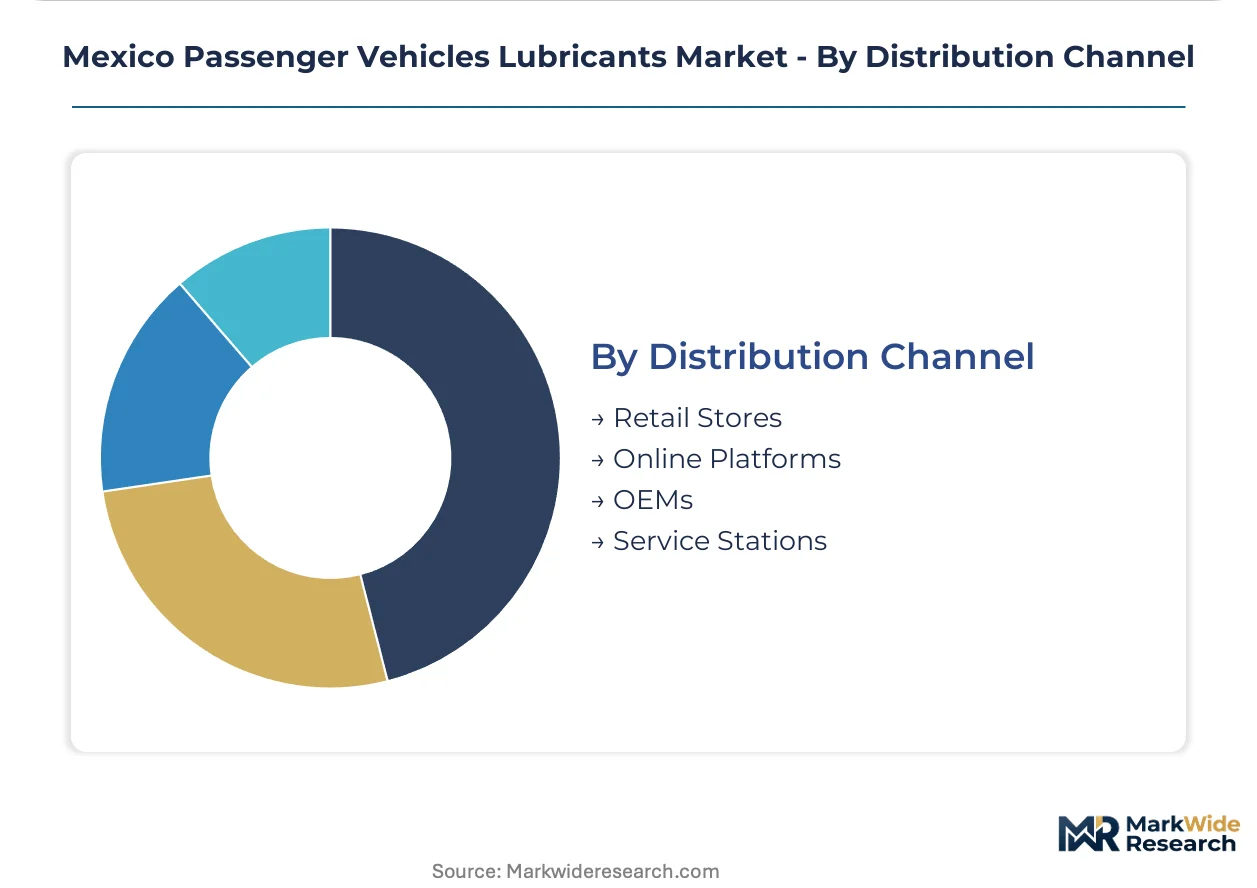
Geography determines channel effectiveness — northern border states enable online platform penetration while central Mexico concentrates service station and OEM dominance.
- Retail Stores:Auto parts chains and hypermarkets capturing price-sensitive consumer self-service demand in urban centers.
- Online Platforms:Cross-border e-commerce enabling direct-to-garage distribution in Baja California and Tamaulipas, bypassing traditional distributor markups.
- OEMs:Factory-fill and authorized service network specifications cascading from Guanajuato and Querétaro assembly plants into captive aftermarket demand.
- Service Stations:Branded lubricant sales tied to fuel retail networks with highest penetration in Mexico City metropolitan zone.
Service Stations and OEMs together dominate value capture. Online Platforms are gaining share fastest in northern border corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's lubricant trade balance tilts toward base-stock imports through Veracruz and Lázaro Cárdenas terminals, while finished formulations flow northward to service maquiladora clusters along the border. Regional demand patterns diverge sharply between central manufacturing corridors and northern logistics hubs.
Mexico City Metropolitan Zone
Ride-hailing fleet density drives semi-synthetic formulation uptake among Uber and Didi operators extending drain intervals. SEMARNAT enforces NOM-085-ECOL-2011 emission thresholds that compress additive chemistry timelines for gasoline direct-injection engines. The capital's congestion cycles accelerate polymer-based viscosity-index improver adoption to protect powertrains during stop-start operation.
Bajío Region
Guanajuato and Querétaro assembly plants mandate lower-viscosity factory-fill specifications cascading into aftermarket replacement demand. OEM service networks in this corridor capture premium synthetic positioning as 0W-16 and 0W-20 grades intersect with hybrid thermal-management requirements. The manufacturing concentration forces blenders to maintain parallel certification portfolios for captive and independent channels.
Nuevo León
Monterrey's industrial base anchors heavy-duty lubricant demand while passenger vehicle formulations compete through distributor density. Independent repair shops consolidate procurement through cooperative buying groups displacing traditional jobber relationships. The metropolitan zone's commercial vehicle heritage creates specification friction as passenger car service bays adopt divergent formulation standards.
Northern Border States
Baja California and Tamaulipas enable cross-border e-commerce platforms bypassing traditional distributor markups for direct-to-garage delivery. Currency volatility transmits directly into formulation cost instability given Group II and III base-stock import dependency. Price-sensitive independent repair shops in this corridor accelerate online platform penetration fastest among Mexican sub-regions.
Jalisco
Guadalajara's metropolitan zone concentrates aftermarket volume through independent repair channels serving aging passenger car fleets. Regional distributors compete on logistics reach into Michoacán and Colima hinterlands where service infrastructure remains fragmented. The state's automotive supplier ecosystem creates latent demand pull as OEM specifications migrate from central Mexico assembly plants.
Mexico Passenger Vehicles Lubricants Market Competitive Landscape
Concentration sits with integrated blenders controlling captive base-oil refining and domestic additive compounding. The competitive terrain stratifies between multinational service-station networks and regional distributors competing on logistics density. Three archetypes dominate: vertically integrated domestic refiners, premium synthetic specialists leveraging branded fuel retail, and border-focused distributors exploiting cross-border procurement channels. Capacity expansion and specification pre-certification constitute the dominant competitive moves as emission harmonization accelerates reformulation cycles.
Within the integrated domestic tier, Roshfrans anchors margin control through captive supply chain configuration across central Mexico. Royal Dutch Shell Plc occupies premium synthetic positioning through service-station network density in the capital metropolitan zone. Mexicana de Lubricantes S A de C V exemplifies regional distribution archetype concentration in northern border states where logistics reach determines competitive viability.
| Leading Market Players |
|---|
| Roshfrans |
| Mexicana de Lubricantes S A de C V |
| Bardahl |
| TotalEnergies |
| Motul |
| BP PLC (Castrol) |
| Royal Dutch Shell Plc |
| Valvoline Inc |
| ExxonMobil Corporation |
| Others |
Supply & Pricing Matrix
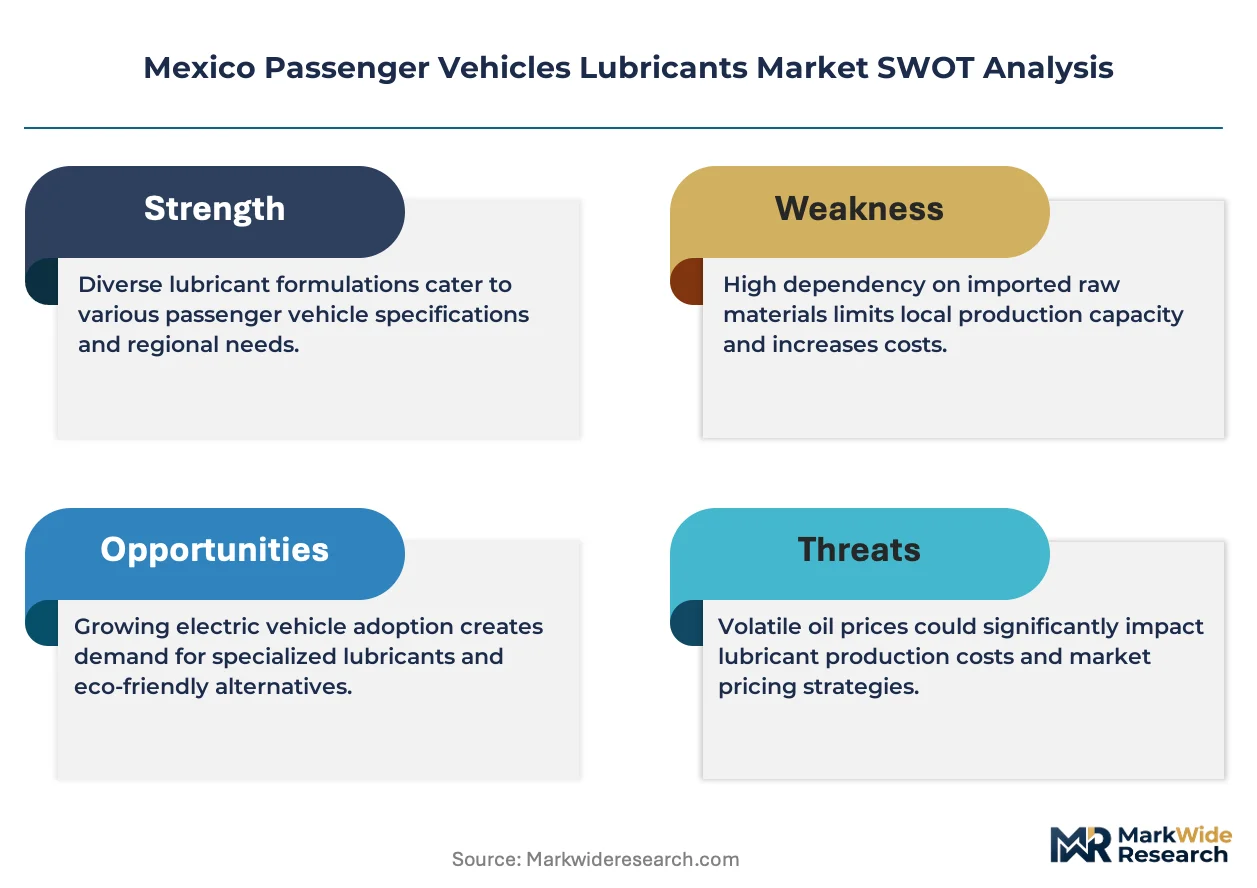
NOM-085-ECOL-2011 certification gates both supply qualification and price differentiation in Mexico's passenger vehicle lubricants sector. Blenders without SEMARNAT-compliant additive packages face market exclusion, while certified formulations command premium positioning through dealer service channels and OEM factory-fill mandates.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in Mexico's lubricant market. Price differentiation stems from certification grade against API SP and ILSAC GF-6 standards alongside volume scale commitments from fleet operators. Cost compression in economy mineral tiers is intensifying because currency volatility transmits directly into Group I base-stock margins. Independent repair shops in Guadalajara and Monterrey exhibit highest price sensitivity, while Bajío corridor OEMs tolerate premium synthetic positioning for warranty compliance.
Supply Chain Analysis
Inventory lead times for Group II and III base stocks extend through Veracruz and Lázaro Cárdenas import terminals, constraining blender formulation flexibility. Supply concentrates in United States Gulf Coast refineries, South Korean Group III producers, and domestic Pemex Group I output. Raw material dependencies span detergent-dispersant packages from global additive suppliers, polymer viscosity-index improvers, and corrosion inhibitor chemistries. Single-source vulnerability in licensed additive technology creates qualification bottlenecks for low-SAPS formulations. Distribution runs through captive OEM service networks, traditional jobber relationships, and emerging cross-border e-commerce channels in northern states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's passenger vehicle lubricants market operates as a regulatory moat where SEMARNAT certification entrenchment creates steep switching costs for fleet operators and OEM service networks.
For Market Incumbents: Compound defensive positioning through captive additive compounding capacity in central Mexico and pre-certification of 0W-16 formulations ahead of NOM-085-ECOL-2011 harmonization with EPA Tier 3. Accelerate backward integration into Group II base-oil sourcing to offset currency exposure on imports. Lock in Bajío corridor OEM service contracts before specification turnover cascades into aftermarket replacement demand. For New Entrants and Emerging Players: PROFECO performance-claim fast-track offers entry pathway through verified laboratory testing infrastructure. White-space concentrates in northern border states where cross-border e-commerce bypasses traditional distributor markups and captures price-sensitive independent repair shops. Target Baja California and Tamaulipas garages with direct-to-garage digital platforms offering semi-synthetic formulations at synthetic-adjacent performance positioning. For Investors and Strategic Acquirers: NOM-085-ECOL-2011 harmonization with EPA Tier 3 reshapes the acquisition landscape toward blenders with pre-certified low-SAPS portfolios and in-house testing capabilities. Long-term viability centers on regulatory compliance velocity rather than scale alone. Target regional distributors with dense logistics networks in Guanajuato and Querétaro manufacturing corridors. Monitor SEMARNAT enforcement intensity as inflection signal for reformulation cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Viscosity Pre-Certification | 0W-16 and 0W-20 approvals capture OEM factory-fill mandates ahead of specification commoditization. |
| Captive Additive Compounding | In-house detergent-dispersant production reduces dependency on four global suppliers controlling Mexican emission compliance. |
| Cross-Border E-Commerce Buildout | Direct-to-garage platforms in Baja California bypass traditional distributor markups for independent repair shops. |
| Group II Base-Oil Integration | Backward integration into imported base stocks hedges currency volatility transmitted through Veracruz terminals. |
| PROFECO Testing Infrastructure | Verified performance data creates compliance moats as labeling surveillance intensifies across retail channels. |
Research Methodology
Cross-validation between blender procurement data and OEM specification registries anchors the qualitative findings in this study. Primary interviews engaged lubricant formulation chemists, fleet procurement managers at Mexico City ride-hailing operators, aftermarket distributors in Monterrey and Guadalajara, and SEMARNAT regulatory affairs specialists. Secondary validation drew from customs import records through Veracruz and Lázaro Cárdenas, API licensing databases, PROFECO market surveillance reports, and Pemex refinery output disclosures. Bottom-up volume estimates from individual blender capacity triangulated against top-down demand projections from vehicle parc and drain-interval modeling.
Sensitivity analysis around base-stock import cost assumptions and NOM-085-ECOL-2011 enforcement timelines frames the projection uncertainty. The analytical framework segments across formulation type, application vehicle class, distribution channel, and regional production cluster throughout the forecast period. CAGRs derive from slope-intercept modeling of specification turnover rates and fleet conversion patterns. Key inputs include OEM factory-fill mandate trajectories from Guanajuato and Querétaro assembly plants and ride-hailing fleet electrification preparation timelines.
Decision-makers should treat outputs as directional under assumptions of sustained NOM-085-ECOL-2011 enforcement and stable base-stock import flows; material deviation in regulatory harmonization velocity or currency volatility would warrant model refresh. Specific risk factors include abrupt SEMARNAT specification updates, Pemex refinery capacity disruptions, and additive supplier consolidation affecting low-SAPS chemistry availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
Global Automotive Timing Belt Market
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Germany Automotive Parts Die Casting Market
Automotive Parts
Automotive Belts and Hoses Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
Brazil Automotive Hydraulic Actuators Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Automotive Parts Magnesium Die Casting Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
South Africa Passenger Vehicles Lubricants Market
Automotive Parts
Air Filter for Automotive Market