
 France Automotive Airfilters Market | 2026-2036
France Automotive Airfilters Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive Airfilters Market Foresight
Aftermarket providers is collapsing as a buyer archetype while vehicle assemblers and tier-1 suppliers consolidate procurement authority. Mann+Hummel Group leverages its vertical integration across media manufacturing and filter assembly to secure OEM contracts. Mahle GmbH sustains R&D intensity in nanofiber layering technologies for next-generation cabin filtration. Robert Bosch GmbH anchors its position through channel control of the independent workshop network across French automotive clusters.
France automotive airfilters are pleated or layered fibrous media devices engineered to remove particulate matter, pollen, and gaseous contaminants from intake or cabin air streams, typically rated for filtration efficiency against ISO 5011 test protocols and designed to protect engine components or occupant respiratory health. Panel air filters dominate installed volume in passenger vehicles due to standardized form factors and replacement simplicity, while nanofiber technology captures the fastest structural expansion as OEMs pursue extended service intervals. Cartridge air filters retain margin concentration in commercial vehicle applications where higher dust-loading environments justify premium pricing.
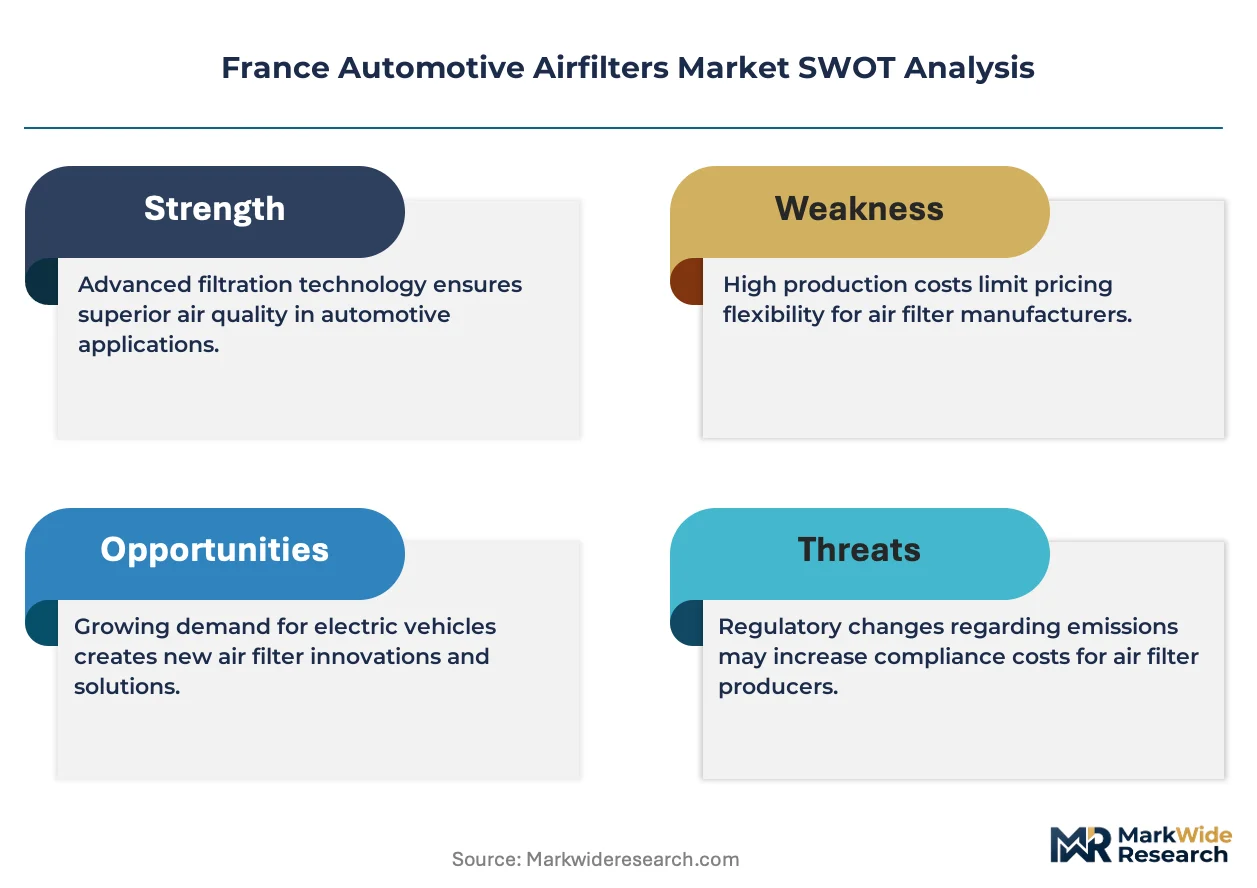
France's national environmental regulator enforces alignment with EU Green Deal emission trajectories, while ECHA oversees REACH compliance for filter media chemistry and material recyclability. ANSM monitors cabin air quality standards that indirectly elevate filtration specifications for vehicles operating in dense urban corridors. Stakeholders must weigh Euro 7 readiness investments against the risk of accelerated electrification reducing total engine airfilter addressable volume.
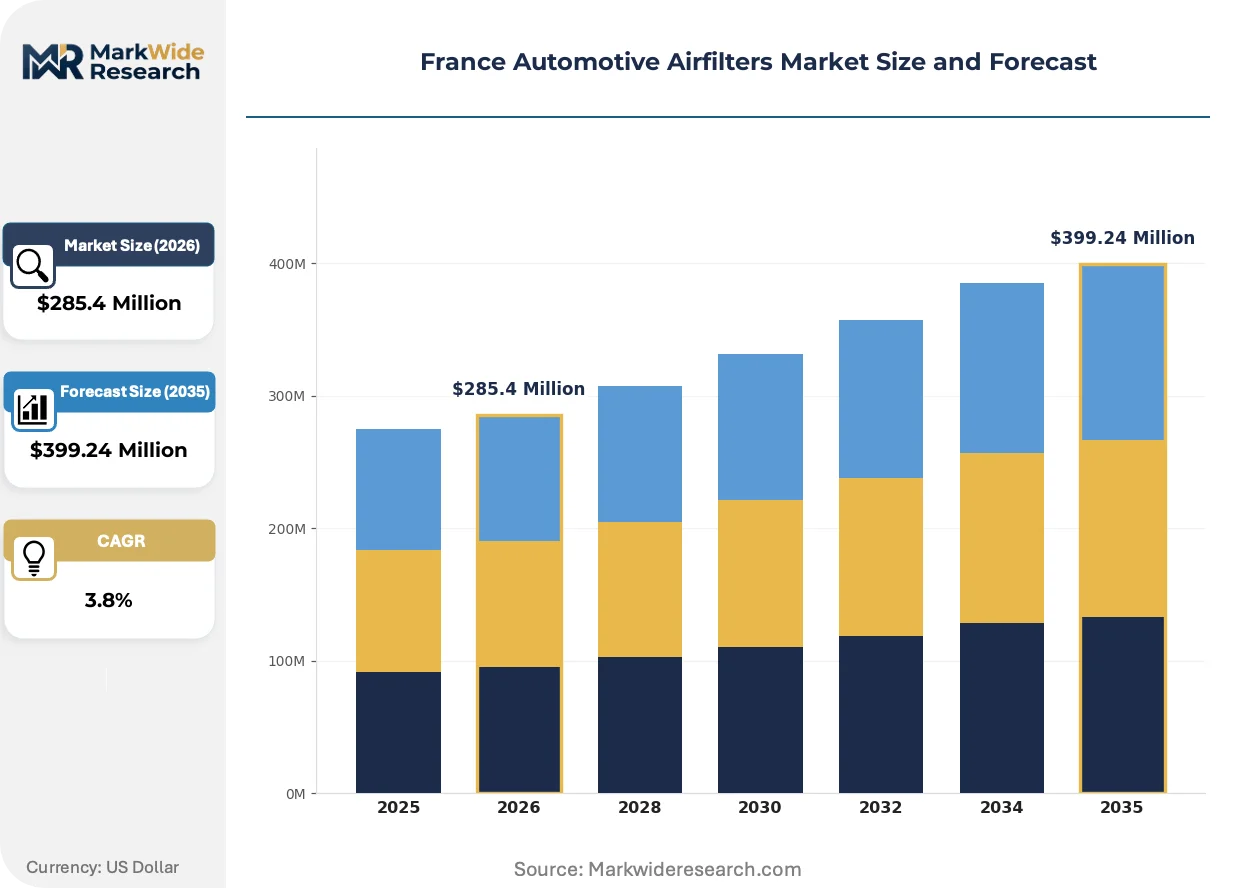
Market Dynamics
The France automotive airfilters market is being reshaped by Euro 7 emission readiness standards, which mandate tighter filtration thresholds and compress replacement cycles for legacy fleet operators.
Growth Catalysts
- Euro 7 Readiness Standards:The EU Green Deal trajectory enforced by France's environmental regulator tightens particulate matter capture requirements, forcing filter upgrades across diesel and gasoline vehicle populations.
- Extended Vehicle Retention:French households now retain passenger cars beyond historical replacement cycles, expanding the addressable aftermarket for cabin and engine airfilter replacements in aging fleets.
- Nanofiber Media Adoption:Advanced layering technologies enable extended service intervals, creating value differentiation for premium filter tiers in the Paris-Ile-de-France corridor where fleet density concentrates.
Market Restraints
- Electrification Substitution:Battery electric vehicles eliminate engine intake filtration entirely, eroding the core revenue base as French OEM electrification timelines accelerate.
- Raw Material Concentration:Synthetic fiber and activated carbon supply chains concentrate in Asian manufacturing clusters, exposing French filter assemblers to input cost volatility and logistics friction.
- REACH Compliance Burden:ECHA oversight of chemical substances in filter media raises formulation costs and extends product certification timelines for REACH-registered compounds.
Strategic Opportunities
- Cabin Air Quality Mandates:ANSM monitoring of urban air quality in dense corridors creates regulatory tailwinds for high-efficiency cabin filtration in vehicles operating across Lyon and Marseille metropolitan zones.
- Independent Workshop Channel Expansion:Workshop networks outside traditional OEM control capture growing filter procurement share, enabling direct-to-installer distribution models bypassing tiered parts hierarchies.
- Recyclable Media Innovation:EU circular economy directives pressure single-use filter disposal, opening white space for biodegradable or closed-loop recyclable media formulations compliant with extended producer responsibility frameworks.
Industry Challenges
- ISO 5011 Testing Bottlenecks:Certification laboratories face capacity constraints validating filtration efficiency claims, delaying product launches for aftermarket suppliers.
- Legacy Fleet Heterogeneity:Fragmented vehicle age profiles across French regions complicate inventory planning, as pre-Euro 6, Euro 6, and emerging Euro 7-ready vehicles require incompatible filter specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive Airfilters Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $399.24 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Air Filter, Cartridge Air Filter, Oil Bath Air Filter, Foam Air Filter, Composite Filter Technology: Dry Filter, Wet Filter, Electrostatic Precipitator, Activated Carbon, Nanofiber Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Industrial Vehicles, Agricultural Machinery End User: Aftermarket Providers, Vehicle Assemblers, Dealerships, Tier-1 Suppliers, Repair Workshops |
| Companies Covered | Mann+Hummel Group, Mahle GmbH, Robert Bosch GmbH, Hengst SE, Denso Corporation, Sogefi S.p.A., Donaldson Company, Valeo S.A., Freudenberg Filtration Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive Airfilters Market Shifts & Advancements
Filter media chemistry and procurement architecture are undergoing parallel transformation, with material science advances colliding against channel restructuring in the French aftermarket.
Nanofiber layering technology is displacing conventional cellulose and synthetic melt-blown media in premium cabin airfilter segments. French OEMs and tier-1 suppliers now specify multilayer nanofiber constructions for HVAC intake systems, capturing ultrafine particulates below 0.3 microns. This displacement compresses margin pools for commodity-grade filter manufacturers while elevating technical barriers to contract participation.
Euro 7 emission readiness standards, enforced through France's national environmental regulator, impose pre-compliance testing obligations on filter suppliers before formal regulation takes effect. The industrial consequence is accelerated R&D expenditure and premature obsolescence of filtration architectures designed to Euro 6d thresholds. Passenger vehicle applications face the steepest compliance gradient, with diesel powertrains in the Paris-Ile-de-France corridor requiring the most aggressive filter media upgrades.
Consolidated procurement authority is migrating from fragmented aftermarket distributors toward vehicle assemblers and tier-1 system suppliers. Independent repair workshops, while expanding volume share, increasingly source through controlled channels rather than open distribution. This concentration is most visible in the Rhône-Alpes and Provence-Alpes-Côte d'Azur regions, where workshop group purchasing organizations negotiate directly with filter manufacturers, compressing traditional parts wholesaler margins.
France Automotive Airfilters Market Segmentation
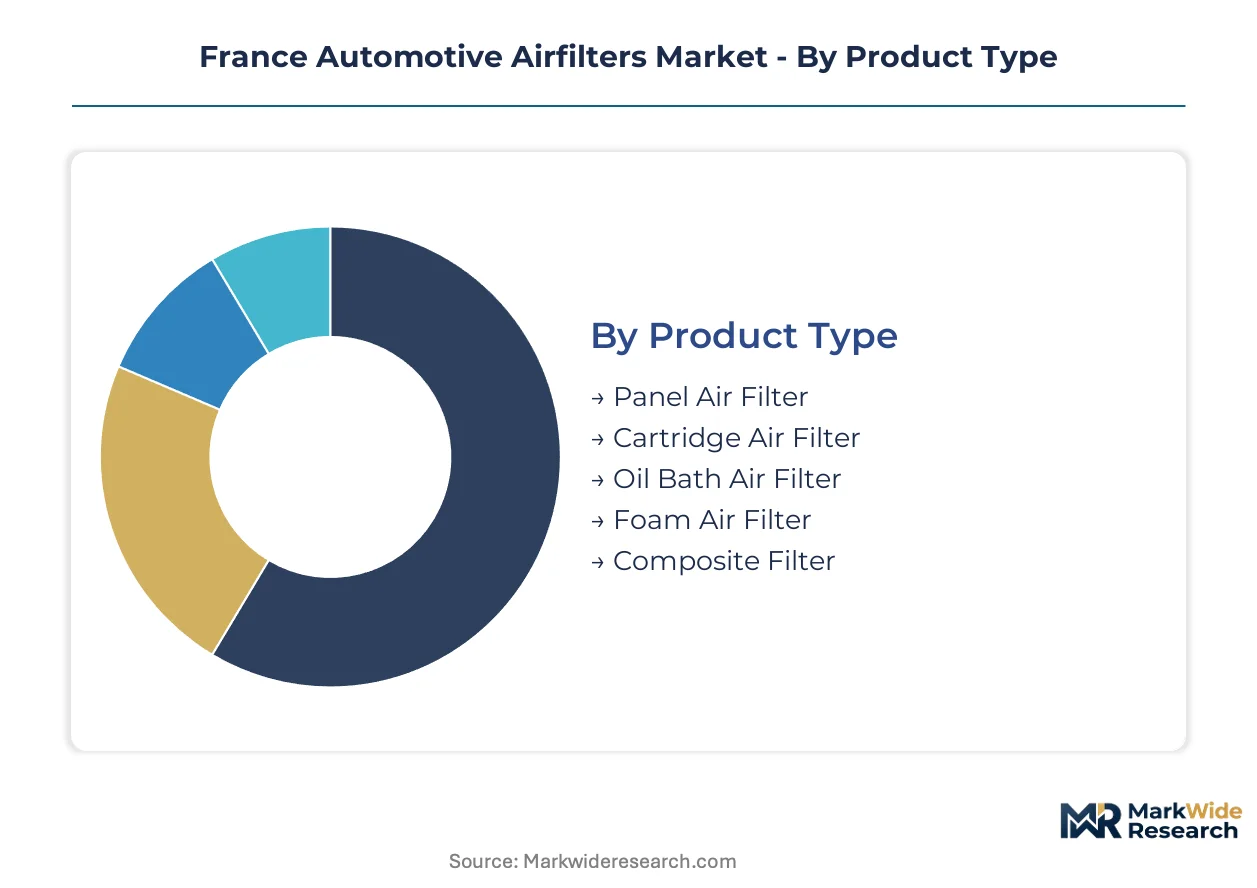
Segmentation in the France automotive airfilters market reveals how procurement authority and margin pools have shifted toward tier-1 suppliers and controlled workshop channels. Filter specifications now diverge sharply between legacy internal combustion fleets and emerging electrification scenarios, forcing suppliers to maintain parallel product architectures.
Product Type:
Margin concentration in this category aligns with replacement frequency and technical complexity rather than unit volume alone.
- Panel Air Filter:Pleated cellulose or synthetic media housed in rigid plastic frames, engineered for drop-in replacement without tooling. Demand clusters in passenger vehicle aftermarket channels across the Paris-Ile-de-France corridor, where high fleet density and Euro 7 pre-compliance maintenance cycles compress replacement intervals. ANSM-monitored air quality standards in dense urban zones further elevate specification requirements.
- Cartridge Air Filter:Cylindrical or oval media elements requiring housing disassembly for service, constructed with higher dust-loading capacity for severe-duty environments. Commercial vehicle operators in Lyon and Marseille metropolitan zones specify these for extended service intervals in logistics and construction applications, justifying premium positioning through total cost-of-ownership calculations.
- Oil Bath Air Filter:Legacy architecture using oil-coated mesh to trap particulates, now confined to vintage vehicle restoration and specific agricultural machinery segments where regulatory grandfathering applies.
- Foam Air Filter:Polyurethane matrix media common in two-wheeler and powersports applications, offering washability and reusability that appeals to cost-conscious owner-maintainers.
- Composite Filter:Hybrid constructions combining multiple media layers for staged particulate capture, specified by French OEMs pursuing extended service interval differentiation in premium vehicle segments.
The dominant share belongs to Panel Air Filter, while Cartridge Air Filter is closing the gap fastest.
Technology:
Cost tier stratification in this category separates commodity replacement media from value-added filtration architectures.
- Dry Filter:Conventional pleated cellulose or synthetic melt-blown media operating without supplemental coating systems, capturing particulates through mechanical interception alone. Volume concentrates in economy aftermarket tiers serving aging pre-Euro 6 fleets across Provence-Alpes-Côte d'Azur, where price sensitivity dominates procurement decisions.
- Wet Filter:Oil-impregnated or coated media enhancing particulate adhesion, historically specified for high-dust environments but declining under REACH compliance burdens for chemical formulation disclosure.
- Electrostatic Precipitator:Active filtration using electrostatic charge to attract and capture sub-micron particles, deployed in premium cabin air systems for luxury vehicle segments where occupant health positioning justifies incremental cost.
- Activated Carbon:Adsorptive layer neutralizing gaseous contaminants and odors, now standard specification in HVAC intake systems for vehicles operating in ANSM-monitored urban air quality corridors.
- Nanofiber:Sub-micron fiber matrices achieving filtration efficiencies below 0.3 microns, capturing the steepest specification upgrades as French OEMs pursue Euro 7 readiness and extended service interval claims.
Dry Filter retains volume leadership, though Nanofiber is expanding share most aggressively.
Application:
Customer type dynamics in this category separate fleet-managed replacement programs from dispersed owner-maintainer behaviors.
- Passenger Vehicles:Light-duty automobiles and SUVs comprising the core installed base, with filtration demand bifurcating between engine intake systems and cabin air quality modules. The Paris-Ile-de-France corridor concentrates aftermarket volume due to fleet density and regulatory enforcement intensity, while electrification timelines threaten long-term engine filter addressable volume.
- Commercial Vehicles:Heavy and medium-duty trucks, buses, and vans operating in severe-duty cycles with higher dust-loading and extended operating hours. Fleet operators in Rhône-Alpes logistics corridors negotiate direct procurement contracts with filter manufacturers, bypassing traditional distribution tiers.
- Two-Wheelers:Motorcycles and scooters with compact filter architectures, representing a fragmented aftermarket served through specialized retail channels rather than mainstream automotive distribution.
- Industrial Vehicles:Construction, mining, and material handling equipment with custom filter specifications tied to non-road mobile machinery emission regulations.
- Agricultural Machinery:Tractors and harvesters operating in high-dust field environments, with seasonal demand patterns and dealer-centric service relationships.
Passenger Vehicles command the dominant position, while Commercial Vehicles are gaining ground through fleet consolidation.
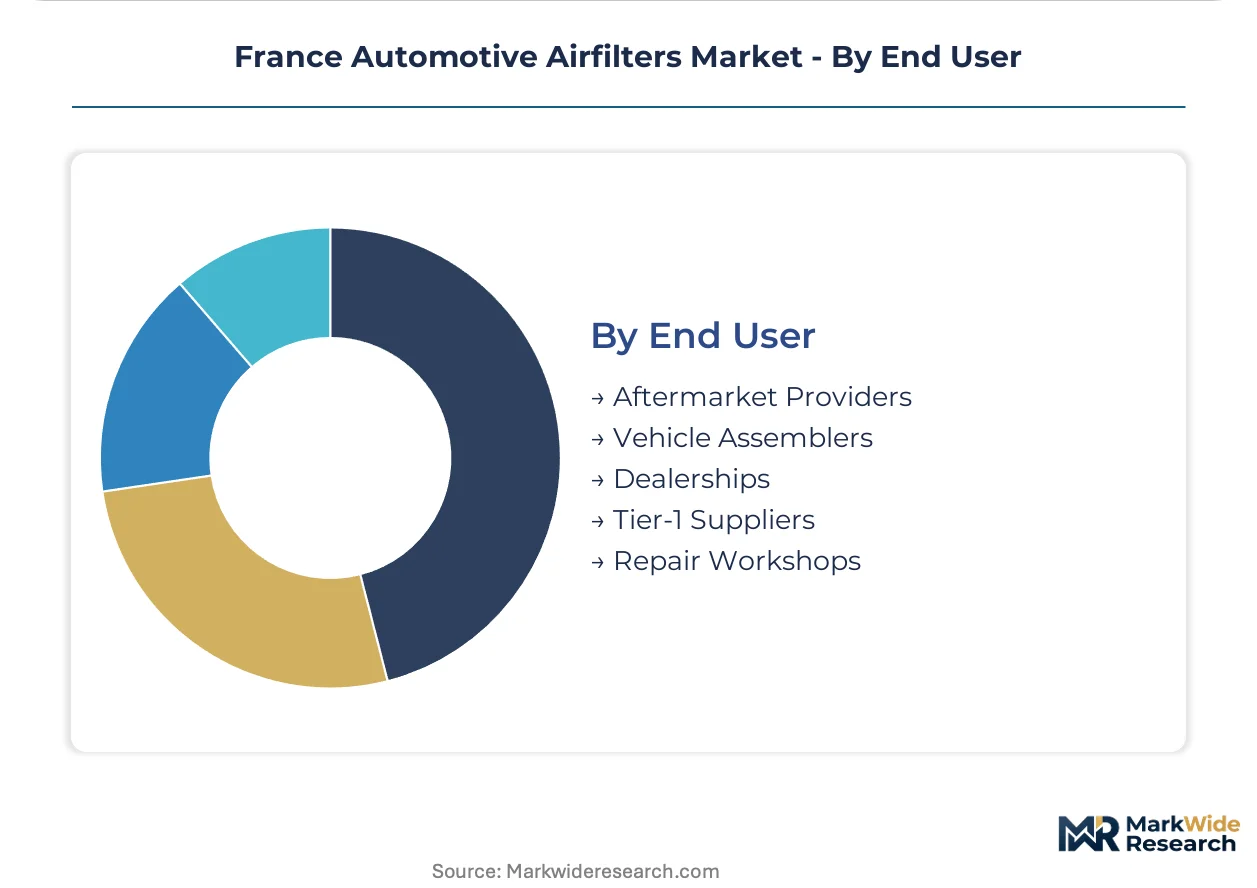
End User:
Supply concentration in this category has shifted procurement authority toward consolidated channel controllers and away from fragmented distributors.
- Aftermarket Providers:Independent distributors and parts wholesalers serving open market demand, now facing margin compression as procurement migrates toward controlled channels and direct manufacturer relationships.
- Vehicle Assemblers:OEMs specifying first-fit filtration systems for new vehicle production, consolidating supplier bases around vertically integrated partners capable of Euro 7 readiness co-development.
- Dealerships:Authorized service networks capturing warranty and routine maintenance filter replacements, with procurement increasingly directed by assembler-mandated supplier programs.
- Tier-1 Suppliers:System integrators supplying complete HVAC or powertrain modules, exercising filtration media selection authority and backward integrating into media manufacturing where scale permits.
- Repair Workshops:Independent service providers expanding volume share as French households retain vehicles longer, increasingly sourcing through group purchasing organizations that negotiate directly with filter manufacturers.
Vehicle Assemblers hold the dominant procurement position, while Repair Workshops are expanding their influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German filter manufacturers export finished media and assemblies to French OEM supply chains through the Rhine-Ruhr logistics corridor, while Spanish aftermarket distributors serve as secondary sourcing nodes for southern French workshop networks.
Île-de-France
Paris metropolitan fleet density drives the highest per-capita filter consumption in France, with Euro 7 pre-compliance maintenance compressing replacement cycles for diesel passenger vehicles. ANSM-monitored air quality standards in the capital zone mandate activated carbon cabin filtration for vehicles operating within the A86 ring road. Tier-1 suppliers cluster in the Plaine Saint-Denis industrial zone, backward integrating into media manufacturing to serve Renault and Stellantis assembly plants.
Auvergne-Rhône-Alpes
Lyon's logistics corridor concentrates commercial vehicle fleet operators negotiating direct procurement contracts with filter manufacturers for heavy-duty cartridge specifications. ECHA REACH compliance costs weigh on small distributors serving the Rhône valley agricultural machinery segment. Saint-Étienne hosts specialty media converters supplying nanofiber layering components to tier-1 HVAC module assemblers.
Provence-Alpes-Côte d'Azur
Marseille-Fos port infrastructure handles bulk activated carbon imports for cabin filter media formulations serving Mediterranean climate conditions. Independent workshop group purchasing organizations in the Aix-en-Provence industrial basin bypass traditional parts wholesalers. The region's tourism-dependent vehicle fleets prioritize cabin air quality upgrades to address seasonal pollen loads.
Hauts-de-France
Lille's cross-border position enables Belgian and Dutch filter distributors to capture procurement share from French fleet operators near the Schengen frontier. The Dunkirk industrial zone hosts chemical fiber production feeding filter media manufacturers. Euro 7 readiness investments concentrate in powertrain engineering facilities serving the broader Northern European automotive cluster.
Nouvelle-Aquitaine
Bordeaux's wine logistics and agricultural machinery base sustains demand for severe-duty filtration in dust-intensive operating environments. The region's lower fleet density relative to northern corridors shifts procurement toward dealer-centric service relationships. Biodegradable media research programs at local engineering institutes align with EU circular economy directives on filter recyclability.
France Automotive Airfilters Market Competitive Landscape
Player mix skews toward vertically integrated German industrial conglomerates with captive media manufacturing capabilities, compressing margin pools for pure-play aftermarket distributors. Structural concentration favors tier-1 system suppliers exercising filtration specification authority within OEM-mandated supplier programs. Three archetypes dominate: full-range filtration specialists with backward integration into media chemistry, automotive system integrators selecting filtration as a module component, and region-focused aftermarket distributors losing share to controlled workshop channels. Competitive moves center on Euro 7 co-development partnerships with French OEMs and direct sourcing arrangements with independent workshop group purchasing organizations.
Among German-based filtration specialists, Mann+Hummel Group and Mahle GmbH exemplify the vertically integrated archetype controlling media manufacturing and filter assembly. Robert Bosch GmbH anchors a distinct positioning through channel control capabilities spanning the independent workshop network. These three entities represent the consolidation trajectory as procurement authority migrates from fragmented distributors toward system-level suppliers capable of Euro 7 readiness co-development.
| Leading Market Players |
|---|
| Mann+Hummel Group |
| Mahle GmbH |
| Robert Bosch GmbH |
| Hengst SE |
| Denso Corporation |
| Sogefi S.p.A. |
| Donaldson Company |
| Valeo S.A. |
| Freudenberg Filtration Technologies |
| Others |
Supply & Pricing Matrix
Nanofiber media substitution for conventional cellulose and synthetic melt-blown architectures simultaneously concentrates supply geography in German and Japanese specialty fiber production zones while compressing pricing economics for commodity-grade filter manufacturers unable to achieve Euro 7 efficiency thresholds. This displacement dynamic elevates procurement power for tier-1 suppliers with backward integration into media chemistry while eroding margin pools for pure-play aftermarket distributors.
Pricing Analysis
The pricing gap separating nanofiber-enabled next-generation filters from dry media current-generation products and legacy wet filter prior-generation architectures defines competitive positioning across French procurement channels. Three-tier pricing structure across premium nanofiber, standard synthetic-cellulose composite, and economy dry media levels reflects certification grade against ISO 5011 protocols and brand premium anchored by Mann+Hummel and Mahle GmbH channel control. Cost compression in economy tiers is intensifying because REACH compliance burdens raise formulation costs for chemical coating systems. Independent repair workshops exhibit highest price sensitivity, while vehicle assemblers prioritize total cost-of-ownership calculations over unit procurement.
Supply Chain Analysis
Germany and Japan anchor specialty nanofiber media manufacturing for French OEM supply chains, while China and South Korea concentrate synthetic fiber and activated carbon production feeding filter assembly operations. Raw material dependencies rest on polypropylene melt-blown media, glass microfiber substrates, and coconut-shell activated carbon for cabin odor control. Single-source vulnerability concentrates in Asian chemical fiber supply clusters exposed to logistics friction through Suez Canal routing. Distribution runs through tier-1 system suppliers exercising filtration specification authority within OEM-mandated supplier programs, bypassing traditional aftermarket wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France automotive airfilters market sits at a platform-economics inflection where HVAC module standardization across Stellantis and Renault vehicle platforms is collapsing supplier diversity and privileging ecosystem-integrated filtration specialists over component vendors.
For Market Incumbents: Secure Euro 7 co-development partnerships with French OEMs before formal regulation takes effect, anchoring procurement relationships through joint testing protocols at certification laboratories facing ISO 5011 capacity constraints. Deepen upstream control over nanofiber media manufacturing to defend margin position against Asian chemical fiber cost volatility, while consolidating channel control of independent workshop group purchasing organizations in the Rhône-Alpes and Provence-Alpes-Côte d'Azur regions. For New Entrants and Emerging Players: ANSM fast-track certification for cabin air quality modules targeting the Paris-Ile-de-France corridor presents the most penetrable entry vector, as regulatory enforcement intensity outpaces incumbent R&D cycles. Biodegradable media formulations aligned with EU circular economy directives offer white-space differentiation in Nouvelle-Aquitaine agricultural machinery segments where seasonal demand patterns favor flexible supply arrangements. Direct-to-installer distribution bypassing tiered parts hierarchies captures procurement share from margin-compressed aftermarket distributors. For Investors and Strategic Acquirers: The market sits at a pre-regulatory compliance phase that favors vertically integrated media manufacturers with captive nanofiber production capabilities and established OEM validation relationships. Long-term viability over the electrification transition window hinges on cabin filtration diversification as engine intake volumes erode. Watch Stellantis and Renault electrification timeline announcements as the critical inflection signal for engine airfilter addressable volume compression.| Strategic Initiative | Industry Significance |
|---|---|
| Euro 7 Co-Development Partnership | Joint validation with ANSM-monitored testing protocols secures OEM first-fit positioning before regulatory enforcement. |
| Nanofiber Media Manufacturing Scale-Up | Captive production of sub-0.3 micron fiber matrices defends margin against Asian input cost volatility. |
| Workshop Group Purchasing Organization Integration | Direct contracting with Rhône-Alpes service networks bypasses traditional distribution margin extraction. |
| Biodegradable Filter Media R&D Program | EU circular economy alignment opens procurement channels in ECHA-regulated sustainability frameworks. |
| Cabin Air Quality Module Platform Standardization | HVAC system integration with Stellantis and Renault architectures captures electrification-resilient revenue streams. |
Research Methodology
Cross-validation between primary interviews with tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and independent workshop group purchasing managers anchors the qualitative findings against secondary validation from vehicle production databases, IHS Markit registration data, ECHA REACH substance filings, and ANSM air quality monitoring reports. Bottom-up segmentation modeling triangulates against top-down market sizing derived from French automotive cluster economic data.
Sensitivity analysis across the projection horizon tests forecast robustness against electrification penetration scenarios, Euro 7 implementation timing variations, and raw material cost volatility assumptions. Segmentation dimensions span product type, technology tier, vehicle application, and end-user procurement channel, with content-per-vehicle metrics and regional fleet density gradients incorporated as automotive-specific forecast inputs. CAGRs derive from regression analysis of historical replacement cycle compression and regulatory-driven specification upgrades.
Decision-makers should treat outputs as directional under base assumptions of sustained internal combustion fleet retention and Euro 7 pre-compliance investment cycles; material deviation in electrification adoption rates or regulatory enforcement timing would warrant model refresh. Recalibration cycles align with material shifts in OEM platform standardization announcements and ANSM air quality mandate expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Automotive Evaporators and Blowers Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
China Automotive Parts Aluminum Die Casting Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Global Aerodynamic Automotive Market
Automotive Parts
Harmonic Gearboxes Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Automotive Suspension Control Arms Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Europe Automotive Parts Die Casting Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
South Africa Commercial Vehicles Lubricants Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Automotive Coolant Market