
 External Combustion Engine Market | 2026-2036
External Combustion Engine Market Size, Share, and Industry Trends Forecast 2026-2036
External Combustion Engine Market Foresight
Alloy substitution toward high-temperature nickel superalloys is shifting thermal tolerance benchmarks for Stirling engine heaters and steam boiler components. Siemens Energy leverages in-house casting capabilities to secure supply chains for these advanced materials. Qnergy Inc. competes through modular Stirling designs optimized for remote oilfield power. Sunpower Inc. anchors its position via precision free-piston architectures that reduce maintenance intervals in continuous-duty applications.
An external combustion engine burns fuel outside the working cylinder, transferring thermal energy through heat exchangers to drive pistons or expand working gases such as helium, hydrogen, or steam at pressures ranging from 15 to 200 bar. This architecture enables multi-fuel flexibility and low-emission operation for baseload power generation, marine auxiliary systems, and industrial heat-to-power conversion. The Stirling engine segment leads in distributed energy deployments due to its compatibility with solar thermal and biomass heat sources, while steam engine variants retain dominance in marine propulsion retrofits where existing boiler infrastructure limits technology switching. Hybrid systems integrating thermal storage with external combustion cycles represent the fastest-expanding technology category as grid operators seek dispatchable renewable backup.
The EPA enforces stationary source emissions limits that favor external combustion configurations in non-attainment zones, while the EU F-Gas Regulation restricts fluorinated working fluids and redirects investment toward helium-based Stirling systems. ISO 9001 and ISO 14001 certifications function as baseline market access requirements for suppliers bidding into European and North American utility procurement frameworks. Stakeholders must track evolving carbon border adjustment mechanisms and working fluid phase-out schedules to preserve product qualification across key jurisdictions.
Market Dynamics
Alloy supply concentration among German and Japanese specialty foundries is compressing heater-head manufacturing timelines for Stirling engine OEMs, forcing procurement teams to qualify secondary material sources eighteen months ahead of production ramps.
Growth Catalysts
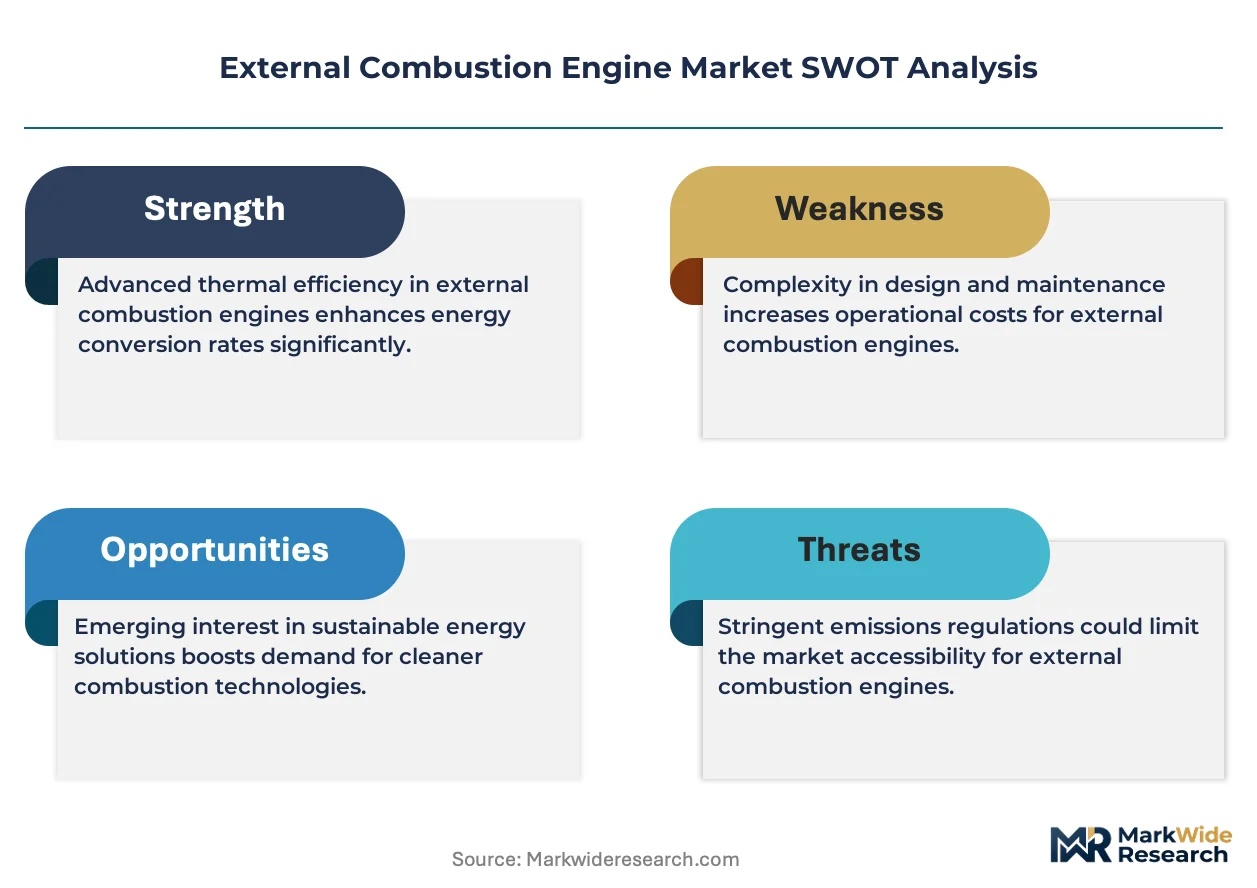
- EU F-Gas Regulation phase-down:Restrictions on HFC working fluids redirect capital toward helium-recovery infrastructure and sealed-system Stirling architectures compatible with inert gas cycles.
- Biomass district heating retrofits:Municipal operators in Denmark and Sweden integrate external combustion CHP units to satisfy national carbon-neutrality mandates for building stock decarbonization.
- Waste-heat recovery:Steel and cement producers deploy organic Rankine cycle variants to capture exhaust thermal energy, converting 150°C to 400°C process streams into exportable electricity.
Market Restraints
- Nickel superalloy price volatility:Inconel 718 and Haynes 230 account for 35-45% of heater-head BOM cost, exposing margins to London Metal Exchange nickel contract swings.
- Precision casting bottleneck:Single-source dependence on German investment casting houses limits Stirling engine production scaling during demand surges.
- Heat exchanger fouling:Biomass combustion deposits degrade thermal transfer efficiency in steam boiler tubes, requiring quarterly maintenance cycles that compress capacity factors.
Strategic Opportunities
- Remote oilfield electrification:Unmanned well pads in West Texas and North Dakota create demand for 5-50 kW Stirling units running on associated gas flares.
- Thermal storage hybridization:Molten salt reservoirs paired with external combustion cycles enable 8-12 hour dispatchable renewable backup for islanded microgrids.
- US Inflation Reduction Act credits:Investment tax incentives for clean hydrogen production create adjacent demand for high-temperature steam electrolysis powered by external combustion heat sources.
Industry Challenges
- Helium containment engineering:Sealing free-piston Stirling engines against working fluid loss demands specialized glass-metal bonding expertise concentrated at three US and Japanese suppliers.
- ISO 9001/14001 audit backlogs:European notified bodies face eighteen-month certification queues, delaying supplier qualification for utility procurement frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | External Combustion Engine Market |
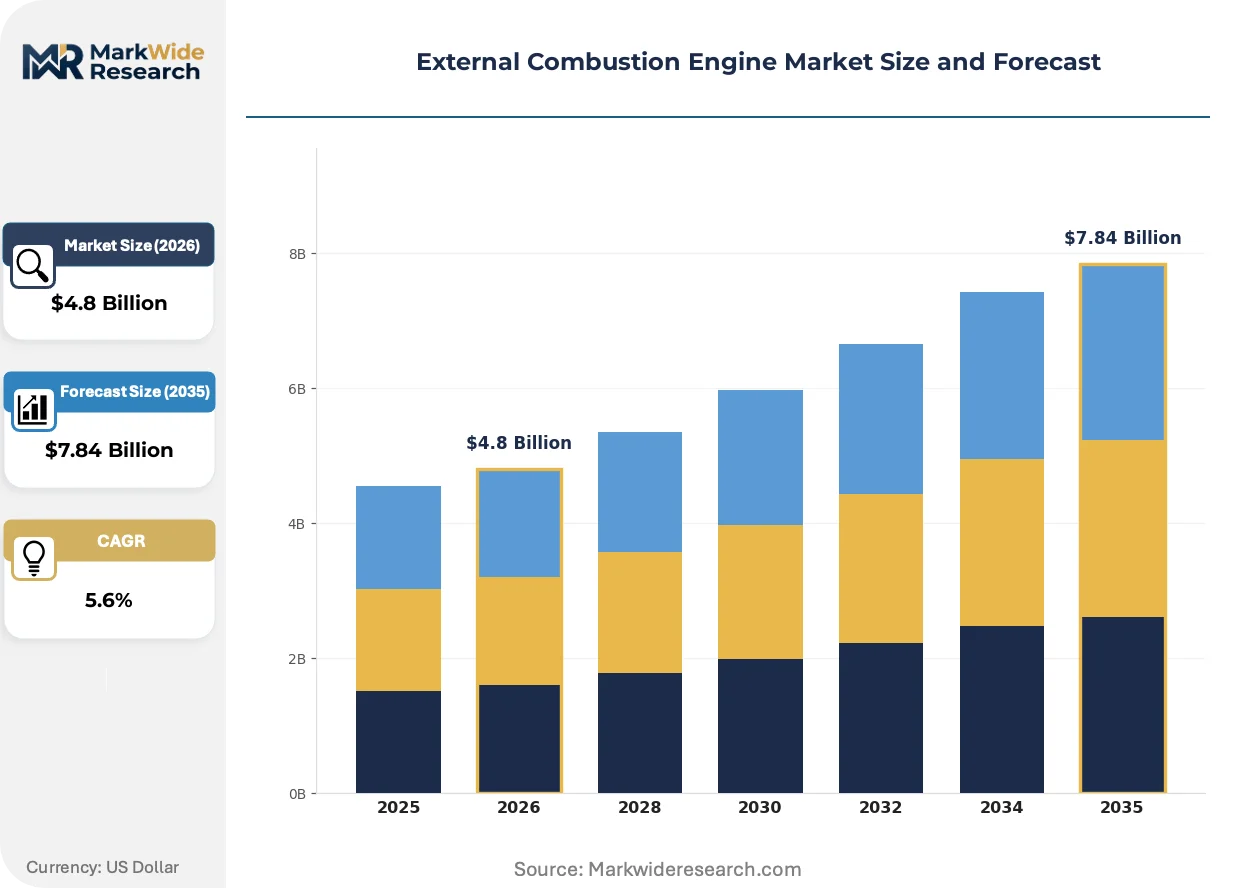
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Engine, Stirling Engine, Hot Air Engine, Tricylinder Engine Technology: Thermal Efficiency, Heat Recovery, Fuel Flexibility, Hybrid Systems Application: Power Generation, Marine Propulsion, Industrial Machinery, Heating Systems End User: Manufacturing, Energy, Agriculture, Transportation |
| Companies Covered | Qnergy Inc., Siemens Energy, FlexEnergy Inc., Aisin Corporation, Genoastirling AB, Stirling Thermal Motors Inc., Sunpower Inc., Deere & Company, Microgen Engine Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
External Combustion Engine Market Shifts & Advancements
Modular Stirling architectures are fragmenting the traditional centralized power plant model, enabling distributed generation at scales from residential CHP to industrial waste-heat recovery without transmission infrastructure dependency.
Free-piston Stirling engines with linear alternators are decentralizing baseload power architecture for remote telecommunications and offshore platforms. Shell and BP field operations teams now specify these units for unmanned installations where diesel resupply costs exceed $8 per liter. The elimination of crankcase lubrication and sliding seals compresses maintenance intervals from quarterly to biennial cycles, reshaping lifecycle cost calculations for asset managers.
EPA stationary source performance standards under the Clean Air Act are forcing coal-reliant industrial facilities toward external combustion retrofits in non-attainment zones. The 2012 Mercury and Air Toxics Standards and subsequent residual risk reviews impose strict particulate and SOx limits that internal combustion engines cannot economically satisfy. Cement producers in the Ohio River Valley respond by converting existing boiler infrastructure to biomass cofiring with external combustion topping cycles.
Utility procurement teams now unbundle equipment supply from long-term service agreements, compressing vendor margins on aftermarket parts. European district heating cooperatives in the Netherlands and Austria negotiate performance-based contracts where OEMs retain ownership of Stirling CHP units and sell guaranteed heat output. This shifts capital burden from municipal balance sheets to equipment financiers, altering competitive dynamics for Siemens Energy and Qnergy bidding strategies.
External Combustion Engine Market Segmentation
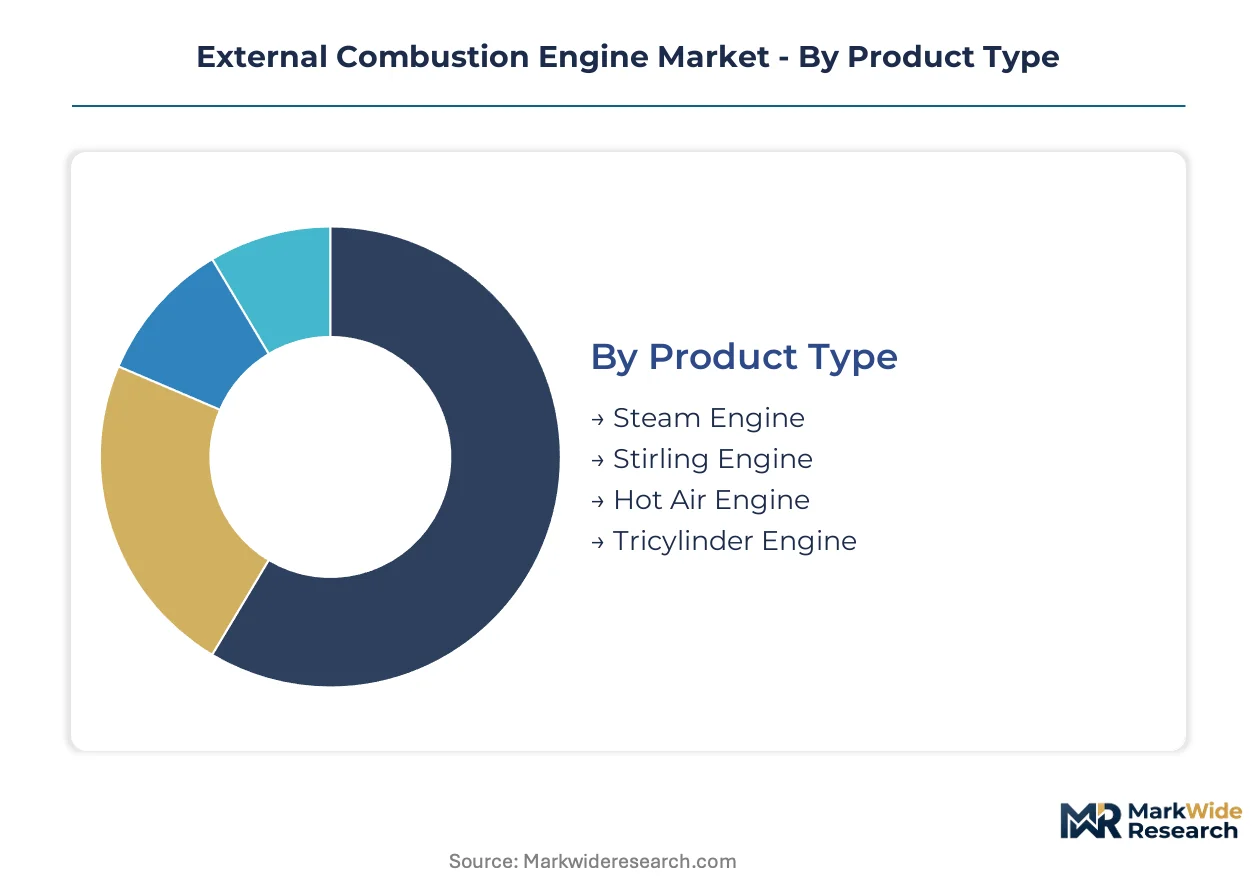
External combustion architectures fragment across thermal cycle designs, integration depths, and fuel-handling capabilities. Procurement patterns diverge sharply between utilities seeking baseload reliability and industrial operators prioritizing waste-heat capture.
Product Type:
Standalone prime movers dominate utility-scale installations, while embedded configurations penetrate distributed energy and marine auxiliary markets.
- Steam Engine:Reciprocating or turbine configurations expand pressurized steam through cylinder arrays or rotating blading at temperatures exceeding 500°C. Demand concentrates in German and Chinese shipyards executing marine propulsion retrofits where existing boiler infrastructure constrains technology migration.
- Stirling Engine:Closed-cycle regenerative systems compress and expand helium or hydrogen via piston-displacer pairs, achieving thermal efficiencies above 40% in free-piston architectures. Danish district heating cooperatives deploy these units for biomass-fired CHP, satisfying national carbon-neutrality mandates for building stock decarbonization.
- Hot Air Engine:Open-cycle external combustion variants utilizing atmospheric air as working fluid, limited to sub-200°C operation by material constraints. Agricultural machinery OEMs in India specify these for irrigation pump drives where fuel flexibility outweighs efficiency priorities.
- Tricylinder Engine:Three-cylinder radial configurations optimizing power-to-weight ratios for compact auxiliary power units. Remote telecommunications installations in Australia specify these for off-grid base station backup.
Volume placements concentrate in Steam Engine configurations; the faster expansion belongs to Stirling Engine architectures.
Technology:
Cost tiers separate mature thermal efficiency improvements from emerging hybrid integrations requiring substantial capital commitment.
- Thermal Efficiency:Advanced regenerator designs and high-temperature heater-head alloys push brake thermal efficiency toward 45% in Stirling variants. Cement producers in the Ohio River Valley prioritize these systems for waste-heat recovery topping cycles.
- Heat Recovery:Organic Rankine cycle and steam bottoming configurations capture exhaust streams from 150°C to 400°C. Steel mills in Japan deploy these to convert process thermal energy into exportable electricity under METI efficiency mandates.
- Fuel Flexibility:Multi-fuel combustion chambers accommodating biomass, syngas, and hydrogen without hardware modification. Remote oilfield operators in West Texas favor these for associated gas utilization.
- Hybrid Systems:Thermal storage integration enabling 8-12 hour dispatchable output from renewable heat sources. Islanded microgrids in Hawaii specify molten salt paired external combustion cycles for grid stability.
Capital deployment favors Thermal Efficiency upgrades; Hybrid Systems are climbing the fastest as grid operators seek dispatchable renewable backup.
Application:
Customer type segmentation reveals divergent procurement patterns between regulated utilities and industrial self-generators.
- Power Generation:Baseload and peaking installations from 50 kW to 50 MW utilizing external combustion for multi-fuel compatibility. Swedish municipal utilities integrate these for biomass district heating CHP.
- Marine Propulsion:Steam turbine and reciprocating engine configurations for commercial shipping retrofits. Chinese shipbuilders dominate order books for existing vessel boiler conversions.
- Industrial Machinery:Process heat-to-power conversion for cement, steel, and chemical production. German specialty foundries supply heater-head castings for these applications.
- Heating Systems:Residential and commercial CHP units below 50 kW thermal output. Austrian district heating cooperatives negotiate performance-based contracts for guaranteed heat delivery.
Equipment shipments concentrate in Power Generation; Marine Propulsion is gaining share fastest amid IMO decarbonization deadlines.
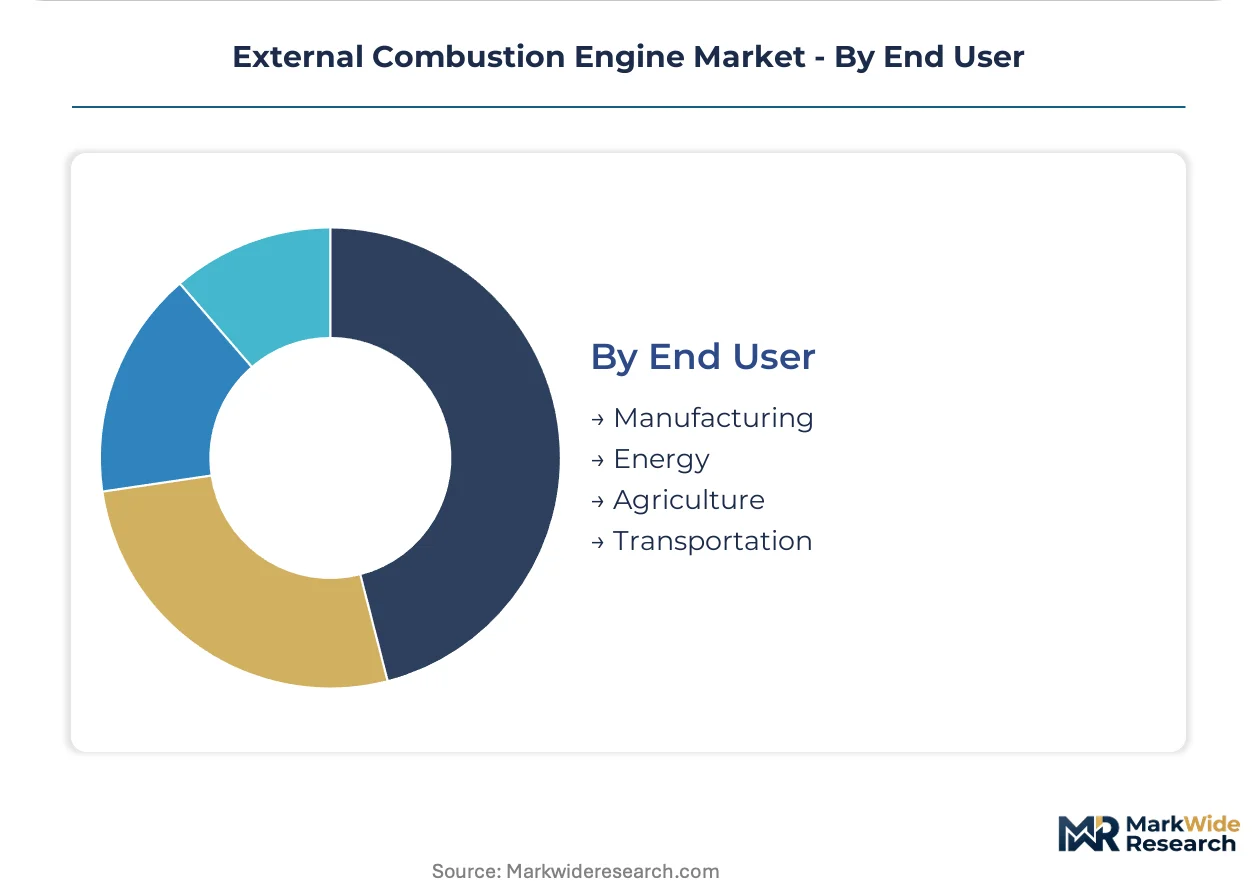
End User:
Supply concentration varies by sector, with energy utilities consolidating procurement and manufacturing fragmenting across specialized vendors.
- Manufacturing:Cement, steel, and chemical producers deploying waste-heat recovery and process steam systems. EPA stationary source standards in US non-attainment zones accelerate external combustion adoption.
- Energy:Utilities and independent power producers seeking baseload renewable capacity. EU F-Gas Regulation phase-down redirects investment toward helium-based Stirling architectures.
- Agriculture:Biomass-fired irrigation pumps and grain drying operations. Indian agricultural cooperatives specify hot air engines for fuel flexibility across crop residue types.
- Transportation:Marine shipping and rail auxiliary power units. Shell and BP field operations specify free-piston Stirling units for unmanned offshore platforms.
Procurement volume concentrates in Energy sector deployments; Agriculture shows the steepest expansion trajectory amid rural electrification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Inflation Reduction Act tax credits and EU Green Deal funding zones concentrate external combustion investment in Germany, China, and the United States. Municipal utilities and industrial operators leverage these incentive structures to retrofit aging thermal infrastructure and expand decentralized energy networks.
Germany
Danish district heating cooperatives source biomass-fired CHP units from German foundries to satisfy national carbon-neutrality mandates. The EU F-Gas Regulation phase-down redirects capital toward helium-recovery infrastructure and sealed-system Stirling architectures. Specialty casting houses in North Rhine-Westphalia supply heater-head components for Stirling engine OEMs facing eighteen-month procurement timelines.
China
Chinese shipbuilders dominate order books for marine propulsion retrofits where existing boiler infrastructure constrains technology migration. The country's dual carbon goals accelerate waste-heat recovery deployments in steel and cement production. Yangtze River Delta industrial clusters integrate organic Rankine cycle variants to capture 150°C to 400°C process exhaust streams.
United States
EPA stationary source emissions limits under the Clean Air Act favor external combustion configurations in non-attainment zones across the Ohio River Valley. Cement producers convert existing boiler infrastructure to biomass cofiring with external combustion topping cycles. West Texas and North Dakota oilfield operators deploy 5-50 kW Stirling units running on associated gas flares for unmanned well pad electrification.
Sweden
Municipal utilities integrate biomass district heating CHP units to satisfy national building stock decarbonization mandates. The EU Green Deal funding mechanisms support retrofit programs across Stockholm and Malmö metropolitan areas. Industrial clusters in Scania prioritize Stirling engine architectures compatible with solar thermal and biomass heat sources.
Japan
METI efficiency mandates drive steel mills to deploy waste-heat recovery systems converting process thermal energy into exportable electricity. Japanese specialty foundries concentrate alloy supply for high-temperature heater-head manufacturing. Kansai region industrial operators specify free-piston Stirling units for continuous-duty applications requiring biennial maintenance intervals.
External Combustion Engine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with utility-scale procurement favoring integrated OEMs while distributed energy favors modular specialists. The vendor base organizes around three strategic archetypes: diversified energy conglomerates with in-house casting capabilities, pure-play Stirling engine designers, and industrial diversification entrants from adjacent power markets. Competitive moves concentrate on backward integration into nickel superalloy supply chains and geographic expansion into IRA-credit-eligible US project development.
Among US-based specialists, Qnergy Inc. and Sunpower Inc. occupy positions within the modular distributed generation tier. Siemens Energy anchors the integrated OEM archetype through captive supply chain control over advanced material casting. These three exemplify the divergence between precision free-piston architectures optimized for remote maintenance intervals and diversified energy platforms capable of utility-scale project execution.
| Leading Market Players |
|---|
| Qnergy Inc. |
| Siemens Energy |
| FlexEnergy Inc. |
| Aisin Corporation |
| Genoastirling AB |
| Stirling Thermal Motors Inc. |
| Sunpower Inc. |
| Deere & Company |
| Microgen Engine Corporation |
| Others |
Supply & Pricing Matrix
London Metal Exchange nickel contract volatility cascades through Stirling engine heater-head manufacturing, compressing margins for OEMs locked into fixed-price utility contracts while forcing spot-market buyers toward premium tiering for supply security.
Pricing Analysis
Lead-time-driven pricing premiums dominate procurement negotiations, with eighteen-month heater-head casting queues commanding standard-tier rates while spot inventory availability triggers economy-tier discounts for flexible buyers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14001-certified German foundry output from secondary Asian sources and uncertified spot market metal. Price differentiation hinges on nickel superalloy grade certification and bundled aftermarket service agreements. Pricing pressure stems from alloy cost pass-through limitations in fixed-price district heating contracts. Municipal utilities in Denmark exhibit highest price sensitivity due to budget-constrained retrofit programs; oilfield operators in West Texas show lowest sensitivity given diesel displacement economics.
Supply Chain Analysis
Single-source vulnerability sits with German investment casting houses in North Rhine-Westphalia, where specialty foundries concentrate heater-head production for global Stirling engine OEMs. Geographic supply concentration centers on Germany, Japan, and China for nickel superalloy feedstock and precision casting capacity. Raw material dependencies draw from Inconel 718, Haynes 230, and high-purity helium recovery infrastructure. Supply chain risk manifests as tariff exposure on Japanese alloy shipments under evolving carbon border adjustment mechanisms. Distribution runs through direct OEM-procurement frameworks for utility-scale projects and specialized industrial distributors for remote oilfield deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The external combustion engine sector is navigating a technology-transition phase as free-piston Stirling architectures displace legacy crankcase-driven systems in continuous-duty applications.
For Market Incumbents: To counter precision-casting supply bottlenecks, Siemens Energy and Qnergy should deepen backward integration into nickel superalloy heater-head production through captive German foundry acquisitions or joint ventures. Certification investment in ISO 9001/14001 audit pre-qualification represents a critical lever for preserving utility procurement framework access amid eighteen-month European notified body queues. For New Entrants and Emerging Players: The price-point gap between premium German-cast Stirling systems and economy-tier hot air engines creates entry space for modular 5-50 kW designs targeting West Texas and North Dakota oilfield electrification. Remote well pad power offers the most penetrable application segment given diesel resupply cost economics. A go-to-market angle anchored to performance-based heat-output contracts—retaining equipment ownership while selling guaranteed energy delivery—sidesteps municipal capital budget constraints. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Stirling engine specialists with established helium-sealing expertise in US and Japanese supply chains. Long-term viability across a 5-10 year window rests on F-Gas Regulation compliance and thermal storage hybridization capability. The signal to watch is EU carbon border adjustment mechanism implementation timing, which will reprice Asian alloy inputs and reshape competitive cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Superalloy Casting | Captive heater-head production insulates Siemens Energy from German foundry queue delays and LME price volatility. |
| Helium Recovery Infrastructure Deployment | Sealed-system Stirling architectures compliant with EU F-Gas Regulation phase-down secure utility procurement eligibility. |
| Thermal Storage Hybridization Partnership | Molten salt integration enables 8-12 hour dispatchable renewable backup for Hawaiian islanded microgrids. |
| Remote Oilfield Electrification Platform | 5-50 kW modular units running on associated gas flares displace $8-per-liter diesel resupply for Shell and BP operations. |
| Performance-Based Heat Contracting | OEM-retained ownership models shift capital burden from Austrian municipal balance sheets to equipment financiers. |
Research Methodology
Independent corroboration across primary interviews with Stirling engine OEM procurement directors, utility planning officers at Swedish municipal utilities, German specialty foundry operations managers, and EPA stationary source compliance officers underwrites the qualitative findings. Secondary validation draws from EIA power generation data, EU ETS carbon price registries, FERC interconnection queue filings, and LME nickel contract archives. Bottom-up unit deployment estimates triangulate against top-down addressable market sizing across biomass CHP, waste-heat recovery, and marine propulsion retrofit segments.
Comparable-period anchoring to historical installation data from Danish district heating cooperatives and Japanese steel mill efficiency programs informs the projection horizon analytical framework. Segmentation dimensions modeled include thermal cycle design, integration depth, fuel-handling capability, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating alloy price pass-through coefficients and IRA credit absorption rates. Industry-specific forecast inputs center on EU F-Gas Regulation phase-down schedules and EPA non-attainment zone expansion boundaries.
Inputs from primary fieldwork and disclosed regulatory filings were available through the study window; gaps in real-time foundry capacity utilization data introduce uncertainty bands around heater-head supply constraints. Forecasts reflect documented assumptions regarding carbon border adjustment implementation timing and helium spot market liquidity. Specific risk factors that could revise projections include nickel superalloy export restriction escalations and accelerated EPA residual risk review timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Saudi Arabia Automotive Lubricants Market
Automotive Parts
Germany Automotive Hydraulic Actuators Market
Automotive Parts
Wheel Arch Liner Market
Automotive Parts
Automotive Brake Caliper Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Japan Commercial Vehicles Lubricants Market
Automotive Parts
South Africa Automotive Lubricants Market
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Thermal Systems Market
Automotive Parts
Auto Parts Manufacturing Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Diesel Common Rail Injection System Market
Automotive Parts
South Africa Passenger Vehicles Lubricants Market
Automotive Parts
Qatar Commercial Vehicles Lubricants Market
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Parking Heater Market