
 Global Electric Vehicles Market | 2026-2036
Global Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Vehicles Market Analysis
Direct-to-consumer digital sales channels is reshaping how electric vehicles reach buyers, bypassing traditional dealer networks in multiple continents. Tesla leverages its owned retail and service infrastructure to control pricing and customer experience across key metros. BYD anchors its dominance through integrated battery-cell-to-vehicle manufacturing at massive scale. Rivian competes in the commercial fleet segment with purpose-built electric vans and trucks for last-mile logistics operators.
Electric vehicles are road-certified automobiles propelled by one or more electric motors drawing energy from rechargeable battery packs, with lithium-ion cells currently delivering energy densities of 250-300 Wh/kg at pack level. Their primary commercial purpose is to displace internal combustion engines in passenger and freight transport through zero tailpipe emission operation. Battery Electric Vehicles capture the dominant margin pool as cell costs decline and range anxiety diminishes among private consumers. Solid State technology represents the fastest-advancing frontier, promising higher energy density and improved thermal stability over incumbent lithium-ion chemistries. Commercial Fleets constitute the most rapidly expanding end-user category as logistics operators amortize higher upfront costs through intensive utilization schedules.
The EPA tailpipe standards in the United States, the EU Green Deal's 2035 combustion sales ban, and China's MIIT dual-credit system collectively mandate electrification timelines that manufacturers cannot defer. These frameworks shape product portfolios by penalizing carbon-intensive fleets while subsidizing zero-emission vehicle production and purchase decisions. Stakeholders must monitor regulatory divergence between jurisdictions that reward early compliance and those that impose accelerating penalties for non-conformance.
Market Dynamics
Cell chemistry standardization around lithium iron phosphate and high-nickel ternary formats is compressing cost curves faster than manufacturing scale alone, forcing incumbent automakers to rewrite procurement strategies and platform architectures.
Growth Catalysts
- EU CO2 Fleet Standards:The 2035 combustion sales ban creates binding compliance obligations that manufacturers cannot defer through credit purchases, accelerating dedicated EV platform investments across German, French, and Italian production networks.
- Logistics Electrification:Last-mile delivery operators in urban corridors are amortizing battery premiums through 24-hour utilization schedules, with depot charging infrastructure now standard in Amazon, DHL, and regional courier specifications.
- Lithium Hydroxide Processing:Conversion capacity expansion in Australia's spodumene belt and Chile's Atacama salares is securing cathode-grade material streams for NCM811 and NCM9½½ chemistries.
Market Restraints
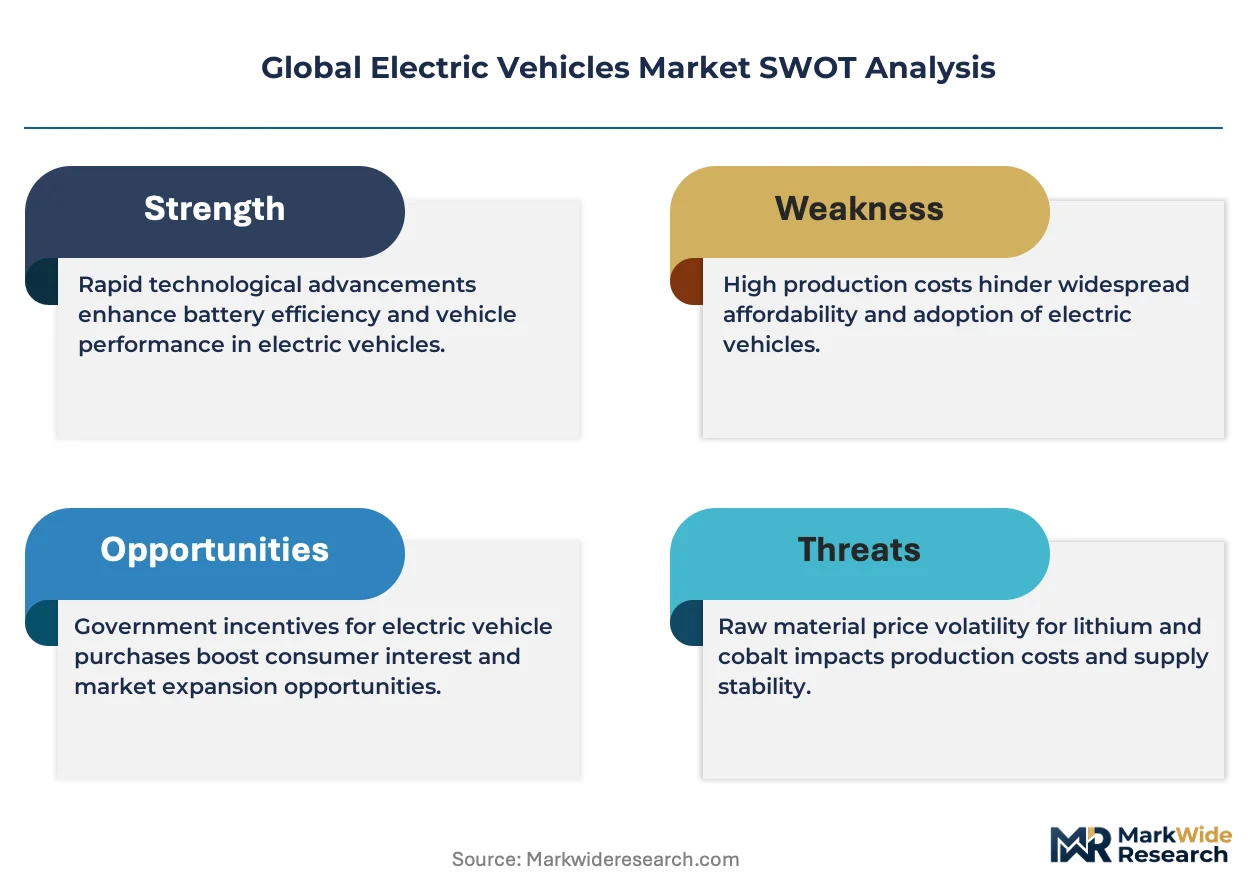
- Cobalt Supply Concentration:The Democratic Republic of Congo's dominance of mined cobalt creates ESG-linked procurement constraints and price volatility that cathode manufacturers cannot fully hedge through recycling streams.
- Fast-Charging Infrastructure Gaps:Highway corridor coverage remains uneven across rural India, Southeast Asian archipelagos, and Central Asian transit routes, limiting intercity commercial adoption.
- Grid Integration Limits:Distribution network capacity constraints in suburban UK, German industrial zones, and Japanese prefectures delay fleet depot electrification regardless of vehicle availability.
Strategic Opportunities
- Brazil Biofuel-EV Hybrid Policy:ANVISA and national energy regulator frameworks are opening flex-fuel PHEV pathways that blend sugarcane ethanol with electric range, creating distinct regulatory space from pure battery mandates.
- Vehicle-to-Grid Aggregation:Bidirectional charging protocols are enabling fleet operators to monetize parked capacity through frequency regulation contracts with ERCOT, National Grid, and Tokyo Electric.
- Solid-State Pilot Production:Toyota, Samsung SDI, and QuantumScape are scaling sulfide and oxide electrolyte lines for 2027-2028 commercialization, promising 400+ Wh/kg density without thermal runaway risk.
Industry Challenges
- Battery Systems Engineering Talent:Shortages in electrochemical modeling, thermal management design, and BMS firmware development are inflating compensation premiums across Detroit, Stuttgart, and Shenzhen hiring markets.
- Homologation Timeline Compression:UN ECE R100, R10, and emerging cybersecurity regulations require 18-24 month certification cycles that conflict with 12-month platform refresh targets.
- Legacy Supplier Transition Friction:Powertrain component specialists with ICE-dependent revenue streams face insolvency risk before EV contract volumes materialize, disrupting established tier-2 supply relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Vehicles Market |
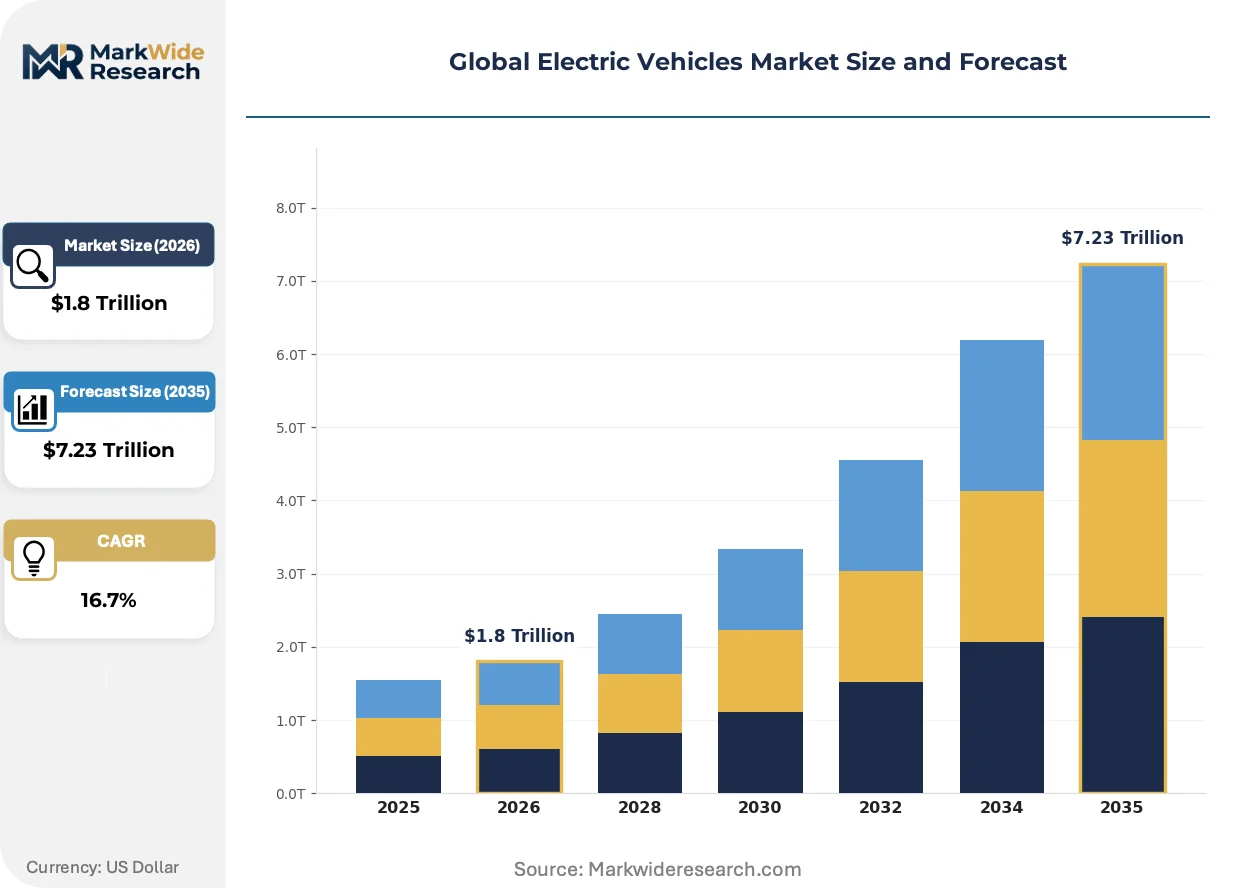
| Market Size in 2026 | $1.8 Trillion |
| Market Size in 2035 | $7.23 Trillion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric Vehicles, Plug-in Hybrid Electric Vehicles, Fuel Cell Electric Vehicles, Extended Range Electric Vehicles Technology: Lithium-ion, Solid State, Lead Acid, Nickel-Metal Hydride Charging Infrastructure: Home Charging, Public Charging, Fast Charging, Wireless Charging End User: Private Consumers, Commercial Fleets, Government Agencies, Ride-Sharing Services |
| Companies Covered | Volkswagen Group, Rivian, BYD, Volvo, XPeng, Tesla, Li Auto, NIO, Xiaomi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Vehicles Market Emerging Trajectories
Platform consolidation around dedicated skateboard architectures is eliminating the engineering compromises of converted ICE vehicles, while software-defined functionality is decoupling hardware lifecycles from feature refresh rates.
Solid-state electrolyte technology is collapsing the energy density gap between passenger range requirements and commercial payload constraints. Sulfide-based cells from Toyota's pilot lines and oxide formulations from Samsung SDI are achieving 400 Wh/kg at cell level. Long-haul trucking operators and premium SUV segments are absorbing first-production premiums to access 600-mile range without pack weight penalties.
China's MIIT dual-credit system is tightening NEV production quotas faster than domestic absorption rates, forcing joint-venture partners to export surplus compliance vehicles into Southeast Asian and Middle Eastern markets. The credit deficit penalty structure now exceeds the marginal cost of battery production, eliminating the economics of ICE-only portfolios. European luxury manufacturers with Chinese joint ventures are restructuring capacity allocation to avoid credit purchase obligations.
Fleet procurement departments are consolidating vehicle sourcing through direct OEM relationships, bypassing dealer networks that cannot price battery-electric units competitively against manufacturer fleet programs. Large logistics operators in California, the Netherlands, and South Korea are negotiating multi-year service bundles that wrap charging infrastructure, maintenance, and residual value guarantees into per-mile contracts. This disintermediation is compressing regional dealer margins while accelerating order-to-delivery timelines for standardized van and truck configurations.
Global Electric Vehicles Market Segmentation
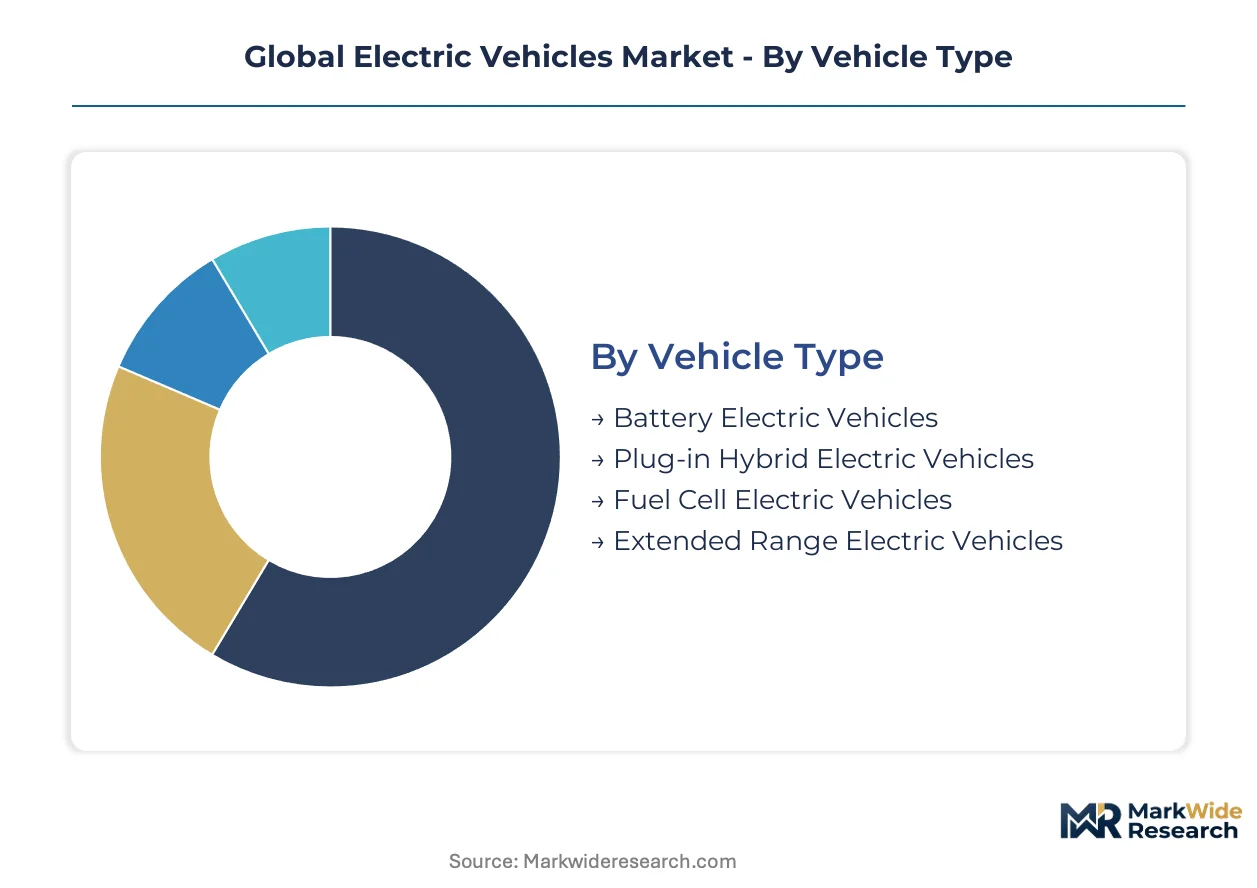
Segmentation in electric vehicles reveals how powertrain architectures, energy storage chemistries, and charging modalities align with distinct operational requirements across passenger and commercial applications. Understanding these divisions exposes where capital is concentrating and which technology combinations command sustainable margin structures.
Vehicle Type:
Powertrain configurations span from pure-electric architectures to range-extended hybrids, each matching specific duty cycles and infrastructure access profiles.
- Battery Electric Vehicles:Zero-emission platforms utilizing lithium-ion or solid-state packs with 250-400 mile range capability. Fleet operators in California and the Netherlands amortize upfront premiums through intensive depot-charging schedules and frequency regulation revenue streams.
- Plug-in Hybrid Electric Vehicles:Dual-powertrain systems combining 30-60 mile electric range with combustion backup for intercity transit. German luxury manufacturers and Chinese joint-venture partners deploy PHEVs as compliance bridges under EU CO2 fleet standards and China's MIIT dual-credit system.
- Fuel Cell Electric Vehicles:Hydrogen-fed proton exchange membrane systems targeting heavy-duty freight corridors with sub-15-minute refueling. South Korean logistics operators and Japanese commercial fleets pilot fuel-cell trucks along dedicated hydrogen highway networks.
- Extended Range Electric Vehicles:Series-hybrid architectures where a small combustion generator sustains battery charge during sustained highway operation. Range anxiety mitigation drives residual demand in rural US markets and Australian interstate corridors with sparse fast-charging coverage.
Established volume favors Battery Electric Vehicles; emerging adoption favors Plug-in Hybrid Electric Vehicles as transitional compliance solutions.
Technology:
Cell chemistry selection determines energy density, thermal stability, and cost trajectories across passenger and commercial vehicle programs.
- Lithium-ion:Dominant chemistry spanning LFP and NCM variants with 250-300 Wh/kg pack-level density. CATL and BYD scale LFP production for cost-sensitive mass-market segments while LG Energy Solution and SK On supply high-nickel ternary cells to premium European OEMs.
- Solid State:Sulfide and oxide electrolyte formulations achieving 400+ Wh/kg without thermal runaway risk. Toyota's pilot production lines and Samsung SDI's oxide developments target 2027-2028 commercialization for long-haul trucking and luxury SUV applications.
- Lead Acid:Mature chemistry retained for auxiliary power and low-speed urban mobility in price-sensitive Indian and Southeast Asian markets.
- Nickel-Metal Hydride:Legacy hybrid applications in Toyota's established parallel-hybrid platforms where proven cycle life outweighs energy density requirements.
Cost compression favors Lithium-ion; performance breakthroughs favor Solid State as the steepest expansion trajectory in premium segments.
Charging Infrastructure:
Refueling modality selection shapes vehicle utilization economics and infrastructure capital deployment across residential, commercial, and public asset classes.
- Home Charging:Level 1 and Level 2 residential installations delivering 3-11 kW overnight replenishment. Suburban US households and German single-family dwellings dominate installation volumes where garage access and distribution capacity permit.
- Public Charging:Destination and curbside Level 2 networks serving urban dwellers without dedicated parking. Municipal procurement in Paris, Amsterdam, and Seoul expands street-side coverage through utility-led concession models.
- Fast Charging:DC rapid systems delivering 150-350 kW for 10-80% replenishment in 20-40 minutes. Highway corridor operators Electrify America and IONITY deploy liquid-cooled cables across German autobahn and US interstate networks.
- Wireless Charging:Inductive pad systems enabling automated fleet depot and dynamic roadway charging. Commercial trials in Gothenburg and Detroit validate taxi and shuttle applications with stationary 11-300 kW transfer capability.
Residential convenience favors Home Charging; fleet monetization favors Fast Charging for revenue-generating utilization schedules.
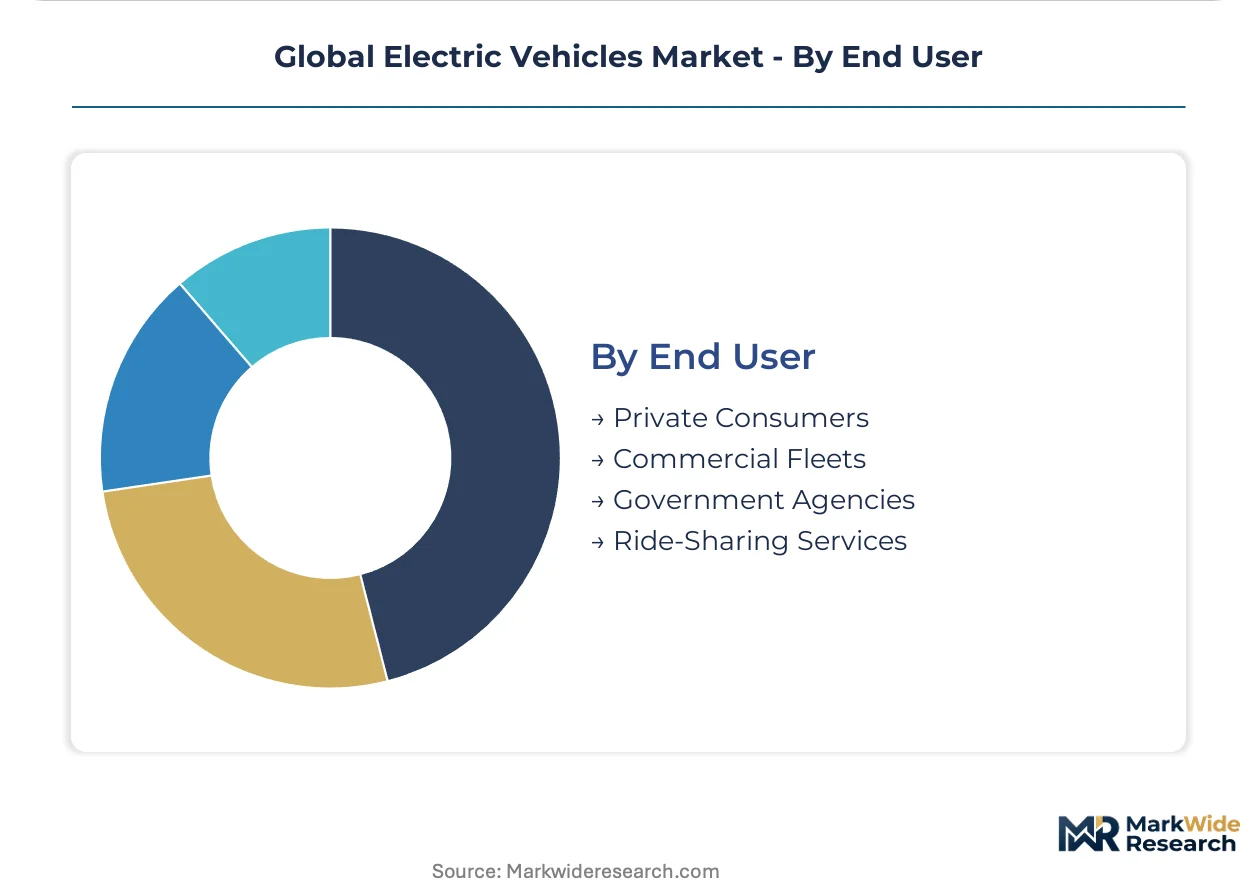
End User:
Customer archetypes exhibit divergent total-cost-of-ownership calculations, procurement timelines, and residual risk tolerances.
- Private Consumers:Individual purchasers evaluating range, brand, and total cost against ICE alternatives. China's Yangtze River Delta manufacturing cluster and Germany's Baden-Württemberg supplier corridor concentrate production for this price-sensitive segment.
- Commercial Fleets:Logistics operators amortizing battery premiums through 24-hour utilization and depot charging infrastructure. Amazon, DHL, and regional courier specifications now standardize battery-electric vans for last-mile urban delivery.
- Government Agencies:Municipal and national procurement programs mandating zero-emission vehicle shares under public fleet decarbonization targets. EPA tailpipe standards and EU Green Deal compliance obligations accelerate dedicated EV platform investments.
- Ride-Sharing Services:Mobility platforms optimizing per-mile economics through high-mileage electric deployment. Uber and Lyft driver incentives in California and European capitals concentrate demand in urban corridors with established fast-charging coverage.
Volume concentration favors Commercial Fleets; policy acceleration favors Government Agencies as procurement mandates tighten compliance thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing power through integrated battery-to-vehicle manufacturing at massive scale, while German premium manufacturers absorb margin compression from compliance-driven platform investments. This asymmetry reshapes regional competitive positioning across the forecast horizon.
China
NEV mandate compliance and MIIT dual-credit penalties now exceed marginal battery production costs, eliminating ICE-only portfolio economics. The Yangtze River Delta manufacturing cluster concentrates cathode-grade lithium hydroxide processing and cell-to-pack integration. BYD and CATL anchor captive supply chains that compress procurement costs below reachable levels for foreign joint-venture partners.
Germany
EU CO2 fleet standards and the 2035 combustion sales ban bind compliance obligations that manufacturers cannot defer through credit purchases. Baden-Württemberg's supplier corridor hosts dedicated EV platform engineering and solid-state pilot production lines. Stuttgart and Munich-based OEMs restructure capacity allocation to avoid credit purchase obligations in Chinese joint ventures.
United States
EPA tailpipe standards and California Air Resources Board mandates accelerate dedicated EV platform investments across Detroit production networks. Fleet operators in California negotiate multi-year service bundles wrapping charging infrastructure and residual value guarantees. The Midwest battery belt—spanning Michigan, Ohio, and Kentucky—attracts cathode active material plants to supply regional cell factories.
South Korea
Logistics operators along the Seoul-Busan highway corridor pilot fuel-cell truck deployment under METI-aligned hydrogen infrastructure programs. Samsung SDI and SK On scale high-nickel ternary cell production for premium European OEM supply contracts. The Busan-Ulsan industrial complex concentrates electrolyte formulation and oxide solid-state development for 2027-2028 commercialization targets.
Japan
Toyota's sulfide-based solid-state pilot production targets 400+ Wh/kg density for long-haul trucking applications without thermal runaway risk. METI funding supports hydrogen highway networks connecting Tokyo, Nagoya, and Osaka for commercial fuel-cell deployment. The Aichi prefecture manufacturing base integrates battery systems engineering talent pools with legacy powertrain supplier transition programs.
Global Electric Vehicles Market Vendor Landscape
Vertically integrated battery specialists and software-defined vehicle platforms split the market between cost-compressed mass-market dominance and premium experience control. The structure concentrates around three strategic archetypes: integrated cell-to-vehicle manufacturers controlling upstream material streams, dedicated EV platform operators disintermediating dealer networks, and legacy OEMs retrofitting compliance-driven electrification onto existing production footprints. Competitive moves center on cathode active material backward integration and direct fleet procurement relationship consolidation.
Within the integrated manufacturing tier, BYD exemplifies cost-structure control through captive lithium iron phosphate cell production, while Tesla anchors direct-to-consumer channel dominance with owned retail infrastructure. Among legacy transformation players, Volkswagen Group occupies a position bridging compliance-scale electrification with existing supplier relationship leverage. These archetypes represent divergent responses to identical regulatory pressure—MIIT dual-credit penalties in China and EU CO2 fleet standards—producing asymmetric margin outcomes across geographies.
| Leading Market Players |
|---|
| Volkswagen Group |
| Rivian |
| BYD |
| Volvo |
| XPeng |
| Tesla |
| Li Auto |
| NIO |
| Xiaomi |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Yangtze River Delta cell manufacturing corridor is compressing cathode active material pricing while forcing European and North American buyers to absorb logistics premiums for secure supply. This utilization imbalance drives divergent supplier behavior: Chinese producers prioritize volume throughput over margin retention, while Western battery belt investments seek tariff-advantaged localization.
Pricing Analysis
The customization-premium spread between configured-to-order fleet contracts and standard retail transactions is widening as commercial buyers negotiate multi-year service bundles. Pricing stratifies across premium, standard, and economy tiers based on battery chemistry grade and charging speed certification. Cost compression in lithium iron phosphate cells is intensifying because CATL and BYD scale captive production. Commercial fleet procurement departments exhibit the highest price sensitivity, while luxury SUV segments absorb solid-state cell premiums for range performance.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for cathode active material procurement. Manufacturing concentrates in China, South Korea, and Japan for cell production, with Australia's spodumene belt and Chile's Atacama salares feeding upstream lithium streams. The network draws from cobalt concentrate originating in the Democratic Republic of Congo, creating single-source vulnerability for high-nickel ternary chemistries. Distribution runs through direct OEM-fleet relationships that bypass traditional dealer networks for standardized van configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from charging infrastructure maintenance and battery health monitoring is expanding faster than vehicle hardware sales, creating recurring-revenue economics that reshape capital allocation priorities across the value chain.
For Market Incumbents: Entrench platform standardization advantages by locking fleet operators into multi-year service bundles that wrap charging infrastructure, predictive maintenance, and residual value guarantees. Threats from solid-state entrants with superior energy density demand accelerated R&D commitments to sulfide electrolyte commercialization. Backward integration into cathode active material production in the US Midwest battery belt secures tariff-advantaged supply. For New Entrants and Emerging Players: Mid-market commercial van operators in Southeast Asian urban corridors represent the most penetrable entry point, with depot charging infrastructure gaps creating white-space for integrated vehicle-charging service offerings. Brazilian flex-fuel PHEV pathways under ANVISA frameworks offer regulatory differentiation from pure battery mandates. A direct fleet procurement model bypassing dealer networks accelerates order-to-delivery timelines for standardized configurations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state pilot production lines as Toyota, Samsung SDI, and QuantumScape scale sulfide and oxide electrolyte capacity. Long-term viability over the next decade hinges on securing offtake agreements with OEMs targeting long-haul trucking applications. Acquisition targets should display captive cathode material processing or proprietary thermal management IP. The signal to watch is frequency regulation contract pricing in ERCOT and National Grid markets as vehicle-to-grid aggregation monetization validates.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL and LG Energy Solution contracts with Detroit OEMs secure cathode-grade lithium hydroxide streams for NCM811 chemistries. |
| Software-Defined Vehicle Investment | Over-the-air functionality updates decouple hardware refresh cycles from feature monetization across Tesla and BYD platforms. |
| Charging Infrastructure Partnership | Electrify America and IONITY highway corridor deployments address fast-coverage gaps across German autobahn and US interstate networks. |
| Platform Standardization | Skateboard architectures eliminate engineering compromises of converted ICE vehicles, reducing per-unit engineering costs for dedicated EV programs. |
| Geographic Manufacturing Footprint | Midwest battery belt investments in Michigan, Ohio, and Kentucky localize cathode active material production for regional cell factories. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, customs and trade records, and OEM SEC filings. Interviews with Tier 1 supplier procurement leads, OEM platform engineers, fleet operations directors, and aftermarket service heads inform demand-side validation. Top-down market sizing triangulates against bottom-up segment builds across vehicle type, technology, charging infrastructure, and end-user categories.
Forecast inputs span propulsion architecture adoption curves, cell chemistry cost trajectories, and regulatory compliance timeline enforcement across the projection horizon. Segmentation dimensions include vehicle class, battery chemistry tier, charging modality, and regional production cluster. CAGRs derive from installed base turnover modeling and replacement demand elasticity. Specific inputs incorporate MIIT dual-credit penalty structures, EU CO2 fleet standard phase-in schedules, and EPA tailpipe standard stringency assumptions.
Practitioners should monitor cobalt price volatility, solid-state pilot production yield rates, and grid integration capacity constraints for early signals of forecast revision. Assumptions reflect current regulatory enforcement postures and technology cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Europe Electric Light Commercial Vehicles Market
Electric Vehicles
48V Mild Hybrid Battery Pack Systems Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
Hoverboard Scooter Market
Electric Vehicles
Luxembourg E-Bike Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Electric Three Wheeler Market
Electric Vehicles
Hybrid EV Conversion Kit Market
Electric Vehicles
Germany Solar E-Bike Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
UK Electric Vehicle Market
Electric Vehicles
Premium Electric Motorcycle Market
Electric Vehicles
Electric Vehicle Power Control Unit Market
Electric Vehicles
Electric Loader Rickshaw Market