
 Automotive Fastener Market | 2026-2036
Automotive Fastener Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fastener Market Analysis
Platform electrification is fragmenting legacy fastener portfolios as battery electric architectures demand lighter, corrosion-resistant joining solutions. Illinois Tool Works leverages its polymer and metal fastening expertise to anchor North American OEM supply relationships. Stanley Black & Decker sustains broad distribution scale across aftermarket channels. LISI Group specializes in high-tensile aerospace-grade solutions that extend into premium automotive applications.
Automotive fasteners are mechanical joining devices—typically threaded bolts, nuts, screws, or rivets manufactured from steel, aluminum, or engineered polymers—that secure components against vibration, thermal cycling, and structural load in vehicle assemblies. Steel bolts remain the volume backbone for chassis and powertrain applications, while aluminum fasteners gain share in body-in-white structures where OEMs pursue mass reduction targets. The OEM end-user segment dominates value capture through long-term platform contracts, whereas aftermarket providers compete on SKU breadth and inventory velocity for collision repair and maintenance demand.
The US EPA and NHTSA jointly enforce fuel economy standards that indirectly mandate lightweight fastener substitution in vehicle assemblies. Europe's REACH regulation and the EU Green Deal framework restrict hexavalent chromium coatings, forcing suppliers to qualify trivalent alternatives or zinc-nickel plating systems. Stakeholders must monitor evolving battery enclosure sealing standards and determine whether to invest in automated robotic installation systems or preserve manual assembly flexibility for mixed-model production lines.
Market Dynamics
Platform electrification is fragmenting legacy fastener portfolios as battery electric architectures demand lighter, corrosion-resistant joining solutions. The transition from internal combustion to electric powertrains is forcing OEMs to requalify entire fastener specifications for thermal management systems and battery enclosures.
Growth Catalysts
- REACH chemical compliance:Europe's tightening restrictions on hexavalent chromium coatings are accelerating qualification of trivalent alternatives and zinc-nickel plating systems among tier suppliers.
- Yangtze River Delta manufacturing cluster:China's concentrated automotive production base generates sustained procurement volume for high-tensile chassis fasteners and body-in-white joining solutions.
- Aluminum fastener adoption:Mass reduction targets in vehicle assemblies are pulling aluminum threaded fasteners into body structures previously dominated by steel grades.
Market Restraints
- Steel alloy price volatility:Input cost swings for high-grade alloy steels compress margin buffers for mid-volume fastener manufacturers serving chassis applications.
- Coating qualification timelines:Extended validation cycles for corrosion-resistant surface treatments under OEM specification protocols delay new product revenue recognition.
- Polymer fastener performance ceiling:Load-bearing limitations of engineered thermoplastics restrict substitution potential in powertrain and suspension assemblies.
Strategic Opportunities
- Battery enclosure sealing standards:Emerging IP67 and IP69K ingress protection requirements for electric vehicle battery packs create specification windows for specialized sealing fasteners.
- Automated robotic installation:OEM investment in mixed-model production lines favors suppliers capable of integrating vision-guided torque systems with programmable feed mechanisms.
- EU Green Deal material sourcing:Circular economy mandates for recycled content in automotive components open qualification pathways for closed-loop steel fastener production.
Industry Challenges
- Surface engineering talent scarcity:Shortages of corrosion chemists and PVD coating specialists constrain R&D throughput for next-generation plating systems.
- Legacy platform coexistence:Simultaneous service of internal combustion and electric architectures fragments production runs and complicates inventory positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fastener Market |
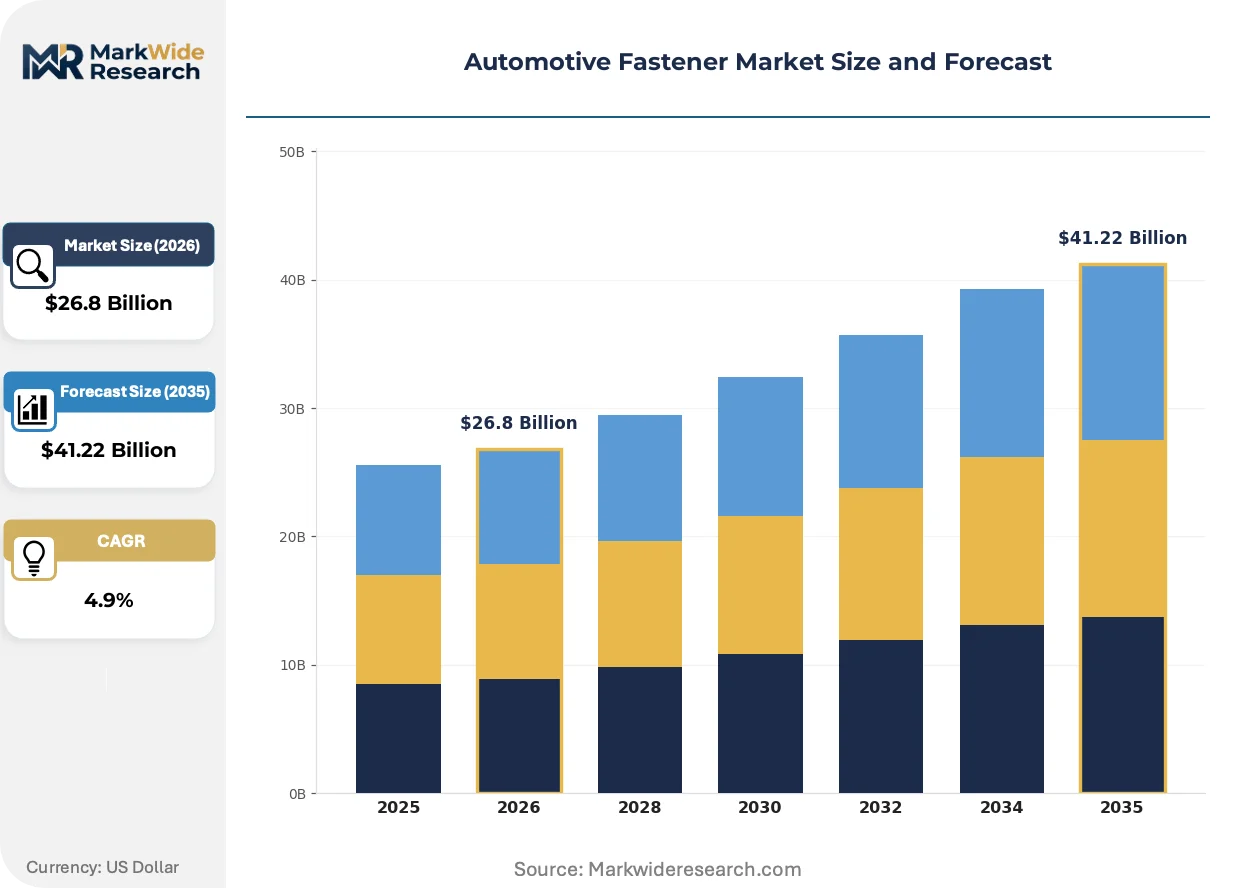
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $41.22 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolts, Nuts, Screws, Rivets Material: Steel, Aluminum, Plastic, Stainless Steel End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Installation Type: Manual, Automated, Semi-Automated, Robotic |
| Companies Covered | Illinois Tool Works Inc., Stanley Black & Decker, Inc., LISI Group, SFS Group AG, Nifco Inc., Bulten AB, Kamax Group, Shanghai Prime Machinery Company Limited, Würth Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fastener Market Emerging Trajectories
Fastener technology is converging with electrification requirements and automated assembly systems. Material science advances and regulatory pressure on surface treatments are reshaping supplier qualification pathways across OEM supply chains.
Multi-material fastening systems are migrating from conventional steel-dominated designs toward hybrid metal-polymer configurations that isolate galvanic corrosion in aluminum-intensive vehicle structures. European and North American OEMs are accelerating adoption of these solutions for battery tray and motor housing assemblies. The shift is compressing demand for single-material high-tensile bolts in non-structural applications.
ECHA's REACH enforcement is tightening permissible thresholds for hexavalent chromium in corrosion-resistant coatings across European automotive supply chains. Tier suppliers are qualifying trivalent chrome and zinc-flake alternatives under accelerated OEM approval timelines. Fastener manufacturers serving German and French vehicle production face the most compressed transition windows.
Consolidated procurement contracts are displacing fragmented multi-source purchasing as OEMs reduce supplier complexity for platform-critical fasteners. Tier-1 integrators are capturing specification authority previously held by smaller specialty distributors. This concentration is most visible in China's Yangtze River Delta, where volume buyers are consolidating fastener supply into single-source framework agreements.
Automotive Fastener Market Segmentation
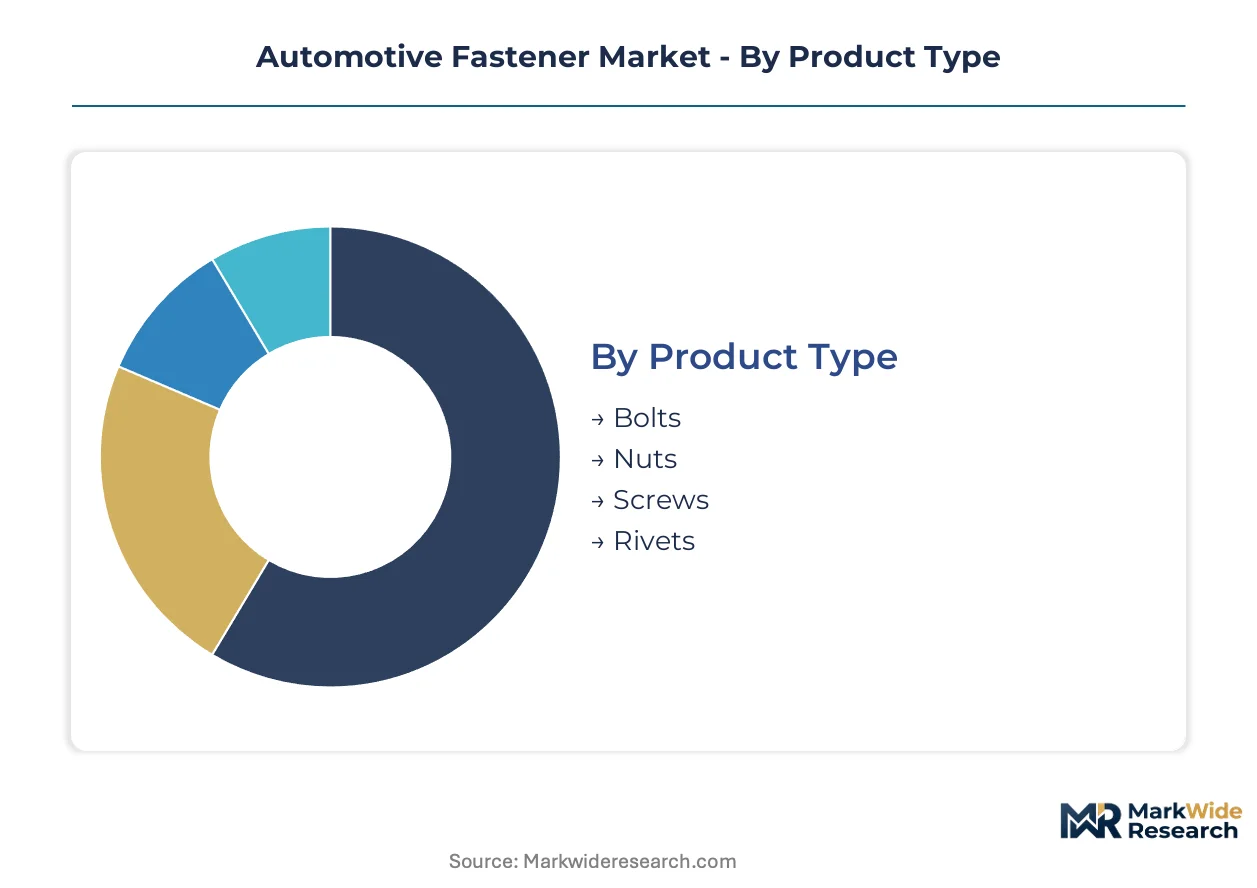
Automotive fastener procurement patterns diverge sharply between platform-contract OEM volumes and fragmented aftermarket replenishment cycles. Segment boundaries are blurring as electrification forces material substitutions and installation automation redefines supplier capabilities.
Product Type:
After-sales service intensity varies dramatically across fastener categories, with collision repair networks demanding rapid availability of threaded fasteners versus structural rivets requiring specialized installation equipment.
- Bolts:Threaded steel and alloy fasteners engineered for high-tensile chassis and powertrain assemblies. Demand concentrates in German and Chinese OEM platform contracts where torque specification precision governs supplier qualification.
- Nuts:Paired threaded components ranging from standard hex nuts to prevailing-torque locknuts for vibration resistance. The Yangtze River Delta manufacturing cluster generates sustained procurement volume for high-tensile flange nuts in body-in-white structures.
- Screws:Self-tapping and machine-threaded fasteners for interior trim, electronics, and non-structural assemblies. Interior module suppliers in Michigan and Ontario specify polymer and coated steel screws for dashboard and infotainment mounting.
- Rivets:Permanent mechanical fasteners including blind rivets and solid rivets for aluminum-intensive body structures. Rivet demand accelerates where OEMs pursue mass reduction through aluminum-steel joining without galvanic corrosion.
Bolts hold the largest share; momentum sits with rivets as aluminum body architectures expand.
Material:
Cost tier stratification separates commodity steel grades from premium alloys and engineered polymers, with coating chemistry adding a secondary pricing dimension.
- Steel:Carbon and alloy grades dominate chassis, suspension, and powertrain applications requiring tensile strength above 800 MPa. REACH-compliant zinc-nickel plating systems are displacing hexavalent chromium coatings in European supply chains.
- Aluminum:Lightweight threaded fasteners gaining share in body-in-white and battery enclosure assemblies where OEMs pursue mass reduction targets. Tesla and BMW specify aluminum fasteners for aluminum-intensive vehicle platforms.
- Plastic:Engineered thermoplastics including PEEK and nylon for interior, electrical, and non-structural applications. Load-bearing limitations restrict plastic fastener penetration in powertrain and suspension assemblies.
- Stainless Steel:Corrosion-resistant grades for exhaust systems, battery enclosures, and exterior trim where salt spray resistance exceeds 1000 hours. Premium pricing limits stainless steel to specification-critical applications.
Steel holds the largest share; aluminum is climbing the fastest as electrification accelerates lightweighting requirements.
End User:
Customer type determines contract structure, with OEM platform agreements demanding engineering collaboration versus aftermarket providers competing on inventory velocity.
- OEMs:Original equipment manufacturers specify platform-critical fasteners through multi-year framework agreements with direct engineering oversight. Volkswagen, Toyota, and Stellantis maintain captive fastener engineering teams for powertrain and chassis specifications.
- Tier-1 Suppliers:System integrators including Bosch, Denso, and Magna consolidate fastener procurement for subassemblies delivered to OEM final assembly plants. Tier-1 specification authority is displacing fragmented distributor purchasing in North America and Europe.
- Aftermarket Providers:Independent distributors and jobbers serving collision repair and maintenance demand through broad SKU availability. SKU breadth and same-day fulfillment velocity determine competitive positioning.
- Dealerships:Authorized service channels sourcing genuine OEM fasteners for warranty repair and certified collision work. Dealership procurement remains tethered to OEM captive supply agreements.
OEMs hold the largest share; Tier-1 Suppliers are gaining share fastest as consolidation concentrates specification authority.
Installation Type:
Volume scale separates high-throughput automated assembly lines from flexible manual stations serving mixed-model production.
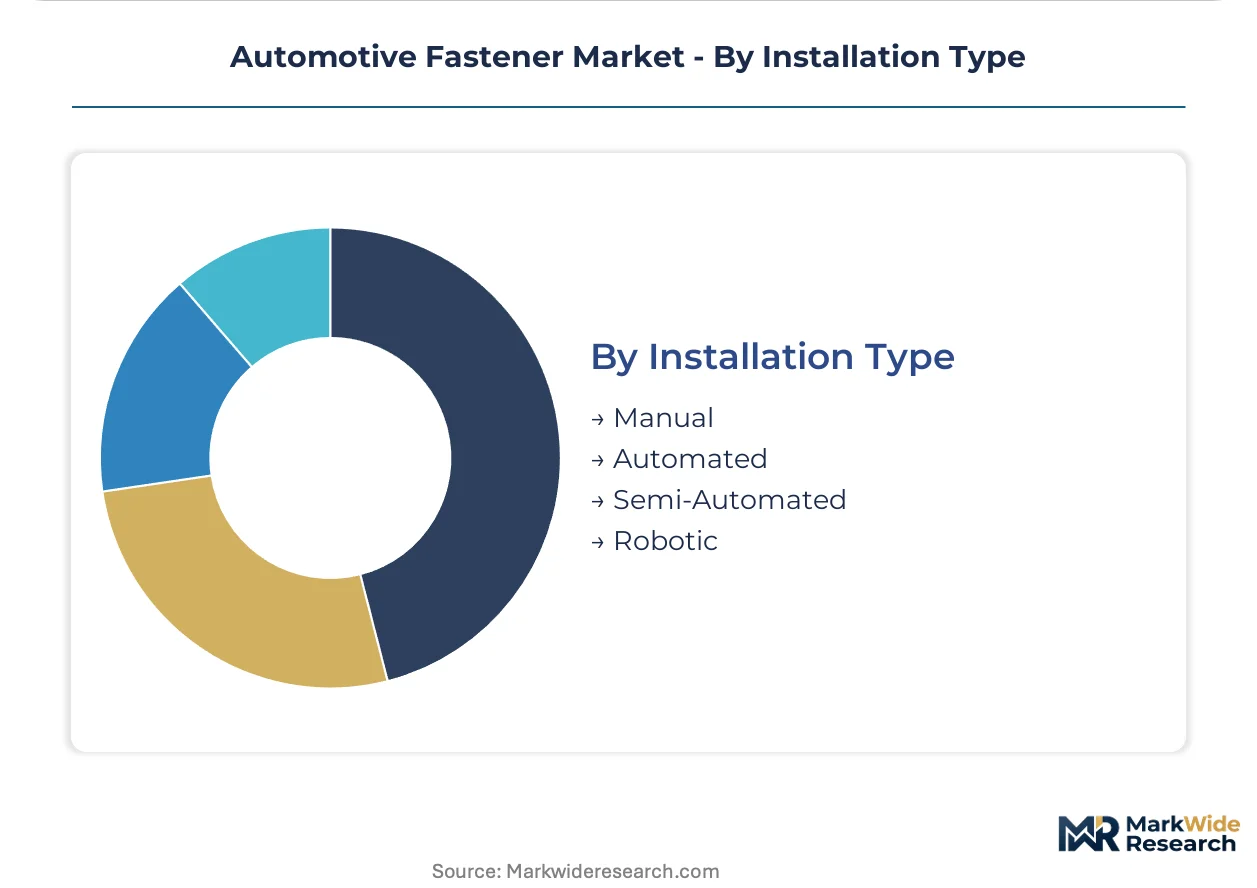
- Manual:Hand-tool installation with torque wrench verification for low-volume specialty vehicles and prototype builds. Manual flexibility preserves supplier optionality for mixed-model lines with frequent changeovers.
- Automated:Fixed-station torque systems with programmable feed mechanisms for high-volume platform production. Hyundai's Alabama and Georgia plants deploy automated fastening cells for SUV and EV assembly.
- Semi-Automated:Operator-assisted power tools with electronic torque logging for quality traceability. Semi-automated systems bridge flexibility and throughput in mid-volume European luxury production.
- Robotic:Vision-guided articulated arms with adaptive torque control for battery enclosure and structural assembly. Robotic installation is expanding most quickly as OEMs qualify mixed-model EV platforms requiring precision sealing.
Automated holds the largest share; robotic is expanding most quickly as battery enclosure sealing standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fastener trade flows tilt toward manufacturing surplus economies, with Germany, China, Japan, and the United States commanding the dominant export positions while import demand concentrates in vehicle assembly hubs lacking upstream metallurgical capacity.
China
Domestic EV production scale and battery enclosure demand pull specialty fastener imports from Germany and Japan while Yangtze River Delta fabricators expand trivalent chrome plating capacity for European OEM qualification. MIIT's dual carbon goals tighten energy intensity standards for steel fastener forges in Jiangsu and Zhejiang provinces. Shanghai Prime Machinery anchors supply relationships with Tesla's Gigafactory Shanghai and BYD's Shenzhen operations.
Germany
High-tensile chassis fastener exports to Chinese and North American OEMs sustain trade surplus despite domestic BEV transition compressing local assembly demand. ECHA's REACH enforcement accelerates hexavalent chromium phase-out across Baden-Württemberg and Bavaria coating facilities. Stuttgart and Munich engineering centers specify zinc-nickel plating systems for Porsche and BMW battery tray architectures.
United States
Detroit Three platform contracts and Tesla's Texas Gigafactory generate procurement volume for threaded steel fasteners while EPA fuel economy standards indirectly mandate aluminum substitution in body structures. NHTSA safety regulations govern torque specification protocols for autonomous vehicle sensor mounting hardware. Southeast manufacturing corridors in Alabama, Georgia, and Tennessee attract automated fastening cell investments from Hyundai and Rivian.
Japan
Precise torque control technology and lean manufacturing discipline sustain premium fastener exports to German and US luxury OEMs despite yen volatility compressing margin structures. METI's green transformation subsidies support hydrogen-ready steel fastener development for next-generation powertrains. Toyota City and Nagoya industrial clusters concentrate cold-forging expertise for hybrid and solid-state battery vehicle programs.
South Korea
Hyundai-Kia's aggressive EV platform rollout and battery joint ventures with LG Energy Solution generate specialized fastener demand for thermal management and enclosure sealing. MFDS chemical safety standards align with REACH-equivalent coating restrictions for European export qualification. Ulsan and Asan production complexes integrate robotic fastening cells for Ioniq and EV6 assembly lines.
Automotive Fastener Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: diversified industrial conglomerates with captive automotive divisions, specialized cold-forging houses with metallurgical expertise, and regional distributors with aftermarket scale. Strategic archetypes include platform-contract anchor suppliers, coating technology specialists, and automated installation system integrators. Dominant competitive moves span backward integration into specialty steel melt shops and strategic partnerships with robotic torque system vendors.
Among diversified industrial conglomerates, Illinois Tool Works Inc. and Stanley Black & Decker, Inc. exemplify the multi-divisional structure that spans polymer and metal fastening technologies. LISI Group occupies a position within the specialized high-tensile tier, representing French metallurgical expertise that extends from aerospace into premium automotive qualification pathways. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Illinois Tool Works Inc. |
| Stanley Black & Decker, Inc. |
| LISI Group |
| SFS Group AG |
| Nifco Inc. |
| Bulten AB |
| Kamax Group |
| Shanghai Prime Machinery Company Limited |
| Würth Group |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor channels cost dynamics from Jiangsu and Zhejiang forges to downstream OEM assembly plants, concentrating pricing power among integrated suppliers while compressing margins for mid-volume distributors serving mixed-model production lines.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium aerospace-grade specifications, standard automotive platform tiers, and economy aftermarket replenishment levels. Price differentiation hinges on tensile certification grade and volume scale commitments, with REACH-compliant zinc-nickel plating commanding premiums over legacy hexavalent chromium alternatives. Cost compression in mid-volume steel alloy grades is intensifying because of scrap metal price volatility and energy intensity penalties. Aftermarket distributors exhibit highest price sensitivity due to inventory velocity pressures, whereas German luxury OEMs prioritize torque precision over unit cost.
Supply Chain Analysis
Extended payment terms from European OEMs and supply-chain finance facilities from Chinese state-backed institutions shape working capital structures for tier suppliers across the value chain. Geographic concentration rests on Germany for high-tensile chassis engineering, China for volume cold-forging capacity, and Japan for precision torque control technology. Raw material dependencies draw from specialty alloy steel melts, trivalent chrome plating chemistries, and engineered polymer feedstocks. Single-source vulnerability concentrates in PVD coating specialist shops serving battery enclosure sealing specifications. Distribution runs through tier-1 integrator consolidation in North America and captive OEM supply agreements in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive fastener market sustains defensive moats through regulatory entrenchment, where REACH coating qualifications and OEM torque specification protocols create multi-year approval barriers that entrench incumbent suppliers.
For Market Incumbents: Build specification authority moats by deepening captive relationships with German and Chinese OEM platform engineering teams while accelerating trivalent chrome plating capacity additions in Baden-Württemberg to preempt REACH enforcement windows. Threats from aluminum fastener substitution in body-in-white structures demand metallurgical R&D investment in hybrid metal-polymer joining systems.
For New Entrants and Emerging Players: Battery enclosure sealing fasteners for Korean and Chinese EV platforms represent the most penetrable entry point given compressed qualification timelines and emerging IP67 specification windows. Target robotic installation system integrators as channel partners to bypass entrenched tier-1 procurement relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core automotive fastening divisions with stranded hexavalent chromium coating assets. Long-term viability hinges on coating technology transition completion and EV platform contract density. Signal to monitor: OEM consolidation of multi-source fastener purchasing into single-source framework agreements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Melt Shops | Captive alloy supply secures margin control against scrap price volatility for high-tensile chassis grades. |
| Trivalent Chrome Plating Capacity Expansion | ECHA REACH compliance deadlines in Stuttgart and Munich accelerate qualification windows for European OEM supply. |
| Robotic Installation System Partnerships | Hyundai's Alabama and Georgia plants favor suppliers integrating vision-guided torque with programmable feed mechanisms. |
| Battery Enclosure Sealing Fastener Development | IP67 and IP69K ingress protection standards for LG Energy Solution joint ventures create specification gaps. |
| Closed-Loop Steel Fastener Production | EU Green Deal circular economy mandates open qualification pathways for recycled content in Volkswagen platform contracts. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, tier-1 supplier procurement directors, aftermarket distribution operators, and coating technology specialists and refined through secondary validation across vehicle production databases, IHS Markit registration data, SEC filings from diversified industrial conglomerates, and ECHA REACH substance restriction updates. Bottom-up demand modeling from fastener content-per-vehicle metrics was triangulated against top-down market sizing from regional production cluster analysis.
Demand-supply balance dynamics across the analysis window were modeled through segmentation across vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from regression analysis of historical platform contract volumes and forward projection of EV transition timelines. Industry-specific inputs included battery enclosure sealing specification adoption curves and automated installation system penetration rates.
Macroeconomic conditions sit as an overlay; deviation in steel alloy spot prices, euro-yen exchange rate volatility, or Chinese industrial electricity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding OEM platform electrification timelines and regulatory enforcement schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Engine Oil Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
Gasoline Direct Injection Market
Automotive Parts
Global Automotive Door Hinges Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market
Automotive Parts
Global EV Speed Reducer Market
Automotive Parts
Wind Shield Washer Market
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Global Automotive Jacks Market
Automotive Parts
Automotive Wheel Speed Sensor Tone Ring Market
Automotive Parts
Bulgaria Automotive Engine Oils Market
Automotive Parts
Automotive Differential Housing Market
Automotive Parts
Heavy Duty Clutches Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market