
 Singapore Passenger Vehicles Lubricants Market | 2026-2036
Singapore Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Passenger Vehicles Lubricants Market Analytics
Buyer concentration among Singapore's authorized dealership networks and premium independent workshops is recalibrating procurement patterns toward bulk synthetic contracts. ExxonMobil Corporation leverages its integrated Jurong Island supply infrastructure to sustain competitive logistics costs for island-wide distribution. Shell dominates the premium service channel through its controlled retail network of branded service centers. Idemitsu Kosan Co Ltd specializes in OEM-co-developed formulations that anchor its position with Japanese marque service outlets.
Singapore passenger vehicles lubricants are formulated hydrocarbon-based fluids engineered to reduce friction, dissipate heat, and prevent wear in internal combustion and hybrid powertrain systems, with SAE viscosity grades and API SP/ILSAC GF-6 performance specifications defining commercial acceptability. Engine oil occupies the dominant value share given mandatory drain intervals tied to COE-extended vehicle operating lifespans. Synthetic oil is expanding fastest as the Vehicular Emissions Scheme penalizes higher-consumption vehicles and manufacturers specify lower-viscosity grades for compliance. Mineral oil retains residual demand among older vehicle cohorts and price-sensitive maintenance segments.
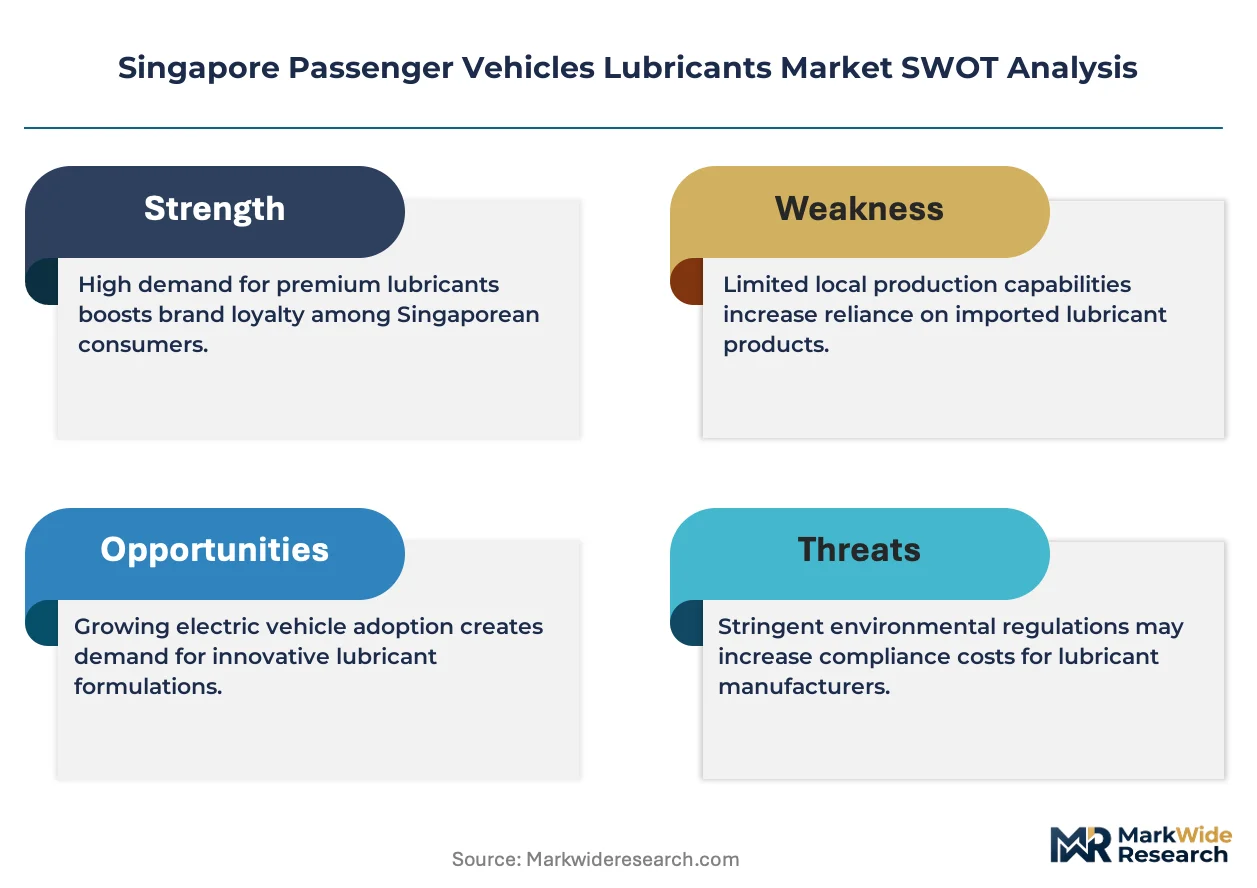
Singapore's LTA administers the Vehicular Emissions Scheme and Euro 6-equivalent standards that dictate permissible lubricant performance levels for registered vehicles. The National Environment Agency enforces hazardous substance controls that constrain formulation chemistry and waste oil handling protocols. Stakeholders must monitor regulatory tightening around carbon intensity metrics and circular economy mandates for used lubricant re-refining infrastructure.
Market Dynamics
COE renewal cycles extending vehicle lifespans past fifteen years are compressing drain intervals and amplifying synthetic lubricant consumption across Singapore's aging passenger fleet. This structural force is reshaping procurement volumes at authorized service centers and independent workshops alike.
Growth Catalysts
- Vehicular Emissions Scheme:The LTA's tightened carbon-based rebates and surcharges are mandating lower-viscosity synthetic formulations that reduce fuel consumption in passenger vehicles.
- Hybrid powertrain proliferation:Japanese and Korean OEMs specifying dedicated hybrid-compatible oils are expanding addressable demand beyond conventional ICE applications.
- Jurong Island refining cluster:Singapore's integrated petrochemical infrastructure enables rapid formulation customization and same-day island-wide distribution to service networks.
Market Restraints
- Base oil import dependency:Singapore lacks domestic Group III+ synthetic base stock production, exposing blenders to freight cost volatility from Middle Eastern and Korean suppliers.
- Workshop consolidation:Authorized dealership networks capturing premium service volumes are squeezing margin pools for independent lubricant distributors.
- Extended drain intervals:OEM-specified 15,000-kilometer synthetic oil change cycles are reducing per-vehicle lubricant throughput despite fleet expansion.
Strategic Opportunities
- Used oil re-refining infrastructure:The National Environment Agency's circular economy mandates are creating licensed collection and re-processing slots for closed-loop lubricant lifecycle management.
- Electric vehicle transition hedging:Thermal management fluids for battery-electric drivetrains represent adjacent formulation white space as Singapore's EV adoption accelerates.
- Digital service integration:Workshop management platforms linking predictive maintenance alerts to automatic lubricant replenishment are emerging in central business district corridors.
Industry Challenges
- API SP/ILSAC GF-6 certification timelines:New performance specifications require 18-24 month testing protocols that delay product launches and strain R&D budgets.
- Hazardous substance compliance:The National Environment Agency's evolving restrictions on zinc, phosphorus, and sulfur content in formulations force continuous reformulation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Passenger Vehicles Lubricants Market |
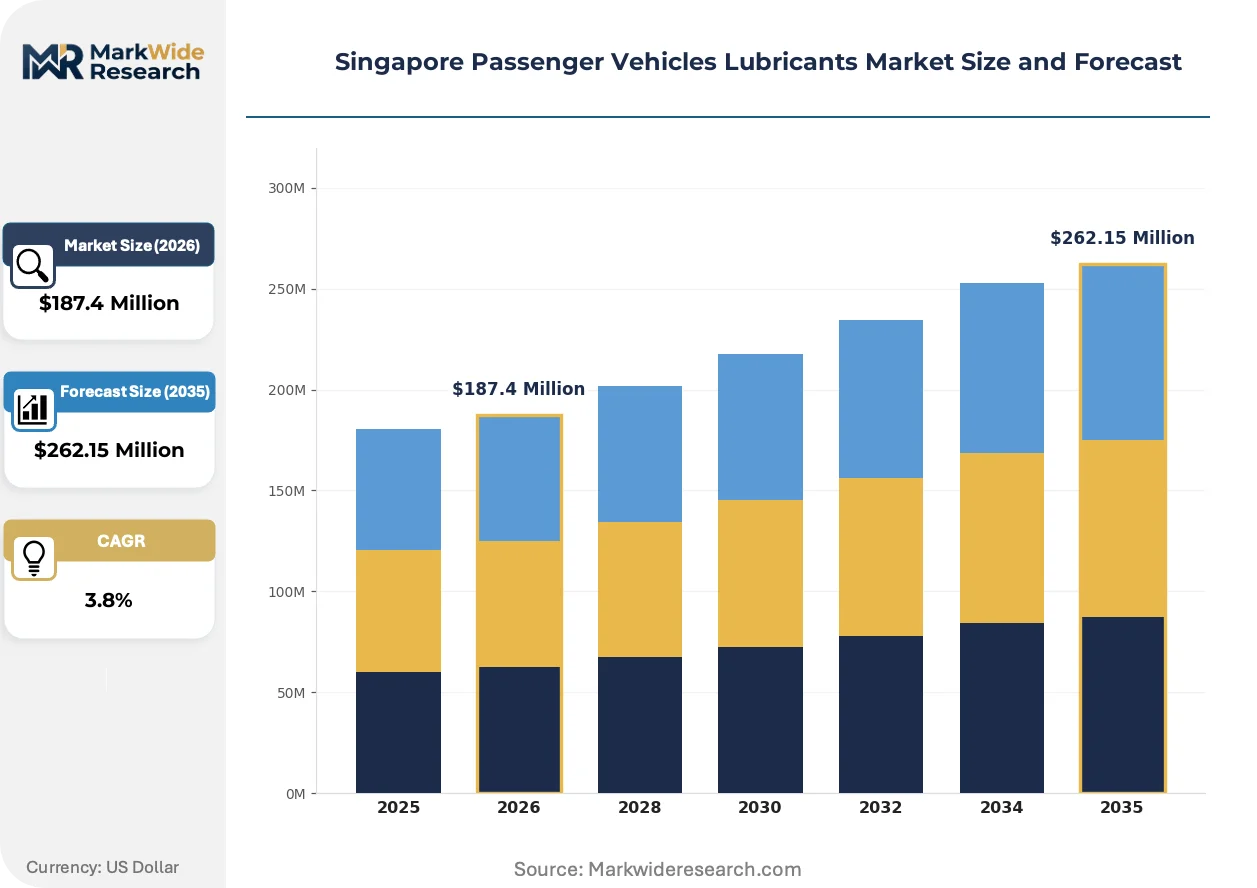
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Brake Fluid Usage Type: Cooling, Lubrication, Cleaning, Sealing Application: Passenger Cars, SUVs, Light Trucks, Commercial Vehicles Form: Mineral Oil, Synthetic Oil, Semi-Synthetic Oil, Biodegradable Oil |
| Companies Covered | BP Plc (Castrol), Chevron Corporation, ExxonMobil Corporation, Royal Dutch Shell Plc, TotalEnergies, Idemitsu Kosan Co Ltd, LIQUI MOLY, Motul, AP Oil, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Passenger Vehicles Lubricants Market Evolving Landscape
Formulation chemistry and distribution logistics are converging around emissions compliance and predictive maintenance capabilities. Three developments are restructuring competitive positioning in Singapore's passenger vehicle lubricant segment.
Artificial intelligence-driven oil condition monitoring is automating drain interval optimization for fleet operators and premium private owners. Shell's lubricant analysis laboratories and independent service chains are deploying sensor-based viscosity and contamination tracking. This capability is automating the transition from calendar-based to condition-based maintenance contracts, compressing traditional prepaid service package models.
Singapore's Vehicular Emissions Scheme and parallel Euro 6-equivalent standards are compelling lubricant marketers to certify carbon intensity metrics alongside performance specifications. The National Environment Agency is integrating lifecycle assessment data into hazardous substance licensing frameworks. Japanese and Korean OEM service outlets are responding by sourcing OEM-co-developed formulations with documented emissions reduction credentials.
Workshop procurement is consolidating around integrated supply contracts bundling lubricants, filters, and consumables. Premium independent operators in Tampines and Jurong East are displacing spot purchasing with annual volume commitments tied to inventory management systems. This behavioral shift is most visible among multi-outlet service chains seeking working capital efficiency and guaranteed synthetic oil availability.
Singapore Passenger Vehicles Lubricants Market Segmentation
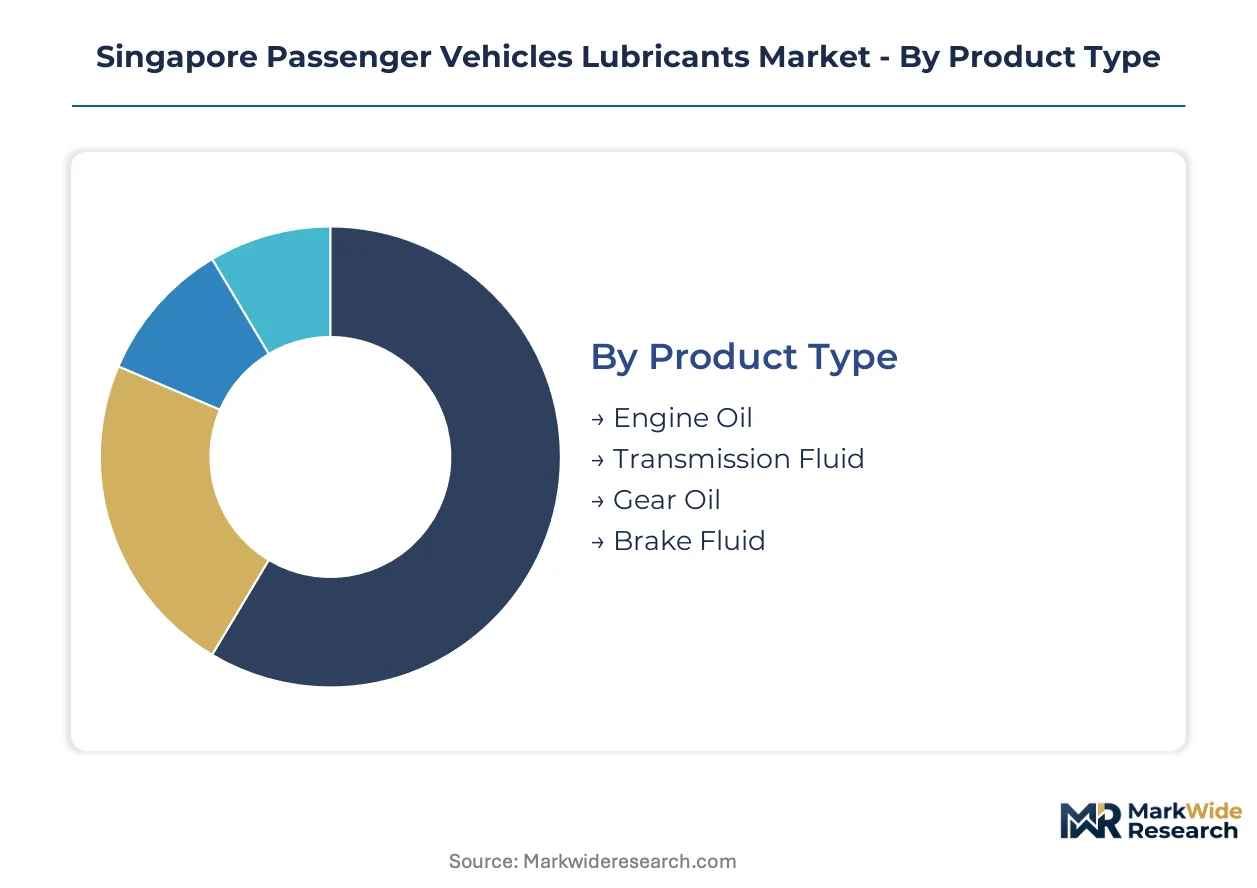
Singapore's passenger vehicle lubricant segmentation reflects the city-state's unique automotive ecosystem shaped by extended COE lifecycles and stringent emissions compliance. Understanding how demand fragments across product specifications, functional applications, and formulation chemistry enables precise targeting of the authorized dealership and premium independent workshop channels that dominate procurement.
Product Type:
Capital intensity varies sharply across product categories, with engine oil requiring the heaviest investment in API/ILSAC certification testing and base oil inventory depth.
- Engine Oil:Formulated hydrocarbon fluids meeting SAE viscosity grades and API SP/ILSAC GF-6 specifications for friction reduction and thermal management in internal combustion and hybrid powertrains. Demand concentrates in Singapore's central business district corridor and high-density HDB estates where COE-extended vehicle lifespans compress drain intervals and amplify synthetic consumption.
- Transmission Fluid:Specialized formulations for automatic and continuously variable transmissions requiring precise friction modification and oxidation stability. Japanese and Korean OEM service outlets in Tampines and Jurong East drive specification-compliant procurement as hybrid powertrain proliferation expands addressable demand beyond conventional ICE applications.
- Gear Oil:High-pressure lubricants for differential and manual transmission systems with extreme pressure additive packages.
- Brake Fluid:Hygroscopic glycol-ether or silicone-based hydraulic fluids meeting DOT specifications for safety-critical braking systems.
Engine oil absorbs the bulk of installed blending capacity; transmission fluid is expanding most quickly as hybrid powertrain penetration accelerates.
Usage Type:
Functional segmentation maps directly to vehicle system architecture and maintenance protocol intensity across Singapore's aging fleet.
- Cooling:Heat transfer fluids managing thermal loads in engine blocks, radiators, and battery-electric drivetrains. Fleet operators and premium private owners deploying sensor-based condition monitoring are automating coolant replacement scheduling.
- Lubrication:Friction-reducing films for rotating and reciprocating components under boundary and hydrodynamic regimes. The Vehicular Emissions Scheme's carbon-based rebates are mandating lower-viscosity synthetic formulations that reduce fuel consumption.
- Cleaning:Detergent-dispersant packages suspending combustion byproducts and wear debris in engine oil suspensions.
- Sealing:Conditioner additives preserving elastomer integrity in gaskets and seal assemblies.
Lubrication commands the largest formulation volume; cooling applications are climbing the fastest as thermal management complexity rises in hybrid and battery-electric vehicles.
Application:
Vehicle category segmentation tracks ownership patterns and service center density across Singapore's constrained geographic footprint.
- Passenger Cars:Sedans and hatchbacks comprising the core of Singapore's Certificate of Entitlement-managed fleet. Private vehicle owners in premium segments are expanding lubricant consumption as fifteen-year COE renewal cycles extend operating lifespans and compress maintenance intervals.
- SUVs:Sport utility vehicles with higher displacement engines and all-wheel-drive systems demanding specialized viscosity grades and additive treat rates. Jurong Island's integrated petrochemical infrastructure enables rapid formulation customization for this segment's specification diversity.
- Light Trucks:Commercial utility vehicles subject to heavier duty cycles and accelerated wear patterns.
- Commercial Vehicles:Fleet-operated delivery and logistics equipment with centralized maintenance contracts.
Passenger cars anchor volume throughput; SUVs are gaining share fastest as premium segment preferences shift toward larger vehicle formats.
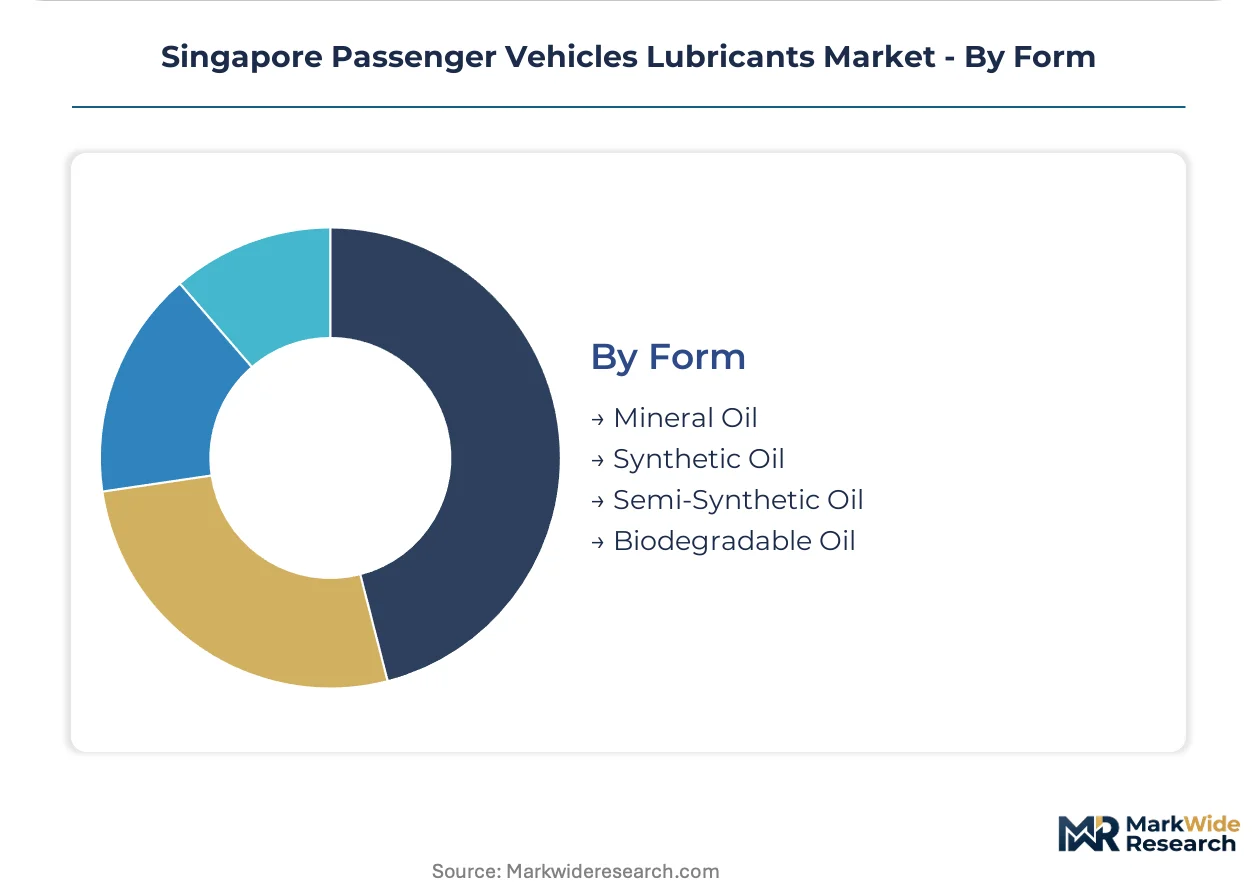
Form:
Base stock chemistry segmentation reflects the tension between emissions compliance requirements and residual price-sensitive demand.
- Mineral Oil:Refined petroleum distillates with natural viscosity indices and additive-dependent performance enhancement. Older vehicle cohorts and price-sensitive maintenance segments in Singapore's outer HDB estates retain residual demand despite regulatory pressure.
- Synthetic Oil:Group III+ and PAO base stocks engineered for thermal stability and low-temperature flow. The Land Transport Authority's tightened emissions standards are pushing demand toward fuel-efficient synthetic formulations across authorized dealership networks.
- Semi-Synthetic Oil:Blended base stock combinations balancing performance enhancement with cost containment.
- Biodegradable Oil:Ester-based or vegetable-derived formulations for environmentally sensitive applications and circular economy mandates.
Synthetic oil dominates value capture; biodegradable formulations are expanding most quickly as the National Environment Agency integrates lifecycle assessment data into hazardous substance licensing frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for passenger vehicle lubricants concentrates in Singapore's central business district corridor and high-density HDB estates, where vehicle ownership rates and service center density run highest. The Land Transport Authority's regulatory framework shapes procurement patterns across the city-state's constrained geographic footprint. Singapore's integrated petrochemical infrastructure on Jurong Island enables rapid formulation customization and same-day island-wide distribution to service networks.
Central Region
The Central Region anchors lubricant consumption through premium sedan and SUV fleets concentrated in the central business district and surrounding private residential enclaves. The Vehicular Emissions Scheme's carbon-based rebates and surcharges mandate lower-viscosity synthetic formulations that reduce fuel consumption. Authorized dealership networks in Orchard Road and Marina Bay service corridors capture premium volumes through controlled retail channels.
East Region
Tampines and Bedok host dense clusters of independent workshops serving aging vehicle cohorts with extended COE renewal cycles. The Land Transport Authority's tightened Euro 6-equivalent standards dictate permissible lubricant performance levels for registered vehicles operating in this corridor. Premium independent operators are displacing spot purchasing with annual volume commitments tied to inventory management systems.
West Region
Jurong East and Clementi service centers benefit from proximity to Jurong Island's refining cluster, enabling rapid formulation customization for specification diversity. The National Environment Agency enforces hazardous substance controls that constrain formulation chemistry and waste oil handling protocols in this industrial zone. Hybrid powertrain proliferation among Japanese and Korean OEM service outlets expands addressable demand beyond conventional ICE applications.
North Region
Woodlands and Yishun HDB estates retain residual mineral oil demand among older vehicle cohorts and price-sensitive maintenance segments. The National Environment Agency's circular economy mandates are creating licensed collection and re-processing slots for closed-loop lubricant lifecycle management. Workshop consolidation among authorized dealership networks is squeezing margin pools for independent lubricant distributors in this corridor.
North-East Region
Sengkang and Punggol service centers serve younger vehicle fleets with OEM-specified synthetic formulations for 15,000-kilometer drain intervals. The Land Transport Authority's Vehicular Emissions Scheme penalizes higher-consumption vehicles, pushing demand toward fuel-efficient synthetic grades. Digital service integration platforms linking predictive maintenance alerts to automatic lubricant replenishment are emerging in these high-density residential zones.
Singapore Passenger Vehicles Lubricants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent formulation spaces including hybrid-compatible and thermal management fluids. The market structures around three tiers: integrated petrochemical majors with captive base oil supply, specialized lubricant blenders with OEM certification depth, and regional distributors serving price-sensitive maintenance segments. Consolidation pressures favor players with API SP/ILSAC GF-6 certification capabilities and hazardous substance compliance infrastructure. Dominant competitive moves include strategic partnerships with authorized dealership networks and portfolio diversification into re-refining services.
Among integrated majors, ExxonMobil Corporation leverages Singapore-based supply infrastructure, while Royal Dutch Shell Plc exemplifies premium channel control through branded service center networks. Idemitsu Kosan Co Ltd occupies a specialized position anchoring Japanese marque service outlets with OEM-co-developed formulations. These three represent distinct archetypes: petrochemical integration, retail network dominance, and OEM technical partnership.
| Leading Market Players |
|---|
| BP Plc (Castrol) |
| Chevron Corporation |
| ExxonMobil Corporation |
| Royal Dutch Shell Plc |
| TotalEnergies |
| Idemitsu Kosan Co Ltd |
| LIQUI MOLY |
| Motul |
| AP Oil |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between API SP/ILSAC GF-6 synthetic formulations and residual mineral oil tiers manifests in divergent margin structures and procurement logistics across Singapore's service network channels. Premium synthetic contracts at authorized dealerships command formulation premiums tied to OEM compliance documentation, while price-sensitive independent workshops in outer HDB estates source mineral-based alternatives through spot market distributors with compressed working capital cycles.
Pricing Analysis
Volume throughput concentrates in economy-grade mineral oil segments serving aging COE-extended fleets, yet margin capture concentrates in synthetic formulations where API SP certification creates scarcity rents. Price differentiation hinges on OEM co-development credentials and bulk contract scale, with authorized dealership networks leveraging annual volume commitments to extract supplier concessions. Cost compression in the mineral tier is intensifying because workshop consolidation is squeezing distributor margins. Fleet operators and premium private owners in the central business district corridor exhibit the lowest price sensitivity, while older vehicle cohorts in Woodlands and Yishun retain acute elasticity.
Supply Chain Analysis
Group III+ synthetic base stock supply rests on Middle Eastern and Korean specialty refiners, exposing Singapore blenders to freight cost volatility and currency fluctuation. Formulation chemistry draws from additive packages manufactured in Japan and the United States, with zinc and phosphorus content constrained by National Environment Agency hazardous substance protocols. Single-source vulnerability concentrates in the Korean Group III+ channel, where limited alternative suppliers extend lead times during regional supply disruptions. Distribution runs through Jurong Island's integrated petrochemical cluster, enabling same-day island-wide replenishment to service centers via controlled tanker and packaged goods networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's passenger vehicle lubricants market is consolidating around players with API certification depth and circular economy licensing, as regulatory compliance costs force sub-scale blenders toward exit or acquisition. Workshop procurement centralization and extended drain interval adoption are accelerating this structural pressure.
For Market Incumbents: To counter margin compression from 15,000-kilometer OEM drain intervals, deepen captive supply of re-refining infrastructure under National Environment Agency circular economy mandates, and secure exclusive synthetic formulation contracts with expanding Japanese and Korean hybrid powertrain service outlets. For New Entrants and Emerging Players: Premium independent workshop chains in Tampines and Jurong East represent the most penetrable channel archetype, given their displacement of spot purchasing with integrated supply contracts. Target thermal management fluid development for battery-electric drivetrains as Singapore's EV adoption accelerates, leveraging digital service integration platforms for automatic replenishment hooks. For Investors and Strategic Acquirers: Re-rating potential sits with specialized blenders holding OEM-co-development credentials and hazardous substance compliance infrastructure, given the Vehicular Emissions Scheme's tightening trajectory and the 18-24 month API certification timeline that delays competitive entry. Acquisition targets should demonstrate re-refining license coverage and hybrid-compatible formulation pipelines. The signal to watch is National Environment Agency circular economy mandate acceleration, which would vertically integrate collection and re-processing economics into lubricant lifecycle value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Re-refining Infrastructure Licensing | National Environment Agency circular economy mandates create closed-loop lifecycle economics for compliant operators. |
| OEM Co-development Partnerships | Japanese and Korean marque service outlets anchor specification-compliant procurement for hybrid powertrain proliferation. |
| Digital Service Integration | Predictive maintenance platforms in Sengkang and Punggol automate lubricant replenishment for fleet operators. |
| Thermal Management Fluid Development | Battery-electric drivetrain cooling represents adjacent formulation white space as Singapore's EV adoption accelerates. |
| API SP/ILSAC GF-6 Certification Investment | Eighteen-month testing protocols delay product launches and strain R&D budgets for sub-scale competitors. |
Research Methodology
Trade customs data, Land Transport Authority vehicle registration statistics, and National Environment Agency hazardous substance licensing records formed the secondary backbone, cross-referenced with primary interviews with lubricant blending plant managers, authorized dealership procurement leads, premium independent workshop operators, and aftermarket distribution channel partners. Bottom-up volume estimates from service center throughput data were reconciled with top-down petrochemical consumption figures across the analysis window.
Historical trendline analysis of synthetic and mineral oil procurement patterns informed elasticity assumptions for price-volume relationships across certification tiers. Segmentation modeling incorporated product type, base stock chemistry, vehicle application, and regional service network density dimensions. CAGRs were derived from regression-adjusted trend extrapolation incorporating COE renewal cycle dynamics and Vehicular Emissions Scheme compliance trajectories as structural inputs.
Caveats apply where Middle Eastern base oil freight cost volatility or accelerated EV adoption could materially shift the outlook for internal combustion lubricant demand. Forecasts reflect documented assumptions regarding regulatory tightening pace and workshop consolidation velocity. A small set of named triggers—National Environment Agency circular economy mandate acceleration, hybrid powertrain penetration rates, and re-refining infrastructure licensing pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
High Speed Rolling Bearings Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Oil Catch Cans Market
Automotive Parts
Argentina Automotive Engine Oils Market
Automotive Parts
Automotive Carbon Canister Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Vietnam Commercial Vehicles Lubricants Market
Automotive Parts
Electric Power Steering System (EPS) Market
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Uae Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Key Blanks Market
Automotive Parts
Global Automotive Damper Market
Automotive Parts
Automotive Trailing Arm Market