
 Global Automotive Parts Remanufacturing Market | 2026-2036
Global Automotive Parts Remanufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Parts Remanufacturing Market Intelligence
Margin differentiation between remanufacturing traditional mechanical components and complex electro-mechanical systems is narrowing as vehicle technology advances. Robert Bosch GmbH leverages its electronics expertise to capture value in advanced transmission and electrical module remanufacturing. Cummins Inc. sustains its leadership through a dominant presence in the diesel engine remanufacturing segment for commercial vehicles. ZF Friedrichshafen AG positions itself by offering a broad portfolio across both mechanical and electronic product lines for passenger and commercial applications.
Automotive parts remanufacturing is an industrial process where used components, or cores, are restored to original equipment manufacturer (OEM) performance specifications. This process involves complete disassembly, cleaning, inspection, and replacement of worn parts, ensuring the final product meets stringent quality and reliability standards. The primary purpose is to offer a cost-effective and environmentally sustainable alternative to new parts for vehicle repair and maintenance. Engine and transmission remanufacturing represent mature, high-value product segments, while demand from the commercial vehicles application provides significant per-unit margin opportunities.
Regulatory frameworks directly shape component standards and market access for remanufacturers. In the United States, state-level 'Right to Repair' legislation affects core availability for the independent aftermarket, while the European Union's Circular Economy Action Plan encourages the use of remanufactured goods. China's Ministry of Industry and Information Technology (MIIT) supports the sector through specific pilot programs and standardization efforts. Future competitive advantage will be determined by securing reliable access to quality cores and navigating evolving intellectual property protections from vehicle OEMs.
Market Dynamics
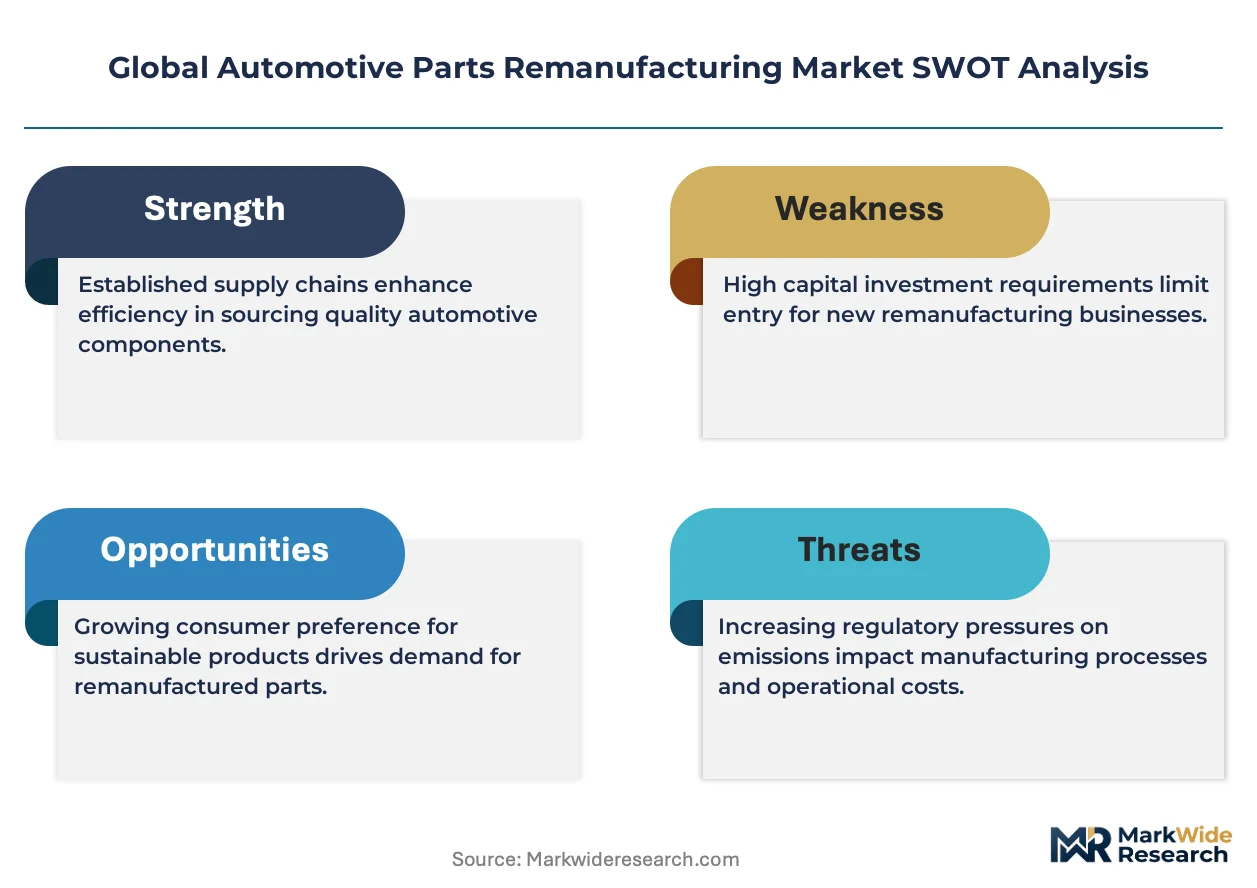
The central tension in the automotive parts remanufacturing market is the conflict between vehicle OEM control over proprietary electronic systems and the independent aftermarket's push for access, a dynamic heavily influenced by evolving 'Right to Repair' regulations.
Growth Catalysts
- Regulatory Frameworks:Europe's Circular Economy Action Plan and Green Deal provide strong policy tailwinds by encouraging the reuse of components, directly benefiting the remanufacturing sector through supportive mandates and sustainability targets.
- Commercial Fleet Economics:North American commercial vehicle operators are a primary demand source, utilizing remanufactured diesel engines and transmissions to achieve a lower total cost of ownership and maximize vehicle uptime.
- Standardization in China:Government-led initiatives from China's MIIT, including pilot programs and the development of national standards, are structuring and scaling the domestic market for remanufactured automotive parts.
Market Restraints
- Intellectual Property Barriers:Vehicle OEMs increasingly use software locks and encryption on electronic control units and other mechatronic modules, effectively preventing third-party remanufacturers from accessing and repairing these complex components.
- Core Supply Volatility:The availability and quality of used parts, or cores, is often inconsistent, especially for newer vehicle models or complex electronic systems, creating significant sourcing challenges and production delays.
- New Part Competition:In some segments, the declining price of new, non-OEM replacement parts manufactured in low-cost regions presents a direct substitution threat to remanufactured mechanical components like alternators and starters.
Strategic Opportunities
- Electric Vehicle Components:The shift to electrification opens a new frontier for remanufacturing high-value EV components, including battery packs, electric drive motors, and power electronics, which are currently underserved.
- South American Market Entry:Large, aging vehicle parcs in countries like Brazil and Argentina present a significant, underpenetrated market for traditional engine, transmission, and drivetrain component remanufacturing.
- Digital B2B Platforms:Developing certified online marketplaces that connect core suppliers, remanufacturers, and workshops can streamline the fragmented supply chain, improving core acquisition, logistics, and price transparency.
Industry Challenges
- Technical Skill Gaps:A shortage of technicians skilled in diagnosing and repairing complex mechatronic systems creates a bottleneck, demanding substantial investment in advanced training and diagnostic equipment for the workforce.
- Navigating OEM Patents:The increasing complexity of OEM intellectual property protections around vehicle software and component design leads to a heightened risk of patent infringement litigation and legal costs for remanufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Parts Remanufacturing Market |
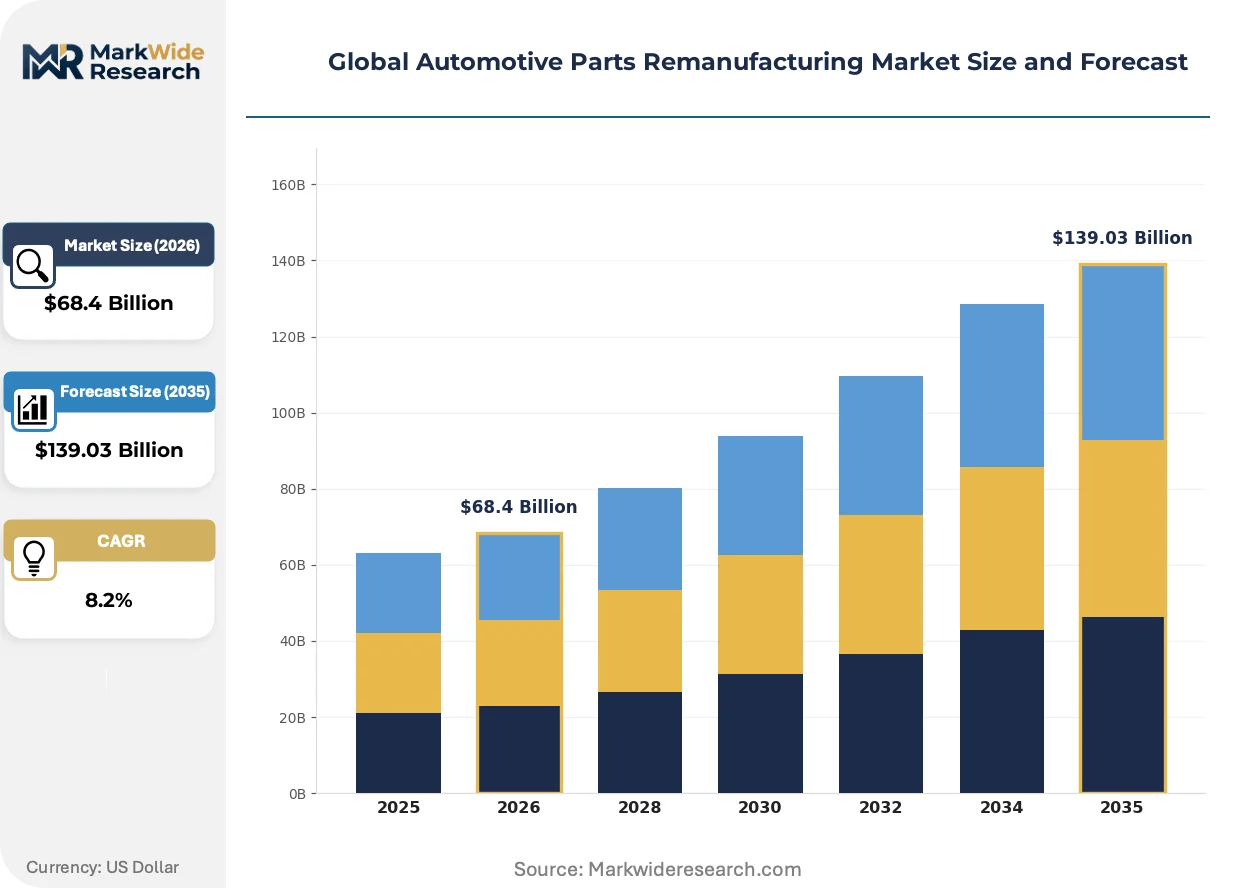
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $139.03 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engines, Transmissions, Steering Systems, Brake Components, Electrical Modules Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Industrial Transport, Agricultural Machinery Technology: Mechanical, Electro-Mechanical, Chemical, Thermal, Surface Treatment End User: OEMs, Tier-1 Suppliers, Aftermarket Retailers, Vehicle Assemblers, Fleet Operators |
| Companies Covered | BorgWarner Inc., Caterpillar Inc., Robert Bosch GmbH, LKQ Corporation, Cummins Inc., ZF Friedrichshafen AG, Denso Corporation, Eaton Corporation, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Parts Remanufacturing Market Strategic Shifts & Innovations
Industrialization within remanufacturing is shifting from a focus on purely mechanical restoration toward data-driven processes for complex electronic systems. This evolution prioritizes component lifecycle management and predictive analytics to ensure performance equivalent to new parts.
Advanced diagnostic tools and non-destructive testing (NDT) methods enable precise evaluation of core component integrity and material fatigue. Independent remanufacturers and large fleet maintenance operations are adopting these systems to assess high-value items like engine blocks and transmission casings. This technological adoption is digitizing the traditionally manual inspection process, allowing for predictive failure analysis and enhancing final product reliability.
State-level 'Right to Repair' legislation in the United States is compelling vehicle OEMs to grant independent repair shops access to essential diagnostic data, tools, and service components. This policy directly improves the availability of viable cores for remanufacturers by counteracting OEM restrictions. The independent aftermarket for powertrain and electronic modules is most affected, securing a more stable foundation for sourcing and servicing advanced vehicle systems.
Large commercial fleet operators are transitioning from simple transactional parts procurement to comprehensive service agreements with remanufacturing partners. These contracts often bundle remanufactured components with core management, predictive maintenance services, and uptime guarantees, displacing the traditional parts-and-labor repair model. This trend is most visible within the heavy-duty trucking sector in North America and Europe, where predictable operational costs are paramount.
Global Automotive Parts Remanufacturing Market Segmentation
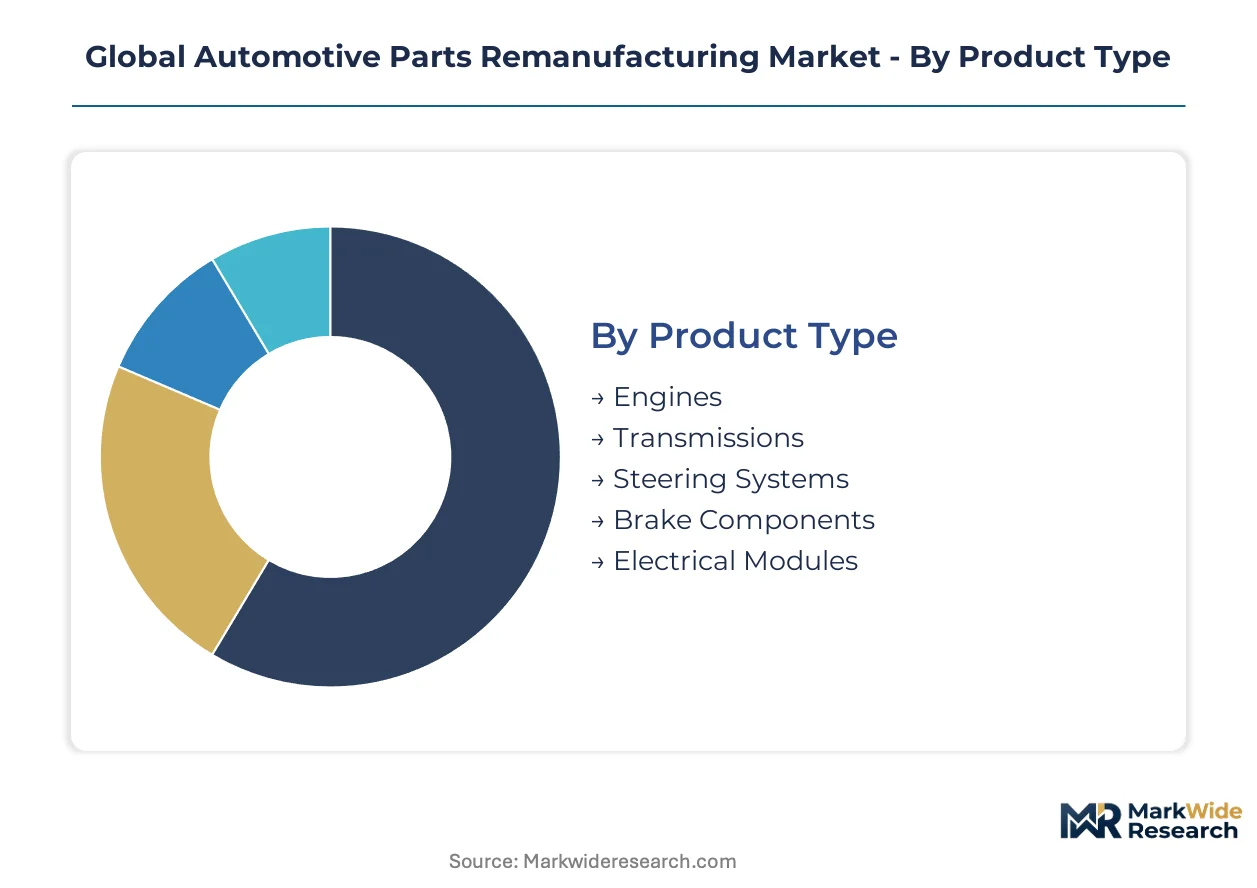
Understanding the varied segments within the automotive parts remanufacturing market provides crucial insights into demand drivers and technological shifts. This analysis categorizes the market by product type, application, underlying technology, and the primary end-users, highlighting distinct commercial opportunities across the value chain.
Product Type:
The specific component being restored delineates distinct market dynamics, from core availability to required technical expertise for remanufacturing processes.
- Engines:These complex power units undergo extensive disassembly, cleaning, and replacement of worn components like pistons, crankshafts, and cylinder heads. Demand concentrates in North American heavy-duty trucking fleets, driven by the need for reliable, cost-effective replacements that extend vehicle service life.
- Transmissions:Automatic and manual transmissions are meticulously rebuilt to OEM specifications, involving gear, bearing, and clutch pack replacement. Commercial vehicle operators in Europe increasingly rely on remanufactured transmissions to lower operational costs and reduce vehicle downtime.
- Steering Systems:Remanufactured steering racks, pumps, and gearboxes offer a sustainable alternative for restoring vehicle handling and safety. These components find consistent demand within the independent aftermarket for older vehicle models globally.
- Brake Components:Remanufacturing brake calipers and master cylinders ensures critical safety functions are restored using high-quality replacement parts. This segment serves both passenger and commercial vehicle repair shops seeking economical solutions.
- Electrical Modules:This segment includes remanufactured electronic control units (ECUs), alternators, and starters, requiring specialized diagnostic and repair capabilities. The independent aftermarket in countries like Germany values these for maintaining legacy vehicle electronics.
Engines holds installed capacity. Electrical Modules is rotating up the share rankings.
Application:
The vehicle type utilizing remanufactured components directly influences volume, product specifications, and purchasing patterns across different sectors.
- Commercial Vehicles:This segment includes heavy-duty trucks, buses, and vans, where remanufactured engines and transmissions are critical for fleet efficiency. North American operators prioritize these parts for their lower total cost of ownership and extended operational uptime.
- Passenger Vehicles:Remanufactured parts for cars and light trucks, such as alternators, starters, and brake calipers, address the need for affordable repairs. The aftermarket in countries like China sees substantial volume for these components, supporting a large vehicle parc.
- Two-Wheelers:Remanufacturing for motorcycles and scooters primarily focuses on engine and transmission components, offering economical repair options. Markets in Southeast Asia, with their high two-wheeler penetration, represent a growing niche for these parts.
- Industrial Transport:This application covers vehicles used in logistics, construction, and mining, which often require robust remanufactured components for heavy-duty use. Demand from the mining sector in Australia emphasizes durability and rapid component availability.
- Agricultural Machinery:Tractors, harvesters, and other farm equipment utilize remanufactured engines and hydraulic components to reduce maintenance costs and extend equipment lifespan. Farmers in Brazil increasingly adopt these solutions to manage operational expenses.
Demand from Commercial Vehicles remains consistent. Agricultural Machinery is expanding most quickly.
Technology:
The underlying technological complexity of the remanufacturing process defines the required equipment, skill sets, and potential for margin differentiation.
- Mechanical:This category encompasses traditional processes like machining, grinding, and re-balancing for components such as engine blocks, crankshafts, and gear sets. These established methods form the backbone of the remanufacturing industry for core powertrain components.
- Electro-Mechanical:Remanufacturing of integrated systems like advanced transmissions, power steering units, and turbochargers involves both mechanical restoration and electronic calibration. Expertise in diagnostics and software integration is critical for these complex assemblies.
- Chemical:Processes such as specialized cleaning, surface preparation, and coating applications fall under this technology type, crucial for restoring material integrity and performance. This is particularly relevant for components exposed to high temperatures or corrosive environments.
- Thermal:Heat treatment, welding, and thermal spraying techniques are applied to restore worn surfaces, improve material hardness, or repair structural damage in specific components. These methods are vital for extending the life of high-stress parts.
- Surface Treatment:This technology involves applying protective or functional coatings to component surfaces to enhance wear resistance, reduce friction, or prevent corrosion. Such treatments are increasingly used for engine and transmission parts to meet modern performance standards.
Traditional Mechanical methods are foundational. Electro-Mechanical innovations are gaining share.
End User:
The specific customer segment procuring remanufactured parts influences distribution channels, quality expectations, and service level agreements.
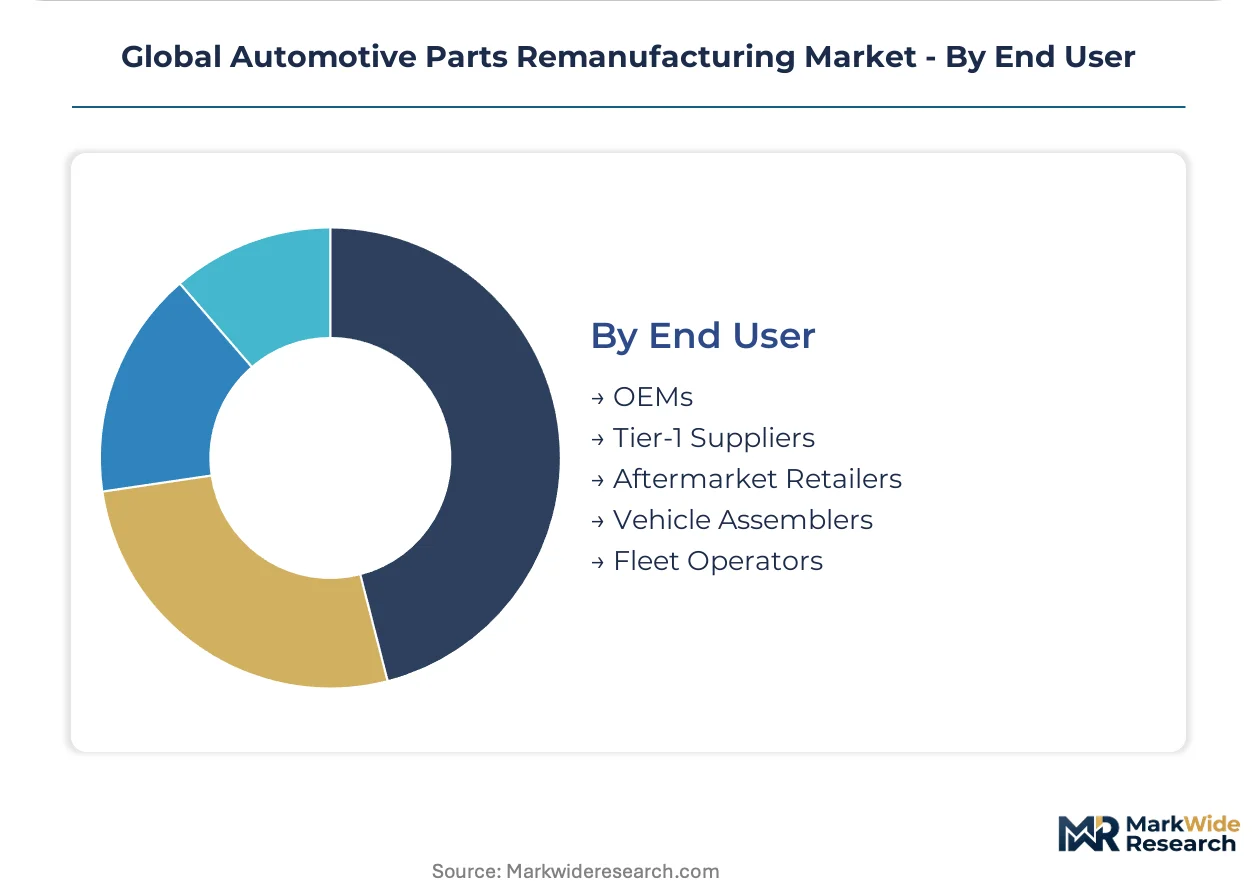
- Fleet Operators:Commercial vehicle fleets, especially in North America and Europe, are major consumers of remanufactured engines and transmissions due to their focus on uptime and total cost of ownership. These operators often seek long-term service contracts with remanufacturers.
- Aftermarket Retailers:These entities, including independent parts stores and online platforms, distribute a wide range of remanufactured components to repair shops and individual consumers. They serve as a crucial link for accessing cost-effective replacement parts across various vehicle makes.
- OEMs:Original Equipment Manufacturers engage in remanufacturing programs for their own components, ensuring brand-specific quality and often offering warranty-backed products. Robert Bosch GmbH and Cummins Inc. exemplify OEMs with strong remanufacturing divisions.
- Tier-1 Suppliers:These suppliers, such as ZF Friedrichshafen AG, remanufacture their proprietary components, including transmissions and steering systems, to support their OEM customers and the independent aftermarket. They leverage their design expertise for high-quality restoration.
- Vehicle Assemblers:While primarily focused on new vehicle production, some assemblers utilize remanufactured components in specific applications or as part of their service parts strategy. This practice is less common but can occur for certain high-value sub-assemblies.
Fleet Operators represents a significant volume channel. OEMs is showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Where commercial fleet operators prioritize total cost of ownership, demand for remanufactured parts exhibits high price elasticity. Conversely, segments requiring specialized electronic module restoration or OEM-level performance show lower sensitivity to initial cost. Regional market dynamics reflect these varying priorities.
United States
Demand for remanufactured diesel engines and transmissions is robust among North American commercial fleet operators. State-level 'Right to Repair' legislation supports core availability for the independent aftermarket. Fleet hubs like Atlanta and Chicago see significant activity in heavy-duty component remanufacturing. This ensures vehicle uptime and reduces operational expenses.
China
Government policies promoting sustainable industrial practices drive significant demand for remanufactured components across China. The Ministry of Industry and Information Technology (MIIT) supports the sector through specific pilot programs and standardization efforts. Major industrial zones in the Yangtze River Delta are developing specialized remanufacturing clusters. This fosters a structured and scaled domestic market.
Germany
The independent aftermarket for legacy vehicle electronics and powertrain components sustains consistent demand in Germany. Europe's Circular Economy Action Plan encourages the use of remanufactured goods across the automotive sector. Cities like Stuttgart, home to major automotive OEMs, are centers for advanced remanufacturing R&D and production. This ensures quality and reliability for complex systems.
Brazil
An aging vehicle parc in Brazil creates substantial demand for traditional engine, transmission, and drivetrain component remanufacturing. Farmers increasingly adopt these solutions for agricultural machinery to manage operational expenses. Industrial centers such as São Paulo and Minas Gerais are emerging as key hubs for remanufacturing activity. This addresses the need for cost-effective equipment maintenance.
France
Europe's Green Deal provides a strong policy tailwind for remanufactured components, boosting demand in France. This regulatory push encourages the reuse of automotive parts, aligning with sustainability targets. Automotive manufacturing regions like Auvergne-Rhône-Alpes are expanding capabilities for remanufacturing various mechanical and electro-mechanical systems. This supports a circular economy model.
Global Automotive Parts Remanufacturing Market Key Industry Players
Capability concentration sits with one tier, particularly in complex electro-mechanical systems, while scale advantage sits with another in traditional mechanical components. The market structure features a tiered landscape, encompassing original equipment manufacturers (OEMs), specialized Tier-1 suppliers, and independent remanufacturers. Strategic partnerships for core acquisition and portfolio diversification into advanced components represent dominant competitive moves. Companies also pursue geographic expansion into underserved markets.
Within the OEM and Tier-1 supplier archetypes, Robert Bosch GmbH, a German-based GmbH, exemplifies expertise in advanced transmission and electrical module remanufacturing, reflecting a focus on complex systems. Cummins Inc., a US-based Inc., anchors the diesel engine remanufacturing segment for commercial vehicles, demonstrating leadership in heavy-duty applications. ZF Friedrichshafen AG, another German AG, occupies a strong position with a broad portfolio spanning both mechanical and electronic product lines, indicating a comprehensive market approach. These established players leverage their engineering heritage and extensive distribution networks to maintain market influence. Their presence signifies the importance of both specialized technical capability and broad product offerings in this evolving market.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Caterpillar Inc. |
| Robert Bosch GmbH |
| LKQ Corporation |
| Cummins Inc. |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Eaton Corporation |
| Valeo SA |
| Others |
Cost & Logistics Intelligence
Core supply volatility, particularly for complex electronic modules, directly determines both pricing tier spreads and the fragmented shape of the automotive remanufacturing supply chain. This dependency creates significant cost variability for remanufacturers.
Pricing Analysis
Aftermarket parts procurement drives lifetime value for commercial fleet operators, influencing pricing strategies. Per-unit transactional pricing dominates for remanufactured components, with quality grade and OEM-backed certification driving differentiation. Pricing softness stems from competition with new, low-cost non-OEM replacement parts. Commercial vehicle fleet operators exhibit high price sensitivity, prioritizing total cost of ownership, while OEM service networks prioritize brand-specific quality.
Supply Chain Analysis
Specialized remanufacturing operations, often integrated within OEM or Tier-1 supplier facilities, hold significant capacity for complex electro-mechanical systems. Geographic supply concentration includes China, driven by MIIT policies, and Germany, a hub for advanced remanufacturing R&D. The supply chain relies on a consistent flow of used components, or cores, creating single-source vulnerability for specific high-value parts. Distribution runs through aftermarket retailers, OEM service networks, and direct contracts with fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive remanufacturing market operates within a landscape of capability scarcity, primarily driven by a critical shortage of technicians skilled in complex electro-mechanical systems. This talent deficit creates bottlenecks and shapes competitive dynamics.
For Market Incumbents: Harden existing core acquisition networks through strategic partnerships with large fleet operators to counter core supply volatility. Invest in proprietary diagnostic tools and advanced training programs for electro-mechanical systems to mitigate technical skill gaps. This shields against OEM intellectual property restrictions and competitive pressure from new, low-cost components. Diversify remanufacturing portfolios into electric vehicle battery packs.
For New Entrants and Emerging Players: Underpenetrated South American markets, particularly Brazil and Argentina, represent the most penetrable entry point for traditional engine and transmission remanufacturing. Focus on developing certified digital B2B platforms to streamline core acquisition and sales to independent workshops. Target high-value electric vehicle components like battery modules and power electronics, which currently lack established remanufacturing infrastructure.
For Investors and Strategic Acquirers: The market sits at a transformative growth phase that favors specialized electro-mechanical remanufacturers with robust technical capabilities. Long-term viability is strong, driven by circular economy mandates and the transition to electric vehicles. Acquire firms with proven expertise in advanced diagnostics and a secure supply of complex electronic cores. The increasing scope of 'Right to Repair' legislation is a critical signal to watch for expanded market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital B2B Platform Development | Certified online marketplaces streamline fragmented core acquisition and distribution for remanufacturers. |
| EV Battery Remanufacturing Capacity | Scaling capabilities for electric vehicle battery packs unlocks a high-value, underserved segment. |
| Advanced Diagnostics Investment | Proprietary tools enable precise evaluation and repair of complex electro-mechanical systems like ECUs. |
| Long-term Core Supply Agreements | Securing reliable access to quality used components mitigates volatility and ensures production stability. |
| Technical Skill Development Programs | Addressing the shortage of skilled technicians enhances diagnostic and repair capabilities for mechatronic systems. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation through published sources. Discussions included OEM procurement managers, independent aftermarket distributors, commercial fleet maintenance heads, and remanufacturing plant engineers. Secondary data sources comprised vehicle production databases, government circular economy reports, and automotive industry association publications. Bottom-up and top-down triangulation ensured data consistency.
Forecast inputs considered historical market performance, current industry trends, and future technological shifts. The analytical framework integrated quantitative and qualitative analysis over the projection horizon. Segmentation dimensions modeled included product type, application, technology, end-user, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical data and projected growth drivers.
Practitioners should monitor regulatory shifts and EV component advancements for early signals of market revision. Forecasts reflect assumptions documented at publication, acknowledging core supply volatility risks. Quarterly review of legislative updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Electric HVAC Compressor Market
Automotive Parts
Automotive Coupling Replacement Kit Market
Automotive Parts
Automotive All Wheel Drive Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
Philippines Passenger Vehicles Lubricants Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Brake Caliper Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Italy Passenger Vehicles Lubricants Market
Automotive Parts
South America Automotive Lubricants Market
Automotive Parts
South Africa Passenger Vehicles Lubricants Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Control Arms Market
Automotive Parts
Automotive Transmission Valve Spool Market