
 Automotive Air Flow Meter Market | 2026-2036
Automotive Air Flow Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Air Flow Meter Market Analysis
Ceramic substrate thinning is rebalancing cost structures across thermal-type air flow meter production. Robert Bosch GmbH leverages captive semiconductor fabrication to sustain margin control on hot-film sensor elements. Denso Corporation anchors its position through R&D intensity in vortex-shedding measurement architectures. Continental AG competes via geographic dominance in European OEM supply chains for mass air flow modules.
An automotive air flow meter measures intake air mass or volume using thermal, pressure, vortex, or ultrasonic detection principles, typically operating within temperature ranges of minus forty to one hundred twenty degrees Celsius to enable precise fuel injection mapping. Mass air flow sensors dominate OEM fitment due to direct correlation with stoichiometric combustion control, while ultrasonic technology represents the fastest-growing segment as manufacturers seek non-intrusive measurement paths for hybrid powertrains. Aftermarket providers occupy a mature channel with compressed margins, whereas heavy duty truck applications concentrate margin pools in calibrated replacement modules for fleet operators.
EPA tailpipe standards, Euro 7 emission frameworks, and Japan's Ministry of Economy Trade and Industry (METI) fuel efficiency mandates collectively tighten sensor accuracy thresholds and accelerate OBD-II diagnostic integration. California Air Resources Board (CARB) zero-emission vehicle regulations further bifurcate demand between precision ICE air metering and battery thermal management airflow sensing. Stakeholders must decide whether to deepen hot-film expertise or redirect development capital toward ultrasonic architectures serving hybrid platforms.
Market Dynamics
Powertrain electrification is fragmenting demand between precision internal combustion engine optimization and battery thermal management airflow sensing, forcing suppliers to maintain dual competency portfolios without scale concentration in either domain.
Growth Catalysts
- EPA Tier 3 emission standards:These tailpipe regulations mandate tighter mass air flow sensor calibration tolerances, compelling passenger vehicle OEMs to upgrade measurement precision across gasoline direct injection platforms.
- Hybrid powertrain architectures:Manufacturers integrating internal combustion engines with electric motors require non-intrusive air measurement paths that thermal-type sensors cannot provide, accelerating ultrasonic technology qualification.
- Japan METI fuel efficiency mandates:These frameworks enforce combustion optimization protocols that depend on accurate intake air mass calculation, sustaining demand for hot-film sensors in domestic kei car and compact vehicle production.
Market Restraints
- Platinum group metal volatility:Hot-film sensor elements depend on platinum and palladium thin-film deposition, exposing producers to raw material price swings that compress gross margins unpredictably.
- Wafer fabrication concentration:Captive semiconductor production for sensor ASICs clusters in Taiwan and South Korea, creating geographic supply vulnerability for European and North American meter manufacturers.
- Ultrasonic path interference:Non-intrusive measurement technologies face signal degradation from intake manifold pulsation and particulate contamination, limiting accuracy in high-performance engine applications.
Strategic Opportunities
- India BIS certification expansion:The Bureau of Indian Standards is implementing automotive component quality protocols that favor precision air metering suppliers with established calibration laboratories.
- Heavy duty fleet telematics integration:Calibrated replacement modules for commercial truck operators now incorporate OBD-II diagnostic streaming, creating recurring revenue attachment beyond hardware sale.
- RoHS exemption phase-out timing:European lead-free soldering mandates for automotive electronics are compressing competitor qualification timelines, advantaging early-compliant producers with existing lead-free sensor packaging.
Industry Challenges
- Embedded software validation:Mass air flow modules now require ASIL-B functional safety certification under ISO 26262, extending development cycles and demanding specialized automotive software engineering talent.
- Dual-source qualification friction:OEMs require redundant sensor suppliers for each engine program, forcing meter manufacturers to replicate proprietary calibration datasets across competing procurement relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Air Flow Meter Market |
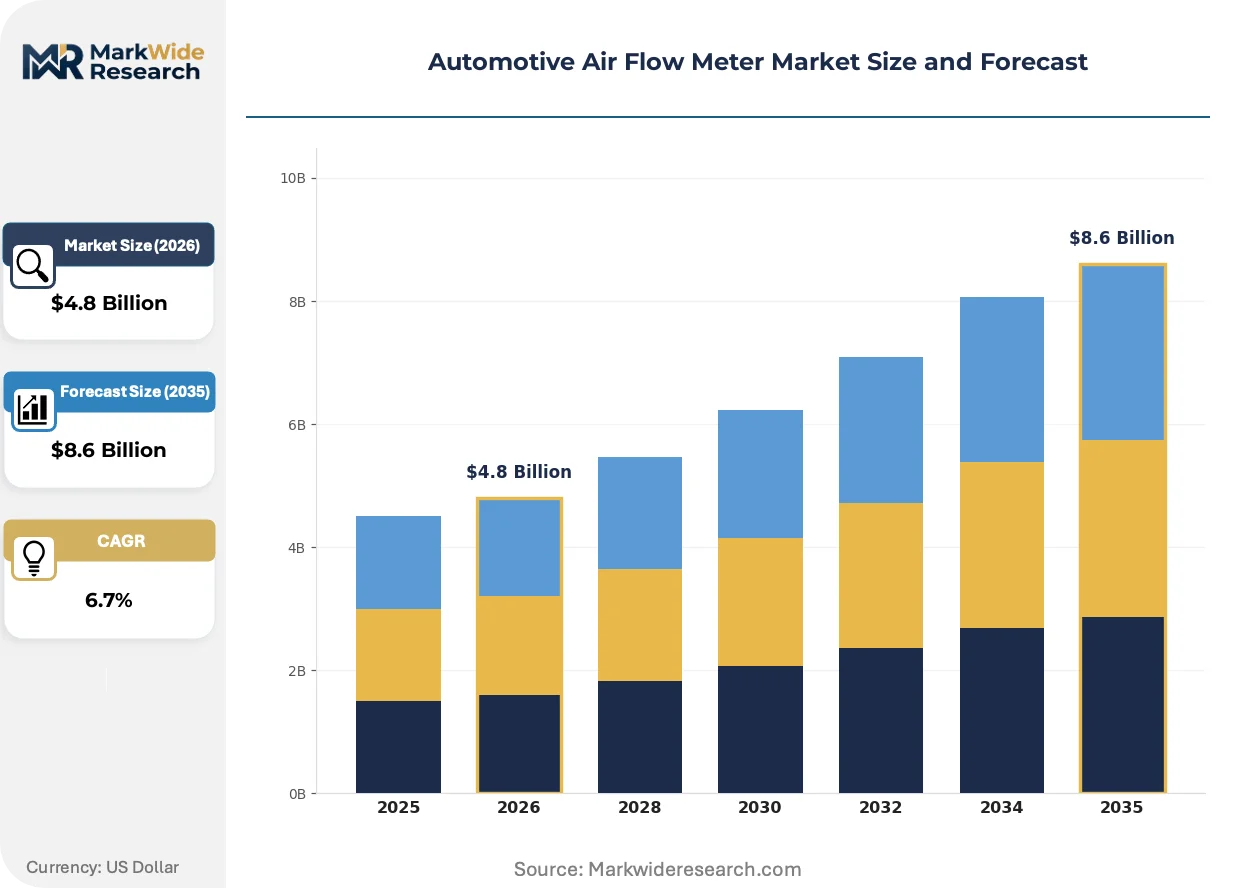
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Mass Air Flow, Volumetric Flow, Differential Pressure, Combination Technology: Thermal, Pressure, Vortex, Ultrasonic End User: OEMs, Aftermarket Providers, Dealerships, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Heavy Duty Trucks, Off-Road Vehicles |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, BorgWarner Inc., Hitachi Automotive Systems Ltd, HELLA GmbH & Co. KGaA, Sensata Technologies Inc, TE Connectivity, Valeo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Air Flow Meter Market Emerging Trajectories
Measurement architecture convergence is dissolving the boundary between intake air sensing and powertrain thermal management, with hybrid platforms demanding multi-physics sensors that operate across combustion and electric domains simultaneously.
MEMS-based hot-film technology is unifying air temperature, pressure, and mass flow detection within single substrate packages. Tier 1 suppliers are adopting these consolidated sensors for engine control module integration to reduce wiring harness complexity. This unification is compressing the addressable market for discrete sensor specialists while elevating semiconductor fabrication capabilities as the primary competitive moat.
EU F-Gas Regulation amendments are restricting hydrofluorocarbon use in automotive climate systems, indirectly tightening requirements for cabin air intake measurement accuracy to optimize refrigerant charge calculations. European OEM supply chains are responding by specifying ultrasonic flow meters with humidity compensation algorithms for HVAC integration, diverting engineering resources from engine bay applications.
Fleet operators now specify outcome-based sensor performance contracts rather than unit procurement, tying supplier payment to diagnostic accuracy uptime over multi-year service intervals. This behavior is displacing traditional aftermarket parts distribution through jobber networks in North American commercial vehicle channels, concentrating volume with direct manufacturer relationships and certified installer programs.
Automotive Air Flow Meter Market Segmentation
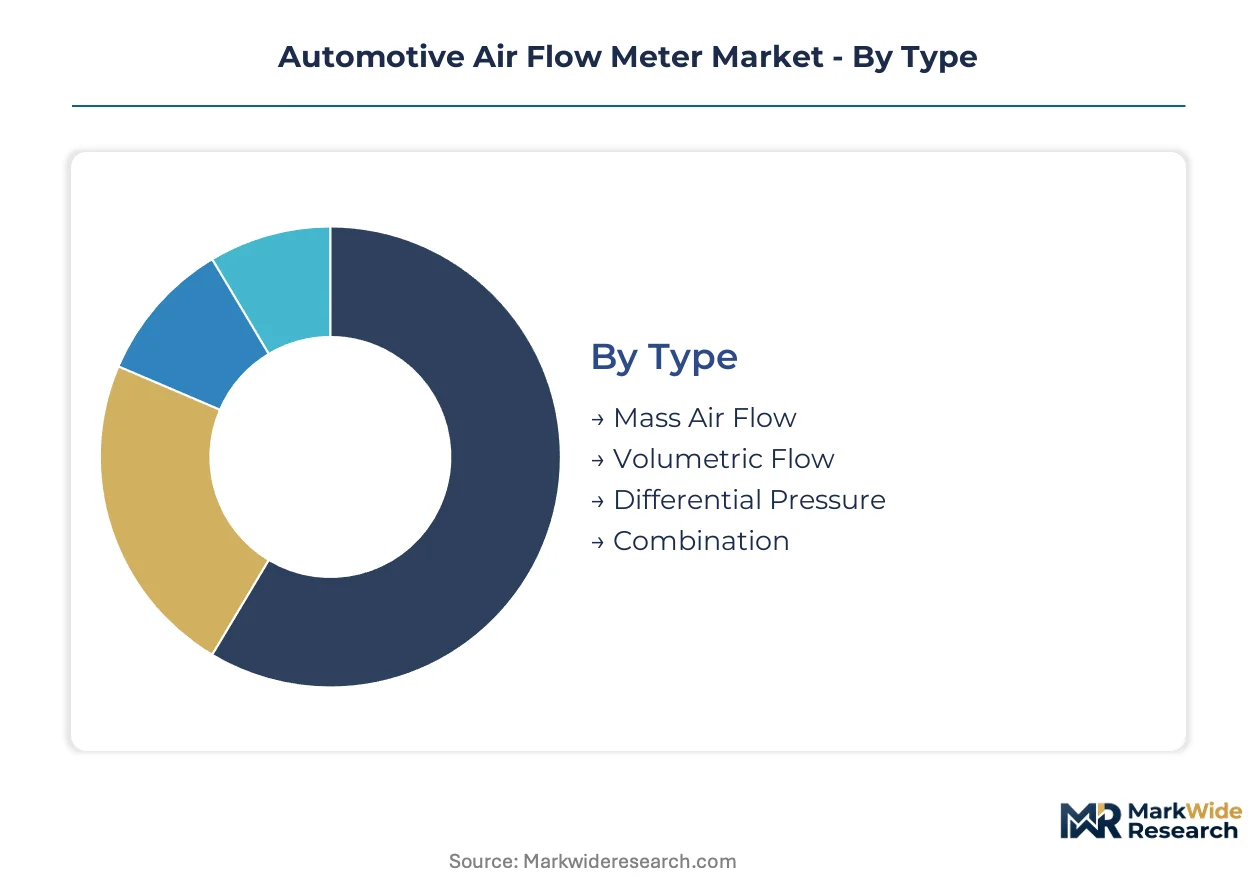
Segmentation reveals how automotive air flow meter suppliers allocate capital across divergent technical requirements. Measurement principle selection determines semiconductor fabrication investment, while end-user channel choice dictates calibration infrastructure and margin capture mechanics.
Type:
Supply concentration in MEMS fabrication favors sensor architectures that consolidate multiple measurement functions within single substrate packages.
- Mass Air Flow:Direct measurement of intake air mass using heated film elements enables stoichiometric fuel injection control. Demand clusters in Germany and Japan where OEMs face EPA Tier 3 and METI efficiency mandates requiring precise combustion calibration.
- Volumetric Flow:Measures air volume displacement through vortex-shedding or mechanical flap mechanisms. Commercial vehicle assemblers in the United States specify these sensors for heavy duty diesel platforms where intake pulsation tolerance exceeds hot-film durability limits.
- Differential Pressure:Calculates flow via pressure drop across calibrated orifices. Fleet telematics integrators favor this architecture for OBD-II diagnostic compatibility.
- Combination:Integrates mass, temperature, and pressure sensing within unified packages. Hybrid powertrain manufacturers specify these to reduce wiring harness complexity.
Today's leader: Mass Air Flow. Tomorrow's challenger: Combination.
Technology:
Cost tier stratification separates premium non-intrusive architectures from commodity thermal sensors facing platinum group metal volatility.
- Thermal:Hot-film and hot-wire elements dominate OEM fitment through direct mass correlation with fuel injection mapping. Robert Bosch GmbH and Denso Corporation concentrate production in Germany and Japan, leveraging captive semiconductor fabrication to offset palladium thin-film cost swings.
- Ultrasonic:Non-intrusive measurement using time-of-flight detection avoids intake manifold contamination issues. This architecture is expanding most quickly in hybrid platforms where thermal sensor intrusion conflicts with packaging constraints.
- Pressure:Differential and absolute pressure transducers serve cost-sensitive commercial vehicle applications. Indian BIS certification expansion favors suppliers with established calibration laboratories for this technology tier.
- Vortex:Fluidic oscillation measurement provides durability in high-turbulence intake environments. Off-road vehicle assemblers specify vortex sensors for mining and construction equipment operating in particulate-heavy conditions.
Volume concentrates in Thermal. Margin migrates toward Ultrasonic.
End User:
Customer type determines calibration dataset ownership and recurring revenue attachment through diagnostic service contracts.
- OEMs:Passenger vehicle manufacturers specify ASIL-B certified modules with proprietary calibration maps locked to engine control units. Dual-source qualification requirements force suppliers to replicate datasets across competing procurement relationships.
- Aftermarket Providers:Mature distribution channels face compressed margins as fleet operators shift toward outcome-based performance contracts.
- Dealerships:Authorized service networks access manufacturer-locked calibration tools for warranty repair segments.
- Vehicle Assemblers:Contract manufacturers for regional brands prioritize BIS-compliant sensors with documented traceability for Indian market entry.
Procurement authority sits with OEMs. Profit pool expansion favors direct fleet relationships.
Application:
Application scope dictates temperature range specifications and thermal cycling durability requirements.
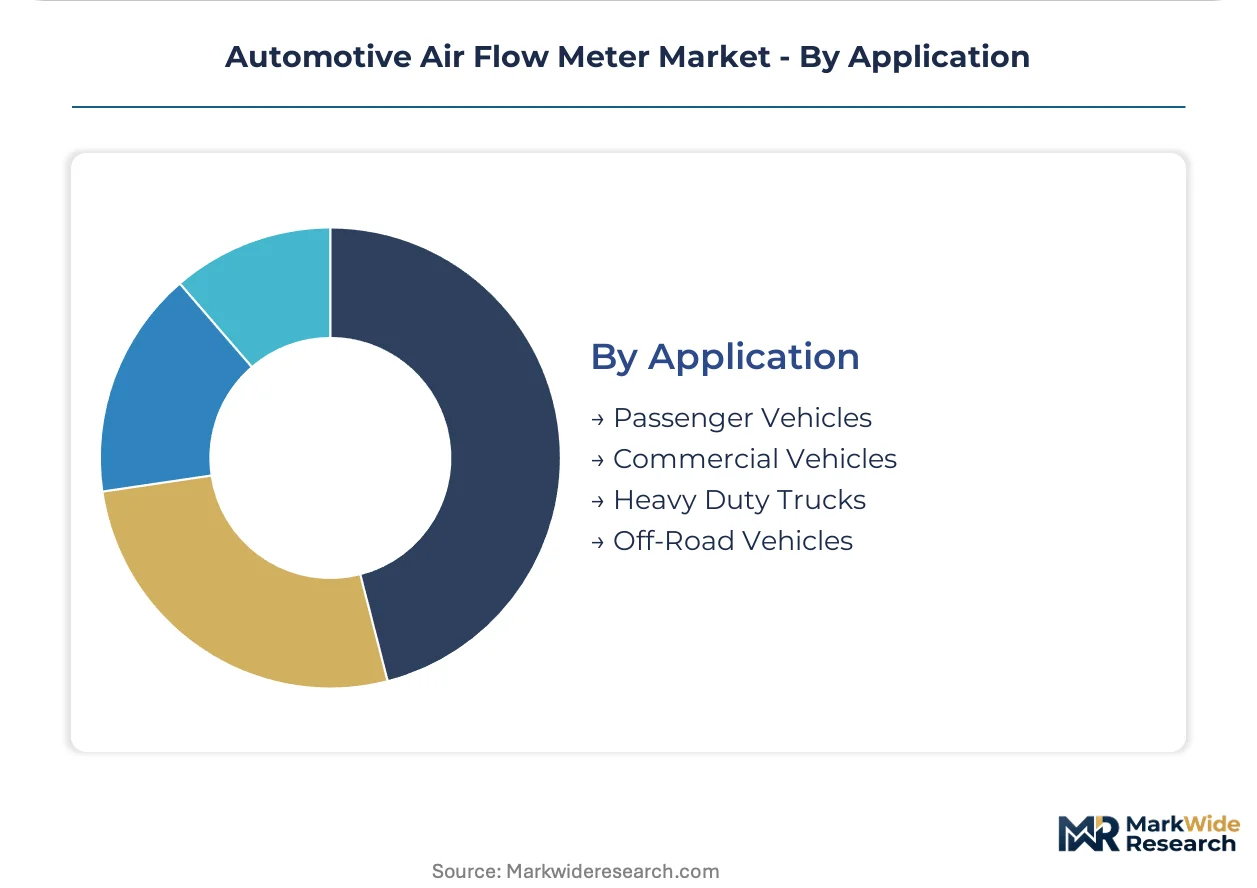
- Passenger Vehicles:Gasoline direct injection platforms require minus forty to one hundred twenty degrees Celsius operating range. Euro 7 emission frameworks tighten accuracy thresholds for this segment.
- Commercial Vehicles:Medium-duty truck specifications prioritize diagnostic integration over absolute precision.
- Heavy Duty Trucks:Fleet operators now specify calibrated replacement modules with embedded telematics streaming. California Air Resources Board regulations bifurcate demand between ICE optimization and battery thermal management sensing.
- Off-Road Vehicles:Construction and agricultural equipment demands sealed housings resistant to dust ingress and vibration fatigue.
Technology investment flows toward Passenger Vehicles. Margin accumulation shifts to Heavy Duty Trucks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing belt anchors precision sensor demand, with Stuttgart and Munich clusters driving MEMS-based hot-film procurement for gasoline direct injection platforms across European OEM supply chains.
Germany
Domestic OEM procurement concentrates mass air flow sensor demand around Stuttgart, Munich, and Wolfsburg production corridors. Euro 7 emission frameworks tighten calibration tolerances for gasoline direct injection systems. Robert Bosch GmbH leverages captive semiconductor fabrication in Reutlingen to offset platinum group metal volatility on hot-film sensor margins.
United States
Passenger vehicle OEMs in Detroit and Silicon Valley expand ultrasonic sensor qualification for hybrid powertrain architectures. EPA Tier 3 tailpipe regulations mandate tighter mass air flow calibration across light-duty gasoline platforms. California Air Resources Board zero-emission vehicle rules bifurcate demand toward battery thermal management airflow sensing in Fremont and Palo Alto EV manufacturing clusters.
Japan
Kei car and compact vehicle production in Nagoya and Tokyo sustains hot-film sensor demand for stoichiometric combustion optimization. METI fuel efficiency mandates enforce intake air mass calculation accuracy thresholds. Denso Corporation anchors domestic supply through R&D intensity in vortex-shedding measurement architectures at its Kariya technical center.
India
Vehicle assembler procurement for regional brands concentrates in Pune, Chennai, and Gurugram manufacturing corridors. Bureau of Indian Standards automotive component quality protocols favor precision air metering suppliers with established calibration laboratories. Domestic contract manufacturers prioritize BIS-compliant sensors with documented traceability for market entry compliance.
South Korea
Semiconductor fabrication concentration in Hsinchu and Seoul creates geographic supply vulnerability for European and North American meter manufacturers seeking sensor ASICs. Wafer production clusters in Suwon and Pyeongtaek feed MEMS substrate demand for combination sensors integrating mass, temperature, and pressure detection. Domestic chaebol procurement patterns favor dual-source qualification requirements that replicate proprietary calibration datasets across competing relationships.
Automotive Air Flow Meter Market Vendor Landscape
Global majors compete with regional champions across semiconductor fabrication capabilities and OEM supply chain integration. The vendor base concentrates around three strategic tiers: captive semiconductor fabricators with in-house MEMS production, Tier 1 module integrators dependent on external wafer supply, and aftermarket specialists serving fleet telematics channels. Competitive positioning hardens through backward integration into sensor ASIC design and geographic expansion into BIS-compliant calibration laboratory networks.
Within the captive fabrication tier, Robert Bosch GmbH and Denso Corporation exemplify vertical control over hot-film element production. Continental AG occupies a position bridging European OEM supply chain dominance with module integration scale. Among diversified automotive electronics suppliers, Sensata Technologies Inc and TE Connectivity represent the external-ASIC-dependent archetype sourcing from Taiwan and South Korea wafer clusters. BorgWarner Inc and Valeo Group sit within the powertrain-focused supplier tier competing on hybrid platform qualification timelines.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| BorgWarner Inc. |
| Hitachi Automotive Systems Ltd |
| HELLA GmbH & Co. KGaA |
| Sensata Technologies Inc |
| TE Connectivity |
| Valeo Group |
| Others |
Supply Flow & Price Mechanics
Passenger vehicle OEM procurement concentration around gasoline direct injection platforms enforces contract-based long-term offtake pricing with volume-scale tiering. Platinum group metal volatility in hot-film sensor elements feeds directly into supplier margin compression, forcing captive semiconductor fabricators to absorb cost swings through backward integration while external-ASIC-dependent Tier 1s face pricing pressure from wafer fabrication concentration.
Pricing Analysis
Platinum and palladium thin-film deposition costs pass through to module pricing in thermal-type sensors, with Robert Bosch GmbH and Denso Corporation offsetting this through in-house MEMS production. Price differentiation hinges on ASIL-B functional safety certification grade and geographic delivery cost to European versus Asian OEM clusters. Pricing pressure stems from fleet operator shift toward outcome-based performance contracts in North American heavy duty channels. Aftermarket providers exhibit highest price sensitivity due to compressed margins in mature distribution networks, while OEMs with dual-source qualification requirements show lowest sensitivity due to calibration dataset lock-in.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Nagoya operate hub-and-spoke patterns feeding just-in-time assembly lines. Wafer fabrication concentrates in Taiwan and South Korea, with MEMS substrate production clustering in Suwon and Pyeongtaek. Raw material dependencies include platinum group metals for hot-film elements, silicon wafers for sensor ASICs, and ceramic substrates for thermal cycling durability. Single-source vulnerability in semiconductor supply creates geographic risk for European and North American meter manufacturers. Distribution runs through Tier 1 module integrators to OEM engine plants, with certified replacement modules bypassing traditional jobber networks for direct fleet relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automotive air flow meters rests on MEMS unification reducing wiring harness complexity and ultrasonic technology migration capturing hybrid platform premiums. Ceramic substrate thinning and captive semiconductor fabrication provide structural cost-down pathways for scale producers.
For Market Incumbents: To counter ultrasonic technology displacement in hybrid powertrain architectures, deepen hot-film expertise through MEMS-based combination sensor development while securing dual-source qualification lock-in with European OEMs. Expand captive wafer fabrication capacity to offset platinum group metal volatility exposure. Prioritize ASIL-B functional safety certification investment to extend development cycle moats against external-ASIC-dependent competitors.
For New Entrants and Emerging Players: Capture India BIS certification expansion by establishing calibration laboratories in Pune and Chennai corridors before competitor qualification timelines compress. Target heavy duty fleet telematics integration with outcome-based sensor performance contracts displacing traditional aftermarket distribution. Pursue direct manufacturer relationships with commercial vehicle operators as the most penetrable channel, leveraging OBD-II diagnostic streaming for recurring revenue attachment.
For Investors and Strategic Acquirers: Tier 1 powertrain suppliers with hybrid platform qualification pipelines are the most active acquirer in this space, seeking MEMS fabrication capabilities to secure sensor ASIC supply. Long-term viability over the next decade favors backward-integrated producers with captive semiconductor production and established OEM calibration dataset libraries. Monitor EPA Tier 3 and Euro 7 emission standard implementation timing as the signal to watch for inflection in precision air metering demand versus battery thermal management sensing bifurcation.
| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Capacity Expansion | Captive wafer production insulates Robert Bosch GmbH and Denso Corporation from Taiwan supply vulnerability. |
| Ultrasonic Technology Qualification | Non-intrusive measurement paths secure hybrid platform share as EPA Tier 3 tightens thermal sensor packaging constraints. |
| ASIL-B Functional Safety Certification | ISO 26262 compliance extends development cycles and elevates semiconductor fabrication capabilities as competitive moat. |
| India Calibration Laboratory Network | BIS-compliant infrastructure captures vehicle assembler procurement for Pune, Chennai, and Gurugram manufacturing corridors. |
| Fleet Telematics Integration | Outcome-based performance contracts displace traditional aftermarket jobber networks in North American commercial vehicle channels. |
Methodological Framework
Coverage spans Germany, Japan, the United States, India, and South Korea, with primary inputs from each regional cluster combining interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet telematics integrators. Secondary validation draws from vehicle production databases, IHS Markit registration data, EPA and CARB regulatory filings, and METI efficiency mandate documentation. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers across the analysis window.
Rate-of-change decomposition separates volume effects from value migration across measurement principle, technology tier, end-user channel, and application segments. The analytical framework models vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster as core dimensions. CAGRs derive from regression against historical fitment rates and regulatory mandate implementation schedules, with semiconductor fabrication capacity and platinum group metal price indices as industry-specific forecast inputs.
Platinum group metal volatility, wafer fabrication geographic concentration, and hybrid powertrain architecture adoption timing are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Japan Ball Bearing Market
Automotive Parts
Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
HCV Brake Components Market
Automotive Parts
Large Volume Injector Market
Automotive Parts
Automotive Brake Shims Market
Automotive Parts
Colombia Automotive Lubricants Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market
Automotive Parts
Brake Pad Market
Automotive Parts
Global Windshield Wiper Blades Market
Automotive Parts
Nigeria Automotive Lubricants Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
South Africa Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Fluids Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market