
 Wiper Blade Market | 2026-2036
Wiper Blade Market Size, Share, and Industry Trends Forecast 2026-2036
Wiper Blade Market Analytics
A capital-intensity divergence between integrated rubber compounders and assembly-only suppliers is redrawing competitive boundaries in wiper blade manufacturing. Bosch leverages captive polymer research to sustain margin control across European OEM channels. Valeo anchors its position through vertical integration into windshield wiper motor systems, extending beyond blade supply. Trico competes aggressively in North American aftermarket distribution, occupying shelf space through private-label partnerships with national retailers.
Wiper blades are precision-molded elastomer assemblies mounted to articulated or tensioned frames, engineered to maintain uniform contact pressure across curved glass surfaces across temperature ranges from minus forty to plus eighty degrees Celsius. Their primary commercial purpose is ensuring optical clarity and operator safety in precipitation conditions across automotive, rail, and marine applications. Beam blade configurations are capturing premium positioning as aerodynamic profiles reduce wind lift at highway speeds, while conventional designs retain volume dominance in emerging markets where cost sensitivity shapes replacement behavior. The aftermarket installation channel generates recurring revenue streams independent of new vehicle sales cycles, though OEM direct-fit specifications are tightening tolerances and compressing universal-fit alternatives.
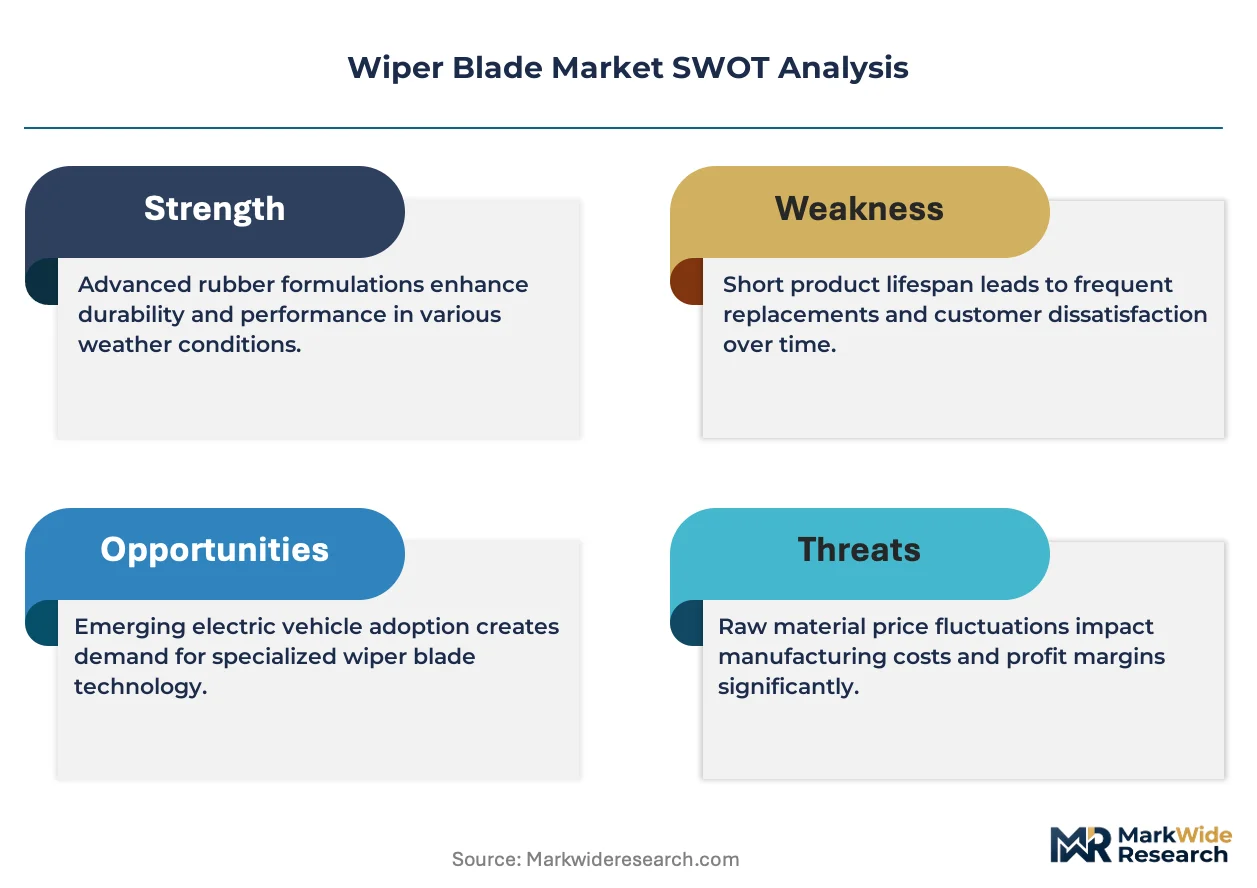
NHTSA Federal Motor Vehicle Safety Standard 104 governs windshield wiping and washing systems in the United States, mandating minimum swept areas and operational speeds that blade designs must satisfy for vehicle type approval. The European Union's REACH regulation restricts certain plasticizers and heavy metal stabilizers in rubber compounds, forcing reformulation of traditional chloroprene and EPDM blade materials. China's GB standards for automotive electrical products, administered by the Standardization Administration, specify corrosion resistance and durability testing protocols for wiper systems sold in the domestic market. Stakeholders must monitor how escalating material compliance costs interact with consumer willingness to pay for extended-life blade technologies.
Market Dynamics
Beam blade architecture is compressing replacement frequency across passenger car fleets while tightening OEM specifications squeeze universal-fit alternatives from direct-fit channels.
Growth Catalysts
- EU pedestrian safety mandates:Stricter impact protection requirements are accelerating adoption of integrated wiper motor-blade systems that reduce hood protrusion hazards in European vehicle designs.
- EPDM compound advances:Improved synthetic rubber formulations are extending operational temperature ranges and UV resistance, enabling longer service intervals in high-sunlight climates.
- China domestic production scaling:Local vehicle manufacturing volumes are creating concentrated demand for premium blade formats as domestic brands upgrade component specifications.
Market Restraints
- Natural rubber price volatility:Plantation supply disruptions in Southeast Asia are squeezing margins for compounders dependent on Hevea brasiliensis feedstocks.
- REACH compliance costs:European chemical restrictions on plasticizers and heavy metal stabilizers are forcing reformulation of traditional chloroprene blade materials at elevated R&D expense.
- Beam blade tooling concentration:Precision extrusion and co-injection molding equipment for frameless designs concentrates among a narrow supplier base in Germany and Japan.
Strategic Opportunities
- India aftermarket underpenetration:Organized retail and e-commerce channels remain underdeveloped for replacement blades, creating first-mover advantages for branded distribution networks.
- Commercial fleet telematics integration:Sensor-enabled wiper systems that report blade wear to fleet management platforms are opening recurring revenue models in logistics and ride-hail segments.
- US IRA clean vehicle incentives:Electric vehicle production tax credits are accelerating domestic EV assembly, where aerodynamic beam blades are specified as standard equipment.
Industry Challenges
- Tooling retooling cycles:Migration from conventional bracket frames to beam architectures requires capital-intensive mold replacement and technician retraining.
- NHTSA type approval timelines:Federal Motor Vehicle Safety Standard 104 testing protocols create extended validation periods for new blade designs seeking OEM fitment.
- Cross-platform compatibility engineering:Proliferating windshield curvatures and wiper arm geometries are multiplying SKU complexity for aftermarket catalog management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wiper Blade Market |
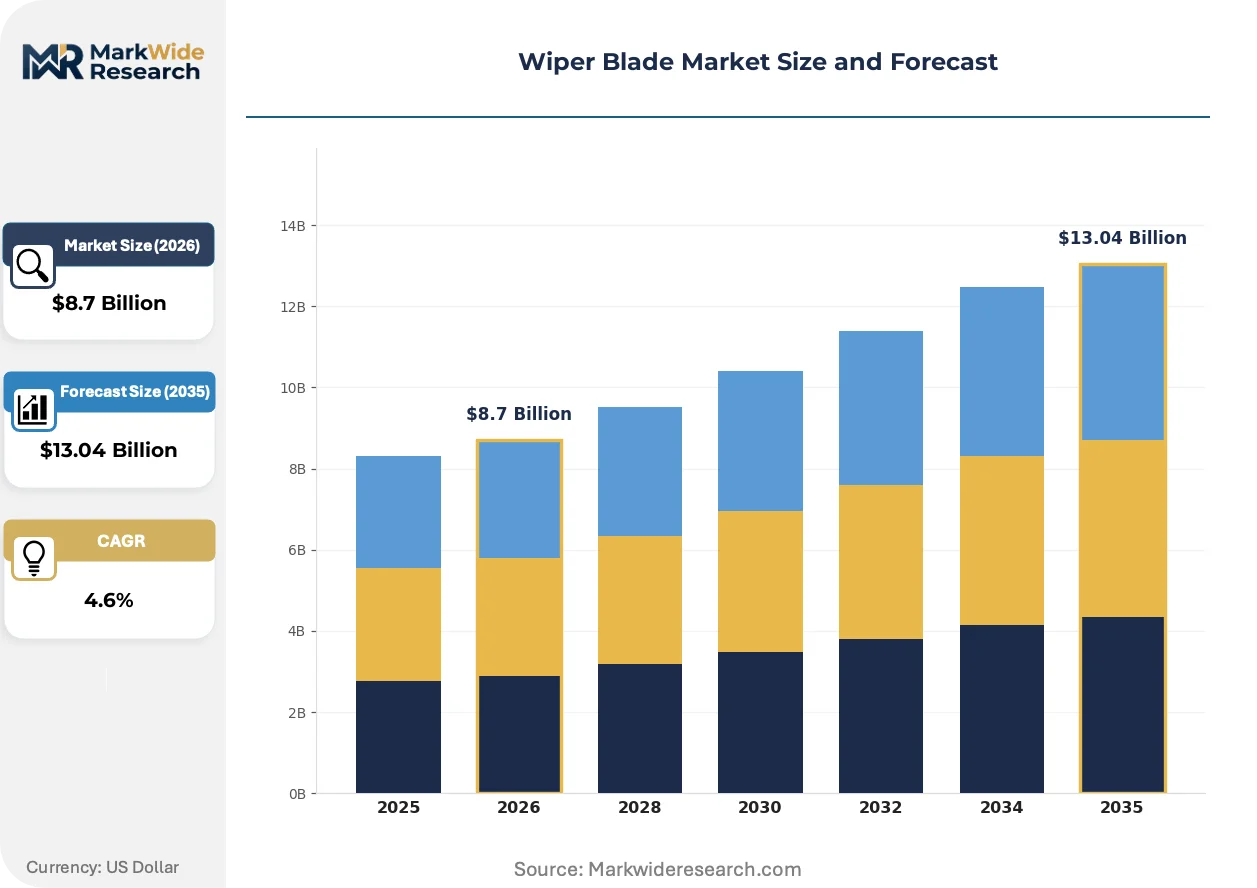
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Beam, Hybrid, Specialty Vehicle Type: Passenger Cars, SUVs, Trucks, Buses Material: Rubber, Silicon, Plastic, Composite Installation Type: OEM, Aftermarket, Direct Fit, Universal |
| Companies Covered | Denso, CLWIPER, Bosch, Rain-X, Scan Top, Valeo, Federal Mogul, Lucas, Trico, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wiper Blade Market Evolving Landscape
Material science breakthroughs and regulatory pressure on visibility performance are restructuring how blade systems are engineered, sourced, and replaced across vehicle categories.
Silicone rubber compounds are decomposing the traditional EPDM-chloroprene duopoly in premium blade segments. Luxury and performance vehicle manufacturers are specifying silicone for its hydrophobic surface treatment and extended durability. This chemistry shift is compressing commodity rubber demand in the upper tier of the replacement market while creating captive supply relationships with specialized compounders.
REACH Annex XVII restrictions on phthalate plasticizers are forcing reformulation of traditional blade edge materials across European supply chains. Compounders must validate alternative flex agents without sacrificing low-temperature elasticity. Aftermarket suppliers serving EU member states are absorbing elevated testing costs while OEM channels pass compliance expenses through contracted pricing.
Fleet operators are consolidating wiper procurement through integrated maintenance contracts rather than ad hoc replacement purchases. National logistics and rental car groups are negotiating multi-year blade supply agreements bundled with installation services. This bundling is most advanced in North American commercial vehicle segments where total cost of ownership metrics dominate supplier selection.
Wiper Blade Market Segmentation
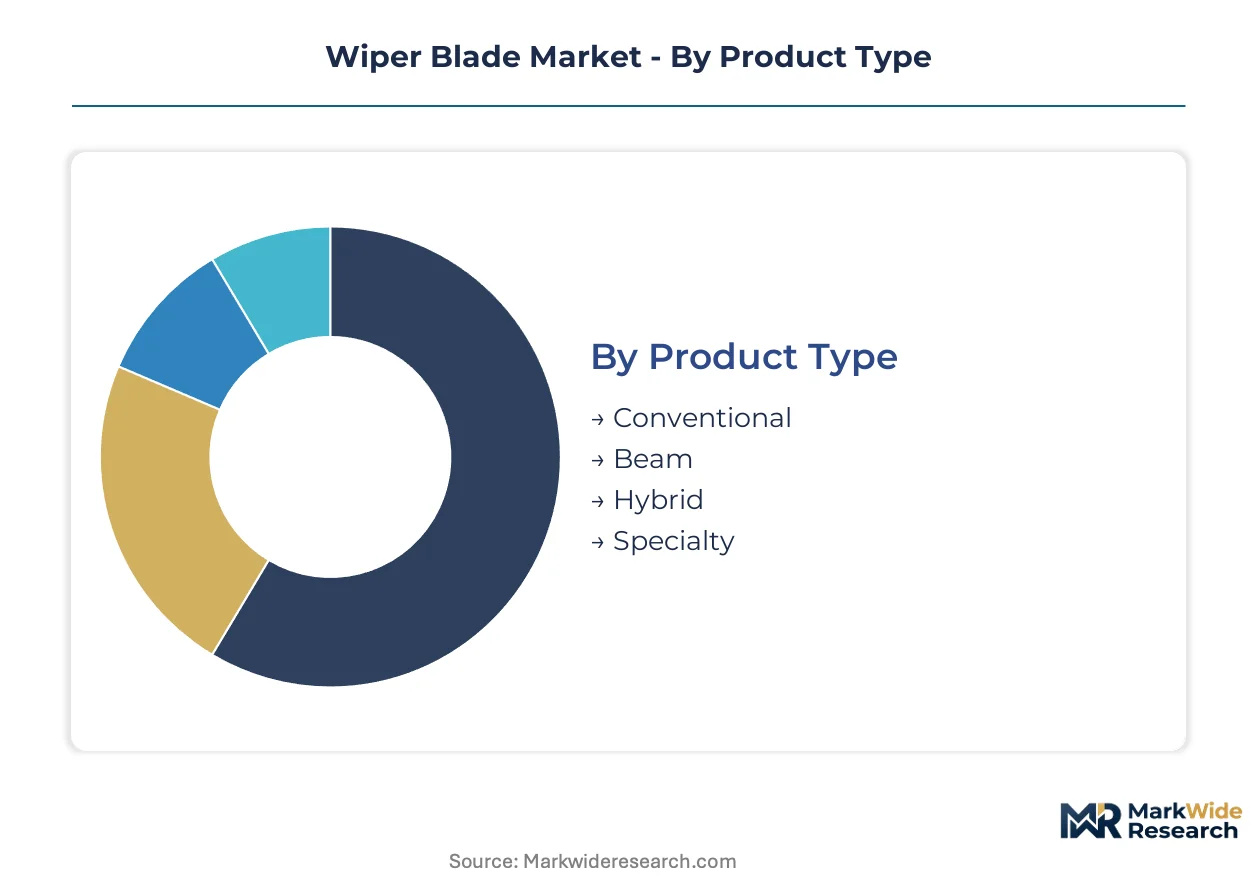
Wiper blade segmentation reveals how product architecture, vehicle application, material chemistry, and distribution channel interact to determine margin structure and replacement frequency. Channel dynamics vary sharply across these dimensions, with OEM direct-fit specifications tightening tolerances while aftermarket universal alternatives compete on price accessibility.
Product Type:
Channel mix diverges sharply across blade architectures, with beam designs concentrating in OEM and premium aftermarket tiers while conventional formats dominate price-driven replacement channels.
- Conventional:Bracket-style metal frames with multiple pressure points remain the volume workhorse in emerging markets and commercial vehicle fleets. Demand concentrates in India and Southeast Asia where cost sensitivity shapes replacement behavior and universal-fit adapters sustain low-price distribution through independent repair shops.
- Beam:Frameless tensioned designs using integrated steel springs deliver uniform pressure across curved windshields. European and North American passenger car OEMs specify these as standard equipment, with aerodynamic profiles reducing wind lift at highway speeds and extending service intervals that compress replacement revenue frequency.
- Hybrid:Enclosed frame designs merge conventional structural elements with aerodynamic covers, occupying a mid-market position in Asian aftermarket channels.
- Specialty:Rear-window and headlamp-specific configurations serve niche fitment requirements with limited SKU proliferation.
By volume, Conventional leads. By growth pace, Beam is ahead.
Vehicle Type:
Cost tier stratification separates premium blade specifications in passenger vehicles from durability-focused procurement in commercial applications.
- Passenger Cars:Sedans and hatchbacks generate the highest blade replacement frequency due to exposed parking conditions and consumer sensitivity to visibility degradation. Beam and hybrid formats capture increasing share as domestic Chinese brands upgrade component specifications.
- SUVs:Larger swept areas and more aggressive windshield curvatures demand precision-engineered tension profiles. North American and European SUV production volumes sustain premium pricing for direct-fit beam configurations.
- Trucks:Heavy-duty commercial applications prioritize durability over aerodynamics, with fleet operators negotiating multi-year maintenance contracts that bundle blade replacement with scheduled service intervals.
- Buses:Municipal and intercity coach operators specify extended-length blades with reinforced frames, procuring through integrated vehicle supply agreements rather than aftermarket channels.
Passenger Cars generate highest unit volume. SUVs show steepest expansion trajectory in premium segment penetration.
Material:
Margin structure varies across chemistry classes, with silicone compounds commanding premium positioning while natural rubber derivatives face feedstock volatility.
- Rubber:EPDM and chloroprene compounds retain cost advantages in high-volume production. REACH Annex XVII restrictions on phthalate plasticizers are forcing reformulation across European supply chains, elevating testing costs for compounders serving EU member states.
- Silicon:Hydrophobic silicone rubber formulations specified by luxury vehicle manufacturers deliver extended durability and water-repellent surface treatment. Japanese and German compounders dominate captive supply relationships in this chemistry class.
- Plastic:Thermoplastic elastomer edges serve economy-tier replacement markets with limited temperature range performance.
- Composite:Multi-layer constructions combining rubber wiping edges with graphite or PTFE coatings target high-performance aftermarket segments.
Rubber retains volume dominance. Silicon gains share fastest in premium OEM specifications.
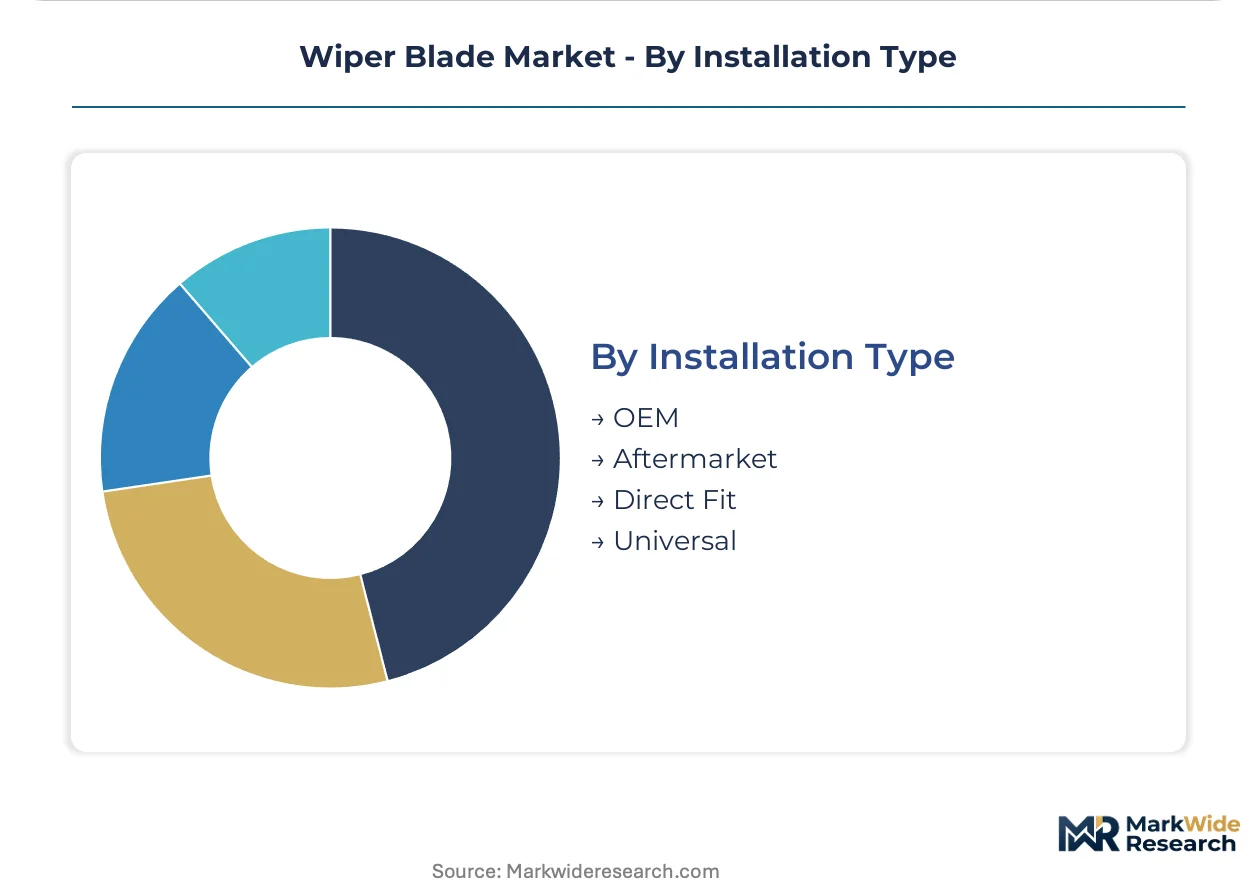
Installation Type:
Customer type separates locked-in OEM supply relationships from fragmented aftermarket procurement patterns.
- OEM:Vehicle manufacturers specify direct-fit blade systems through multi-year supply agreements with tier-one component suppliers. NHTSA Federal Motor Vehicle Safety Standard 104 validation requirements create extended approval timelines that entrench incumbent relationships.
- Aftermarket:Independent replacement channels generate recurring revenue independent of new vehicle sales cycles. National retailers and e-commerce platforms compete on price transparency and installation convenience.
- Direct Fit:Vehicle-specific adapters and pre-mounted connectors command premium pricing over universal alternatives, concentrating in European and North American markets where consumers prioritize ease of installation.
- Universal:Multi-adapter kits serve price-sensitive segments in emerging markets, though proliferating wiper arm geometries are compressing compatibility coverage and elevating return rates.
Aftermarket leads by unit volume. Direct Fit expands most quickly as OEM specification tolerances tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Chinese consumers upgrade aggressively to beam blade formats, while Indian buyers prioritize cost-minimizing conventional replacements. European and North American markets absorb premium pricing through regulatory-mandated performance tiers.
China
Domestic vehicle production scaling concentrates blade demand in Shanghai and Guangzhou manufacturing corridors. MIIT-administered GB standards for automotive electrical products specify corrosion resistance testing that elevates quality thresholds for local suppliers. Yangtze River Delta compounders are expanding silicone rubber capacity to serve premium domestic EV brands.
Germany
Precision engineering culture sustains premium beam blade specifications across Stuttgart and Munich OEM supply chains. KBA type-approval requirements enforce pedestrian safety integration that reduces hood protrusion hazards. Baden-Württemberg tooling specialists dominate precision extrusion equipment for frameless architectures.
United States
Fleet operator consolidation in logistics and ride-hail segments drives multi-year maintenance contract bundling. NHTSA Federal Motor Vehicle Safety Standard 104 mandates minimum swept areas that compress universal-fit alternatives. Michigan-based tier-one suppliers anchor OEM direct-fit relationships with domestic vehicle assemblers.
India
Organized retail and e-commerce channels remain underdeveloped for replacement blades, sustaining independent repair shop dominance. BIS automotive component standards are gradually tightening tolerance requirements for safety-critical visibility systems. Tamil Nadu and Maharashtra manufacturing clusters are attracting foreign compounders seeking cost-advantaged export bases.
Japan
Luxury vehicle manufacturers specify hydrophobic silicone formulations that extend service intervals and compress replacement frequency. METI industrial standards coordinate with JIS specifications for wiper system durability validation. Kanto region compounders maintain captive supply relationships with premium domestic OEMs.
Wiper Blade Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in wiper blade manufacturing. Captive polymer research capabilities separate compounders with margin control from assembly-only suppliers dependent on commodity feedstocks. Two strategic archetypes dominate: vertically integrated rubber compounders and windshield wiper motor system integrators. Competitive moves concentrate on backward integration into polymer formulation and geographic expansion through private-label distribution partnerships.
Within the integrated compounder tier, Denso and Valeo exemplify archetypes that anchor OEM supply relationships through captive material capabilities. Bosch occupies a position representing European research-intensive fabrication. Trico sits within the aftermarket-focused specialist category. These three names illustrate how competitive positioning fragments across channel concentration rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| Denso |
| CLWIPER |
| Bosch |
| Rain-X |
| Scan Top |
| Valeo |
| Federal Mogul |
| Lucas |
| Trico |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day compounder lead times for EPDM formulations tie pricing power to polymer inventory positioning and backward integration depth among European and Japanese suppliers. This inventory-to-pricing linkage concentrates margin control with compounders maintaining captive rubber research facilities while squeezing assembly-only distributors.
Pricing Analysis
Aftermarket replacement revenue drives lifetime value across wiper blade portfolios. Three-tier pricing structure across premium, standard, and economy levels separates silicone-specified luxury OEM fitments from EPDM aftermarket commodities. Price differentiation hinges on REACH compliance certification and aerodynamic beam architecture. Cost compression in conventional bracket segments is intensifying because Southeast Asian natural rubber feedstock volatility squeezes compounder margins. Fleet procurement managers show lowest price sensitivity due to bundled maintenance contracts, while independent repair shops in emerging markets prioritize universal-fit economy tiers.
Supply Chain Analysis
Just-in-time polymer delivery dominates European OEM channels, while strategic stockpiling of natural rubber feedstocks persists among Southeast Asian compounders hedging against plantation supply disruptions. Manufacturing concentrates in Germany, Japan, and China, with Baden-Württemberg tooling specialists and Yangtze River Delta compounders anchoring precision extrusion capacity. Raw material dependencies center on Hevea brasiliensis natural rubber, EPDM synthetic feedstocks, and steel spring components. Single-source vulnerability in precision co-injection molding equipment creates chokepoint exposure. Distribution runs through tier-one OEM supply agreements and national retail private-label partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet telematics integration is transforming wiper procurement from transactional replacement into subscription-enabled visibility platforms, creating interoperability lock-in between sensor hardware and fleet management software ecosystems.
For Market Incumbents: Shield OEM direct-fit relationships by deepening backward integration into silicone compound research and securing multi-year supply agreements with domestic Chinese EV manufacturers. Beam blade specification tightening by NHTSA and KBA regulators threatens universal-fit aftermarket alternatives. Priority levers include captive polymer formulation capacity and precision tooling ownership in Germany and Japan. For New Entrants and Emerging Players: Differentiate on sensor-enabled wear monitoring bundled with predictive maintenance software for commercial logistics fleets. India's underdeveloped organized retail and e-commerce replacement channels offer the most penetrable white space. A direct-to-fleet go-to-market angle bypasses entrenched distributor relationships dominating North American aftermarket shelf space. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue platform play because fleet telematics integration transforms blade replacement from sporadic purchase into data-subscription attachment. Acquisition targets should display captive silicone compounding capabilities and established OEM validation relationships. Watch for inflection when sensor-enabled blade attach rates in commercial vehicle segments cross twenty percent penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Compound Capacity Expansion | Yangtze River Delta investments serve premium domestic Chinese EV brand specifications. |
| Fleet Telematics Integration | Sensor-enabled wear reporting creates recurring revenue attachment in logistics segments. |
| REACH Compliance Reformulation | Alternative flex agent validation elevates R&D barriers for European aftermarket suppliers. |
| Precision Tooling Acquisition | Co-injection molding equipment ownership secures beam blade manufacturing chokepoints. |
| India Distribution Network Buildout | Organized retail partnerships capture first-mover advantage in underpenetrated replacement channels. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with tier-one supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet maintenance managers; and secondary validation against vehicle production databases, customs trade records for rubber compound flows, NHTSA FMVSS 104 filings, and REACH Annex XVII regulatory updates. Bottom-up demand modeling triangulated against top-down market sizing across the projection horizon.
Across the modeling period, the analytical framework segmented volume and value outputs by product architecture, vehicle class, material chemistry, and installation channel. CAGRs were derived from replacement cycle elasticity modeling and OEM specification trend analysis. Forecast inputs incorporated beam blade adoption curves in Chinese domestic production and fleet telematics penetration rates in North American commercial segments.
Material uncertainties — natural rubber plantation supply disruptions, REACH plasticizer restriction enforcement, and NHTSA type-approval timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions about sustained OEM specification tightening and aftermarket channel consolidation. Revision becomes warranted when silicone rubber cost parity against EPDM compounds crosses threshold viability in economy-tier segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
UK Automotive Actuators Market
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
Brazil Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive AHSS Market
Automotive Parts
Automotive Electric Drivetrain Components Market
Automotive Parts
Argentina Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Rammer Market
Automotive Parts
Auxiliary Oil Cooler Market
Automotive Parts
Cycloid Gear Market
Automotive Parts
Automotive Suspension Control Arms Market
Automotive Parts
Transfer Case Market
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
Automotive Steel Market
Automotive Parts
Automotive All Wheel Drive Market
Automotive Parts
United States Automotive Parts Die Casting Market