
 Mexico Autonomous Navigation Market | 2026-2036
Mexico Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Autonomous Navigation Market Insights
Northern Mexico is rewriting autonomous logistics deployment across the Monterrey-Saltillo manufacturing belt. Aurora Innovation anchors long-haul freight automation through partnerships with Mexican carriers moving goods across Nuevo Laredo and Laredo. Kodiak Robotics competes on highway corridor mapping, sustaining its position through proprietary perception stacks trained on Mexican road conditions. Volvo Autonomous Solutions dominates mining site automation, leveraging its existing construction equipment relationships in Zacatecas and Sonora.
Autonomous navigation encompasses self-guiding platforms that fuse Lidar point clouds, GPS-RTK positioning, and neural network-based path planning to execute movement without human intervention, typically achieving lane-keeping accuracy within 10 centimeters and obstacle detection ranges exceeding 200 meters. The technology serves industrial and commercial operators seeking to eliminate driver fatigue, reduce collision rates, and enable 24-hour continuous operations in hazardous or remote environments. Lidar-based systems lead product type adoption in Mexican mining and port applications where dust and darkness degrade camera performance. AI Algorithms represent the fastest-growing technology segment as local engineering centers in Guadalajara develop Spanish-language scene understanding and informal road behavior prediction. Defense end users concentrate margin pools around encrypted communications and jam-resistant GPS, with L3Harris Technologies and Northrop Grumman competing for military contracts.
Mexico's Ministry of Economy oversees NOM-194 vehicle automation standards, while the Federal Telecommunications Institute regulates spectrum allocation for V2X communications, and SCT infrastructure guidelines shape highway sensor deployment requirements. These frameworks create compliance costs for foreign suppliers but open procurement pathways for domestic system integrators meeting local certification. Stakeholders must monitor whether upcoming NOM revisions mandate fail-operational architectures or permit conditional driverless operation on designated freight corridors.
Market Dynamics
Mexico's NOM-194 vehicle automation standards are forcing foreign suppliers to recertify sensor fusion systems through domestic laboratories, compressing deployment timelines for mining and logistics operators while opening procurement pathways for local integrators.
Growth Catalysts
- Freight corridor designation:SCT infrastructure guidelines for designated autonomous freight lanes along the Monterrey-Nuevo Laredo corridor enable 24-hour continuous haulage operations without cross-border driver handoffs.
- Mining automation mandates:Labor safety regulations in Sonora and Chihuahua now incentivize pit vehicle automation to reduce underground exposure incidents and shift-based fatigue errors.
- Guadalajara engineering clusters:Spanish-language neural network development centers are accelerating AI algorithm localization for informal road behavior prediction in rural Mexican driving conditions.
Market Restraints
- Lidar import cost structure:High duties on solid-state Lidar arrays from Asian suppliers inflate upfront system costs for mid-tier mining operators in Zacatecas.
- Spectrum allocation uncertainty:IFT deliberations over C-V2X band licensing create deployment hesitation for port operators requiring guaranteed low-latency vehicle-to-infrastructure links.
- GPS-RTK coverage gaps:Sparse base station networks in Baja California and southern Chiapas limit centimeter-level positioning accuracy for precision agriculture applications.
Strategic Opportunities
- Underpenetrated port automation:Lázaro Cárdenas and Manzanillo container terminals lack autonomous yard tractor deployments, presenting first-mover openings for integrated navigation stack vendors.
- Defense encryption standards:Secretariat of National Defense requirements for jam-resistant GPS and encrypted V2X communications create premium-margin procurement pools separate from commercial markets.
- AgTech convergence:Fusion of autonomous navigation with precision irrigation systems in Sinaloa and Jalisco farming cooperatives opens equipment bundling opportunities.
Industry Challenges
- Certification timeline compression:NOM-194 recertification cycles for updated sensor firmware extend product launch windows by eight to fourteen months, straining R&D amortization schedules.
- Legacy fleet integration:Retrofit compatibility with existing Caterpillar and Komatsu mining haulers requires custom mechanical interface engineering for each pit site.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Autonomous Navigation Market |
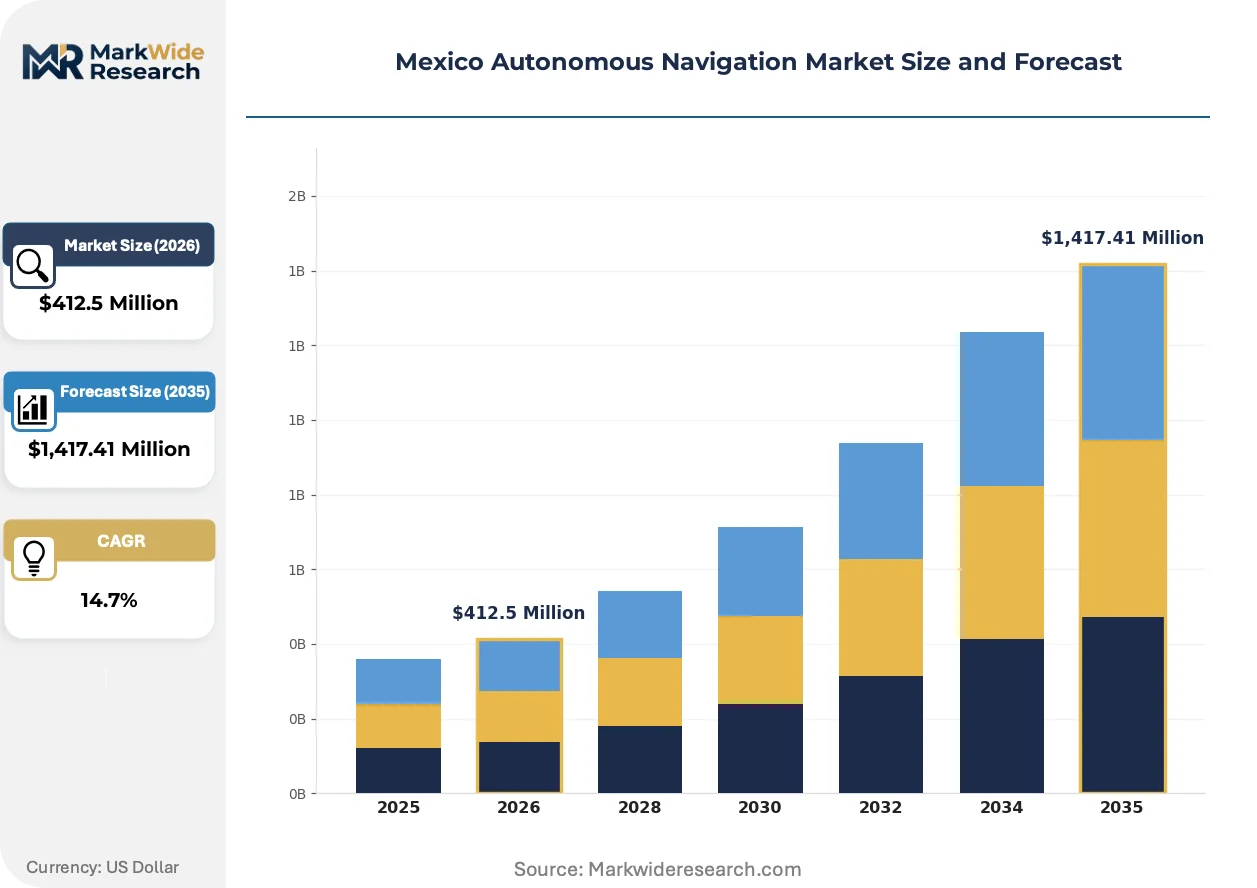
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,417.41 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Driving Cars, Drones, Autonomous Boats, Delivery Robots Technology: Lidar, Computer Vision, GPS, AI Algorithms End User: Logistics Providers, Public Transport, Defense, Agriculture Application: Goods Delivery, Surveillance, Passenger Transport, Agricultural Monitoring |
| Companies Covered | Aurora Innovation, Kodiak Robotics, Volvo Autonomous Solutions, Waymo Via, ABB, Trimble Inc., L3Harris Technologies Inc., Northrop Grumman Corporation, Collins Aerospace, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Autonomous Navigation Market Trends and Innovations
Neural network architectures trained on Mexican road conditions are displacing imported perception models, while regulatory pressure on fail-operational systems accelerates hardware redundancy investments across the supplier base.
Solid-state Lidar arrays with MEMS beam steering are rendering obsolete mechanical spinning units in dust-heavy mining environments. Pit operators in Sonora are adopting these sealed systems within eighteen-month replacement cycles. The shift is compressing maintenance intervals from quarterly to annual while eliminating gimbal failure modes that previously dominated downtime statistics.
NOM-194 revisions under Ministry of Economy review are mandating redundant braking architectures for conditional driverless operation. Equipment suppliers must now certify dual-channel fail-operational systems through domestic testing facilities. Mining OEMs are responding by pre-integrating backup hydraulic circuits before formal rule publication.
Asset-light contracting models are displacing capital purchase structures for mid-tier logistics fleets. Third-party autonomous trucking providers near the Saltillo manufacturing belt now offer per-kilometer navigation services with embedded insurance and maintenance. This reconfiguration concentrates procurement authority with fleet managers rather than CFOs, shortening sales cycles and intensifying vendor performance scrutiny.
Mexico Autonomous Navigation Market Segmentation
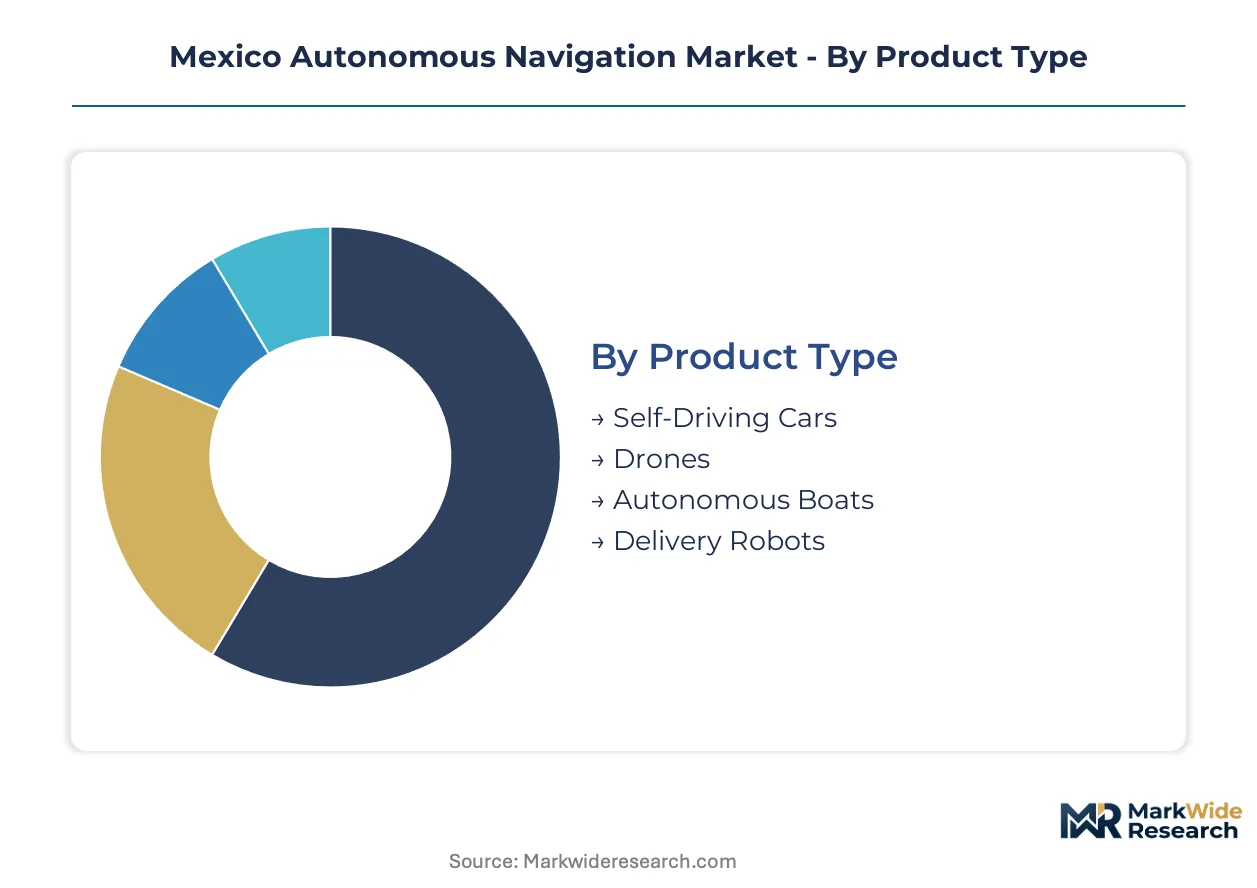
Mexico's autonomous navigation market fragments across distinct hardware platforms, sensor modalities, operational domains, and mission profiles. Each segment carries unique certification burdens under NOM-194 and faces divergent infrastructure readiness across Sonora mining pits, Monterrey freight corridors, and Jalisco agricultural zones.
Product Type:
Use-case spectrum spans closed industrial environments through open-road public deployment, with hardware form factors dictating regulatory pathway complexity and operational envelope constraints.
- Self-Driving Cars:Heavy-duty freight tractors and passenger shuttles integrate Lidar-GPS-IMU fusion stacks for highway lane-keeping within 10-centimeter accuracy. Demand clusters along the Monterrey-Nuevo Laredo manufacturing belt where carriers seek 24-hour cross-border haulage without driver handoff delays.
- Drones:Multirotor and fixed-wing unmanned aerial vehicles carry hyperspectral cameras and RTK-GNSS modules for precision agriculture and infrastructure inspection. Regulatory fragmentation between IFT spectrum allocation and SCT airspace coordination limits beyond-visual-line-of-sight operations in Baja California and Chiapas coverage gaps.
- Autonomous Boats:Surface and subsurface maritime platforms deploy sonar-Lidar fusion for port security and offshore pipeline monitoring. Manzanillo and Lázaro Cárdenas terminals present first-mover deployment opportunities for yard craft automation.
- Delivery Robots:Sidewalk-class last-mile carriers with sealed drivetrains and curb-climbing suspensions navigate Guadalajara's informal street geometries. Spanish-language neural network localization from local engineering centers accelerates scene understanding development.
Established volume favors Self-Driving Cars; emerging adoption favors Delivery Robots.
Technology:
Cost tier stratification separates capital-intensive sensor hardware from software-intensive perception layers, with import duties and domestic engineering capacity reshaping supplier economics.
- Lidar:Solid-state MEMS beam-steering arrays with sealed enclosures withstand Sonora mining dust while eliminating mechanical gimbal failure modes. Asian import duties inflate upfront costs for Zacatecas mid-tier operators.
- Computer Vision:Camera-based perception stacks with neural network object detection suffer performance degradation in low-light pit conditions and coastal fog. Guadalajara development centers train Spanish-language models on informal road behaviors.
- GPS:RTK-corrected positioning requires dense base station networks absent across southern Chiapas and Baja California peninsula. Sparse coverage limits centimeter-accurate agriculture guidance in Sinaloa cooperative territories.
- AI Algorithms:Path planning and predictive behavior models trained on Mexican driving datasets enable collision avoidance in unmarked rural corridors. This segment climbs the fastest as local engineering talent concentrates in Jalisco technology parks.
Hardware procurement concentrates in Lidar; capability differentiation concentrates in AI Algorithms.
End User:
Customer type determines procurement authority structure, with defense buyers demanding encrypted communications while commercial operators prioritize uptime guarantees and insurance bundling.
- Logistics Providers:Asset-light per-kilometer contracting models near Saltillo concentrate procurement with fleet managers rather than CFOs, shortening sales cycles and intensifying vendor performance scrutiny.
- Public Transport:Municipal and intercity shuttle operators face NOM-194 certification delays for passenger-carrying autonomous platforms. Domestic testing facility bottlenecks extend launch timelines.
- Defense:Secretariat of National Defense mandates jam-resistant GPS and encrypted V2X communications, creating premium-margin procurement pools separate from commercial markets with specialized supplier qualification.
- Agriculture:Sinaloa and Jalisco farming cooperatives bundle autonomous navigation with precision irrigation systems, requiring equipment vendors to integrate across disparate machinery OEM protocols.
Commercial scale favors Logistics Providers; margin concentration favors Defense.
Application:
Mission profile dictates sensor payload configuration and operational tempo, with surveillance applications demanding persistent endurance while passenger transport prioritizes fail-operational redundancy.
- Goods Delivery:Cross-border freight automation between Nuevo Laredo and Laredo eliminates customs-delayed driver handoffs. Aurora Innovation anchors this corridor through Mexican carrier partnerships.
- Surveillance:Persistent perimeter monitoring and infrastructure inspection missions require encrypted datalinks and all-weather sensor suites. Defense and energy sector buyers dominate this segment.
- Passenger Transport:NOM-194 revisions mandate redundant braking architectures for conditional driverless operation, forcing pre-integration of backup hydraulic circuits before formal rule publication.
- Agricultural Monitoring:Hyperspectral crop health mapping fused with autonomous tractor guidance enables variable-rate input application. GPS-RTK coverage gaps in southern growing regions constrain deployment.
Freight economics favor Goods Delivery; regulatory complexity favors Passenger Transport.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment suppliers cluster along Mexico's northern manufacturing belt where cross-border freight automation intersects with mining automation mandates. Nuevo León and Sonora anchor deployment volumes, while Jalisco engineering centers localize AI perception systems.
Nuevo León
Monterrey's industrial corridor concentrates autonomous trucking demand from OEMs and logistics hubs near the U.S. border. SCT infrastructure guidelines for designated freight lanes enable continuous haulage operations without cross-border driver handoffs. Aurora Innovation anchors long-haul partnerships with Mexican carriers moving goods across Nuevo Laredo and Laredo.
Sonora
Mining operators in Cananea and Nacozari expand fleet automation to cut labor costs and improve pit safety. Labor safety regulations incentivize pit vehicle automation to reduce underground exposure incidents. Solid-state Lidar arrays with sealed enclosures withstand dust-heavy environments while eliminating mechanical gimbal failure modes.
Chihuahua
Underground mining automation concentrates around Ciudad Juárez supply chains serving U.S. automotive manufacturers. NOM-194 vehicle automation standards pressure suppliers to certify localization and sensor fusion systems through domestic laboratories. Shift-based fatigue errors drive demand for 24-hour continuous autonomous haulage.
Jalisco
Guadalajara engineering clusters accelerate Spanish-language neural network development for informal road behavior prediction. Local technology parks train AI algorithms on Mexican driving datasets for collision avoidance in unmarked rural corridors. Delivery robot deployment navigates informal street geometries with curb-climbing suspensions.
Baja California
Precision agriculture applications face GPS-RTK coverage gaps limiting centimeter-level positioning accuracy. Sparse base station networks constrain autonomous tractor guidance in southern growing regions. Port automation opportunities emerge at Ensenada maritime terminals for yard craft deployment.
Mexico Autonomous Navigation Market Competitive Landscape
Long-haul freight specialists and mining automation incumbents split the market between cross-border logistics corridors and closed industrial environments. Consolidation pressure favors players with pre-certified NOM-194 sensor fusion systems and existing equipment relationships in Sonora and Zacatecas. Three archetypes dominate: U.S.-based autonomous trucking platforms, European mining OEMs with construction equipment heritage, and defense contractors serving encrypted communications mandates. Competitive moves center on domestic laboratory partnerships for accelerated certification and per-kilometer service contracting to displace capital purchase structures.
Among U.S.-based autonomous trucking platforms, Aurora Innovation and Kodiak Robotics occupy positions exemplifying the freight corridor automation archetype. Volvo Autonomous Solutions represents the mining equipment incumbent archetype through its construction equipment relationships. Within the defense tier, L3Harris Technologies and Northrop Grumman anchor premium-margin procurement pools separate from commercial markets.
| Leading Market Players |
|---|
| Aurora Innovation |
| Kodiak Robotics |
| Volvo Autonomous Solutions |
| Waymo Via |
| ABB |
| Trimble Inc. |
| L3Harris Technologies Inc. |
| Northrop Grumman Corporation |
| Collins Aerospace |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Asian solid-state Lidar manufacturing is compressing module costs for Sonora mining operators while simultaneously pressuring Tier 2 domestic integrators to absorb certification margin erosion under NOM-194 recertification cycles.
Pricing Analysis
NOM-194 dictates the pricing tier structure across Mexico's autonomous navigation market. Three-tier pricing structure across premium, standard, and economy levels separates fail-operational redundant systems from single-channel architectures and retrofit-only sensor kits. Price differentiation hinges on domestic laboratory certification completion and embedded insurance bundling. Cost compression in economy-tier retrofit packages is intensifying because mid-tier Zacatecas operators delay replacement cycles. Logistics providers running per-kilometer contracts show least price sensitivity; small agricultural cooperatives in Chiapas exhibit highest.
Supply Chain Analysis
Export controls on MEMS beam-steering components and RTK-GNSS correction modules limit flows from U.S. and European suppliers to Mexican system integrators. Component sourcing draws from China, South Korea, and Taiwan for solid-state Lidar arrays; Germany and Japan for precision IMU units; and domestic Guadalajara facilities for Spanish-language AI training datasets. Single-source vulnerability concentrates in Asian Lidar substrate supply. Distribution runs through Monterrey industrial corridor distributors serving mining OEMs and Saltillo logistics fleet managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's autonomous navigation market represents a high-growth disruption as NOM-194 fail-operational mandates force hardware redundancy investments across the supplier base.
For Market Incumbents: Harden NOM-194 certification pipelines by pre-integrating backup hydraulic circuits before formal rule publication. Deepen backward integration into Guadalajara AI development centers to capture Spanish-language neural network localization. Aurora Innovation and Volvo Autonomous Solutions face emerging pressure from asset-light per-kilometer service providers consolidating procurement authority with fleet managers.
For New Entrants and Emerging Players: Lázaro Cárdenas and Manzanillo container terminals represent the most penetrable entry point for integrated navigation stack vendors given absent autonomous yard tractor deployments. Jalisco delivery robot corridors with informal street geometries offer second white-space target. Lead with curb-climbing hardware demonstrations to bypass established mining equipment relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light autonomous trucking services as per-kilometer contracting displaces capital purchase structures. Long-term viability favors domestic system integrators with pre-certified NOM-194 sensor fusion systems and established laboratory partnerships. Watch IFT C-V2X spectrum allocation decisions as inflection indicator for port automation deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| NOM-194 Certification Pre-Integration | Domestic laboratory partnerships compress eight-to-fourteen month recertification cycles for mining OEMs. |
| Per-Kilometer Service Contracting | Asset-light models concentrate procurement authority with fleet managers near Saltillo manufacturing belt. |
| Guadalajara AI Localization Investment | Spanish-language neural network development accelerates informal road behavior prediction capability. |
| Solid-State Lidar Sealed Enclosure Adoption | MEMS beam-steering eliminates gimbal failure modes in Sonora dust-heavy pit environments. |
| Defense Encryption Capability Buildout | Jam-resistant GPS and encrypted V2X communications access premium-margin Secretariat procurement pools. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Interviews incorporated autonomous system engineering directors at mining OEMs, fleet procurement managers at Monterrey logistics operators, NOM-194 certification leads at domestic testing laboratories, and SCT infrastructure planning officers. Secondary sources included Ministry of Economy regulatory filings, IFT spectrum allocation proceedings, SEC disclosures from listed autonomous vehicle technology providers, and customs import records for Lidar and GPS-RTK components. Bottom-up equipment deployment estimates triangulated against top-down market sizing from OEM shipment data.
Forecast inputs considered product type segmentation across self-driving cars, drones, autonomous boats, and delivery robots; technology layers spanning Lidar, computer vision, GPS, and AI algorithms; and end-user categories including logistics providers, public transport operators, defense procurement, and agricultural cooperatives. CAGRs were derived from equipment replacement cycle analysis and regulatory mandate implementation timelines. Modeling incorporated NOM-194 revision schedules, IFT deliberation timelines, and GPS-RTK base station expansion plans as industry-specific trajectory variables across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in peso-dollar exchange rates, mining commodity prices, and cross-border freight volumes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation pace and infrastructure deployment schedules. Material shifts in NOM-194 fail-operational architecture mandates or IFT C-V2X licensing decisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Parking System Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
Autopilot Systems Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Driverless Taxi Market
Autonomous Vehicles
Global Connected, Autonomous, Shared, and Electric (CASE) Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Africa Autonomous Navigation Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
Automotive AI Market
Autonomous Vehicles
Middle East and Africa ADAS Market