
 Electric Off-Road Vehicles Market | 2026-2036
Electric Off-Road Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Off-Road Vehicles Market Intelligence
Multi-source battery procurement is broadening as manufacturers hedge against raw material volatility. Polaris Inc. anchors North American production with vertically integrated powertrain assembly in Minnesota. Yamaha Motor Co., Ltd. competes through dedicated R&D centers in Japan focused on solid-state battery integration for extreme terrain. Zero Motorcycles specializes in high-torque electric drivetrains that dominate competitive motocross segments.
Electric off-road vehicles are self-propelled, zero-emission machines engineered with sealed battery enclosures, regenerative braking systems, and torque-vectoring electric motors designed to traverse unpaved surfaces without atmospheric emissions. These vehicles serve commercial, recreational, and institutional users requiring low-noise, low-heat operation in environmentally sensitive or enclosed workspaces. Battery electric propulsion leads volume shipments due to mature cell chemistry supply chains and falling pack costs, while fuel cell electric architectures occupy niche military and expedition roles where refueling speed outweighs infrastructure density. UTVs capture the deepest margin pools through fleet sales to mining and agricultural operators, whereas dirt bikes sustain the fastest growth trajectory among adventure enthusiasts seeking track-day alternatives to two-stroke engines.
EPA tailpipe regulations and NHTSA rollover standards in the United States compel frame redesigns and battery crash-protection testing that add certification costs but lock out informal importers. The EU Green Deal and REACH chemical directives in Europe restrict certain electrolyte additives and mandate end-of-life battery recycling, reshaping material sourcing for exporters. Stakeholders must monitor how evolving federal land-use policies across multiple geographies determine where electric off-road vehicles gain fleet-access permits versus combustion-era restrictions.
Market Dynamics
Battery chemistry supply chain consolidation is concentrating cell procurement leverage among a handful of Asian suppliers, forcing Western OEMs to secure long-term offtake agreements or risk production delays.
Growth Catalysts
- EPA tailpipe regulations:The United States Environmental Protection Agency's tightening emissions standards for non-road engines are accelerating fleet electrification timelines among commercial operators.
- Underground mining ventilation:Australian mining operators are eliminating diesel particulate exposure costs by converting UTV fleets to battery-electric architectures, reducing tunnel ventilation infrastructure requirements.
- Lithium iron phosphate chemistry:Improved thermal stability and cycle life in LFP cells are extending vehicle duty cycles in extreme temperature environments previously hostile to nickel-cobalt formulations.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings between 2022-2024 have compressed pack gross margins and complicated OEM pricing strategies.
- Charging infrastructure deserts:Remote recreation areas across the western United States lack grid connectivity, constraining electric ATV deployment for trail riding enthusiasts.
- NHTSA rollover certification:Battery crash-protection testing protocols for side-by-side vehicles extend development timelines by 8-14 months versus combustion equivalents.
Strategic Opportunities
- Federal land electrification mandates:United States Forest Service and Bureau of Land Management procurement directives favor zero-emission ranger patrol vehicles across California, Colorado, and Utah.
- Solid-state battery convergence:Integration of ceramic electrolyte architectures with existing chassis platforms promises energy density improvements without thermal runaway redesigns.
- Rental fleet channel expansion:Adventure tourism operators in Moab and Sedona are adding electric UTVs to guided excursion packages, creating new B2B demand pools.
Industry Challenges
- Power electronics talent scarcity:OEMs face acute shortages of motor control firmware engineers capable of optimizing torque-vectoring algorithms for variable terrain.
- Legacy dealer service infrastructure:Rural dealership networks lack high-voltage technician certification and specialized diagnostic equipment for battery pack maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Off-Road Vehicles Market |
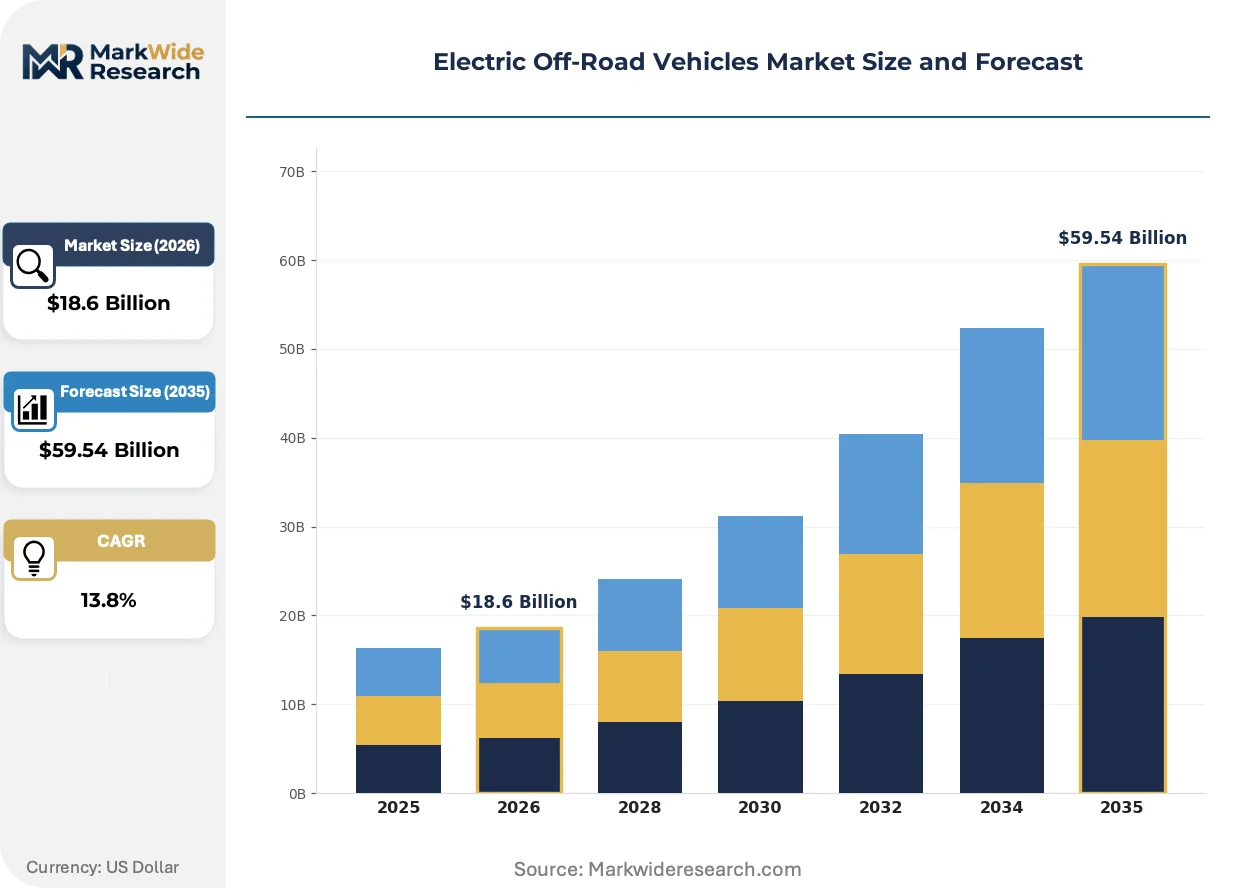
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $59.54 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ATVs, UTVs, Dirt Bikes, Dune Buggies, Snowmobiles Propulsion: Battery Electric, Hybrid Electric, Fuel Cell Electric, Solar Electric End User: Adventure Enthusiasts, Farming Operators, Construction Firms, Military Units, Wilderness Rangers Distribution Channel: Specialty Dealers, Online Platforms, Rental Services, Event Organizers, Direct Sales |
| Companies Covered | Polaris Inc., Yamaha Motor Co., Ltd., Honda Motor Co., Ltd., BRP Inc., Arctic Cat Inc., Textron Specialized Vehicles, John Deere, Can-Am, Zero Motorcycles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Off-Road Vehicles Market Strategic Shifts & Innovations
Solid-state battery research is accelerating commercialization timelines, while regulatory pressure on combustion engines intensifies across multiple jurisdictions. These forces are compressing product development cycles and reshaping competitive positioning.
Solid-state ceramic electrolyte architectures are expanding into off-road vehicle prototypes, replacing flammable liquid electrolytes with fire-resistant solid materials. Mining fleet operators in Australia and Canada are piloting pre-commercial units for 24-hour continuous duty cycles. This technology is expanding into segments previously blocked by thermal management constraints, enabling deeper penetration of enclosed underground workspaces.
The EU Green Deal's battery passport requirements and end-of-life recycling mandates are forcing redesigns of cell module accessibility and material traceability systems. European exporters must now document cobalt sourcing and establish reverse logistics networks for pack collection. This regulatory pressure is concentrating most acutely on mid-volume manufacturers serving EU agricultural and forestry segments.
Direct-to-consumer online configuration tools are displacing traditional dealer lot inventory models for recreational electric dirt bikes. Younger riders in the United States and Germany are specifying custom suspension tunes and battery capacities through manufacturer portals, bypassing retail intermediaries. This channel shift is most visible in competitive motocross-adjacent segments where technical specifications drive purchase decisions over physical test rides.
Electric Off-Road Vehicles Market Segmentation
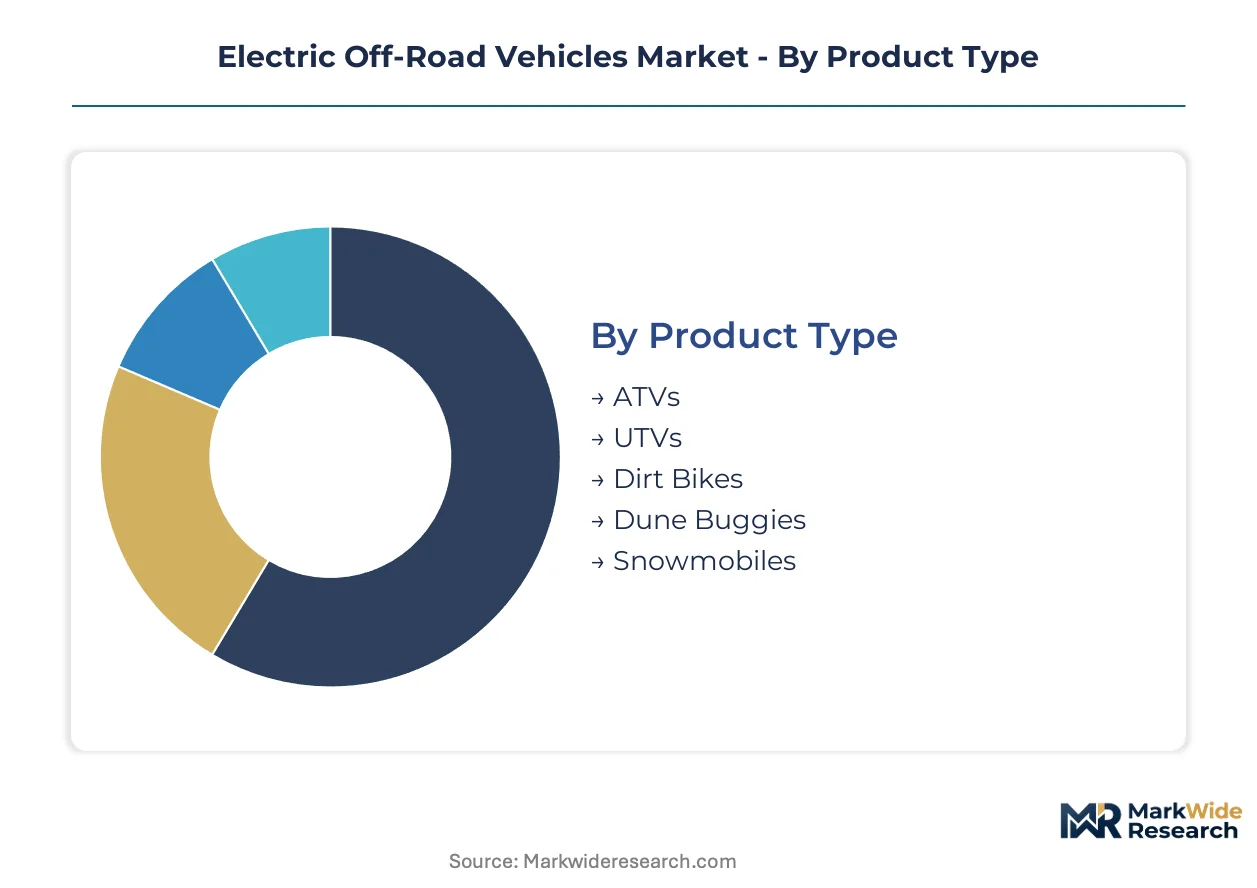
Segmentation in electric off-road vehicles reveals distinct engineering requirements and purchasing behaviors across user archetypes. Product architecture, powertrain selection, and channel strategy diverge sharply between commercial fleet operators and recreational buyers.
Product Type:
Standardization dominates utility segments while adventure categories demand extensive customization for terrain and rider preference.
- ATVs:Compact four-wheeled platforms with independent suspension and sealed battery enclosures rated for water fording. Demand clusters with farming operators in the United States Midwest seeking zero-emission alternatives for livestock management and property maintenance where noise restrictions apply.
- UTVs:Side-by-side configurations with cargo beds and two-to-six passenger capacity, engineered for continuous duty cycles in mining and agricultural fleets. Underground operators in Australia specify these for diesel particulate elimination and reduced ventilation infrastructure costs.
- Dirt Bikes:Lightweight motocross and enduro frames with high-torque electric drivetrains and swappable battery packs.
- Dune Buggies:Open-cockpit recreational vehicles with long-travel suspension for sand terrain.
- Snowmobiles:Track-driven platforms with thermal management systems for sub-zero battery operation.
Leading the category by volume: UTVs. Expanding most quickly: Dirt Bikes.
Propulsion:
Application urgency and refueling infrastructure availability determine powertrain selection across end-use scenarios.
- Battery Electric:Lithium-ion cell architectures with regenerative braking and onboard charging systems. Mature supply chains and falling pack costs drive volume leadership across recreational and commercial segments in the United States and Europe.
- Fuel Cell Electric:Hydrogen proton-exchange membrane systems with rapid refueling capability. Military expedition units and remote mining operations in Canada prioritize these where grid connectivity is absent and downtime carries operational penalties.
- Hybrid Electric:Range-extender configurations combining battery packs with small combustion generators.
- Solar Electric:Photovoltaic panel integration with auxiliary charging for extended wilderness operation.
Dominant by deployment scale: Battery Electric. Gaining share fastest: Fuel Cell Electric.
End User:
Purchasing authority and total cost of ownership calculations separate institutional procurement from individual acquisition patterns.
- Adventure Enthusiasts:Individual riders and weekend recreationists prioritizing torque delivery and maintenance reduction over upfront cost. Track-day participants in Germany and the United States drive specification demands for competitive motocross-adjacent segments.
- Farming Operators:Agricultural enterprises with fleet standardization requirements and seasonal utilization patterns. These buyers emphasize dealer service networks and parts availability across rural distribution territories.
- Construction Firms:Site contractors requiring emission-compliant equipment for urban projects and enclosed workspaces.
- Military Units:Defense procurement agencies with acoustic signature requirements and expeditionary logistics constraints.
- Wilderness Rangers:Federal and state land management agencies with sustainability mandates and patrol coverage obligations.
Highest volume concentration: Farming Operators. Steepest expansion trajectory: Wilderness Rangers.
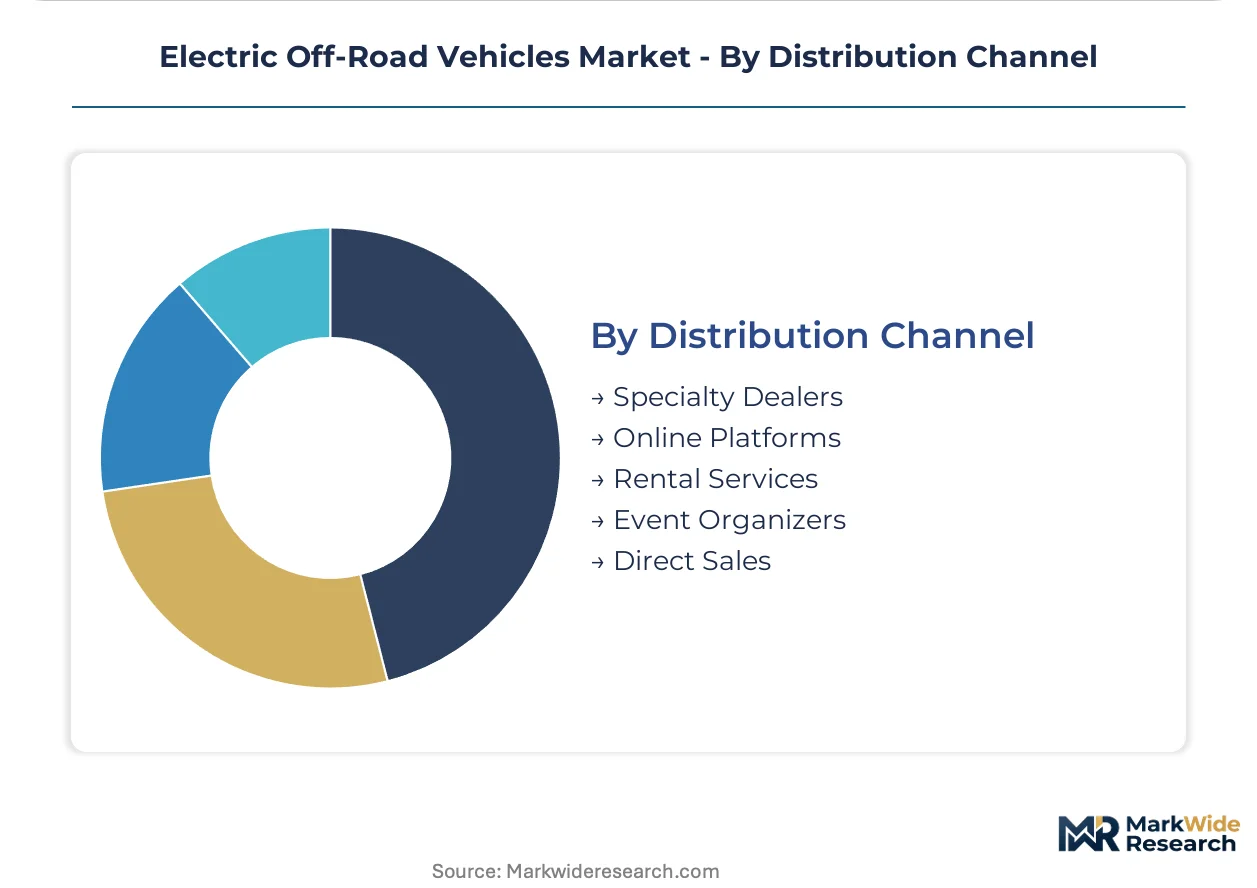
Distribution Channel:
Technical complexity and purchase frequency shape channel profitability and manufacturer investment priorities.
- Specialty Dealers:Authorized retail networks with certified technicians and physical inventory for test rides and immediate delivery. These outlets capture the majority of UTV and ATV transactions where service relationships influence repeat purchases.
- Online Platforms:Direct-to-consumer configuration portals with factory fulfillment and home delivery. Younger dirt bike buyers in the United States and Germany increasingly specify custom suspension tunes and battery capacities through manufacturer websites.
- Rental Services:Adventure tourism operators and fleet lessors providing hourly or daily access.
- Event Organizers:Competition promoters and experience providers with temporary vehicle deployment.
- Direct Sales:Manufacturer-owned channels for institutional and government procurement.
Channel leader by transaction volume: Specialty Dealers. Climbing the fastest: Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate refining capacity in Chile underpins South American feedstock security for battery cell production serving off-road vehicle OEMs.
United States
Federal land management agencies in California, Colorado, and Utah are electrifying ranger patrol fleets. EPA tailpipe regulations and NHTSA rollover standards compel frame redesigns and battery crash-protection testing. Polaris anchors North American production with vertically integrated powertrain assembly in Minnesota.
Australia
Underground mining operators are eliminating diesel particulate exposure costs by converting UTV fleets to battery-electric architectures. The country's national mining safety regulator mandates reduced ventilation infrastructure in enclosed tunnels. Western Australia hosts pilot programs for solid-state battery prototypes in 24-hour continuous duty cycles.
Germany
Adventure enthusiasts and track-day participants drive specification demands for competitive motocross-adjacent segments. The EU Green Deal and REACH chemical directives restrict certain electrolyte additives and mandate end-of-life battery recycling. Bavaria-based rental fleet operators are adding electric UTVs to guided excursion packages.
Canada
Remote mining operations prioritize fuel cell electric architectures where grid connectivity is absent and downtime carries operational penalties. Environment and Climate Change Canada enforces emission standards for non-road engines. Ontario hosts military expedition units testing rapid refueling hydrogen systems.
Japan
Yamaha Motor Co., Ltd. competes through dedicated R&D centers focused on solid-state battery integration for extreme terrain. METI promotes battery supply chain resilience and domestic cell production capacity. Nagoya-area engineering clusters concentrate motor control firmware development for torque-vectoring algorithms.
Electric Off-Road Vehicles Market Key Industry Players
Strategic partnerships dominate the current landscape as OEMs secure battery offtake agreements and charging infrastructure alliances. The vendor base concentrates among diversified powersports conglomerates, specialized electric drivetrain engineers, and agricultural equipment manufacturers extending into off-road segments. Three archetypes define positioning: vertically integrated North American producers, Japanese R&D-led technology specialists, and pure-play electric motorcycle innovators. M&A activity and geographic expansion into federal procurement channels represent the dominant competitive moves.
Among North American powersports manufacturers, Polaris Inc. and BRP Inc. occupy positions as diversified conglomerates with established dealer networks. Arctic Cat Inc. represents the tier of regional specialists seeking technology partnerships to bridge combustion heritage with electric architectures. Zero Motorcycles exemplifies the pure-play electric specialist archetype, anchoring the high-torque drivetrain segment without legacy manufacturing constraints.
| Leading Market Players |
|---|
| Polaris Inc. |
| Yamaha Motor Co., Ltd. |
| Honda Motor Co., Ltd. |
| BRP Inc. |
| Arctic Cat Inc. |
| Textron Specialized Vehicles |
| John Deere |
| Can-Am |
| Zero Motorcycles |
| Others |
Cost & Logistics Intelligence
Backward integration into powertrain assembly anchors both supply security and pricing power for North American manufacturers, while Asian cell suppliers concentrate procurement leverage through long-term offtake agreements that lock in volume discounts for mining fleet operators.
Pricing Analysis
Warranty and service bundling separates premium UTV configurations from unbundled dirt bike sales, with fleet buyers negotiating comprehensive maintenance packages while recreational purchasers absorb per-incident repair costs. Three-tier pricing structure across premium, standard, and economy levels reflects battery capacity grades and NHTSA certification tiers. Cost compression in the mid-tier is intensifying because lithium carbonate volatility has compressed pack gross margins. Farming operators in the United States Midwest exhibit the highest price sensitivity due to seasonal utilization patterns, whereas Australian mining fleets prioritize total cost of ownership over upfront acquisition costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale mining fleet demand, while specialty dealer networks manage recreational buyer fulfillment with localized inventory and test-ride availability. Cell production concentrates in China, South Korea, and Japan, with cathode active material refining anchored in Chile and Australia. The supply chain draws from lithium carbonate, nickel sulfate, and cobalt hydroxide feedstocks, with ceramic electrolyte precursors emerging for solid-state prototypes. Single-source vulnerability in high-purity lithium refining exposes Western OEMs to export restriction risks. Distribution runs through authorized dealer networks for UTV and ATV segments, bypassing intermediaries for direct-to-consumer dirt bike configuration portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery architectures are displacing liquid-electrolyte lithium-ion systems across commercial fleet segments, compressing product development cycles and reshaping supplier relationships throughout the value chain.
For Market Incumbents: Deepen captive supply arrangements for lithium iron phosphate cells to insulate against raw material volatility, while accelerating NHTSA rollover certification investments to lock out informal importers. Polaris and BRP must defend their dealer network control against direct-to-consumer channel displacement by Zero Motorcycles and emerging pure-play entrants. For New Entrants and Emerging Players: Launch via online configuration portals targeting German and United States dirt bike enthusiasts seeking custom suspension tunes and swappable battery packs. Federal land management procurement in California, Colorado, and Utah represents the most penetrable institutional segment, with ranger patrol electrification mandates creating immediate fleet-access opportunities absent combustion-era restrictions. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified powersports conglomerates seeking electric drivetrain capabilities, with strategic buyers prioritizing motor control firmware engineering talent and solid-state battery prototyping assets. The five-to-ten-year viability window favors targets with established mining fleet relationships and NHTSA certification completion. Watch for EPA tailpipe regulation acceleration as the inflection indicator for institutional procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term offtake contracts with Asian cell suppliers secure LFP capacity for mining fleet expansion. |
| Platform Standardization | Modular chassis architectures reduce NHTSA certification timelines across UTV and ATV product lines. |
| Charging Infrastructure Partnership | Collaborations with federal land agencies deploy grid connectivity at remote ranger stations in western states. |
| Geographic Manufacturing Footprint | Minnesota-based powertrain assembly anchors North American production for Polaris fleet contracts. |
| Software-Defined Vehicle Investment | Torque-vectoring algorithm development addresses acute power electronics talent scarcity in Nagoya engineering clusters. |
Research Approach
Document review covered EPA regulatory filings, NHTSA safety standard databases, and mining operator procurement records, complemented by interviews with powersports OEM platform engineers, underground mine ventilation officers, federal land management fleet directors, and specialty dealer service managers. Secondary validation drew from SEC 10-K disclosures, IHS Markit vehicle registration data, and Australian national mining safety regulator reports. Bottom-up unit shipment estimates triangulated against top-down market value projections.
Segment-level outputs across the analysis window reflect propulsion architecture, product type, end-user archetype, and regional production cluster dimensions. CAGRs were derived from regression analysis of historical fleet conversion rates and regulatory compliance timelines, with inputs including lithium carbonate price indices, NHTSA certification completion data, and federal land electrification procurement announcements.
Raw material price swings, regulatory delay extensions, and charging infrastructure deployment shortfalls are the dominant revision risks for forecast trajectories. Forecasts reflect documented assumptions regarding battery chemistry cost curves and fleet electrification mandates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off-Highway Vehicle Engine Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
Off Highway Vehicles Brake Systems Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
All-Terrain Vehicle (ATV) Engines Market
Off Road Vehicles
Global Off-Highway Vehicle Telematics Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
All-Terrain Vehicle Market
Off Road Vehicles
Mining Vehicle Attachments Market
Off Road Vehicles
Off-Highway Electric Vehicle Market
Off Road Vehicles
Off-Road Equipment Market
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Snow Scooter Market