
 Snow Scooter Market | 2026-2036
Snow Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Snow Scooter Market Analytics
Premium carbon fiber performance models and commodity-grade plastic recreational units are consolidating into separate demand pools with divergent margin profiles. Ski-Doo leverages its established dealer network to sustain parts and service revenue across North American winter sports regions. Taiga Motors Corporation anchors its competitive position through vertical integration into electric powertrain design and proprietary battery thermal management.
A snow scooter is a motorized or human-propelled vehicle engineered for travel across snow-covered terrain, typically employing track-and-ski configurations with power outputs ranging from entry-level electric motors to high-displacement two-stroke combustion engines exceeding 150 horsepower for commercial guiding and search-rescue operations. Electric snow scooters are capturing outsized engineering investment as battery energy density improvements enable viable cold-weather range, while the rental services segment faces margin compression from seasonal utilization constraints and fleet maintenance cycles. Performance snow scooters command premium positioning through aluminum and carbon fiber chassis construction that reduces unsprung weight for competitive racing and professional guiding applications.
The EPA enforces emissions certification under CFR Title 40 for internal-combustion snow scooters sold in the United States, while the EU F-Gas Regulation constrains refrigerant choices in battery thermal management systems for electric variants distributed across European markets. Health Canada and the PMRA coordinate seasonal vehicle safety standards that affect import timelines and product homologation for manufacturers targeting Canadian winter tourism operators. Stakeholders must monitor regulatory divergence between combustion-phaseout timelines and charging infrastructure deployment across their priority geographic markets.
Market Dynamics
Electrification is splitting the snow scooter market into dual supply chains serving distinct buyer archetypes, with combustion-engine incumbents defending parts revenue while electric entrants capture fleet procurement from Nordic tourism operators.
Growth Catalysts
- EU F-Gas Regulation:Battery thermal management mandates are accelerating R&D investment into solid-state cell architectures for sub-zero operation.
- Finland's Lapland corridor:Tour operators are tripling fleet renewal cycles to meet surging winter tourism demand from Asian and Middle Eastern visitors.
- Lithium-silicon anode chemistry:Energy density improvements are extending electric range sufficiently for commercial guiding routes previously reserved for two-stroke engines.
Market Restraints
- Neodymium supply concentration:Permanent magnet dependency on Chinese rare earth processing creates procurement vulnerability for electric powertrain manufacturers.
- EPA CFR Title 40 certification costs:Small-batch combustion manufacturers face disproportionate compliance burden relative to volume leaders.
- Snowmobile substitution:Multi-passenger sleds retain cost advantage for family recreation segments, constraining single-rider scooter addressable market.
Strategic Opportunities
- Search-and-rescue electrification:Canadian provincial emergency services are piloting battery-powered fleets for reduced acoustic signature in avalanche zones.
- Swiss alpine rental networks:Premium experience operators are adopting hourly subscription models displacing traditional daily rates.
- Battery-as-a-service:Thermal-swappable pack architectures eliminate downtime constraints for commercial fleet operators.
Industry Challenges
- Power electronics thermal engineering:Inverter design for sustained cold-weather output requires scarce semiconductor packaging expertise.
- Homologation timeline compression:Health Canada seasonal approval windows force compressed product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snow Scooter Market |
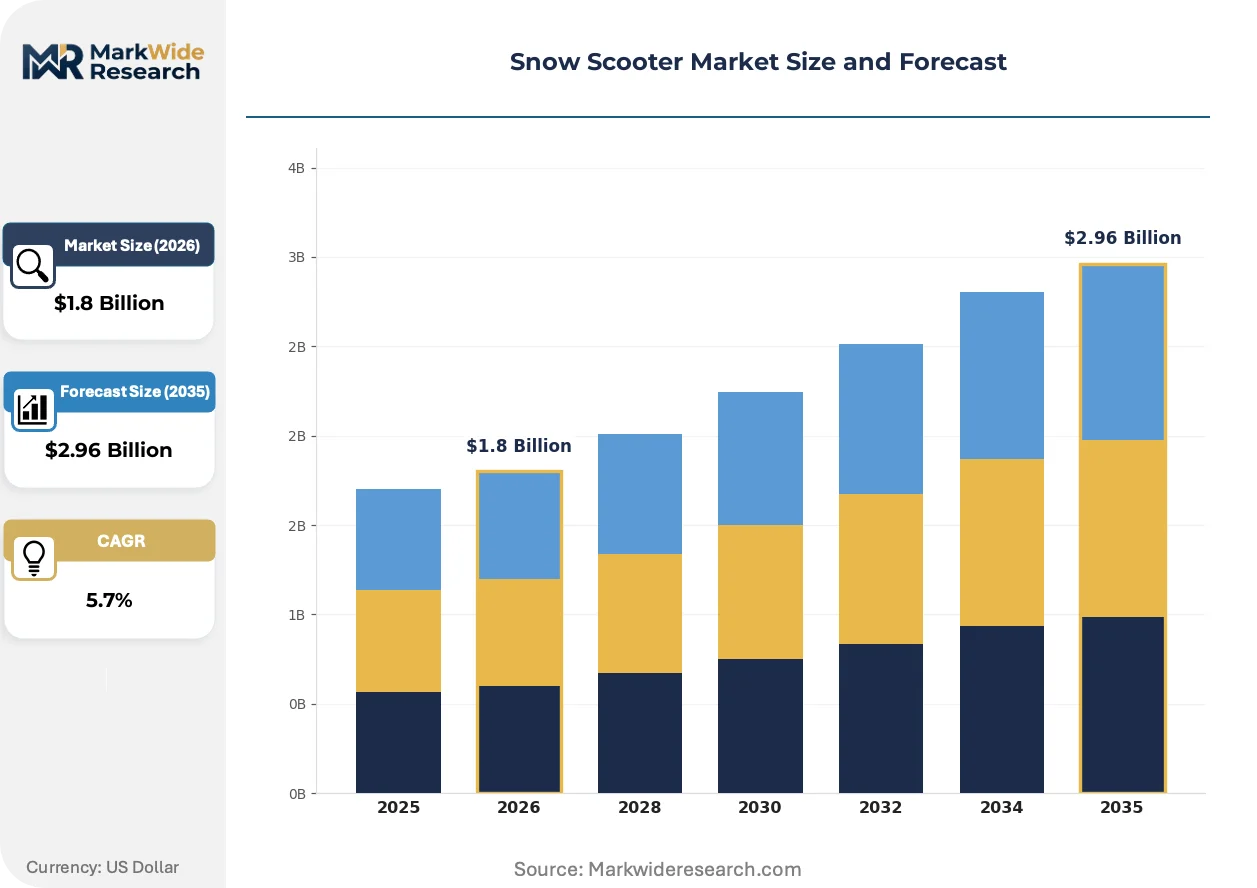
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Snow Scooters, Manual Snow Scooters, Hybrid Models, Performance Snow Scooters End User: Recreational Users, Sports Enthusiasts, Tour Operators, Rental Services Material: Aluminum, Carbon Fiber, Plastic, Steel Weight Capacity: Up to 100 kg, 101-150 kg, 151-200 kg, Above 200 kg |
| Companies Covered | Yamaha Motor Corporation, Ski-Doo, Bombardier Recreational Products Inc. (BRP), Taiga Motors Corporation, Alpina Snowmobiles S.r.l., Polaris Inc., Lynx, Aurora Powertrains, Arctic Cat Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snow Scooter Market Evolving Landscape
Powertrain architecture decisions are locking manufacturers into irreversible platform commitments, with thermal management IP emerging as the primary competitive moat rather than chassis design or brand heritage.
Solid-state battery cell chemistry is rewriting cold-weather viability thresholds for electric snow scooters. Commercial guiding operators in Norway and Sweden are transitioning test fleets ahead of consumer adoption. Range anxiety compression is enabling direct displacement of 800cc two-stroke workhorses in professional applications.
EPA emissions certification under CFR Title 40 is tightening particulate thresholds for internal combustion engines. Manufacturers are diverting engineering resources toward exhaust after-treatment systems. North American mountain resorts are accelerating procurement deadlines to secure grandfathered inventory before phase-in dates.
Hourly rental subscriptions are displacing ownership models among occasional recreational users. Nordic tourism corridors are deploying app-based fleet access replacing traditional lodge-based rental desks. Finland's Levi and Ruka resort clusters exhibit highest penetration of usage-based pricing structures.
Snow Scooter Market Segmentation
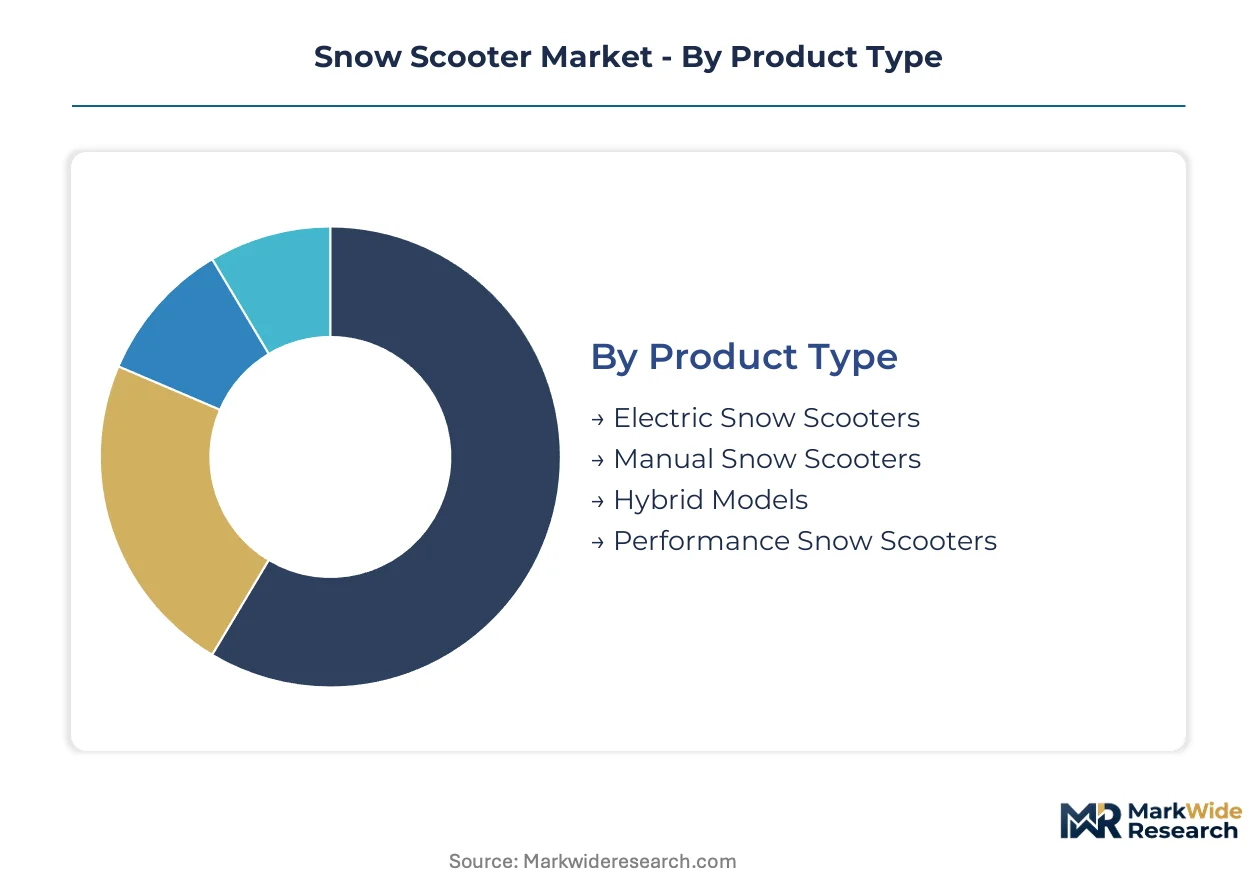
Snow scooter manufacturers face divergent engineering and margin pressures across product tiers. Electrification is fragmenting traditional segmentation while rental networks and tourism operators reshape demand concentration by end-use.
Product Type:
Customization intensity spans from standardized recreational units to bespoke performance configurations with proprietary thermal management systems.
- Electric Snow Scooters:Solid-state battery architectures with silicon-anode cells enable sub-zero range viability previously unattainable. Norwegian and Swedish commercial guiding operators are transitioning test fleets ahead of broader Nordic tourism corridor deployment.
- Performance Snow Scooters:Carbon fiber and aluminum chassis construction reduces unsprung weight for competitive racing and professional avalanche rescue applications. Finnish Lapland tour operators specify these for high-value Asian and Middle Eastern visitor segments.
- Manual Snow Scooters:Human-propelled configurations serve entry-level recreational demand with minimal maintenance overhead.
- Hybrid Models:Dual powertrain architectures bridge range anxiety gaps in remote backcountry access corridors.
Most installed capacity flows through Performance Snow Scooters. Expansion is steepest in Electric Snow Scooters.
End User:
Volume concentration shifts toward fleet procurement as ownership economics deteriorate for occasional users.
- Tour Operators:Fleet renewal cycles have tripled across Finland's Levi and Ruka resort clusters to accommodate surging winter tourism demand. Asian and Middle Eastern visitor growth drives specification for premium carbon fiber units with extended range.
- Rental Services:Hourly subscription models displace daily rates in Swiss alpine networks. App-based fleet access eliminates traditional lodge-based rental desk infrastructure while compressing margins through seasonal utilization constraints.
- Recreational Users:Occasional riders increasingly defer purchase decisions toward on-demand rental access.
- Sports Enthusiasts:Competitive racing participants specify lightweight chassis for sanctioned circuit participation.
Procurement volume concentrates with Tour Operators. Rental Services are gaining share fastest.
Material:
Cost-to-performance ratios stratify procurement decisions across commercial and consumer segments.
- Carbon Fiber:Premium chassis construction commands pricing multiples for professional guiding and competitive racing where unsprung weight reduction directly impacts handling precision.
- Aluminum:Mid-tier structural material balances durability and weight for commercial fleet operators.
- Plastic:Commodity-grade recreational units serve price-sensitive entry demand with standardized molding processes.
- Steel:Heavy-duty configurations for above-200kg weight capacity segments in industrial and rescue applications.
Production volume runs through Aluminum. Carbon Fiber is climbing the fastest.
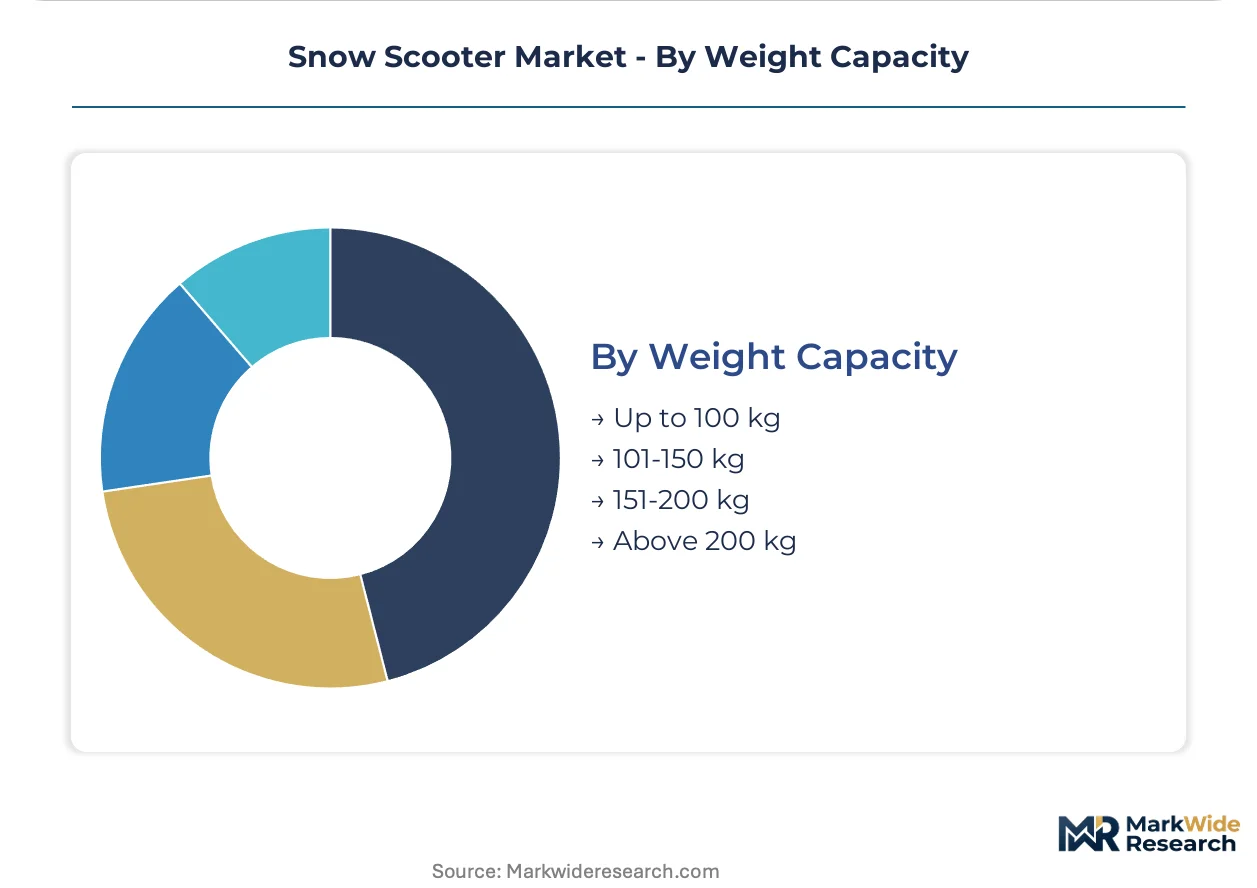
Weight Capacity:
Load specification correlates directly with powertrain architecture and intended operational severity.
- 101-150 kg:Standard commercial specification for Nordic tourism fleet operators balancing passenger accommodation with energy efficiency. Finnish Lapland corridor procurement clusters here for dual-rider compatibility.
- Above 200 kg:Search-and-rescue and commercial guiding configurations with auxiliary equipment mounting requirements. Canadian provincial emergency services pilot battery-powered variants for reduced acoustic signature in avalanche zones.
- Up to 100 kg:Single-rider recreational and youth market specification.
- 151-200 kg:Heavy-duty commercial and light industrial applications.
Fleet procurement concentrates in 101-150 kg. Above 200 kg shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish engineering talent concentrated around Oulu and Rovaniemi anchors electric powertrain development for sub-zero applications. Norwegian and Swedish technical institutes supply battery thermal management specialists to manufacturers serving Nordic tourism corridors.
Finland
Tour operators across the Levi and Ruka resort clusters tripled fleet renewal cycles to accommodate surging Asian and Middle Eastern visitor demand. The Finnish Transport and Communications Agency (Traficom) enforces seasonal vehicle safety standards that compress product homologation timelines. Oulu-based engineering teams develop solid-state battery architectures for commercial guiding applications.
Norway
Commercial guiding operators in Troms and Finnmark pilot electric test fleets for reduced acoustic signature in avalanche terrain. The Norwegian Environment Agency implements emissions standards aligned with EU F-Gas Regulation constraints on refrigerant systems. Bergen-area suppliers specialize in carbon fiber chassis components for premium performance configurations.
Sweden
Search-and-rescue services in Norrbotten County deploy battery-powered units for wilderness emergency response. The Swedish Transport Agency coordinates type-approval processes with EU battery passport requirements. Kiruna mining corridor operators specify heavy-duty configurations for industrial access applications.
Canada
Provincial emergency services in British Columbia and Alberta pilot electric fleets for backcountry rescue operations. Health Canada and the PMRA enforce seasonal safety standards affecting import timelines for winter tourism equipment. Whistler and Banff resort networks drive specification for premium carbon fiber units in high-value visitor segments.
United States
Mountain resort operators across Colorado and Utah accelerate procurement ahead of EPA CFR Title 40 emissions phase-in dates. The Environmental Protection Agency tightens particulate thresholds for internal combustion engines through 2026 certification cycles. Denver-area distributors stockpile grandfathered inventory for Rocky Mountain winter sports networks.
Snow Scooter Market Competitive Landscape
Top-tier vendors anchor premium carbon fiber and electric powertrain segments, while commodity-grade recreational manufacturers compete on molding cost and distribution reach. The vendor base stratifies across three tiers: established powersports conglomerates with dealer network leverage, electric-native entrants with captive battery technology, and regional fabricators serving rental fleet procurement. Consolidation pressure intensifies as electrification splits supply chains into irreversible platform commitments. Strategic moves center on backward integration into cell manufacturing and exclusive resort network partnerships.
Among North American powersports conglomerates, Bombardier Recreational Products Inc. and Polaris Inc. occupy positions defined by established service infrastructure and parts revenue streams. Taiga Motors Corporation exemplifies the electric-native archetype through in-house production of powertrain components. Yamaha Motor Corporation anchors the diversified mobility portfolio segment with cross-platform engineering capabilities. These three representations illustrate how competitive positioning increasingly depends on thermal management intellectual property rather than legacy brand equity.
| Leading Market Players |
|---|
| Yamaha Motor Corporation |
| Ski-Doo |
| Bombardier Recreational Products Inc. (BRP) |
| Taiga Motors Corporation |
| Alpina Snowmobiles S.r.l. |
| Polaris Inc. |
| Lynx |
| Aurora Powertrains |
| Arctic Cat Inc. |
| Others |
Value Network & Pricing Analysis
Backward integration into battery cell manufacturing anchors both supply security and pricing power for electric-native manufacturers serving Nordic tourism corridors. Captive production of lithium-silicon anode architectures insulates fleet operators from rare earth procurement volatility while supporting premium positioning against commodity-grade competitors.
Pricing Analysis
The bundled-vs-unbundled service split separates ownership economics from access-based models across the market. Hourly subscription pricing stratifies across premium, standard, and economy tiers in Swiss alpine rental networks, while tour operators in Finland's Lapland corridor negotiate volume contracts for carbon fiber performance units. Cost compression in commodity plastic recreational segments is intensifying because of molding oversupply in Asian manufacturing hubs. Rental services exhibit highest price sensitivity due to seasonal utilization constraints, whereas search-and-rescue procurement shows lowest sensitivity given operational criticality.
Supply Chain Analysis
Certification and qualification gating through EPA CFR Title 40 and EU F-Gas Regulation constrains supplier eligibility for North American and European markets. Manufacturing concentration centers on Finland, Norway, and Sweden for electric powertrain assembly, with carbon fiber chassis sourcing from Bergen-area specialists. Critical inputs include neodymium permanent magnets, solid-state electrolyte materials, and aluminum structural extrusions. Single-source vulnerability in Chinese rare earth processing creates procurement exposure for electric powertrain manufacturers. Distribution runs through established powersports dealer networks and direct fleet procurement relationships with resort operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EPA emissions phase-in timelines and EU F-Gas mandates are accelerating fleet replacement cycles among commercial operators.
For Market Incumbents: Cement dealer network loyalty through exclusive parts and service agreements before electric entrants establish direct fleet relationships. Prioritize certification investment in solid-state battery thermal management to defend against Taiga Motors' captive technology advantage. Combustion-engine incumbents face substitution threat from battery-powered search-and-rescue pilots in Canadian provincial services. For New Entrants and Emerging Players: App-based fleet access platforms offer the lowest customer acquisition cost route into Nordic tourism corridors where traditional lodge-based rental infrastructure is being dismantled. Target hourly subscription penetration in Swiss alpine networks before expanding to Finnish Levi and Ruka resort clusters. White-space exists in battery-as-a-service thermal-swappable architectures for commercial operators. For Investors and Strategic Acquirers: Consolidation pressure builds where electric powertrain IP scarcity intersects with seasonal cash flow volatility among regional fabricators. Long-term viability favors manufacturers with captive cell chemistry capabilities and exclusive resort network partnerships. Acquisition target archetype: mid-tier electric-native specialists with Health Canada homologation progress. Watch solid-state battery range thresholds crossing commercial guiding viability as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Scale-Up | Enables sub-zero range viability for Norwegian commercial guiding operators transitioning from two-stroke engines. |
| Resort Network Exclusivity | Locks out competitors from Finland's Levi and Ruka corridor where Asian visitor growth concentrates demand. |
| Thermal-Swappable Pack Architecture | Eliminates fleet downtime constraints for tour operators running compressed seasonal utilization windows. |
| Carbon Fiber Chassis Backward Integration | Reduces unsprung weight for competitive racing while securing margin control against Bergen-area suppliers. |
| Health Canada Homologation Fast-Track | Compresses product launch cycles to capture provincial emergency services electrification pilots. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate market sizing and growth trajectory assumptions. Primary interviews engaged powersports OEM procurement directors, Nordic tourism fleet managers, battery thermal management engineers, and alpine resort operations heads. Secondary validation drew from EPA certification filings, EU F-Gas Regulation implementation notices, Health Canada seasonal vehicle safety standards, and customs trade data for snow vehicle imports. Bottom-up unit economics from fleet operator interviews were cross-checked against top-down market value estimates from regional tourism authority statistics.
Comparable-period anchoring linked projection assumptions to historical fleet replacement cycles and regulatory compliance deadlines across the analysis window. Segmentation modeling spanned propulsion architecture, chassis material tier, weight capacity specification, and end-use application. CAGRs were derived from fitted growth curves against observed procurement patterns. Industry-specific forecast inputs included battery energy density improvement trajectories and Nordic winter tourism visitor growth projections.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for electric displacement of combustion workhorses. Forecasts reflect assumptions about regulatory phase-in adherence and charging infrastructure deployment pace. A model refresh is warranted upon material change in EPA emissions certification timelines or breakthroughs in silicon-anode cell manufacturing cost.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Small Off-Road Engines Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Global Automotive Off Highway Engine Market
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
Mining Vehicle Attachments Market
Off Road Vehicles
Off-Highway Vehicle Engine Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Off-Highway Wheels Market
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
Global Off-Highway Vehicle Telematics Market
Off Road Vehicles
Electric Off-Road Vehicles Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
US Off-Road Vehicles Market
Off Road Vehicles
Off Highway Vehicles Brake Systems Market