
 Mining Vehicle Attachments Market | 2026-2036
Mining Vehicle Attachments Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Vehicle Attachments Market Analytics
Aftermarket telematics subscriptions is restructuring how attachment vendors monetize hardware, shifting revenue from one-time sales to recurring performance-monitoring contracts. Caterpillar Inc. leverages its dealer network to bundle predictive maintenance with bucket rebuild programs. Komatsu Ltd. anchors its Smart Construction platform to track ripper wear in real time across Australian iron ore sites. Epiroc AB differentiates through autonomous-ready grapple interfaces that integrate with its drill-and-load automation stack.
Mining vehicle attachments are heavy-duty implements—typically fabricated from quenched-and-tempered high-strength steel plate with Brinell hardness ratings exceeding 400 HB—mounted to excavators, loaders, and haul trucks to perform excavation, material handling, and ground-engaging tasks in abrasive mineral environments. Steel dominates material selection for ground-engaging tools due to weldability and impact toughness, though alloy grades with embedded tungsten carbide overlays are gaining share in high-abrasion copper and iron ore applications where service intervals directly dictate fleet uptime. Buckets and rippers together command the majority of replacement demand, while composite liner inserts represent an emerging margin pool as operators seek to reduce carry-back and fuel burn in transport applications.
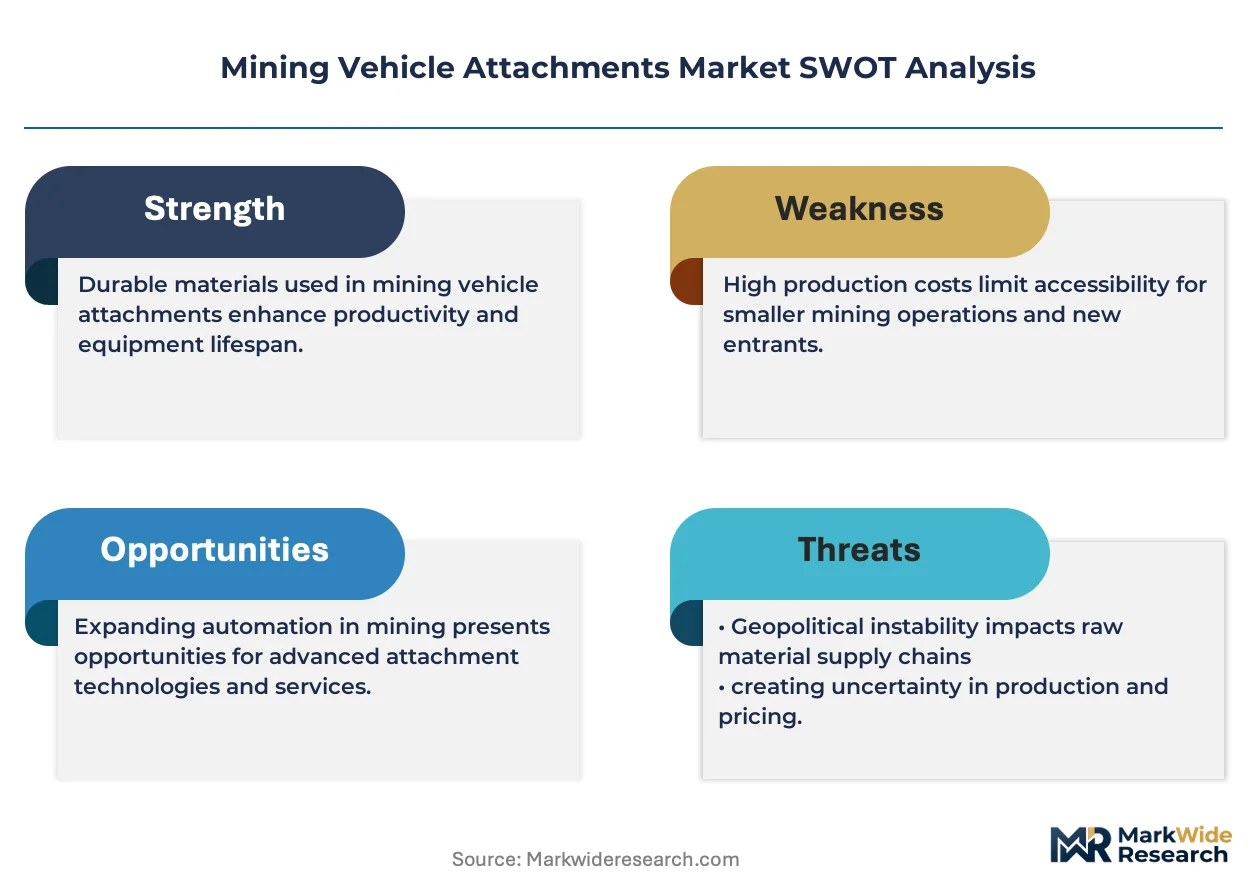
MSHA enforces structural integrity standards for above-ground attachments in US surface mines, while the EU Machinery Directive and CE marking requirements govern safety interlocks and hydraulic quick-coupler designs sold into European quarrying operations. Australia's state-based mine safety regulators, particularly in Queensland and Western Australia, mandate third-party certification for lifting attachments used in crane-assisted maintenance tasks. Stakeholders must weigh aftermarket telemetry monetization against the capital intensity of qualifying new attachment designs under diverging national certification regimes.
Market Dynamics
The Mining Vehicle Attachments Market pivots on the tension between mechanized extraction intensity and regulatory mandates for lighter, acoustically dampened designs. Underground contractors in Western Australia's Pilbara iron ore district are expanding attachment fleets to match super-pit throughput requirements while EPA emissions standards and MSHA noise regulations force OEMs to reengineer structural geometries.
Growth Catalysts
- Western Australia's Pilbara iron ore super-pits:Ultra-class loader buckets and dump truck bodies command replacement cycles tied to 24/7 extraction schedules, concentrating demand among operators running the world's largest mechanized fleets.
- EPA emissions standards:Lighter attachment designs reduce fuel burn per ton moved, creating compliance pathways for surface mine operators facing tightened federal thresholds on diesel particulate output.
- Tungsten carbide overlay alloys:Embedded hardfacing technologies extend service intervals in high-abrasion copper applications, directly improving fleet uptime metrics that govern contract renewals.
Market Restraints
- Quenched-and-tempered steel plate volatility:Brinell 400+ HB grades face input cost swings tied to scrap metal and alloying element markets, compressing fabrication margins without commensurate pricing power.
- Western Australian demand concentration:Geographic clustering of super-pit operators exposes attachment vendors to single-region commodity cycle risk and procurement budget freezes during iron ore price corrections.
- MSHA structural integrity certification timelines:Above-ground attachment approvals for US surface mines extend 12-18 months, freezing design iterations and delaying revenue recognition on new product lines.
Strategic Opportunities
- Composite liner inserts for haul truck bodies:Polyurethane and rubber-ceramic hybrid materials reduce carry-back and fuel consumption in transport applications, opening margin pools beyond traditional steel replacement parts.
- EU Machinery Directive CE marking for hydraulic quick-couplers:Safety interlock mandates for European quarrying operations create certified-product premiums for vendors willing to navigate divergent national approval regimes.
- Autonomous-ready grapple interfaces:Drill-and-load automation stacks in Australian underground mines require standardized attachment-to-vehicle communication protocols that early movers can establish as de facto industry specifications.
Industry Challenges
- Certification fragmentation across Queensland and Western Australia state regulators:Third-party lifting attachment approvals for crane-assisted maintenance tasks require redundant testing protocols, extending time-to-market for multi-state vendors.
- Welding technician scarcity for high-strength steel fabrication:Quenched-and-tempered plate joining demands specialized heat-affected zone control that conventional training programs inadequately address.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Vehicle Attachments Market |
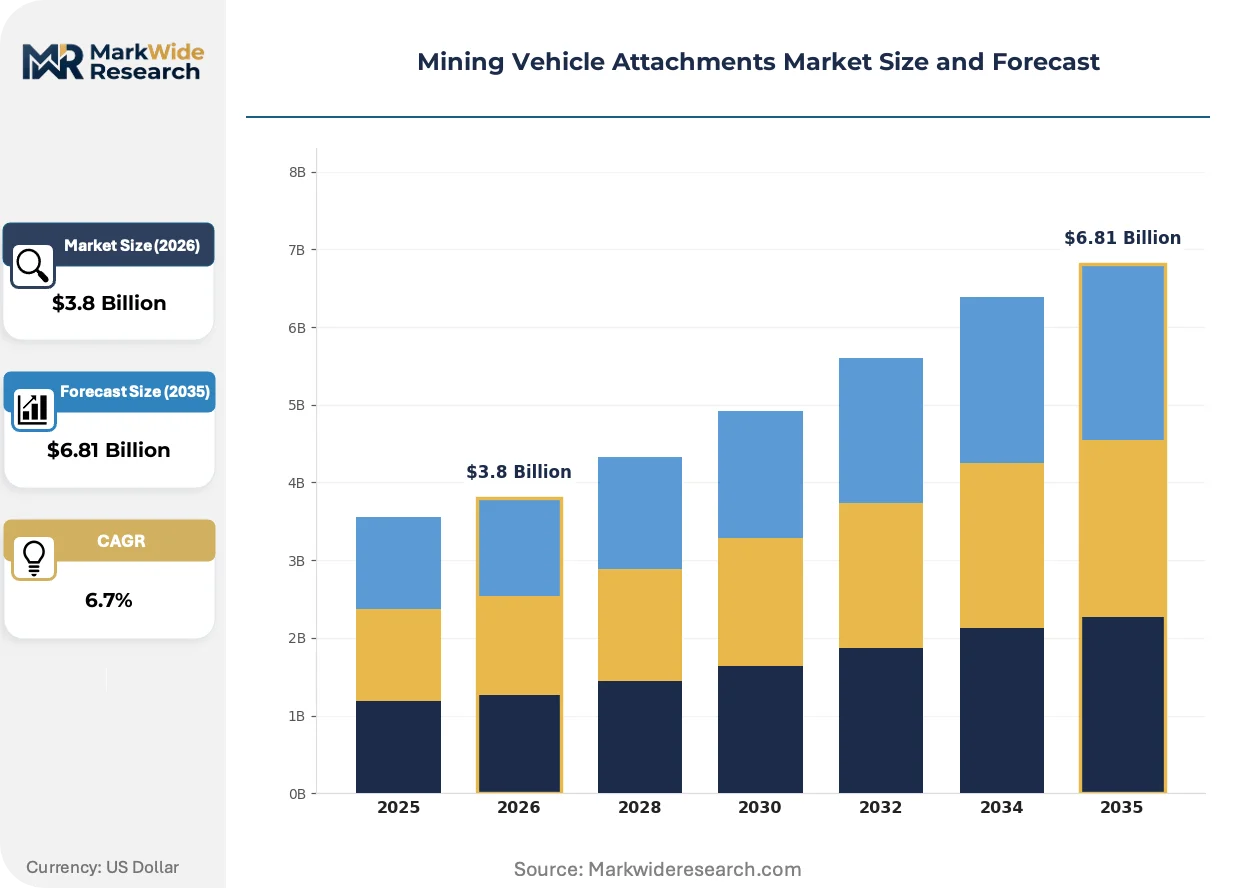
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Buckets, Rippers, Blades, Grapples Material: Steel, Alloy, Composite, Rubber Application: Excavation, Material Handling, Transport, Grading End User: Contractors, Mining Companies, Equipment Rental Firms, Others |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Epiroc AB, Hitachi Construction Machinery Co., Ltd., Liebherr Group, Sandvik AB, JCB, Doosan Infracore, Volvo Construction Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Vehicle Attachments Market Evolving Landscape
Aftermarket telematics is restructuring how attachment vendors capture value, shifting revenue from one-time hardware sales toward recurring performance-monitoring contracts tied to wear prediction and predictive maintenance scheduling.
Additive manufacturing of tungsten carbide matrix overlays is decentralizing hardfacing repair operations from centralized OEM facilities to mine-site maintenance workshops. Australian iron ore operators with captive fabrication capabilities are adopting portable laser cladding systems for in-situ bucket lip restoration. This technology is decentralizing service revenue streams and compressing OEM aftermarket capture rates.
MSHA noise regulation enforcement is accelerating acoustically dampened attachment designs across US surface mining operations. Revised permissible exposure limits for operator cabins are forcing structural modifications to ripper shanks and loader bucket backbones to reduce vibration transmission. Above-ground excavation segments in Appalachia and the Powder River Basin are absorbing the highest compliance costs, with contractors retrofitting existing fleets rather than awaiting new-build solutions.
Buyer consolidation among tier-one mining houses is compressing procurement cycles and demanding unbundled after-sales service contracts. Western Australian super-pit operators now separate attachment purchase from rebuild programming and telemetry subscription, forcing vendors to price components transparently. This unbundling is most pronounced in iron ore and copper segments where fleet standardization across multiple mine sites enables volume-based supplier rationalization.
Mining Vehicle Attachments Market Segmentation
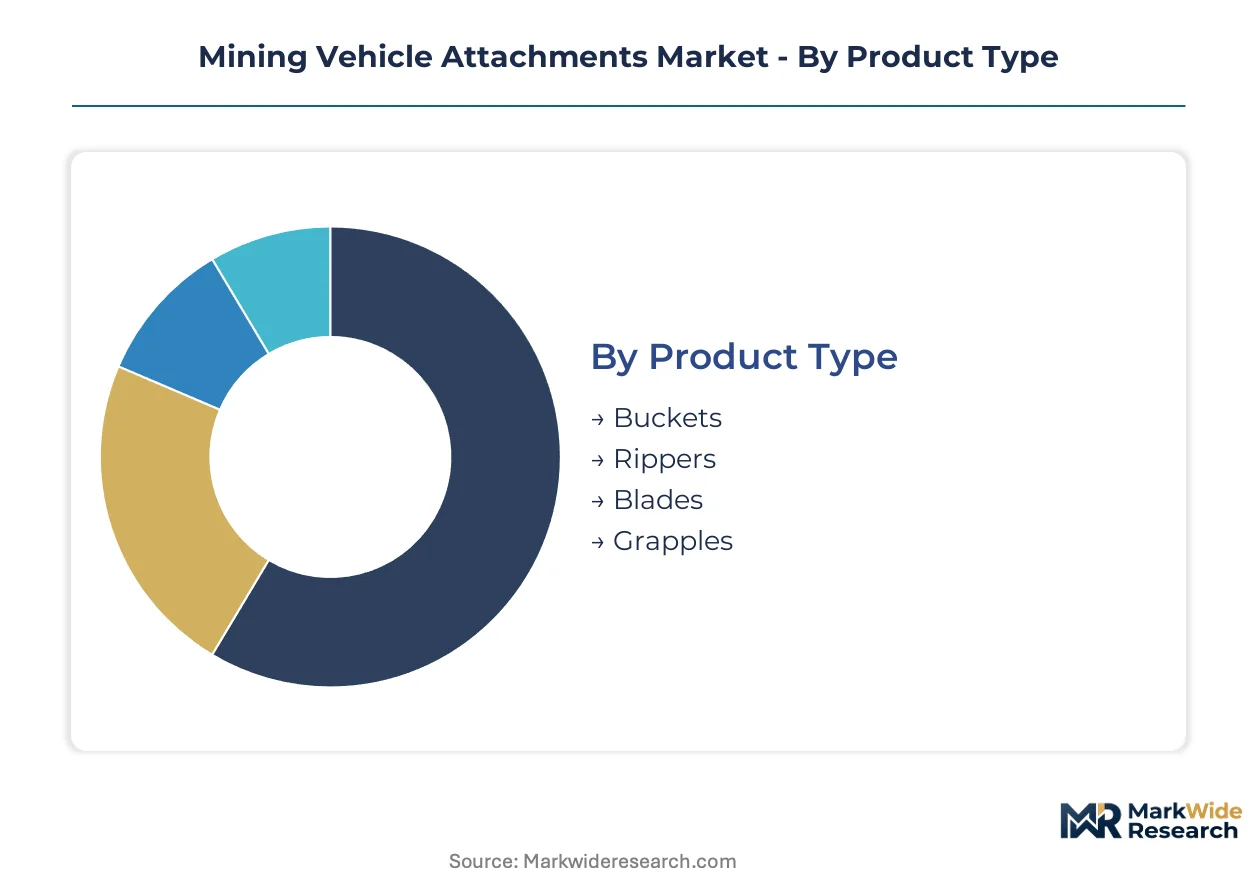
Attachment specification directly determines wear life and fuel efficiency in high-abrasion mining environments. Procurement decisions split across structural material choices, duty-cycle intensity, and fleet standardization mandates imposed by tier-one operators.
Product Type:
Structural geometry and ground-engaging intensity define the specification axis across implement categories.
- Buckets:Fabricated from quenched-and-tempered plate exceeding 400 Brinell hardness, these implements dominate replacement demand in Western Australia's Pilbara iron ore super-pits where 24/7 extraction cycles drive wear-based procurement. Ultra-class loader buckets command premium positioning due to captive fleet standardization among BHP and Rio Tinto operations.
- Rippers:Shank assemblies with replaceable tooth systems penetrate consolidated overburden in Appalachian coal and Chilean copper applications. MSHA noise regulations are forcing structural modifications to reduce vibration transmission into operator cabins, extending design-to-certification timelines.
- Blades:Moldboard configurations for dozer fleets prioritize penetration angle adjustability across varying rock hardness.
- Grapples:Hydraulic-actuated clamshell designs serve crane-assisted maintenance tasks in Queensland underground operations.
Buckets lead on scale; grapples lead on momentum.
Material:
Cost-to-lifecycle performance ratios govern alloy selection in high-wear applications.
- Steel:Weldable quenched-and-tempered grades remain the baseline for ground-engaging tools due to impact toughness and repairability. Input cost volatility tied to scrap metal markets compresses fabrication margins without commensurate pricing power.
- Alloy:Embedded tungsten carbide overlays extend service intervals in Chilean copper and Pilbara iron ore sites where uptime metrics govern contract renewals. Additive manufacturing of hardfacing matrices is decentralizing repair operations to mine-site workshops.
- Composite:Polyurethane-ceramic hybrid liners reduce carry-back and fuel consumption in haul truck body applications.
- Rubber:Elastomeric dampening inserts address MSHA noise compliance in US surface mining retrofit programs.
Steel dominates volume; alloy captures the steepest expansion trajectory.
Application:
Duty-cycle intensity and abrasiveness determine attachment specification and replacement frequency.
- Excavation:Ground-engaging tools in overburden removal face the highest wear rates and drive scheduled rebuild programming. Western Australian super-pit operators unbundle excavation attachment purchase from telemetry subscription and rebuild contracts.
- Material Handling:Loader and shovel buckets in stockpile management prioritize fill factor optimization over penetration resistance. Australian iron ore sites demand autonomous-ready grapple interfaces for drill-and-load automation stacks.
- Transport:Haul truck body liners focus on reducing carry-back to minimize fuel burn per ton-kilometer.
- Grading:Dozer blades in mine site maintenance require edge retention across loose and consolidated surfaces.
Excavation leads on scale; material handling leads on momentum.
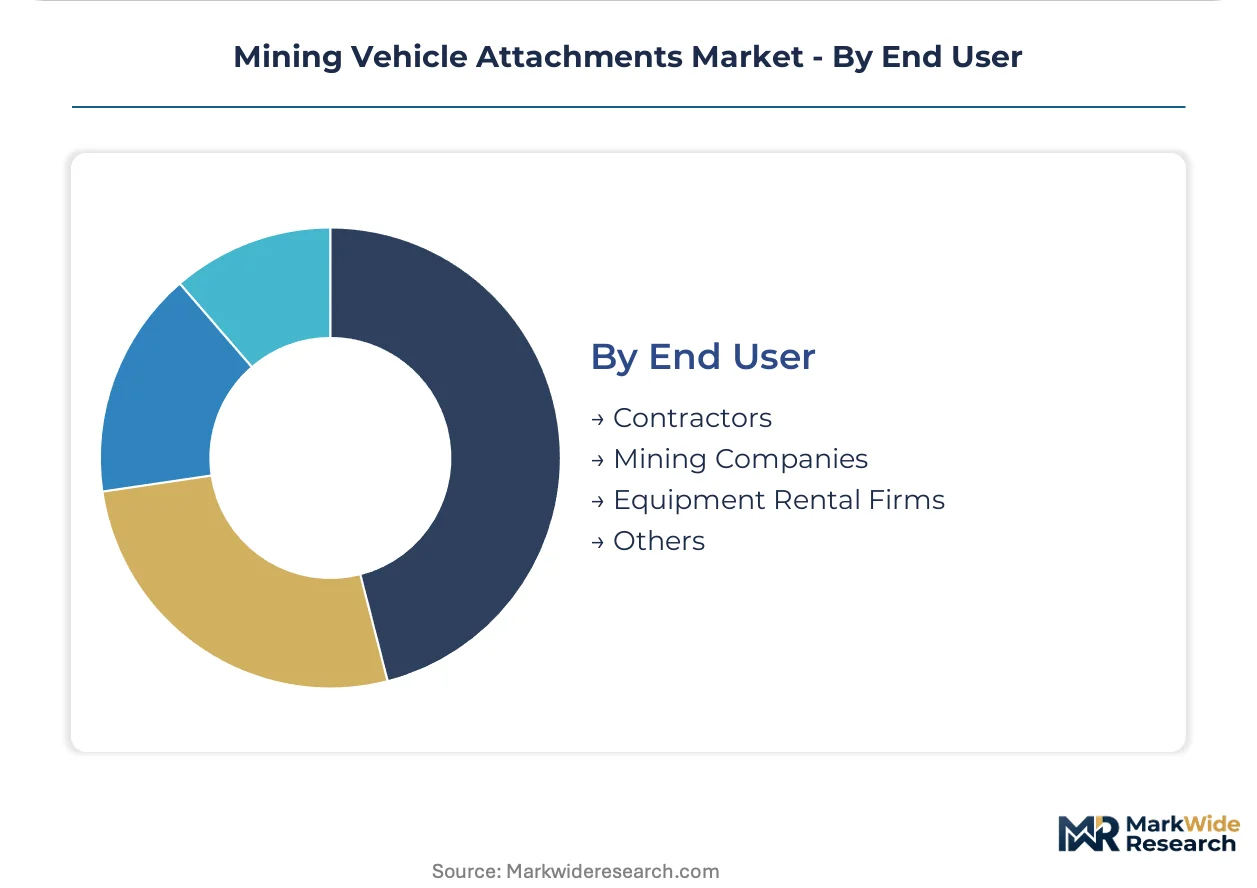
End User:
Procurement centralization and captive technical capability shape vendor relationship structures.
- Mining Companies:Tier-one houses with standardized multi-site fleets command volume-based pricing and unbundled service contracts. BHP and Rio Tinto operations in Western Australia separate attachment purchase from predictive maintenance subscriptions.
- Contractors:Underground specialists in Queensland and Western Australia expand attachment fleets to match mechanized extraction intensity while lacking captive fabrication capabilities.
- Equipment Rental Firms:Fleet lessors prioritize interchangeability and quick-coupler compatibility across mixed OEM populations.
- Others:Quarrying and construction-adjacent operators represent fragmented, price-sensitive demand.
Mining companies lead on scale; contractors lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where attachment fabricators locate production capacity, with OEMs shifting final assembly toward jurisdictions offering streamlined certification pathways for high-strength steel welding operations.
Australia
Western Australia's Pilbara iron ore super-pits concentrate global demand for ultra-class loader buckets and dump truck bodies. TGA-equivalent state regulators in Queensland and Western Australia mandate third-party certification for lifting attachments used in crane-assisted maintenance. Perth-based fabrication workshops supply BHP and Rio Tinto operations with autonomous-ready grapple interfaces for drill-and-load automation stacks.
United States
Appalachian coal and Powder River Basin surface mining drive replacement cycles for ground-engaging tools. EPA emissions standards and MSHA noise regulations force structural modifications to ripper shanks and loader bucket backbones, extending design-to-certification timelines to 12-18 months. Above-ground excavation contractors in West Virginia and Wyoming absorb the highest compliance costs through fleet retrofit programs.
Chile
High-abrasion copper extraction in the Atacama Desert extends service intervals for tungsten carbide overlay alloys. The country's national mining regulator enforces structural integrity standards for above-ground attachments that align with ISO certification frameworks. Antofagasta-based operators prioritize uptime metrics that govern contract renewals with tier-one mining houses.
China
Domestic iron ore and coal extraction sustains demand for quenched-and-tempered steel plate fabrications. MIIT industrial standards govern weldability and impact toughness specifications for ground-engaging tools. Shanxi Province coal operations and Hebei iron ore clusters represent the densest concentrations of mechanized fleet operators.
South Africa
Platinum and gold underground mining drives attachment fleet expansion to match mechanized extraction intensity. The country's national mine safety regulator enforces structural certification for lifting attachments that parallels Australian state-based frameworks. Rustenburg and Johannesburg mining corridors concentrate procurement demand among contractors lacking captive fabrication capabilities.
Mining Vehicle Attachments Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-line OEMs commanding premium positioning in autonomous-ready interfaces while regional fabricators capture replacement-part volumes. The vendor base stratifies into three tiers: integrated mining equipment houses with captive attachment divisions, independent hardfacing specialists, and mine-site service workshops with additive manufacturing capabilities. Consolidation pressure is accelerating as tier-one mining houses unbundle procurement and demand transparent component pricing.
Within the integrated equipment tier, Caterpillar Inc. and Komatsu Ltd. occupy positions that exemplify dealer-network bundling of predictive maintenance with rebuild programs. Epiroc AB anchors the automation-ready specialization vector through standardized grapple interfaces. These three companies represent divergent strategic postures: captive distribution leverage, smart construction platform integration, and autonomous system compatibility.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Epiroc AB |
| Hitachi Construction Machinery Co., Ltd. |
| Liebherr Group |
| Sandvik AB |
| JCB |
| Doosan Infracore |
| Volvo Construction Equipment |
| Others |
Value Network & Pricing Analysis
Quenched-and-tempered steel plate volatility feeds directly into attachment fabrication margins, with Brinell 400+ HB grade cost swings compressing pricing power before reaching Western Australian super-pit operators and Appalachian coal contractors downstream.
Pricing Analysis
Distributor margins for aftermarket attachments typically absorb 15-25 points before mine-site delivery, though direct-to-OEM volume contracts bypass this layer entirely. Pricing stratifies across autonomous-ready premium tiers, MSHA-certified mid-tier rebuilds, and unbranded economy replacement parts, with differentiation anchored in certification grade and predictive maintenance bundling. Cost compression in economy steel fabrications is intensifying because scrap metal input volatility outpaces contract pricing adjustments. Contractors in Queensland underground operations exhibit highest price sensitivity, while BHP and Rio Tinto captive fleets prioritize uptime metrics over unit cost.
Supply Chain Analysis
Welding technician scarcity for high-strength steel fabrication concentrates production capacity in Perth, Antofagasta, and Pittsburgh metro corridors where specialized heat-affected zone training programs exist. Supply draws from Australian iron ore district demand clusters, Chilean copper belt service hubs, and US Appalachian coal repair networks. Raw material dependencies center on quenched-and-tempered plate, tungsten carbide powder, and polyurethane-ceramic composite feedstocks. Single-source vulnerability in certified welding labor pools threatens fabrication throughput during peak replacement cycles. Distribution runs through OEM captive dealer networks, independent hardfacing specialists, and mine-site additive manufacturing workshops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in mining vehicle attachments rests on composite liner insert adoption and telemetry subscription unbundling, both shifting revenue from transactional hardware toward recurring service architectures.
For Market Incumbents: Hedge against additive manufacturing decentralization by acquiring portable laser cladding service providers in Pilbara and Atacama corridors. Secure captive welding technician pipelines through Queensland and Western Australia vocational partnerships before certification fragmentation worsens. Defensive positioning requires backward integration into tungsten carbide overlay alloy supply.
For New Entrants and Emerging Players: MSHA noise regulation enforcement in US surface mining opens a window for acoustically dampened ripper shank designs with 12-18 month certification runway. Target Appalachian retrofit programs and Powder River Basin contractor fleets as most penetrable segments. White-space exists in EU Machinery Directive CE-marked hydraulic quick-couplers for European quarrying. Go-to-market through independent hardfacing specialists bypasses OEM dealer network lock-in.
For Investors and Strategic Acquirers: Roll-up economics work for regional hardfacing specialists with captive welding certification because tier-one mining house unbundling fragments procurement across multiple attachment vendors. Five-to-ten year viability favors autonomous-ready grapple interface developers with drill-and-load automation stack integration. Signal to monitor: BHP and Rio Tinto telemetry subscription renewal rates as predictive maintenance contract penetration inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Carbide Supply | Captive hardfacing alloy production insulates margin from powder metal volatility in Chilean copper applications. |
| Autonomous-Ready Grapple Interface Development | Standardized communication protocols with Epiroc drill-and-load stacks establish de facto specifications for Australian underground. |
| Mine-Site Additive Manufacturing Deployment | Portable laser cladding systems in Pilbara workshops compress OEM aftermarket capture rates for bucket lip restoration. |
| CE Marking Investment for Quick-Couplers | Safety interlock certification unlocks premium positioning in European quarrying operations under Machinery Directive. |
| Predictive Maintenance Subscription Unbundling | Separating telemetry from hardware purchase responds to Western Australian super-pit procurement rationalization demands. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining maintenance directors at Pilbara iron ore operations, aftermarket service heads at OEM dealer networks, procurement leads at tier-one mining houses, and welding technicians at Perth fabrication workshops with secondary validation. Primary sources included MSHA certification databases, Australian state mine safety regulator filings, SEC 10-K equipment segment disclosures, and customs records for quenched-and-tempered steel plate imports. Bottom-up attachment unit demand models triangulated against top-down mining fleet size estimates.
Historical reference periods anchored forward projections across the analysis window, with segmentation modeling spanning product type, material alloy grade, application duty-cycle intensity, and end-user procurement centralization. CAGRs derived from regression against mechanized extraction intensity indices and replacement cycle frequency data. Industry-specific forecast inputs incorporated EPA emissions compliance cost trajectories and autonomous mining equipment deployment timelines.
Revisions become necessary when iron ore price corrections freeze Western Australian procurement budgets, MSHA extends structural integrity certification timelines, or welding technician scarcity forces fabrication capacity constraints. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
All-Terrain Vehicle Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Off-Highway Wheels Market
Off Road Vehicles
Off-Road Equipment Market
Off Road Vehicles
Global Automotive Off Highway Engine Market
Off Road Vehicles
All-Terrain Vehicle (ATV) Engines Market
Off Road Vehicles
Off-Highway Electric Vehicle Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
Off-Highway Vehicle Engine Market
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
Electric Utility-Terrain Vehicle (UTV) Market