
 Off-Road Equipment Market | 2026-2036
Off-Road Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Road Equipment Market Outlook
EPA Tier 4 Final is realigning the cost-of-entry calculus for off-road equipment manufacturers serving North American construction and agriculture buyers. Caterpillar leverages its vertical integration into engine manufacturing to sustain compliance leadership across heavy-duty product lines. Deere & Company anchors its position through R&D intensity in precision agriculture systems that integrate with off-road machinery platforms. Komatsu Ltd differentiates via autonomous haulage technology leadership in mining applications.
Off-road equipment encompasses wheeled and tracked vehicles engineered for operation on unpaved surfaces, typically featuring reinforced suspensions, high-torque powertrains, and ground clearance exceeding 250 millimeters to navigate irregular terrain. These machines serve commercial earthmoving, material handling, and specialized transport functions where conventional on-highway vehicles lack operational viability. Construction application demand leads absolute volume, while electric fuel type configurations represent the fastest-expanding margin pool as urban emissions restrictions proliferate. ATV and UTV equipment types dominate recreational end-user spending, though contractor-grade utility segments command premium pricing through durability specifications and service-network density.
Federal emissions oversight from EPA in the United States, Stage V standards enforced by European regulators, and China's MIIT technology mandates collectively reshape product development timelines and certification costs across manufacturing footprints. OSHA workplace safety requirements and ISO 3449 falling-object protective structures further constrain design flexibility while creating compliance barriers for new entrants. Stakeholders must monitor battery-electric platform readiness against impending diesel restrictions in major metropolitan construction zones.
Market Dynamics
The convergence of EPA Tier 4 Final compliance deadlines and EU Stage V urban diesel bans is compressing product development cycles while accelerating electric powertrain substitution in contractor fleets.
Growth Catalysts
- Autonomous Haulage Systems:Mining contractors in Australia and Chile are expanding fleets of self-driving haul trucks to reduce labor costs and improve pit-to-crusher cycle times in 24-hour operations.
- Stage V Urban Mandates:European construction zones with strict diesel prohibitions are pulling battery-electric excavators and wheel loaders into active deployment ahead of total cost parity.
- Precision Agriculture Integration:North American farming operations are retrofitting off-road platforms with GPS-guided implements and variable-rate application systems to optimize input efficiency.
Market Restraints
- After-Treatment Cost Burden:Diesel particulate filters and selective catalytic reduction systems add 15-25% to engine bill-of-materials, squeezing margin on mid-horsepower equipment.
- Battery Supply Concentration:Lithium-ion cell production clusters in China create geopolitical exposure and raw material price volatility for electric equipment manufacturers.
- Charging Infrastructure Gaps:Rural construction sites and remote mining locations lack grid capacity or fast-charging networks to support electric fleet conversion.
Strategic Opportunities
- India Infrastructure Buildout:National highway expansion and irrigation projects are creating demand for motor graders and compactors in states with limited equipment penetration.
- Hydrogen Fuel Cell Convergence:Integration of fuel cell stacks with electric drivetrains offers zero-emission range extension for large mining trucks operating beyond tethered charging reach.
- Rental Channel Digitization:Equipment-as-a-service platforms with telematics-enabled utilization tracking are displacing traditional ownership models among mid-size contractors.
Industry Challenges
- Software-Hardware Integration Complexity:Autonomous control systems require embedded engineers with robotics and machine learning expertise that traditional mechanical design teams lack.
- Certification Timeline Compression:EPA and EU type-approval processes for new powertrain architectures now extend 18-24 months, delaying revenue recognition on redesigned platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Road Equipment Market |
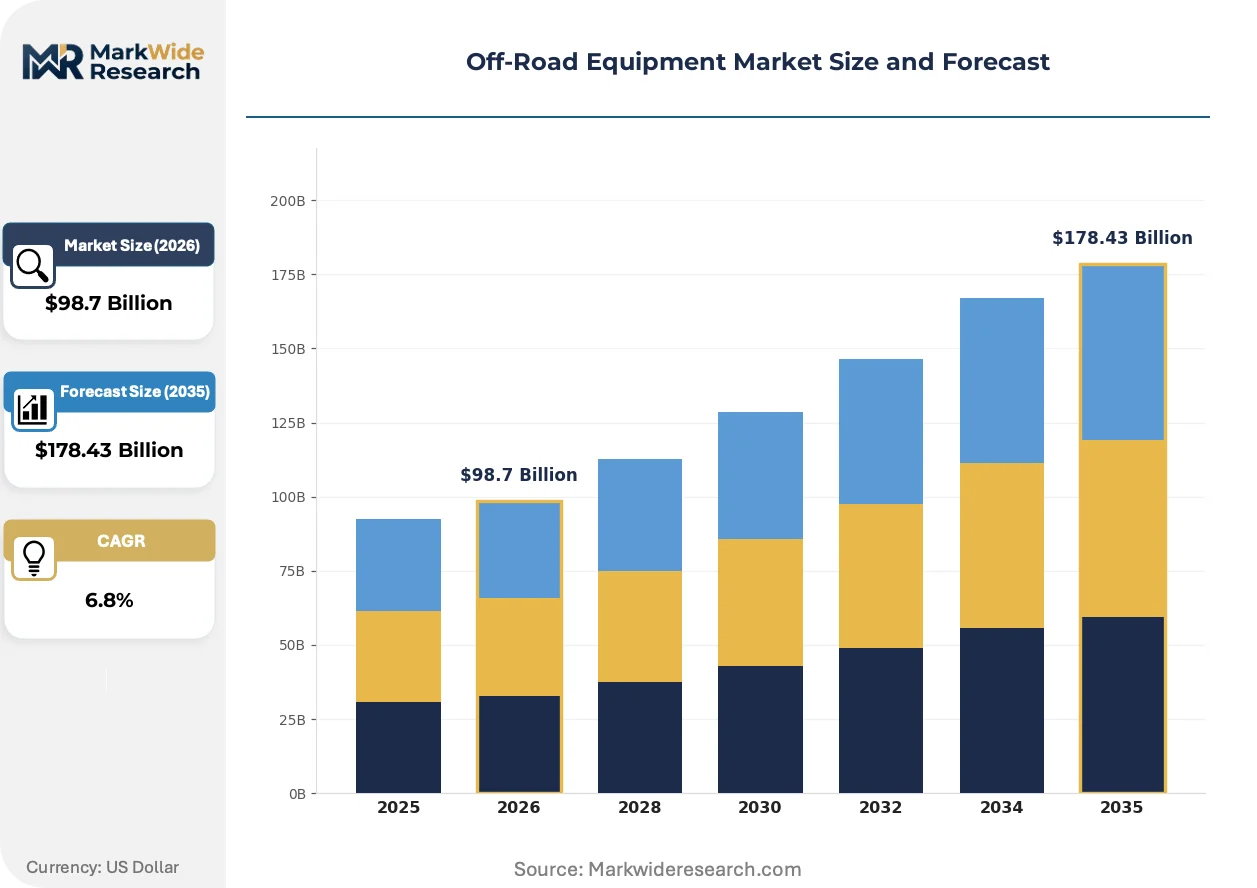
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: ATVs, UTVs, Dirt Bikes, Rock Crawlers Application: Construction, Agriculture, Recreation, Landscaping End User: Contractors, Farmers, Recreational Users, Municipalities Fuel Type: Gasoline, Diesel, Electric, Hybrid |
| Companies Covered | CNH Industrial N.V, Liebherr Group, Caterpillar, Volvo Construction Equipment, Hitachi Construction Machinery, Deere & Company, Kubota Corporation, Sany Heavy Industry, Komatsu Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Road Equipment Market Strategic Shifts
Electrification architectures and autonomous control systems are rewriting equipment specifications while reshaping how contractors acquire and deploy machinery across project sites.
Battery-electric powertrains are overtaking diesel-electric hybrids as the dominant zero-emission architecture for sub-50-ton equipment categories. European urban contractors are specifying all-electric excavators for inner-city demolition and utility work to comply with municipal diesel restrictions. This shift is compressing the addressable market for conventional engine suppliers and forcing joint-ventures with battery pack assemblers.
EPA Tier 4 Final and EU Stage V emissions standards are mandating exhaust after-treatment systems that add weight, complexity, and thermal management requirements to engine compartments. Engine manufacturers are responding with modular SCR-DPF packages and predictive regeneration algorithms to minimize operator intervention. The construction segment bears the highest compliance cost burden due to intermittent load cycles that complicate catalyst temperature maintenance.
Telematics-enabled fleet management is replacing manual maintenance scheduling and paper-based utilization logs across equipment rental and owner-operator segments. Contractors are subscribing to cloud-based platforms that aggregate machine health data, parts inventory, and service technician dispatch into unified dashboards. This behavioral shift is most pronounced in North American markets where cellular coverage supports real-time data transmission from remote job sites.
Off-Road Equipment Market Segmentation
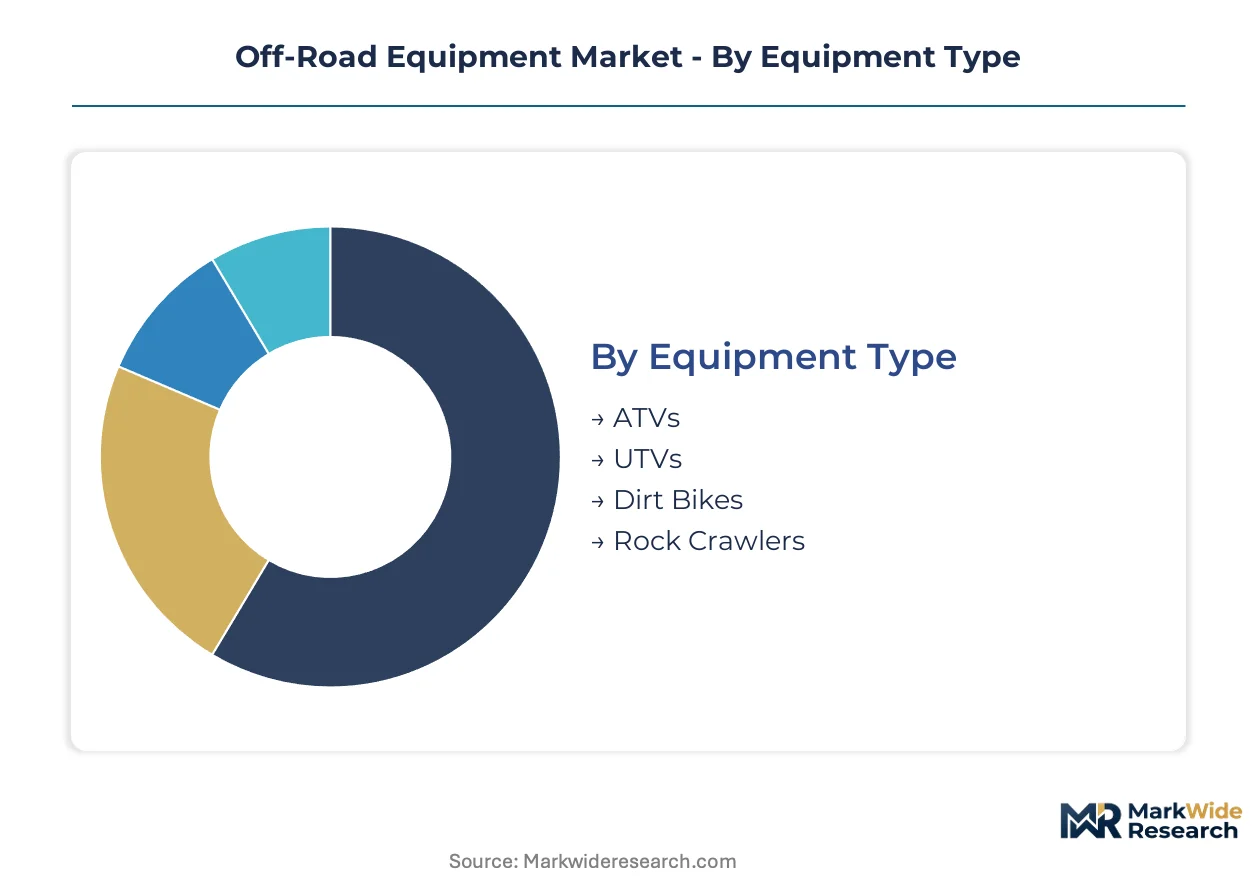
Off-road equipment manufacturers configure product portfolios across four intersecting dimensions that determine pricing power, distribution channels, and regulatory exposure. Equipment type and fuel type classifications drive the steepest margin differentiation, while application and end-user segments dictate service-network density and financing structures.
Equipment Type:
Customization intensity varies from mass-produced recreational units to purpose-built mining haulers with site-specific modifications.
- ATVs:Compact four-wheeled vehicles with rigid suspensions and sub-500cc engines dominate recreational trail riding and light utility work on farms. Demand concentrates in North American rural properties where landowners maintain fencing and transport supplies across uneven terrain. EPA emissions compliance for small spark-ignition engines adds certification overhead that squeezes margin on entry-level models.
- UTVs:Side-by-side configurations with bench seating and cargo beds command premium pricing through contractor-grade durability specifications. European construction zones with urban diesel bans are pulling battery-electric UTV variants into municipal maintenance fleets ahead of total cost parity.
- Dirt Bikes:Lightweight two-wheeled machines with long-travel suspension and high-power-to-weight ratios serve competitive motocross and off-trail recreation. Japanese manufacturers anchor global production through JIS standards compliance and racing-derived technology transfer.
- Rock Crawlers:Highly modified vehicles with locked differentials and ultra-low gearing address extreme terrain navigation for enthusiast segments. Aftermarket parts ecosystems in the United States sustain niche builders with limited OEM competition.
Most installed capacity flows through UTVs. Expansion is steepest in electric ATV configurations.
Application:
Volume distribution tracks infrastructure investment cycles and seasonal agricultural patterns across end-use verticals.
- Construction:Earthmoving and material handling operations require reinforced frames and ground clearance exceeding 250 millimeters to navigate unpaved job sites. Australian mining contractors are expanding autonomous haul truck fleets to compress pit-to-crusher cycle times in 24-hour operations.
- Agriculture:Precision farming integration with GPS-guided implements and variable-rate application systems is optimizing input efficiency across North American operations. Deere & Company anchors this segment through R&D intensity in connected off-road machinery platforms.
- Recreation:Trail riding and competitive racing drive discretionary spending on performance upgrades and aftermarket accessories. ATV and UTV equipment types dominate this margin pool through brand loyalty and dealer experience investments.
- Landscaping:Municipal and commercial grounds maintenance demands compact footprint machines with low ground pressure for turf protection. Battery-electric configurations are gaining traction in European urban zones with strict noise and emissions restrictions.
Construction absorbs the highest absolute unit volume. Landscaping applications are climbing the fastest as urban greening initiatives accelerate.
End User:
Procurement sophistication ranges from individual cash purchases to fleet-level telematics-enabled equipment-as-a-service contracts.
- Contractors:Mid-size construction and earthmoving firms are displacing traditional ownership models through rental channel digitization with utilization tracking dashboards. Telematics platforms aggregate machine health data and service technician dispatch into unified procurement workflows.
- Farmers:Owner-operators prioritize total cost of ownership and dealer service network density over acquisition price. Precision agriculture retrofits on existing off-road platforms extend equipment lifecycles while improving input efficiency.
- Recreational Users:Individual consumers respond to brand heritage and racing sponsorship visibility with high accessory attachment rates. Financing penetration remains lower than commercial segments due to discretionary purchase timing.
- Municipalities:Public sector procurement favors domestic content requirements and multi-year service contracts with predictable operating cost structures. EU Stage V urban diesel bans are accelerating battery-electric specifications in European city fleets.
Contractor fleets represent the largest revenue concentration. Municipal procurement is expanding most quickly as infrastructure stimulus programs deploy.
Fuel Type:
Powertrain selection determines regulatory compliance pathways and total cost of ownership trajectories across operating environments.
- Gasoline:Spark-ignition engines dominate recreational and light utility segments where power density and refueling convenience outweigh efficiency considerations. Small-engine emissions standards from EPA constrain product development timelines for carbureted architectures.
- Diesel:Compression-ignition powertrains anchor heavy-duty construction and mining applications through torque delivery and fuel energy density. After-treatment systems for EPA Tier 4 Final and EU Stage V compliance add 15-25% to engine bill-of-materials.
- Electric:Battery-electric architectures are overtaking diesel-electric hybrids as the dominant zero-emission configuration for sub-50-ton categories. Charging infrastructure gaps at rural construction sites and remote mining locations constrain fleet conversion timelines.
- Hybrid:Diesel-electric and gasoline-electric systems offer transitional efficiency gains without full grid dependency. Intermittent load cycles in construction applications complicate thermal management for catalyst temperature maintenance in parallel hybrid configurations.
Diesel retains the largest installed base. Electric powertrains are gaining share fastest as urban emissions restrictions proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled mining equipment operators and autonomous systems engineers concentrate in Australia and Chile, anchoring demand for heavy haulage platforms. Construction equipment technicians cluster in Germany and the United States, supporting fleet modernization cycles. Agricultural machinery specialists dominate the Midwestern United States and Punjab regions, driving precision farming retrofits.
Australia
Mining contractors in Western Australia and Queensland are expanding autonomous haul truck fleets to compress pit-to-crusher cycle times in 24-hour operations. The country's Work Health and Safety Act mandates falling-object protective structures compliant with ISO 3449 standards. Perth anchors the largest concentration of autonomous mining technology deployment, with Rio Tinto and BHP operating fully driverless haulage corridors.
Germany
Construction equipment manufacturers face EU Stage V urban diesel bans pulling battery-electric excavators into municipal fleets ahead of total cost parity. The KBA enforces type-approval processes extending 18-24 months for new powertrain architectures. Bavaria hosts the densest cluster of engine manufacturing and exhaust after-treatment development, with suppliers co-locating near Munich and Stuttgart.
United States
EPA Tier 4 Final compliance deadlines are compressing product development cycles for construction and agriculture equipment serving North American buyers. OSHA workplace safety requirements constrain design flexibility for falling-object protective structures. Illinois and Iowa anchor precision agriculture R&D intensity, with Deere & Company integrating GPS-guided implements across connected off-road machinery platforms.
China
MIIT technology mandates are reshaping product development timelines for domestic equipment manufacturers serving infrastructure buildout demand. The country's national emissions regulator enforces technology mandates that accelerate electric powertrain substitution in contractor fleets. Shandong Province concentrates compact excavator and wheel loader manufacturing, with Sany Heavy Industry and local suppliers scaling battery-electric configurations for urban construction zones.
Chile
Copper mining operations in the Atacama Desert are deploying autonomous haulage systems to reduce labor costs in remote, high-altitude extraction environments. The country's national mining regulator enforces workplace safety standards aligned with ISO certifications for heavy equipment operation. Antofagasta anchors the largest autonomous mining truck fleet in South America, with contractors retrofitting existing pits for 24-hour driverless operations.
Off-Road Equipment Market Competitive Environment
The competitive structure tilts toward vertically integrated engine manufacturers with captive compliance capabilities and autonomous systems specialists with robotics expertise. Tier-1 conglomerates with construction, mining, and agriculture divisions dominate absolute revenue concentration. Mid-scale regional fabricators compete on price-sensitive compact equipment categories. The dominant competitive moves involve strategic partnerships between engine suppliers and battery pack assemblers, plus geographic expansion into India's highway and irrigation infrastructure buildout.
Among diversified industrial conglomerates, Caterpillar, Deere & Company, and Komatsu Ltd occupy positions exemplifying distinct strategic archetypes. Caterpillar represents backward integration into engine manufacturing to sustain compliance leadership across heavy-duty product lines. Deere & Company anchors precision agriculture integration through R&D intensity in connected off-road machinery platforms. Komatsu Ltd exemplifies autonomous haulage technology leadership in mining applications, with its position concentrated in Australian and Chilean pit-to-crusher operations.
| Leading Market Players |
|---|
| CNH Industrial N.V |
| Liebherr Group |
| Caterpillar |
| Volvo Construction Equipment |
| Hitachi Construction Machinery |
| Deere & Company |
| Kubota Corporation |
| Sany Heavy Industry |
| Komatsu Ltd |
| Others |
Value Chain & Pricing Dynamics
EU Stage V urban diesel bans gate qualified supply for premium-tier electric excavators and wheel loaders, compressing margins on conventional diesel platforms while elevating pricing power for battery-electric configurations with certified fast-charging compatibility. Contractors in European construction zones face step-function cost increases for emissions-compliant machinery, redirecting procurement toward bundled service contracts that internalize after-treatment maintenance and residual value risk.
Pricing Analysis
Bundled equipment-as-a-service contracts are displacing unbundled transactional sales among mid-size contractors seeking predictable operating cost structures. Three-tier pricing structure across premium, standard, and economy levels separates autonomous-ready mining haulers from telematics-enabled construction units and bare recreational ATVs. Price differentiation hinges on certification grade for EPA Tier 4 Final and EU Stage V compliance, plus geographic delivery cost to remote job sites. Cost compression in mid-horsepower diesel equipment is intensifying because after-treatment systems add 15-25% to engine bill-of-materials. Municipal procurement teams exhibit highest price sensitivity due to fixed budget cycles, while Australian mining contractors show lowest sensitivity given 24-hour operational uptime requirements.
Supply Chain Analysis
Lithium-ion cell production rests on Chinese battery pack assemblers, South Korean cathode material specialists, and Australian hard-rock lithium miners. Engine manufacturing draws from German exhaust after-treatment developers, Japanese precision component suppliers, and North American steel foundries. Supply chain risk centers on single-source vulnerability for high-nickel cathode chemistries subject to geopolitical export restrictions. Distribution runs through OEM-owned dealer networks for contractor-grade equipment, direct-to-consumer online channels for recreational units, and rental platform intermediaries for short-cycle construction deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Off-Road Equipment Market reads as a late-cycle quality story where contractor fleet replacement cycles favor premium specifications with embedded telematics and emissions compliance certification. Precision agriculture retrofits and autonomous haulage upgrades are pulling demand toward connected platforms with software-enabled feature expansion.
For Market Incumbents: Deepen captive engine manufacturing capabilities to sustain EPA Tier 4 Final compliance leadership without margin erosion from external supplier markups. Expand autonomous systems engineering teams in Perth and Antofagasta to defend mining market share against robotics specialists entering haulage applications. Prioritize certification investment for EU Stage V battery-electric platforms ahead of urban diesel ban enforcement timelines. For New Entrants and Emerging Players: Enter via electric UTV configurations for European municipal maintenance fleets where incumbent dealer networks show coverage gaps in urban greening contracts. Target India's highway expansion corridor with motor graders and compactors in states with limited equipment penetration and price-sensitive procurement. Pursue joint-venture go-to-market angles with domestic fabricators to navigate BIS certification requirements and state-level tender processes. For Investors and Strategic Acquirers: Roll-up economics work for regional rental fleet operators because telematics platform standardization enables consolidated utilization tracking and cross-market parts inventory pooling. Five-to-ten year viability hinges on battery-electric platform conversion rates in European construction zones. Watch hydrogen fuel cell stack cost curves as the inflection signal for large mining truck electrification beyond tethered charging infrastructure reach.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cell offtake with CATL or LG Energy Solution secures electric platform production capacity ahead of competitor lock-up. |
| Autonomous Haulage Deployment | Perth corridor expansion with Rio Tinto validates 24-hour driverless operations for technology licensing to Chilean copper miners. |
| After-Treatment Modularization | SCR-DPF package standardization across construction product lines reduces EPA certification timeline compression penalties. |
| Rental Channel Digitization | Telematics-enabled equipment-as-a-service platforms displace traditional ownership models among North American mid-size contractors. |
| Precision Agriculture Integration | GPS-guided implement connectivity with Deere & Company platforms extends equipment lifecycle value for Midwestern farming operations. |
Study Parameters
Direct dialogue with mining operations managers, construction fleet procurement directors, agricultural equipment dealers, and autonomous systems engineers anchored qualitative findings in operational constraints and purchasing decision criteria. Secondary validation drew from EPA certification filings, EU type-approval databases, MIIT technology mandate disclosures, and customs trade records for engine and battery component flows. Bottom-up equipment shipment tallies by equipment type and fuel configuration were triangulated against top-down infrastructure investment forecasts and agricultural commodity price cycles.
Installed base projections and revenue estimates across the analysis window reflect segment-level modeling of replacement demand, fleet expansion rates, and powertrain substitution elasticities. Segmentation dimensions included equipment type, application vertical, end-user procurement sophistication, fuel architecture, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves for electric powertrain penetration and linear extrapolation of mining automation deployment timelines. Industry-specific forecast inputs incorporated copper price volatility effects on Chilean haul truck demand and European urban diesel ban phase-in schedules.
Inputs from OEM production disclosures, dealer inventory surveys, and mining contractor fleet announcements were available through the study window; gaps in autonomous systems utilization data and battery-electric total cost of ownership field results introduce uncertainty bands around electric substitution rate assumptions. Forecasts reflect documented assumptions regarding charging infrastructure buildout pace and after-treatment cost trajectory. Material deviation in copper prices, EU emissions enforcement timing, or lithium supply contract renegotiations warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
Electric Off-Road Vehicles Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
Off-Highway Vehicle HVAC Market
Off Road Vehicles
Off-Highway Wheels Market
Off Road Vehicles
Four-Wheel Drive Vehicles Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Global Electric Off-Highway Equipment Market
Off Road Vehicles
Off Highway Vehicles Brake Systems Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market