
 Amphibious ATV Market | 2026-2036
Amphibious ATV Market Size, Share, and Industry Trends Forecast 2026-2036
Amphibious ATV Market Outlook
Multi-source component procurement is consolidating as tier-one suppliers narrow their vendor lists to reduce qualification overhead. Argo leverages its North American manufacturing footprint to sustain defense contracts with standardized hull configurations. Sherp competes through extreme-terrain buoyancy systems that dominate Arctic and swamp deployment scenarios.
An amphibious ATV is a wheeled or tracked all-terrain vehicle engineered with sealed hull architecture and water propulsion capability, typically achieving amphibious transition without operator modification. These platforms incorporate corrosion-resistant aluminum or composite monocoque structures with tire inflation systems adjustable for varying substrate density, serving military logistics, agricultural access, and remote resource extraction where conventional vehicles fail. Utility ATV configurations anchor current revenue pools through forestry and agricultural deployment, while electric fuel type variants represent the fastest-growing segment as battery energy density improves for submerged-duty cycles. Military end user demand concentrates margin in institutional procurement channels with multi-year contract structures.
EPA off-road emission regulations and EU F-Gas refrigerant standards constrain internal combustion powertrain options, while ISO 5704 buoyancy safety protocols govern export market access for hull-certified manufacturers. Compliance cost dispersion favors scaled producers with dedicated homologation teams over regional assemblers. Stakeholders must monitor battery thermal management certification progress for electric amphibious platforms intended for defense and commercial deployment.
Market Dynamics
Defense procurement consolidation and EPA emission tightening are compressing powertrain options while elevating hull-certified manufacturers with dedicated compliance infrastructure over regional assemblers.
Growth Catalysts
- NATO Military Procurement:Multi-year defense contracts for all-terrain amphibious platforms are institutionalizing demand through standardized hull configurations and corrosion-resistant aluminum monocoque specifications.
- Battery Energy Density Gains:Lithium-ion cell improvements for submerged-duty cycles are enabling electric fuel type variants to penetrate forestry and agricultural deployment scenarios previously dominated by combustion engines.
- Federal Land Management Channels:United States resource extraction and remote access requirements are concentrating orders through defense contracting and federal procurement vehicles with multi-year structures.
Market Restraints
- EPA Tier 4 Final Compliance:Off-road emission regulations are eliminating small-displacement diesel powertrains and forcing costly aftertreatment integration for internal combustion variants.
- EU F-Gas Refrigerant Constraints:HVAC and thermal management system sourcing is narrowing as fluorinated gas restrictions limit supplier pools for climate-controlled cabin configurations.
- ISO 5704 Certification Overhead:Buoyancy safety protocol compliance requires dedicated homologation teams and extended testing cycles that disadvantage regional assemblers against scaled producers.
Strategic Opportunities
- Arctic Sovereignty Operations:Canada and Norway are expanding patrol requirements across thawing northern corridors where extreme-terrain buoyancy systems command premium positioning.
- Battery Thermal Management Certification:Early movers securing defense-grade validation for electric platforms will capture institutional procurement channels as NATO members electrify logistics fleets.
- Swamp Agricultural Mechanization:Southeast Asian palm oil and rice producers are adopting amphibious platforms for field access during monsoon cycles where conventional equipment cannot operate.
Industry Challenges
- Submerged Electronics Integration:Sealed hull architectures require specialized marine-grade wiring and connector expertise that sits outside traditional ATV engineering competencies.
- Multi-source Vendor Consolidation:Tier-one suppliers narrowing vendor lists are forcing component manufacturers to absorb qualification overhead without guaranteed volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amphibious ATV Market |
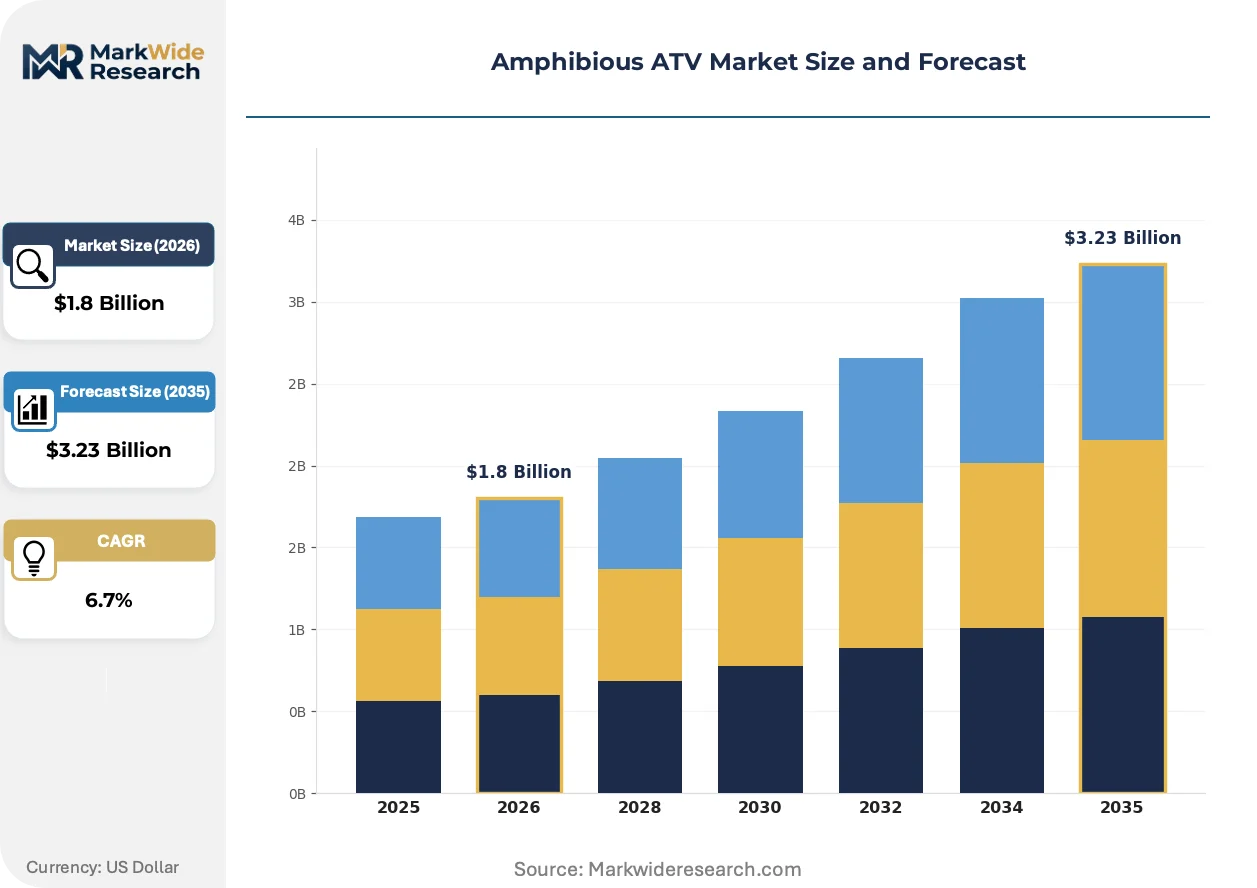
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Utility ATV, Sports ATV, Recreational ATV, Military ATV Fuel Type: Gasoline, Diesel, Electric, Hybrid End User: Agriculture, Military, Recreation, Forestry Deployment Model: Commercial, Residential, Institutional, Government |
| Companies Covered | Avtoros, Trekol, Recreatives Industries, Rusak, Atlas, Argo, Burlak, Ghe-O Systems, Sherp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amphibious ATV Market Strategic Shifts
Powertrain electrification, regulatory compliance automation, and defense procurement centralization are restructuring competitive advantage around certification depth and thermal management capability rather than raw terrain performance.
High-voltage battery architectures with integrated liquid cooling loops are rewriting the technical basis for amphibious platform endurance. Defense contractors in the United States are specifying these systems for submerged-duty logistics cycles exceeding four hours. This capability compression is marginalizing air-cooled combustion alternatives in institutional procurement channels.
EPA off-road emission standards and EU F-Gas Regulation are synchronizing compliance timelines across Atlantic supply chains. Manufacturers must now homologate powertrains for both jurisdictions simultaneously to maintain NATO interoperability contracts. Electric platforms face accelerated scrutiny as battery thermal runaway protocols become mandatory for hull certification under emerging ISO amendments.
Multi-year service contracts with performance guarantees are displacing transactional equipment sales in defense and federal land management channels. Buyers in the United States now demand availability metrics and depot-level maintenance inclusion rather than standalone platform procurement. This shift compresses margin for assemblers without captive service networks or forward-staged spare part inventories.
Amphibious ATV Market Segmentation
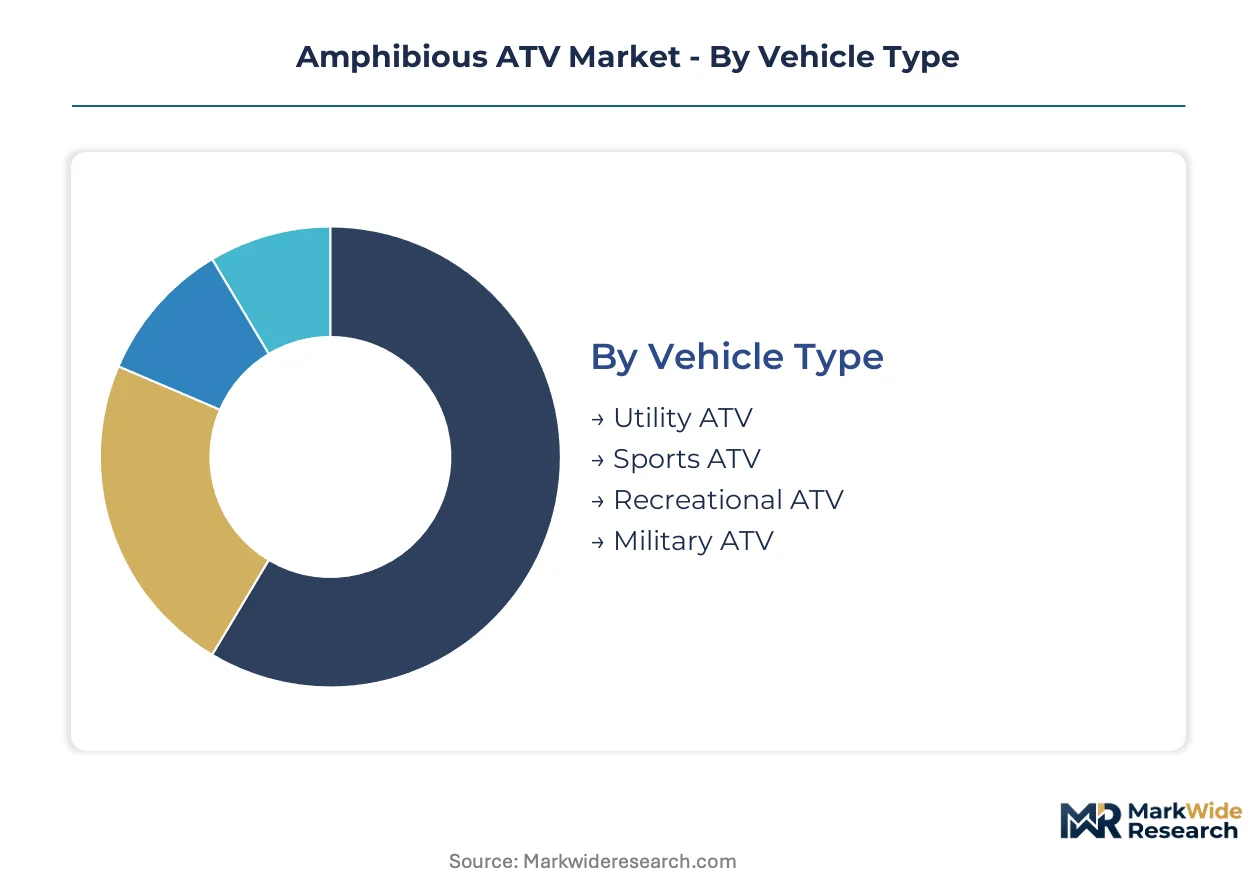
Amphibious ATV procurement splits sharply between institutional buyers with multi-year service contracts and transactional purchasers seeking standalone platforms. Segmentation reveals how hull certification requirements and powertrain compliance costs concentrate margin in specific configurations.
Vehicle Type:
Buyers in this category separate by duty cycle intensity and hull durability requirements rather than price sensitivity.
- Utility ATV:Aluminum monocoque hulls with adjustable tire inflation systems dominate forestry and agricultural deployment. Demand concentrates in United States federal land management channels where corrosion-resistant specifications anchor multi-year procurement structures.
- Military ATV:Sealed architectures with submerged-duty electronics integration command premium positioning. NATO member state procurement programs in Canada and Norway are expanding orders for extreme-terrain buoyancy systems across thawing Arctic corridors.
- Sports ATV:Lightweight composite hull configurations prioritize speed over payload capacity.
- Recreational ATV:Entry-level sealed designs serve leisure markets with limited submerged-operation requirements.
Utility ATV leads volumes today; Military ATV is gaining share fastest.
Fuel Type:
Powertrain selection hinges on emission compliance jurisdiction and submerged-duty cycle duration.
- Electric:High-voltage battery architectures with liquid cooling loops enable submerged-duty cycles exceeding four hours. Defense contractors in the United States are specifying these systems for logistics electrification as NATO members decarbonize fleet operations.
- Gasoline:Small-displacement internal combustion engines face EPA Tier 4 Final elimination pressures. Remaining demand clusters in price-sensitive recreational segments where aftertreatment costs prove prohibitive.
- Diesel:Compression-ignition powertrains retain foothold in heavy-load agricultural applications.
- Hybrid:Range-extended architectures bridge emission compliance and endurance requirements for remote resource extraction.
Gasoline retains installed base dominance; Electric exhibits steepest expansion trajectory.
End User:
Institutional versus commercial orientation determines service contract inclusion and availability metric requirements.
- Military:Multi-year defense contracts with depot-level maintenance inclusion displace transactional sales. Standardized hull configurations and NATO interoperability specifications consolidate procurement around certified manufacturers with dedicated homologation teams.
- Agriculture:Southeast Asian palm oil and rice producers are adopting platforms for monsoon field access. Swamp mechanization requirements in Indonesia and Malaysia concentrate orders in extreme-terrain buoyancy configurations.
- Forestry:Remote access demands in boreal regions favor corrosion-resistant aluminum structures.
- Recreation:Leisure buyers prioritize acquisition cost over submerged-duty certification depth.
Military commands highest margin per unit; Agriculture is expanding most quickly.
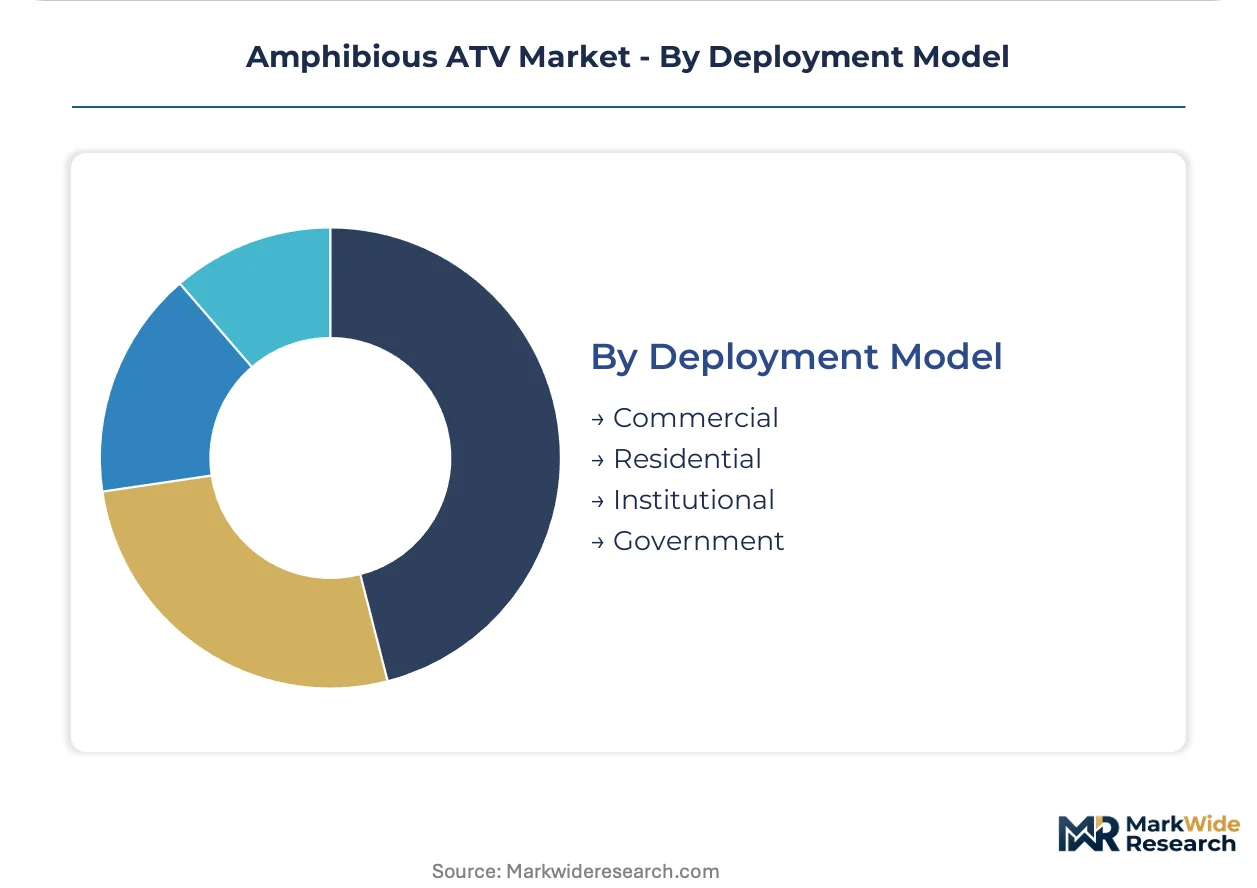
Deployment Model:
Ownership structure determines spare parts inventory obligations and forward-staging requirements.
- Government:Federal procurement vehicles in the United States demand performance guarantees and availability metrics. Defense contracting channels now require captive service networks rather than standalone platform delivery.
- Institutional:Universities and research stations specify hull-certified platforms for Arctic and wetland scientific access.
- Commercial:Resource extraction operators absorb qualification overhead through tier-one supplier consolidation.
- Residential:Individual buyers face ISO 5704 certification cost barriers that disadvantage scaled producers.
Government absorbs largest absolute spend; Commercial is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States defense contracting channels concentrate institutional procurement for hull-certified amphibious platforms with multi-year service structures. Federal land management programs in Alaska and the Pacific Northwest drive corrosion-resistant aluminum monocoque specifications. EPA Tier 4 Final emission standards eliminate small-displacement diesel options for domestic manufacturers.
United States
Department of Defense logistics electrification programs and Bureau of Land Management remote access contracts sustain standardized hull procurement. EPA off-road emission regulations force aftertreatment integration for combustion powertrains. Manufacturing clusters in Michigan and Wisconsin anchor defense contractor supply chains for NATO interoperability specifications.
Canada
Arctic sovereignty patrol expansion across thawing northern corridors generates extreme-terrain buoyancy system orders. Canadian Environmental Protection Act refrigerant standards align with EU F-Gas constraints for HVAC-equipped cabin configurations. Quebec and Ontario fabrication facilities serve domestic military procurement with corrosion-resistant aluminum structures.
Norway
Coastal ranger command modernization programs prioritize submerged-duty electronics integration for fjord and ice-edge operations. Norwegian Climate and Environment Agency emission targets accelerate fleet electrification timelines. Kongsberg-area defense contractors specify four-hour submerged endurance for logistics platform tenders.
Germany
Bundeswehr all-terrain vehicle replacement programs standardize NATO hull certification requirements across member state procurement. KBA type-approval processes for off-road emission compliance create qualification barriers for non-EU assemblers. Bavarian industrial clusters supply thermal management components for liquid-cooled battery architectures.
Australia
Resource extraction operators in Queensland and Western Australia adopt hybrid powertrains for remote site access during wet season flooding. Department of Agriculture biosecurity patrols in northern wetlands specify sealed hull configurations. Perth-based defense contractors integrate ISO 5704 buoyancy certification for export market access.
Amphibious ATV Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue extreme-terrain specialization with premium positioning. The vendor base stratifies across defense-certified manufacturers with dedicated homologation teams and regional assemblers facing ISO 5704 certification overhead. Three archetypes dominate: NATO interoperability specialists, Arctic buoyancy system developers, and agricultural mechanization providers. Competitive moves concentrate on battery thermal management certification capture and multi-year service contract bundling.
Within the extreme-terrain tier, Sherp and Argo exemplify divergent technical approaches to hull architecture and propulsion integration. Russian-origin manufacturers including Avtoros and Trekol occupy positions emphasizing large-displacement capability for resource extraction markets. Ghe-O Systems represents the European specialist archetype with Romanian-based fabrication serving defense and agricultural dual-use applications.
| Leading Market Players |
|---|
| Avtoros |
| Trekol |
| Recreatives Industries |
| Rusak |
| Atlas |
| Argo |
| Burlak |
| Ghe-O Systems |
| Sherp |
| Others |
Value Chain & Pricing Dynamics
Aluminum LME spot pricing volatility cascades through hull fabrication costs into three distinct procurement tiers, with NATO defense contractors absorbing premium monocoque specifications while Southeast Asian agricultural buyers face compressed margins on standardized configurations.
Pricing Analysis
Input-cost pass-through from marine-grade aluminum and lithium-ion cell suppliers stratifies pricing across certification-grade tiers. Three-tier pricing structure across premium, standard, and economy levels separates NATO-interoperable hull-certified platforms from regional assemblers lacking ISO 5704 validation. Pricing pressure stems from EPA Tier 4 Final aftertreatment integration costs that eliminate small-displacement diesel options. Recreational buyers exhibit highest price sensitivity, while military procurement channels prioritize availability metrics over unit economics.
Supply Chain Analysis
Reverse-logistics flows for depot-level maintenance and hull refurbishment concentrate in Michigan, Wisconsin, and Ontario fabrication clusters serving defense service contracts. Battery thermal management components draw from Bavarian industrial suppliers and South Korean cell manufacturers. Single-source vulnerability sits with specialized marine-grade wiring harness producers outside traditional ATV engineering networks. Distribution runs through tier-one defense contractors with captive service networks rather than independent dealer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EPA-regulated US manufacturing and EU F-Gas-constrained European assembly, with compliance cost differentials favoring North American hull-certified producers.
For Market Incumbents: Acquire battery thermal management certification capabilities ahead of NATO electrification mandates. Consolidate vendor lists to reduce qualification overhead as tier-one suppliers narrow approved component pools. Capture Arctic sovereignty patrol contracts in Canada and Norway through extreme-terrain buoyancy system investments.
For New Entrants and Emerging Players: Launch via swamp agricultural mechanization channels in Indonesia and Malaysia where ISO 5704 certification barriers remain lower than defense procurement. Target monsoon-season field access applications for palm oil and rice producers. Pursue joint development agreements with Southeast Asian plantation operators lacking submerged-duty equipment access.
For Investors and Strategic Acquirers: Asymmetric upside sits with hull-certified manufacturers possessing dedicated homologation teams and NATO interoperability validation. Long-term viability favors producers with integrated service networks and forward-staged spare part inventories. Monitor EPA battery thermal runaway protocol amendments as electrification inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Thermal Management Certification | Defense-grade validation captures NATO logistics electrification tenders requiring four-hour submerged endurance. |
| Arctic Buoyancy System Development | Extreme-terrain configurations command premium positioning across thawing northern corridors in Canada and Norway. |
| Multi-Year Service Contract Bundling | Performance guarantees displace transactional sales in US federal land management and defense contracting channels. |
| Vendor Consolidation Programs | Tier-one supplier list narrowing reduces qualification overhead for scaled producers with captive compliance teams. |
| Swamp Agricultural Mechanization Partnerships | Monsoon-cycle field access agreements in Southeast Asia open white-space beyond institutional procurement. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with defense procurement officers, federal land management fleet directors, agricultural plantation equipment managers, and hull certification engineers informed demand-side segmentation. Secondary sources include EPA emission compliance filings, EU F-Gas regulatory updates, NATO standardization agreements, and customs trade data for amphibious platform imports. Bottom-up unit economics triangulate against top-down defense budget allocation analysis.
Rate-of-change decomposition separates volume growth from price mix shifts across the projection horizon. Segmentation dimensions include vehicle type, fuel architecture, end-use application, and deployment ownership structure. CAGR derivation incorporates battery energy density improvement curves and regulatory compliance phase-in schedules. Submerged-duty cycle duration assumptions and hull certification penetration rates serve as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated NATO electrification timelines or aluminum supply disruption scenarios. Practitioners should monitor EPA battery thermal runaway protocol progress and Arctic sovereignty patrol budget announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Mining Vehicle Attachments Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
Global Automotive Off Highway Engine Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Electric Utility-Terrain Vehicle (UTV) Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
All-Terrain Vehicle Market
Off Road Vehicles
Off-Highway Electric Vehicle Market
Off Road Vehicles
Off-Highway Vehicle Engine Market
Off Road Vehicles
Off-Road Equipment Market
Off Road Vehicles
Snow Scooter Market