
 Off Highway Vehicle Lighting Market | 2026-2036
Off Highway Vehicle Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Off Highway Vehicle Lighting Market Intelligence
European-based manufacturers of off-highway vehicle lights are broadening their production capabilities to include advanced smart and adaptive lighting systems for global distribution. HELLA GmbH and Co. KGaA leverages its extensive automotive engineering background to develop sophisticated lighting for mining vehicles. J.W. Speaker Corporation differentiates its brand with a focus on premium, high-output LED work lights. Grote Industries sustains its market presence in North America through a deep channel partnership network.
Off-highway vehicle lighting encompasses illumination systems designed for vehicles not operated on public roads, such as those in agriculture and construction. These systems are engineered to withstand extreme vibration, dust ingress with ratings like IP67, and temperature fluctuations while providing critical visibility for safety. LED products now dominate the product type segment due to their longevity and efficiency, displacing older halogen technologies. Within applications, the construction machinery segment commands a significant share, while agricultural equipment represents a key area for technology upgrades to smart lighting.
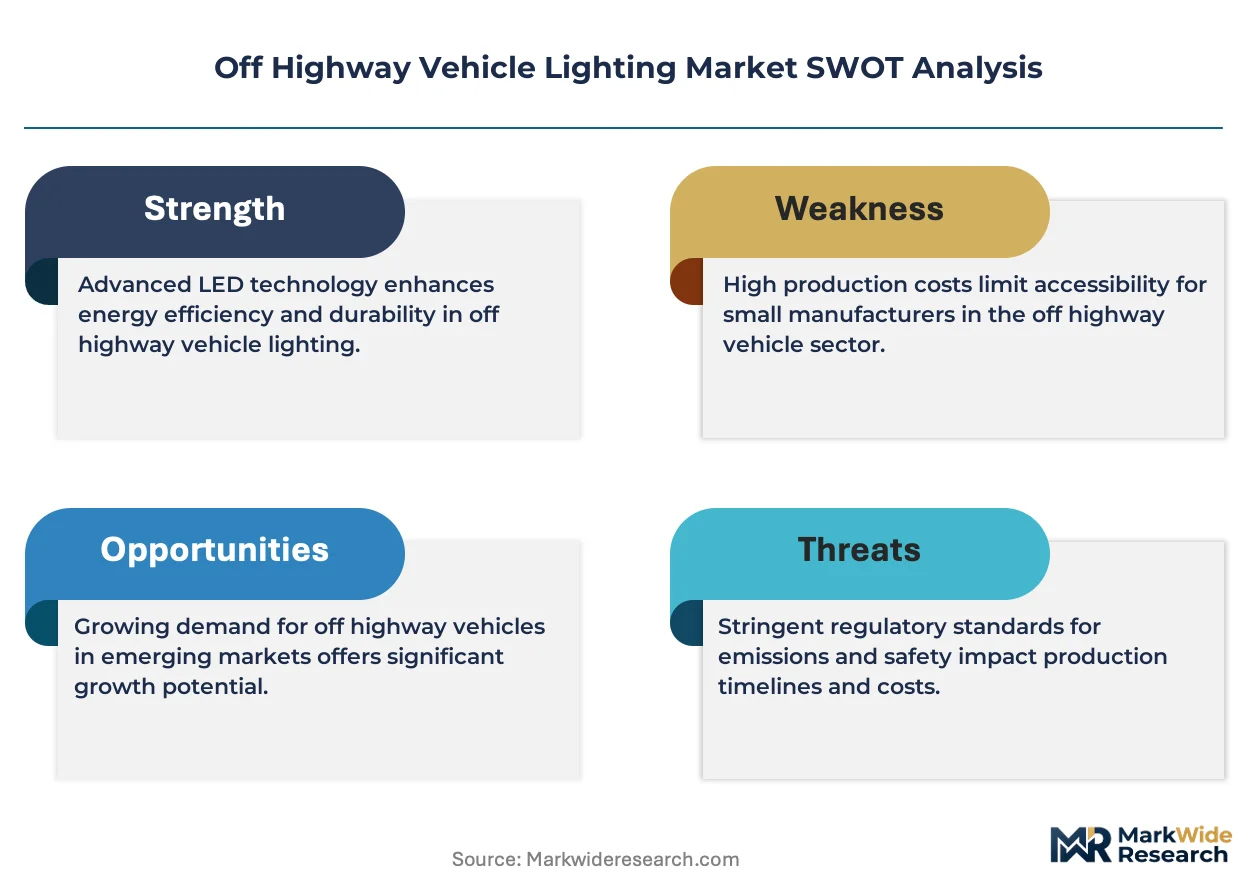
Product design and market access are governed by standards like the Economic Commission for Europe (ECE) regulations and specific performance criteria from organizations such as the American Society of Agricultural and Biological Engineers (ASABE). In the United States, OSHA guidelines on worksite illumination also influence equipment specifications for construction and mining vehicles. Future competitive advantage will hinge on integrating sensor-driven adaptive lighting technology that improves operator safety and operational efficiency.
Market Dynamics
The transition from halogen to solid-state LED technology is the central force shaping the off-highway vehicle lighting market. This shift is driven by demands from the agriculture and construction sectors for lighting systems with superior durability, energy efficiency, and longer operational lifespans in harsh environments.
Growth Catalysts
- Regulatory Mandates:Stricter ECE regulations and ASABE performance criteria for worksite visibility and operator safety are compelling equipment manufacturers to upgrade lighting components.
- LED Technology Advancement:Continuous improvements in lumen-per-watt efficacy and falling production costs for high-power LEDs make them economically viable replacements for legacy technologies across all equipment tiers.
- Precision Agriculture:The expansion of 24-hour farming operations requires powerful and reliable lighting, creating sustained demand from the agricultural equipment sector for both new and retrofit installations.
Market Restraints
- High Initial Cost:Advanced LED and smart lighting systems carry a significant price premium over conventional halogen lights, posing a budget barrier for smaller fleet owners and the cost-sensitive aftermarket segment.
- Component Sourcing:The supply chain for critical electronic components, including specific microcontrollers and high-power LED chips, exhibits geographic concentration, creating potential price volatility and supply risks.
- Legacy System Integration:Integrating modern, digitally controlled lighting with older vehicle electrical architectures can be complex, often requiring specialized harnesses and creating potential for electromagnetic interference with other onboard systems.
Strategic Opportunities
- Adaptive Lighting Systems:The convergence of sensor technology, such as cameras and radar, with LED lighting creates an opportunity for intelligent systems that dynamically adjust beam patterns in response to terrain or obstacles.
- Aftermarket Retrofit Kits:A large installed base of older construction and agricultural vehicles with halogen lighting represents a significant, underpenetrated market for pre-configured LED upgrade kits that simplify installation.
- Autonomous Vehicle Illumination:Developing specialized lighting solutions designed to optimize machine vision and sensor perception for autonomous haul trucks and tractors is a key area for future product development.
Industry Challenges
- Harsh Environment Durability:Ensuring lighting systems can consistently withstand extreme shock, vibration, and temperature swings in mining and construction environments requires rigorous and expensive validation testing to achieve high IP ratings.
- Protocol Standardization:The lack of a common communication standard for smart lighting across different heavy equipment OEMs complicates development and limits interoperability for mixed-fleet managers.
- EMI Shielding Complexity:High-intensity LED systems can generate electromagnetic interference that disrupts sensitive vehicle electronics, requiring sophisticated shielding and circuit design to ensure operational safety and compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off Highway Vehicle Lighting Market |
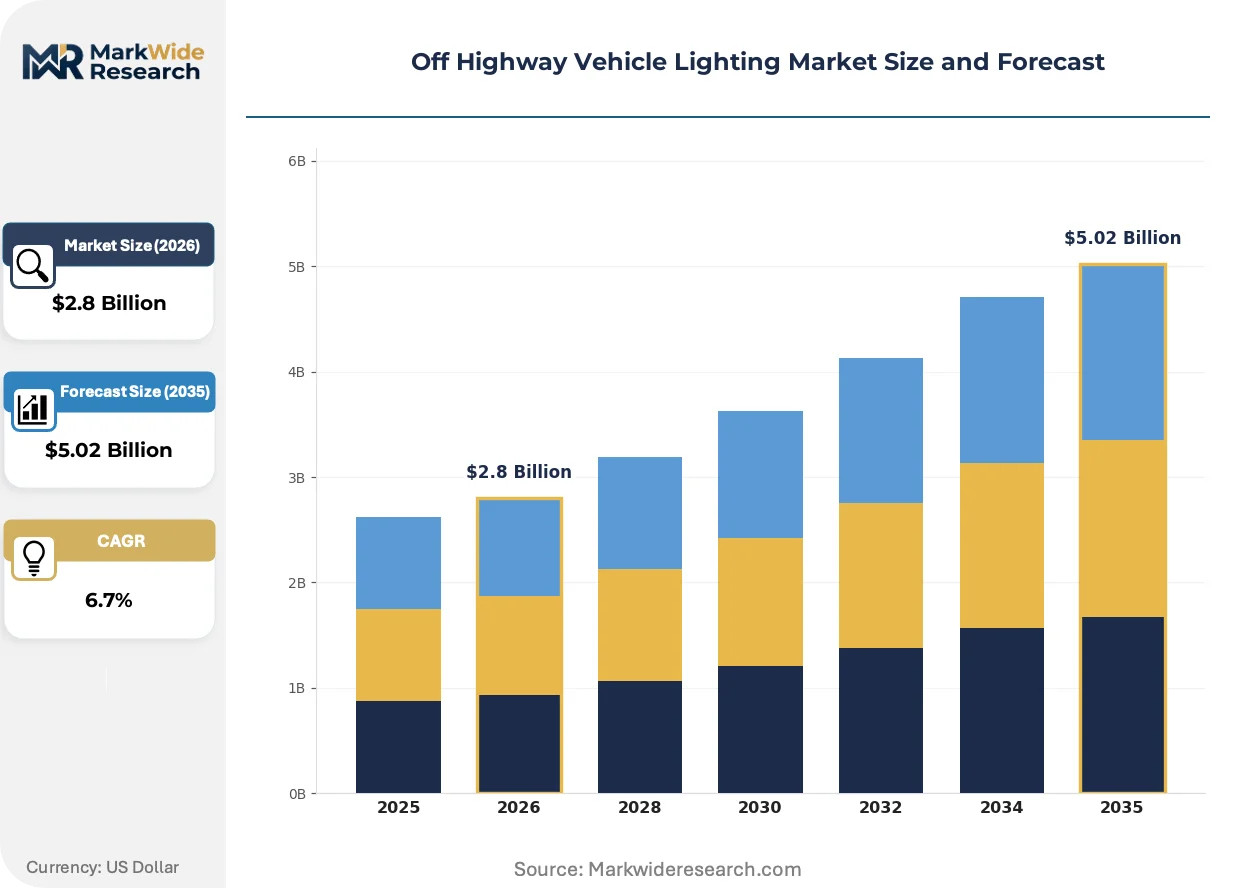
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, HID, Incandescent Application: Agricultural Equipment, Construction Machinery, Mining Vehicles, Forestry Vehicles Mount Type: Fixed Mount, Magnetic Mount, Portable Mount, Adjustable Mount Technology: Smart Lighting, Traditional Lighting, Adaptive Lighting, Emergency Lighting |
| Companies Covered | Peterson Manufacturing Co., WESEM, Truck-Lite, Hamsar Diversco Inc., APS Lighting and Safety, Grote Industries, J.W. Speaker Corporation, ABL Lights Group, HELLA GmbH and Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off Highway Vehicle Lighting Market Strategic Shifts & Innovations
Intelligent systems are redefining vehicle illumination, moving beyond basic visibility toward integrated solutions that enhance operational data and operator safety. This evolution is driven by advancements in digital controls, new regulatory pressures, and changing procurement models among fleet operators.
Smart lighting controllers represent a key product evolution. Large-scale mining and agricultural fleets are the primary adopters, seeking greater control over worksite illumination. This technology is decentralizing lighting control from a central switch to individual, addressable light heads, enabling dynamic beam shaping and task-specific illumination zones.
United States OSHA guidelines for worksite illumination directly influence equipment specifications. These rules mandate minimum light levels for safety, pushing demand for higher-lumen-output fixtures that provide broad, even coverage. The construction machinery segment is most impacted, with OEMs increasingly specifying powerful LED work light packages to ensure compliance.
A notable behavioral change is the move from buying individual components to specifying fully integrated lighting systems. This disrupts the parts-focused aftermarket channel, as large fleet operators now prefer suppliers who can guarantee system-level performance and compatibility. This pattern is especially prominent within North American agriculture, where minimizing equipment downtime is a primary concern.
Off Highway Vehicle Lighting Market Segmentation
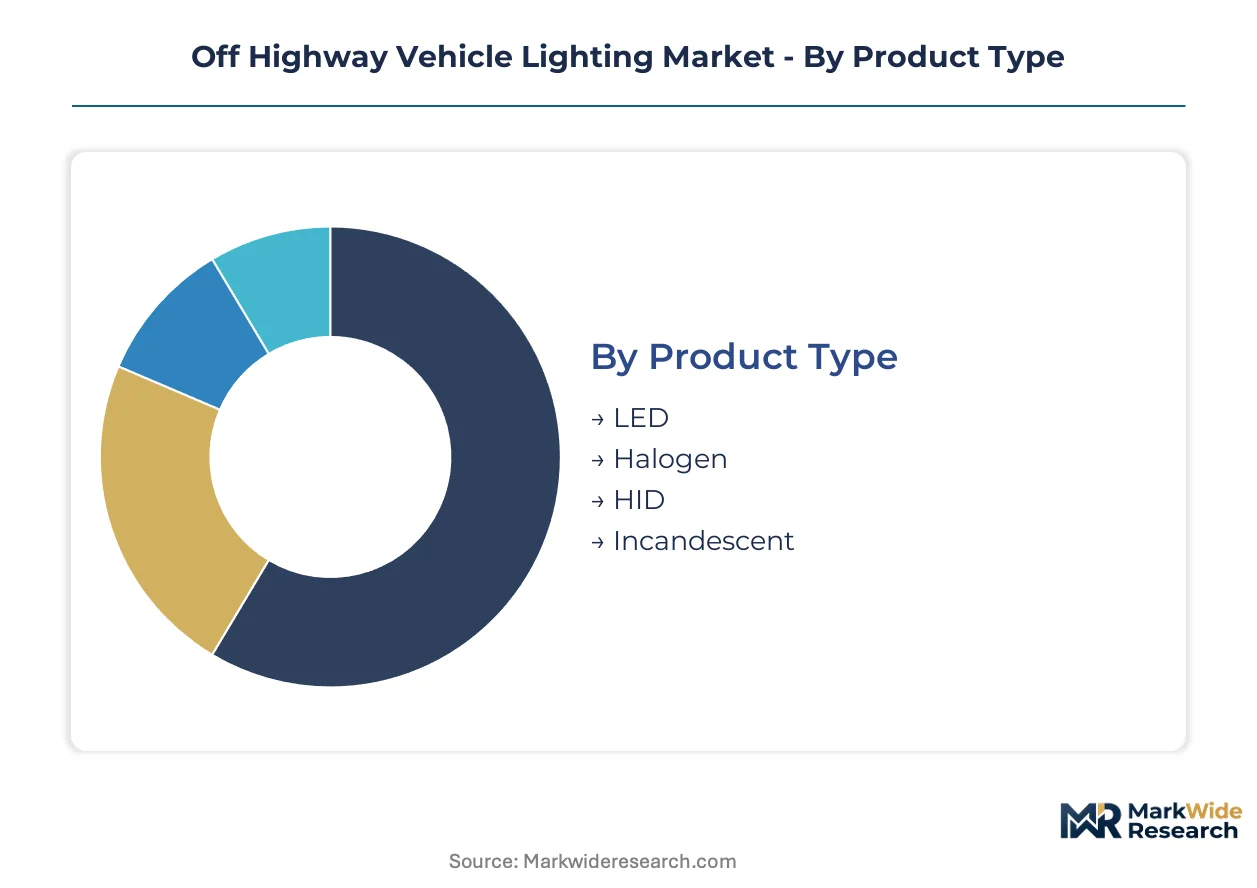
Understanding the off-highway vehicle lighting market through its segmentation reveals the specific technological shifts and application demands driving industry evolution. Each segment reflects unique operational requirements, durability standards, and integration complexities for specialized vehicles.
Product Type:
Supply concentration in advanced component manufacturing significantly influences the product type offerings within off-highway vehicle lighting, dictating performance and cost structures.
- LED:These lighting systems utilize light-emitting diodes, offering superior energy efficiency, extended lifespan, and extreme durability against vibration and shock. Demand concentrates in the agricultural and construction sectors, driven by requirements for continuous operation and reduced maintenance in North America and Europe.
- Halogen:Featuring a tungsten filament encased in a halogen gas-filled bulb, these lights provide warm, broad illumination at a lower initial cost. Their displacement by more efficient technologies is accelerating, though they retain a presence in cost-sensitive aftermarket segments and older vehicle fleets.
- HID:High-Intensity Discharge lights produce intense white light through an electrical arc between two electrodes within a gas-filled quartz capsule. They offer higher lumen output than halogen but are less energy-efficient and durable than modern LEDs.
- Incandescent:Traditional incandescent bulbs use a heated filament to produce light, representing the oldest and least efficient lighting technology in this market. Their use is largely confined to legacy systems and very basic, low-cost applications due to poor durability and high power consumption.
Today's leader: LED. Tomorrow's challenger: HID.
Application:
The varied operational environments dictate distinct lighting requirements, influencing product specifications and market demand across diverse off-highway vehicle applications.
- Construction Machinery:Lighting systems for construction equipment must withstand severe impacts, dust ingress, and constant vibration, providing critical illumination for safe operation on dynamic worksites. Demand is strong in the United States, propelled by infrastructure projects and OSHA illumination guidelines.
- Agricultural Equipment:These lighting solutions support extended operating hours and precision tasks, requiring robust, wide-area illumination to enhance visibility during night-time planting and harvesting. The transition to 24-hour farming operations in the Midwest United States creates sustained demand for powerful and reliable systems.
- Mining Vehicles:Lighting for mining operations requires extreme durability, high lumen output, and often specialized beam patterns for underground or low-visibility conditions. These systems must meet stringent safety regulations and withstand corrosive environments.
- Forestry Vehicles:Illumination for forestry equipment needs to endure harsh outdoor conditions, including impacts from branches and exposure to moisture, while providing clear visibility in dense, uneven terrain.
Agricultural equipment applications are expanding most quickly, driven by the need for 24-hour operations.
Mount Type:
Mount type differentiation stems from the need for installation flexibility and environmental resilience, ensuring lights remain secure and functional across diverse vehicle types and operating conditions.
- Fixed Mount:These lights are permanently bolted or integrated into the vehicle's structure, offering maximum stability and durability against extreme vibrations and impacts. Demand for fixed mount solutions is foundational across all off-highway vehicle types, ensuring robust, long-term illumination.
- Magnetic Mount:Utilizing powerful magnets for attachment, these lights provide flexible positioning and easy removal, suitable for temporary lighting needs or retrofitting. This mount type gains traction in the aftermarket for construction and agricultural vehicles in Europe, offering adaptability without permanent installation.
- Portable Mount:Designed for easy transport and temporary placement, portable lights often include handles or stands, providing illumination where vehicle-mounted options cannot reach. These are frequently used for auxiliary tasks or emergency situations.
- Adjustable Mount:Featuring swiveling or tilting mechanisms, adjustable mounts allow operators to direct light precisely where needed, optimizing visibility for specific tasks or changing work environments.
Fixed mount solutions remain dominant, while magnetic mount options are climbing the fastest for versatility.
Technology:
Technology segmentation showcases the evolution from basic illumination to integrated intelligence, with advanced systems enhancing both safety and operational efficiency.
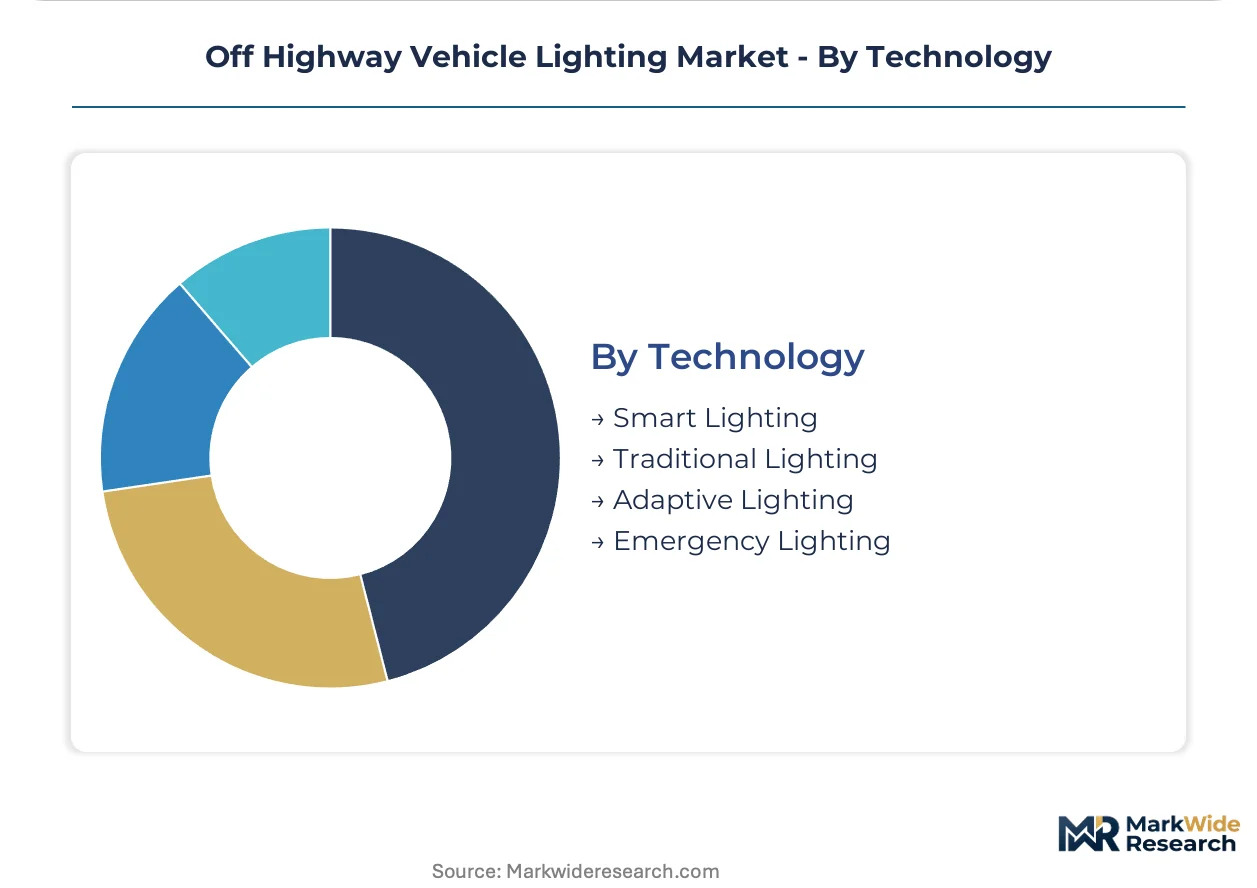
- Smart Lighting:These systems incorporate sensors and digital controls to dynamically adjust light output, beam patterns, and color temperature based on ambient conditions or operational needs. Large-scale mining and agricultural fleets in Australia are primary adopters, seeking optimized worksite illumination and data integration.
- Adaptive Lighting:Adaptive lighting actively responds to real-time inputs, such as vehicle speed, steering angle, or detected obstacles, to automatically modify light distribution and intensity. This technology enhances operator safety and situational awareness, particularly in complex construction environments.
- Traditional Lighting:This segment includes basic, manually controlled lighting systems without advanced sensors or digital interfaces, primarily comprising older halogen and incandescent technologies. Traditional lighting remains prevalent in older vehicle fleets and cost-sensitive segments.
- Emergency Lighting:Dedicated to warning and safety, emergency lighting includes flashing beacons, strobe lights, and warning lamps, essential for indicating vehicle presence or hazardous conditions. These systems are critical for compliance with worksite safety regulations.
Smart lighting technologies are gaining share fastest, propelled by integration with vehicle automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage influences off-highway vehicle lighting production decisions, as manufacturers seek optimal compliance costs and market access. Companies evaluate differing regional standards for worksite visibility and product durability. This strategic assessment drives investment in specific geographic locations, balancing market proximity with operational efficiency.
United States
The United States drives significant demand for off-highway vehicle lighting, particularly for modernizing farming and construction fleets. OSHA guidelines on worksite illumination and ASABE performance criteria compel equipment manufacturers to upgrade lighting components. The Midwest United States shows concentrated demand for powerful and reliable systems, supporting 24-hour farming operations.
Germany
Germany represents a hub for European-based manufacturers broadening production capabilities to include advanced smart and adaptive lighting systems. Stricter ECE regulations mandate higher performance standards for vehicle lighting, influencing product development. Companies like HELLA GmbH leverage their engineering background in German industrial centers to develop sophisticated lighting solutions.
Australia
Australia demonstrates strong adoption of smart lighting technologies, particularly within large-scale mining and agricultural fleets. Stringent safety regulations in Australian mining operations necessitate high lumen output and specialized beam patterns for low-visibility conditions. Mining regions across Western Australia are primary adopters, seeking optimized worksite illumination and data integration.
India
India's expanding agricultural sector and infrastructure development fuel demand for durable and energy-efficient off-highway vehicle lighting. Local safety standards for construction and agricultural equipment guide product specifications and market entry. Manufacturing clusters in states like Maharashtra are developing production capabilities for robust lighting systems to meet domestic requirements.
Off Highway Vehicle Lighting Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue advanced smart and adaptive lighting systems. The market exhibits a tiered structure, with specialists focusing on premium, high-output LED solutions. Strategic archetypes include integrated system providers, component manufacturers, and niche aftermarket suppliers. Companies engage in portfolio diversification and geographic expansion to capture market share.
On the premium-tier vector, J.W. Speaker Corporation exemplifies a focus on high-output LED work lights, catering to specialized performance demands from discerning operators. Grote Industries, a North American entity, represents a strong regional presence through its deep channel partnership network, serving a broad aftermarket base. HELLA GmbH and Co. KGaA, a German-based firm, occupies a position leveraging its extensive automotive engineering background to develop sophisticated lighting for demanding applications, particularly in mining vehicles globally.
| Leading Market Players |
|---|
| Peterson Manufacturing Co. |
| WESEM |
| Truck-Lite |
| Hamsar Diversco Inc. |
| APS Lighting and Safety |
| Grote Industries |
| J.W. Speaker Corporation |
| ABL Lights Group |
| HELLA GmbH and Co. KGaA |
| Others |
Cost & Logistics Intelligence
Large-scale mining and agricultural fleets drive a value-based pricing model in off-highway vehicle lighting. Their demand for integrated systems shifts procurement away from component-level transactions.
Pricing Analysis
Direct-to-OEM discounts significantly influence pricing dynamics for off-highway vehicle lighting systems. Contract-based long-term agreements for integrated systems dominate OEM procurement. Performance specifications like IP ratings and lumen output, alongside after-sales service, drive premium pricing. Component sourcing for high-power LEDs creates cost volatility. Smaller fleet owners and the aftermarket segment exhibit high price sensitivity, favoring halogen alternatives.
Supply Chain Analysis
Logistics and freight costs significantly impact the final price of off-highway vehicle lighting, particularly for specialized components. Component manufacturing for high-power LED chips concentrates in China and parts of Southeast Asia. Germany contributes advanced optical and control system components. The industry relies heavily on specific microcontrollers and high-power LED chips. Geographic concentration of these critical electronic components creates potential price volatility and supply risks. Distribution primarily runs through direct-to-OEM channels for new equipment and regional channel partners for the aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The off-highway vehicle lighting market acts as a stable compounder, driven by the ongoing transition from traditional halogen to advanced LED technology. This shift ensures sustained demand for durable and energy-efficient illumination systems.
For Market Incumbents: Deepen integration with key OEM partners to secure long-term supply contracts for advanced lighting systems. Invest in R&D for adaptive lighting to counter emerging specialized entrants offering niche smart solutions. Leverage extensive automotive engineering expertise for complex mining vehicle applications. Expand production capabilities for smart and adaptive systems to maintain market share against new technologies.
For New Entrants and Emerging Players: Launch via specialized e-commerce platforms targeting the aftermarket retrofit segment. Focus on developing smart lighting solutions for smaller agricultural fleets seeking efficiency upgrades. The aftermarket for older construction and agricultural vehicles with halogen lighting remains a penetrable segment. Offer pre-configured LED upgrade kits that simplify installation for cost-sensitive buyers.
For Investors and Strategic Acquirers: Heavy equipment OEMs are the most active acquirers in this space, seeking to internalize advanced lighting capabilities. The market offers sustained growth over the next five to ten years due to continuous technological upgrades and regulatory pushes. Focus on niche specialists in adaptive lighting or integrated sensor-driven systems. A key signal to watch is increased M&A activity for companies with strong IP in machine vision optimization.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Adaptive Lighting Platforms | Enhances operator safety and efficiency in complex construction environments. |
| Expand Aftermarket Retrofit Kit Offerings | Captures a large installed base of older agricultural and construction vehicles. |
| Invest in Autonomous Vehicle Lighting R&D | Optimizes machine vision and sensor perception for future autonomous haul trucks. |
| Strengthen Channel Partnerships in North America | Grote Industries maintains market presence through deep regional distribution networks. |
| Secure Long-term OEM Supply Agreements | HELLA GmbH leverages automotive engineering for sophisticated mining vehicle lighting. |
Research Approach
Bottom-up agricultural equipment and construction machinery modeling reconciled against top-down LED component supply tracking forms the analytical core of this study. This approach combined primary interviews with product development executives, fleet managers, and procurement leads, alongside extensive secondary validation. Engaged stakeholders included OEM engineers, aftermarket distributors, agricultural equipment operators, and mining safety officers. Secondary sources comprised ECE regulations, ASABE performance criteria, OSHA guidelines, and industry association reports.
Historical trendline analysis established foundational growth trajectories across the off-highway vehicle lighting market. The quantitative framework projects market evolution across the analysis window, considering various segmentation dimensions. Segmentation included product type, application, mount type, technology, and regional adoption patterns. Compound annual growth rates were derived from projected market values and volumes, incorporating infrastructure spending forecasts and agricultural equipment sales data.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events and rapid shifts in raw material commodity prices. Forecasts reflect assumptions regarding technological adoption rates and regulatory stability. Disruptions to global supply chains or sudden changes in regional infrastructure investments could revise projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Off-Highway Engine Market
Off Road Vehicles
US Off-Road Vehicles Market
Off Road Vehicles
Global Off-Highway Vehicle Telematics Market
Off Road Vehicles
Off-Highway Vehicle Engine Market
Off Road Vehicles
Off-Highway Wheels Market
Off Road Vehicles
Off Highway Hybrid Vehicles Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
Off Highway Vehicles Brake Systems Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market
Off Road Vehicles
All-Terrain Vehicle (ATV) Engines Market
Off Road Vehicles
Global Automotive Off Highway Engine Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Global Off-Road Trailers Market