
 All-Terrain Vehicle (ATV) Engines Market | 2026-2036
All-Terrain Vehicle (ATV) Engines Market Size, Share, and Industry Trends Forecast 2026-2036
All-Terrain Vehicle (ATV) Engines Market Outlook
North American engine manufacturing capacity is restructuring as domestic producers adapt to stricter emission benchmarks and shifting buyer preferences. Polaris Industries Inc. leverages its Minnesota-based vertical integration to control powertrain development for recreational and utility platforms. Honda Motor Co., Ltd. anchors the premium four-stroke segment through its Ohio assembly operations and established dealer density across the United States. Yamaha Motor Co., Ltd. competes on dual-sport engine architecture that spans ATV and motorcycle applications, sustaining R&D economies across product lines.
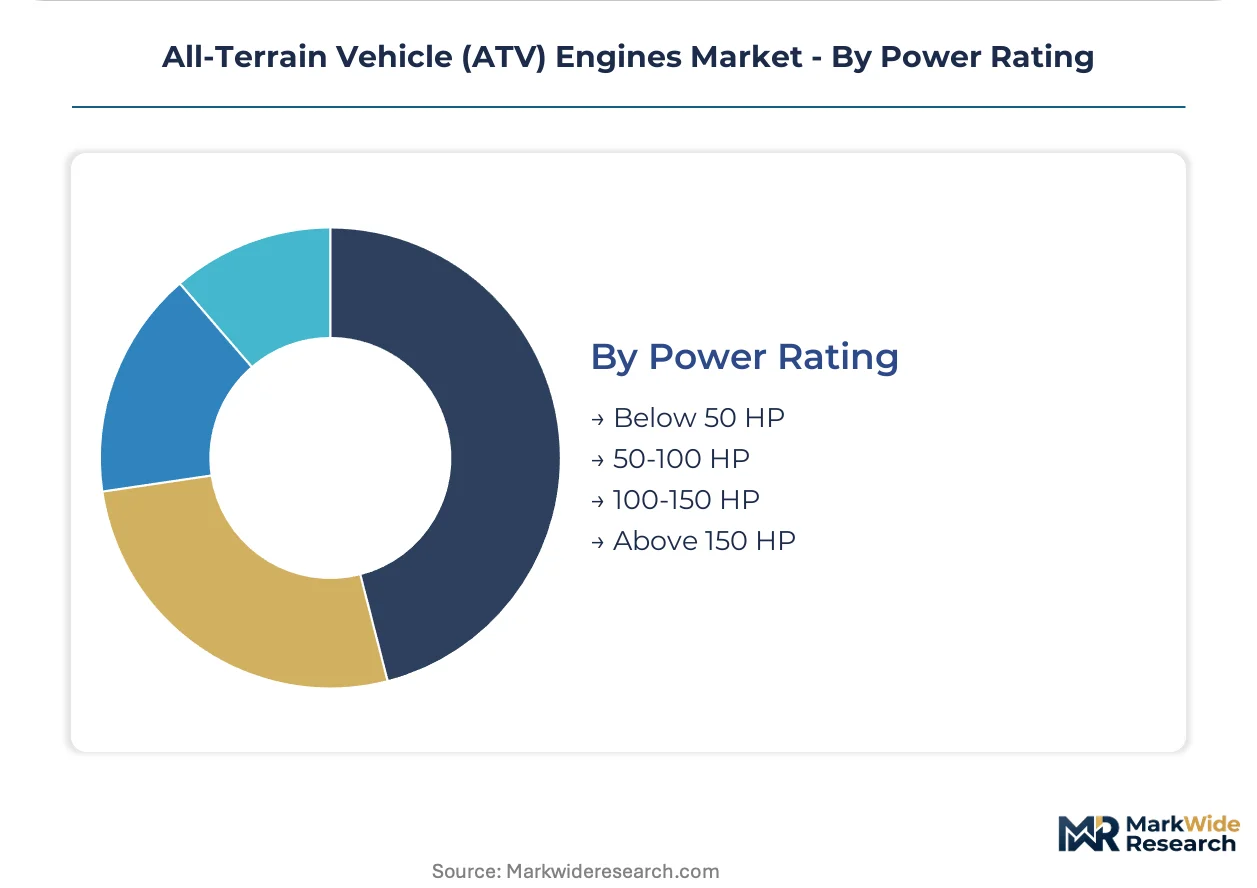
All-terrain vehicle engines are internal combustion or electric power units purpose-built for off-highway vehicles, typically displacing 90 cc to 1,000 cc and producing 10 HP to 100 HP for traction across unimproved surfaces. Four-stroke gasoline configurations dominate installed base due to torque linearity and emission compliance, while electric motor variants are gaining share in closed-course recreation and low-speed utility tasks. The engine type dimension shows four-stroke engines occupying the mature volume tier, electric powertrains representing the fastest-growing margin pool, and diesel holding niche positions in agricultural utility applications. Power rating segmentation reveals the 50-100 HP band as the primary revenue concentration, where agricultural and recreational buyer requirements overlap and pricing power remains strongest.
The EPA enforces emission standards under 40 CFR Part 1051 that limit hydrocarbon and carbon monoxide output, compelling manufacturers to invest in fuel injection and catalytic after-treatment. CARB operates parallel certification requirements that effectively set the compliance ceiling for engines sold in California and states adopting its framework. The NHTSA oversees vehicle-level safety standards that influence engine placement, cooling architecture, and crashworthiness integration. Stakeholders must monitor regulatory divergence between federal and state-level emission pathways while calibrating platform development bets across combustion and electric architectures.
Market Dynamics
EPA 40 CFR Part 1051 emission mandates and CARB parallel certification are compressing two-stroke engine viability while accelerating four-stroke and electric powertrain investment across the supply base.
Growth Catalysts
- Adventure tourism fleet expansion:Off-road park operators in the United States are scaling vehicle purchases to serve rising consumer demand for guided trail experiences.
- CARB regulatory alignment:California's emission framework has been adopted by multiple states, creating a unified compliance target that streamlines manufacturer product planning.
- Closed-course electrification:Electric powertrains are penetrating recreational riding facilities where range limitations are mitigated by controlled course layouts and centralized charging infrastructure.
Market Restraints
- Aluminum and steel input volatility:Engine block and chassis material costs fluctuate with commodity markets, compressing margin predictability for powertrain assemblers.
- Four-stroke R&D concentration:Technical expertise for clean combustion architectures clusters among established Midwest and Japanese engineering centers, limiting new entrant access.
- Electric range physics:Battery energy density constraints restrict electric ATV deployment to low-speed utility and closed-course applications, excluding long-distance trail riding.
Strategic Opportunities
- Agricultural utility electrification:Farm operators in the United States are piloting electric ATVs for barn and feedlot tasks where daily mileage remains low and charging access is reliable.
- Dealer service revenue unbundling:Powertrain manufacturers can capture aftermarket maintenance through direct parts distribution, bypassing traditional dealer markups.
- IRA clean vehicle incentives:Federal tax credits for electric off-highway vehicles are narrowing the upfront cost gap between electric and combustion powertrains for fleet buyers.
Industry Challenges
- Power electronics talent scarcity:Electric powertrain development requires embedded software and motor control expertise that remains concentrated in automotive and aerospace sectors.
- Dual certification timelines:Manufacturers must sequence EPA and CARB approval processes, extending product launch windows and freezing platform updates.
- Legacy dealer integration:Combustion-focused service networks lack diagnostic equipment and technician training for electric powertrain maintenance.
Report Scope
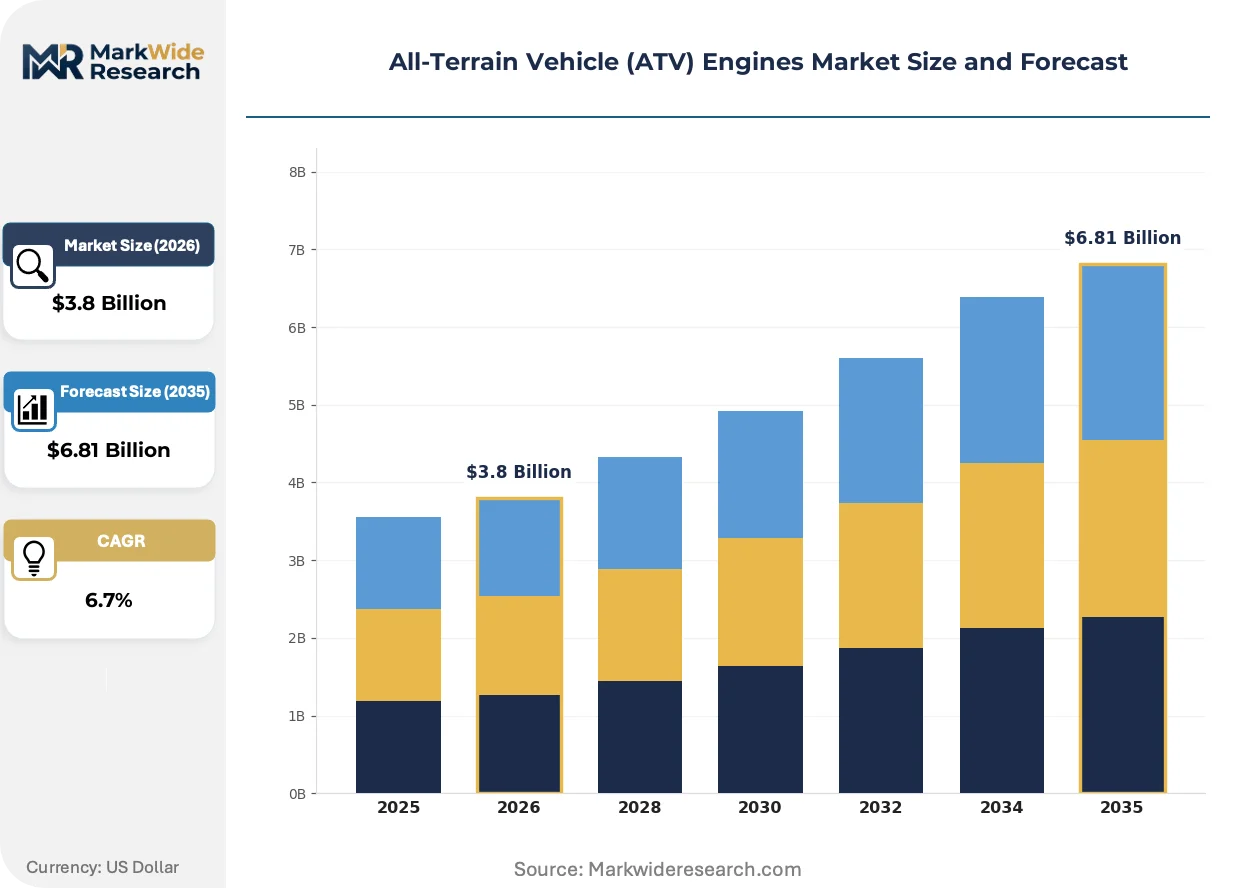
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | All-Terrain Vehicle (ATV) Engines Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Two-Stroke, Four-Stroke, Electric, Diesel Fuel Type: Gasoline, Ethanol, Biodiesel, Propane Application: Recreation, Agriculture, Military, Utility Power Rating: Below 50 HP, 50-100 HP, 100-150 HP, Above 150 HP |
| Companies Covered | Polaris Industries Inc., Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., Bombardier Recreational Products Inc., Kawasaki Heavy Industries, Ltd., Zhejiang CFMoto Power Co., Ltd., Suzuki Motor Corporation, Arctic Cat Inc., KTM AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
All-Terrain Vehicle (ATV) Engines Market Strategic Shifts
Modular powertrain architectures are fragmenting the traditional integrated engine-vehicle value chain. Component specialization is enabling new supplier entry points while compressing incumbent control over system-level performance optimization.
Swappable battery systems are decentralizing energy ownership in commercial ATV fleets. Rental operators and agricultural contractors are adopting standardized pack formats that separate vehicle acquisition from energy provisioning. This architecture is decentralizing capital deployment across fleet lifecycle and enabling third-party energy service specialization.
EPA enforcement of evaporative emission controls under 40 CFR Part 1051 is mandating sealed fuel systems and carbon canister integration. Engine manufacturers are redesigning tank venting and cap sealing to meet diurnal and hot-soak test protocols. The agricultural utility segment is absorbing the highest compliance cost burden due to extended idle operation patterns and large fuel tank capacities.
Direct-to-fleet procurement is compressing dealer intermediation in commercial ATV transactions. Agricultural cooperatives and rental companies are negotiating powertrain supply agreements at the OEM level, bypassing traditional retail channels. This pattern is most pronounced in the Midwest grain belt where volume concentration supports dedicated fleet sales teams.
All-Terrain Vehicle (ATV) Engines Market Segmentation
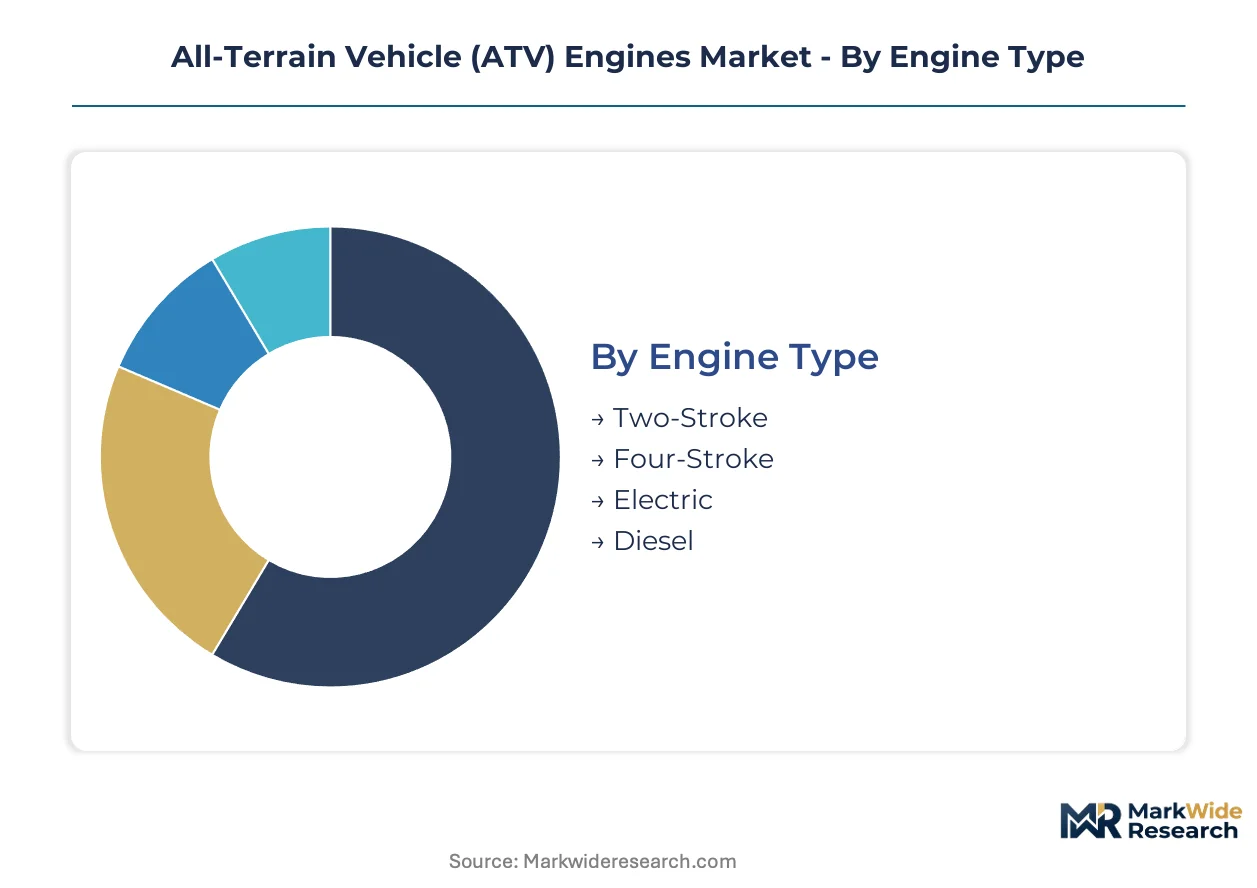
Engine configuration, fuel chemistry, application workload, and power output stratify buyer requirements across recreational, agricultural, and utility deployments. Each dimension carries distinct regulatory exposure, margin structure, and supplier concentration that shapes procurement decisions.
Engine Type:
Powertrain architecture determines emission compliance burden, maintenance interval, and total cost of ownership across buyer segments.
- Four-Stroke:Overhead valve designs with catalytic after-treatment dominate installed base due to EPA 40 CFR Part 1051 compliance and torque linearity for trail and farm tasks. Midwest agricultural operators and Southwest recreational fleets concentrate demand here, driven by CARB alignment across fourteen states and established dealer service density.
- Electric:Permanent magnet synchronous motors with lithium-ion packs penetrate closed-course recreation and low-speed utility where range anxiety disappears and centralized charging infrastructure exists. California off-road parks and Arizona rental operators are scaling fleet pilots, constrained by battery energy density physics that exclude long-distance trail riding.
- Two-Stroke:Crankcase-compression designs persist in price-sensitive niches and export markets with weaker emission enforcement.
- Diesel:Compression-ignition architectures serve agricultural utility with high-torque, low-RPM operation for towing and implement work.
Four-stroke leads volumes today; electric is gaining share fastest.
Fuel Type:
Energy chemistry selection tracks regional fuel availability, storage infrastructure, and agricultural byproduct access.
- Gasoline:87-93 octane formulations with 10% ethanol tolerance power the overwhelming majority of recreational and utility ATVs. Demand concentrates in United States trail systems and private land operations where pump infrastructure is ubiquitous and EPA evaporative emission controls under 40 CFR Part 1051 mandate sealed fuel systems with carbon canister integration.
- Ethanol:E85-compatible flex-fuel configurations serve agricultural cooperatives with captive corn ethanol supply and on-farm storage, particularly across Iowa and Illinois grain belts where fuel cost arbitrage against gasoline reaches meaningful scale.
- Biodiesel:B20-B100 blends operate in diesel ATV variants for farm operators with soybean or canola processing proximity.
- Propane:LPG conversions serve indoor utility applications and closed mines where ventilation constraints prohibit gasoline vapor accumulation.
Gasoline dominates revenue contribution; ethanol climbs fastest among alternative fuels.
Application:
End-use workload intensity dictates durability specification, duty cycle calibration, and fleet procurement patterns.
- Recreation:Trail riding, dune operation, and closed-course racing demand lightweight powertrains with throttle response priority over fuel efficiency. United States off-road parks in Utah, Colorado, and Texas are expanding fleet purchases to serve adventure tourism growth, with electric variants penetrating controlled environments where noise restrictions and emission regulations tighten fastest.
- Agriculture:Pasture management, livestock handling, and light towing require high-torque, low-speed operation with extended idle tolerance. Farm operators across Kansas, Nebraska, and the Dakotas prioritize four-stroke reliability and diesel torque for daily utility tasks where downtime carries livestock and crop management penalties.
- Military:Tactical mobility platforms demand sealed air intake systems, multi-fuel capability, and electromagnetic interference hardening for command integration.
- Utility:Industrial site maintenance, pipeline inspection, and forestry patrol require rack-mounted power take-off compatibility and severe-service cooling packages.
Recreation anchors volume concentration; agriculture shows steepest expansion trajectory for electrification pilots.
Power Rating:
Horsepower segmentation aligns with implement towing requirements, terrain severity, and licensing thresholds across buyer types.
- 50-100 HP:Single-cylinder and V-twin configurations displacing 400-800 cc serve the overlapping zone where recreational trail riders and agricultural utility buyers converge. This band commands strongest pricing power due to dual-market demand density and EPA certification cost amortization across highest production volumes, with particular concentration in Wisconsin and Minnesota manufacturing corridors.
- Below 50 HP:90-400 cc engines power youth models, entry recreation, and light utility where licensing restrictions and insurance costs constrain displacement.
- 100-150 HP:Large-bore twins and parallel triples serve heavy utility towing and high-performance recreation with premium pricing and lower volume concentration.
- Above 150 HP:Specialized racing and extreme terrain builds occupy niche custom fabrication with limited OEM participation.
50-100 HP leads unit economics; below 50 HP shows fastest volume growth in youth and rental segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engine production migrates toward jurisdictions with stable emission enforcement timelines and established supplier density. Manufacturers calibrate facility placement against compliance cost differentials and proximity to recreational trail networks.
United States
Midwest agricultural cooperatives and Southwest off-road park operators drive fleet procurement. EPA 40 CFR Part 1051 mandates sealed fuel systems and catalytic after-treatment. Minnesota and Wisconsin manufacturing corridors concentrate four-stroke assembly capacity serving both utility and recreational demand.
Canada
Forestry contractors and northern mining operators require severe-service cooling packages for extended idle operation. Environment Canada aligns evaporative emission standards with EPA benchmarks, simplifying cross-border product planning. Ontario and Quebec house powertrain distribution hubs serving prairie agricultural and western resource extraction markets.
Germany
EU Green Deal decarbonization targets accelerate electric powertrain pilot programs for closed-course recreation. REACH chemical regulations constrain lubricant formulations and surface treatments. Baden-Württemberg engineering centers develop modular architectures spanning ATV and compact utility vehicle applications.
Japan
METI industrial policy supports dual-sport engine platforms sharing R&D across motorcycle and ATV lines. JIS standards harmonize component specifications for export markets. Chubu region manufacturing clusters leverage precision machining expertise from automotive supplier networks.
China
Domestic recreational park development and agricultural mechanization expand addressable demand. MIIT emission standards for off-road vehicles tighten in parallel with GB standard revisions. Zhejiang and Jiangsu provinces concentrate assembly capacity for export-oriented manufacturers and domestic brand development.
All-Terrain Vehicle (ATV) Engines Market Competitive Environment
United States producers anchor the integrated vehicle-engine tier; Japanese specialists hold position in dual-sport architecture and premium four-stroke reliability. The vendor base stratifies across three tiers: captive powertrain divisions of major vehicle OEMs, independent engine specialists serving aftermarket and private-label channels, and emerging electric drivetrain entrants. Dominant competitive moves include geographic expansion into tariff-advantaged assembly jurisdictions and technology licensing agreements that transfer emission-compliant designs to regional partners.
Within the integrated manufacturer tier, Polaris Industries Inc. and Honda Motor Co., Ltd. exemplify divergent geographic anchoring strategies. Zhejiang CFMoto Power Co., Ltd. occupies a position bridging domestic Chinese production scale with export market penetration. Yamaha Motor Co., Ltd. represents the dual-sport specialization archetype, leveraging shared engineering investment across product categories.
| Leading Market Players |
|---|
| Polaris Industries Inc. |
| Honda Motor Co., Ltd. |
| Yamaha Motor Co., Ltd. |
| Bombardier Recreational Products Inc. |
| Kawasaki Heavy Industries, Ltd. |
| Zhejiang CFMoto Power Co., Ltd. |
| Suzuki Motor Corporation |
| Arctic Cat Inc. |
| KTM AG |
| Others |
Value Chain & Pricing Dynamics
Family-owned Midwest engine specialists anchor the supply base, transmitting raw material volatility directly into contract renegotiation cycles while preserving pricing discipline through long-term agricultural fleet relationships.
Pricing Analysis
Distributor margin stacking layers 12-18 points between foundry and end-user, compressing as direct-to-fleet procurement bypasses traditional retail channels. Three-tier pricing structure across premium four-stroke, standard utility, and economy two-stroke levels tracks EPA certification grade and volume scale, with CARB-aligned configurations commanding sustained premiums. Pricing pressure stems from aluminum and steel input volatility, particularly for cast engine block foundries serving the agricultural segment. Fleet buyers at agricultural cooperatives exhibit highest price sensitivity, while closed-course recreation operators prioritize emission compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for crankcase castings and fuel injection systems mandate multi-supplier qualification across foundry partners in the United States, Japan, and China. Critical inputs draw from aluminum billet producers in the Midwest, precision machining clusters in Chubu, and rare-earth magnet processors for electric motor stators. Single-source vulnerability concentrates in catalytic converter substrate supply, where ceramic honeycomb production rests on limited qualified vendors. Distribution runs through captive OEM service parts operations, aftermarket warehouse distributors, and direct fleet procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA 40 CFR Part 1051 emission mandates compound demand for compliant four-stroke and electric powertrains, creating sustained procurement pull from fleet operators facing regulatory deadlines.
For Market Incumbents: Lock in foundry capacity through backward integration or long-term offtake agreements with Midwest aluminum suppliers, insulating margin position from commodity volatility. Prioritize CARB certification investment to maintain access across fourteen adopting states, defending against emerging electric entrants in closed-course recreation. For New Entrants and Emerging Players: Begin with agricultural utility electrification pilots in the Midwest grain belt, where daily mileage constraints and reliable barn charging infrastructure neutralize range limitations. Target farm cooperatives with battery-swapping service models, bypassing dealer network requirements through direct procurement relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among independent engine specialists lacking EPA certification portfolios, presenting consolidation opportunities for platform buyers with compliance infrastructure. Long-term viability hinges on electric powertrain transition execution; watch CARB state adoption velocity as inflection indicator for combustion engine residual value.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captive aluminum casting capacity insulates Polaris and Honda from Midwest commodity volatility. |
| CARB Certification Fast-Track Program | Parallel EPA and California approval processes compress launch timelines for four-stroke platforms. |
| Swappable Battery Architecture Development | Standardized pack formats enable third-party energy services for Arizona rental fleet operators. |
| Direct-to-Fleet Sales Channel Expansion | Bypassing dealer intermediation captures margin from Kansas and Nebraska agricultural cooperatives. |
| Power Electronics Talent Acquisition | Motor control expertise from automotive suppliers accelerates electric ATV development timelines. |
Study Parameters
Multiple input streams — powertrain engineering directors, agricultural fleet procurement managers, EPA regulatory affairs specialists, and aftermarket distribution executives — were reconciled against EPA certification databases, NHTSA safety filings, and state-level vehicle registration data. Primary fieldwork captured platform development timelines and fleet replacement cycles across Midwest and Southwest operator bases. Secondary validation drew from SEC 10-K disclosures of listed OEMs, commodity price indices for aluminum and steel inputs, and CARB regulatory dockets. Bottom-up unit shipment estimates triangulated against top-down value projections across the analysis window.
Data-stream reconciliation anchored volume and value outputs across engine type, fuel chemistry, application workload, and power rating dimensions, with electric powertrain penetration tracked separately for closed-course and utility deployment patterns. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic indicators and regulatory compliance cost trajectories. Forecast inputs incorporated EPA enforcement intensity assumptions, CARB state adoption velocity, and battery energy density improvement curves for electric variants.
Caveats apply where EPA enforcement delays, CARB regulatory divergence, or battery cost trajectory deviations could materially shift the outlook. Forecasts reflect assumptions on emission standard stringency and fleet electrification willingness. Deviation in aluminum input pricing or power electronics talent availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Off-Highway Vehicle HVAC Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
Off-Highway Engine Market
Off Road Vehicles
Off Highway Hybrid Vehicles Market
Off Road Vehicles
Off-Road Equipment Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
Off-Road Vehicle Market
Off Road Vehicles
Off-Highway Wheels Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Global Electric Off-Highway Equipment Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
Snow Scooter Market
Off Road Vehicles
Electric Utility-Terrain Vehicle (UTV) Market
Off Road Vehicles
Off Highway Vehicles Brake Systems Market