
 Europe Off-Highway Vehicle HVAC Market | 2026-2036
Europe Off-Highway Vehicle HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Off-Highway Vehicle HVAC Market Foresight
The capability gap between integrated thermal system suppliers and component assemblers is collapsing as electrified off-highway platforms demand unified thermal management architectures. Denso Corporation leverages its refrigerant circuit expertise to anchor electrified compressor supply chains for European OEMs. Valeo Group sustains R&D intensity in heat pump integration for hybrid construction machinery. MAHLE GmbH differentiates through backward integration into electric compressor manufacturing, reducing dependency on tier-two suppliers.
Europe Off-Highway Vehicle HVAC encompasses cabin thermal management systems engineered to maintain operator environments across temperature extremes, typically integrating vapor-compression refrigeration cycles with capacity ratings from 3 kW to 12 kW and R-1234yf or R-454B refrigerant charges for Stage V and emerging Stage VI compliance. These systems serve to protect operator productivity, reduce fatigue-related incidents, and preserve electronic control unit performance within sealed cabs. Air Conditioning product lines command the dominant revenue share given universal fitment across equipment classes, while Heat Pump technology represents the fastest-expanding segment as electrified drivelines reject less waste heat for cabin warming. OEM Installation channels capture the majority of margin pools through multi-year supply agreements with equipment manufacturers, though Aftermarket Solutions are gaining structural importance as fleet operators extend equipment life cycles amid capital constraints.
The EU F-Gas Regulation and ECHA REACH restrictions on refrigerant chemistry are reshaping product development roadmaps, compelling suppliers to validate alternative working fluids and redesign seals for compatibility. CE marking under the Machinery Directive governs safety integration, while national type-approval requirements in Germany through KBA-aligned processes affect roadable equipment categories. Stakeholders must monitor the trajectory of Stage VI emission proposals and their thermal management implications for engine-off operation modes.
Market Dynamics
The EU F-Gas Regulation's phasedown of high-GWP refrigerants is compressing supplier margins while forcing simultaneous R&D into heat pump architectures and alternative working fluids across European off-highway equipment supply chains.
Growth Catalysts
- Stage V Emissions Mandate:Agricultural and construction OEMs in Germany and France must factory-integrate climate systems to maintain engine certification and operator productivity metrics during extended work cycles.
- Electrified Driveline Penetration:Battery-electric excavators and tractors reject insufficient waste heat for cabin warming, creating pull for integrated heat pump solutions across Nordic and Alpine operating environments.
- Precision Farming Economics:German arable operations specify warranty-aligned HVAC installation to preserve residual equipment value and secure financing for fleet modernization programs.
Market Restraints
- Refrigerant Chemistry Constraints:ECHA REACH restrictions on seal compatibility and flammability classifications limit rapid formulation switching, extending validation timelines for R-454B and R-1234yf alternatives.
- Compressor Supply Concentration:European OEM dependency on Asian-sourced electric compressor motors creates exposure to shipping lane disruptions and rare earth processing bottlenecks.
- Copper and Aluminum Volatility:Heat exchanger raw material costs fluctuate with energy-intensive smelting economics, compressing system assembler margins on fixed-price annual contracts.
Strategic Opportunities
- Polish and Romanian Fleet Retrofit:Eastern European contractors operating aging equipment outside warranty coverage represent underpenetrated aftermarket demand for drop-in heat pump upgrade kits.
- CE Marking Harmonization:Machinery Directive alignment with emerging Stage VI proposals creates first-mover advantage for suppliers pre-validating engine-off thermal management modes.
- Telematics-HVAC Convergence:Integration of cabin climate data with fleet management platforms enables predictive maintenance contracts and remote diagnostics for large German agricultural cooperatives.
Industry Challenges
- Refrigerant Handling Certification:Technician training gaps for mildly flammable A2L working fluids slow service network expansion and increase warranty claim risk for independent repair channels.
- Multi-Physics Simulation Talent:Suppliers compete for scarce thermal-fluid engineers capable of optimizing heat pump performance across −20°C to +45°C ambient operating envelopes.
- Legacy 12V Architecture Integration:Electrified compressor systems require voltage conversion and control logic retrofitting, complicating backward compatibility with existing equipment electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Off-Highway Vehicle HVAC Market |
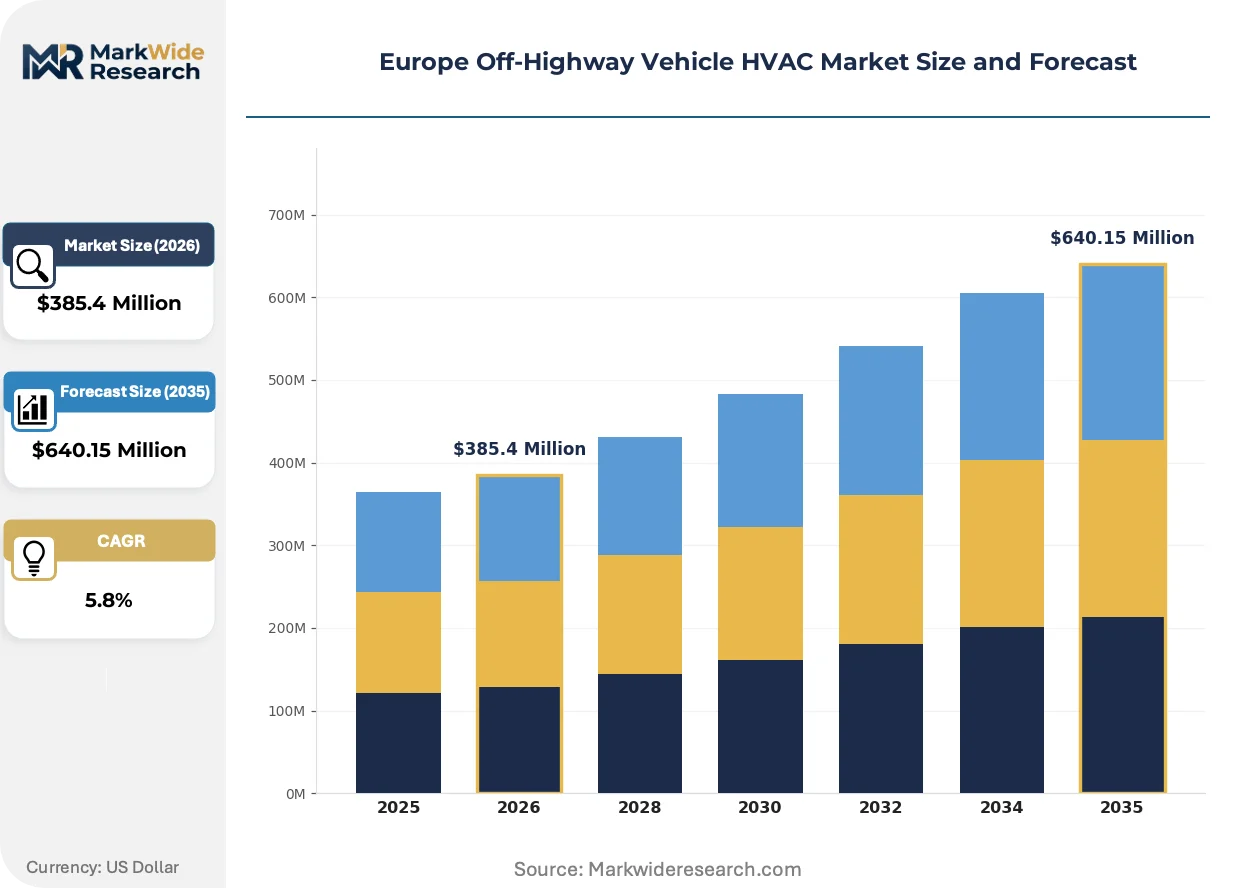
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Conditioning, Heating Systems, Ventilation Units, Climate Control Technology: Refrigeration, Heat Pump, Evaporative Cooling, Dual-Zone Systems End User: Agricultural Equipment, Construction Machinery, Mining Vehicles, Forestry Equipment Installation: OEM Installation, Aftermarket Solutions, Custom Systems, Retrofit Options |
| Companies Covered | Denso Corporation, Valeo Group, MAHLE GmbH, Hanon Systems, Webasto SE, Marelli Corporation, Sanden Holdings Corporation, Magneti Corporation, Bergstrom Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Off-Highway Vehicle HVAC Market Shifts & Advancements
Thermal management architectures are converging with powertrain electrification roadmaps, compressing development cycles and redefining supplier qualification criteria across European off-highway manufacturing.
Heat pump technology is bifurcating the competitive landscape between integrated system suppliers and component assemblers. Vapor-compression cycles with reversible refrigerant flow now serve both cooling and heating functions in battery-electric tractors and hybrid excavators. German precision farming OEMs specify these systems for factory installation to maintain warranty coverage. The technology is bifurcating margin pools toward suppliers with captive compressor manufacturing and refrigerant circuit design expertise.
REACH and the EU F-Gas Regulation are mandating seal material validation for alternative working fluids with lower global warming potential. Industrial consequence includes extended qualification timelines for R-454B and hydrofluoroolefin blends in construction equipment applications. Agricultural machinery segments face compressed product launch windows as Stage VI emission proposals advance through Brussels legislative procedures.
Fleet procurement patterns now prioritize total cost of ownership metrics over upfront system pricing. Large French and German agricultural cooperatives unbundle HVAC service contracts from equipment purchase agreements, favoring suppliers with regional spare parts distribution. This behavioral shift concentrates aftermarket revenue with vertically integrated thermal system specialists maintaining captive service networks across Benelux and Northern Germany.
Europe Off-Highway Vehicle HVAC Market Segmentation
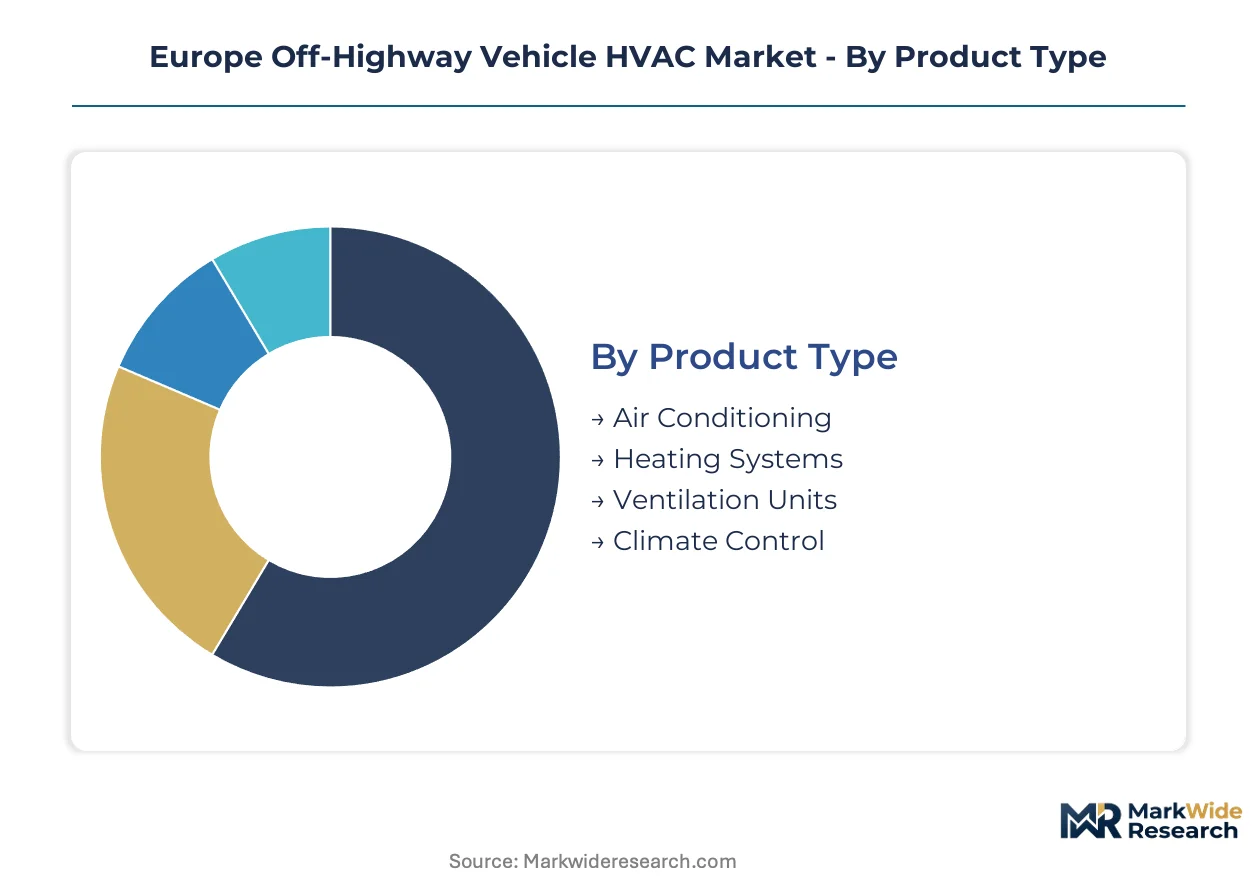
European off-highway HVAC procurement flows through distinct technical and commercial channels. OEMs prioritize factory-integrated systems for warranty alignment, while fleet operators drive aftermarket retrofit demand amid capital constraints.
Product Type:
Factory channels favor premium climate systems with multi-year service contracts, whereas aftermarket procurement concentrates on drop-in replacements for aging equipment outside warranty coverage.
- Air Conditioning:Vapor-compression refrigeration cycles rated 3 kW to 12 kW dominate factory fitment across German and French agricultural OEMs. Precision farming operators specify these systems to maintain residual equipment value and secure fleet financing.
- Heating Systems:Combustion-based and electric resistance units serve construction machinery operating in Nordic winter conditions. Battery-electric platforms reject insufficient waste heat, pulling demand toward integrated heat pump alternatives in Alpine markets.
- Ventilation Units:Cab air exchange systems preserve electronic control unit performance in sealed operator environments.
- Climate Control:Integrated thermal management modules unify heating, cooling, and filtration for Stage V compliance.
By volume, Air Conditioning leads. By growth pace, Climate Control is expanding most quickly.
Technology:
Cost tiers separate validated refrigerant architectures from emerging heat pump platforms requiring extended qualification timelines.
- Refrigeration:Conventional vapor-compression systems using R-1234yf or R-454B refrigerants anchor current production. ECHA REACH restrictions on seal compatibility extend validation cycles for alternative working fluids.
- Heat Pump:Reversible refrigerant flow architectures serve both cooling and heating in battery-electric tractors and hybrid excavators. German OEMs specify these for factory installation to preserve warranty coverage in electrified driveline programs.
- Evaporative Cooling:Water-based systems suit open-cab forestry equipment in Mediterranean climates with low humidity.
- Dual-Zone Systems:Independent temperature control for operator and passenger compartments appears in large mining haul trucks.
By installed base, Refrigeration dominates. By technology transition speed, Heat Pump is gaining share fastest.
End User:
Application-specific thermal loads and operating environments shape specification requirements across equipment classes.
- Agricultural Equipment:Tractors and harvesters demand robust climate systems for 12-16 hour seasonal work cycles. German arable operations prioritize warranty-aligned HVAC to maintain equipment residual values and financing eligibility.
- Construction Machinery:Excavators and wheel loaders require sealed cabs with filtration for dust-heavy environments. Electrified platforms in French urban projects pull heat pump integration for engine-off operation compliance.
- Mining Vehicles:Underground haul trucks specify explosion-protected climate systems with reinforced compressor housings.
- Forestry Equipment:Forwarders and harvesters in Nordic markets combine heating priority with cab pressurization for debris exclusion.
Agricultural Equipment commands the largest volume. Construction Machinery shows the steepest expansion trajectory as electrification accelerates.
Installation:
Customer type bifurcates between OEM-integrated procurement with multi-year supply agreements and independent fleet retrofit programs.
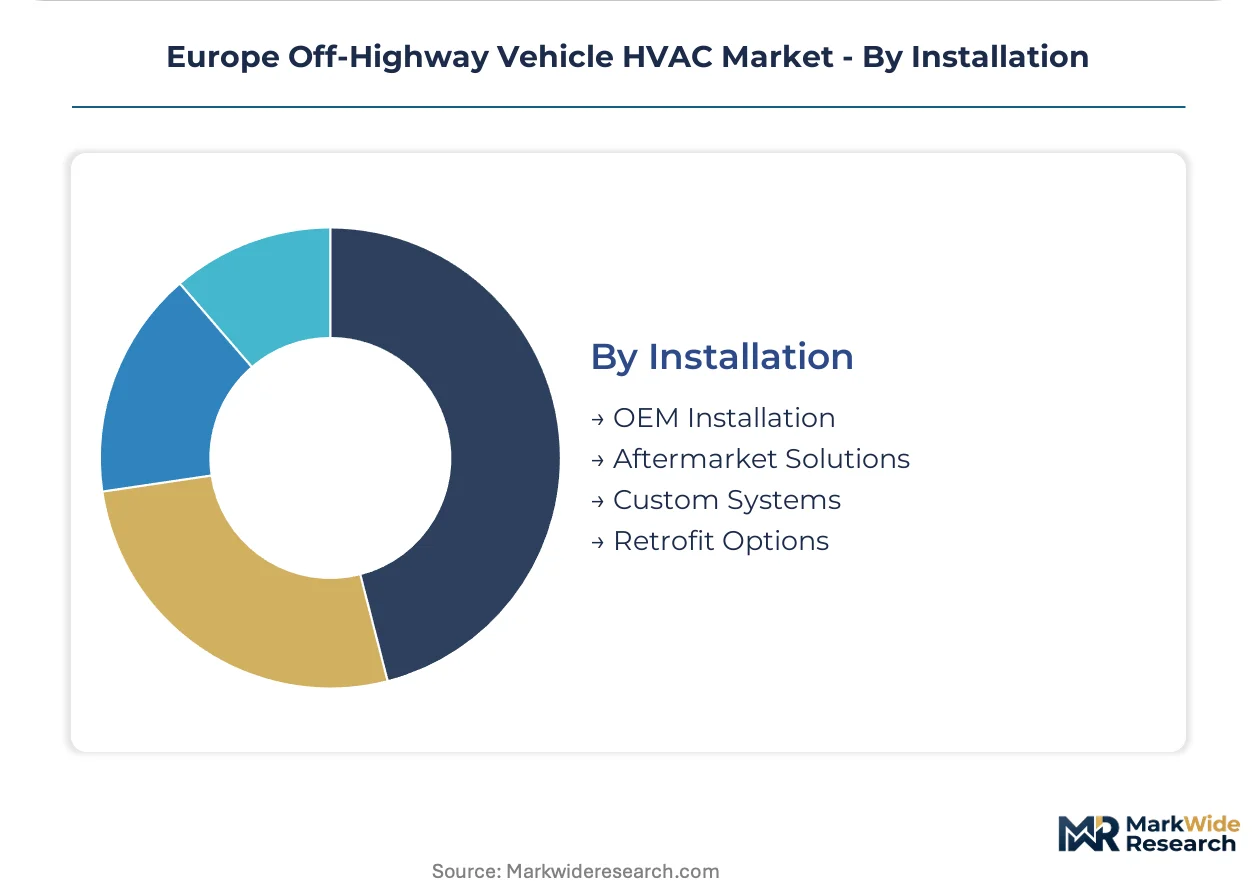
- OEM Installation:Factory-integrated systems capture margin pools through exclusive supply contracts with German and French equipment manufacturers. These installations maintain warranty coverage and residual value benchmarks required by agricultural financing programs.
- Aftermarket Solutions:Independent service channels address aging equipment in Eastern European contractor fleets. Polish and Romanian operators outside warranty coverage represent underpenetrated demand for heat pump upgrade kits.
- Custom Systems:Specialized configurations serve mining and forestry OEMs with non-standard cab architectures.
- Retrofit Options:Drop-in replacement modules extend equipment life cycles amid capital constraints across Benelux agricultural cooperatives.
OEM Installation leads by revenue concentration. Aftermarket Solutions climb the fastest as fleet operators delay new equipment purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a structural trade surplus in off-highway HVAC systems, exporting factory-integrated thermal modules to French and Polish equipment assemblers while importing electric compressor motors from Asian suppliers. This exchange pattern concentrates value capture in engineering-intensive components while exposing European OEMs to shipping lane disruptions.
Germany
Precision farming OEMs in Baden-Württemberg and Lower Saxony specify warranty-aligned HVAC installation to preserve residual equipment values. The KBA enforces national type-approval requirements that affect roadable equipment categories. Stuttgart-based thermal system specialists anchor electrified compressor supply chains for domestic tractor manufacturers.
France
Urban construction projects in Île-de-France pull heat pump integration for engine-off operation compliance in electrified excavators. The EU F-Gas Regulation phases down high-GWP refrigerants across French territory. Lyon and Auvergne-Rhône-Alpes host agricultural cooperatives unbundling HVAC service contracts from equipment purchase agreements.
Poland
Eastern European contractors operating aging equipment outside warranty coverage generate aftermarket demand for drop-in heat pump upgrade kits. ECHA REACH restrictions on seal compatibility extend validation timelines for alternative working fluids. Warsaw and Silesian industrial zones concentrate independent service channels addressing capital-constrained fleet operators.
Italy
Specialized vineyard and orchard machinery manufacturers in Emilia-Romagna and Veneto require compact climate systems for narrow-cab tractors. CE marking under the Machinery Directive governs safety integration for Italian exports. Bologna-based component suppliers validate R-454B refrigerant compatibility for Mediterranean operating conditions.
Sweden
Forestry equipment operators in Västerbotten and Norrbotten demand robust heating systems for sub-zero work environments. The EU Green Deal accelerates electrification mandates affecting thermal management architectures. Stockholm-region OEMs specify heat pump solutions for battery-electric forwarders and harvesters.
Europe Off-Highway Vehicle HVAC Market Competitive Landscape
Concentration sits with integrated thermal system suppliers possessing captive compressor manufacturing and refrigerant circuit design expertise. The vendor base fragments between these full-architecture providers and component assemblers dependent on tier-two sourcing. Three archetypes dominate: Japanese diversified automotive suppliers, European automotive component conglomerates, and specialized HVAC fabricators. Competitive moves center on backward integration into electric compressor production and multi-year supply agreement capture with German and French OEMs.
Among Japanese diversified suppliers, Denso Corporation and Sanden Holdings Corporation occupy positions exemplifying integrated refrigerant circuit expertise. European automotive component specialists include Valeo Group and MAHLE GmbH, with the latter anchoring the tier of manufacturers reducing dependency on external compressor sourcing. Webasto SE and Hanon Systems represent specialists with established thermal management footprints. Bergstrom Inc. sits within the North American-originated fabricator archetype serving aftermarket channels. Marelli Corporation and Magneti Corporation exemplify Italian-rooted automotive suppliers extending into off-highway applications.
| Leading Market Players |
|---|
| Denso Corporation |
| Valeo Group |
| MAHLE GmbH |
| Hanon Systems |
| Webasto SE |
| Marelli Corporation |
| Sanden Holdings Corporation |
| Magneti Corporation |
| Bergstrom Inc. |
| Others |
Supply & Pricing Matrix
R-454B refrigerant substitution for R-1234yf across German and French OEM supply chains simultaneously relocates seal validation programs toward Bologna and Stuttgart testing clusters while compressing margin structures for assemblers lacking captive chemistry expertise. This input transition forces tier-two suppliers to absorb extended qualification timelines or cede position to integrated thermal system specialists with in-house refrigerant circuit design.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across German precision farming equipment programs. Pricing stratifies across factory-integrated premium tiers with multi-year service bundling, standard aftermarket replacement modules, and economy retrofit kits for Eastern European contractor fleets. Cost compression in the economy tier intensifies because Polish and Romanian operators prioritize upfront capital minimization over residual value preservation. Fleet procurement teams at large French agricultural cooperatives exhibit lowest price sensitivity due to unbundled service contract economics, while independent Eastern European repair channels face acute margin pressure from fixed-price annual agreements.
Supply Chain Analysis
Inventory buffers for electric compressor motors have thinned to eight-week coverage across Stuttgart and Lyon assembly plants as Asian rare earth processing constraints propagate through maritime lanes. European OEM supply chains draw from China for permanent magnet materials, Japan for precision motor winding, and Germany for thermal module integration. Single-source vulnerability concentrates in NdFeB magnet supply from Chinese processing facilities. Distribution runs through captive OEM logistics networks for factory-integrated systems and independent parts distributors for aftermarket channels across Benelux and Northern Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards suppliers possessing multi-physics simulation capabilities for heat pump optimization across Alpine and Nordic operating envelopes, yet European engineering programs graduate insufficient thermal-fluid specialists to populate expanding R&D teams.
For Market Incumbents: Consolidate refrigerant circuit design expertise through selective acquisition of Italian seal validation specialists in Emilia-Romagna. Denso Corporation and Valeo Group should expand captive electric compressor manufacturing capacity in Stuttgart industrial zones to reduce dependency on Asian motor sourcing. This backward integration into compressor production defends margin structures against rare earth price volatility and shipping lane disruption. For New Entrants and Emerging Players: Aftermarket telematics integration for predictive HVAC maintenance represents the most penetrable service layer, with large German agricultural cooperatives currently underserved by incumbent warranty-focused business models. Polish contractor fleets operating aging Stage III equipment outside OEM coverage offer white-space demand for drop-in heat pump retrofit kits bundled with remote diagnostics. A channel partnership strategy with Silesian independent service networks accelerates market entry without direct OEM supply agreement competition. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors vertically integrated thermal system specialists with captive compressor manufacturing and refrigerant chemistry expertise. Long-term viability over the next decade hinges on positioning ahead of Stage VI emission proposals and their engine-off thermal management implications. The signal to watch is KBA-aligned type-approval acceleration for heat pump architectures in roadable equipment categories.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Architecture Validation | CE marking alignment with Stage VI proposals secures first-mover supply agreements with German OEMs. |
| Backward Integration into Electric Compressors | Captive motor manufacturing reduces exposure to Asian rare earth processing bottlenecks and shipping disruptions. |
| Aftermarket Telematics Convergence | Cabin climate data integration with fleet management platforms enables predictive maintenance contracts for French cooperatives. |
| Seal Material Chemistry Investment | ECHA REACH-compliant R-454B validation programs defend qualification timelines against regulatory compression. |
| Eastern European Service Network Expansion | Polish and Romanian independent channel partnerships capture capital-constrained fleet retrofit demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing thermal system procurement managers at German and French agricultural OEMs, aftermarket service directors at Benelux distributor networks, and refrigerant chemistry specialists at ECHA-aligned validation laboratories. Secondary validation drew from EU F-Gas Regulation implementation reports, KBA type-approval databases, and machinery production statistics from Stuttgart and Lyon industrial associations. Bottom-up equipment fitment rates and top-down regional macroeconomic indicators were triangulated to anchor market size estimates.
Across the projection horizon, the analytical framework modeled value and volume trajectories by product type, technology architecture, end-use equipment class, and installation channel. CAGRs were derived from segment-level growth rate synthesis rather than single-point extrapolation. Key forecast inputs included electrified driveline penetration curves for European construction and agricultural equipment, plus refrigerant phase-down schedules under EU F-Gas Regulation amendments.
Underlying assumptions cover Stage V compliance maintenance and gradual Stage VI proposal advancement, with deviation risk concentrated in regulatory timeline acceleration or delay. Electrification adoption rates and rare earth supply chain stability represent additional forecast sensitivity factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off Highway Vehicles Brake Systems Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Global Off-Highway Vehicle Telematics Market
Off Road Vehicles
Global Electric Off-Highway Equipment Market
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
Electric Utility-Terrain Vehicle (UTV) Market
Off Road Vehicles
US Off-Road Vehicles Market
Off Road Vehicles
Global Automotive Off Highway Engine Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Off-Highway Engine Market
Off Road Vehicles
Mining Vehicle Attachments Market
Off Road Vehicles
Off Road Motorcycles Market