
 Electric Vehicle HV Cables Market | 2026-2036
Electric Vehicle HV Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle HV Cables Market Insights
China is rewriting supply chain geography for electric vehicle HV cables as domestic foundries and copper processing clusters expand around Shanghai and Shenzhen manufacturing zones. LEONI AG leverages its European automotive heritage to sustain qualification relationships with premium German OEMs. Sumitomo Electric Industries anchors high-voltage shielding expertise across Asian battery platform programs. Prysmian Group competes on cable extrusion scale, extending its energy infrastructure know-how into automotive voltage classes.
Electric vehicle HV cables are insulated conductor assemblies rated typically from 600V to 1500V DC, engineered with cross-linked polyethylene or silicone rubber dielectrics and braided copper shields to contain electromagnetic interference across battery-to-inverter and inverter-to-motor pathways. Their primary purpose is to transmit high power with minimal losses while protecting occupants and electronics from electrical faults and thermal runaway propagation. The cables segment within product type captures the dominant share of bill-of-material value, whereas connectors command margin premiums due to precision contact engineering and waterproof sealing requirements. DC Fast Charging technology infrastructure is expanding fastest among technology categories, pulling demand for higher-amperage cable assemblies capable of sustained thermal performance.
FDA does not regulate this automotive segment, but China's MIIT enforces GB/T standards for high-voltage safety, while Europe's REACH and RoHS frameworks restrict halogenated flame retardants in cable jacketing compounds. These regulatory layers force suppliers to reformulate insulation chemistries and re-qualify platforms across multiple jurisdictions. Stakeholders must monitor how battery platform voltage architectures migrate toward 800V and above, as this shift will obsolete incumbent cable gauges and connector formats before the next product cycle stabilizes.
Market Dynamics
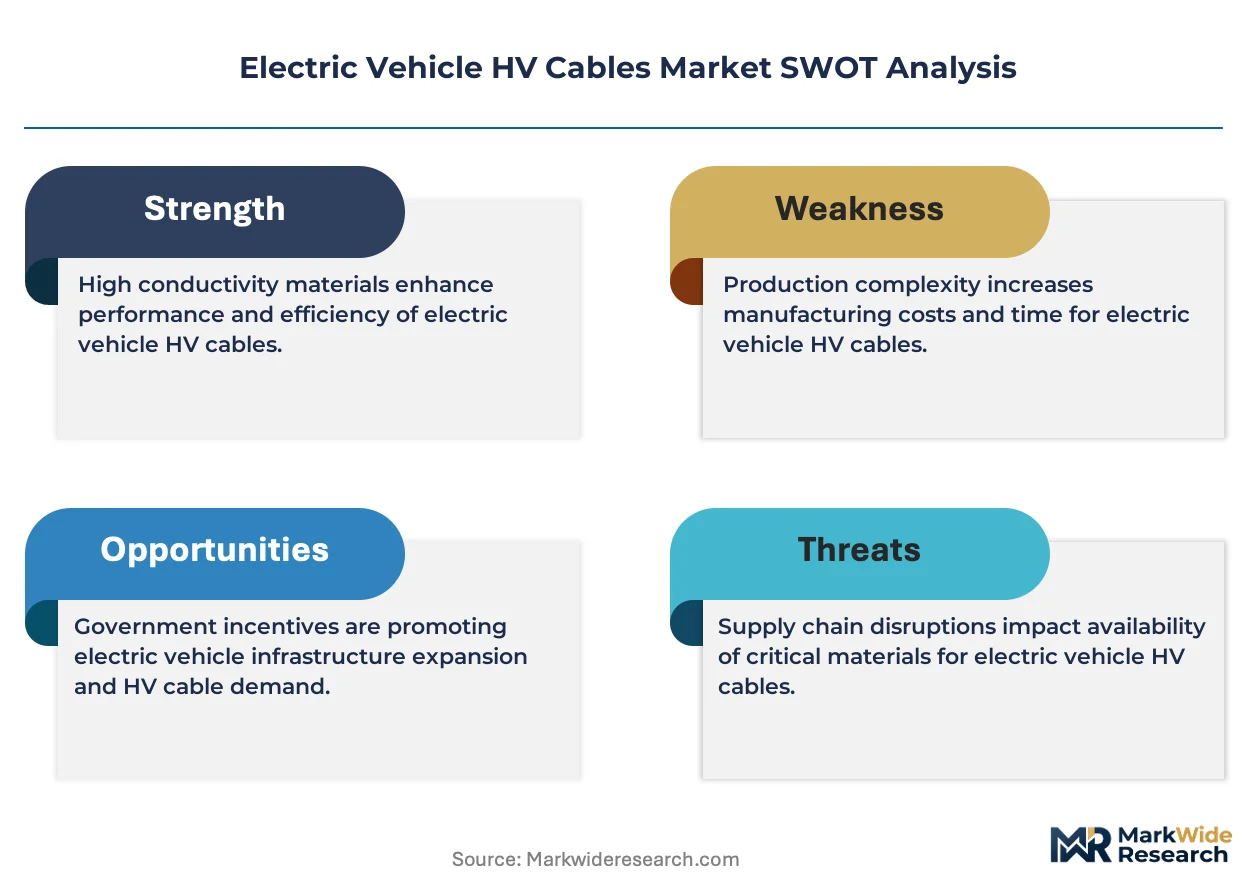
Voltage architecture migration toward 800V and 1500V platforms is compressing cable qualification cycles and forcing simultaneous reformulation of insulation chemistries and shielding geometries across supplier portfolios.
Growth Catalysts
- GB/T Standard Harmonization:China's MIIT mandates unified high-voltage safety protocols, accelerating platform consolidation among domestic battery-electric vehicle manufacturers and reducing supplier qualification fragmentation.
- DC Fast Charging Infrastructure Rollout:Charging network operators deploy higher-amperage cable assemblies, pulling demand for thermal-stabilized conductor systems rated above 500A continuous operation.
- Copper Processing Cluster Expansion:Foundry capacity concentration around Shanghai and Shenzhen manufacturing zones shortens procurement lead times for stranded conductor raw material.
Market Restraints
- Lithium-Price Volatility:Battery pack cost fluctuations constrain original equipment manufacturer cable budget flexibility, forcing tier-two suppliers to absorb margin compression.
- Fluoropolymer Supply Concentration:FEP and PFA resin production clusters in Japan and Germany create single-source vulnerability for high-temperature jacketing compounds.
- REACH Compliance Friction:ECHA restrictions on halogenated flame retardants force complete reformulation of established PVC and XLPE insulation platforms without grandfathering provisions.
Strategic Opportunities
- Second-Life Battery Integration:Stationary energy storage installations repurpose automotive-grade HV cable specifications, opening aftermarket volume for thermal-runaway-resistant assemblies.
- Wireless Power Transfer Convergence:Inductive charging pad deployment creates demand for high-frequency shielding expertise transferable from current cable engineering teams.
- India PLI Scheme Tailwinds:Production-linked incentive structures for advanced chemistry cell manufacturing attract cable suppliers to establish localized extrusion and termination capabilities.
Industry Challenges
- Cross-Disciplinary Engineering Scarcity:Cable suppliers compete for electrochemical thermal management specialists capable of simulating joule heating under pulse-width modulation load profiles.
- Platform-Specific Qualification Timelines:German OEM validation protocols extend 18-24 months, freezing design iterations and locking suppliers into obsolete conductor gauges mid-cycle.
- Legacy Connector Interoperability:400V architecture residual stock complicates inventory management as 800V platforms demand incompatible terminal geometries and sealing specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle HV Cables Market |
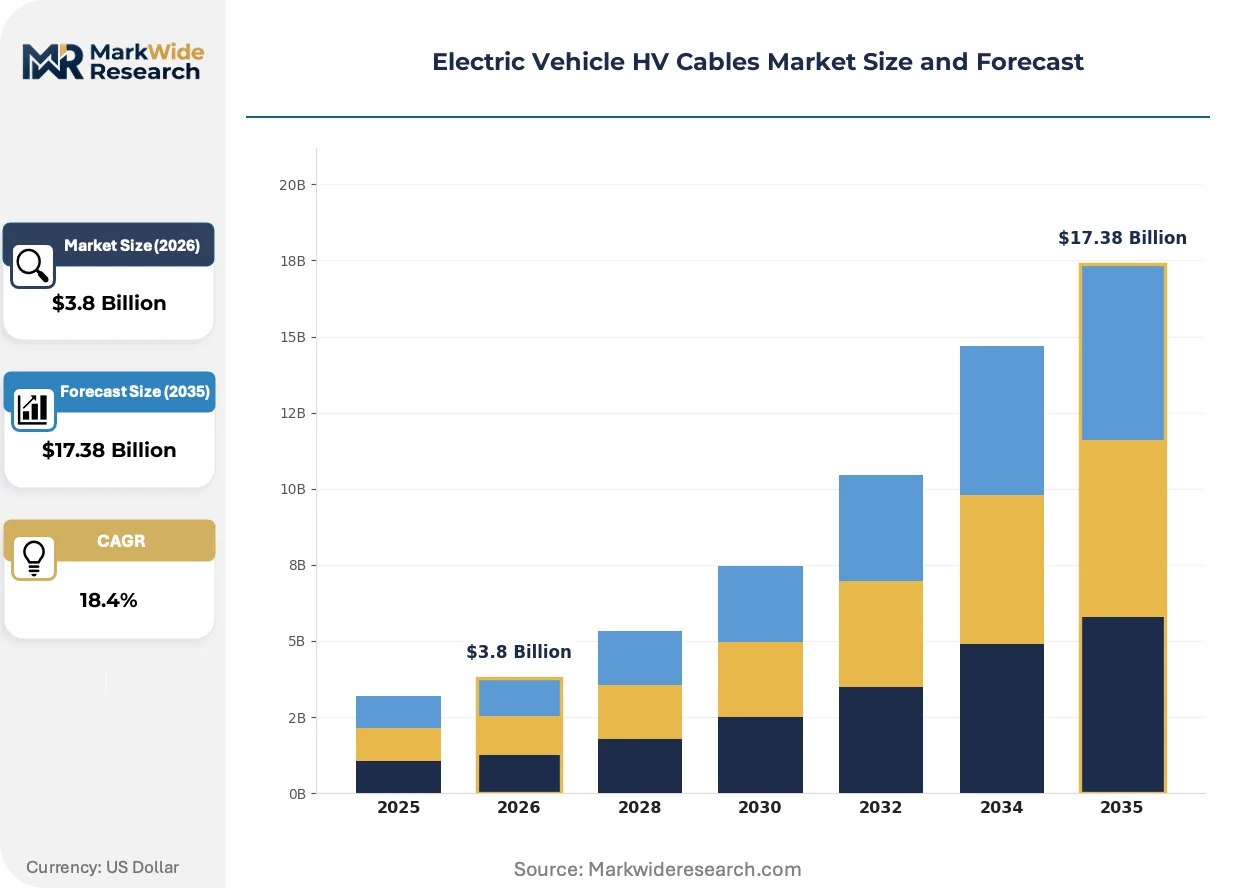
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cables, Connectors, Junction Boxes, Charging Stations End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: On-Road, Off-Road, Residential, Commercial Technology: DC Fast Charging, AC Charging, Wireless Charging, Others |
| Companies Covered | LEONI AG, Sumitomo Electric Industries, ACOME Group, Coroplast Fritz Müller GmbH & Co. KG, Prysmian Group, HUBER+SUHNER, Champlain Cable Corporation, SHANGHAI KMCABLE GROUP, JYFT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle HV Cables Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are simultaneously pushing dielectric innovation while compressing the acceptable performance envelope for electromagnetic compatibility and thermal endurance.
Silicone rubber insulation compounds are hybridizing with ceramic filler loadings to achieve 200°C continuous temperature ratings without fluoropolymer cost structures. Tier-one battery platform engineers specify these formulations for inverter-to-motor pathways where space constraints limit conductor gauge. The technology is hybridizing procurement categories previously separated into automotive and industrial cable specifications.
Europe's F-Gas Regulation tightens restrictions on perfluorinated compounds used in high-performance cable jacketing, forcing compounders to validate bio-based aromatic polyamides as thermal barriers. Industrial consequence includes extended qualification timelines as alternative materials undergo accelerated aging protocols. Asian suppliers with fluoropolymer-dependent portfolios face the steepest reformulation burden.
Vehicle-as-a-service fleet operators now specify outcome-based cable lifecycle contracts rather than component procurement, transferring obsolescence risk to suppliers. Leasing subsidiaries of German premium OEMs pilot these arrangements for commercial van platforms. This shift concentrates most visibly in urban logistics corridors where uptime guarantees override upfront capital expenditure minimization.
Electric Vehicle HV Cables Market Segmentation
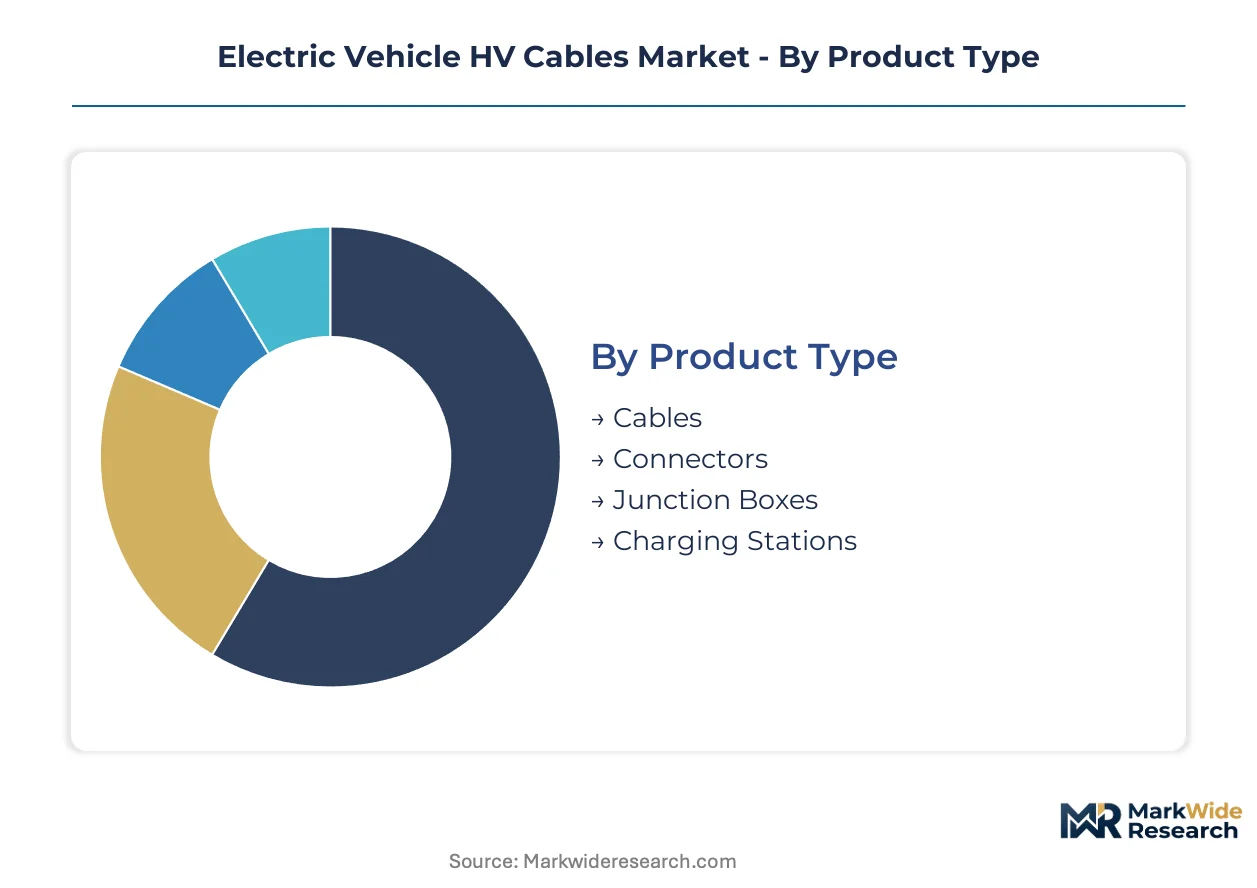
Segmentation in electric vehicle HV cables reveals divergent procurement rhythms across product categories. Cable assemblies and connectors operate on fundamentally different replacement cycles and qualification timelines, reshaping supplier portfolio strategies and inventory deployment.
Product Type:
Cable assemblies turn over fastest due to thermal degradation under pulse-width modulation loads, while charging station infrastructure commits capital across decade-long depreciation schedules.
- Cables:Stranded copper conductors with cross-linked polyethylene or silicone rubber dielectrics and braided electromagnetic shields form the conductive backbone between battery packs, inverters, and traction motors. Procurement concentrates around Shanghai and Shenzhen processing clusters where foundry capacity shortens lead times for high-purity copper rod. China's MIIT GB/T standards enforce shielding effectiveness thresholds that disqualify legacy PVC formulations.
- Connectors:Precision-machined terminal housings with waterproof sealing systems and high-cycle-life contact interfaces command margin premiums due to qualification rigor. German OEM validation protocols extend 18-24 months, freezing design iterations and concentrating demand among suppliers with established platform relationships.
- Junction Boxes:Power distribution nodes integrating fuse protection and busbar termination points.
- Charging Stations:Pedestal-mounted cable management systems with thermal-stabilized conductors rated for sustained 500A operation.
Cables anchors the volume base while charging stations gains share at the steepest rate.
End User:
Customer type determines contract structure, with OEMs demanding platform-specific qualification and aftermarket providers seeking interchangeable catalog specifications.
- OEMs:Battery-electric vehicle manufacturers specify custom cable gauges and connector geometries locked to proprietary platform architectures. Germany's industrial corridor dominates procurement volume as premium brands extend qualification cycles to 24 months.
- Tier-1 Suppliers:Integrated module providers procure cable assemblies for battery pack integration and power electronics packaging.
- Aftermarket Providers:Independent distributors stock replacement cables for collision repair and warranty claims.
- Vehicle Assemblers:Contract manufacturers building white-label electric vehicles for fleet operators.
OEMs command the largest contract values while tier-1 suppliers expand procurement most aggressively.
Installation:
Application environment dictates jacketing chemistry and mechanical armor requirements, with off-road duty cycles imposing the most severe abrasion and chemical exposure constraints.
- On-Road:Passenger vehicle underhood and chassis routing applications.
- Off-Road:Mining trucks and agricultural machinery require reinforced conduit systems with crush-resistant metallic armor and hydrocarbon-resistant elastomer jackets.
- Residential:Home garage charging installations with moderate thermal cycling profiles.
- Commercial:Fleet depot and public charging infrastructure subject to vandalism resistance specifications and high-utilization thermal loads.
On-road installations generate the highest unit volumes while commercial deployments show the steepest expansion trajectory.
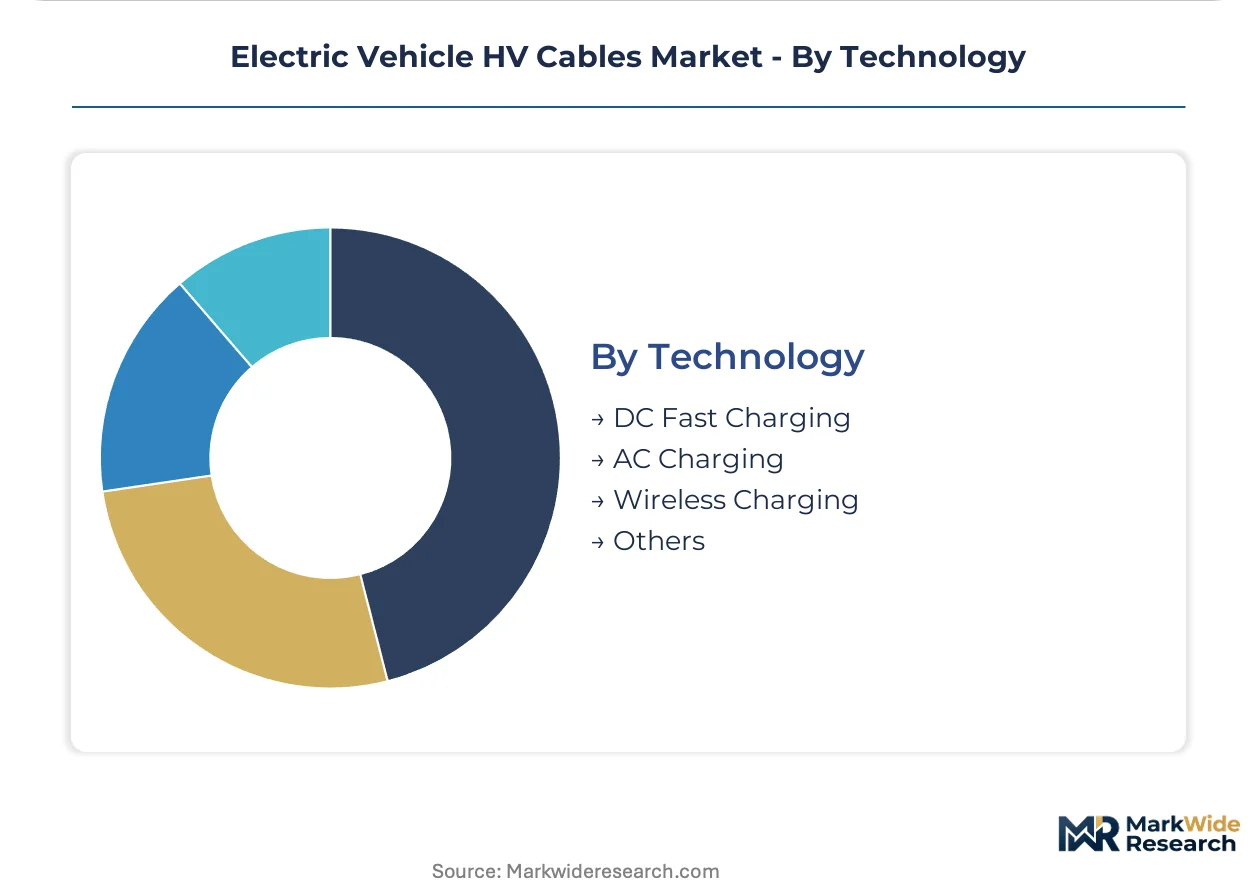
Technology:
Voltage and frequency characteristics segment engineering talent pools, with DC fast charging pulling thermal management specialists from power electronics disciplines.
- DC Fast Charging:High-amperage cable assemblies with liquid-cooled conductors and active thermal monitoring sustain continuous operation above 350kW. Charging network operators in Germany and China deploy these systems along highway corridors, pulling demand for qualification-tested suppliers.
- AC Charging:Onboard charger inlet cables with simpler thermal profiles and lower shielding requirements.
- Wireless Charging:Inductive pad systems requiring high-frequency electromagnetic compatibility expertise transferable from cable engineering teams.
- Others:Pantograph and overhead catenary systems for commercial bus and truck applications.
AC charging retains the installed base majority while DC fast charging climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper processing capacity clusters in China's Yangtze and Pearl River deltas, Germany's industrial corridor, and the US Midwest shape procurement geography for electric vehicle HV cables. Foundry concentration around Shanghai, Shenzhen, and Detroit shortens lead times for high-purity conductor rod while OEM qualification protocols in Stuttgart and Munich freeze supplier selection cycles.
China
Battery-electric vehicle production volume and DC fast charging infrastructure deployment absorb the dominant share of regional cable procurement. MIIT enforces GB/T standards for high-voltage safety and electromagnetic shielding effectiveness. Shanghai and Shenzhen manufacturing zones concentrate copper foundry and extrusion capacity, shortening raw material lead times for stranded conductor assemblies.
Germany
Premium OEM platform qualification cycles extending 18-24 months concentrate demand among established supplier relationships. The EU's F-Gas Regulation and REACH restrictions on halogenated flame retardants force insulation chemistry reformulation. Stuttgart, Munich, and Wolfsburg anchor the industrial corridor where cable validation protocols determine supplier selection.
United States
Domestic battery cell manufacturing expansion under the Inflation Reduction Act pulls demand for localized cable assembly capacity. NHTSA safety standards and state-level zero-emission vehicle mandates accelerate platform electrification timelines. Michigan, Ohio, and Tennessee industrial clusters concentrate emerging extrusion and termination capabilities near new cell production facilities.
Japan
Fluoropolymer resin production concentration for high-temperature jacketing compounds creates supply-side leverage. METI industrial policy supports advanced materials development for next-generation voltage architectures. Osaka and Nagoya manufacturing zones anchor specialty compounder capacity serving both domestic and export cable markets.
India
Production-linked incentive schemes for advanced chemistry cell manufacturing attract cable suppliers to establish localized capabilities. BIS standards for automotive electrical safety create qualification requirements distinct from European and Chinese protocols. Tamil Nadu and Gujarat industrial corridors concentrate emerging battery platform and cable assembly investments.
Electric Vehicle HV Cables Market Competitive Landscape
European automotive heritage specialists and Asian integrated electronics manufacturers split the market between qualification-driven OEM relationships and scale-oriented platform supply. Supplier tiers stratify by validation timeline access, with premium positions requiring 24-month German OEM approval cycles. Three archetypes dominate: legacy automotive cable houses with deep OEM relationships, diversified electronics conglomerates with materials science depth, and regional copper processors with cost-advantaged conductor supply. Competitive moves concentrate on geographic capacity expansion near battery cell clusters and insulation chemistry reformulation to meet fluoropolymer restrictions.
Within the European heritage tier, LEONI AG and Coroplast Fritz Müller GmbH & Co. KG exemplify suppliers whose qualification relationships anchor premium OEM positions. Sumitomo Electric Industries occupies a position bridging Asian battery platform scale with high-voltage shielding expertise. Among diversified industrial cable specialists, Prysmian Group represents the archetype leveraging energy infrastructure extrusion scale across automotive voltage classes. SHANGHAI KMCABLE GROUP sits within the regional processor tier concentrated around Chinese copper foundry clusters.
| Leading Market Players |
|---|
| LEONI AG |
| Sumitomo Electric Industries |
| ACOME Group |
| Coroplast Fritz Müller GmbH & Co. KG |
| Prysmian Group |
| HUBER+SUHNER |
| Champlain Cable Corporation |
| SHANGHAI KMCABLE GROUP |
| JYFT |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor's freight cost volatility feeds directly into cable assembly landed pricing, amplifying margin pressure on European tier-two suppliers while Chinese foundries exploit proximity premiums in domestic battery platform procurement.
Pricing Analysis
Europe's F-Gas Regulation dictates the pricing tier structure across the Electric Vehicle HV Cables Market, separating fluoropolymer-dependent premium formulations from bio-based aromatic polyamide alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with GB/T-compliant shielding commanding premiums and REACH-reformulated compounds carrying compliance surcharges. Cost compression in standard-grade XLPE insulation is intensifying because tier-two suppliers absorb margin pressure from lithium-price volatility in battery pack budgets. Aftermarket providers exhibit highest price sensitivity due to interchangeable catalog specifications, while German OEMs prioritize qualification-tested suppliers over unit cost minimization.
Supply Chain Analysis
Export control regimes on fluoropolymer resin technology limit FEP and PFA compound flows from Japanese and German production clusters, constraining high-temperature jacketing availability for Asian cable assemblers. Supply concentrates in China, Germany, and Japan, with copper rod processing anchored in Shanghai-Shenzhen foundry corridors and specialty compounder capacity in Osaka-Nagoya zones. The supply chain draws from high-purity copper cathode, ceramic filler loadings for silicone rubber hybridization, and braided electromagnetic shielding mesh. Single-source vulnerability in fluoropolymer resin production creates structural risk exposure. Distribution runs through OEM direct procurement contracts, tier-1 supplier module integration, and aftermarket distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical thermal management simulation capability sits at acute scarcity, with cable suppliers competing for specialists capable of modeling joule heating under pulse-width modulation load profiles across 800V and 1500V architectures.
For Market Incumbents: Insulate qualification relationships with German OEMs through accelerated GB/T standard pre-certification investments in Shanghai extrusion facilities, while backward integration into ceramic filler compound production reduces fluoropolymer supply concentration exposure. Lock 24-month validation protocol positions before voltage architecture migration obsoletes incumbent conductor gauges. For New Entrants and Emerging Players: Build out localized extrusion and termination capabilities in Tamil Nadu and Gujarat industrial corridors to capture India PLI scheme tailwinds for advanced chemistry cell manufacturing. Target commercial fleet depot charging infrastructure as the most penetrable segment, where uptime guarantee contracts transfer obsolescence risk from operators to cable suppliers. For Investors and Strategic Acquirers: Regional copper processors with captive foundry supply and emerging GB/T certification capabilities represent the priority acquisition archetype for exposure to China's battery-electric vehicle production volume. Long-term viability hinges on insulation chemistry reformulation agility as F-Gas and REACH restrictions tighten. Watch for MIIT announcements on 1500V DC platform standardization as inflection signal for gauge obsolescence cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Insulation Chemistry Reformulation | REACH and F-Gas compliance forces bio-based aromatic polyamide validation without grandfathering provisions. |
| Copper Foundry Backward Integration | Shanghai and Shenzhen processing clusters shorten lead times for high-purity stranded conductor rod supply. |
| GB/T Pre-Certification Investment | MIIT high-voltage safety protocols accelerate platform consolidation among domestic battery-electric manufacturers. |
| Second-Life Battery Cable Repurposing | Stationary energy storage installations open aftermarket volume for thermal-runaway-resistant automotive-grade assemblies. |
| Wireless Power Transfer Shielding Pivot | Inductive charging pad deployment transfers high-frequency electromagnetic compatibility expertise from cable engineering teams. |
Research Methodology
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement leads, charging network infrastructure planners, and aftermarket distributor category managers anchored the qualitative base for this study. Primary interview data combined with secondary validation from MIIT GB/T standard filings, ECHA REACH restriction updates, vehicle production databases, and customs trade records on copper rod and fluoropolymer resin flows. Bottom-up cable assembly volume estimates triangulated against top-down battery-electric vehicle platform deployment projections.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation modeled by product type, voltage architecture tier, end-user contract structure, installation environment, and charging technology category. CAGRs derived from platform deployment curves, voltage migration timelines, and infrastructure investment trajectories. Forecast inputs incorporated DC fast charging amperage escalation, ceramic filler loading adoption rates, and regional copper processing capacity expansion.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed copper processors or European fluoropolymer compounders would shift outcomes. Material shifts in MIIT voltage standardization, ECHA halogenated flame retardant restriction scope, or lithium price volatility trajectories would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive EMI Shielding Market
Automotive Electrical & Electronics
Electrical Steering Column Lock Market
Automotive Electrical & Electronics
In-Chassis Cooling Market
Automotive Electrical & Electronics
Global Automotive Electronic Lock Differential Market
Automotive Electrical & Electronics
Electrical Park Brake (EPB) Market
Automotive Electrical & Electronics
Automotive Thermal Management System Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market
Automotive Electrical & Electronics
Automotive Clean Cold Technology Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
Automotive Electronic Logging Device (ELD/E-Log) Market
Automotive Electrical & Electronics
Automotive Chassis Electronics Market
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
China Electric Power Steering Market
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market
Automotive Electrical & Electronics
Automotive E/ E Architecture Market