
 Off Highway Vehicles Brake Systems Market | 2026-2036
Off Highway Vehicles Brake Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Off Highway Vehicles Brake Systems Market Outlook
Chinese foundry capacity for heavy-duty brake discs is decoupling from European forging traditions as domestic producers scale ductile iron casting. Brembo leverages motorsport-derived thermal management for off-highway caliper designs. Knorr-Bremse anchors European construction OEM supply through integrated pneumatic actuator systems. ZF Friedrichshafen AG dominates hydraulic brake valve production for agricultural machinery in Germany.
Off highway vehicles brake systems encompass friction-based deceleration assemblies engineered for equipment operating beyond paved surfaces, typically rated for axle loads exceeding 12 tonnes and duty cycles involving mud, dust, and thermal shock. These systems convert kinetic energy through sacrificial friction interfaces to enable controlled stopping of loaders, haul trucks, and harvesters operating on gradients up to 35 percent. Disc brakes now lead the product type landscape in mining applications where heat dissipation requirements exceed drum brake thermal capacity. ABS technology penetration is accelerating fastest in construction fleets as telematics integration demands wheel-speed data for stability control. Mechanical braking retains margin dominance in emerging-market agricultural machinery where cost sensitivity overrides electronic sophistication.
ISO 3450 earthmoving equipment braking performance standards, EPA Tier 4 Final emissions compliance affecting engine braking strategies, and China's GB/T hydraulic safety codes collectively shape product certification requirements and aftermarket parts interchangeability. The EU Machinery Directive's updated brake control reliability clauses are forcing redesigns of pneumatic parking brake circuits for European-sold equipment. Stakeholders must monitor how electrified drivelines in mining trucks redistribute friction brake duty cycles toward emergency-only functions.
Market Dynamics
Electrified drivelines in mining haul trucks are redistributing friction brake duty cycles toward emergency-only functions, compressing replacement part demand while elevating thermal management specifications for residual hydraulic systems.
Growth Catalysts
- ISO 3450 compliance mandates:Earthmoving equipment operators in Australia and Chile must upgrade friction materials to meet revised stopping-distance requirements, forcing systematic component replacement across existing fleets.
- Mining fleet expansion:Indonesian copper and Mongolian coal operations are adding heavy haul trucks rated for 400-tonne payloads, each requiring redundant brake circuits and cooled disc assemblies.
- Thermal management advances:Motorsport-derived heat dissipation coatings are migrating to off-highway caliper designs, extending service intervals in high-gradient applications.
Market Restraints
- Raw material concentration:High-carbon ferroalloy supply for brake disc metallurgy concentrates in Chinese smelters, exposing European and North American foundries to input cost volatility and tariff exposure.
- Technical ceiling for drum brakes:Thermal capacity limitations prevent drum architectures from meeting heat rejection requirements in 300-tonne-class mining trucks, constraining supplier options to disc-based systems.
- Substitution by regenerative braking:Battery-electric and trolley-assist mining trucks capture deceleration energy through motor inversion, reducing friction brake engagement by sixty to eighty percent in downhill haul cycles.
Strategic Opportunities
- Telematics-enabled predictive maintenance:Wheel-speed sensors and brake temperature monitoring are integrating with fleet management platforms, creating recurring software and sensor revenue streams alongside hardware sales.
- Aftermarket service unbundling:Mining operators in Western Australia are separating brake system maintenance from OEM service contracts, opening independent service provider channels for relining and caliper refurbishment.
- EU Machinery Directive tailwinds:Updated brake control reliability clauses for European-sold equipment mandate redundant pneumatic parking circuits, requiring redesign contracts for suppliers with pneumatic actuator expertise.
Industry Challenges
- Skill scarcity in friction engineering:Compound formulation expertise for high-temperature brake pads is concentrating among retiring specialists, complicating R&D pipeline continuity at mid-tier suppliers.
- Certification timeline compression:Simultaneous ISO 3450, EPA Tier 4 Final, and China's GB/T hydraulic safety code compliance is stretching engineering resources across incompatible test protocols.
- Legacy system integration friction:Electronic brake monitoring retrofit kits must interface with thirty-year-old pneumatic architectures in South American mining fleets, multiplying installation complexity and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off Highway Vehicles Brake Systems Market |
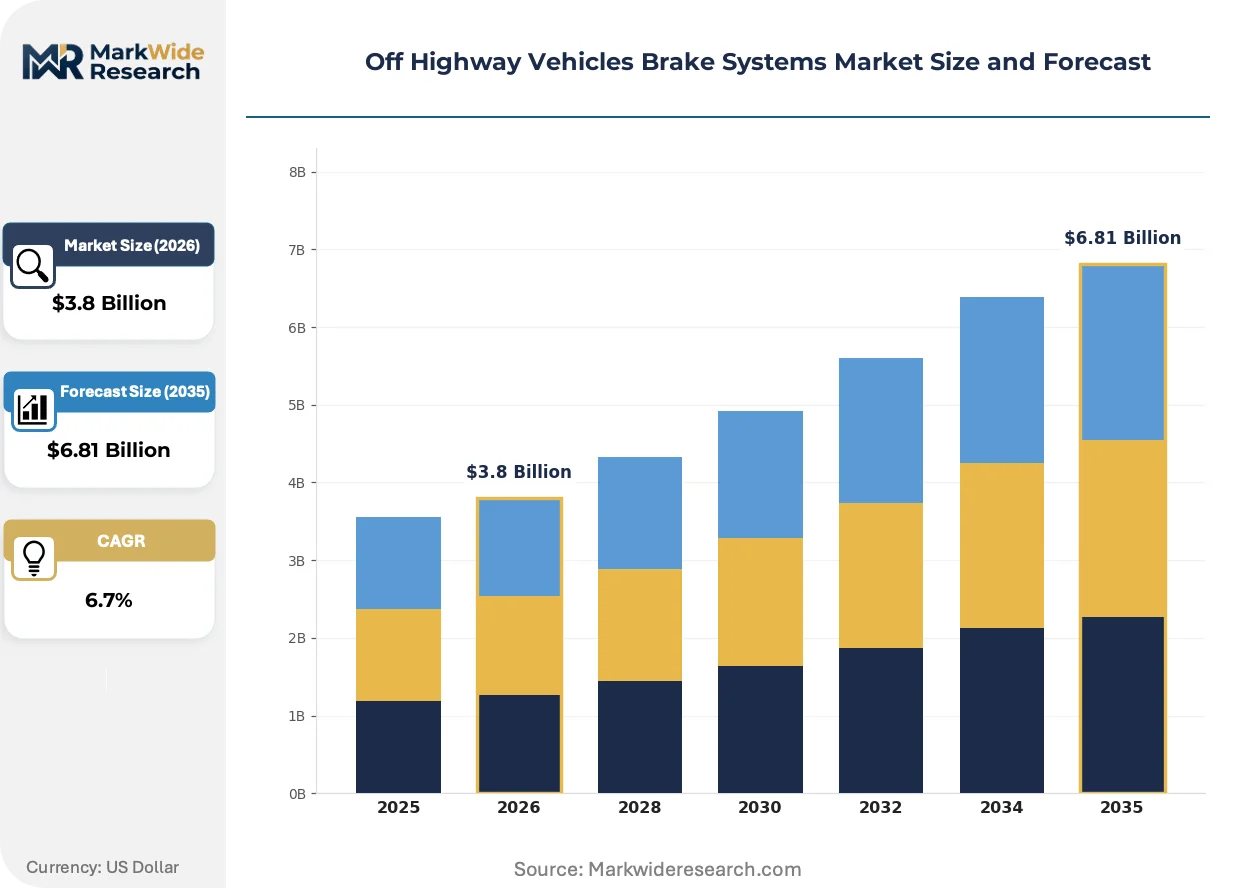
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brakes, Drum Brakes, Hydraulic Brakes, Pneumatic Brakes End User: Agriculture, Construction, Mining, Forestry Technology: ABS, EBD, EBS, Mechanical Application: Heavy-duty Vehicles, Earthmoving Equipment, Agricultural Machinery, Utility Vehicles |
| Companies Covered | Brembo, Carlisle Brake & Friction, Knorr-Bremse, Aisin Seiki, WABCO, ZF Friedrichshafen AG, Robert Bosch GmbH, Hitachi Automotive Systems, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off Highway Vehicles Brake Systems Market Strategic Shifts
Active thermal management and sensor fusion are converging to transform brake systems from passive safety components into data-generating assets that anchor fleet optimization platforms.
Electro-hydraulic brake actuation is integrating wheel-speed data with autonomous haulage systems, enabling predictive slip control on loose surfaces. Mining operators in Western Australia are adopting these integrated architectures fastest, driven by pit-road gradient extremes. The technology is integrating friction management with central vehicle control units, compressing supplier scope from standalone brake vendors to subsystem integrators.
EPA Tier 4 Final emissions compliance is constraining engine braking strategies that previously supplemented friction systems, forcing higher thermal loads onto service brakes. Off-highway OEMs are responding with enlarged cooling passages and forced-air disc designs. Construction equipment sold in North America faces the steepest redesign requirements, as engine brake reliance was historically highest in this segment.
Fleet procurement teams are consolidating brake system sourcing under lifecycle cost frameworks rather than unit-price contracts, unbundling hardware from installation and predictive maintenance services. Channel intermediaries in the Asia-Pacific mining corridor are losing volume to direct OEM-fleet arrangements. This behavioral shift is most visible in Indonesian coal operations, where integrated service contracts now cover five-year brake system performance guarantees.
Off Highway Vehicles Brake Systems Market Segmentation
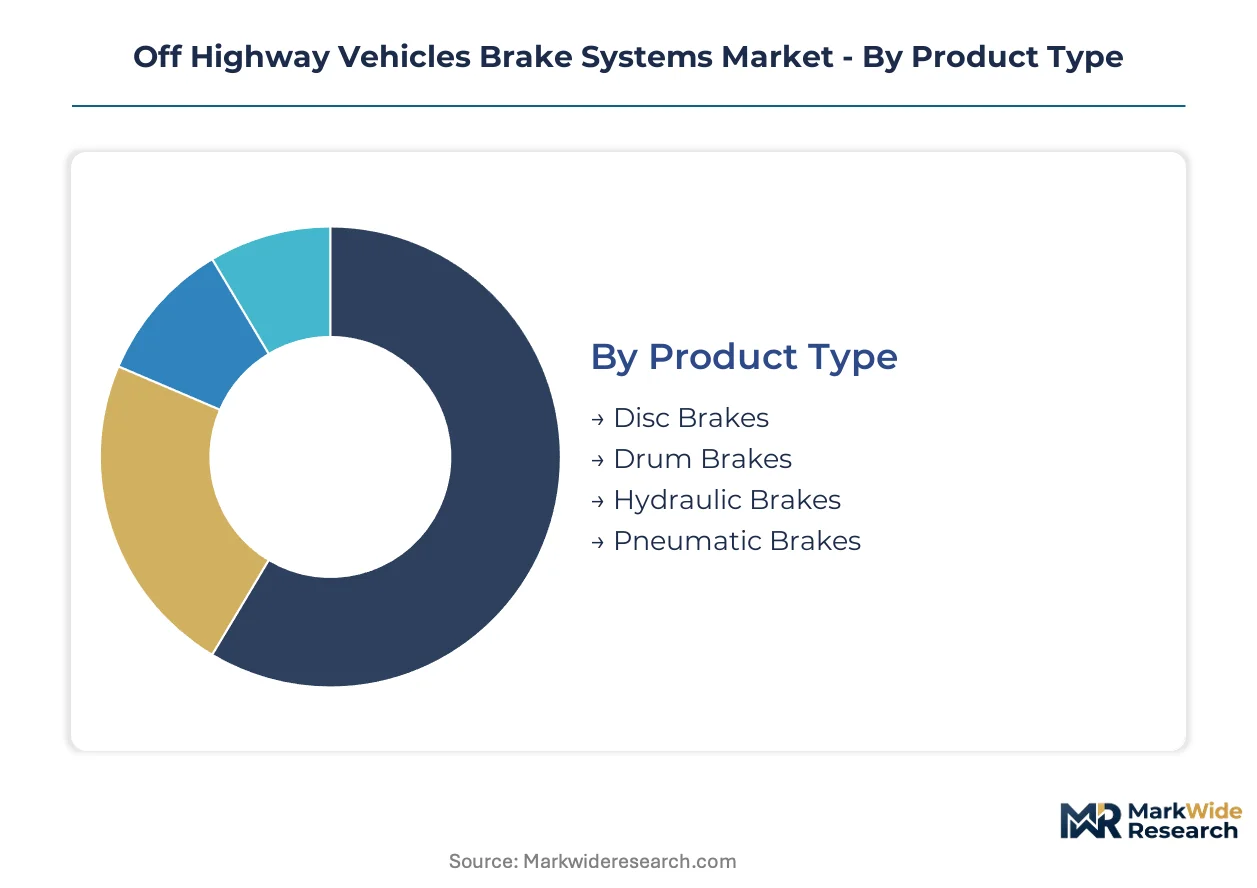
Brake system specifications diverge sharply across equipment categories, with mining haul trucks demanding ISO 3450-certified thermal performance while agricultural machinery prioritizes cost-efficient mechanical architectures. Certification burdens and duty cycle intensity create tiered supplier strategies that fragment procurement patterns across end-use verticals.
Product Type:
ISO 3450 compliance mandates disproportionately burden disc and pneumatic architectures, while drum and hydraulic systems face lighter certification timelines in lower-duty applications.
- Disc Brakes:Cooled disc assemblies with enlarged friction surfaces handle kinetic energy dissipation in 300-tonne-class mining trucks operating on 35 percent gradients. Australian iron ore fleets in Western Australia's Pilbara region specify redundant disc circuits for pit-road descent protocols, compressing replacement cycles under revised stopping-distance requirements.
- Hydraulic Brakes:Closed-loop hydraulic circuits with mineral oil or water-glycol fluids dominate agricultural machinery and mid-size construction equipment. Germany's agricultural OEM supply chains anchor demand here, with ZF Friedrichshafen AG valve production serving Deere and CLAAS harvester platforms where electronic sophistication yields to cost sensitivity.
- Drum Brakes:S-cam and wedge-actuated drum architectures retain foothold in emerging-market agricultural trailers and legacy forestry skidders. Thermal capacity ceilings prevent penetration into heavy mining applications.
- Pneumatic Brakes:Compressed-air systems with spring-applied parking circuits anchor European construction equipment under EU Machinery Directive reliability clauses. Knorr-Bremse integrated actuator designs dominate this specification tier.
Leading the category by volume: Hydraulic Brakes. Growing fastest: Disc Brakes.
End User:
Customer procurement frameworks separate lifecycle-cost optimizers from unit-price buyers, with mining operators unbundling service contracts while agricultural dealers bundle brake hardware into equipment financing.
- Mining:Copper and coal operations in Indonesia and Mongolia specify five-year performance guarantees for cooled disc assemblies on 400-tonne payload haul trucks. Fleet expansion in these corridors concentrates demand for redundant brake circuits and predictive maintenance integration.
- Construction:Earthmoving fleets in Australia and Chile face simultaneous ISO 3450 and EPA Tier 4 Final compliance, forcing friction material upgrades and engine brake strategy redesigns. Telematics penetration is accelerating fastest here as wheel-speed data feeds autonomous stability control.
- Agriculture:Mechanical braking retains dominance where harvester and tractor OEMs in Germany and Brazil prioritize first-cost reduction over electronic sophistication. Replacement part demand concentrates in aftermarket channels rather than factory-fit specifications.
- Forestry:Skidders and forwarders operating in Nordic markets and Pacific Northwest regions require corrosion-resistant caliper coatings for mud and thermal shock duty cycles. Drum brake legacy systems persist in older equipment fleets.
Volume concentration: Mining. Margin expansion: Construction.
Technology:
Electronic sophistication correlates directly with fleet telematics maturity, creating a technology ladder from mechanical systems through sensor-fused integrated architectures.
- ABS:Wheel-speed sensors enabling anti-lock modulation are penetrating construction fleets fastest as telematics platforms demand rotational data for slip control on loose surfaces. Western Australian mining operators lead integration with autonomous haulage systems.
- EBS:Electronic braking systems with electro-pneumatic actuation compress supplier scope from standalone component vendors to subsystem integrators. EU Machinery Directive updates mandate redundant control circuits for European-sold equipment.
- EBD:Electronic brake force distribution remains niche in off-highway applications, constrained by axle load variability that complicates algorithm calibration across uneven terrain.
- Mechanical:Cable and rod-actuated systems persist in agricultural machinery sold through Brazilian and Indian dealer networks where electronic service infrastructure is sparse and operator training limits diagnostic capability.
Widest installed base: Mechanical. Steepest expansion trajectory: ABS.
Application:
Payload rating and gradient exposure determine thermal management specifications, with heavy-duty vehicles and earthmoving equipment driving advanced materials adoption.
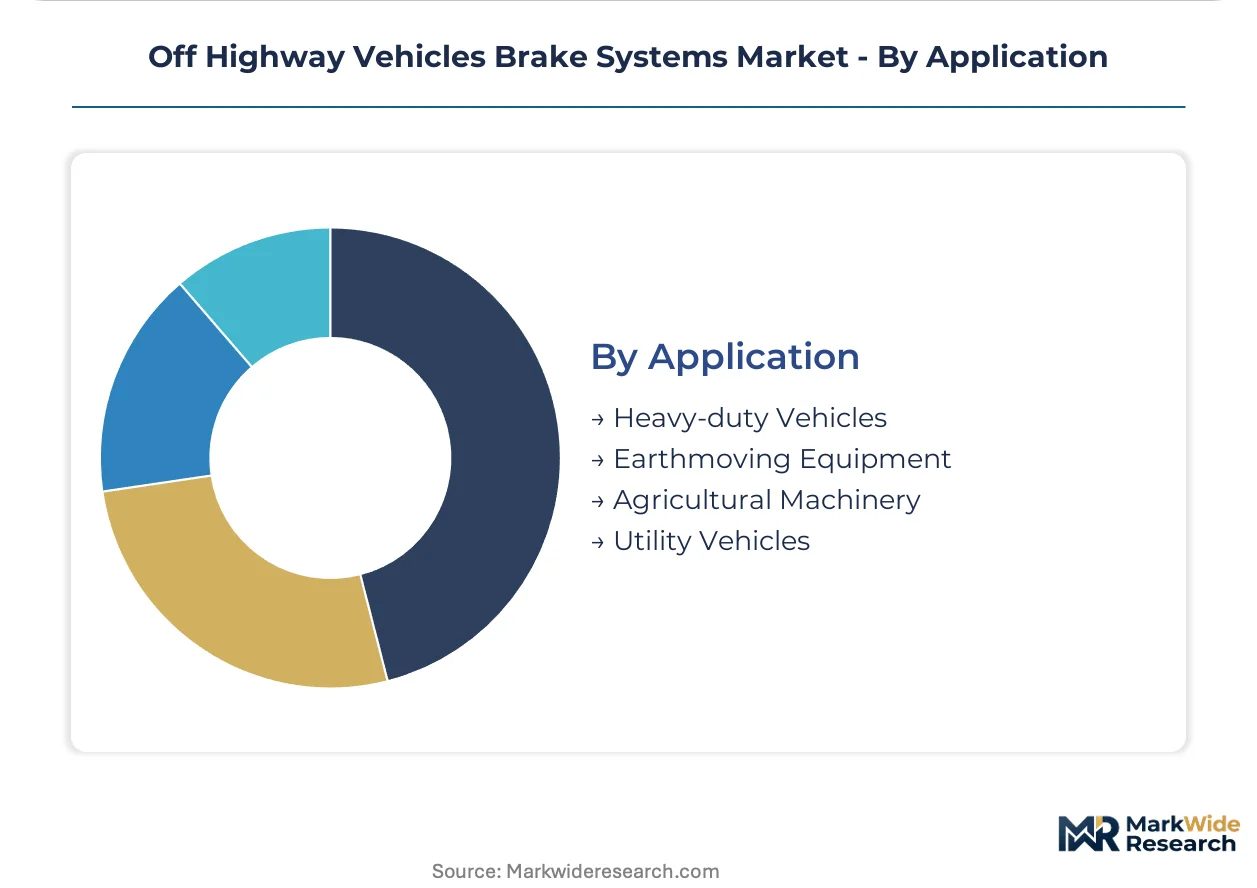
- Heavy-duty Vehicles:Mining haul trucks rated above 200 tonnes require forced-air disc cooling and sacrificial friction interfaces engineered for continuous descent braking. Indonesian copper operations specify these configurations for mountainous terrain.
- Earthmoving Equipment:Loaders and dozers in Australian and Chilean fleets face ISO 3450 stopping-distance mandates that force systematic component replacement. EPA Tier 4 Final constraints on engine braking elevate thermal loads onto service brake systems.
- Agricultural Machinery:Harvesters and tractors in German OEM supply chains prioritize hydraulic valve integration over electronic brake control, with ZF Friedrichshafen AG dominating factory-fit specifications.
- Utility Vehicles:Compact loaders and telehandlers serving rental fleets in North America specify cost-optimized drum or disc configurations with minimal electronic content, prioritizing field serviceability over performance margins.
Revenue concentration: Heavy-duty Vehicles. Technology migration: Earthmoving Equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-carbon ferroalloy smelters in China's Henan and Shandong provinces anchor brake disc metallurgy supply, concentrating raw material sourcing for foundries serving mining and construction equipment manufacturers worldwide.
Australia
Iron ore operations in Western Australia's Pilbara region specify redundant cooled disc circuits for 400-tonne haul trucks descending 35 percent gradients. ISO 3450 compliance mandates from WorkSafe Australia force systematic friction material upgrades across existing earthmoving fleets. Perth-based service providers are unbundling brake maintenance from OEM contracts, opening independent refurbishment channels.
China
Domestic foundries in Shandong and Hebei provinces scale ductile iron casting capacity for heavy-duty brake discs, decoupling from European forging traditions. GB/T hydraulic safety codes from the Standardization Administration of China shape certification requirements for construction equipment exports. The Yangtze River Delta cluster hosts integrated brake actuator assembly for agricultural machinery OEMs.
Germany
Agricultural machinery OEMs in Baden-Württemberg and Lower Saxony specify hydraulic valve integration from ZF Friedrichshafen AG for harvester platforms. EU Machinery Directive updates from Brussels mandate redundant pneumatic parking circuits, forcing redesign contracts for European-sold equipment. Stuttgart-area engineering centers anchor electro-hydraulic brake actuation development for autonomous construction fleets.
Indonesia
Copper mining operations in Papua and Sulawesi specify five-year performance guarantees for cooled disc assemblies on mountainous haul routes. The Ministry of Industry's local content regulations incentivize domestic brake component sourcing for imported mining equipment. Jakarta-based procurement teams consolidate brake system sourcing under integrated service contracts covering predictive maintenance.
Chile
Copper mines in the Atacama Desert face simultaneous ISO 3450 stopping-distance mandates and steep pit-road gradients exceeding 30 percent. CONAMA environmental regulations constrain engine braking strategies, elevating thermal loads onto service brake systems. Antofagasta and Calama host concentrated fleets requiring systematic friction material replacement cycles.
Off Highway Vehicles Brake Systems Market Competitive Environment
Global majors compete with regional champions across thermal management and actuator integration dimensions, producing a tiered structure where European pneumatic specialists, Asian hydraulic fabricators, and motorsport-derived coating innovators occupy distinct competitive positions. The vendor base stratifies into three archetypes: integrated subsystem suppliers, component specialists, and aftermarket service unbundlers. Consolidation pressure concentrates among mid-tier friction material compounders lacking R&D continuity. Dominant competitive moves include backward integration into ferroalloy sourcing and technology licensing for predictive maintenance software.
Among European-based integrated suppliers, Knorr-Bremse and ZF Friedrichshafen AG exemplify the pneumatic-hydraulic subsystem tier, anchoring OEM supply relationships through actuator and valve expertise. Brembo occupies a position within motorsport-derived thermal management specialists, representing coating technology migration from racing to off-highway applications. These three companies illustrate how geographic origin and corporate structure correlate with archetype positioning across the competitive landscape.
| Leading Market Players |
|---|
| Brembo |
| Carlisle Brake & Friction |
| Knorr-Bremse |
| Aisin Seiki |
| WABCO |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Hitachi Automotive Systems |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Backward integration into high-carbon ferroalloy sourcing anchors supplier pricing power across the brake disc value chain, with Chinese foundries in Henan and Shandong provinces capturing margin through captive metallurgy supply while European and North American competitors face tariff-adjusted input volatility.
Pricing Analysis
Warranty bundling unbundling patterns differentiate procurement frameworks across buyer archetypes, with mining operators in Western Australia separating predictive maintenance from hardware acquisition while agricultural OEMs in Brazil embed brake systems into equipment financing. Pricing stratifies across ISO 3450-certified premium tiers, uncertified standard replacement, and economy mechanical configurations for emerging markets. Cost compression in the standard tier intensifies as Indonesian copper fleets consolidate under five-year performance guarantees. Agricultural machinery buyers in India exhibit highest price sensitivity, while Australian iron ore operators prioritize thermal specification over unit cost.
Supply Chain Analysis
Regional distribution centers in Perth, Jakarta, and Santiago anchor hub-and-spoke aftermarket service networks, with cooled disc assemblies and friction materials flowing through mining corridor logistics nodes. Manufacturing concentrates in China, Germany, and Australia, with ductile iron casting capacity expanding in Shandong province and hydraulic valve production anchored in Baden-Württemberg. Supply chains draw from high-carbon ferroalloy smelters, friction compound formulators, and electro-hydraulic actuator specialists. Single-source vulnerability concentrates in Chinese ferroalloy supply, exposing European foundries to input disruption. Distribution runs through OEM-integrated channels for factory-fit specifications and independent service providers for aftermarket refurbishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity constraints in high-carbon ferroalloy metallurgy prop pricing power for integrated suppliers, with Chinese smelter dominance creating structural scarcity that elevates thermal management component valuations.
For Market Incumbents: Deploy predictive maintenance software integration to capture recurring revenue streams as hardware replacement cycles compress under electrified driveline adoption. Deepen backward integration into ferroalloy sourcing to defend margin position against Chinese input cost volatility. Consolidate R&D pipelines around ISO 3450 certification investment as regulatory timelines tighten across Australian and Chilean mining fleets. For New Entrants and Emerging Players: EU Machinery Directive updates in Europe open a window for pneumatic actuator specialists to capture redesign contracts for redundant parking brake circuits. Target aftermarket service unbundling in Western Australia where mining operators separate brake maintenance from OEM contracts. Pursue telematics-enabled sensor fusion as the most penetrable technology tier, integrating wheel-speed monitoring with fleet management platforms for construction equipment autonomy. For Investors and Strategic Acquirers: Exit pathways concentrate in subsystem integration specialists with electro-hydraulic actuation capabilities and motorsport-derived thermal management IP. Long-term viability favors vendors positioned across electrified driveline residual brake demand and predictive maintenance software recurring revenue. Monitor trolley-assist mining truck deployment rates as the critical signal for friction brake duty cycle compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferroalloy Sourcing | Captive supply of high-carbon metallurgy from Henan smelters insulates margin from tariff exposure. |
| Predictive Maintenance Software Development | Telematics integration with Komatsu and Caterpillar fleet platforms creates recurring revenue anchoring. |
| ISO 3450 Certification Investment | WorkSafe Australia mandates force systematic friction material replacement across Pilbara iron ore fleets. |
| Aftermarket Service Unbundling | Perth-based independent providers capture brake refurbishment volume from OEM maintenance contracts. |
| Electro-Hydraulic Actuator Scale-Up | Autonomous haulage integration in Western Australia demands wheel-speed sensor fusion with central control units. |
Study Parameters
Multi-period observation of brake replacement cycle compression, thermal specification migration, and telematics penetration anchored the trend analysis, supplemented by interviews with mining fleet maintenance directors, agricultural OEM procurement teams, construction equipment plant engineers, and aftermarket service channel heads. Secondary validation drew from ISO 3450 certification databases, EPA Tier 4 Final compliance filings, customs records for high-carbon ferroalloy trade flows, and SEC disclosures from brake system suppliers. Bottom-up equipment population modeling triangulated against top-down mining fleet expansion announcements across Indonesia, Australia, and Mongolia.
Segment-weighting applied equipment payload ratings, duty cycle intensity, and regional regulatory cluster maturity to distribute value across product types and end-use verticals. The analytical framework modeled disc, hydraulic, drum, and pneumatic architectures against mining, construction, agriculture, and forestry applications throughout the projection horizon. CAGRs derived from replacement part demand elasticity, fleet expansion rates, and technology substitution curves for regenerative braking adoption. Industry-specific inputs incorporated pit-road gradient exposure data from Pilbara operations and GB/T hydraulic safety code implementation timelines.
The model assumes a particular technology adoption path for electrified driveline penetration; alternative pathways for trolley-assist and battery-electric mining trucks would alter friction brake duty cycle assumptions and residual hardware demand. Forecasts reflect stated assumptions regarding ISO 3450 compliance timelines, ferroalloy supply concentration, and telematics integration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Off-Highway Engine Market
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
Global Electric Off-Highway Equipment Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Mining Vehicle Attachments Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
Off-Road Equipment Market
Off Road Vehicles
Global Automotive Off Highway Engine Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
Electric Utility-Terrain Vehicle (UTV) Market
Off Road Vehicles
Global Off-Highway Vehicle Telematics Market