
 All-Terrain Vehicle Market | 2026-2036
All-Terrain Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
All-Terrain Vehicle Market Analysis
Aftermarket service revenue is narrowing toward authorized dealer networks as OEMs tighten parts distribution and technical training access. Polaris Inc. leverages its North American dealer density to capture recurring maintenance spend. Honda Motor Co., Ltd. sustains loyalty through vertically integrated engine supply and long model lifecycles. BRP competes aggressively in the performance segment with turbocharged engine platforms that command premium pricing.
An all-terrain vehicle is a motorized off-highway vehicle with four low-pressure tires, a straddled seat, and handlebar steering, designed for traversing unpaved surfaces including mud, sand, and rocky inclines. Engine displacements typically range from 50cc to 1000cc, with utility configurations rated for towing loads exceeding 1,300 pounds and hauling capacities approaching 600 pounds. The UTV segment leads unit economics through higher average selling prices and fleet sales to agricultural and commercial operators, while electric powertrains represent the fastest-growing structural category as lithium-ion battery energy density improves and charging infrastructure penetrates rural trail systems. Recreational end users dominate volume but generate lower per-unit margins than military and commercial accounts with multi-year procurement contracts.
The EPA enforces emission thresholds under CFR Title 40 that constrain two-stroke engine configurations and push manufacturers toward fuel-injected four-stroke architectures. NHTSA rollover stability standards and state-level trail access permits shape product design priorities and geographic marketability. OSHA guidelines for workplace ATV operation influence fleet purchasing specifications among agricultural and commercial buyers. Stakeholders must monitor the trajectory of battery-electric range capabilities against trail network charging deployment timelines to calibrate platform investment cycles.
Market Dynamics
Electric powertrain development is compressing engine displacement hierarchies as lithium-ion energy density improvements enable viable trail-range performance without the emission compliance burdens of internal combustion architectures.
Growth Catalysts
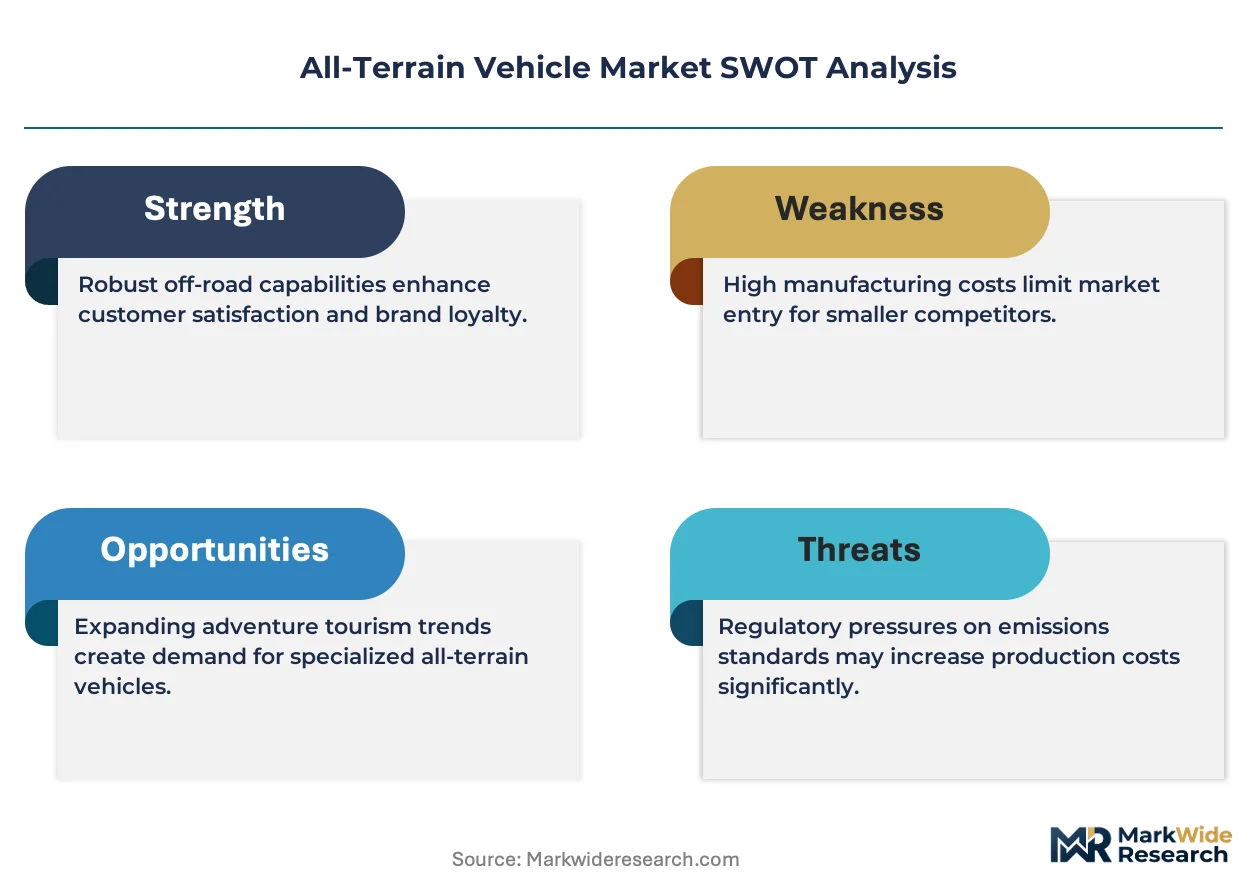
- Recreational trail riding:Off-road tourism infrastructure in Utah, Colorado, and Tennessee is expanding trail network density and permit accessibility for leisure consumers seeking motorized outdoor access.
- EPA emission thresholds under CFR Title 40:These standards are accelerating fuel-injected four-stroke adoption by constraining two-stroke engine configurations and pushing manufacturers toward cleaner combustion architectures.
- Fleet sales to agricultural operators:Commercial buyers with multi-year procurement contracts generate higher per-unit margins than recreational volume purchasers, concentrating OEM investment in utility-rated towing and hauling specifications.
Market Restraints
- Lithium price volatility:Battery-grade lithium carbonate spot markets create input cost instability for electric powertrain assembly, compressing margin predictability for manufacturers scaling EV platforms.
- Rural charging infrastructure gaps:Trail network electrification lags behind vehicle capability deployment, limiting electric ATV practical range in backcountry access corridors across the Mountain West and Pacific Northwest.
- OSHA workplace operation guidelines:These specifications add compliance documentation burdens for fleet purchasers in agriculture and commercial landscaping, lengthening procurement cycles and requiring specialized operator training investments.
Strategic Opportunities
- Military procurement contracts:Defense logistics applications for tactical mobility and base perimeter patrol represent an underpenetrated account type with multi-year volume commitments and premium pricing tolerance.
- Dual-use platform architectures:Modular chassis designs that accept swappable powertrain modules are enabling manufacturers to serve both emission-restricted urban trail systems and unrestricted rural markets from common production lines.
- Authorized dealer network exclusivity:OEMs tightening parts distribution and technical training access are creating recurring revenue capture opportunities through captive aftermarket service and maintenance contracts.
Industry Challenges
- Power electronics thermal management:Electric ATV motor controllers and battery pack cooling systems require specialized engineering talent scarce in traditional small-engine manufacturing regions, creating recruitment bottlenecks for EV platform teams.
- NHTSA rollover stability certification:Extended validation timelines for tip-over protection systems delay new model introductions and compress competitive response windows when rivals launch refreshed architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | All-Terrain Vehicle Market |
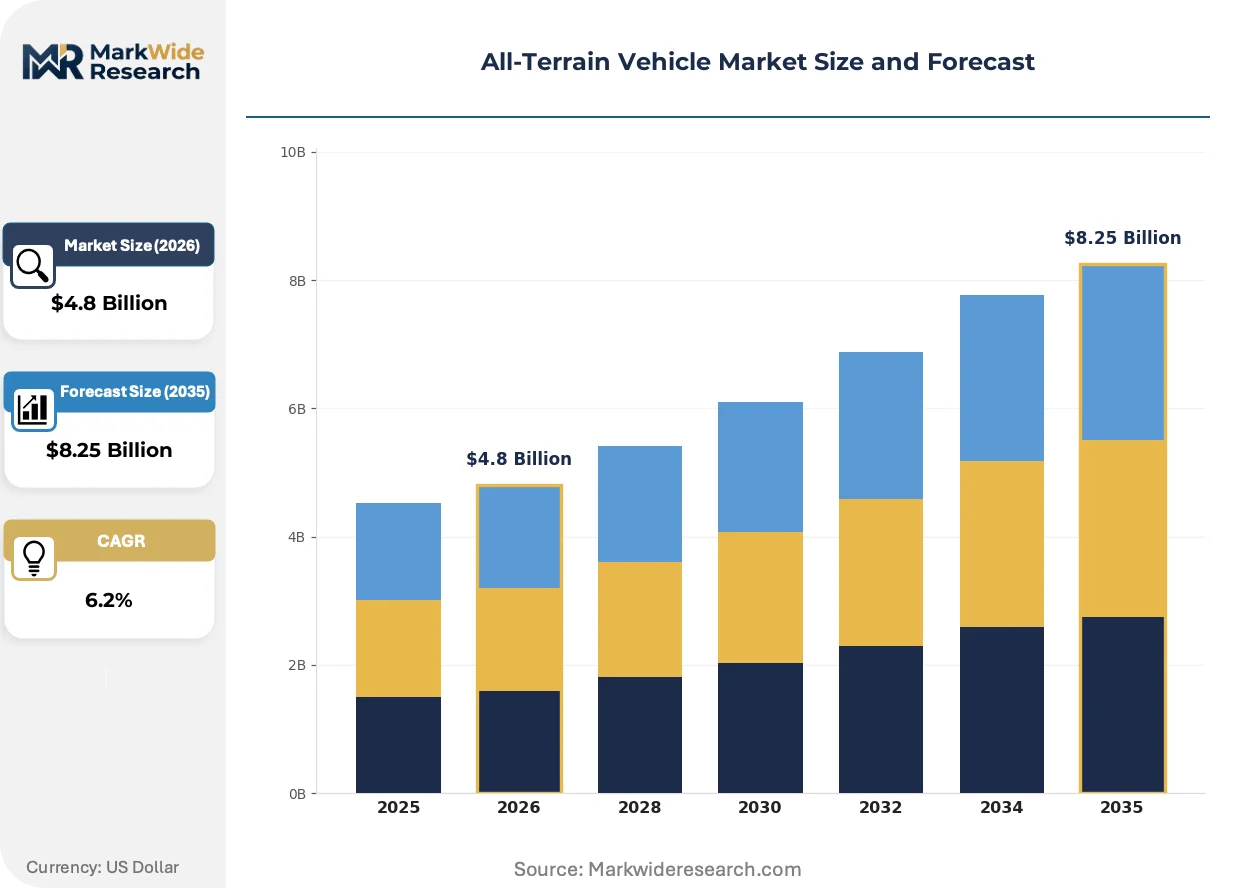
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ATV, UTV, SSV, Dirt Bike End User: Recreational Users, Military, Agricultural, Commercial Power Source: Gasoline, Diesel, Electric, Hybrid Terrain Type: Forest, Desert, Snow, Mud |
| Companies Covered | Polaris Inc., Honda Motor Co., Ltd., BRP, Kawasaki Heavy Industries, Ltd., Yamaha Motor Co., Ltd., CFMOTO, Arctic Cat Inc., Textron Inc., Suzuki Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
All-Terrain Vehicle Market Emerging Trajectories
Powertrain electrification is rewriting competitive differentiation criteria as torque delivery characteristics, battery thermal management, and charging ecosystem partnerships displace engine displacement and horsepower as primary purchase determinants.
Silicon carbide inverter technology is collapsing switching losses in high-voltage electric drivetrains, enabling smaller thermal packages and extended range per kilowatt-hour. Agricultural fleet operators in California's Central Valley are piloting these systems for vineyard slope work where diesel particulate restrictions tighten annually. The technology is collapsing the historical trade-off between electric efficiency and sustained high-load performance that constrained early battery-electric ATV adoption.
EPA emission thresholds under CFR Title 40 are tightening hydrocarbon and nitrogen oxide limits for off-highway recreational vehicles, forcing accelerated fuel system redesigns and exhaust after-treatment integration. Manufacturers are responding by consolidating engine families around common four-stroke architectures with direct injection and closed-loop catalytic control. The utility segment faces the steepest compliance cost escalation due to higher duty cycles and load ratings that stress emission control durability.
Trail access permit systems are fragmenting purchase decisions across jurisdictional boundaries as state-level land management agencies implement divergent electrification mandates and noise ordinances. Buyers in Colorado and Utah now prioritize platform flexibility for multi-state trail networks over single-terrain optimization. This behavioral shift is compressing brand loyalty cycles as consumers evaluate manufacturer charging partnerships and software update roadmaps alongside traditional mechanical reliability metrics.
All-Terrain Vehicle Market Segmentation
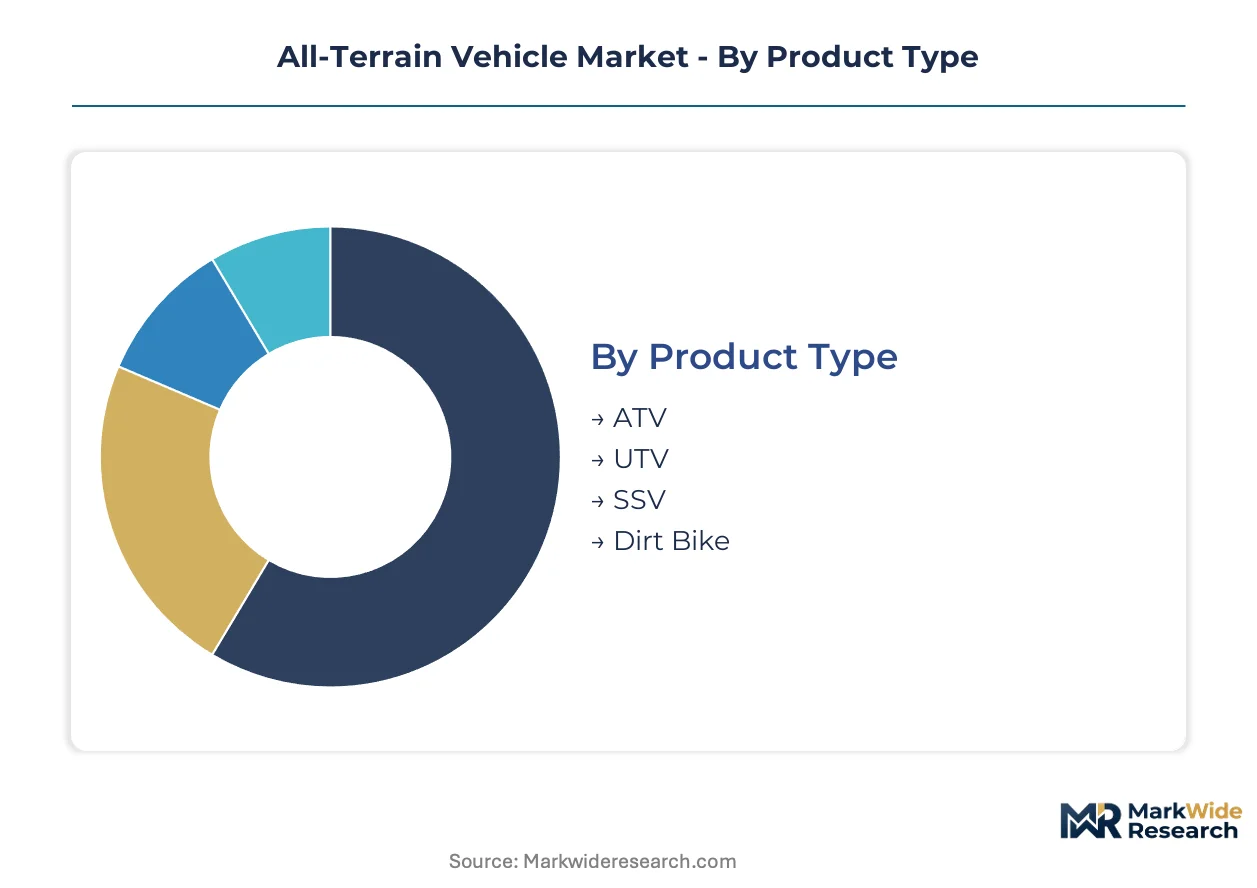
Segmentation in the all-terrain vehicle market reveals divergent engineering priorities across powertrain architectures and duty cycles. Product specifications, end-use requirements, and terrain adaptability create distinct competitive arenas with margin profiles that reward specialized platform development over universal designs.
Product Type:
Cost tier structures separate recreational entry points from premium utility configurations with divergent component sourcing and assembly complexity.
- ATV:Straddled-seat configurations with handlebar steering dominate entry-level recreational access and youth-oriented trail riding. Demand concentrates in Texas, Arizona, and Tennessee where state permit systems favor compact single-rider platforms for narrow trail corridors. EPA emission compliance costs under CFR Title 40 squeeze margin on small-displacement gasoline engines.
- UTV:Side-by-side seating with automotive-style controls commands fleet procurement from California Central Valley agricultural operators and commercial landscaping contractors. The steepest expansion trajectory runs through vineyard slope work and orchard maintenance where diesel particulate restrictions tighten annually.
- SSV:Sport-focused variants with long-travel suspension and reinforced rollover protection target dune recreation in Utah and competitive racing circuits.
- Dirt Bike:Two-wheeled off-highway motorcycles serve motocross competition and single-track trail access with minimal regulatory overlap with four-wheeled categories.
UTV commands the established base. The steepest expansion runs through electric powertrain variants of utility platforms.
End User:
Customer type determines procurement cycle length, pricing tolerance, and aftermarket service attachment rates.
- Recreational Users:Individual leisure purchasers generate volume throughput with seasonal demand peaks tied to trail permit availability in Colorado and Utah. Higher financing penetration and accessory attachment rates offset lower per-unit margins compared to fleet accounts.
- Military:Defense logistics applications for tactical mobility and base perimeter patrol carry multi-year procurement commitments with premium pricing tolerance and stringent reliability specifications.
- Agricultural:Commercial operators in California and Florida prioritize towing capacity and hauling ratings for livestock management and crop maintenance with extended duty cycles.
- Commercial:Landscaping and property maintenance fleets in Texas and North Carolina value platform durability and standardized operator training protocols.
Agricultural and commercial accounts command the established base. The steepest expansion runs through military procurement programs.
Power Source:
Application requirements and regulatory pressure are fragmenting the historical dominance of internal combustion architectures.
- Gasoline:Carbureted and fuel-injected four-stroke engines retain cost advantages for recreational trail riding where refueling infrastructure is ubiquitous. EPA hydrocarbon limits under CFR Title 40 force continuous fuel system redesigns and exhaust after-treatment integration.
- Electric:Lithium-ion battery platforms with silicon carbide inverters enable viable trail-range performance for vineyard slope work and urban-adjacent trail networks. Charging infrastructure gaps in Mountain West backcountry corridors constrain practical deployment.
- Diesel:Compression-ignition architectures serve high-torque agricultural applications with extended operating hours and established refueling logistics.
- Hybrid:Range-extender configurations combining small displacement engines with electric traction motors bridge infrastructure gaps for mixed-terrain commercial operators.
Gasoline commands the established base. The steepest expansion runs through battery-electric platforms.
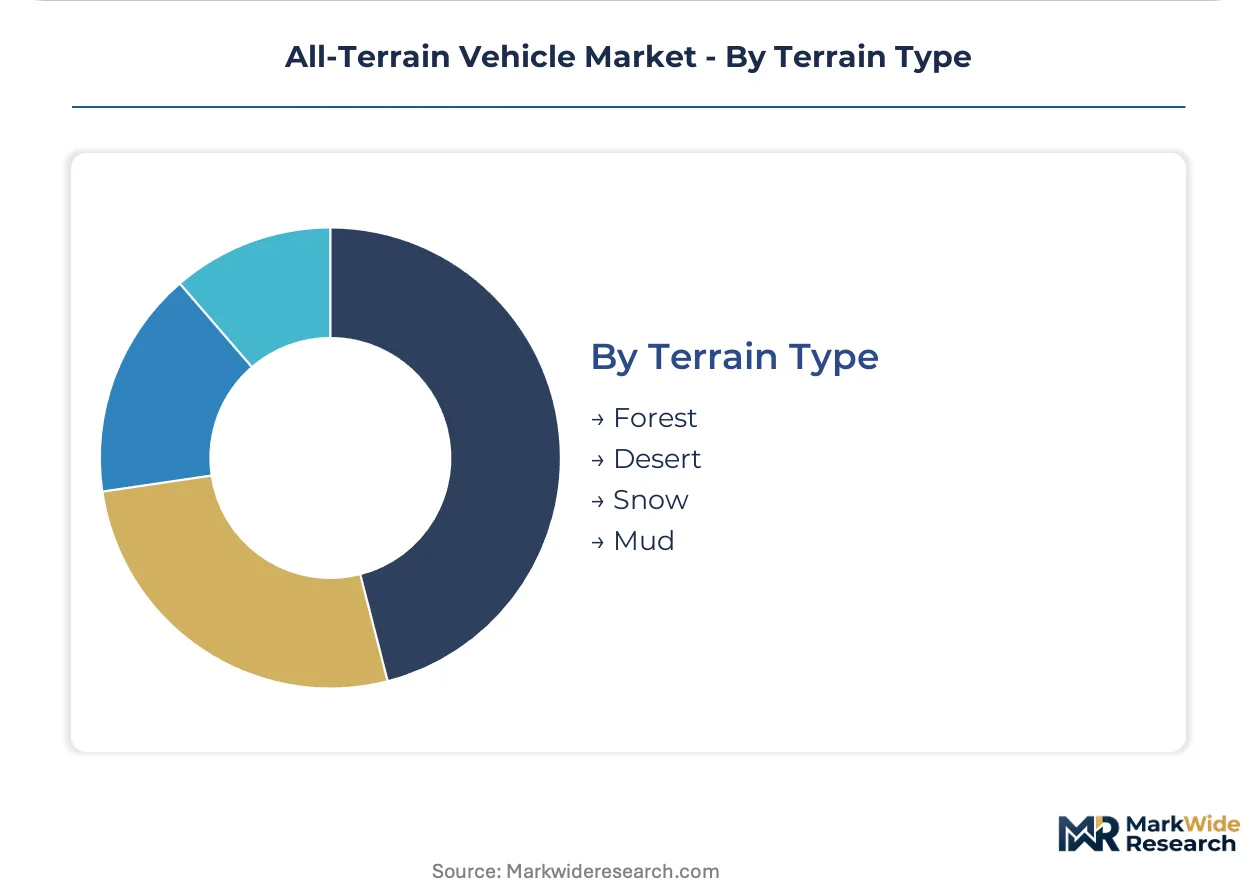
Terrain Type:
Geographic specialization drives suspension geometry, traction systems, and thermal management specifications.
- Forest:Narrow trail configurations with obstacle clearance prioritization serve Pacific Northwest and Appalachian trail networks with wet-weather traction requirements.
- Desert:High-speed dune and rock-crawling platforms with extended suspension travel dominate Utah and Arizona recreation markets with sand-specific cooling system demands.
- Snow:Track conversion kits and specialized lubrication systems enable winter access in Minnesota and Vermont where trail grooming infrastructure supports seasonal motorized recreation.
- Mud:Sealed drivetrain components and elevated air intake systems target Gulf Coast and Carolina low-country hunting and fishing access.
Forest and desert configurations command the established base. The steepest expansion runs through snow-adapted platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recreational buyers in Canada and Australia demonstrate the lowest price elasticity, absorbing premium electric powertrain premiums for trail access compliance, while agricultural operators in Brazil and India negotiate aggressively on utility platform procurement.
United States
Recreational trail riding in Utah, Colorado, and Tennessee drives gasoline ATV volume, while California's Central Valley agricultural operators pilot electric UTV platforms for vineyard compliance. EPA emission thresholds under CFR Title 40 constrain two-stroke engine configurations and accelerate fuel-injected four-stroke adoption. Minneapolis-St. Paul anchors snow-adapted platform development where track conversion kits enable winter trail access.
Canada
Electric powertrain demand concentrates in British Columbia and Ontario where provincial electrification mandates intersect with urban-adjacent trail networks. Health Canada and PMRA coordinate emission and chemical safety standards that exceed federal EPA baselines. Quebec's Laurentian Mountains host expanding off-road tourism infrastructure that favors quieter electric platforms for noise ordinance compliance.
Germany
Agricultural utility applications in Bavaria and Baden-Württemberg prioritize diesel-electric hybrid architectures for extended duty cycles. KBA enforces EU-wide type approval standards that add certification complexity for imported platforms. Stuttgart industrial corridor hosts power electronics engineering clusters developing silicon carbide inverter systems for electric drivetrain thermal management.
Australia
Recreational desert and forest terrain access in Queensland and Western Australia sustains premium gasoline sport platform demand with minimal electrification pressure. TGA coordinates product safety standards that influence regional specification requirements. Perth-based mining operations drive commercial UTV fleet procurement for remote site logistics with severe-duty reliability specifications.
Brazil
Agricultural utility demand in São Paulo and Minas Gerais states dominates volume with price-sensitive procurement patterns and extended financing requirements. ANVISA regulates workplace safety equipment standards that influence fleet operator compliance documentation. Campinas industrial region concentrates assembly operations serving Mercosur duty-free trade zone distribution.
All-Terrain Vehicle Market Vendor Landscape
Integrated powertrain manufacturers and modular platform specialists split the market along electrification readiness lines. The vendor base concentrates among North American and Japanese parent companies with captive engine supply chains, while Chinese and specialized regional fabricators challenge on cost-optimized recreational segments. Two strategic archetypes dominate: vertically integrated engine producers leveraging manufacturing scale, and agile platform developers prioritizing battery-electric speed-to-market. Competitive moves center on dual-use chassis architectures enabling powertrain modularity, and exclusive dealer network contracts capturing aftermarket service revenue.
Within the integrated manufacturer tier, Polaris Inc. and Honda Motor Co., Ltd. occupy positions defined by established North American dealer density and long model lifecycle strategies. BRP exemplifies the performance-specialist archetype with turbocharged platform positioning. CFMOTO represents the emerging cost-competitive challenger from Chinese manufacturing origins. Arctic Cat Inc. and Textron Inc. sit within the diversified industrial conglomerate structure, leveraging cross-divisional engineering resources. Kawasaki Heavy Industries, Ltd., Yamaha Motor Co., Ltd., and Suzuki Motor Corporation anchor the Japanese motorcycle-origin diversification pattern into four-wheeled off-highway categories.
| Leading Market Players |
|---|
| Polaris Inc. |
| Honda Motor Co., Ltd. |
| BRP |
| Kawasaki Heavy Industries, Ltd. |
| Yamaha Motor Co., Ltd. |
| CFMOTO |
| Arctic Cat Inc. |
| Textron Inc. |
| Suzuki Motor Corporation |
| Others |
Supply Flow & Price Mechanics
Minneapolis-St. Paul anchors North American snow-adapted platform assembly, where seasonal production cadences and dedicated track conversion kit manufacturing concentrate OEM pricing power in winter-configured variants. This geographic specialization enables premium capture when trail grooming infrastructure activates across Minnesota and Vermont, while compressing margins on commodity recreational units sourced from higher-volume assembly nodes.
Pricing Analysis
Aftermarket service contracts and authorized dealer maintenance programs drive lifetime value beyond initial unit transactions. Three-tier pricing structure across premium performance, standard utility, and economy recreational levels segments buyers by towing capacity and suspension travel specifications. Pricing pressure stems from lithium carbonate spot volatility feeding into electric powertrain assembly costs. Agricultural fleet operators in California's Central Valley demonstrate lowest price elasticity, absorbing silicon carbide inverter premiums for diesel particulate compliance, while Brazilian commercial buyers negotiate aggressively on extended financing terms.
Supply Chain Analysis
Supplier-financing facilities with 90-120 day payment terms dominate upstream component procurement for Japanese and North American OEMs. Engine block casting concentrates in Japan, Michigan, and Ontario, while lithium-ion cell supply draws from South Korea and China. Single-source vulnerability sits with silicon carbide substrate suppliers for high-voltage inverter production. Distribution runs through exclusive dealer networks capturing captive parts and service revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The all-terrain vehicle market is recovering from a cyclical trough driven by post-pandemic recreational demand normalization and agricultural capital expenditure delays. Fleet replacement cycles and electrification infrastructure deployment will determine recovery velocity.
For Market Incumbents: Insulate margin position by tightening authorized dealer exclusivity on diagnostic software and battery thermal management training. Accelerate backward integration into lithium-ion pack assembly to offset cell supplier pricing power. The EPA's CFR Title 40 hydrocarbon threshold tightening represents the primary regulatory threat requiring continuous fuel system redesign investment. For New Entrants and Emerging Players: Electric vineyard slope work platforms for California Central Valley operators represent the most penetrable entry point, with noise ordinance compliance commanding premium positioning. Military tactical mobility contracts offer multi-year volume commitments with limited incumbent lock-in. Partner with regional charging infrastructure developers to bundle trail network access with unit sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors power electronics specialists with silicon carbide inverter capabilities over legacy engine manufacturers. Long-term viability hinges on dual-use chassis architectures enabling swappable powertrain modules. Watch battery-electric range capabilities against rural trail charging deployment timelines as the inflection indicator for platform investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Use Chassis Architecture | Swappable powertrain modules enable serving emission-restricted urban trails and unrestricted rural markets from common production lines. |
| Authorized Dealer Network Exclusivity | Tightened parts distribution and technical training access captures recurring aftermarket service revenue from fleet and recreational accounts. |
| Silicon Carbide Inverter Integration | Collapsing switching losses extends electric range per kilowatt-hour for vineyard slope work and backcountry trail access. |
| Military Procurement Contract Pursuit | Defense logistics applications for tactical mobility carry multi-year commitments with premium pricing tolerance and stringent reliability specifications. |
| Charging Infrastructure Partnership | Trail network electrification deployment in Mountain West and Pacific Northwest corridors unlocks practical electric ATV range for recreational buyers. |
Methodological Framework
Desk research of EPA emission compliance filings, NHTSA rollover stability certifications, and state-level trail permit databases preceded structured interviews with OEM platform engineers, agricultural fleet procurement managers, and aftermarket service directors. Primary fieldwork with dealership operations in Utah, Colorado, and Tennessee validated volume assumptions against seasonal permit issuance patterns. Secondary triangulation drew from customs trade data, SEC manufacturing disclosures, and power electronics engineering publications. Bottom-up unit economics across powertrain architectures were cross-checked against top-down market sizing from recreational tourism expenditure reports.
Assumptions held fixed include EPA CFR Title 40 emission threshold trajectories and lithium-ion energy density improvement curves, while charging infrastructure deployment pace and military procurement budget allocations were modeled as scenario variables. The analytical framework segmented by product type, end user, power source, and terrain type across the projection horizon. CAGRs were derived from regression analysis of historical fleet replacement cycles and electrification adoption patterns. Forecast inputs incorporated agricultural diesel particulate restriction timelines and state-level trail electrification mandates.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, defense procurement budgets, or battery-grade lithium spot markets would shift the trajectory. Forecasts reflect documented assumptions about regulatory compliance costs and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off-Highway Electric Vehicle Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
Off Highway Hybrid Vehicles Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
Global Off-Highway Vehicle Telematics Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
Off-Highway Vehicle HVAC Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Global Electric Off-Highway Equipment Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market
Off Road Vehicles
Off-Highway Engine Market
Off Road Vehicles
Electric Off-Road Vehicles Market
Off Road Vehicles
All-Terrain Vehicle (ATV) Engines Market
Off Road Vehicles
Off-Highway Vehicle Engine Market