
 Off-Highway Electric Vehicle Market | 2026-2036
Off-Highway Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Highway Electric Vehicle Market Intelligence
The EU Green Deal is pivoting European quarry and tunneling contractors toward zero-emission fleet commitments. Caterpillar Inc. anchors North American electrified mining truck development through its in-house powertrain laboratory investments. Komatsu Ltd. dominates Japanese underground loader electrification with its proprietary battery-thermal management architecture. Deere And Company extends its agricultural electrification roadmap through autonomous electric tractor prototypes.
Off-highway electric vehicles integrate battery-electric, hybrid-electric, or fuel-cell powertrains into non-road mobile machinery rated above 19 kW, replacing diesel combustion for material movement and earthworks in confined or emissions-regulated environments. These machines employ high-voltage architectures, typically 400–800 VDC, with liquid-cooled lithium-ion packs and regenerative braking to sustain repetitive duty cycles in mining headings or construction cuttings. Battery electric technology captures the dominant margin pool as energy density improvements and fast-charging infrastructure reduce total cost of ownership parity thresholds against diesel equivalents. Construction applications lead current deployment volumes, while mining segments represent the fastest-growing adoption trajectory as ventilation cost savings and diesel particulate exposure limits reshape underground operating economics.
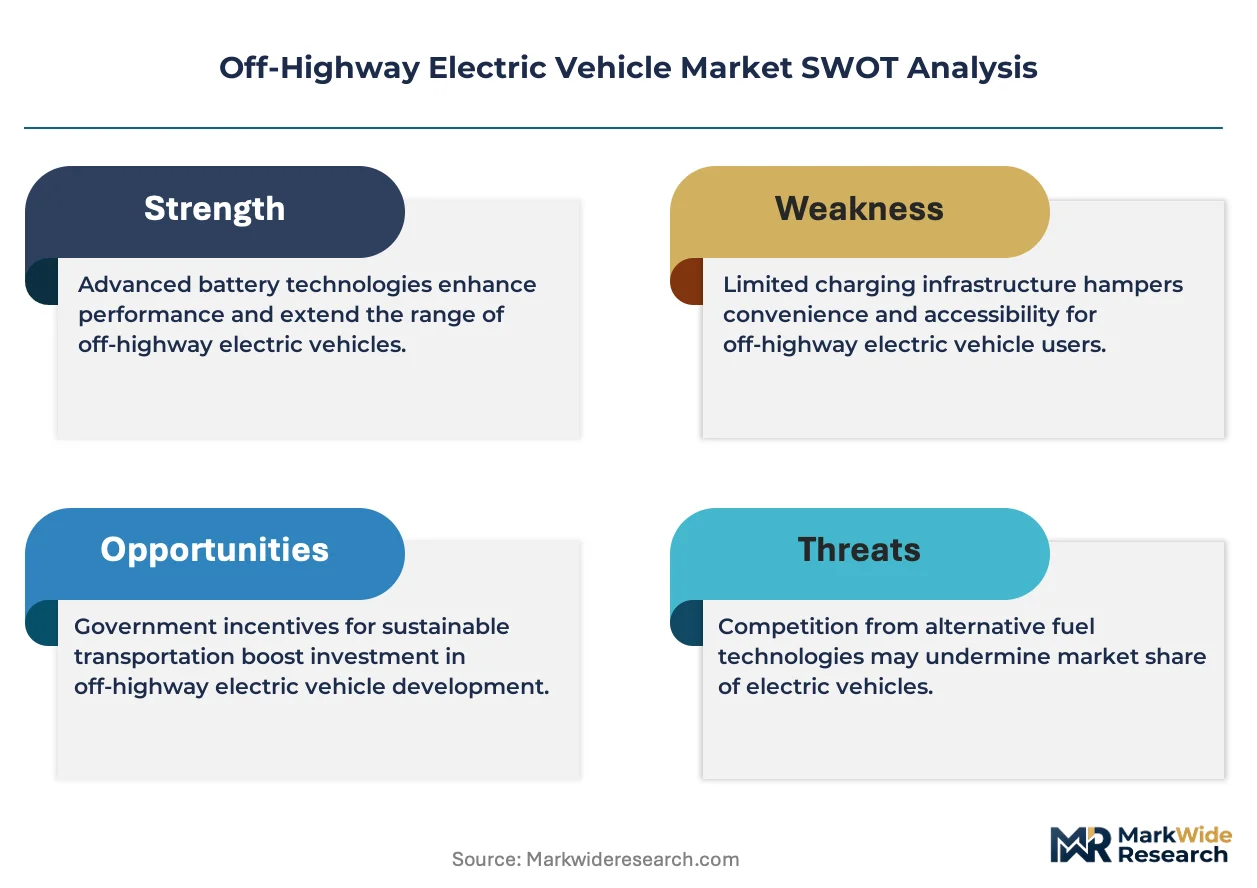
The EPA's Tier 4 Final non-road emissions standards and the EU F-Gas Regulation constrain diesel and refrigerant pathways, compelling OEMs to certify electric alternatives for market access. China's MIIT dual carbon goals and GB standard updates for new energy construction machinery are accelerating domestic battery supply chain localization. Stakeholders must monitor regulatory phase-in calendars and charging infrastructure buildout commitments across their operating geographies to sequence capital deployment.
Market Dynamics
Battery-electric powertrains are compressing diesel equipment viability through total cost of ownership parity achieved at 4,000 annual operating hours in underground mining applications.
Growth Catalysts
- EU F-Gas Regulation:The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in diesel machine cooling systems, forcing OEMs to certify electric alternatives for continued market access in European tunneling and quarry operations.
- Underground ventilation economics:Chilean copper mines are eliminating diesel particulate exposure limits through battery-electric loader fleets that cut ventilation infrastructure capex by removing combustion exhaust requirements.
- Lithium-iron-phosphate chemistry:Cell-to-pack architectures using lithium-iron-phosphate cathodes are extending cycle life beyond 8,000 charge cycles in construction equipment duty profiles.
Market Restraints
- Cathode material concentration:Refined lithium and cobalt processing concentrates in China's Jiangxi and Hunan provinces, exposing non-Chinese OEMs to supply disruption from export licensing delays.
- Fast-charging infrastructure gaps:Mine site electrical distribution systems rated for 480V three-phase power require transformer upgrades to support 350kW DC fast-charging stations for 300kWh battery packs.
- Hydrogen fuel cell substitution:PEM fuel cell systems for 100-ton-class haul trucks are capturing pilot deployment budgets in Australian iron ore operations with 24-hour continuous duty requirements.
Strategic Opportunities
- India's PLI scheme for ACC batteries:India's Production-Linked Incentive scheme for advanced chemistry cell manufacturing is localizing battery supply chains for domestic construction equipment electrification.
- Autonomous-electric convergence:Integration of lidar perception stacks with electric drivetrains is enabling tele-remote operation in underground headings where diesel fumes previously limited automation deployment.
- Second-life battery stationary storage:Retired construction equipment battery packs are repurposing for mine site peak-shaving applications, creating circular revenue streams for fleet operators.
Industry Challenges
- High-voltage technician scarcity:OEMs face 18-month training pipelines for technicians certified to service 800VDC architectures and thermal runaway containment protocols.
- Homologation timeline compression:UN ECE R100 battery safety certification and regional electromagnetic compatibility testing are extending new model launch cycles by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Highway Electric Vehicle Market |
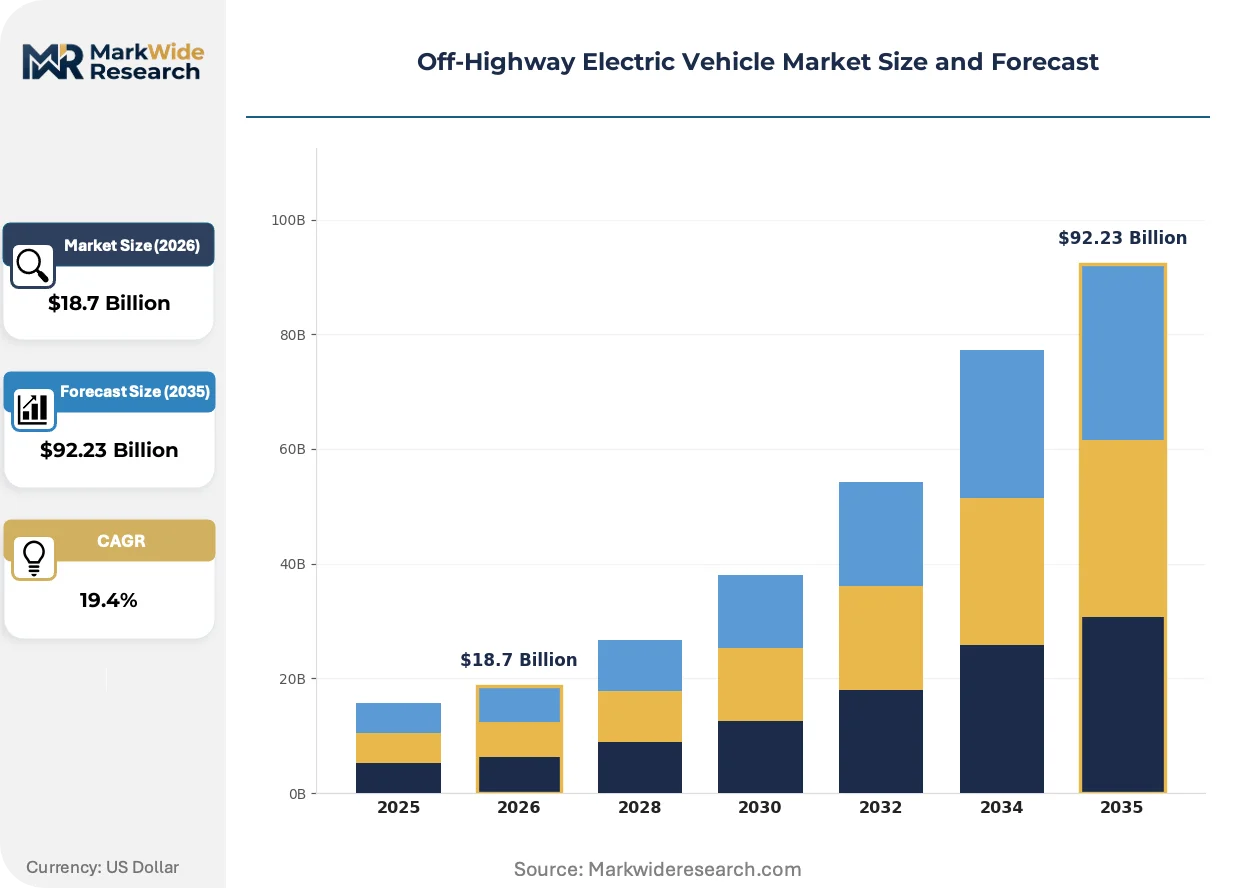
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agricultural, Construction, Mining, Forestry Technology: Battery Electric, Hybrid Electric, Fuel Cell, Plug-in Hybrid End User: OE Manufacturers, Dealers, Rental Companies, Fleet Operators Application: Material Handling, Land Preparation, Excavation, Transportation |
| Companies Covered | Komatsu Ltd., JC Bamford Excavators Ltd., Caterpillar Inc., Kubota Corporation, Cnh Industrial NV, Volvo Construction Equipment AB, Hitachi Construction Machinery Co. Ltd., Liebherr Group, Deere And Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Highway Electric Vehicle Market Strategic Shifts & Innovations
Solid-state battery prototyping and silicon-carbide power electronics are converging to reshape heavy equipment electrification architectures. These advances are compressing charging windows and extending operational availability in continuous-duty applications.
Lithium-metal anode solid-state cells are overtaking conventional liquid-electrolyte designs in underground loader prototypes tested by European mining contractors. These cells deliver 400 Wh/kg energy density, enabling 12-hour shifts without mid-cycle charging. The structural consequence is that diesel-equipment resale values are collapsing in emissions-regulated jurisdictions as electric alternatives achieve functional parity.
China's MIIT dual carbon goals are mandating new energy construction machinery penetration rates that force domestic OEMs to localize battery supply chains. The policy requires 25% electric share in new equipment sales for specified machinery categories. Shanxi Province coal modernization zones are responding with dedicated charging corridors and preferential electricity tariffs for battery-electric fleet operators.
Equipment-as-a-service contracting is replacing capital purchase models in North American quarry operations with high utilization certainty. Fleet managers are unbundling maintenance and energy costs into per-tonne pricing structures. This shift is most visible in limestone aggregate operations where 6,000+ annual operating hours justify full-electric conversion with guaranteed uptime clauses.
Off-Highway Electric Vehicle Market Segmentation
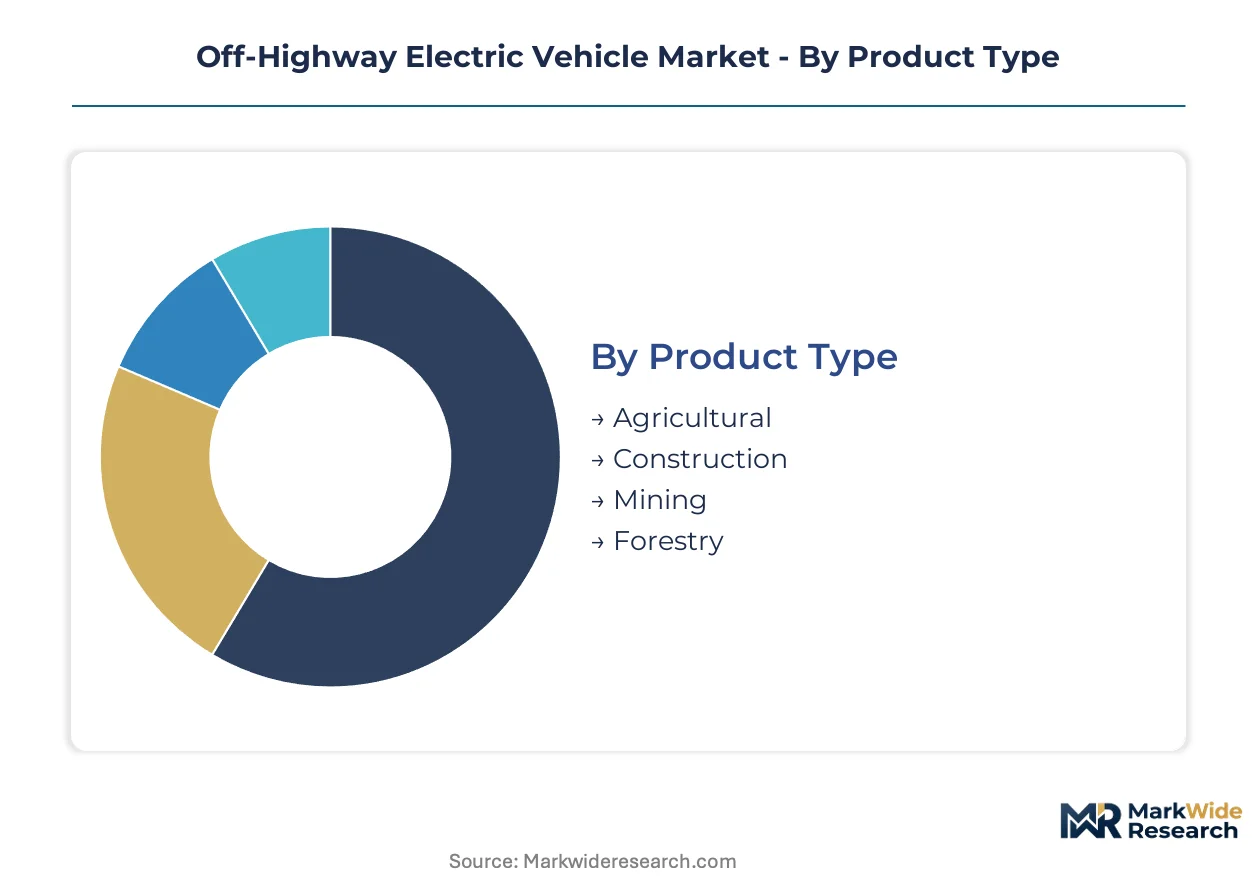
Segmentation in off-highway electric vehicles reveals divergent capital requirements across duty cycles and infrastructure dependencies. Equipment buyers sequence electrification investments based on utilization intensity, regulatory exposure, and charging feasibility rather than uniform technology substitution.
Product Type:
Mining equipment demands the steepest upfront capital outlays due to battery scale and explosion-proofing requirements, while agricultural machinery benefits from lower per-unit energy storage needs and established dealer service networks.
- Mining:Underground loaders and haul trucks integrate 300-500 kWh liquid-cooled battery packs with thermal runaway containment systems. Chilean copper operations in the Atacama region are consolidating procurement around battery-electric fleets to eliminate diesel particulate exposure and slash ventilation infrastructure spending.
- Construction:Excavators and wheel loaders employ 100-200 kWh architectures with regenerative hydraulics. China's Shanxi Province coal modernization zones are concentrating demand for electric excavators through preferential electricity tariffs and dedicated charging corridors mandated under MIIT dual carbon goals.
- Agricultural:Tractors and harvesters utilize modular 50-150 kWh packs with field-swappable configurations. European arable farming cooperatives are piloting autonomous electric tractors under EU Green Deal emissions compliance timelines.
- Forestry:Forwarders and harvesters require reinforced battery enclosures for impact resistance in remote terrain. Nordic forestry contractors are testing hybrid-electric architectures where charging infrastructure remains sparse.
Construction absorbs the bulk of installed capacity; mining is expanding most quickly.
Technology:
Powertrain selection hinges on duty cycle continuity and energy replenishment windows rather than technology maturity alone.
- Battery Electric:Pure-electric architectures with 400-800 VDC systems and lithium-iron-phosphate cells dominate underground mining where ventilation cost savings justify infrastructure investment. Cell-to-pack designs are extending cycle life beyond 8,000 charge cycles in repetitive loading operations.
- Hybrid Electric:Diesel-electric series hybrids with downsized combustion engines serve forestry and remote construction sites lacking grid connectivity. These systems recover braking energy while maintaining operational range independence.
- Plug-in Hybrid:Grid-chargeable hybrids with 30-80 kWh electric range buffer offer transitional economics for mixed-duty agricultural fleets. European contractors are deploying these for seasonal intensity peaks without full charging infrastructure commitment.
- Fuel Cell:PEM hydrogen systems target 100-ton-class haul trucks in Australian iron ore operations with continuous 24-hour duty requirements. Pilot deployments are capturing budgets where battery energy density limits operational availability.
Battery electric commands the dominant investment share; fuel cell is gaining traction fastest in ultra-heavy continuous duty.
End User:
Procurement authority concentrates with entities capable of underwriting charging infrastructure and managing energy cost volatility.
- Fleet Operators:Large-scale mining and aggregate companies with 6,000+ annual operating hours per machine are driving equipment-as-a-service contracting models. These operators unbundle maintenance and energy into per-tonne pricing with guaranteed uptime clauses.
- OE Manufacturers:Original equipment manufacturers with captive financing arms are structuring battery-leasing arrangements to reduce customer capital barriers. Caterpillar and Komatsu are deploying this model for underground loader fleets in emissions-regulated jurisdictions.
- Rental Companies:Short-term equipment providers face utilization risk from charging downtime and are concentrating electric offerings in urban construction markets with established fast-charging networks.
- Dealers:Authorized distribution networks are absorbing technician training costs for high-voltage service certification, extending new model launch cycles by 8-12 months due to homologation requirements.
Fleet operators deploy the majority of units; rental channels are scaling fastest where charging infrastructure density permits.
Application:
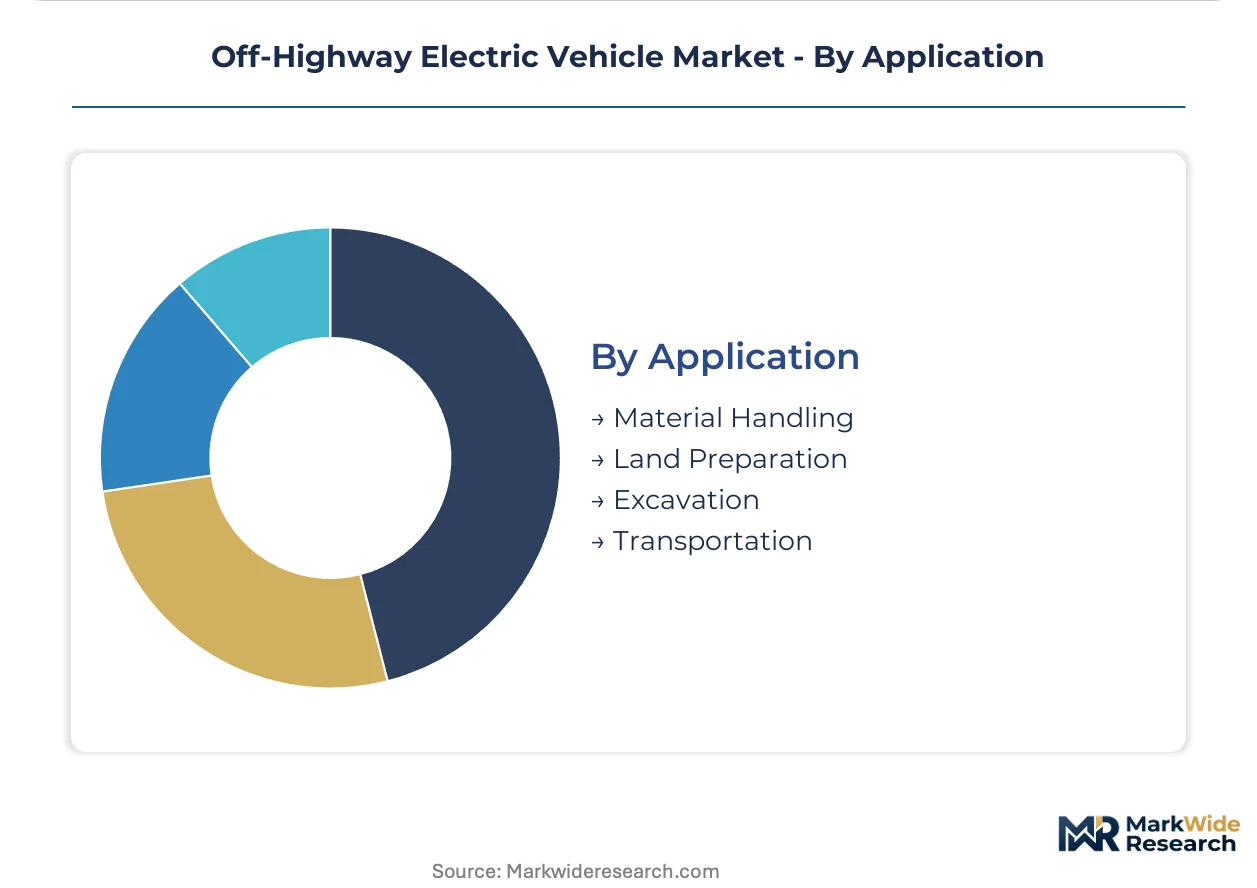
Functional use cases determine battery sizing, thermal management intensity, and automation integration potential.
- Excavation:High-torque digging operations with intermittent peak power demands favor battery-electric systems with supercapacitor buffering. Urban tunneling contractors in Germany are specifying electric excavators under EU F-Gas Regulation compliance deadlines.
- Material Handling:Repetitive loading and stockpiling cycles with predictable energy consumption profiles enable precise total cost of ownership calculations. Underground mining headings are prioritizing electric loaders for ventilation cost reduction.
- Transportation:Long-haul haul truck duty cycles with variable gradients strain pure-electric range; Australian iron ore operators are piloting fuel cell alternatives for 300-ton-class vehicles.
- Land Preparation:Agricultural tillage and seeding operations with seasonal utilization patterns suit modular battery swapping or plug-in hybrid architectures where grid access is seasonal.
Material handling anchors current deployment volumes; excavation is climbing the fastest as urban emissions zones expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanxi Province's coal modernization zones concentrate China's electric construction equipment deployment through MIIT-mandated charging corridors and preferential industrial electricity tariffs. The EU Green Deal's machinery emissions standards are compressing diesel viability across European quarry operations. Underground copper mines in Chile's Atacama region are consolidating procurement around battery-electric fleets.
China
Shanxi Province coal modernization zones drive electric excavator demand through dedicated charging infrastructure and preferential electricity tariffs. MIIT dual carbon goals mandate 25% electric share in new construction machinery sales. Domestic OEMs are localizing lithium-iron-phosphate supply chains in Jiangxi and Hunan provinces to reduce import dependency.
United States
Limestone aggregate operations in the Midwest and Southeast are piloting equipment-as-a-service contracting with guaranteed uptime clauses. EPA Tier 4 Final non-road emissions standards constrain diesel refrigerant pathways for tunneling contractors. Caterpillar's in-house powertrain laboratory in Illinois anchors North American electrified mining truck development.
Germany
Urban tunneling contractors in the Ruhr and Bavaria regions specify electric excavators under EU F-Gas Regulation compliance deadlines. ECHA REACH restrictions on industrial chemicals extend to battery material processing standards. Stuttgart's automotive supplier ecosystem is repurposing powertrain expertise for construction equipment electrification.
Chile
Underground copper mines in the Atacama Desert eliminate diesel particulate exposure through battery-electric loader fleets. National mining regulators enforce ventilation cost accountability that favors zero-emission equipment. Santiago-based procurement consortia are standardizing 300-500 kWh battery specifications across Codelco and private operators.
Australia
Pilbara iron ore operations pilot PEM fuel cell systems for 100-ton-class haul trucks with 24-hour continuous duty requirements. State mining safety authorities calculate ventilation savings from electric fleet conversions. Perth-based equipment lessors structure hydrogen infrastructure partnerships for remote site deployments.
Off-Highway Electric Vehicle Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates with captive financing arms and construction equipment specialists with electrification roadmaps. Tier-one positioning requires integrated powertrain laboratories and certified high-voltage service networks. Three archetypes dominate: mining-focused electrification leaders, agricultural machinery diversifiers, and construction equipment full-liners. Strategic moves concentrate on battery-leasing arrangements to reduce customer capital barriers and autonomous-electric convergence for underground tele-remote operation.
Within the diversified industrial tier, Caterpillar Inc., Komatsu Ltd., and Deere And Company exemplify contrasting geographic and sectoral emphases. Caterpillar anchors North American mining truck electrification through Illinois-based powertrain development. Komatsu occupies a position in Japanese underground loader electrification with proprietary thermal management architectures. Deere represents agricultural machinery diversification into autonomous electric tractor prototypes. These three conglomerates sit within distinct regulatory exposure zones—EPA Tier 4 Final, METI carbon neutrality targets, and EU Green Deal compliance timelines respectively—shaping their electrification investment sequencing.
| Leading Market Players |
|---|
| Komatsu Ltd. |
| JC Bamford Excavators Ltd. |
| Caterpillar Inc. |
| Kubota Corporation |
| Cnh Industrial NV |
| Volvo Construction Equipment AB |
| Hitachi Construction Machinery Co. Ltd. |
| Liebherr Group |
| Deere And Company |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between UN ECE R100-compliant architectures and pre-certified legacy designs splits pricing power between premium OEMs and cost-pressured challengers. This divergence concentrates battery procurement through qualified tier-one cell suppliers while forcing secondary players toward spot-market lithium-iron-phosphate sourcing.
Pricing Analysis
Throughput-guarantee contracting anchors value-based pricing for underground mining fleets, with per-tonne rates bundling energy and maintenance into uptime commitments. Price differentiation separates explosion-proof certified loaders from surface-construction equivalents, with ventilation-cost savings justifying 40% capital premiums in Chilean copper operations. Cost compression in mid-tier construction equipment intensifies as China's MIIT localization mandates flood domestic markets with cell-to-pack architectures. Fleet operators with 6,000+ annual hours show lowest price sensitivity; rental channels facing utilization risk demand steepest discounts.
Supply Chain Analysis
Dual-sourcing requirements from non-Chinese OEMs mandate qualified cell suppliers in South Korea and Japan alongside dominant Chinese lithium-iron-phosphate producers. Battery pack assembly draws from refined lithium carbonate in Chile's Atacama salares, cathode precursor from Jiangxi province, and separator membranes from Japanese petrochemical specialists. Single-source vulnerability concentrates in cobalt hydroxide refining, where export licensing delays from the DRC and Zambia disrupt just-in-time production schedules. Distribution runs through OEM captive financing arms structuring battery-leasing arrangements to defer customer capital outlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's machinery emissions standards erect a cost-of-compliance barrier that rewards early-certification investments while stranding pre-certified inventory. This regulatory moat consolidates procurement authority with OEMs possessing UN ECE R100 testing capabilities and certified high-voltage service networks.
For Market Incumbents: Anticipate hydrogen fuel cell substitution in Australian iron ore haul trucks by securing PEM system partnerships before pilot budgets crystallize around rival suppliers. Defend margin position through backward integration into lithium-iron-phosphate cell production in India's PLI-accredited manufacturing zones, reducing exposure to China's export licensing volatility.
For New Entrants and Emerging Players: Mid-scale limestone aggregate contractors in the US Midwest represent an underserved buyer archetype receptive to equipment-as-a-service contracting with guaranteed uptime clauses. Target this segment through telematics-integrated battery-leasing models that unbundle capital risk from operational commitment, bypassing entrenched dealer networks.
For Investors and Strategic Acquirers: Re-rating potential sits with autonomous-electric convergence specialists given the lidar-perception-stack integration catalyst reshaping underground tele-remote operation. Long-term viability favors targets with captive high-voltage technician training pipelines and MIIT dual-carbon compliance certification. Watch for inflection when Chilean mining regulators mandate ventilation-cost accounting disclosure across Codelco and private operator filings.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Leasing Arrangement Deployment | Caterpillar and Komatsu reduce customer capital barriers through captive financing arms structuring per-cycle energy costs. |
| High-Voltage Technician Certification Pipeline | OEMs extend service network coverage by absorbing 18-month training costs for 800VDC thermal runaway containment protocols. |
| Autonomous-Electric Convergence Investment | Lidar perception stack integration enables tele-remote operation in Chilean headings where diesel fumes previously limited automation. |
| Second-Life Battery Stationary Storage | Retired construction equipment packs repurpose for mine site peak-shaving, creating circular revenue streams for fleet operators. |
| PLI-Accredited Cell Manufacturing Localization | India's advanced chemistry cell scheme anchors domestic supply chains for construction equipment electrification outside China. |
Research Approach
Multi-period observation of battery procurement volumes, charging infrastructure deployment timelines, and regulatory certification calendars anchored the trend analysis, supplemented by interviews with underground mining maintenance directors, OEM platform engineers, fleet procurement managers, and aftermarket service heads. Secondary validation drew from EPA Tier 4 Final filings, EU F-Gas Regulation implementation notices, MIIT new energy machinery penetration data, and SEC equipment-manufacturer disclosures. Bottom-up unit deployment tracking triangulated against top-down TCO parity modeling across operating hour thresholds.
Input-output matrices mapped battery pack cost trajectories against diesel fuel price volatility and ventilation infrastructure spending to generate segment-specific adoption curves across the projection horizon. Segmentation dimensions modeled include equipment class, powertrain architecture, annual utilization intensity, and regional regulatory exposure cluster. CAGRs derived from logistic diffusion curves fitted to early-adopter procurement data and infrastructure commitment announcements. Industry-specific forecast inputs incorporated lithium-iron-phosphate cell price forecasts and mine site electrical upgrade capex schedules.
Revisions become necessary when battery energy density improvements accelerate TCO parity timelines or when hydrogen fuel cell pilots in Australian iron ore achieve operational scale beyond current demonstration parameters. Deviation in China's export licensing enforcement for refined lithium and cobalt would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off Highway Hybrid Vehicles Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
Mining Vehicle Attachments Market
Off Road Vehicles
Off-Highway Vehicle HVAC Market
Off Road Vehicles
All-Terrain Vehicle Market
Off Road Vehicles
Off Highway Vehicles Brake Systems Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Off-Highway Wheels Market
Off Road Vehicles
Snow Scooter Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
All-Terrain Vehicle (ATV) Engines Market
Off Road Vehicles
Off Road Motorcycles Market