
 Utility Terrain Vehicles (UTV) Market | 2026-2036
Utility Terrain Vehicles (UTV) Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Terrain Vehicles (UTV) Market Analytics
Multi-source chassis sourcing is decoupling from traditional captive foundry models across the UTV supply base. Polaris Inc. leverages vertical integration in powertrain manufacturing to control cost positions in recreational segments. BRP Inc. competes through specialized suspension engineering that dominates high-performance trail categories. John Deere anchors its agricultural UTV line with dealer network density across rural North America.
Utility Terrain Vehicles are four- to six-wheeled off-highway machines with payload capacities typically ranging from 500 to 2,000 pounds, engineered for traversing unimproved terrain at speeds below 50 mph across commercial, agricultural, and recreational duties. Agricultural UTVs command the largest installed base due to year-round utility demands in crop and livestock operations, while electric powertrains represent the fastest-expanding engine category as fleet operators seek to reduce fuel costs and maintenance intervals. Recreational UTVs concentrate margin pools in accessorized premium configurations, whereas commercial end users prioritize diesel durability and service interval predictability.
EPA Tier 4 emissions standards and NHTSA rollover protective structure mandates shape powertrain architecture and chassis design requirements for manufacturers selling into the United States. OSHA workplace safety directives influence fleet procurement specifications for commercial and industrial operators requiring operator protection systems. Stakeholders must monitor battery supply chain localization progress and charging infrastructure deployment pace to assess electric UTV viability against established gasoline and diesel platforms.
Market Dynamics
The Utility Terrain Vehicles market is experiencing structural pressure from EPA Tier 4 emissions compliance costs, which are compressing margins for gasoline-powered platforms while accelerating capital reallocation toward electric powertrain development.
Growth Catalysts
- Precision Agriculture Adoption:Large-scale farming operations in the American Midwest are replacing aging utility fleets with UTVs equipped for GPS-guided crop management and autonomous spraying functions.
- NHTSA Rollover Protection Mandates:Federal safety requirements for occupant protection structures are driving replacement demand as pre-2018 machines age out of fleet eligibility.
- Lithium-Ion Battery Cost Curves:Declining cell prices are enabling electric UTV configurations that match diesel torque profiles for commercial material-handling tasks.
Market Restraints
- Steel and Aluminum Input Volatility:Chassis material costs fluctuate with commodity indexes, squeezing fixed-price contract margins for fleet suppliers.
- Powertrain Supplier Concentration:Critical engine management systems and emission control modules source from a narrow tier of German and Japanese electronics manufacturers.
- Electric Range Limitations:Current battery energy density constrains all-day field operation without mid-shift charging infrastructure, limiting electric UTV penetration in remote agricultural deployments.
Strategic Opportunities
- OSHA Workplace Safety Directives:Commercial landscaping and grounds maintenance fleets face mandated operator protection upgrades, creating specification pull for enclosed-cab UTV configurations.
- Vineyard and Orchard Robotics Integration:Narrow-track electric UTVs with autonomous navigation are penetrating specialty crop operations in California and Washington state.
- Dealer Network Service Contracts:Predictive maintenance telemetry embedded in powertrain control modules enables subscription-based revenue streams beyond unit sales.
Industry Challenges
- Power Electronics Talent Scarcity:Electric drivetrain engineering expertise concentrates in automotive and aerospace sectors, forcing UTV manufacturers to compete for embedded systems designers.
- Homologation Timeline Compression:Dual certification requirements for EPA emissions and NHTSA crashworthiness extend product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Terrain Vehicles (UTV) Market |
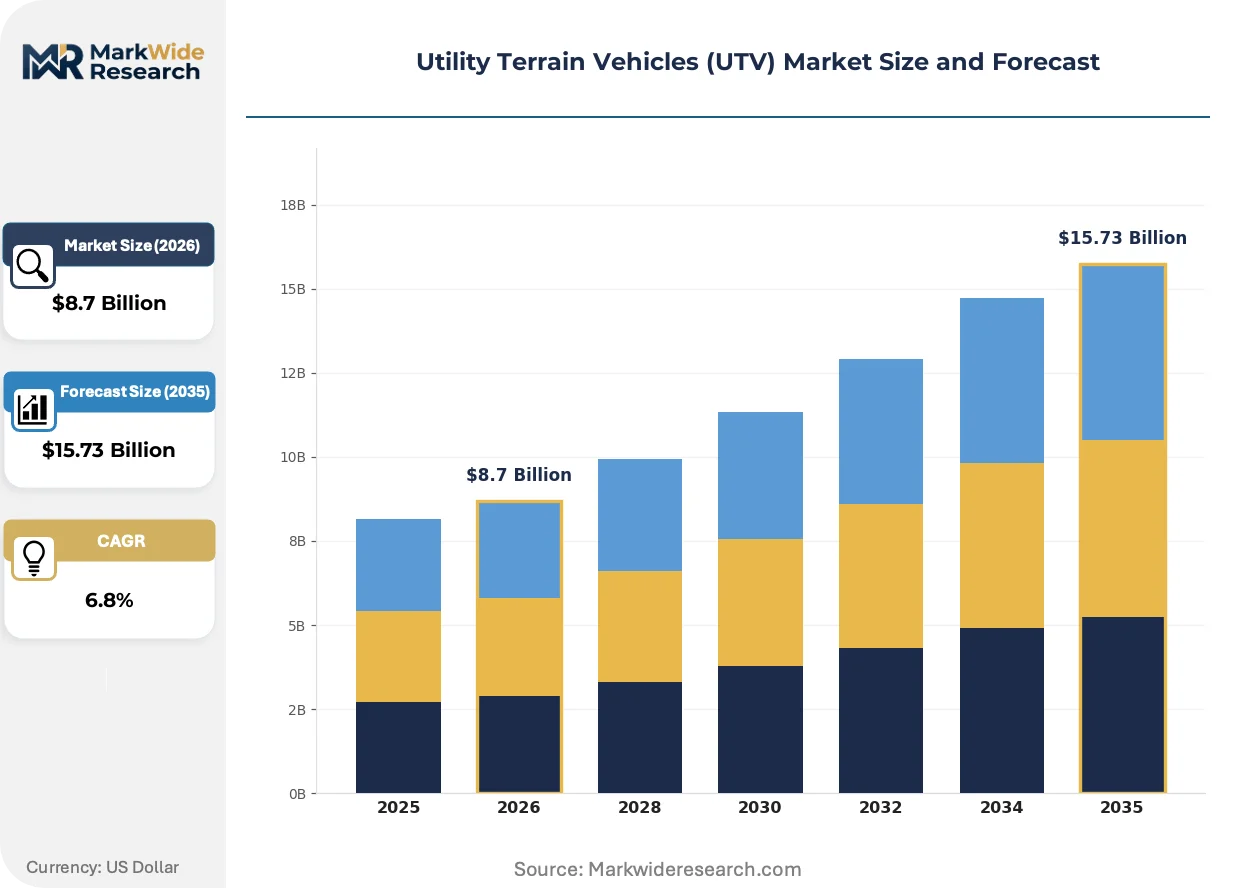
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recreational UTVs, Agricultural UTVs, Military UTVs, Commercial UTVs Engine Type: Gasoline, Diesel, Electric, Hybrid Application: Agriculture, Construction, Landscaping, Off-Road Recreation End User: Consumer, Commercial, Government, Industrial |
| Companies Covered | Polaris Inc., BRP Inc., John Deere, Honda Motor Co., Ltd., Kawasaki Heavy Industries, Ltd., Yamaha Motor Co., Ltd., Kubota Corporation, CFMOTO, Textron Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Terrain Vehicles (UTV) Market Evolving Landscape
Powertrain architecture is undergoing fundamental reconfiguration as electrification penetrates commercial utility segments previously dominated by diesel durability claims.
Permanent magnet synchronous motors paired with silicon carbide inverters are delivering torque curves that exceed equivalent displacement combustion engines. Agricultural cooperatives in Iowa and Nebraska are piloting electric UTVs for grain bin monitoring and livestock checking where daily distances remain below 40 miles. This transition is electrifying competitive positioning among incumbent manufacturers, forcing accelerated R&D commitments to avoid displacement by specialized electric entrants.
EPA Tier 4 Final standards for non-road spark-ignition engines are tightening hydrocarbon and NOx limits below 1.0 gram per kilowatt-hour. Manufacturers serving the United States market must integrate gasoline particulate filters and advanced catalytic systems, adding $800-$1,200 in per-unit emission hardware costs. The recreational segment absorbs these premiums through accessorized pricing, while commercial buyers extend replacement cycles to amortize compliance investments.
Fleet procurement is consolidating through integrated equipment management platforms that bundle UTV acquisition with telematics subscriptions and scheduled maintenance. Large agricultural operations in Kansas and Illinois are shifting from dealer relationships to direct manufacturer contracts with guaranteed uptime clauses. This restructuring concentrates purchasing power among fewer buyers while compressing regional distributor margins, particularly visible in the Corn Belt where 500-plus unit annual orders now dominate volume allocation.
Utility Terrain Vehicles (UTV) Market Segmentation
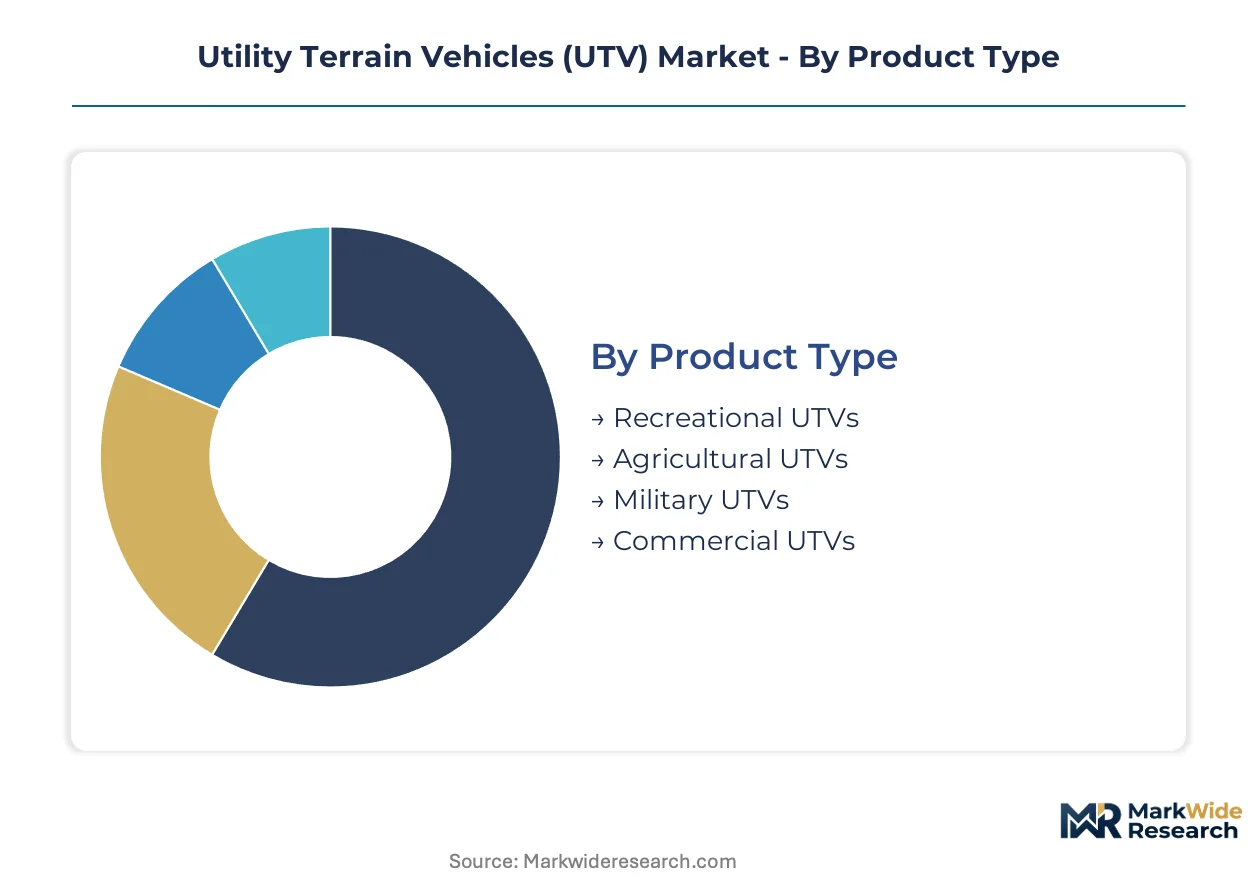
Segment boundaries in the Utility Terrain Vehicles market reflect divergent durability requirements, duty-cycle intensity, and regulatory exposure across buyer types. Understanding these divisions clarifies where powertrain investments concentrate and which customer groups drive specification changes.
Product Type:
Buyers differentiate by terrain severity, payload frequency, and operator protection mandates rather than surface styling.
- Agricultural UTVs:Built with reinforced steel cargo beds rated for 1,200-2,000 pound payloads and corrosion-resistant finishes for chemical exposure. Midwest grain operations and livestock ranches in Iowa and Nebraska generate replacement demand as fleets age past 7-year depreciation schedules.
- Recreational UTVs:Prioritize suspension travel and power-to-weight ratios over utility specifications. Arizona and Utah desert trail systems sustain accessorized premium configurations where buyers accept higher price points for performance differentiation.
- Commercial UTVs:Specified for facility maintenance and material handling with enclosed cabs meeting OSHA rollover requirements. Grounds management fleets at universities and corporate campuses drive specification standardization.
- Military UTVs:Incorporate armor-ready chassis and electromagnetic hardening for tactical communications. Procurement flows through defense logistics channels with multi-year contract structures.
Agricultural UTVs lead volumes today; electric configurations across all product types are gaining share fastest.
Engine Type:
Powertrain selection hinges on fuel infrastructure access, daily operating hours, and emission zone restrictions.
- Gasoline:Dominates recreational and light-commercial segments with lower upfront capital requirements. EPA Tier 4 Final compliance adds particulate filtration hardware, compressing margins on entry-level units.
- Electric:Permanent magnet synchronous motors with silicon carbide inverters now match diesel torque curves below 50 mph. California vineyard operations and Nebraska livestock checking routes under 40 miles daily pilot battery-electric fleets.
- Diesel:Retains position in high-hour commercial applications where refueling infrastructure is remote and engine longevity outweighs acquisition cost. Construction and industrial end users prioritize 5,000-hour service intervals.
- Hybrid:Combines electric torque fill with combustion range extension for variable-duty cycles. Emerging configurations target landscaping fleets with intermittent high-load demands.
Gasoline engines retain the largest installed base; electric powertrains are climbing the fastest as battery costs decline and charging infrastructure spreads.
Application:
Duty-cycle predictability and seasonal utilization rates separate application segments.
- Agriculture:Year-round deployment for crop scouting, spraying, and livestock management creates the highest utilization rates. GPS guidance integration and autonomous spraying functions now specify procurement in Kansas and Illinois row-crop operations.
- Off-Road Recreation:Seasonal demand concentrated in Arizona, Utah, and Colorado trail systems. Accessory attachment rates exceed 40% of base vehicle price, sustaining premium margin pools.
- Construction:Site mobility and material transport on unimproved ground. OSHA workplace safety directives mandate rollover protective structures for commercial deployment.
- Landscaping:Municipal parks departments and commercial grounds maintenance fleets. Enclosed-cab specifications are expanding under mandated operator protection upgrades.
Agricultural applications generate the highest annual hours per unit; landscaping represents the steepest expansion trajectory as commercial fleet electrification accelerates.
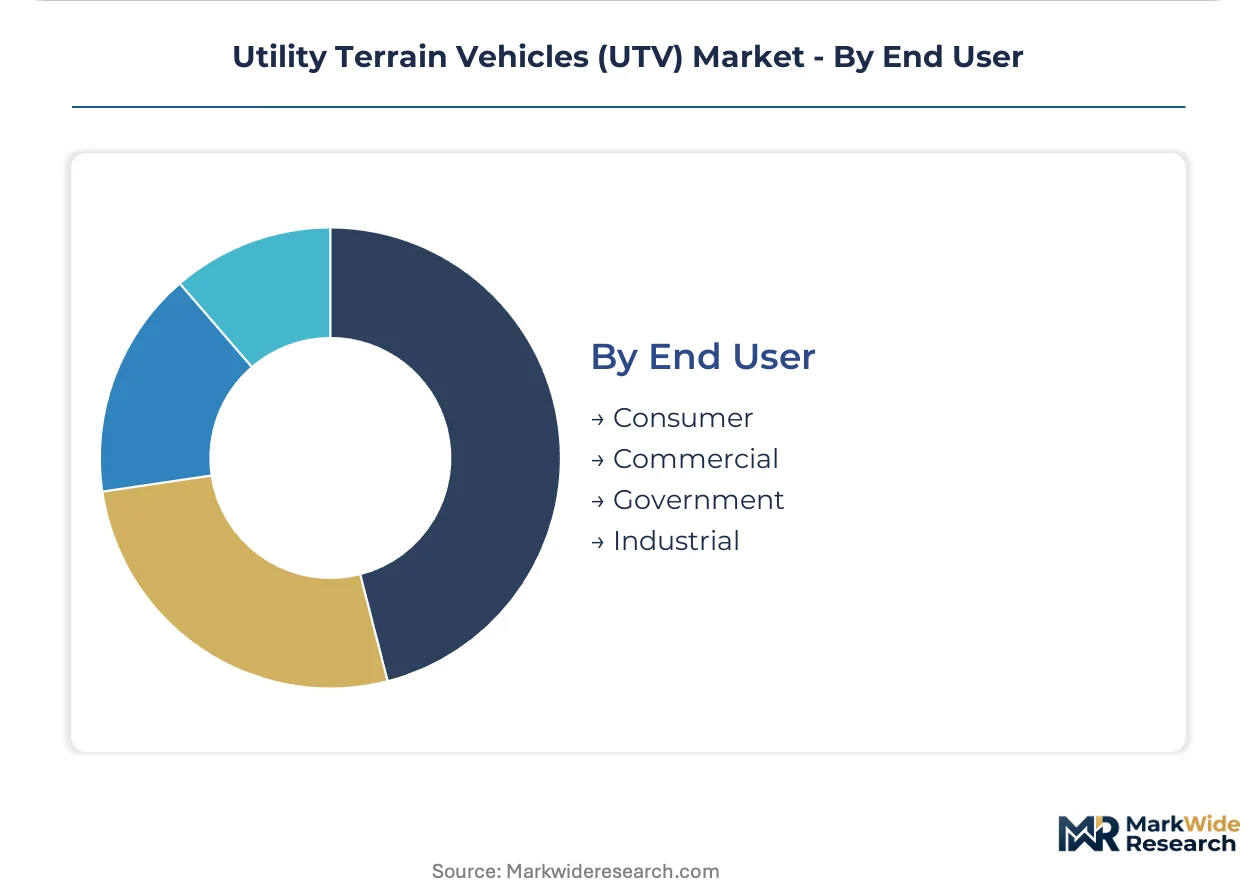
End User:
Purchasing authority and total cost of ownership calculation methods diverge sharply across buyer categories.
- Commercial:Fleet managers with centralized procurement authority negotiate direct manufacturer contracts with guaranteed uptime clauses. Large agricultural cooperatives in the Corn Belt now bypass traditional dealer networks for 500-plus unit orders.
- Industrial:Mining, oil and gas, and utility operators prioritize diesel durability in remote deployments. Procurement emphasizes service interval predictability and parts availability over capital cost minimization.
- Consumer:Individual buyers with recreational or rural property maintenance needs. Financing sensitivity and accessory attachment rates drive dealer profitability.
- Government:Federal, state, and municipal procurement with bid-based acquisition rules. Defense and public lands management agencies specify armor-ready or fire-suppression-equipped variants.
Commercial end users dominate current volume; government procurement is expanding most quickly as federal fleet electrification mandates take effect.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The American Midwest concentrates UTV demand through large-scale agricultural operations in Iowa, Illinois, and Nebraska that drive replacement cycles for utility-class machines.
United States
Midwest grain operations in Kansas and Illinois generate 500-plus unit fleet orders with GPS-guided crop management specifications. EPA Tier 4 Final emissions standards and NHTSA rollover protection mandates shape powertrain architecture and chassis design requirements for manufacturers. The Corn Belt states anchor procurement volume as agricultural cooperatives shift from dealer networks to direct manufacturer contracts.
Canada
Prairie province farming operations in Saskatchewan and Alberta deploy UTVs for livestock checking and remote field access where distances exceed 40 miles daily. Health Canada and PMRA coordinate emission and chemical exposure standards with US EPA benchmarks. Ontario manufacturing clusters near Toronto supply chassis components to North American assembly plants.
Germany
Baden-Württemberg and Bavaria host precision agriculture equipment engineering centers that export autonomous navigation systems to North American UTV manufacturers. KBA oversees type approval for non-road mobile machinery under EU framework regulations. Stuttgart-area automotive suppliers transfer electric drivetrain expertise to off-highway vehicle programs.
China
Shandong and Jiangsu provinces manufacture steel chassis components and permanent magnet motors for export to North American and European UTV assemblers. MIIT and SAMR enforce GB standards for electric vehicle safety and battery certification. Yangtze River Delta industrial parks concentrate lithium-ion cell production that feeds global battery supply chains.
Japan
Kanto region engineering centers in Tokyo and Kanagawa prefecture develop compact diesel engines and electronic fuel injection systems for commercial UTV applications. METI coordinates industrial policy supporting carbon neutrality targets for off-road equipment. Osaka-based manufacturers supply emission control modules to Tier 4 compliance programs.
Utility Terrain Vehicles (UTV) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electric powertrain specialization and autonomous navigation integration. The vendor base spans diversified powersports conglomerates, agricultural equipment incumbents, and specialized off-road vehicle fabricators. Three archetypes dominate: vertically integrated recreational specialists, dealer-network-dependent agricultural equipment suppliers, and contract-manufacturing-dependent value-positioned brands. Competitive moves concentrate on backward integration into powertrain manufacturing and strategic partnerships for battery supply security.
Among North American recreational powersports specialists, Polaris Inc. and BRP Inc. exemplify the vertically integrated archetype with in-house suspension engineering capabilities. John Deere anchors the agricultural equipment tier through dealer network density across rural North America. These three companies represent distinct competitive positioning vectors: recreational performance differentiation, agricultural utility integration, and fleet-scale service contract capture.
| Leading Market Players |
|---|
| Polaris Inc. |
| BRP Inc. |
| John Deere |
| Honda Motor Co., Ltd. |
| Kawasaki Heavy Industries, Ltd. |
| Yamaha Motor Co., Ltd. |
| Kubota Corporation |
| CFMOTO |
| Textron Inc. |
| Others |
Value Network & Pricing Analysis
EPA Tier 4 Final compliance mandates gate qualified supply access for gasoline-powered UTV platforms while simultaneously compressing margin pools that manufacturers attempt to recover through premium-tier pricing differentiation on accessorized recreational configurations.
Pricing Analysis
Steel and aluminum commodity pass-through dynamics dominate UTV pricing architecture across the forecast period. Three-tier pricing structure across premium, standard, and economy levels separates recreational performance configurations from agricultural utility specifications and entry-level commercial units. Price differentiation hinges on suspension engineering sophistication and EPA certification tier. Pricing pressure stems from emission hardware cost absorption in fixed-price fleet contracts. Commercial agricultural buyers exhibit highest price sensitivity due to volume procurement leverage, while recreational consumers demonstrate lowest sensitivity on performance-differentiated variants.
Supply Chain Analysis
Regional distribution centers in Iowa, Illinois, and Kansas anchor hub-and-spoke fulfillment patterns for Midwest agricultural fleet operators. Chassis fabrication concentrates in China, Mexico, and the United States. Permanent magnet motors and lithium-ion cells draw from South Korean and Japanese suppliers. Single-source vulnerability in German and Japanese engine management electronics creates procurement risk. Distribution runs through captive dealer networks for agricultural segments and direct-to-retail channels for recreational buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in electric powertrain platforms where battery cost curves enable premium pricing capture against legacy diesel configurations.
For Market Incumbents: Deploy backward integration into silicon carbide inverter manufacturing to secure electric drivetrain cost positions against specialized entrants. Consolidate dealer service contract penetration in Corn Belt agricultural cooperatives. Accelerate R&D commitments to permanent magnet motor architectures before displacement by pure-electric specialists materializes.
For New Entrants and Emerging Players: California vineyard operators with sub-40-mile daily routes represent an underserved buyer archetype requiring narrow-track electric configurations. Autonomous navigation integration for specialty crop spraying commands specification pull unavailable to incumbent agricultural equipment suppliers. Pursue direct manufacturer contracts with guaranteed uptime clauses to bypass established dealer network barriers.
For Investors and Strategic Acquirers: Roll-up economics work for electric powertrain specialists because chassis fabrication commoditization separates from motor-inverter integration value capture. Five-to-ten-year viability favors platforms with battery supply security and charging infrastructure partnerships. Monitor lithium-ion cell localization progress as inflection indicator for electric UTV penetration against established gasoline and diesel platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Powertrain Platform Launch | Silicon carbide inverter integration enables torque profiles exceeding equivalent displacement combustion engines. |
| Dealer Network Service Contract Expansion | Predictive maintenance telemetry embedded in powertrain control modules generates subscription revenue beyond unit sales. |
| Battery Supply Agreement Execution | Yangtze River Delta cell procurement secures cost positions against vertically integrated recreational powersports competitors. |
| Autonomous Navigation Partnership | Baden-Württemberg engineering center collaboration transfers precision agriculture guidance systems to North American vineyard applications. |
| OSHA-Compliant Enclosed Cab Introduction | Rollover protective structures meeting federal workplace safety directives penetrate commercial landscaping fleet specifications. |
Research Methodology
Bottom-up agricultural and commercial fleet modeling reconciled against top-down powersports manufacturer production tracking forms the analytical core of this study. Primary interviews with agricultural cooperative procurement managers, dealership operations directors, powertrain engineering leads, and fleet maintenance supervisors combined with secondary validation against EPA certification databases, NHTSA rollover test filings, and customs trade records. Triangulation across stakeholder inputs and documentary sources ensures cross-verified demand and supply estimates.
Historical trendline analysis of replacement cycle patterns in Midwest grain operations and recreational accessory attachment rates in Arizona and Utah trail systems informed projection parameters. Segmentation dimensions span product type, engine architecture, application intensity, and end-user procurement authority. CAGRs derive from installed base depreciation schedules and electrification penetration curves. Battery energy density trajectories and charging infrastructure deployment pace serve as industry-specific forecast inputs.
Underlying measurement precision varies by segment; agricultural fleet procurement specifications carry tighter precision than recreational consumer sentiment. Forecasts reflect assumptions regarding emission compliance timeline adherence and commodity input cost stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
US Off-Road Vehicles Market
Off Road Vehicles
All-Terrain Vehicle Market
Off Road Vehicles
Off Highway Hybrid Vehicles Market
Off Road Vehicles
Small Off-Road Engines Market
Off Road Vehicles
Snow Scooter Market
Off Road Vehicles
All-Terrain Vehicle (ATV) Engines Market
Off Road Vehicles
Global Automotive Off Highway Engine Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market
Off Road Vehicles
Off-Highway Engine Market
Off Road Vehicles
Off-Highway Electric Vehicle Market
Off Road Vehicles
Off-Road Vehicle Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
Four-Wheel Drive Vehicles Market