
 Dynamic Positioning System Market | 2026-2036
Dynamic Positioning System Market Size, Share, and Industry Trends Forecast 2026-2036
Dynamic Positioning System Market Analysis
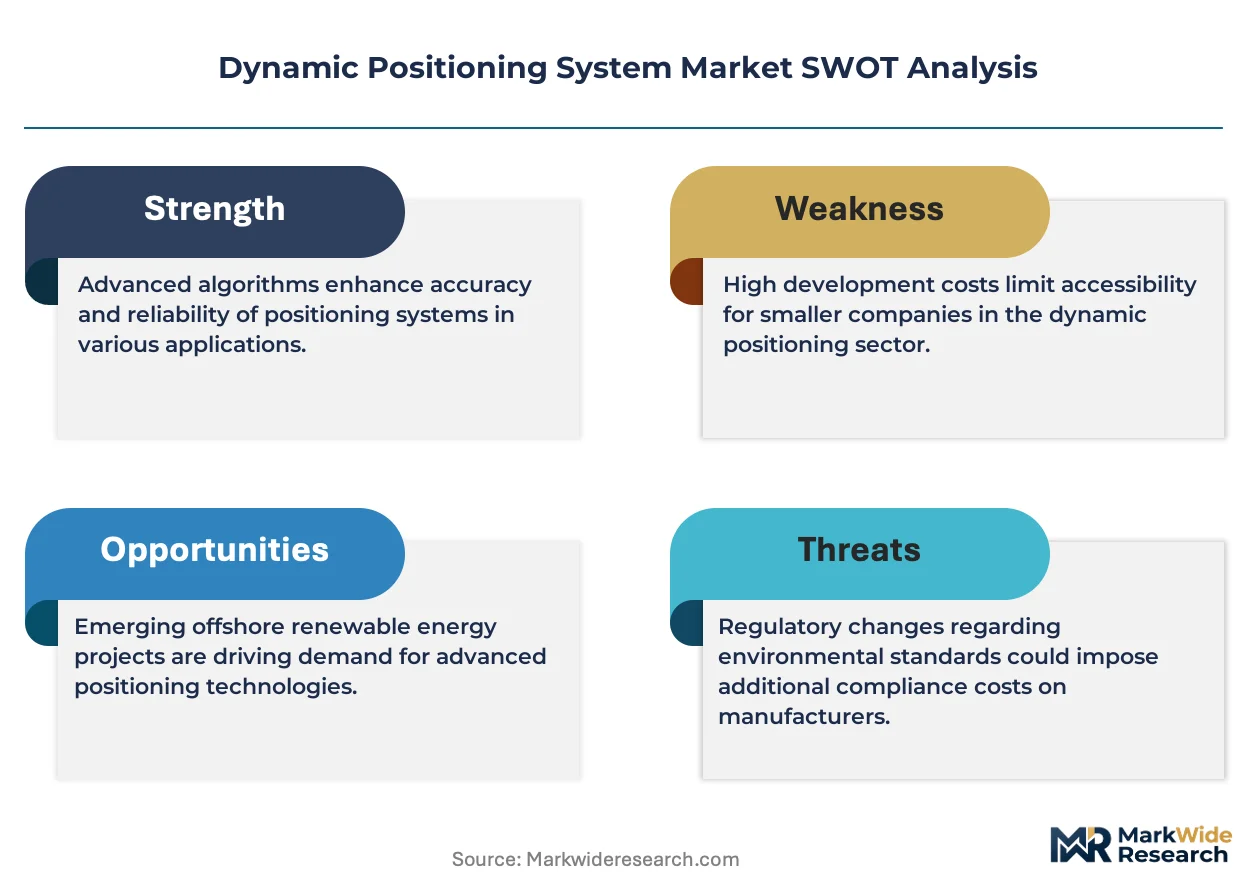
Class-3 redundancy certification is redrawing procurement criteria for deepwater vessels. Kongsberg Maritime dominates integrated bridge-to-propulsion architectures across the North Sea. Wärtsilä leverages its in-house thruster manufacturing to anchor long-term service contracts. ABB competes through electric propulsion integration that extends dynamic positioning into hybrid-electric platform designs.
A dynamic positioning system uses sensor fusion, control algorithms, and variable-thruster arrays to maintain vessel station without anchors, typically achieving position-hold accuracy within one meter under IEC 62065 standards. Closed-loop architectures lead installed base volumes due to proven reliability in harsh North Atlantic conditions, while hybrid configurations represent the fastest-growing system type as operators retrofit diesel-electric vessels with battery-buffered thruster banks. Offshore oil drilling commands the largest end-user spend pool, though marine research vessels concentrate margin in high-precision custom software solutions.
IMO, DNV, and the US Coast Guard shape equipment mandates through redundant-system classification rules and mandatory failure-mode testing for vessels operating beyond 150 nautical miles from shore. Norway's Petroleum Safety Authority and Brazil's ANVISA-equivalent maritime regulator enforce additional national station-keeping standards for floating production units. Stakeholders must monitor how forthcoming EU Green Deal fuel-mix requirements alter thruster power architectures and retrofit economics.
Market Dynamics
Class-3 redundancy certification is compressing procurement timelines for deepwater vessel operators while simultaneously elevating supplier qualification barriers. Norway's North Sea cluster is driving this structural shift through accelerated subsea construction vessel orders.
Growth Catalysts
- IMO MARPOL Annex VI:Tightening vessel emissions standards are forcing propulsion efficiency investments across offshore drilling fleets. Operators retrofit existing vessels with integrated dynamic positioning to meet compliance deadlines.
- Subsea construction acceleration:Norway's North Sea cluster is generating concentrated demand for station-keeping precision in harsh Atlantic conditions. Specialized vessel orders are expanding the addressable equipment base.
- Sensor fusion advancement:Multi-source positioning algorithms are achieving sub-meter accuracy without GPS augmentation. Deepwater drilling contractors are specifying these architectures for floating production units.
Market Restraints
- Thruster power electronics cost:Silicon carbide switching modules and liquid cooling systems represent concentrated input cost exposure. Supply constraints in wide-bandgap semiconductor foundries extend lead times.
- Norwegian supplier concentration:Integrated bridge-to-propulsion architectures rely on a narrow base of certified system integrators. Geographic clustering creates vulnerability to regional labor disputes or logistics disruptions.
- IEC 62065 certification burden:Mandatory failure-mode testing for redundant systems extends validation cycles. Smaller vessel operators defer upgrades due to documentation and sea-trial requirements.
Strategic Opportunities
- Brazil pre-salt expansion:ANVISA-equivalent maritime regulators are enforcing national station-keeping standards for floating production units. Local content rules favor regional system integration partnerships.
- Battery-buffered hybrid retrofits:Convergence of diesel-electric propulsion with lithium-ion storage banks enables peak-shaving thruster architectures. Offshore support vessel operators are piloting these configurations.
- EU Green Deal fuel-mix mandates:Forthcoming requirements for alternative propulsion fuels will alter thruster power architectures. Early movers in methanol-ammonia compatible systems will capture retrofit economics.
Industry Challenges
- Control systems engineering talent:Shortage of specialists in Kalman filtering and model-predictive control limits deployment velocity. Universities produce fewer marine automation graduates than replacement demand.
- Legacy vessel integration complexity:Retrofitting 1990s-era diesel-mechanical propulsion with closed-loop dynamic positioning requires custom mechanical-to-digital interfaces. Project engineering costs escalate unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dynamic Positioning System Market |
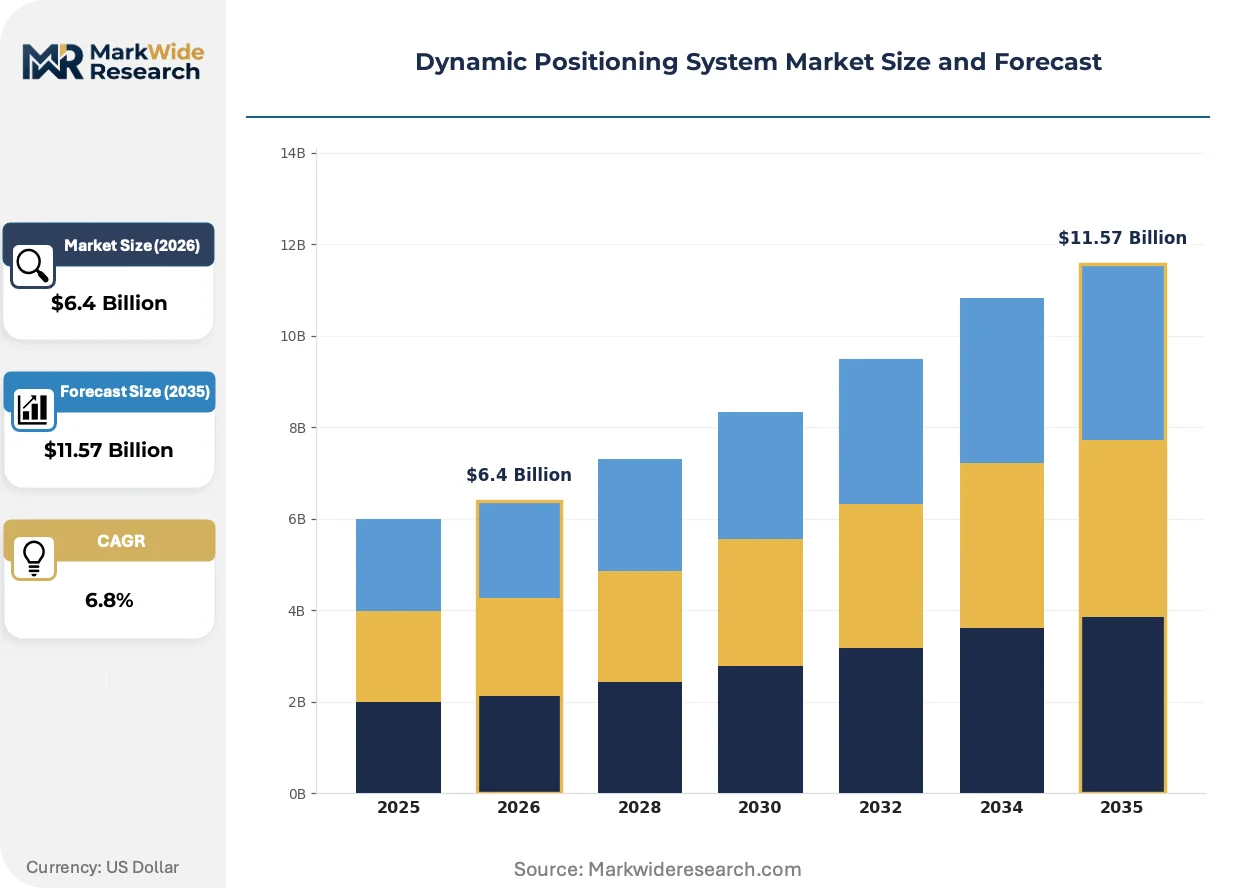
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Open-Loop, Closed-Loop, Hybrid, Integrated End User: Shipping Companies, Offshore Oil Drilling, Marine Research, Towage Operators Component: Sensors, Control Systems, Thrusters, Software Solutions Deployment Mode: Onshore, Offshore, Vessel-Based, Platform-Based |
| Companies Covered | ABB, Praxis Automation Technology B.V., Kongsberg Maritime, Rolls-Royce plc, L3Harris Technologies, Inc., Wärtsilä, Brunvoll AS, Japan Radio Co., GE Vernova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dynamic Positioning System Market Emerging Trajectories
Control hardware footprint reduction is enabling distributed processing architectures that embed intelligence directly at thruster nodes. This structural shift is compressing cabling runs and reducing single-point failure modes across vessel designs.
Edge computing nodes for real-time position estimation are miniaturizing from rack-mounted industrial PCs to IP67-rated embedded modules. Subsea construction vessel operators are specifying these compact units for thruster-local processing. The technology is miniaturizing redundant control loops, allowing triple-modular redundancy without dedicated equipment rooms.
DNV's revised rules for autonomous and remote-controlled vessels are mandating deterministic Ethernet for safety-critical control networks. Shipyards must now document latency budgets and failure-mode containment for integrated bridge systems. Offshore drilling contractors operating beyond 150 nautical miles from shore face the most stringent documentation requirements and are front-loading compliance engineering.
After-sales service unbundling is fragmenting long-term maintenance contracts into component-level subscriptions. Thruster manufacturers now sell predictive analytics separately from spare parts agreements. Norway's North Sea cluster exhibits this pattern most acutely, where operators negotiate sensor-data access independently from hardware warranties.
Dynamic Positioning System Market Segmentation
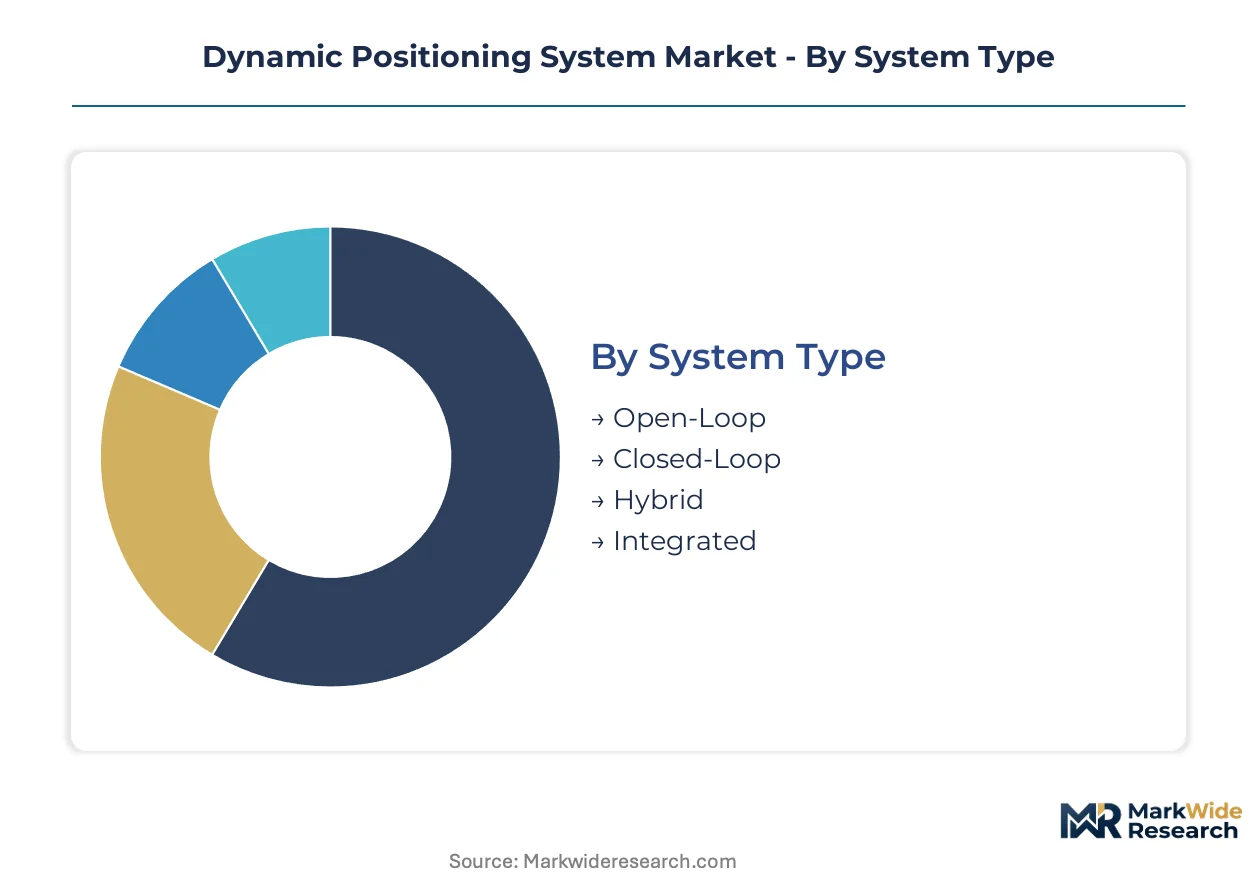
Segmentation reveals how procurement channels bifurcate between fleet-wide retrofits and newbuild specifications. Equipment vendors calibrate sales motions differently for each route, with retrofits demanding custom engineering while newbuilds favor standardized architectures.
System Type:
Channel flow splits sharply: closed-loop systems move through established maritime integrators with long-term service attachments, while hybrid configurations increasingly route through battery system vendors seeking propulsion partnerships.
- Closed-Loop:Proven reliability in harsh North Atlantic conditions has entrenched this architecture across Norway's offshore fleet. Deepwater drilling contractors specify these systems for floating production units where failure-mode containment is non-negotiable under IEC 62065.
- Hybrid:Diesel-electric vessels retrofitted with lithium-ion buffered thruster banks are gaining traction among offshore support operators. Battery-buffered architectures enable peak-shaving that extends generator life while meeting tightening MARPOL Annex VI efficiency mandates.
- Open-Loop:Simpler control logic suits harbor tugs and coastal workboats where position-hold tolerances exceed ten meters.
- Integrated:Full bridge-to-propulsion unification remains concentrated in specialized naval and ice-class newbuilds.
Closed-loop dominates installed base. Hybrid is where expansion concentrates.
End User:
Cost tier stratification separates specification-grade procurement from price-sensitive fleet standardization.
- Offshore Oil Drilling:Floating production units command the largest equipment spend pool, with Class-3 redundancy certification now mandatory for operations beyond 150 nautical miles from shore. Brazilian pre-salt expansion and Norway's North Sea cluster are driving concentrated demand for station-keeping precision.
- Marine Research:High-precision custom software solutions concentrate margin here, with sub-meter accuracy requirements for deep-ocean sampling operations. Kalman filtering specialists command premium engineering rates for these deployments.
- Shipping Companies:Container and bulk carriers prioritize fuel efficiency gains from optimized station-keeping during port approaches.
- Towage Operators:Harbor and escort tugs favor ruggedized control systems with minimal calibration requirements.
Offshore oil drilling anchors revenue concentration. Marine research delivers margin expansion.
Component:
Supply concentration varies dramatically across the stack, with thruster manufacturing consolidating while software remains fragmented.
- Thrusters:Silicon carbide switching modules and liquid cooling systems represent concentrated input cost exposure. Wide-bandgap semiconductor foundry constraints extend lead times for azimuth and tunnel thruster deliveries.
- Control Systems:Model-predictive control algorithms are the primary differentiation layer, with university pipeline shortages limiting deployment velocity for advanced architectures.
- Sensors:GPS, gyrocompass, and wind sensor fusion enables sub-meter accuracy without augmentation systems.
- Software Solutions:Predictive analytics modules are unbundling from hardware warranties into separate subscription offerings.
Thrusters dominate bill-of-materials value. Control systems is where vendor differentiation concentrates.
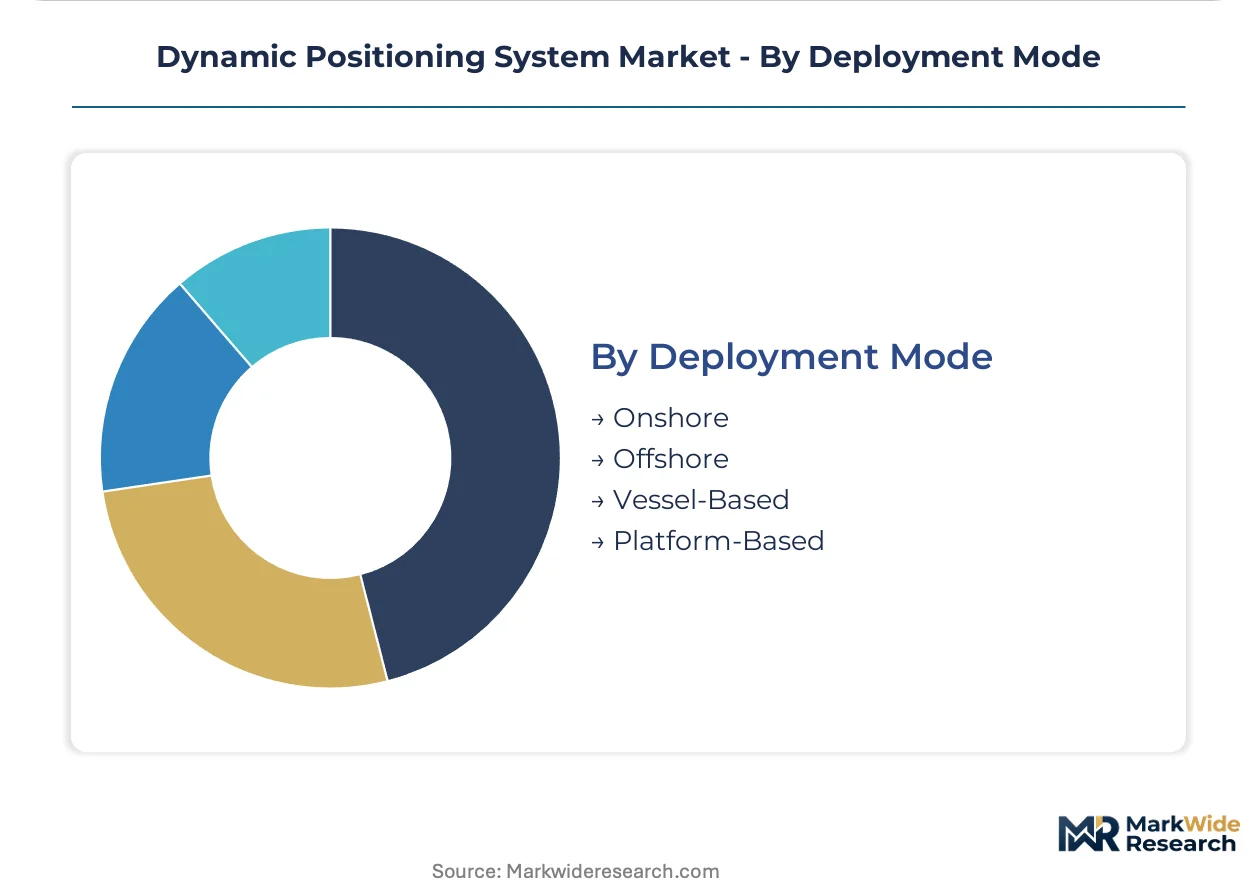
Deployment Mode:
Geographic clustering shapes deployment patterns, with North Sea conditions favoring vessel-based mobility while Gulf of Mexico operators prefer fixed platform integration.
- Vessel-Based:Mobile station-keeping enables multi-field service contracts for construction and intervention vessels. Norway's subsea construction acceleration is expanding this addressable base fastest.
- Platform-Based:Semi-submersible production platforms require permanent DP integration for riser management and offloading operations. Brazil's ANVISA-equivalent maritime regulator enforces national standards here.
- Offshore:Floating drilling units operating in deepwater basins represent the certification-intensive core of demand.
- Onshore:Test facilities and training simulators constitute a niche specification channel.
Vessel-based dominates order flow. Platform-based is where contract duration concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor Norwegian system integrators supplying North Sea drilling contractors, while Brazilian local-content rules redirect procurement toward regional partnerships. Equipment flows concentrate where subsea construction vessel orders accelerate and national regulators enforce redundant-system mandates.
Norway
Stavanger and Bergen anchor Europe's densest cluster of subsea construction vessel operators demanding Class-3 redundancy certification. The country's Petroleum Safety Authority enforces station-keeping standards exceeding IEC 62065 baselines for floating production units. Kongsberg Maritime dominates integrated bridge-to-propulsion architectures across this North Sea corridor.
Brazil
Pre-salt basin expansion drives floating production unit procurement requiring dynamic positioning integration for riser management. ANVISA-equivalent maritime regulators enforce national station-keeping standards with local-content provisions favoring regional system integration partnerships. Rio de Janeiro state concentrates shipyard activity for these deepwater deployments.
United States
Gulf of Mexico deepwater drilling contractors face US Coast Guard redundant-system classification rules for operations beyond 150 nautical miles from shore. The Port of Houston serves as the primary integration hub for thruster and control system imports serving offshore support fleets. Platform-based deployment modes dominate contract duration here versus vessel-based mobility.
China
Yangtze River Delta shipyards are scaling dynamic positioning integration for domestic offshore support vessel construction. MIIT standards on marine automation equipment align with IEC frameworks while favoring local sensor and thruster suppliers. Shanghai's port infrastructure enables thruster module export to Southeast Asian drilling markets.
United Kingdom
Aberdeen maintains North Sea engineering concentration despite fleet rationalization, with specialized consultancies supplying Kalman filtering expertise for marine research vessel specifications. The Maritime and Coastguard Agency implements IMO MARPOL Annex VI enforcement through port-state control inspections. Scottish waters host testing grounds for autonomous vessel control architectures.
Dynamic Positioning System Market Vendor Landscape
Concentration sits with integrated system architects commanding long-term service attachments across Norway's offshore fleet. Three tiers structure participation: full-stack bridge-to-propulsion integrators, thruster manufacturers backward integrating into control software, and component specialists supplying silicon carbide power electronics. Competitive moves center on battery-hybrid retrofit partnerships and predictive analytics subscription unbundling from hardware warranties.
Among Nordic integrated system providers, Kongsberg Maritime and Wärtsilä occupy positions spanning control algorithm development through thruster manufacturing. ABB represents the electric propulsion integration archetype, extending dynamic positioning architectures into hybrid-electric platform designs. These three anchors exemplify how vendor strategies diverge between hardware-captive service models and software-centric differentiation.
| Leading Market Players |
|---|
| ABB |
| Praxis Automation Technology B.V. |
| Kongsberg Maritime |
| Rolls-Royce plc |
| L3Harris Technologies, Inc. |
| Wärtsilä |
| Brunvoll AS |
| Japan Radio Co. |
| GE Vernova |
| Others |
Supply Flow & Price Mechanics
Thruster manufacturing scale economies in Norway and Finland concentrate supplier bargaining power while anchoring price floors for Class-3 certified systems. Wide-bandgap semiconductor capacity utilization rates across Asian foundries directly shape lead-time premiums and retrofit project economics for offshore vessel operators.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the North Sea fleet, with pricing stratifying across Class-3 certification, Class-2 redundancy, and uncertified harbor-tier tiers. Price differentiation hinges on IEC 62065 compliance grade and after-sales predictive analytics bundling. Cost compression in standard-tier control systems is intensifying because silicon carbide module shortages force thruster manufacturers to allocate premium inventory to certified integrators. Offshore support vessel operators exhibit highest price sensitivity due to fragmented fleet ownership, while floating production unit contractors absorb premium pricing for integrated bridge-to-propulsion architectures.
Supply Chain Analysis
Extended lead times for azimuth thruster deliveries now stretch eighteen to thirty-six months depending on power rating and cooling configuration. Geographic supply concentration rests on Norway, Finland, and China, with Stavanger and Bergen anchoring control system integration while Yangtze River Delta shipyards scale thruster module assembly. Raw material dependencies draw from silicon carbide substrates, rare-earth magnetic materials for permanent magnet motors, and marine-grade aluminum castings. Single-source vulnerability in wide-bandgap semiconductor foundries represents the dominant structural risk. Distribution runs through maritime system integrators with captive service networks rather than open component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Station-keeping autonomy software presents a credible substitute threat to conventional hardware-centric architectures, forcing incumbents to defend integrated service positions against algorithmic displacement.
For Market Incumbents: Shield long-term service contract renewal rates by embedding predictive analytics modules that raise switching costs for Norwegian offshore operators. Deepen backward integration into silicon carbide power electronics to buffer thruster margin exposure against semiconductor supply volatility. Prioritize certification pre-engineering for methanol-ammonia compatible thruster architectures ahead of EU Green Deal enforcement timelines. For New Entrants and Emerging Players: Predictive maintenance software unbundling from hardware warranties creates immediate white-space opportunity, as North Sea vessel operators increasingly negotiate sensor-data access independently from OEM service agreements. Battery-buffered hybrid retrofit engineering services represent the most penetrable segment, with offshore support vessel fleets lacking in-house electrical integration capability. Pursue joint development partnerships with Yangtze River Delta shipyards to establish thruster-control system integration credibility without legacy certification burden. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors control software specialists with embedded Kalman filtering expertise over capital-intensive thruster manufacturers facing input cost inflation. Long-term viability hinges on differentiation durability as sensor fusion commoditizes. Acquisition targets should demonstrate recurring revenue from predictive analytics subscriptions rather than project-based hardware sales. Watch for ANVISA-equivalent regulatory harmonization across Brazilian pre-salt expansion as inflection indicator for regional system integration consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Hybrid Retrofit Partnership | Enables peak-shaving thruster architectures that extend generator life under MARPOL Annex VI. |
| Predictive Analytics Unbundling | Transforms hardware warranty relationships into recurring software revenue streams with Norwegian operators. |
| Silicon Carbide Backward Integration | Captive supply of wide-bandgap switching modules insulates thruster margins from foundry allocation constraints. |
| Alternative Fuel Certification Pre-Engineering | Methanol-ammonia compatible system architectures capture EU Green Deal retrofit economics early. |
| Regional System Integration Partnership | Local content compliance with Brazilian ANVISA-equivalent standards unlocks pre-salt basin procurement access. |
Methodological Framework
Operator-level perspectives from offshore drilling contractors, subsea construction vessel fleet managers, maritime system integrators, and classification society surveyors anchored the qualitative base. Primary interviews combined with secondary validation from DNV rule development documentation, IMO MARPOL submission records, Norwegian Petroleum Safety Authority incident databases, and IEC 62065 certification registries. Bottom-up vessel order book analysis and top-down fleet automation spend estimates were triangulated to constrain projection ranges.
Sensitivity analysis across thruster power rating tiers, redundancy class specifications, and regional regulatory enforcement intensity shaped the analytical framework. Segmentation dimensions modeled include system type architecture, end-user operational profile, component stack position, and deployment mode mobility. CAGRs were derived from installed base replacement cycles and newbuild order acceleration patterns. Forecast inputs incorporated silicon carbide supply expansion timelines and battery-buffered hybrid adoption curves among offshore support operators.
Forecasts assume regulatory continuity in IMO MARPOL Annex VI, EU Green Deal fuel-mix mandates, and Norwegian Petroleum Safety Authority station-keeping standards; material policy shifts would require re-modeling. Class-3 certification timeline extensions or wide-bandgap semiconductor supply disruptions could compress replacement demand. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Shaft Power Meter Market
Marine
Digital Nautical Charts Market
Marine
Offshore AUV and ROV Market
Marine
India Boat Davits Market
Marine
Marine Fender Systems Market
Marine
Marine Airbags Market
Marine
Marine Pipes Market
Marine
Hydraulic Marine Cranes Market
Marine
Marine Big Data Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
Marine Strip Market
Marine
Freighter Conversions Market
Marine
Pneumatic Marine Fender Market
Marine
Buoys and Beacon Market
Marine
Fishing Vessel Market
Marine
Marine Elevators Market