
 Off-Highway Vehicle Engine Market | 2026-2036
Off-Highway Vehicle Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Highway Vehicle Engine Market Analysis
Mining contractors and large-scale agricultural operators is bifurcating demand away from general construction rental fleets. Cummins Inc. leverages its integrated aftertreatment architecture to defend position in high-horsepower mining applications. Deere & Company anchors the North American row-crop segment through captive engine production and proprietary precision-ag interfaces. Kubota Corporation specializes in sub-100 HP compact powertrains for orchard and vineyard equipment where emissions compliance costs disproportionately burden smaller competitors.
Off-highway vehicle engines are compression-ignition or spark-ignition powerplants purpose-built for mobile equipment operating outside public road networks, typically engineered with reinforced blocks, wet-sleeve liners, and extended-duty cooling systems to survive continuous load cycles in abrasive environments. Diesel configurations retain structural dominance across agriculture and mining end-user segments due to torque density and refueling infrastructure maturity, though electric powertrains are capturing share in below-100 HP municipal and indoor construction niches where runtime predictability offsets battery mass penalties. Natural gas and hybrid variants occupy intermediate positions in 100-200 HP and 200-300 HP brackets where total cost of ownership calculations favor fuel price stability over capital expenditure minimization.
EPA Tier 4 Final and EU Stage V frameworks have forced widespread deployment of diesel particulate filters and selective catalytic reduction across above-300 HP engine portfolios, adding hardware cost and packaging complexity that favors manufacturers with vertically integrated emissions control supply chains. China's MEE and India's CEA are tightening domestic off-road emissions benchmarks, creating parallel certification burdens for suppliers serving export-heavy construction equipment OEMs. Stakeholders must monitor divergence between regional test cycles and in-use compliance verification protocols when allocating R&D budgets across power rating tiers.
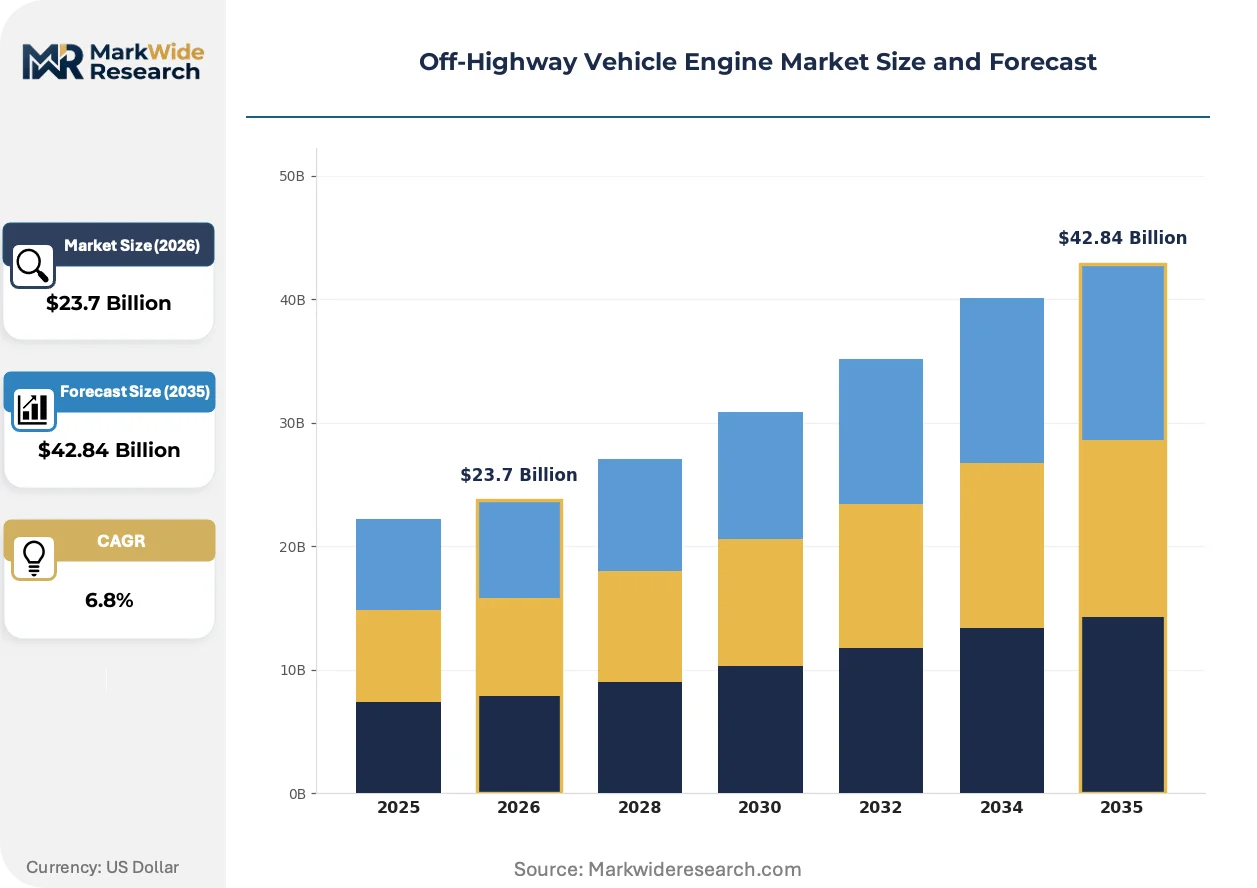
Market Dynamics
Emissions compliance deadlines are compressing development cycles and forcing capital reallocation toward aftertreatment integration, while mining and agricultural end-users pull procurement forward to lock in higher-displacement diesel units before Tier 5-equivalent standards take effect.
Growth Catalysts
- EPA Tier 4 Final and EU Stage V frameworks:These regulations mandate diesel particulate filters and selective catalytic reduction across above-300 HP portfolios, creating replacement demand as older equipment faces operational restrictions.
- Brazilian soybean mechanization:Intensifying farm consolidation in Mato Grosso and Goiás is driving fleet renewal toward higher-horsepower tractors and harvesters with compliant powertrains.
- Underground mining electrification pilots:Battery-electric load-haul-dump vehicles are validating zero-emission architectures in Canadian and Australian hard-rock operations, opening adjacent engine displacement opportunities.
Market Restraints
- Platinum group metal cost volatility:Diesel oxidation catalysts and selective catalytic reduction systems depend on palladium and rhodium, with price spikes passing directly to engine bill-of-materials.
- Foundry capacity concentration:Heavy-duty engine block casting relies on a concentrated supplier base in Germany, China, and India, exposing procurement to regional energy cost fluctuations.
- Battery energy density limitations:Lithium-ion cell gravimetric performance below 300 Wh/kg prevents electrification of 300+ HP continuous-duty applications without unacceptable mass penalties.
Strategic Opportunities
- India's construction equipment upcycle:National infrastructure project acceleration under the CEA's tightening emissions trajectory creates first-mover advantage for Stage V-ready suppliers.
- Renewable diesel compatibility:Hydrotreated vegetable oil and biomass-to-liquid fuels offer drop-in compliance pathways for existing Tier 4 Final fleets without hardware modification.
- Telematics-integrated predictive maintenance:OEMs bundling engine health monitoring with fluid analysis services are capturing aftermarket revenue previously lost to independent rebuilders.
Industry Challenges
- Calibration engineering talent scarcity:The intersection of combustion optimization, aftertreatment thermal management, and embedded controls requires skill sets concentrated among a shrinking cohort of specialists.
- Parallel certification burdens:China's MEE test cycles diverge from EPA and EU protocols, forcing duplicate validation programs for export-heavy construction equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Highway Vehicle Engine Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Diesel, Natural Gas, Electric, Hybrid End User: Agriculture, Construction, Mining, Forestry Power Rating: Below 100 HP, 100-200 HP, 200-300 HP, Above 300 HP Fuel Type: Biofuel, Propane, Gasoline, Others |
| Companies Covered | Caterpillar Inc., Cummins Inc., Deutz AG, Kubota Corporation, Deere & Company, Komatsu Ltd., Weichai Power Co., Ltd., AGCO Corporation, Volvo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Highway Vehicle Engine Market Emerging Trajectories
Powertrain architectures are diverging across horsepower brackets as electrification captures predictable-duty niches while diesel retains dominance in variable-load mining and agriculture, with hybrid systems occupying an expanding middle ground.
Modular aftertreatment packaging is fragmenting competitive positioning in the 200-400 HP range. Manufacturers adopting standardized catalyst canisters and urea dosing hardware reduce platform-specific engineering overhead. Agricultural OEMs in North America and Europe are prioritizing these architectures to accelerate model-year turnover. The approach is fragmenting historical supplier relationships as engine makers with captive emissions control capabilities capture share from specialized exhaust component vendors.
EU Stage V and EPA Tier 5-equivalent proposals are tightening particulate number limits and introducing in-use compliance verification through portable emissions measurement systems. Engine manufacturers must now design for real-world operating profiles rather than laboratory test cycles alone. Mining contractors in Australia and Canada face the steepest adaptation costs as underground duty cycles differ markedly from standardized test protocols.
Equipment-as-a-service contracting is displacing traditional unit sales in municipal and rental fleet segments. Buyers in Scandinavian markets and select US states now prioritize total cost-per-operating-hour over capital expenditure minimization. This shift favors engine suppliers offering guaranteed maintenance intervals and fluid consumption warranties over those competing solely on upfront pricing.
Off-Highway Vehicle Engine Market Segmentation
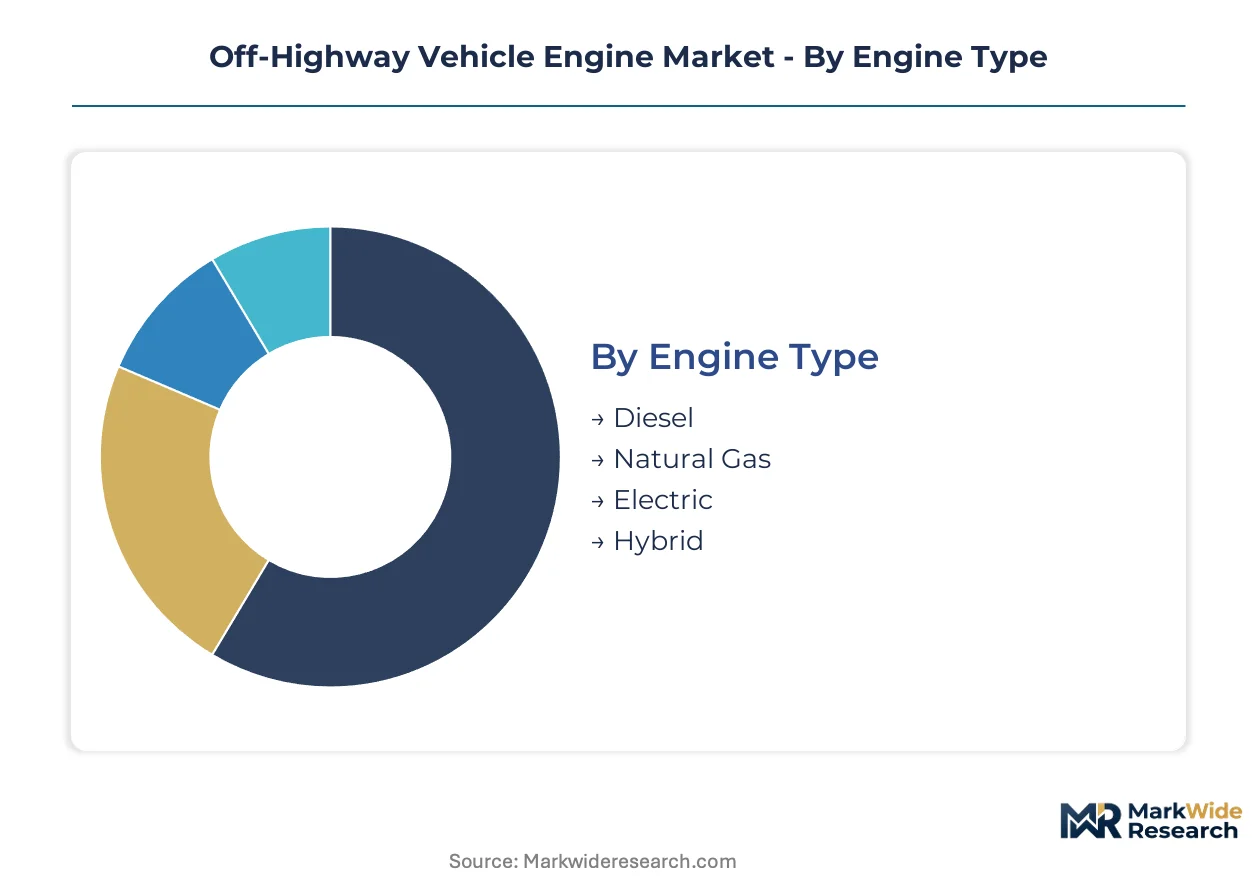
Segmentation reveals how emissions architecture and duty-cycle intensity fragment procurement patterns across powertrain categories. Equipment OEMs configure engine portfolios differently for Brazilian soybean harvesters versus Australian underground loaders, creating divergent margin structures within each dimension.
Engine Type:
Margins concentrate in diesel architectures where aftertreatment integration and thermal management expertise create defendable positions.
- Diesel:Compression-ignition powertrains with reinforced blocks and wet-sleeve liners dominate mining and agriculture due to torque density and refueling infrastructure maturity. Mining contractors in Australia and Canada are accelerating procurement of higher-displacement units ahead of Tier 5-equivalent EPA deadlines.
- Electric:Battery-electric architectures capture municipal and indoor construction niches below 100 HP where runtime predictability offsets lithium-ion mass penalties. Canadian hard-rock mining pilots validate zero-emission load-haul-dump vehicles.
- Natural Gas:Spark-ignition variants occupy 100-200 HP and 200-300 HP brackets where fuel price stability favors total cost of ownership over capital expenditure minimization.
- Hybrid:Parallel and series-hybrid systems bridge duty-cycle unpredictability in variable-load applications where pure electric range falls short.
The dominant share belongs to Diesel, while Electric is closing the gap fastest in sub-100 HP municipal fleets.
End User:
Customer concentration patterns split between fleet operators with captive maintenance capabilities and rental channels outsourcing service risk.
- Agriculture:Row-crop and specialty crop machinery in Brazil's Mato Grosso belt and North American corn-soy regions drive demand for 200-400 HP compliant powertrains with precision-ag interface compatibility.
- Mining:Hard-rock and surface operations in Australia, Canada, and select African jurisdictions specify engines for continuous load cycles, with underground electrification pilots creating adjacent displacement opportunities.
- Construction:General rental fleets and municipal operators prioritize total cost-per-operating-hour over upfront pricing, favoring suppliers with guaranteed maintenance intervals.
- Forestry:Harvesters and forwarders in Nordic markets and Pacific Northwest require robust cooling systems for abrasive environments with limited refueling infrastructure.
Agriculture commands the largest revenue pool, though Mining exhibits the steepest expansion trajectory as fleet renewal accelerates ahead of emissions deadlines.
Power Rating:
Hardware complexity and aftertreatment packaging costs escalate non-linearly above 300 HP, reshaping competitive positioning across brackets.
- Below 100 HP:Compact powertrains for orchard and vineyard equipment where emissions compliance costs disproportionately burden smaller competitors. Kubota specializes in this bracket with captive production.
- 100-200 HP:Municipal loaders and compact excavators balance fuel flexibility with packaging constraints, with natural gas and hybrid variants gaining traction.
- 200-300 HP:Mid-range agricultural tractors and construction equipment face modular aftertreatment fragmentation as standardized catalyst canisters reduce platform-specific engineering overhead.
- Above 300 HP:EPA Tier 4 Final and EU Stage V mandates force diesel particulate filter and selective catalytic reduction deployment, adding hardware cost that favors vertically integrated emissions control supply chains.
Above 300 HP retains the dominant share, while Below 100 HP is gaining share fastest as electrification validates predictable-duty architectures.
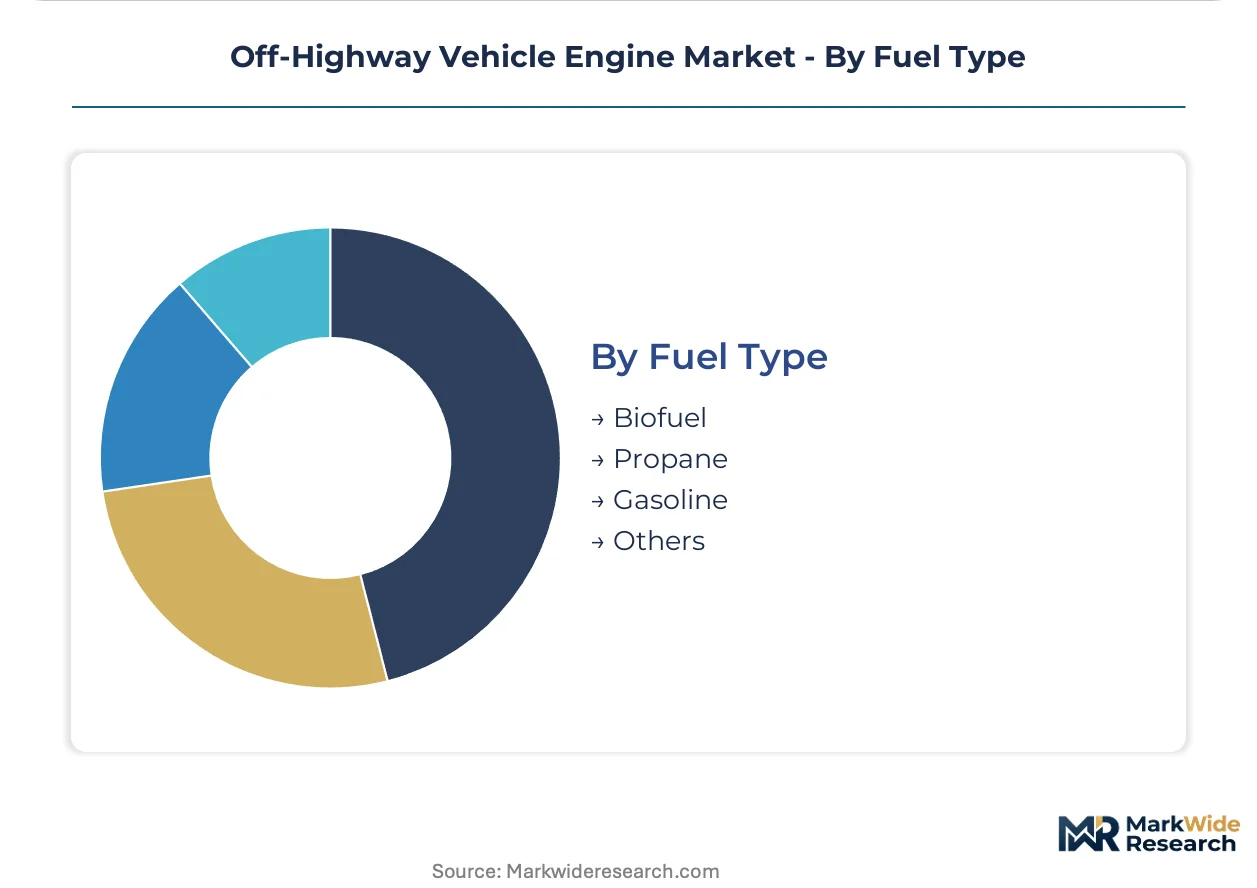
Fuel Type:
Compatibility certification and infrastructure availability determine addressable market boundaries for alternative fuels.
- Biofuel:Hydrotreated vegetable oil and biomass-to-liquid fuels offer drop-in compliance pathways for existing Tier 4 Final fleets without hardware modification, particularly in European markets with renewable fuel mandates.
- Propane:LPG configurations serve indoor construction and warehouse equipment where emissions restrictions limit diesel operation, with refueling infrastructure concentrated in North American distribution networks.
- Gasoline:Spark-ignition powertrains dominate sub-50 HP consumer-grade equipment where first-cost sensitivity outweighs fuel efficiency considerations.
- Others:Emerging synthetic and hydrogen-derived fuels occupy pilot-phase validation in select mining and port equipment applications.
Biofuel holds the dominant share among alternatives, while Propane is expanding most quickly in indoor construction niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engine exports flow to Brazilian agricultural OEMs while Australian mining contractors source from North American suppliers ahead of Tier 5-equivalent deadlines.
United States
EPA Tier 4 Final compliance deadlines drive fleet renewal in row-crop agriculture and surface mining. The agency's proposed Tier 5-equivalent standards are compressing procurement timelines for above-300 HP diesel units. Illinois and Iowa manufacturing clusters concentrate precision-ag engine production for domestic and export markets.
Germany
EU Stage V particulate number limits force redesign of aftertreatment architectures for construction and agricultural machinery. ECHA oversight of platinum group metal supply chains adds procurement complexity for catalyst manufacturers. Baden-Württemberg foundries supply heavy-duty engine blocks to OEMs across Europe and export markets.
Brazil
Soybean mechanization in Mato Grosso and Goiás drives demand for 200-400 HP compliant tractors and harvesters. ANVISA-aligned emissions trajectories are tightening faster than historical regulatory cycles. São Paulo state industrial parks host assembly operations for both domestic sales and Mercosur export fulfillment.
Australia
Underground hard-rock mining electrification pilots create adjacent demand for conventional engine displacement in surface operations. State-level environmental regulators in Western Australia and Queensland enforce mine-site emissions reporting beyond federal minimums. Perth engineering clusters service Pilbara iron ore and Bowen Basin coal fleet operators.
China
MEE tightening of domestic off-road emissions benchmarks creates parallel certification burdens for export-heavy construction equipment suppliers. National infrastructure project acceleration under dual carbon goals sustains equipment demand despite efficiency mandates. Weifang and Chongqing manufacturing bases supply both domestic OEMs and Belt and Road export contracts.
Off-Highway Vehicle Engine Market Vendor Landscape
Listed leaders compete with private specialists across aftertreatment integration capabilities and captive foundry access. The market structures around three tiers: diversified industrial conglomerates with full vertical scope, independent engine specialists with emissions control partnerships, and regional powertrain assemblers serving protected domestic markets. Competitive moves concentrate on modular platform sharing to amortize certification costs and strategic alliances for battery-electric subsystem development.
Among North American-listed industrial manufacturers, Caterpillar Inc. and Cummins Inc. exemplify the integrated-architecture archetype with in-house aftertreatment design. Deere & Company anchors the agricultural captive-production segment where proprietary precision-ag interfaces create equipment-level stickiness. Kubota Corporation occupies a distinct position in sub-100 HP compact powertrains, representing the specialized-regional-player archetype against larger diversified competitors.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Deutz AG |
| Kubota Corporation |
| Deere & Company |
| Komatsu Ltd. |
| Weichai Power Co., Ltd. |
| AGCO Corporation |
| Volvo Group |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 Final and EU Stage V compliance deadlines gate both supplier qualification and price differentiation simultaneously, as only manufacturers with vertically integrated aftertreatment capabilities can absorb the non-linear cost escalation above 300 HP while maintaining competitive positioning across agricultural and mining procurement tiers.
Pricing Analysis
Current-generation Tier 4 Final/Stage V-compliant powertrains command substantial premiums over prior-generation Tier 3 inventory and anticipated next-generation Tier 5-equivalent architectures. Three-tier pricing structure across premium certified, standard compliant, and economy transitional levels reflects certification grade and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from platinum group metal cost volatility passing directly to diesel oxidation catalyst bill-of-materials. Municipal rental fleets exhibit highest price sensitivity due to total cost-per-operating-hour contracting models, while mining contractors prioritize guaranteed maintenance intervals over upfront capital minimization.
Supply Chain Analysis
Germany, China, and India anchor heavy-duty engine block casting through concentrated foundry capacity in Baden-Württemberg, Weifang, and select industrial corridors. Production draws from palladium and rhodium feedstocks for catalytic converter manufacturing, plus wet-sleeve liner forgings and precision urea dosing hardware. Single-source vulnerability concentrates in platinum group metal refining capacity, exposing procurement to commodity price spikes. Distribution runs through OEM captive assembly networks and authorized dealer channels serving fleet operators with embedded service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
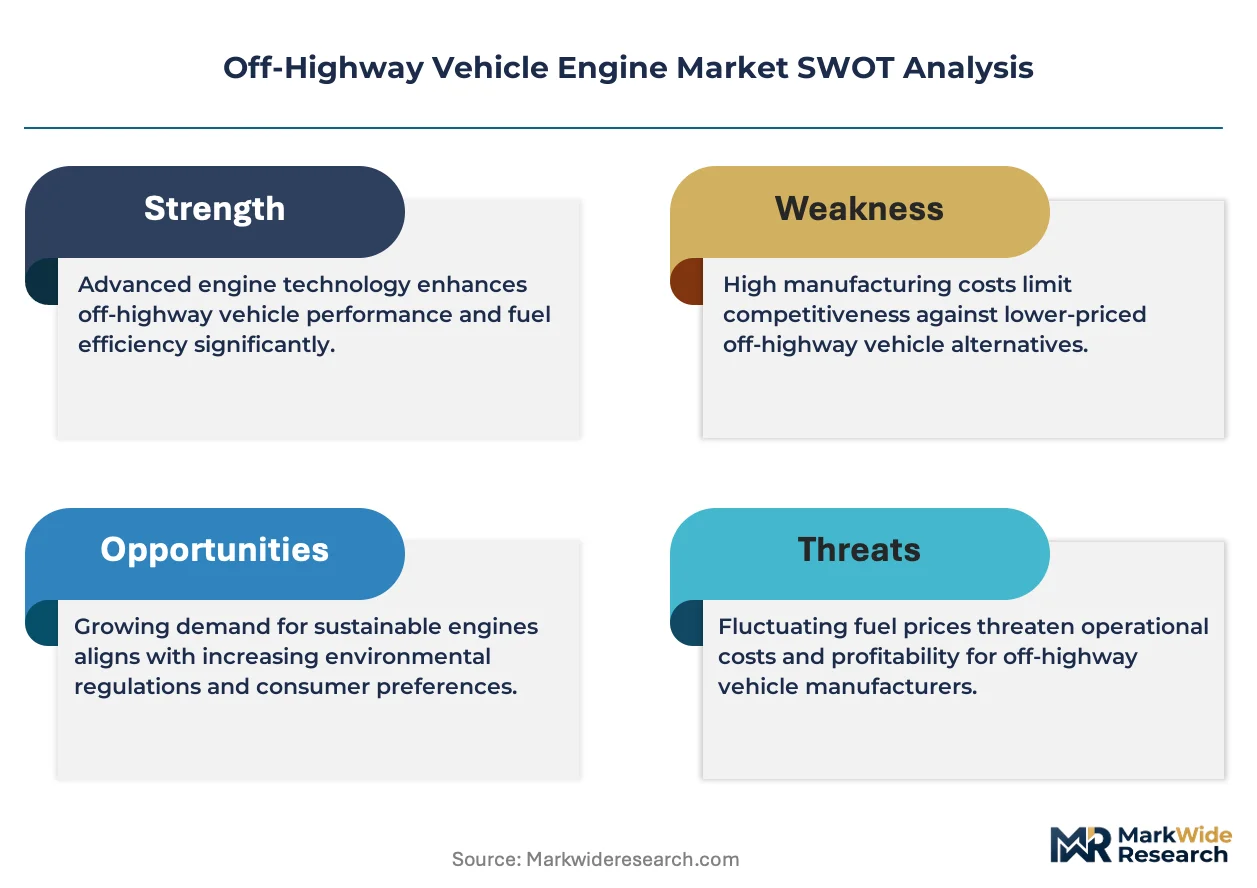
The off-highway vehicle engine market represents a high-growth disruption as electrification pilots in underground mining validate zero-emission architectures while diesel retains structural dominance in variable-load applications, creating parallel investment theses across divergent powertrain trajectories.
For Market Incumbents: Shield core mining and agricultural positions through backward integration into aftertreatment catalyst manufacturing and captive foundry capacity expansion in Germany or India. Accelerate modular platform sharing with construction equipment OEMs to amortize rising EU Stage V certification costs across higher production volumes. Prioritize calibration engineering talent retention as combustion optimization expertise concentrates among shrinking specialist cohorts.
For New Entrants and Emerging Players: Differentiate on battery-electric subsystem integration for sub-100 HP municipal and indoor construction niches where runtime predictability offsets lithium-ion mass penalties. Target Brazilian agricultural OEMs in Mato Grosso and Goiás with Stage V-ready powertrain offerings as ANVISA-aligned emissions trajectories tighten faster than historical regulatory cycles. Pursue telematics-integrated predictive maintenance partnerships to capture aftermarket revenue from independent rebuilders.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across above-300 HP diesel architectures as selective catalytic reduction and diesel particulate filter deployment adds hardware cost and packaging complexity. Acquisition focus should center on mid-cap specialists with captive emissions control supply chains and precision-ag interface capabilities serving North American row-crop segments. Monitor divergence between China's MEE test cycles and EPA/EU protocols as signal for duplicate validation burden intensity affecting export-heavy suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Aftertreatment Platform Sharing | Reduces platform-specific engineering overhead for agricultural OEMs accelerating model-year turnover. |
| Backward Integration into Catalyst Manufacturing | Insulates margins from palladium and rhodium price volatility passing to diesel oxidation systems. |
| Battery-Electric Subsystem Partnerships | Validates zero-emission architectures in Canadian and Australian hard-rock underground operations. |
| Telematics-Integrated Predictive Maintenance | Captures aftermarket revenue previously lost to independent engine rebuilders in municipal fleets. |
| Renewable Diesel Compatibility Certification | Enables drop-in compliance pathways for existing Tier 4 Final fleets without hardware modification. |
Methodological Framework
A spread of perspectives from mining fleet procurement directors, agricultural OEM platform engineers, aftertreatment system technical leads, and construction equipment rental channel managers converged on the working assumptions. Primary fieldwork combined with secondary validation from EPA regulatory filings, EU Stage V implementation guidance, ANVISA emissions trajectory documentation, and customs trade data for engine block castings. Bottom-up equipment unit demand modeling and top-down powertrain revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled include engine type, end-user application, power rating bracket, and fuel compatibility certification across the projection horizon. CAGRs derived from equipment replacement cycle analysis, emissions deadline procurement acceleration patterns, and regional infrastructure investment trajectories. Industry-specific forecast inputs incorporated platinum group metal price elasticity effects and foundry capacity utilization rates.
The analysis sits within stated boundaries; outcomes outside sustained mining capital expenditure levels, agricultural commodity price stability, or battery energy density improvement trajectories would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation timing and OEM platform standardization decisions. Recalibration cycles align with material shifts in emissions compliance verification protocols and electrification pilot commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Mining Vehicle Attachments Market
Off Road Vehicles
Off-Highway Vehicle HVAC Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market
Off Road Vehicles
Off-Highway Wheels Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
Off Highway Hybrid Vehicles Market
Off Road Vehicles
Global Electric Off-Highway Equipment Market
Off Road Vehicles
Global Automotive Off Highway Engine Market
Off Road Vehicles
Off-Highway Electric Vehicle Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
Off-Highway Engine Market
Off Road Vehicles
Electric Utility-Terrain Vehicle (UTV) Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market