
 Hybrid Off-Road Vehicle Market | 2026-2036
Hybrid Off-Road Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Off-Road Vehicle Market Foresight
EPA Tier 4 Final emissions standards for off-highway compression-ignition engines is realigning the cost-of-entry calculus for diesel-dependent manufacturers. Toyota leverages its parallel hybrid architecture to sustain dominance in recreational SUV segments across North American trail systems. Volvo anchors its position through integrated electrified powertrain manufacturing for heavy-duty off-road applications. Jeep competes on brand equity and aftermarket channel control in the sport-utility conversion space.
Hybrid off-road vehicles combine internal combustion engines with electric motor assist, typically deploying 48V to 400V battery systems paired with regenerative braking and torque-fill capabilities for low-speed traction over unimproved terrain. The primary purpose centers on extending operational range while reducing fuel consumption and particulate emissions in environments lacking charging infrastructure. The UTV segment leads volume as agriculture and forestry operators prioritize payload capacity with electrified assist, while plug-in hybrid configurations represent the fastest-growing drive system category where recreation users access trailhead charging. Full hybrid architectures still occupy the mature margin pool in military end-use applications where reliability requirements resist newer electrification formats.
The EPA governs exhaust emissions and fuel economy labeling for off-highway vehicles sold in the United States, while the EU Green Deal and F-Gas Regulation constrain refrigerant and manufacturing process choices for European-market units. China's MIIT enforces dual carbon goals that tighten corporate average fuel consumption for domestic hybrid off-road production. Stakeholders must monitor how divergent regional compliance timelines fragment platform development costs and force modular powertrain strategies.
Market Dynamics
EPA Tier 4 Final emissions standards are compressing diesel powertrain economics and forcing fleet operators toward electrified architectures. Mining contractors in Australia face compressed procurement timelines as state-level carbon thresholds accelerate hybrid UTV adoption.
Growth Catalysts
- Dual carbon goals:China's MIIT mandates tighten corporate average fuel consumption for domestic manufacturers, accelerating 48V system deployment across utility vehicle platforms.
- Federal land electrification:US National Park Service and Bureau of Land Management ranger fleets are replacing legacy diesel inventories with hybrid patrol vehicles.
- Torque-fill technology:Electric motor assist at low RPM enables diesel downsizing without sacrificing crawl-ratio performance in unimproved terrain.
Market Restraints
- Lithium supply concentration:Cell-grade lithium hydroxide processing concentrates in Chile and Australia, exposing battery pack costs to geopolitical logistics disruptions.
- High-voltage certification delays:400V system homologation timelines stretch 18-24 months under evolving UN ECE R100 safety protocols.
- Diesel price arbitrage:Off-highway fuel tax exemptions in remote mining regions sustain cost advantages for conventional compression-ignition engines.
Strategic Opportunities
- Trailhead charging infrastructure:Recreation users in Colorado and Utah access Level 2 charging at public land access points, enabling plug-in hybrid configurations.
- Swappable battery architectures:Forestry contractors in Nordic regions adopt modular pack designs for continuous operation without charging downtime.
- EU Green Deal procurement rules:Public-sector tender specifications now weight lifecycle emissions, favoring hybrid powertrains in municipal utility fleets.
Industry Challenges
- Power electronics talent scarcity:Inverter and DC-DC converter design expertise concentrates among automotive suppliers, forcing off-road OEMs into costly external engineering contracts.
- Regenerative braking calibration:Traction control integration across variable terrain surfaces requires extensive field validation, stretching development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Off-Road Vehicle Market |
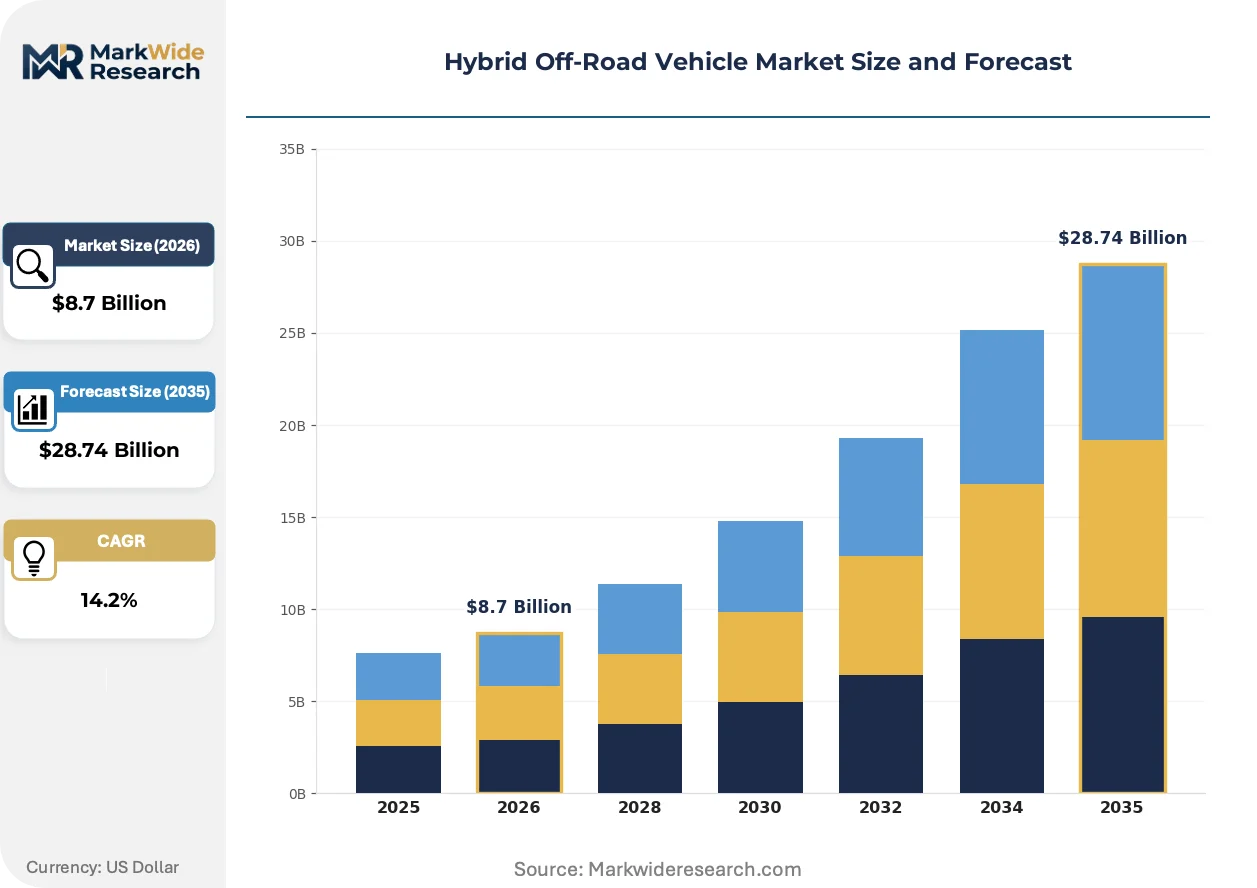
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: ATV, UTV, SUV, Truck Drive System: Parallel Hybrid, Series Hybrid, Plug-in Hybrid, Full Hybrid End User: Agriculture, Forestry, Military, Recreation Fuel Source: Gasoline, Diesel, Electricity, Biofuel |
| Companies Covered | Volvo, Lexus, Toyota, Mazda, Hyundai, Jeep, Land Rover, Honda, Subaru, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Off-Road Vehicle Market Shifts & Advancements
Electrification architectures are diverging across voltage classes as manufacturers balance thermal management against payload preservation. Three distinct trajectories are compressing product development cycles.
Silicon carbide (SiC) power semiconductors are reducing inverter switching losses by half compared to silicon IGBTs. Heavy-duty off-road OEMs in Germany and Japan are adopting 800V SiC inverters for mining haulers. This voltage escalation is electrifying powertrain thermal budgets and enabling liquid-cooled motor designs previously impractical at 400V.
EU F-Gas Regulation is banning refrigerants with global warming potential above 150 in mobile air conditioning systems. Off-road vehicle HVAC suppliers must reformulate thermal management circuits before 2027. European agricultural equipment manufacturers are accelerating R-1234yf adoption, while Australian mining operators face retrofit complexity in tropical operating conditions.
Fleet procurement is consolidating around total cost of ownership models that weight fuel savings against acquisition premiums. US federal contractors now require 10-year lifecycle analysis in RFP scoring. State transportation departments in California and Washington are embedding carbon accounting into equipment lease structures, redirecting capital toward hybrid platforms.
Hybrid Off-Road Vehicle Market Segmentation
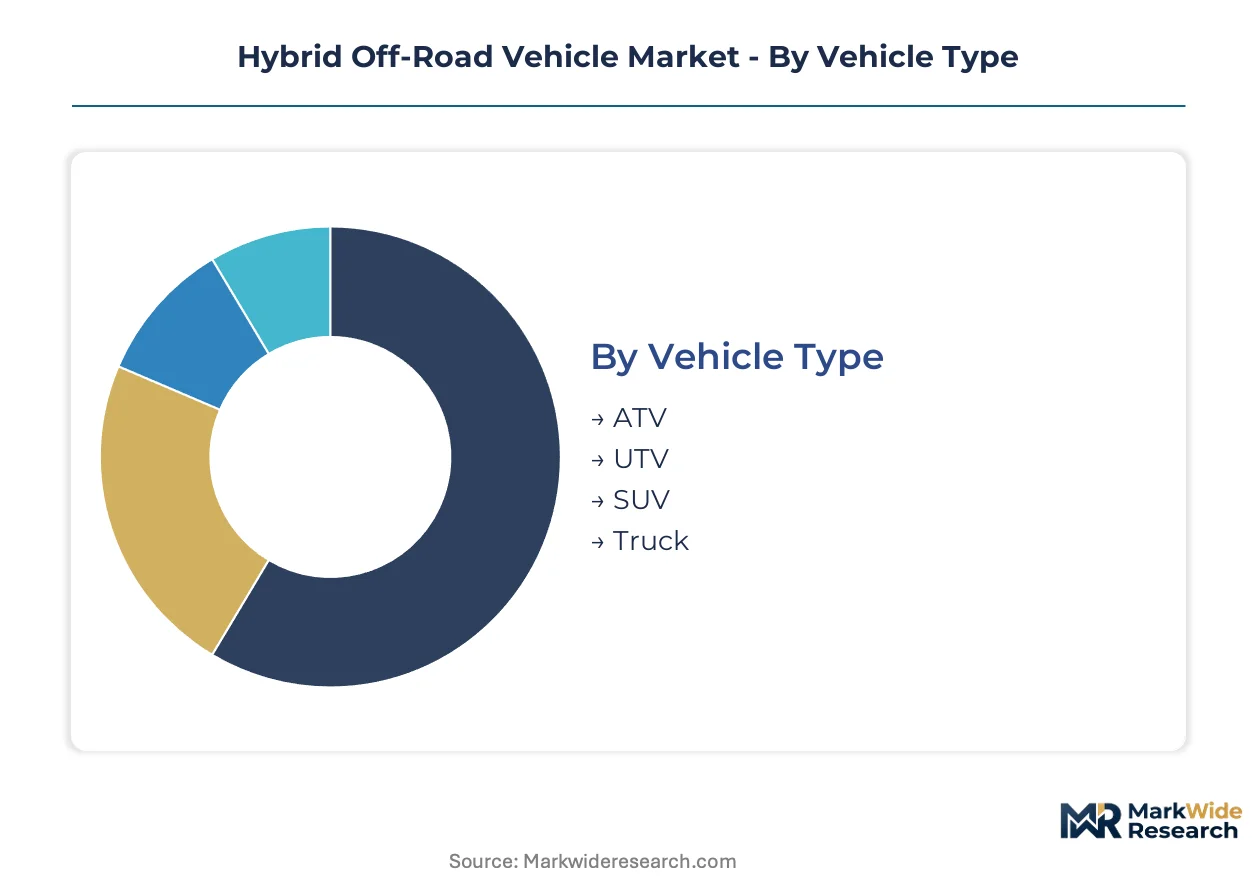
Hybrid off-road vehicle procurement decisions pivot on terrain demands, duty cycles, and charging access. Manufacturers configure powertrain architectures differently across vehicle formats and operational profiles, creating distinct margin pools and development priorities.
Vehicle Type:
Payload requirements and trail width regulations determine fleet composition for commercial operators versus recreation buyers.
- UTV:Side-by-side configurations with 48V mild-hybrid assist dominate agricultural and forestry fleet orders. Australian mining contractors prioritize these units for diesel emissions compliance under state carbon thresholds, accepting acquisition premiums against fuel savings.
- SUV:Unibody platforms integrate parallel hybrid architectures for trail access and daily drivability. US National Park Service ranger fleets are electrifying patrol inventories with these configurations, driven by federal land management mandates.
- ATV:Compact single-rider units with limited battery packaging space favor simple regenerative braking over full hybrid systems.
- Truck:Heavy-duty frames for mining and military applications require 400V architectures with torque-fill capabilities for unimproved terrain.
Volume sits with UTV platforms; growth tilts toward SUV configurations as recreation users access trailhead charging infrastructure.
Drive System:
Development cycle compression varies by electrification depth, with certification timelines stretching for higher-voltage architectures.
- Plug-in Hybrid:Larger battery packs enabling 20-40 mile electric-only range attract Colorado and Utah recreation users with trailhead Level 2 access. These configurations carry the steepest acquisition premiums but deliver maximum fuel displacement where charging infrastructure exists.
- Full Hybrid:Self-charging architectures with no plug dependency dominate military end-use applications where reliability requirements resist newer formats. The mature margin pool here reflects proven field performance in austere environments.
- Parallel Hybrid:Toyota's architecture sustains dominance in recreational segments through shared powertrain economics with passenger car platforms.
- Series Hybrid:Range-extender configurations with engine-isolated traction motors see limited adoption due to thermal packaging constraints in off-road duty cycles.
Procurement concentrates on full hybrid architectures; plug-in configurations are climbing fastest where charging infrastructure penetrates.
End User:
Operational intensity and emissions exposure create divergent total-cost-of-ownership calculations across sectors.
- Agriculture:Seasonal duty cycles with high idle times favor 48V systems for torque-fill during low-speed field operations. European farmers face EU Green Deal procurement rules weighting lifecycle emissions in equipment tenders.
- Military:Reliability certification and supply chain security requirements sustain demand for full hybrid architectures despite technology advances elsewhere.
- Forestry:Nordic contractors adopt swappable battery modular designs for continuous operation without charging downtime in remote harvesting zones.
- Recreation:Weekend trail users with intermittent access to charging infrastructure drive plug-in hybrid adoption in US mountain states.
Revenue pools concentrate in agriculture; military procurement offers margin stability through long-term supply agreements.
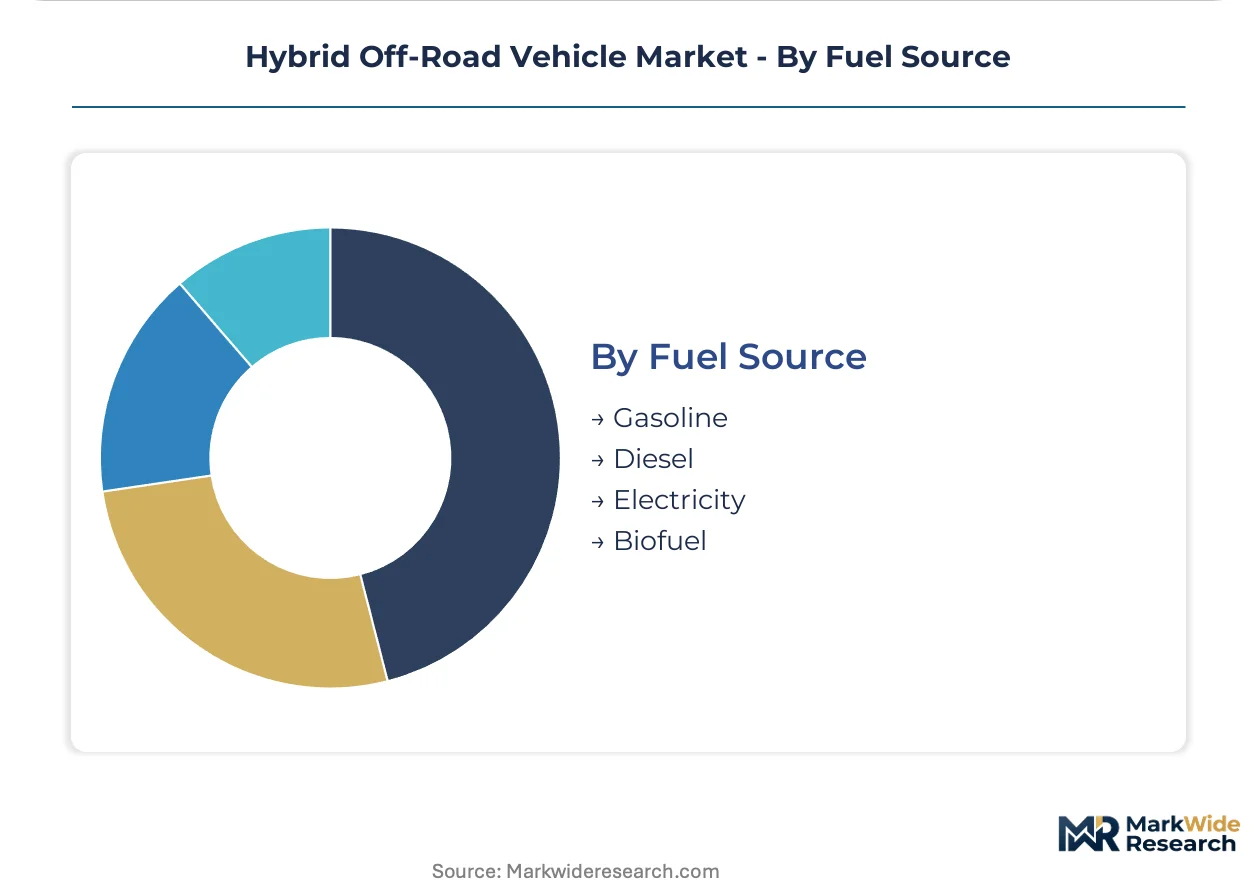
Fuel Source:
Energy density and refueling infrastructure availability constrain architecture choices in remote operating environments.
- Diesel:Compression-ignition hybrids with electric assist enable downsizing without sacrificing crawl-ratio performance. EPA Tier 4 Final emissions standards are compressing economics for conventional diesel, accelerating hybrid adoption.
- Gasoline:Spark-ignition engines paired with electric motors dominate recreation and light utility segments where refueling infrastructure is ubiquitous.
- Electricity:Grid-charged operation remains limited to plug-in hybrid architectures given charging infrastructure gaps in off-highway environments.
- Biofuel:Renewable diesel and HVO compatibility offers emissions reduction without powertrain redesign for European agricultural equipment.
Diesel retains volume in heavy-duty applications; gasoline-electric configurations are gaining share fastest in recreation and light commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia's mining tax incentive zones are concentrating hybrid UTV procurement as state carbon thresholds compress fleet replacement timelines. Chile's lithium-rich Atacama region anchors battery supply chain integration for South American operators. German industrial clusters in Bavaria and Baden-Württemberg drive powertrain engineering density for heavy-duty applications.
United States
Federal land management agencies in Colorado and Utah are electrifying ranger inventories through Bureau of Land Management procurement mandates. EPA Tier 4 Final emissions standards compress diesel economics for off-highway compression-ignition engines. Detroit's automotive engineering corridor sustains parallel hybrid architecture development for recreational SUV platforms.
Australia
Queensland and Western Australia mining contractors face compressed procurement timelines under state-level diesel emissions thresholds. The country's national environmental regulator enforces carbon intensity benchmarks for remote operations. Perth's resource technology cluster anchors fleet conversion consulting for open-pit extraction operators.
China
Domestic manufacturers accelerate 48V system deployment across utility vehicle platforms to meet MIIT corporate average fuel consumption mandates. Dual carbon goals tighten development cycles for NMPA certification timelines. Yangtze River Delta manufacturing bases concentrate battery pack integration for agricultural equipment exports.
Germany
Bavarian agricultural equipment manufacturers adopt R-1234yf refrigerant systems ahead of EU F-Gas Regulation deadlines. EU Green Deal procurement rules weight lifecycle emissions in municipal utility fleet tenders. Stuttgart's automotive engineering ecosystem develops 800V silicon carbide inverters for heavy-duty mining haulers.
Japan
METI efficiency standards accelerate mild-hybrid system deployment across domestic utility vehicle production. Full hybrid architectures dominate military end-use procurement where reliability requirements resist newer electrification formats. Nagoya's industrial corridor sustains integrated powertrain manufacturing for torque-fill applications.
Hybrid Off-Road Vehicle Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across voltage class segments and end-use applications. The market structure tilts toward consolidated control in heavy-duty mining and military procurement, while recreation and agriculture segments sustain fragmented competition among regional assemblers. Strategic archetypes include integrated powertrain manufacturers, brand-equity-driven sport-utility converters, and modular battery system suppliers. Dominant competitive moves center on backward integration into cell-grade lithium supply and geographic expansion through fleet service partnerships in resource extraction zones.
Among established automotive conglomerates, Toyota and Volvo exemplify divergent strategic positioning within electrified off-road architectures. Toyota anchors recreational segments through shared passenger car powertrain economics, while Volvo occupies heavy-duty applications through integrated manufacturing for mining and construction end-uses. Jeep represents brand-equity-driven competition in sport-utility conversion markets where aftermarket channel control sustains margin capture.
| Leading Market Players |
|---|
| Volvo |
| Lexus |
| Toyota |
| Mazda |
| Hyundai |
| Jeep |
| Land Rover |
| Honda |
| Subaru |
| Others |
Supply & Pricing Matrix
Federal land management procurement mandates for electrified ranger fleets are compressing supplier lead times and forcing battery pack integrators to absorb certification costs that cascade into tiered pricing structures. This demand-side pressure concentrates pricing power among 400V system suppliers capable of meeting 18-24 month UN ECE R100 homologation timelines.
Pricing Analysis
Lead-time premiums dominate pricing architecture, with 400V architecture suppliers commanding acquisition premiums against 48V mild-hybrid alternatives available on spot procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates certified 800V SiC inverter platforms from 400V silicon IGBT configurations and uncertified 48V assist systems. Cost compression in 48V tiers is intensifying because Chinese MIIT efficiency mandates are flooding agricultural export markets with domestic production overcapacity. Mining contractors in Australia exhibit lowest price sensitivity due to state carbon threshold compliance deadlines, while Nordic forestry operators demonstrate highest sensitivity as swappable battery modular designs commoditize pack-level value capture.
Supply Chain Analysis
Cell-grade lithium hydroxide processing rests on Chilean and Australian chemical conversion facilities, with cathode active material production concentrated in China and South Korea. Silicon carbide wafer supply draws from Japanese substrate producers and German epitaxy specialists, while high-voltage inverter assembly clusters in Bavaria and Nagoya. Single-source vulnerability concentrates in 800V SiC module packaging, where automotive Tier 1 suppliers restrict capacity allocation to off-road OEMs. Distribution runs through fleet service partnerships in Western Australian mining tax incentive zones and direct OEM contracts for US federal land management procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final emissions standards function as a cost-of-compliance moat, elevating capital requirements for diesel-dependent entrants while rewarding electrified architecture incumbents with procurement preference in federal and state fleet tenders.
For Market Incumbents: Anchor market position through backward integration into cell-grade lithium supply chains in Chile and Australia, securing pack cost stability against geopolitical logistics disruptions. Defend against emerging Chinese 48V system exporters by accelerating 800V SiC certification investments that exploit 18-24 month UN ECE R100 homologation barriers. Channel control through fleet service partnerships in Queensland and Western Australia sustains margin capture against modular battery system specialists. For New Entrants and Emerging Players: Fleet leasing companies represent the most accessible channel partner type for bypassing incumbent OEM direct sales relationships. Target US Bureau of Land Management ranger fleet replacement cycles in Colorado and Utah, where trailhead charging infrastructure penetration enables plug-in hybrid value propositions absent from incumbent 48V-heavy portfolios. White-space concentration sits in swappable battery modular designs for Nordic forestry contractors, where continuous operation requirements resist conventional charging-dependent architectures. For Investors and Strategic Acquirers: The window for entry favors power electronics specialists with inverter and DC-DC converter design expertise currently concentrated among automotive Tier 1 suppliers. Long-term viability hinges on regulatory compliance depth rather than volume scale, positioning certified 400V-800V system developers for sustained procurement preference as EPA and EU Green Deal timelines tighten. Monitor lithium hydroxide spot price volatility as the inflection signal for battery pack cost compression trajectories and hybrid acquisition premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Cell-grade lithium offtake from Chilean processors secures cost visibility for 400V pack assembly. |
| 800V SiC Certification Investment | UN ECE R100 homologation capability differentiates suppliers in Australian mining fleet tenders. |
| Fleet Service Partnership | Direct maintenance contracts with Western Australian contractors capture lifecycle revenue beyond unit sale. |
| Swappable Battery Modular Design | Nordic forestry adoption eliminates charging downtime constraints in remote harvesting zones. |
| Backward Integration into Lithium Processing | Upstream control over hydroxide conversion mitigates Chile-Australia logistics disruption exposure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across OEM platform engineers, mining fleet procurement directors, federal land management vehicle coordinators, and power electronics supplier technical leads. EPA Tier 4 Final rulemaking documents, MIIT corporate average fuel consumption bulletins, EU F-Gas Regulation implementation guidance, and UN ECE R100 safety protocol amendments supplied regulatory trajectory validation. Bottom-up triangulation across vehicle registration databases in Colorado, Utah, Queensland, and Western Australia reconciled with top-down mining contractor capex survey data.
Data-stream reconciliation across production volume tracking, battery pack shipment manifests, and fleet procurement award announcements informed the analytical framework across the analysis window. Segmentation dimensions modeled include vehicle class, propulsion architecture voltage tier, end-use sector operational intensity, and regional regulatory compliance cluster. CAGRs derived from logistic diffusion curves fitted to electrification penetration patterns in comparable heavy-duty equipment categories, with explicit incorporation of lithium hydroxide price elasticity and charging infrastructure density thresholds as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including military procurement security classifications, autonomous off-road vehicle development trajectories, and hydrogen fuel cell alternative powertrain commercialization timelines. Forecasts reflect documented assumptions regarding EPA enforcement consistency, EU Green Deal procurement rule implementation pace, and Chilean lithium export policy stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Mining Vehicle Attachments Market
Off Road Vehicles
Off-Highway Engine Market
Off Road Vehicles
Four-Wheel Drive Vehicles Market
Off Road Vehicles
Electric Off-Road Vehicles Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
Off-Highway Electric Vehicle Market
Off Road Vehicles
Electric Utility-Terrain Vehicle (UTV) Market
Off Road Vehicles
Off Highway Vehicles Brake Systems Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Off-Highway Vehicle Engine Market
Off Road Vehicles
Off-Road Vehicle Market