
 Australia Cold Chain Logistics Market | 2026-2036
Australia Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Cold Chain Logistics Market Analysis
Temperature-monitoring software subscriptions is decoupling asset ownership from operational control in Australian cold chain contracts. Linfox leverages its national depot network to anchor pharmaceutical lanes requiring validated thermal profiles. NewCold Advanced Cold Logistics sustains automated high-bay density advantages that reduce energy cost exposure in Victoria and Queensland. Toll Group competes through integrated port-to-warehouse customs brokerage for import-reliant perishables.
Australia cold chain logistics encompasses the temperature-controlled movement and storage of perishable goods within a range typically spanning minus 25 degrees Celsius to plus 25 degrees Celsius, utilizing vapor-compression refrigeration, phase-change materials, and real-time telemetry to preserve product integrity across extended distances. The primary commercial purpose centers on bridging the geographic separation between concentrated agricultural production zones and dispersed urban consumption centers while satisfying strict biosecurity and pharmaceutical stability requirements. Refrigerated transport commands the largest share of technology expenditure as fleet operators retrofit diesel units with electric alternatives to meet state-level emissions frameworks. Pharmaceuticals application segments attract premium service margins due to TGA-mandated qualification documentation and the clinical cost of temperature excursions. Tracking solutions represent the fastest-growing technology category as blockchain-integrated visibility becomes a procurement precondition for major retailers and distributors.
TGA sets validation and documentation standards for therapeutic goods distribution, while state-level environmental protection agencies enforce refrigerant phase-down schedules under national ozone obligations. Food Standards Australia New Zealand mandates temperature control requirements through Chapter 3 of its code, directly shaping equipment specifications and HACCP audit frequency. The Australian Energy Market Commission influences cold storage facility economics through demand-response tariff structures that penalize peak-period consumption. Stakeholders must monitor the pace of electric refrigerated vehicle TCO parity against diesel equivalents and the readiness of renewable-powered warehouse microgrids to offset grid dependency.
Market Dynamics
Electric refrigeration retrofits are compressing fleet replacement cycles as state emissions frameworks in New South Wales and Victoria accelerate diesel phase-out timelines for temperature-controlled transport.
Growth Catalysts
- TGA validation protocols:Tightening documentation requirements for temperature-sensitive biologics are expanding qualified cold storage capacity across pharmaceutical distribution networks nationwide.
- Intermodal corridor investment:Concentrated infrastructure deployment along the Sydney-Melbourne freight corridor is reducing transit time variability for perishable cargo.
- Blockchain-integrated telemetry:Real-time temperature logging with immutable audit trails is becoming a procurement precondition for major Australian retailers and hospital networks.
Market Restraints
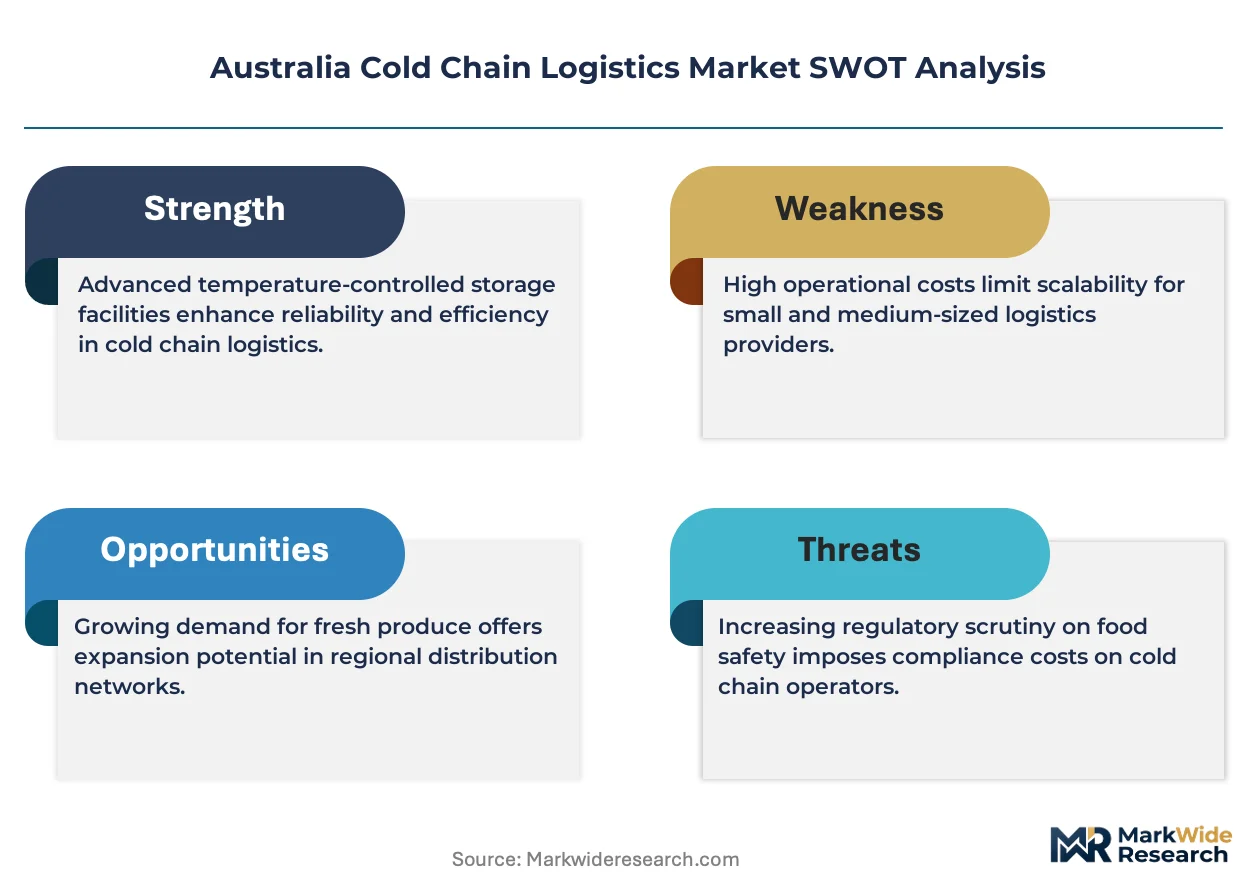
- Electric vehicle TCO gap:Battery-electric refrigerated trucks carry 35-45% capital cost premiums over diesel equivalents before state incentive offsets.
- Refrigerant supply concentration:Hydrofluorocarbon phase-down schedules under national ozone obligations are compressing service parts availability for legacy vapor-compression units.
- Grid dependency exposure:Cold storage facilities face demand-response tariff penalties during peak consumption periods under Australian Energy Market Commission structures.
Strategic Opportunities
- Queensland agricultural export expansion:Underdeveloped validated cold chain infrastructure between Brisbane and regional produce zones creates first-mover positioning for temperature-controlled logistics providers.
- Renewable-powered warehouse microgrids:Solar-battery hybrid systems can offset grid dependency and reduce exposure to peak-period electricity pricing at distribution facilities.
- Automated high-bay density systems:Robotics-enabled storage configurations reduce energy cost exposure per pallet position in Victoria and Queensland facilities.
Industry Challenges
- Thermal qualification specialist scarcity:Validated packaging engineering and cold chain mapping expertise remains concentrated among a limited pool of consultants familiar with TGA documentation requirements.
- Legacy fleet integration complexity:Mixed diesel-electric operations create maintenance training bifurcation and spare parts inventory duplication for transport operators.
- Biosecurity certification timelines:Australian Department of Agriculture export approvals for temperature-controlled perishables extend lead times for new lane establishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Cold Chain Logistics Market |
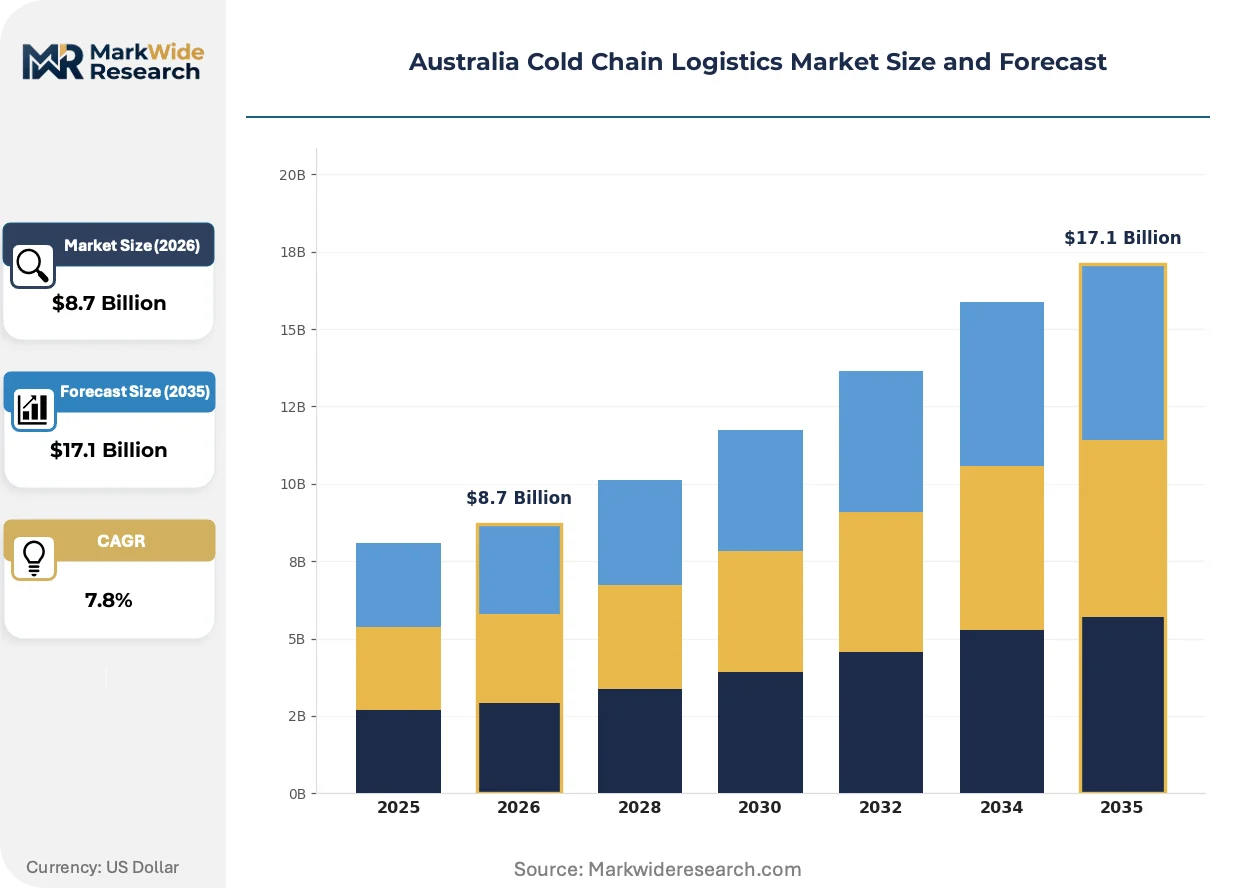
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Dairy Products, Meat Technology: Refrigerated Transport, Temperature Monitoring, Insulated Packaging, Tracking Solutions Application: Pharmaceuticals, Food & Beverage, Biotechnology, Chemicals End User: Retailers, Distributors, Wholesalers, Manufacturers |
| Companies Covered | NewCold Advanced Cold Logistics, Toll Group, Linfox, Lineage Logistics, Americold Logistics, Karras Cold Logistics, DP World, QMC Logistics, Laverton Cold Storage, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Cold Chain Logistics Market Emerging Trajectories
Telemetry convergence with distributed ledger architectures is redefining accountability structures in temperature-controlled logistics. Three developments are compressing competitive differentiation timelines.
Phase-change material (PCM) thermal packaging is expanding into pharmaceutical last-mile distribution as courier networks seek passive temperature protection without active refrigeration units. Hospital pharmacies and specialty clinics in metropolitan Sydney and Melbourne are adopting PCM shippers for same-day biologics delivery. This expansion is compressing the addressable market for conventional refrigerated van services in urban pharmaceutical logistics.
TGA's 2023 guidance on continuous temperature monitoring for gene therapies is mandating redundant sensor arrays and automated excursion alerting across distribution networks. The regulation is forcing wholesale distributors to upgrade warehouse management systems and transport validation protocols. Pharmaceutical 3PL providers in New South Wales and Victoria are responding with dedicated qualification engineering teams and accelerated thermal mapping cycles.
Subscription-based visibility platforms are displacing capital-intensive fleet ownership models among mid-sized produce exporters. Queensland and Victorian agricultural cooperatives are contracting temperature-monitoring as a service rather than investing in owned refrigerated assets. This behavioral shift is most visible in the berry and stone fruit segments, where seasonal volume volatility makes fixed fleet commitments economically unattractive.
Australia Cold Chain Logistics Market Segmentation
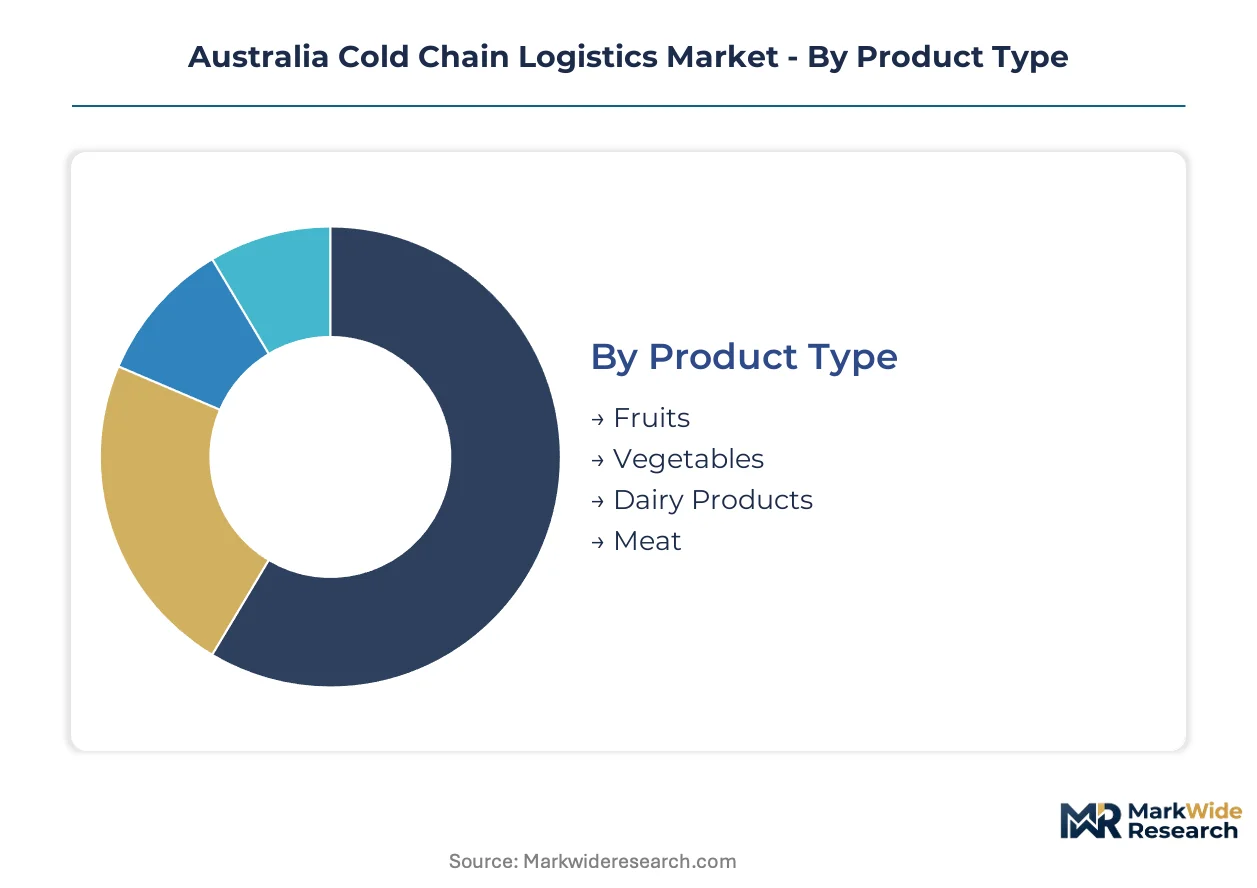
Australian cold chain logistics segments by product, technology, application, and end user. Each dimension shapes capital deployment and operational requirements differently across the Sydney-Melbourne corridor and emerging Queensland lanes.
Product Type:
Standalone refrigerated warehousing dominates high-volume perishables, while embedded last-mile solutions serve fragmented produce networks.
- Meat:Beef and lamb exports drive the largest refrigerated container volumes through Port of Melbourne. Queensland and New South Wales processing facilities require minus 18 degrees Celsius holding capacity for Middle Eastern and Asian market access under biosecurity protocols.
- Dairy Products:Cheese and butter exports concentrate in Victorian Gippsland production zones. Temperature excursions above 4 degrees Celsius trigger export rejection, forcing validated cold chain investment across collection, processing, and port staging.
- Fruits:Stone fruit and berry exporters in Victoria and Queensland face seasonal volume spikes that strain fixed fleet capacity.
- Vegetables:Leafy greens and brassicas demand rapid cooling post-harvest to preserve shelf life in domestic supermarket distribution.
Meat leads volumes today; dairy is gaining share fastest on export premiumization.
Technology:
Cost tier separation is pronounced between capital-intensive active systems and lower-entry passive alternatives.
- Refrigerated Transport:Diesel-powered mechanical refrigeration units still anchor intermodal corridors, though New South Wales and Victoria emissions frameworks are compressing retrofit timelines. Fleet operators face 35-45% capital premiums for battery-electric alternatives before state incentive offsets.
- Temperature Monitoring:Real-time telemetry with blockchain-integrated audit trails is becoming mandatory for pharmaceutical distribution under TGA guidance. Hospital networks and major retailers now require continuous data logging as a procurement precondition.
- Tracking Solutions:GPS-integrated visibility platforms enable dynamic rerouting during transit disruptions.
- Insulated Packaging:Phase-change material shippers reduce dependency on active refrigeration for last-mile pharmaceutical delivery.
Refrigerated transport leads volumes today; temperature monitoring is expanding most quickly on regulatory compulsion.
Application:
Margin structure varies dramatically between premium-validated pharmaceutical lanes and price-sensitive food commodity flows.
- Pharmaceuticals:Gene therapies and biologics require TGA-mandated qualification documentation, redundant sensor arrays, and automated excursion alerting. Distribution networks in New South Wales and Victoria are deploying dedicated thermal mapping teams to satisfy tightening validation protocols.
- Food & Beverage:Supermarket supply chains drive standardized temperature requirements under Food Standards Australia New Zealand Chapter 3. High-volume perishables concentrate demand along the Sydney-Melbourne freight corridor where intermodal cold storage capacity is expanding.
- Biotechnology:Clinical trial materials and research specimens require ultra-low temperature holding below minus 70 degrees Celsius.
- Chemicals:Temperature-sensitive industrial inputs face less stringent documentation but require hazardous goods compliance.
Food and beverage leads volumes today; pharmaceuticals shows the steepest margin expansion trajectory.
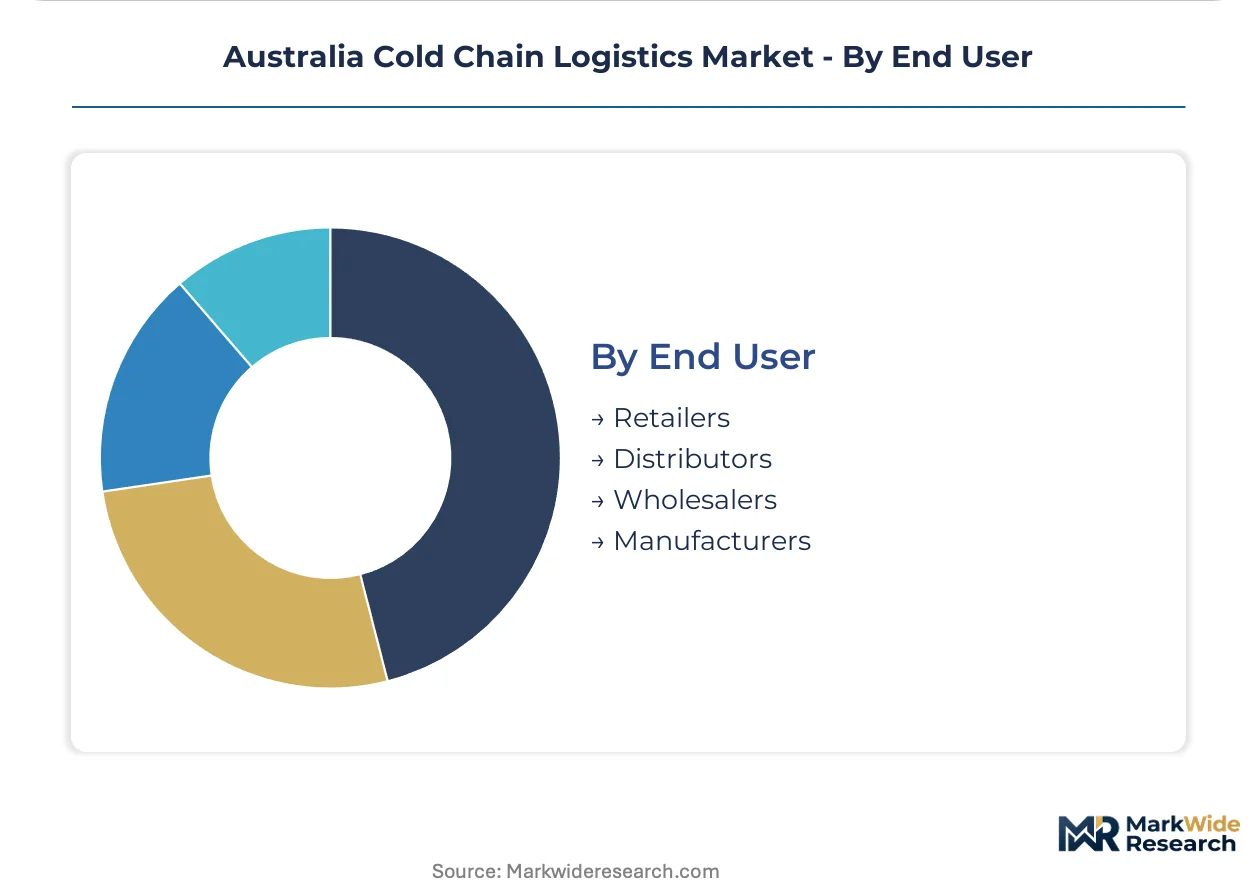
End User:
Customer type determines contract structure, with integrated retailers capturing operational control through software subscriptions.
- Retailers:Coles and Woolworths dominate domestic cold chain procurement, mandating supplier compliance with centralized visibility platforms. Their national distribution centers in Sydney and Melbourne anchor temperature-controlled lane requirements.
- Distributors:Pharmaceutical wholesale networks face TGA thermal qualification burdens that favor outsourced 3PL partnerships over owned infrastructure.
- Manufacturers:Food processors in regional Victoria and Queensland seek flexible capacity arrangements to manage seasonal harvest peaks.
- Wholesalers:Independent produce aggregators concentrate fragmented agricultural supply for export consolidation.
Retailers lead volumes today; distributors are climbing fastest on pharmaceutical outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New South Wales and Victoria command the majority of Australian cold chain investment, while Queensland and Western Australia present contrasting infrastructure maturity profiles that shape competitive entry strategies.
New South Wales
Sydney's port and intermodal terminals anchor pharmaceutical distribution networks serving hospital networks and biotech clusters. TGA validation requirements for temperature-sensitive biologics are tightening documentation protocols across wholesale distributors. The Botany Bay logistics precinct is adding validated cold storage capacity to capture gene therapy distribution volumes.
Victoria
Gippsland dairy processing and Melbourne's pharmaceutical manufacturing base generate dual-demand streams for minus 18 and plus 2 to plus 8 Celsius lanes. State-level emissions frameworks are accelerating diesel fleet phase-out timelines for refrigerated transport operators. The Port of Melbourne cold chain corridor is expanding automated high-bay density warehousing to reduce energy cost exposure.
Queensland
Brisbane's underdeveloped validated infrastructure relative to southern states creates positioning opportunities for temperature-controlled logistics providers targeting agricultural export growth. The Australian Energy Market Commission's demand-response tariffs are penalizing peak-period cold storage consumption. Regional produce zones between Brisbane and the Darling Downs lack consistent refrigerated capacity for stone fruit and berry exporters.
Western Australia
Perth's geographic isolation from eastern intermodal corridors necessitates dedicated cold storage investment for domestic food security and mining camp provisioning. Biosecurity certification timelines from the Australian Department of Agriculture extend lead times for temperature-controlled perishable exports. The Kewdale freight terminal is adding refrigerated container handling to reduce dwell times for chilled meat shipments.
South Australia
Adelaide's wine and seafood export sectors require precise temperature control through Port Adelaide staging facilities. Food Standards Australia New Zealand Chapter 3 mandates are shaping equipment specifications for cross-border movements into Victoria and New South Wales. The Edinburgh Parks industrial zone is attracting automated cold storage investment to serve premium agricultural processing.
Australia Cold Chain Logistics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated logistics providers capturing pharmaceutical lanes through qualification expertise while regional cold storage operators defend food commodity volumes on price. Market structure tilts toward consolidation in metropolitan corridors where intermodal access and TGA-compliant infrastructure create barriers. Three archetypes dominate: global cold storage networks with automated density advantages, national transport operators leveraging depot networks for lane control, and regional specialists capturing seasonal agricultural peaks. Capacity expansion and qualification engineering investments represent the dominant competitive moves as operators respond to tightening pharmaceutical validation protocols.
Among national-scale operators, Linfox, Toll Group, and NewCold Advanced Cold Logistics occupy distinct positioning vectors. Linfox exemplifies the depot-network archetype, anchoring pharmaceutical lanes through validated thermal profile capabilities. Toll Group represents integrated port-to-warehouse service bundling for import-reliant perishables. NewCold Advanced Cold Logistics sits within the automated high-bay density tier, reducing energy cost exposure through robotics-enabled storage configurations in Victoria and Queensland facilities.
| Leading Market Players |
|---|
| NewCold Advanced Cold Logistics |
| Toll Group |
| Linfox |
| Lineage Logistics |
| Americold Logistics |
| Karras Cold Logistics |
| DP World |
| QMC Logistics |
| Laverton Cold Storage |
| Others |
Supply Flow & Price Mechanics
Horizontal consolidation among pharmaceutical 3PL providers in New South Wales and Victoria anchors both supply positioning and premium pricing power through TGA-validated infrastructure scarcity. This integration pattern allows incumbent operators to capture margin premiums from gene therapy distributors while locking out unqualified competitors.
Pricing Analysis
Capacity additions in Victoria and Queensland are reshaping price floors for standard cold storage tiers while validated pharmaceutical lanes sustain premiums. Three-tier pricing structure across premium, standard, and economy levels separates TGA-qualified biologics handling from commodity perishables and seasonal agricultural overflow. Price differentiation hinges on certification grade and geographic delivery cost, with Sydney-Melbourne corridor lanes commanding premiums over regional Queensland routes. Pricing pressure stems from electric fleet capital premiums compressing transport margins, though pharmaceutical segments show least price sensitivity due to clinical cost of temperature excursions.
Supply Chain Analysis
Returns and refurbishment flows for phase-change material shippers and reusable thermal packaging are creating secondary supply loops that reduce raw material dependency in pharmaceutical last-mile networks. Equipment manufacturing concentrates in China, Germany, and the USA, while refrigerant chemical supply draws from Chinese and Indian specialty chemical producers. Supply chain risk centers on single-source vulnerability for hydrofluorocarbon alternatives under national ozone phase-down schedules. Distribution runs through intermodal corridors anchored by Port of Melbourne and Port Botany, with regional Queensland lanes remaining fragmented.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TGA validation requirements in Australia impose compliance costs that exceed Southeast Asian alternatives, creating geographic-arbitrage pressure for cost-sensitive agricultural exporters while rewarding premium pharmaceutical infrastructure investment domestically.
For Market Incumbents: Hedge against electric fleet transition risks by securing renewable-powered warehouse microgrids before Australian Energy Market Commission tariff structures harden. Defend TGA-qualified lane positions through accelerated thermal mapping capabilities and redundant sensor array deployment that emerging competitors cannot replicate quickly. For New Entrants and Emerging Players: TGA's 2023 gene therapy guidance in Australia opens a window for specialist qualification engineering services that incumbent 3PLs must outsource. Target underdeveloped Queensland agricultural corridors between Brisbane and Darling Downs with subscription-based temperature-monitoring platforms rather than capital-intensive fleet ownership. For Investors and Strategic Acquirers: Consolidation pressure builds where TGA compliance burdens exceed standalone operator capital capacity. Five-to-ten year viability favors automated high-bay density facilities with energy cost advantages. Watch electric refrigerated vehicle total-cost-of-ownership parity against diesel equivalents as the inflection signal for transport asset revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Qualification Engineering Investment | Dedicated thermal mapping teams capture gene therapy distribution volumes under tightening validation protocols. |
| Renewable-Powered Warehouse Microgrid Deployment | Solar-battery hybrid systems offset Australian Energy Market Commission peak-period tariff penalties. |
| Automated High-Bay Density Expansion | Robotics-enabled storage reduces energy cost exposure per pallet position in Victoria and Queensland. |
| Subscription-Based Visibility Platform Launch | Temperature-monitoring as a service displaces capital-intensive fleet ownership among Queensland agricultural cooperatives. |
| Electric Fleet Retrofit Acceleration | Battery-electric refrigerated units satisfy New South Wales and Victoria emissions frameworks before diesel phase-out deadlines. |
Methodological Framework
Direct dialogue with cold chain operations directors, pharmaceutical distribution managers, TGA compliance consultants, and fleet procurement officers grounded the qualitative assessment, cross-referenced against customs trade data, Australian Energy Market Commission tariff filings, TGA guidance documents, and Food Standards Australia New Zealand regulatory updates. Bottom-up capacity modeling across states triangulated with top-down expenditure analysis from major retailers and hospital networks.
Segment-level projections across product type, technology, application, and end user dimensions were generated through driver elasticity modeling and infrastructure investment tracking throughout the forecast period. CAGRs were derived from capacity expansion pipelines, fleet replacement cycles, and regulatory compliance cost trajectories, with electric vehicle adoption curves and renewable energy tariff structures serving as key forecast inputs.
Revisions become necessary when TGA guidance timelines accelerate, state emissions frameworks shift diesel phase-out deadlines, or Australian Energy Market Commission demand-response structures materially change. Forecasts reflect documented assumptions about infrastructure investment continuity and technology cost curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Vietnam Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
Vietnam Logistics Market
Logistics and Shipping
Turkey Courier Express and Parcel (CEP) Market
Logistics and Shipping
GCC Event Logistics Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
Container Terminal Automation Market
Logistics and Shipping
South Korea Parcel Delivery Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Russia 3PL Market
Logistics and Shipping
Iraq Air Freight Transport Market
Logistics and Shipping
GCC Trailer Market