
 US Off-Road Vehicles Market | 2026-2036
US Off-Road Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
US Off-Road Vehicles Market Analysis
EPA Tier 4 and CARB-certified engine specifications is unwinding legacy two-stroke dominance in the dirt bike category. Polaris Inc. leverages its Rokon and Ranger platforms to sustain dealer network density across the Rocky Mountain corridor. Honda Motor Co. anchors the entry-level ATV segment with proven automatic transmission architectures. BRP differentiates through its Can-Am lineup by dominating the high-displacement side-by-side niche with turbocharged Rotax engines.
US off-road vehicles encompass motorized machines engineered for unpaved terrain traversal, typically featuring minimum ground clearances exceeding eight inches, four-wheel-drive or all-wheel-drive configurations, and roll-cage structures rated to SAE J1194 or OSHA 1928.53 standards for occupant protection. These machines serve ranchers, recreational riders, military trainers, and commercial contractors who require mobility across surfaces where conventional highway vehicles cannot operate. The gasoline fuel type still occupies the largest installed base, though electric powertrains are concentrating fastest in California and Arizona where charging infrastructure for rural properties is expanding. UTV applications lead unit economics due to higher average selling prices and attachment ecosystems, while the recreational end-user category controls the broadest aftermarket parts and accessories revenue pool.
The EPA enforces evaporative emissions standards under 40 CFR Part 1051 that constrain carburetor-fed engine designs and push manufacturers toward electronic fuel injection. OSHA mandates rollover protective structures and seatbelt integration for agricultural and commercial deployments under 29 CFR 1928.51, directly shaping UTV chassis engineering priorities. The CPSC maintains active defect surveillance for ATV stability incidents, influencing manufacturer recall protocols and youth model restrictions. Stakeholders must monitor how state-level OHV registration fee structures and trail access permitting in Utah, Colorado, and Arizona reshape regional demand patterns without warning.
Market Dynamics
Electric powertrain migration is compressing gasoline engine development cycles while EPA Tier 4 emissions deadlines force rapid fuel injection retrofits across the dirt bike and ATV supplier base.
Growth Catalysts
- EPA Tier 4 Final Standards:Evaporative emissions rules under 40 CFR Part 1051 are eliminating carburetor-fed engines and opening procurement windows for electronic fuel injection platforms.
- Ranching Fleet Modernization:Texas and Montana property management operations are replacing aging ATV fleets with utility task vehicles rated for OSHA 1928.53 rollover protection.
- Desert Recreation Corridors:Arizona and Utah trail access permitting expansions are channeling registration fee revenue into maintained OHV infrastructure.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production for electric UTV prototypes depends on processing capacity concentrated in Nevada and overseas, creating input cost volatility.
- Two-Stroke Legacy Installed Base:Carburetor-dependent recreational dirt bikes face premature obsolescence as CARB zero-emission mandates tighten pre-2027.
- Charging Infrastructure Gaps:Rural properties in Wyoming and Idaho lack 240V service density for electric side-by-side deployment at scale.
Strategic Opportunities
- California ZEV Mandate Alignment:CARB-certified electric powertrain development opens preferential fleet procurement channels for municipal and agricultural buyers.
- Attachment Ecosystem Expansion:UTV hydraulic and PTO-compatible implements for Colorado ranching operations extend average revenue per unit beyond base chassis sales.
- Direct-to-Property Distribution:Bypassing traditional dealer networks for Texas and Montana large-acreage customers reduces margin leakage and accelerates replacement cycles.
Industry Challenges
- Powertrain Engineering Talent Scarcity:Electronic fuel injection calibration and battery thermal management expertise is concentrating at Tier 1 automotive suppliers, raising recruitment costs.
- SAE J1194 Certification Timelines:Rollover protective structure testing delays for new UTV chassis designs compress product launch windows against regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Off-Road Vehicles Market |
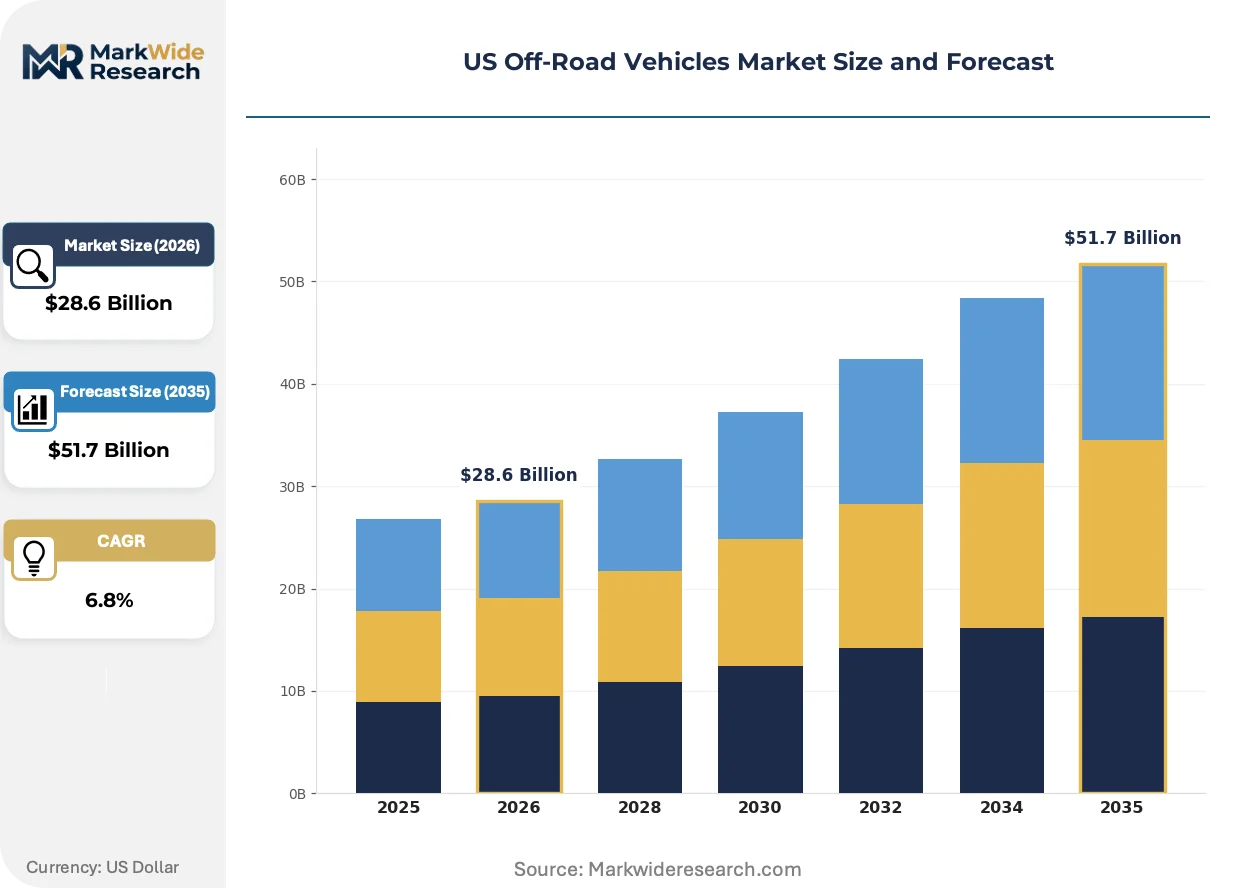
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: ATV, UTV, Dirt Bike, 4x4 Truck Fuel Type: Gasoline, Diesel, Electric, Hybrid Application: Recreational, Agricultural, Military, Commercial End User: Individuals, Government Agencies, Enterprises, Clubs |
| Companies Covered | Polaris Inc., Honda Motor Co., Yamaha Motor Co., BRP, Arctic Cat, Kawasaki Heavy Industries, Can-Am, John Deere, CFMOTO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Off-Road Vehicles Market Emerging Trajectories
Powertrain diversification is splitting the supplier base into gasoline optimization specialists and electric architecture developers, with regulatory deadlines forcing parallel investment rather than sequential transition.
Modular battery pack architectures are fragmenting the traditional integrated powertrain supply relationship. Ranching and commercial contractors in Arizona are piloting swappable battery configurations for multi-shift property management operations. This technology is fragmenting dealer service revenue streams away from engine rebuilds toward electrical diagnostics and cell replacement protocols.
OSHA 29 CFR 1928.51 mandates for agricultural UTV deployments are hardening seatbelt integration and rollover structure requirements. Manufacturers serving Texas and Montana ranching fleets must now engineer chassis platforms that satisfy both recreational trail access and commercial occupational safety standards. The side-by-side segment bears the heaviest compliance burden as agricultural buyers represent its fastest-growing end-use vertical.
Subscription-based fleet management tools are replacing discrete equipment purchases for large-scale property operations. Colorado and Utah recreational rental operators now bundle UTV access with maintenance scheduling and trail permitting through mobile platforms. This shift concentrates buyer power among multi-unit fleet managers and compresses aftermarket parts revenue into bundled service agreements.
US Off-Road Vehicles Market Segmentation
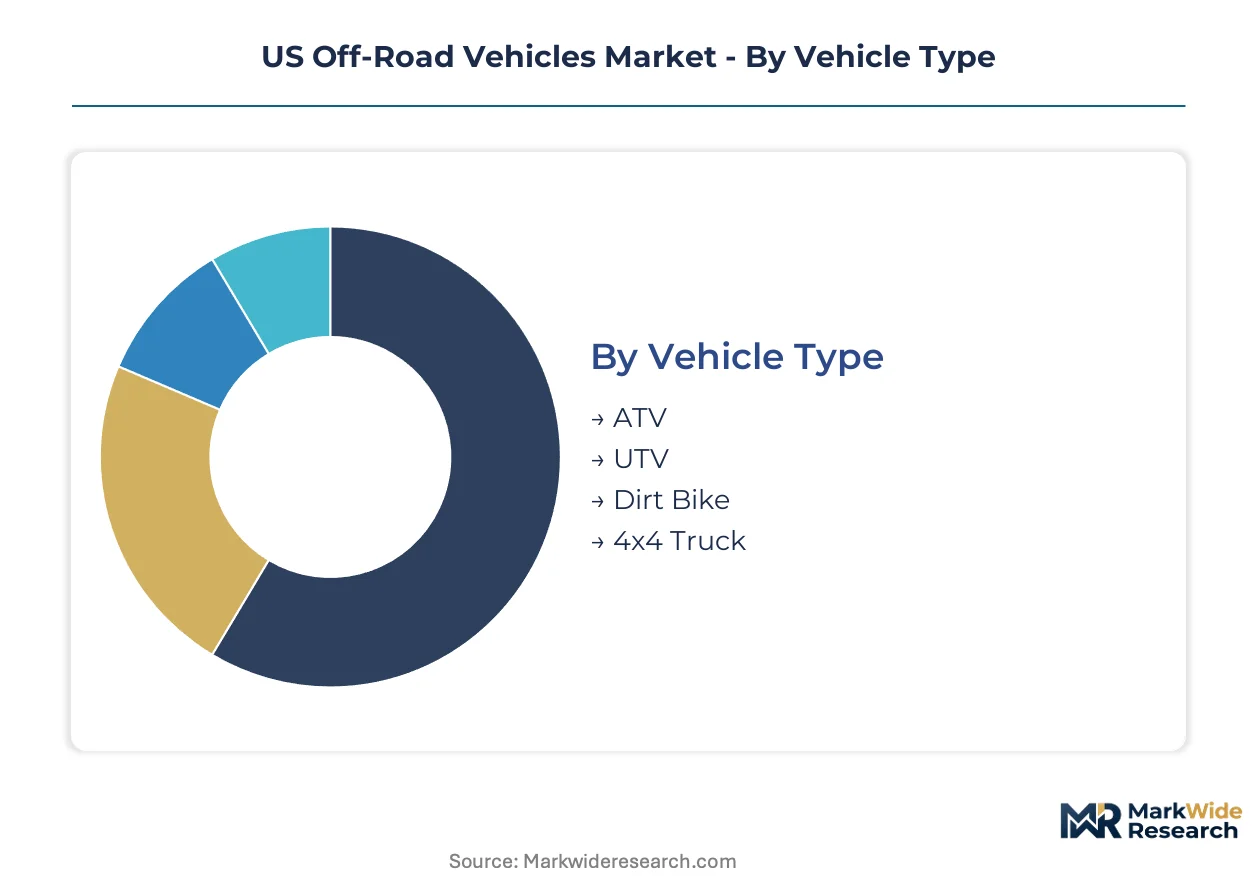
Segmentation reveals how EPA emissions deadlines and OSHA safety mandates concentrate investment across distinct equipment categories. Channel strategies differ sharply between recreational dealers serving Arizona trail riders and direct fleet sales penetrating Texas ranching operations.
Vehicle Type:
Dealer networks in the Rocky Mountain corridor stock disproportionately toward utility platforms, while recreational specialists in the Southwest emphasize high-displacement trail machines. OEM distribution investments track these channel divergences.
- ATV:Compact four-wheel platforms with automatic transmission architectures anchor entry-level ranching purchases. Demand concentrates in Montana property management where aging fleet replacement cycles align with OSHA rollover compliance deadlines.
- UTV:Side-by-side configurations featuring SAE J1194-rated roll cages and hydraulic PTO compatibility command premium positioning. Texas and Colorado commercial buyers drive expansion through attachment ecosystem purchases extending per-unit economics.
- Dirt Bike:Two-stroke engine architectures face accelerated obsolescence under CARB zero-emission mandates.
- 4x4 Truck:Modified highway-legal platforms bridge recreational and commercial use cases in Utah desert corridors.
ATV maintains the broadest installed base. UTV is where expansion concentrates.
Fuel Type:
Cost tier stratification separates carburetor-fed legacy platforms from electronic fuel injection and electric architectures, with compliance deadlines forcing premature replacement cycles rather than organic upgrade demand.
- Gasoline:Electronic fuel injection platforms now dominate new unit production as EPA Tier 4 evaporative emissions rules eliminate carburetor designs. Arizona and California charging infrastructure gaps sustain gasoline relevance for rural property deployments.
- Electric:Modular battery pack architectures enable swappable configurations for multi-shift ranching operations. California CARB-certified procurement channels and Nevada cell processing proximity concentrate development investment.
- Diesel:Compression-ignition platforms persist in high-torque agricultural implements.
- Hybrid:Range-extended architectures remain experimental for remote property applications.
Gasoline retains volume leadership. Electric is climbing the fastest.
Application:
Customer type determines margin structure, with commercial and military buyers demanding bundled service agreements while recreational purchasers generate fragmented aftermarket parts revenue.
- Recreational:Trail access permitting in Utah and Arizona channels registration fee revenue into maintained OHV infrastructure. Seasonal demand patterns concentrate in Southwestern desert corridors.
- Agricultural:OSHA 29 CFR 1928.51 mandates harden rollover protection and seatbelt integration requirements. Texas and Montana ranching fleets drive UTV specification toward commercial-grade chassis platforms.
- Military:Training applications demand ruggedized architectures with simplified field maintenance protocols.
- Commercial:Contractor deployments in Colorado require hybrid recreational-commercial certification compliance.
Recreational controls aftermarket breadth. Agricultural is gaining share fastest.
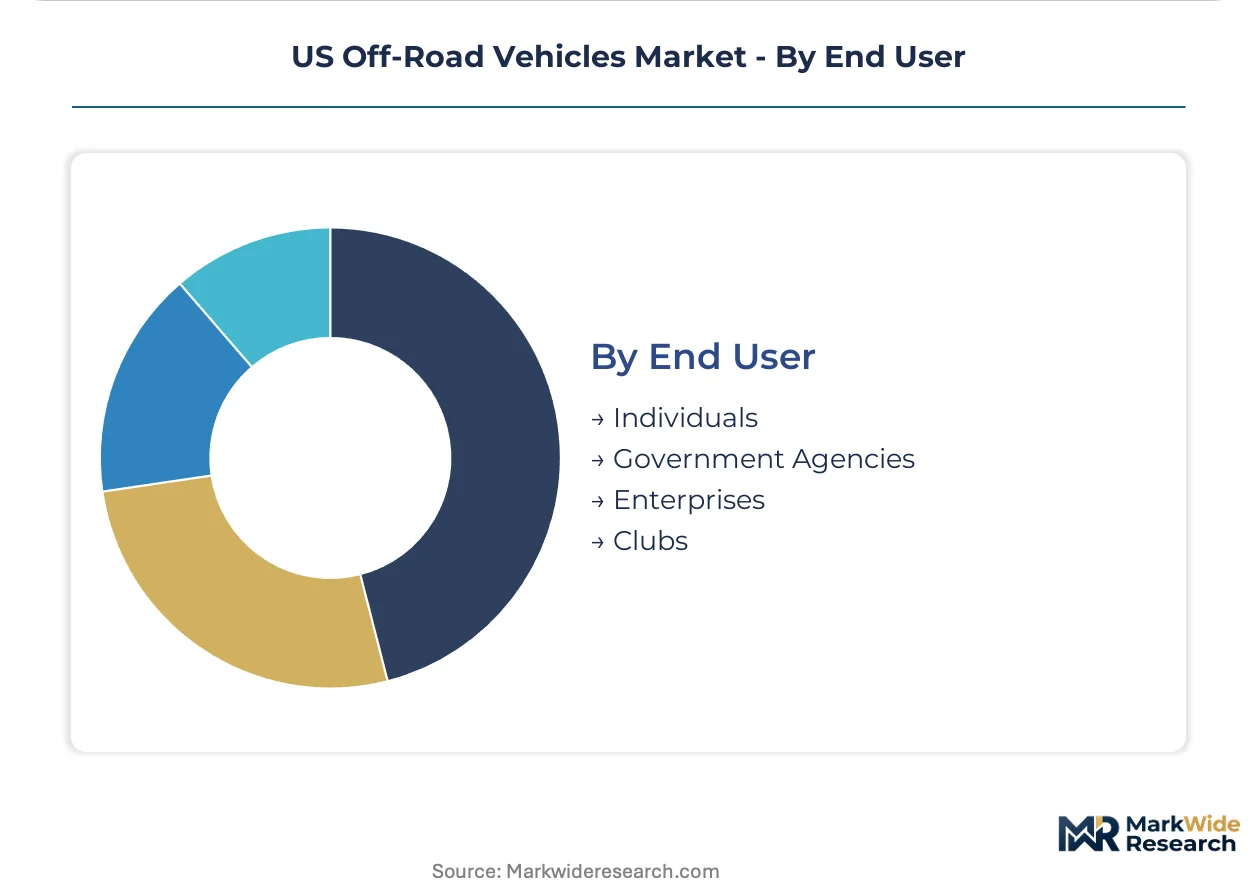
End User:
Procurement scale fragments the buyer landscape, with enterprise fleet managers consolidating purchasing power through subscription-based maintenance bundles while individual buyers remain price-sensitive and dealer-dependent.
- Individuals:Price-sensitive purchasers dominate entry-level ATV and dirt bike categories through traditional dealer financing.
- Government Agencies:Municipal and federal procurement in California prioritizes CARB-certified electric platforms for preferential fleet channels.
- Enterprises:Large-acreage ranching operations in Texas and Montana bypass dealer networks for direct manufacturer relationships.
- Clubs:Organized recreational groups in Utah and Colorado negotiate volume pricing for seasonal fleet access.
Individuals represent the deepest installed base. Enterprises are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US off-road vehicles sector operates as a net importer of specialized components while maintaining domestic final assembly capacity concentrated in the Upper Midwest and Southwest. Regional demand patterns diverge sharply between commercial ranching applications in the Great Plains and recreational desert riding corridors.
Texas
Large-acreage ranching operations in the Panhandle and Hill Country drive fleet-scale UTV procurement for property management and livestock handling. OSHA 29 CFR 1928.51 mandates for rollover protection and seatbelt integration shape procurement specifications toward commercial-grade chassis platforms. The Dallas-Fort Worth metroplex anchors distribution infrastructure serving agricultural buyers across the state.
California
CARB zero-emission mandates accelerate electric powertrain development for both recreational and utility applications. The state's evaporative emissions standards under Title 13 CCR constrain carburetor-fed engine sales and open procurement windows for electronic fuel injection and battery-electric platforms. Charging infrastructure expansion in rural Imperial and Riverside counties enables electric side-by-side deployment for agricultural operations.
Arizona
Desert recreation corridors in Mohave and Yuma counties channel registration fee revenue into maintained OHV trail infrastructure. The state land department's permitting expansions support seasonal demand concentration from Southwestern trail riders. Phoenix-area dealers stock disproportionately toward high-displacement recreational platforms with SAE J1194-rated rollover structures.
Montana
Expanding ranching operations in the Eastern Plains and Mountain West drive replacement cycles for aging ATV fleets with OSHA-compliant utility task vehicles. Property management applications prioritize hydraulic PTO compatibility and attachment ecosystem flexibility. Billings and Missoula serve as distribution nodes for agricultural fleet sales across the Northern Rockies.
Colorado
Recreational rental operators in the Western Slope and Front Range urban corridor pilot subscription-based fleet management tools bundling UTV access with maintenance scheduling. The state's trail access permitting system concentrates registration revenue into maintained OHV infrastructure serving both local riders and destination tourists. Denver-based commercial contractors demand hybrid recreational-commercial certification compliance for multi-use deployments.
US Off-Road Vehicles Market Vendor Landscape
Listed leaders compete with private specialists across powertrain architecture and distribution channel strategy. The vendor base concentrates around three tiers: diversified powersports conglomerates with captive engine manufacturing, agricultural equipment incumbents leveraging dealer networks, and emerging electric specialists targeting CARB-certified procurement channels. Competitive moves center on attachment ecosystem expansion to extend per-unit economics and direct-to-property distribution bypassing traditional dealer networks for large-acreage ranching customers.
Within the diversified powersports tier, Polaris Inc. and BRP exemplify platform breadth across utility and recreational segments, while Honda Motor Co. anchors the entry-level automatic transmission architecture segment. Arctic Cat occupies a position within the specialist tier focusing on cold-climate performance adaptations. These three companies represent distinct strategic archetypes: platform diversification, transmission technology leadership, and regional specialization respectively.
| Leading Market Players |
|---|
| Polaris Inc. |
| Honda Motor Co. |
| Yamaha Motor Co. |
| BRP |
| Arctic Cat |
| Kawasaki Heavy Industries |
| Can-Am |
| John Deere |
| CFMOTO |
| Others |
Supply Flow & Price Mechanics
Electronic fuel injection retrofits displacing carburetor-fed legacy engines are simultaneously redrawing component sourcing maps from Midwest machining clusters toward Tier 1 automotive electronics suppliers and compressing margin structures for dirt bike and ATV manufacturers facing EPA Tier 4 compliance deadlines.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the UTV segment, with SAE J1194 certification grade and hydraulic PTO compatibility serving as primary price differentiation drivers. Cost compression in the entry-level ATV tier is intensifying because electronic fuel injection system costs exceed legacy carburetor architectures, forcing absorption or pass-through tradeoffs. Ranching fleet purchasers in Texas and Montana show lowest price sensitivity due to attachment ecosystem bundling, while individual recreational riders in Arizona exhibit highest sensitivity to base chassis pricing.
Supply Chain Analysis
Inventory lead times for electronic fuel injection controllers and battery management systems have extended as semiconductor allocation prioritizes automotive OEMs over powersports suppliers. Manufacturing concentration rests on Mexico for chassis fabrication, Japan for precision transmission components, and domestic Upper Midwest facilities for final assembly. Lithium-ion cell supply draws from Nevada processing capacity and overseas refining operations, creating single-source vulnerability for electric UTV prototypes. Distribution runs through captive dealer networks in the Rocky Mountain corridor and direct-to-property channels for large-acreage ranching operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment, where EPA and OSHA certification requirements create structural barriers that compound over successive compliance cycles.
For Market Incumbents: Compound certification entrenchment by accelerating SAE J1194 rollover structure testing capacity ahead of OSHA 1928.51 enforcement expansion, while securing captive supply of electronic fuel injection controllers through backward integration into Tier 1 automotive electronics partnerships. Electric powertrain specialists and modular battery pack developers represent the primary emerging threat to gasoline-optimized platform economics. For New Entrants and Emerging Players: Swappable battery service layers for multi-shift ranching operations expose an incumbent underservice gap in Arizona and Texas property management applications. Target direct-to-property distribution bypassing dealer networks for Montana and Colorado large-acreage customers, with subscription-based fleet management tools as the primary go-to-market angle against transactional equipment sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed powersports conglomerates holding fragmented attachment ecosystem portfolios. Long-term viability favors platforms with demonstrated CARB certification pathways and established OSHA compliance architectures. Watch EPA Tier 4 enforcement variance across state environmental agencies as the signal for margin compression inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Electronic Fuel Injection Platform Migration | EPA Tier 4 compliance eliminates carburetor-fed engines and opens procurement windows for EFI suppliers. |
| Modular Battery Pack Architecture Development | Swappable configurations enable multi-shift ranching operations and fragment dealer service revenue streams. |
| Direct-to-Property Distribution Expansion | Bypassing dealer networks for Texas and Montana large-acreage customers reduces margin leakage. |
| Attachment Ecosystem Acquisition | Hydraulic and PTO-compatible implements extend average revenue per unit beyond base chassis sales. |
| CARB-Certified Electric Powertrain Investment | California ZEV mandate alignment opens preferential municipal and agricultural fleet procurement channels. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers at Texas and Montana ranching operations, powersports dealer principals in Arizona and Colorado, OEM platform engineers, and aftermarket parts distributors. Secondary validation drew from EPA 40 CFR Part 1051 filings, OSHA 29 CFR 1928.51 enforcement data, state OHV registration databases, and SEC disclosures from listed powersports manufacturers. Bottom-up unit shipment estimates triangulated against top-down value projections across vehicle type, fuel architecture, and application segments.
Across the analysis window, volume and value outputs reflect segmentation modeling across vehicle type, fuel architecture, application, and end-user procurement scale dimensions. CAGRs were derived from regression-based trajectory fitting against historical replacement cycles and regulatory deadline impacts. Industry-specific forecast inputs include EPA Tier 4 compliance cost pass-through assumptions and OSHA rollover protection mandate adoption curves by state.
Underlying assumptions cover stable lithium-ion cell processing capacity expansion in Nevada, with deviation risk concentrated in semiconductor allocation priorities and state-level OHV trail access permitting volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Off Highway Hybrid Vehicles Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
Global Automotive Off Highway Engine Market
Off Road Vehicles
Off-Highway Wheels Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Global Electric Off-Highway Equipment Market
Off Road Vehicles
Hybrid Off-Road Vehicle Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Global Off-Highway Vehicle Telematics Market
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Off-Road Equipment Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
Off Road All Terrain E-Scooter Market
Off Road Vehicles
Small Off-Road Engines Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market