
 Marijuana Drying and Curing Equipment Market | 2026-2036
Marijuana Drying and Curing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Marijuana Drying and Curing Equipment Market Analysis
Stainless steel is decoupling from aluminum as the dominant chamber material in premium curing systems, altering unit economics for manufacturers and buyers alike. Yofumo Technologies leverages proprietary terpene preservation algorithms to anchor its position in climate-controlled curing. Triminator specializes in trim-to-cure workflow integration, while EnWave Corporation extends its radiation drying expertise from food processing into cannabis applications.
Marijuana drying and curing equipment encompasses engineered systems that reduce post-harvest moisture content from approximately 75% to 10-15% while preserving cannabinoid and terpene profiles through precise temperature, humidity, and airflow management. These systems serve licensed cultivators and processors who must meet batch consistency requirements for regulated retail distribution. Climate control systems command the deepest margin pools due to integrated sensor arrays and software subscriptions, while vacuum drying represents the fastest-expanding technology segment as solventless extraction feedstock standards tighten. Commercial growers absorb the majority of medium-scale and large-scale capacity deployments as multi-state operators standardize post-harvest infrastructure.
State cannabis regulatory commissions in Colorado and California enforce microbial and moisture-content testing that directly dictates curing protocol compliance, while OSHA guidelines govern volatile organic compound exposure in processing facilities. The FDA maintains indirect influence through good manufacturing practice expectations that percolate into ancillary equipment specifications. Stakeholders must weigh capital allocation between scalable industrial platforms and modular units as federal scheduling reconsideration threatens to reshape interstate commerce rules and equipment depreciation schedules.
Market Dynamics
Vacuum drying technology is electrifying post-harvest infrastructure decisions as cultivators face escalating terpene retention mandates from state cannabis regulatory commissions.
Growth Catalysts
- State-level cannabis quality mandates:Colorado and California have tightened microbial and moisture-content testing protocols, forcing licensed cultivators to upgrade curing infrastructure to maintain compliance and avoid batch rejection.
- Solventless extraction feedstock standards:Premium hashish and rosin producers require precisely controlled moisture profiles that legacy convection methods cannot reliably deliver, pulling investment toward vacuum and climate-controlled systems.
- Multi-state operator standardization:Large commercial growers across the United States are deploying uniform post-harvest platforms across facilities to reduce operational variance and simplify training protocols.
Market Restraints
- Stainless steel input cost volatility:Chamber fabrication depends on nickel-alloy pricing, and premium curing system manufacturers absorb margin compression when commodity markets spike.
- Single-source sensor array dependency:Integrated climate control systems rely on specialized humidity and gas sensors concentrated among a narrow supplier base in East Asian electronics manufacturing clusters.
- Federal scheduling uncertainty:Potential rescheduling of cannabis under the Controlled Substances Act threatens to invalidate existing equipment depreciation schedules and interstate commerce assumptions embedded in capital planning.
Strategic Opportunities
- Canadian export infrastructure buildout:Licensed producers in Ontario and British Columbia are expanding curing capacity to serve international medical cannabis markets with strict stability-testing requirements.
- Good manufacturing practice alignment:FDA-adjacent quality expectations are percolating into equipment specifications, creating upgrade cycles among processors seeking pharmaceutical-adjacent certifications.
- Convergence of IoT telemetry and terpene analytics:Real-time cannabinoid degradation monitoring paired with automated climate adjustment opens subscription revenue streams for equipment vendors.
Industry Challenges
- Post-harvest technician skill scarcity:Operating precision curing environments requires training in psychrometrics and microbial management that legacy cultivation labor pools rarely possess.
- Legacy facility retrofit complexity:Installing automated curing infrastructure in existing warehouse spaces demands HVAC reconfiguration and electrical upgrades that extend commissioning timelines.
- Batch record system integration:Seed-to-sale tracking mandates require curing equipment to communicate with state compliance software, creating middleware development burdens for smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marijuana Drying and Curing Equipment Market |
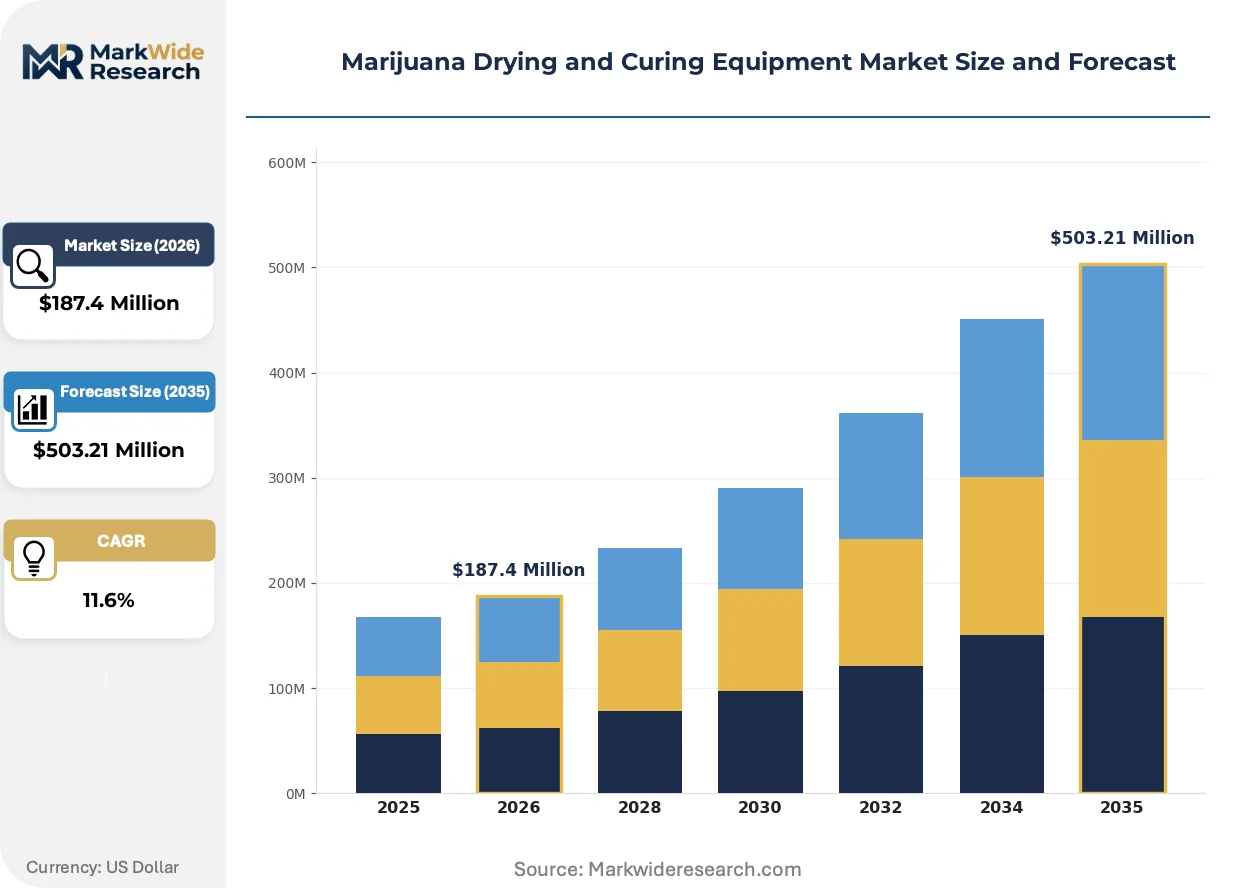
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oven, Dehumidifier, Drying Rack, Climate Control System Technology: Convection, Radiation, Freeze Drying, Vacuum Drying End User: Commercial Growers, Home Growers, Processing Facilities, Research Institutions Capacity: Small Scale, Medium Scale, Large Scale, Industrial |
| Companies Covered | Yofumo Technologies, Triminator, Cann Systems, DHydra Technologies, Darwin Chambers, Harvest Right, EnWave Corporation, HARTER, Conviron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marijuana Drying and Curing Equipment Market Emerging Trajectories
Post-harvest technology is converging around terpene preservation and data-driven quality assurance, compressing the gap between agricultural processing and pharmaceutical manufacturing standards.
Radio-frequency vacuum drying is electrifying moisture removal protocols by applying electromagnetic energy directly to water molecules rather than heating ambient air. Precision cultivators in California's Emerald Triangle are retrofitting facilities with these systems to reduce drying time from fourteen days to under seventy-two hours while preserving volatile monoterpene fractions. The structural consequence is compressing working capital cycles and reducing mold risk exposure during seasonal humidity spikes.
OSHA guidelines governing volatile organic compound exposure in cannabis processing facilities are tightening ventilation and containment specifications for curing rooms. Equipment manufacturers must now engineer negative-pressure chamber designs and activated carbon filtration integration to maintain worker safety compliance. California and Colorado processors face the steepest retrofit requirements, with multi-facility operators standardizing across their portfolios to simplify audit preparation.
Buyers are consolidating vendor relationships around full-lifecycle service contracts rather than discrete equipment purchases. Large commercial growers in Michigan and Oklahoma now demand predictive maintenance subscriptions and remote diagnostics bundled with hardware, displacing the traditional capital-expenditure-only procurement model. This shift concentrates purchasing power among integrated platform providers and squeezes standalone equipment vendors into niche trim-tool or consumables positions.
Marijuana Drying and Curing Equipment Market Segmentation
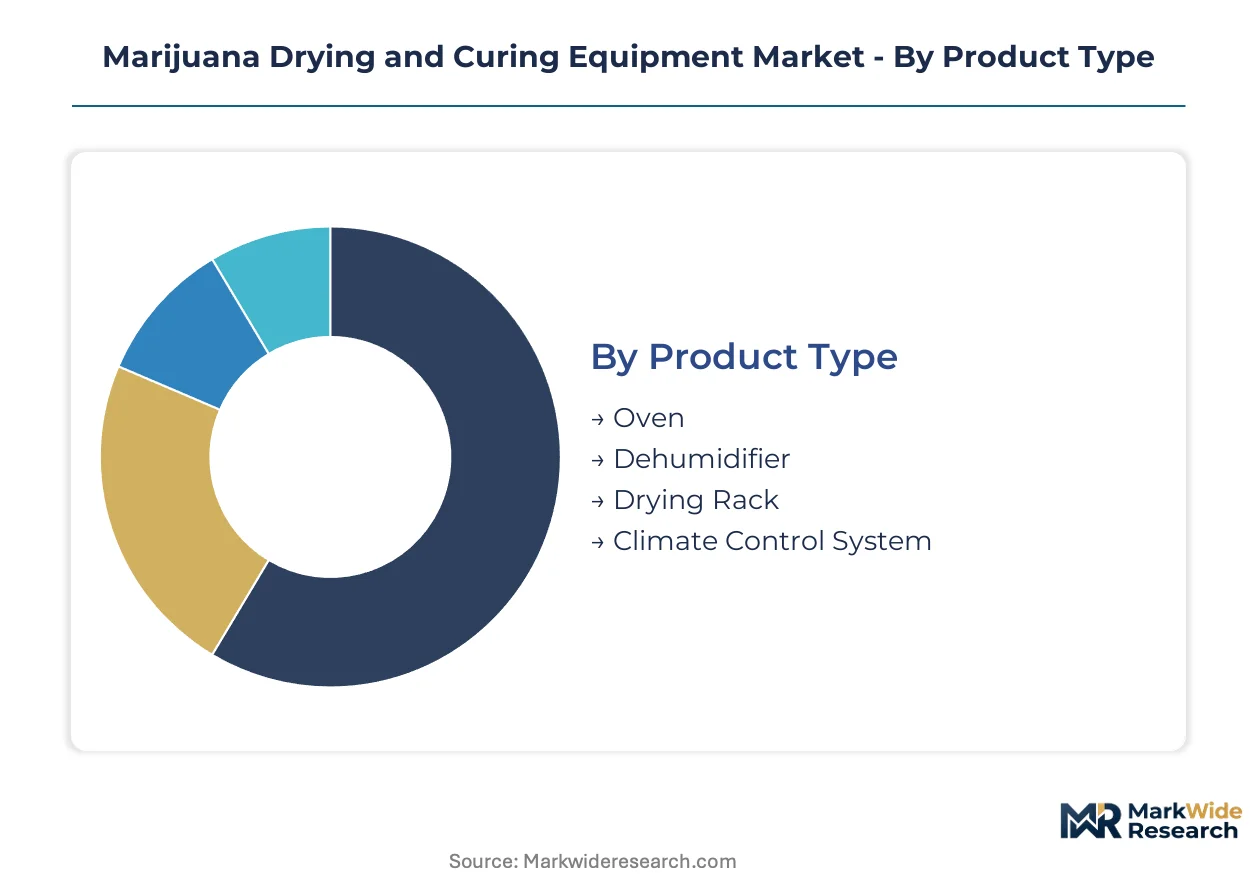
Equipment segmentation in cannabis post-harvest infrastructure reveals stark capital-intensity gradients. Procurement patterns diverge sharply between artisanal cultivators optimizing for terpene preservation and industrial operators standardizing throughput metrics across multi-facility networks.
Product Type:
Capital intensity peaks with integrated climate control systems requiring sensor arrays and software architecture, while drying racks represent minimal upfront outlay.
- Climate Control System:Encompasses programmable humidity, temperature, and airflow management with integrated telemetry for batch documentation. Demand concentrates among Colorado and California commercial cultivators facing state microbial testing mandates that legacy equipment cannot satisfy.
- Oven:Heated chamber systems applying conductive and convective energy transfer for moisture reduction. Commercial processors in Michigan and Oklahoma deploy these for standardized throughput across multi-state operator portfolios.
- Dehumidifier:Standalone moisture extraction units for ambient humidity management.
- Drying Rack:Passive suspension systems for hang-drying with minimal mechanical intervention.
Most installed capacity flows through Climate Control System. Expansion is steepest in Oven as multi-state operators consolidate procurement.
Technology:
Technology selection determines terpene retention rates and cycle time compression, with vacuum-based methods commanding premium positioning.
- Vacuum Drying:Pressure-reduced environments lower water boiling points to enable low-temperature moisture removal. Precision cultivators in California's Emerald Triangle adopt these systems to meet solventless extraction feedstock standards that convection methods fail to achieve.
- Convection:Heated air circulation through biomass remains the baseline technology. Home growers and legacy facilities in Oklahoma and Michigan retain this approach due to lower capital barriers and simpler maintenance protocols.
- Radiation:Electromagnetic energy transfer directly to water molecules.
- Freeze Drying:Sublimation-based moisture removal preserving cellular structure for premium applications.
Vacuum Drying commands the steepest price premiums. Convection retains the broadest installed base.
End User:
Customer type dictates equipment sophistication, with commercial operators driving integrated platform adoption against fragmented home-grower procurement.
- Commercial Growers:Licensed cultivators operating at scale with compliance documentation requirements. These operators in Colorado and California absorb the majority of medium-scale and large-scale deployments as state quality mandates tighten.
- Processing Facilities:Dedicated post-harvest operations serving multiple cultivation sources. Facilities in Michigan and Oklahoma standardize equipment across contract processing networks to reduce operational variance.
- Home Growers:Personal-use cultivators in jurisdictions permitting limited plant counts.
- Research Institutions:Academic and pharmaceutical laboratories studying cannabinoid stability.
Commercial Growers absorb the majority of new capacity. Processing Facilities are expanding most quickly as vertical specialization accelerates.
Capacity:
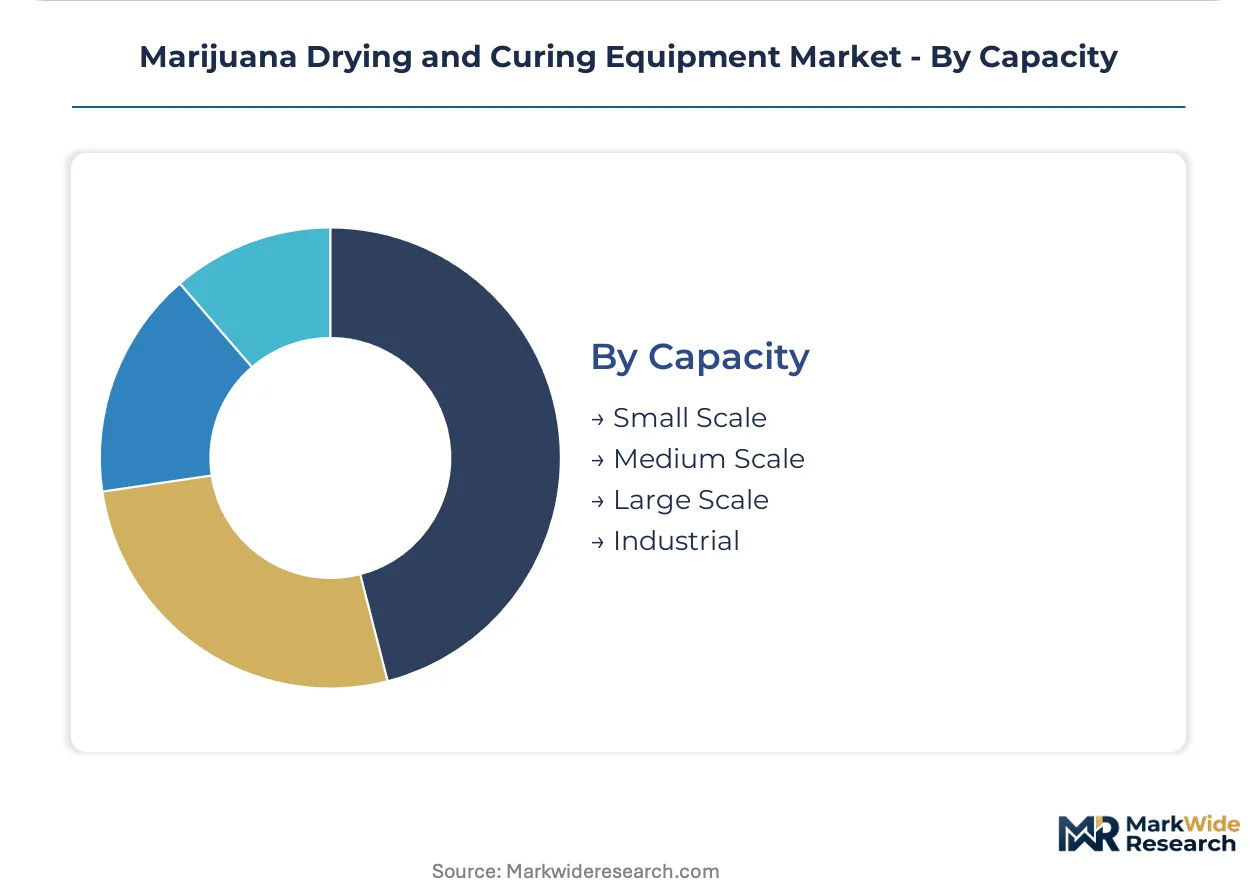
Scale tiers separate artisanal flexibility from industrial throughput, with depreciation schedules and facility retrofit costs driving selection.
- Industrial:Continuous-flow systems processing metric-ton quantities with automated loading and climate adjustment. Canadian licensed producers in Ontario and British Columbia deploy these for international medical cannabis export markets with strict stability-testing requirements.
- Large Scale:Batch systems handling hundreds of kilograms with programmable protocols. Multi-state operators across the United States standardize on this tier to balance throughput against facility retrofit complexity.
- Medium Scale:Modular units serving single-facility commercial operations.
- Small Scale:Compact systems for boutique cultivators and research applications.
Large Scale dominates current procurement volumes. Industrial is gaining share fastest as Canadian export infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Emerald Triangle anchors the highest concentration of precision curing infrastructure, with cultivators retrofitting facilities to meet solventless extraction feedstock standards that command premium positioning in regulated retail channels.
United States
Colorado and California commercial cultivators drive medium-scale and large-scale equipment deployments as state cannabis regulatory commissions enforce microbial and moisture-content testing protocols. The FDA maintains indirect influence through good manufacturing practice expectations that percolate into ancillary equipment specifications. Denver and Oakland processing clusters absorb the majority of climate control system upgrades as multi-state operators standardize post-harvest infrastructure.
Canada
Licensed producers in Ontario and British Columbia expand industrial-scale curing capacity to serve international medical cannabis markets with strict stability-testing requirements. Health Canada and PMRA oversight shapes equipment validation protocols for export-bound product streams. Toronto and Vancouver facilities deploy continuous-flow systems with automated loading to meet pharmaceutical-adjacent certification demands.
Germany
Medical cannabis importers and domestic cultivators invest in climate-controlled curing infrastructure to satisfy BfArM batch documentation requirements for pharmacy distribution. The EU Green Deal and national sustainability frameworks pressure chamber material selection toward recyclable stainless steel configurations. Berlin and Munich processing facilities lead GMP-aligned equipment procurement as the market transitions from import-dependent to domestic production.
Netherlands
Bedrocan and legacy coffee shop supply chains modernize curing protocols to align with evolving Office of Medicinal Cannabis quality mandates for standardized cannabinoid profiles. Dutch greenhouse technology expertise transfers into post-harvest climate control system design. Randstad region equipment vendors integrate IoT telemetry with seed-to-sale tracking middleware to simplify compliance documentation.
Australia
Licensed producers in Victoria and New South Wales build out curing capacity to serve domestic medical cannabis demand and emerging Asia-Pacific export opportunities. TGA stability-testing requirements dictate equipment validation protocols that exceed baseline agricultural processing standards. Melbourne and Sydney facilities adopt vacuum drying technology to compress working capital cycles and reduce seasonal mold risk exposure.
Marijuana Drying and Curing Equipment Market Vendor Landscape
Global majors compete with regional champions across technology licensing and service contract bundling, producing a tiered structure where integrated platform providers capture lifecycle revenue while standalone equipment vendors retreat into niche positions. The vendor base separates into three strategic archetypes: climate control specialists commanding software subscription margins, vacuum technology licensors extending food-processing expertise, and trim-to-cure workflow integrators reducing operational handoff friction. Capacity expansion and predictive maintenance subscription bundling dominate competitive moves as buyers consolidate vendor relationships.
Within the climate-controlled curing tier, Yofumo Technologies and Conviron occupy positions defined by integrated sensor architecture and pharmaceutical-adjacent validation protocols. Triminator anchors the workflow integration archetype, while EnWave Corporation represents vacuum technology extension from adjacent processing industries. These three exemplify divergent paths to capturing post-harvest infrastructure spending as cultivators prioritize either terpene preservation precision, operational throughput, or capital cycle compression.
| Leading Market Players |
|---|
| Yofumo Technologies |
| Triminator |
| Cann Systems |
| DHydra Technologies |
| Darwin Chambers |
| Harvest Right |
| EnWave Corporation |
| HARTER |
| Conviron |
| Others |
Supply Flow & Price Mechanics
Psychrometrics-trained technicians in Colorado's Front Range corridor command wage premiums that widen the spread between premium climate-controlled systems and basic convection units. Labor-cost differentials between specialized post-harvest operators and legacy cultivation labor pools directly feed into manufacturer pricing-tier architecture.
Pricing Analysis
Input-cost pass-through from nickel-alloy volatility governs chamber fabrication economics, with stainless steel price spikes compressing margins for premium curing system manufacturers who cannot fully transfer costs to buyers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because multi-state operators consolidate procurement around predictive maintenance subscriptions. Home growers exhibit the highest price sensitivity, while commercial cultivators in California and Colorado prioritize terpene retention metrics over upfront capital outlay.
Supply Chain Analysis
Dual-sourcing requirements for humidity and gas sensor arrays compel equipment manufacturers to qualify suppliers across South Korean, Japanese, and Taiwanese electronics manufacturing clusters. Chamber fabrication draws from Chinese stainless steel mills, German compressor specialists, and domestic HVAC component fabricators. Single-source vulnerability concentrates in specialized sensor arrays concentrated in East Asian supplier bases. Distribution runs through direct manufacturer relationships with large commercial growers, supplemented by regional equipment distributors serving boutique cultivators and retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where state-level microbial testing mandates in Colorado and California continuously force upgrade cycles among licensed cultivators.
For Market Incumbents: Hedge against federal scheduling uncertainty by diversifying revenue streams into pharmaceutical-adjacent equipment validation services. Secure backward integration into sensor array supply through partnerships with Taiwanese electronics manufacturers to reduce single-source vulnerability. Expand predictive maintenance subscription attach rates to lock in recurring revenue before capital expenditure budgets tighten.
For New Entrants and Emerging Players: Radio-frequency vacuum drying systems offer a technology-first wedge into solventless extraction feedstock supply chains where precision cultivators pay premiums for terpene preservation. Target underpenetrated processing facilities in Michigan and Oklahoma where contract processing networks lack standardized post-harvest infrastructure. Lead with terpene analytics software bundled with hardware to differentiate from established climate control vendors.
For Investors and Strategic Acquirers: Multi-state cannabis operators are the most active acquirer in this space, seeking to internalize post-harvest capabilities across facility portfolios. Long-term viability hinges on federal scheduling resolution that would unlock interstate equipment depreciation standardization and service contract portability. Monitor Health Canada export license issuance as the inflection indicator for industrial-scale capacity deployment demand.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Telemetry Platform Launch | Enables real-time cannabinoid degradation monitoring for California cultivators facing batch consistency mandates. |
| Sensor Array Backward Integration | Reduces dependency on East Asian electronics clusters for critical humidity and gas measurement components. |
| GMP Certification Pathway Investment | Aligns equipment specifications with FDA-adjacent quality expectations percolating into processor procurement criteria. |
| Predictive Maintenance Subscription Rollout | Transforms capital expenditure relationships into recurring revenue streams with Michigan and Oklahoma commercial growers. |
| Canadian Export Infrastructure Partnership | Positions industrial-scale systems for Ontario and British Columbia licensed producers serving international medical markets. |
Methodological Framework
Direct dialogue with post-harvest operations directors, cultivation facility managers, equipment procurement leads at multi-state operators, and regulatory compliance officers at state cannabis commissions grounded the qualitative foundation. Secondary validation drew from FDA guidance documents, Health Canada equipment validation protocols, OSHA ventilation standards, and SEC filings of publicly traded cannabis equipment vendors. Bottom-up demand modeling from individual facility deployments triangulated against top-down market sizing from capital expenditure disclosures across the analysis window.
Segment-level projections across technology type, capacity tier, end-user category, and regional regulatory cluster fed into the analytical framework. CAGRs were derived from equipment shipment volumes, replacement cycle assumptions, and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated state-level testing protocol adoption curves and federal scheduling scenario probabilities.
The model holds under continued state-level regulatory tightening; deviation in federal rescheduling outcomes or interstate commerce authorization would shift capital expenditure timing and equipment depreciation assumptions materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Blood Viscometer Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
Cell Culture Incubator Market
Medical Equipment
Global Medical Vacuum System Market
Medical Equipment
Blood Banking Equipment Market
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
Tissue Culture Incubator Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
Medical Automation Market
Medical Equipment
Diathermy Equipment Market
Medical Equipment
Urodynamic Equipment Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
Global Operating Table Mattresses Market