
 France Bariatric Surgery Market | 2026-2036
France Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
France Bariatric Surgery Market Foresight
CE marking under the EU Medical Device Regulation (MDR) is rotating the competitive field for implantable restriction devices and stapling systems in France. Medtronic PLC (Covidien PLC) leverages its integrated surgical stapling portfolio to anchor high-volume gastric bypass procedures in academic medical centers. Johnson & Johnson (Ethicon Inc) sustains market presence through specialized energy devices and suture portfolios calibrated for bariatric anatomy. Peters Surgical competes on cost-efficient instrumentation bundles tailored to public hospital procurement frameworks.
Bariatric surgery comprises metabolic and gastrointestinal surgical interventions designed to induce weight loss through gastric restriction, malabsorption, or combined mechanisms, typically requiring stapling devices, adjustable bands, or anastomotic configurations with specific pressure tolerance parameters and biocompatibility grades for prolonged implantation. Sleeve gastrectomy now dominates procedure volumes in France due to its relative technical simplicity and durable metabolic outcomes compared to adjustable gastric banding, which has matured into a declining replacement-maintenance segment with compressed margins. Specialty clinics capture disproportionate margin pools by concentrating high-throughout bariatric programs with dedicated nursing protocols, while academic medical centers anchor complex revisional and adolescent cases requiring multidisciplinary coordination.
ANSM (Agence Nationale de Sécurité du Médicament) enforces post-market surveillance obligations for implantable bariatric devices, compelling manufacturers to maintain France-specific vigilance databases that elevate compliance costs for smaller entrants. The EU MDR transition extends conformity assessment timelines for legacy devices, temporarily constraining product line refreshes while favoring firms with notified body relationships and robust quality management systems. Stakeholders must monitor HAS reimbursement re-evaluation cycles for emerging endoscopic bariatric procedures, as coverage expansion or restriction will redirect capital flows between invasive surgical platforms and minimally invasive alternatives.
Market Dynamics
HAS reimbursement re-evaluation cycles for sleeve gastrectomy and gastric bypass are redirecting capital flows between academic medical centers and private specialty clinics across Île-de-France, compressing margins for providers unable to demonstrate durable metabolic outcomes.
Growth Catalysts
- Metabolic disease burden:Rising type 2 diabetes prevalence among adult females in the Paris region is expanding HAS-eligible candidate pools for metabolic intervention procedures.
- EU MDR harmonization:CE marking standardization under the Medical Device Regulation is consolidating quality benchmarks for implantable restriction devices across French procurement frameworks.
- Post-operative care infrastructure:Dedicated nursing protocols in Île-de-France specialty clinics are reducing 30-day readmission rates and attracting cross-regional patient flows.
Market Restraints
- Notified body bottlenecks:EU MDR transition timelines for legacy device recertification are extending conformity assessment periods beyond 18 months for stapling system manufacturers.
- Adjustable gastric banding decline:Technical complexity and inferior long-term weight maintenance are relegating banding procedures to replacement-maintenance segments with compressed reimbursement rates.
- ANSM vigilance costs:Post-market surveillance obligations for implantable devices require France-specific adverse event databases that elevate compliance expenditures disproportionately for smaller instrumentation suppliers.
Strategic Opportunities
- Endoscopic bariatric alternatives:Intragastric balloons and endoscopic sleeve gastroplasty await HAS coverage determination, with expansion redirecting volume from invasive surgical platforms.
- Revisional surgery specialization:Academic medical centers in Lyon and Marseille can anchor complex revision cases requiring multidisciplinary coordination beyond primary bariatric capacity.
- Public hospital procurement bundles:Cost-efficient instrumentation packages tailored to HAS framework agreements offer penetration pathways outside Paris-region private clinic concentration.
Industry Challenges
- Bariatric surgeon scarcity:Fellowship-trained specialists concentrate in Île-de-France, limiting program expansion in Auvergne-Rhône-Alpes and Occitania regions where demand growth exceeds supply.
- Multidisciplinary coordination complexity:Adolescent and super-obese cases require endocrinology, psychiatry, and anesthesia integration that stretches operational bandwidth beyond standalone surgical capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Bariatric Surgery Market |
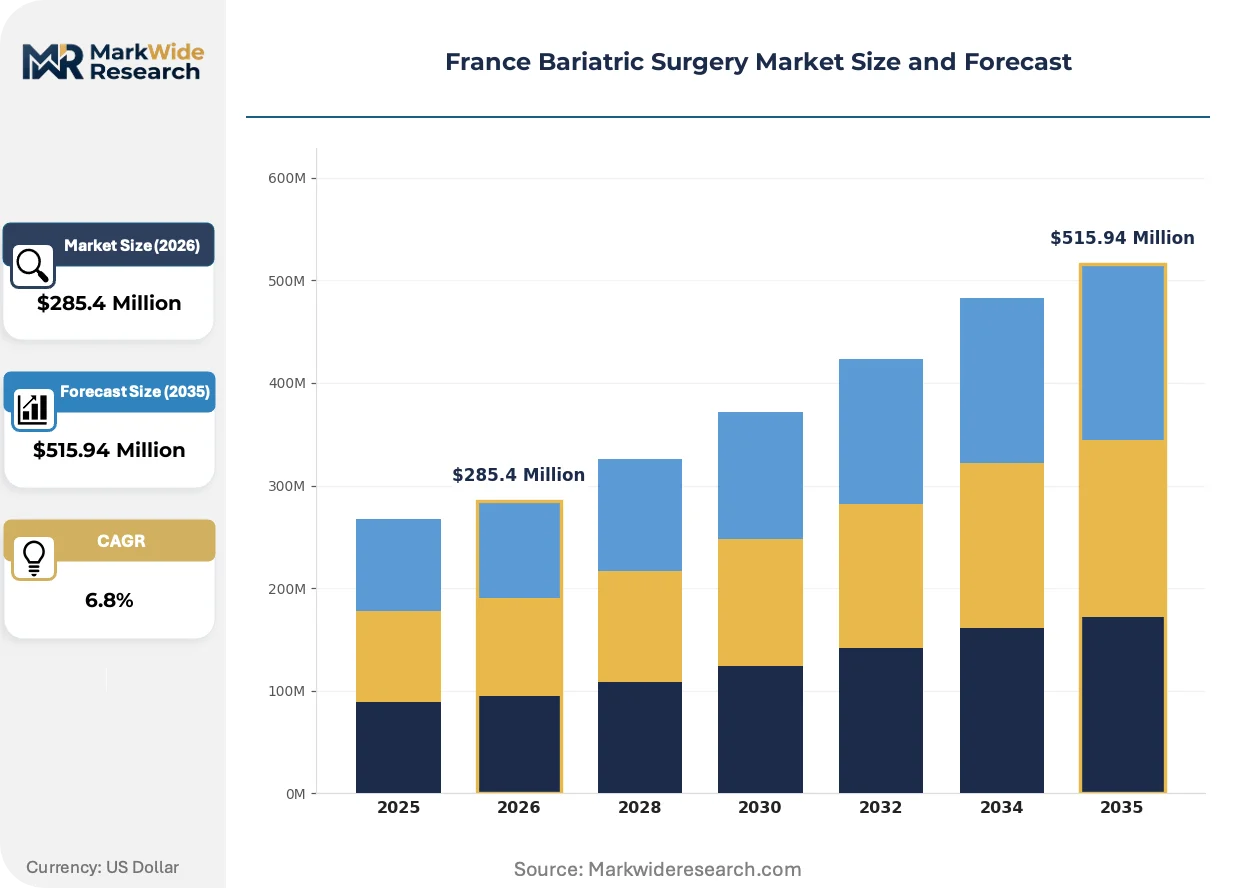
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Banding, Biliopancreatic Diversion Patient Demographic: Adult Females, Adult Males, Adolescents, Geriatric Patients Facility Type: Specialty Clinics, Ambulatory Surgery Centers, Private Hospitals, Academic Medical Centers Payment Method: Public Insurance, Private Insurance, Out-of-Pocket, Employer-Sponsored Programs |
| Companies Covered | Apollo Endosurgery Inc, Johnson & Johnson (Ethicon Inc), Conmed Corporation, Medtronic PLC (Covidien PLC), B. Braun SE, Stryker, Peters Surgical, Olympus Corporation, TransEnterix Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Bariatric Surgery Market Shifts & Advancements
Surgical stapling technology and energy-based vessel sealing systems are actively reshaping procedural economics in French bariatric centers, with device selection increasingly tied to bundled payment outcomes rather than standalone capital cost.
Robotic-assisted stapling platforms are bifurcating the high-volume gastric bypass segment in France. Academic medical centers in Paris and Lyon are adopting these systems for complex anastomotic configurations, while private specialty clinics retain conventional laparoscopic instrumentation. This divergence is compressing margin pools for mid-tier mechanical stapling suppliers unable to serve both installation bases.
EU MDR Article 120 transitional provisions are extending legacy device market access timelines for stapling cartridges and adjustable bands already holding valid CE certificates. French manufacturers with established notified body relationships are accelerating product line refreshes, while competitors lacking robust quality management systems face portfolio gaps. ANSM enforcement of vigilance reporting obligations is elevating post-market clinical follow-up requirements specifically for gastric bypass staple line complications.
Patient self-referral patterns are fragmenting traditional primary care gatekeeping in French bariatric access. Direct-to-clinic scheduling through dedicated obesity management platforms is displacing endocrinologist-mediated pathways in Île-de-France and Provence-Alpes-Côte d'Azur. This channel shift concentrates volume with marketing-capable private providers and reduces public hospital capture rates for initial consultations.
France Bariatric Surgery Market Segmentation
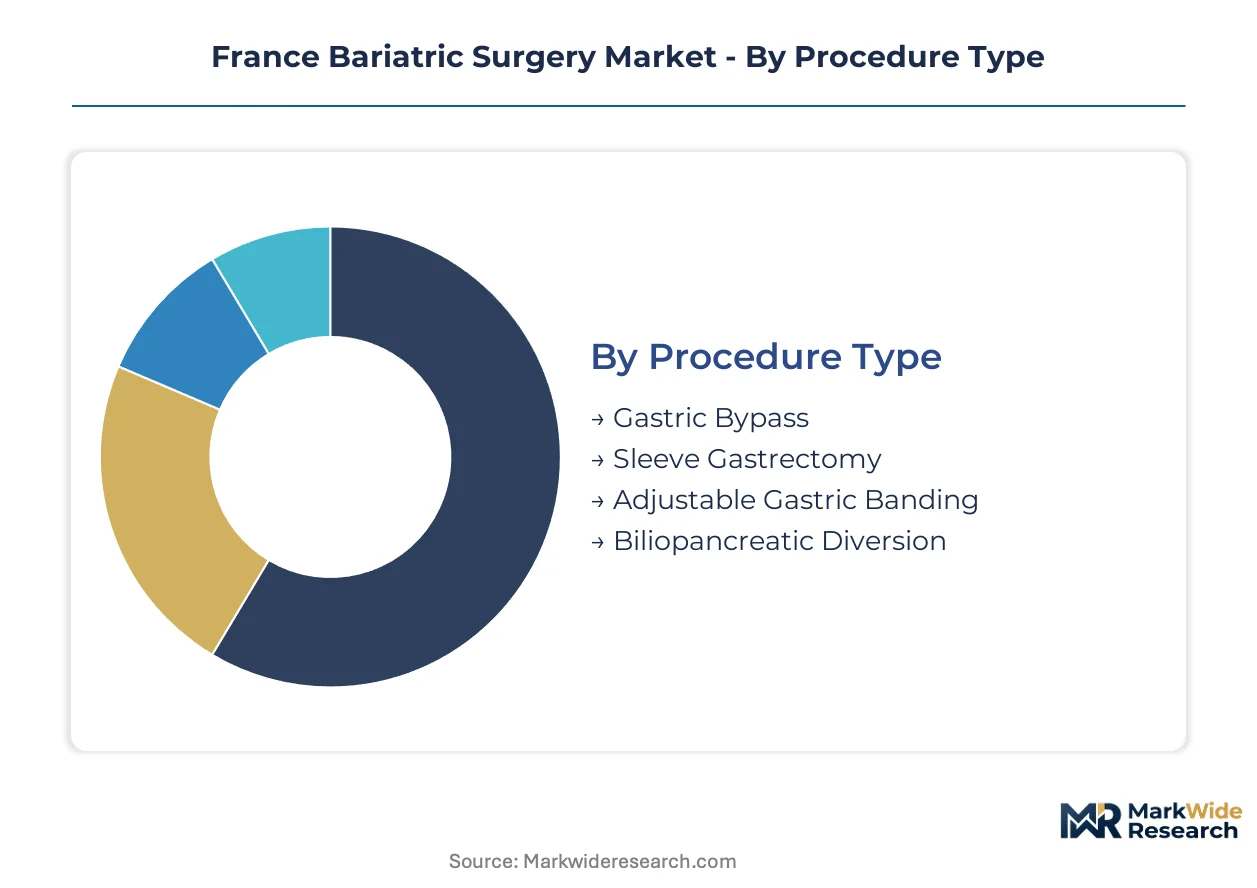
Segmentation in French bariatric surgery reveals how HAS reimbursement eligibility, regional surgeon concentration, and facility infrastructure allocate patient flows across procedure types and care settings. Understanding these partitions clarifies where capital investments concentrate and which access pathways dominate metabolic intervention delivery.
Procedure Type:
Endoscopic alternatives and pharmacological weight management are exerting substitution pressure on invasive surgical volumes, with each traditional procedure facing distinct displacement risk from minimally invasive platforms awaiting HAS coverage determination.
- Sleeve Gastrectomy:Partial gastric resection creating a tubular stomach pouch through stapling along the greater curvature, requiring 60-80 mL residual volume calibration. Demand concentrates in Île-de-France specialty clinics where dedicated nursing protocols and high surgeon throughput enable standardized 45-minute operative times. HAS reimbursement stability and technical reproducibility sustain its position as the default first-line metabolic intervention.
- Gastric Bypass:Roux-en-Y configuration establishing 15-30 mL gastric pouch with 75-150 cm Roux limb and biliopancreatic diversion of 30-50 cm common channel. Academic medical centers in Paris and Lyon anchor complex cases requiring anastomotic precision, while private hospitals expand capacity for straightforward presentations. Robotic-assisted stapling platforms are bifurcating installation bases between high-complexity centers and conventional laparoscopic sites.
- Adjustable Gastric Banding:Silicone inflatable restriction device with 10-14 cm circumference and 4-10 mL fill volume range, now relegated to replacement-maintenance segment.
- Biliopancreatic Diversion:Malabsorptive-extensive procedure with 50-100 cm common channel preservation, reserved for super-obese cases in tertiary referral centers.
Sleeve gastrectomy retains volume leadership; biliopancreatic diversion holds the steepest expansion curve among invasive procedures as super-obese candidacy expands.
Patient Demographic:
Metabolic disease burden distribution and HAS eligibility criteria create divergent demand profiles across age and gender cohorts, with adult females commanding disproportionate program investment due to diabetes prevalence patterns in the Paris region.
- Adult Females:Primary candidate pool for sleeve gastrectomy and gastric bypass, driving Île-de-France clinic expansion and dedicated post-operative care infrastructure development.
- Adult Males:Emerging segment with cardiovascular comorbidity profiles favoring metabolic intervention, concentrated in employer-sponsored screening programs.
- Adolescents:Multidisciplinary coordination requirement involving endocrinology, psychiatry, and anesthesia integration stretches operational bandwidth beyond standalone surgical capacity.
- Geriatric Patients:Revisional and complication-management focus in academic medical centers with anesthesia risk stratification protocols.
Adult females anchor current volume; adolescents are gaining share fastest as HAS evaluates expanded eligibility criteria for metabolic intervention in younger populations.
Facility Type:
Capital intensity and reimbursement rate differentials stratify the provider landscape, with private specialty clinics capturing margin pools through dedicated high-throughput programs while public hospitals face procurement constraint pressures.
- Specialty Clinics:Concentrated bariatric programs with dedicated nursing protocols and standardized post-operative pathways, capturing cross-regional patient flows through direct-to-clinic scheduling platforms.
- Private Hospitals:Expanding bariatric capacity in the Paris region with integrated metabolic surgery units and HAS framework agreement compliance.
- Academic Medical Centers:Complex revisional, adolescent, and super-obese case anchoring with multidisciplinary coordination requirements and robotic-assisted platform adoption.
- Ambulatory Surgery Centers:Limited penetration due to HAS reimbursement restrictions on overnight stay requirements and complication management protocols.
Specialty clinics dominate volume concentration; academic medical centers are expanding most quickly through revisional surgery specialization and robotic platform installation.
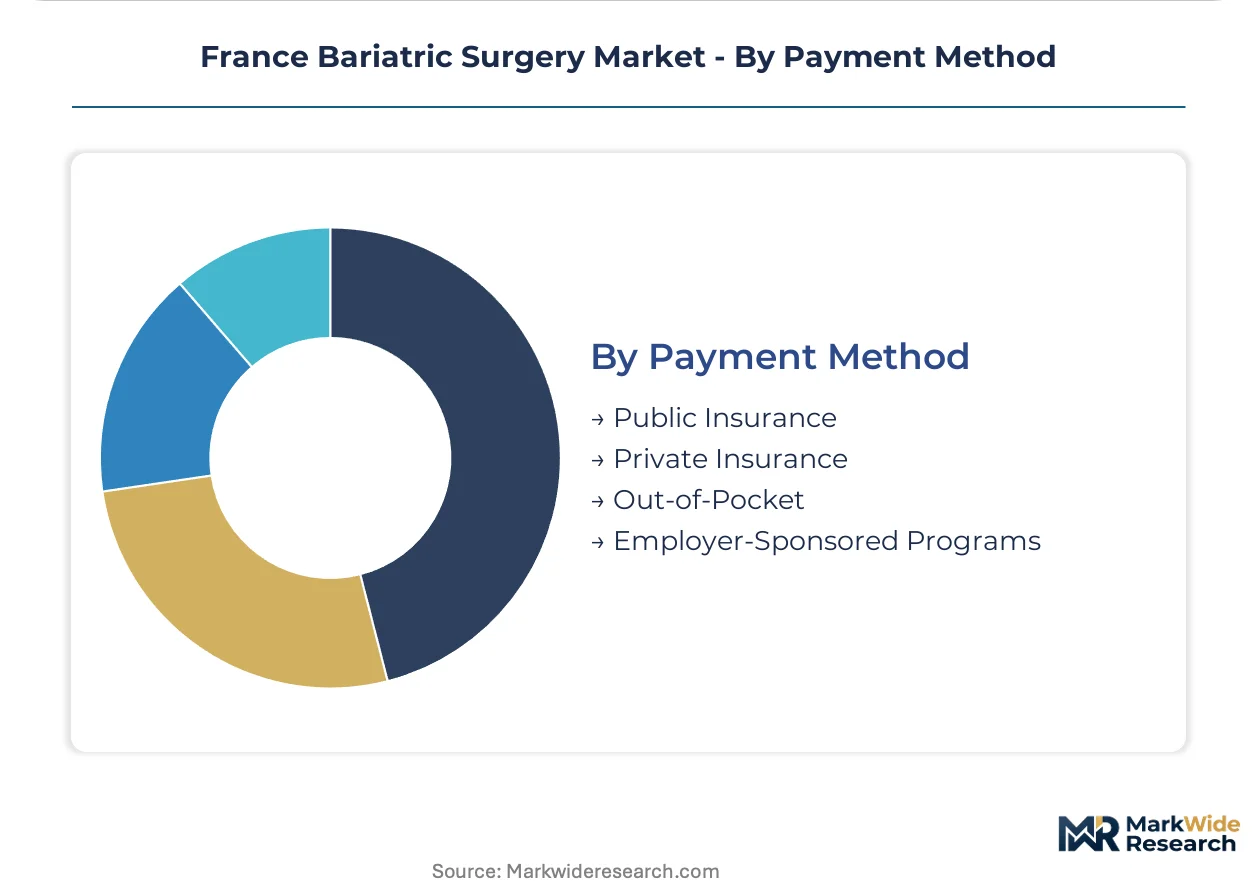
Payment Method:
Reimbursement pathway fragmentation is redirecting patient flows between public hospital capture and private clinic self-referral channels, with coverage determination timelines creating access delays that alter provider selection behavior.
- Public Insurance:HAS framework agreement coverage for eligible candidates, requiring endocrinologist-mediated pathways and standardized pre-operative evaluation protocols.
- Private Insurance:Supplementary coverage enabling expedited scheduling and facility selection outside public hospital queues.
- Out-of-Pocket:Direct-to-clinic payment for non-HAS-eligible candidates or accelerated access, concentrated in Île-de-France private specialty clinics.
- Employer-Sponsored Programs:Emerging channel through occupational health screening and metabolic disease management initiatives.
Public insurance retains volume leadership; employer-sponsored programs are climbing the fastest as workplace wellness initiatives expand metabolic intervention coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HAS reimbursement frameworks and regional surgeon concentration patterns are redistributing bariatric procedure volumes across French metropolitan areas and peripheral regions. Public hospital procurement constraints and private clinic expansion incentives create divergent infrastructure investment trajectories.
Île-de-France
Adult female diabetes prevalence and employer-sponsored screening programs are expanding HAS-eligible candidate pools in the Paris region. ANSM vigilance reporting obligations for implantable devices shape post-market surveillance investments by manufacturers serving this concentration. Private specialty clinics in Paris and its inner suburbs anchor high-throughput bariatric programs with dedicated nursing protocols that draw cross-regional patient flows.
Auvergne-Rhône-Alpes
Metabolic disease burden among working-age populations is elevating demand for sleeve gastrectomy and gastric bypass procedures in Lyon and Grenoble. HAS framework agreement compliance requirements filter provider participation in public insurance reimbursement pathways. Academic medical centers in Lyon specialize in complex revisional cases requiring multidisciplinary coordination beyond primary bariatric capacity.
Provence-Alpes-Côte d'Azur
Direct-to-clinic scheduling platforms are fragmenting traditional primary care gatekeeping in Marseille and Nice, concentrating volume with marketing-capable private providers. EU MDR Article 120 transitional provisions extend legacy device market access for stapling systems used in regional hospital networks. Robotic-assisted platform adoption in Marseille academic centers bifurcates the high-complexity gastric bypass segment from conventional laparoscopic sites.
Occitanie
Bariatric surgeon scarcity relative to demand growth is limiting program expansion in Toulouse and Montpellier compared to Paris-region saturation. Public hospital procurement bundles tailored to HAS framework agreements offer cost-efficient instrumentation penetration pathways outside private clinic concentration zones. Post-operative care infrastructure gaps constrain 30-day readmission rate performance versus Île-de-France benchmarks.
Hauts-de-France
Adjustable gastric banding replacement-maintenance procedures concentrate in Lille and regional centers where legacy device populations require ongoing surveillance. ANSM enforcement of post-market clinical follow-up for gastric bypass staple line complications elevates compliance expenditures for regional hospital suppliers. Employer-sponsored metabolic intervention programs remain underdeveloped relative to southern and eastern regions.
France Bariatric Surgery Market Competitive Landscape
Player mix skews toward diversified surgical technology conglomerates with integrated stapling and energy device portfolios. Market structure concentrates around three to five entities with notified body relationships and robust quality management systems capable of navigating EU MDR transition timelines. Strategic archetypes include full-stack surgical platform providers, cost-efficient instrumentation bundlers, and specialized implantable device manufacturers. Competitive moves center on portfolio diversification into robotic-assisted platforms and geographic expansion through academic medical center anchoring.
Among diversified surgical technology conglomerates, Medtronic PLC (Covidien PLC) and Johnson & Johnson (Ethicon Inc) occupy positions reflecting integrated portfolio breadth across stapling systems and energy devices. Peters Surgical represents the cost-efficient instrumentation archetype tailored to public hospital procurement frameworks. Apollo Endosurgery Inc exemplifies specialized implantable device positioning within endoscopic bariatric alternatives awaiting HAS coverage determination. Stryker and B. Braun SE sit within the mid-tier mechanical and suture instrumentation segment serving conventional laparoscopic installation bases.
| Leading Market Players |
|---|
| Apollo Endosurgery Inc |
| Johnson & Johnson (Ethicon Inc) |
| Conmed Corporation |
| Medtronic PLC (Covidien PLC) |
| B. Braun SE |
| Stryker |
| Peters Surgical |
| Olympus Corporation |
| TransEnterix Inc |
| Others |
Supply & Pricing Matrix
Eighteen-month CE marking recertification timelines for legacy stapling systems concentrate procurement leverage with academic medical centers and high-volume private clinics in Île-de-France, compressing margin pools for mid-tier suppliers while amplifying pricing power for notified body-anchored manufacturers with robust quality management systems.
Pricing Analysis
Certification level under EU MDR Article 120 transitional provisions creates the primary spread between premium robotic-assisted stapling platforms and conventional laparoscopic instrumentation bundles. Three-tier pricing structure across premium, standard, and economy levels stratifies by surgeon throughput volume and post-operative care infrastructure investment. Cost compression in standard mechanical stapling tiers intensifies as public hospital procurement frameworks prioritize HAS framework agreement compliance over feature differentiation. Private specialty clinics demonstrate lowest price sensitivity due to cross-regional patient flow capture, while ambulatory surgery centers face acute budget constraints from overnight stay reimbursement restrictions.
Supply Chain Analysis
Notified body capacity bottlenecks in Germany and the Netherlands constrain conformity assessment throughput for implantable restriction devices and energy-based vessel sealing systems entering French distribution channels. Manufacturing concentration for surgical stapling cartridges rests on precision metal stamping from Switzerland and polymer molding from Germany, with sterilization validation services concentrated in Belgium and Ireland. Single-source vulnerability in titanium alloy feedstock for anastomotic staples elevates exposure to commodity price volatility from aerospace sector demand competition. Distribution runs through hospital procurement consortiums and GPO contracts rather than direct manufacturer-to-facility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France bariatric surgery sits in early-cycle expansion as HAS evaluates expanded eligibility criteria for adolescent metabolic intervention and endoscopic alternatives await coverage determination, with patient self-referral patterns fragmenting traditional primary care gatekeeping.
For Market Incumbents: Shield high-volume gastric bypass positions in academic medical centers by accelerating robotic-assisted platform refresh cycles ahead of EU MDR legacy device expiration timelines. Deepen backward integration into energy-based vessel sealing technology to capture margin pools from conventional mechanical stapling commoditization. Prioritize ANSM vigilance database infrastructure investment to sustain post-market surveillance compliance cost advantages over smaller instrumentation entrants. For New Entrants and Emerging Players: Lead with endoscopic bariatric alternatives positioned for HAS coverage expansion, targeting private specialty clinics in Provence-Alpes-Côte d'Azur where direct-to-clinic scheduling platforms concentrate patient acquisition leverage. Occitanie presents the most penetrable geography given bariatric surgeon scarcity relative to demand growth and underdeveloped post-operative care infrastructure. Anchor go-to-market strategy through employer-sponsored metabolic intervention program partnerships rather than public hospital procurement queues. For Investors and Strategic Acquirers: Long-term, this sits as a reimbursement-expansion play because HAS re-evaluation cycles for sleeve gastrectomy and emerging endoscopic procedures will redirect capital flows between invasive surgical platforms and minimally invasive alternatives across the analysis window. Acquisition targets should cluster around specialized implantable device manufacturers with notified body relationships and robust quality management systems capable of navigating EU MDR transition timelines. Monitor ANSM post-market surveillance enforcement intensity as the inflection signal for compliance cost barriers elevating market concentration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 120 transitional provisions extend legacy device access while favoring notified body-anchored manufacturers with robust quality management systems. |
| Hospital System Partnership | Academic medical center anchoring in Lyon and Marseille captures complex revisional cases requiring multidisciplinary coordination beyond primary bariatric capacity. |
| Reimbursement Strategy | HAS framework agreement compliance filters provider participation in public insurance pathways and shapes procurement bundle specifications. |
| Software Companion Development | Direct-to-clinic scheduling platforms displace endocrinologist-mediated access pathways in Île-de-France and Provence-Alpes-Côte d'Azur. |
| Backward Integration | In-house production of energy-based vessel sealing systems captures margin pools from conventional mechanical stapling commoditization. |
Research Methodology
Initial hypotheses were tested against primary input from bariatric surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation against ANSM vigilance databases, HAS reimbursement framework documentation, EU MDR regulatory filings, and hospital procurement records. Bottom-up procedure volume estimates triangulated with top-down market sizing across facility type and procedure type segmentation dimensions.
Variance decomposition across the projection horizon isolates volume drivers from pricing dynamics and regulatory shift impacts. Segmentation dimensions modeled include procedure type, patient demographic, facility type, and payment method, with regional surgeon concentration and HAS eligibility criteria as industry-specific forecast inputs. CAGRs derived from procedure volume trajectory analysis and reimbursement rate stability assumptions.
The analysis sits within stated boundaries; outcomes outside HAS coverage determination timelines, EU MDR recertification completion rates, or ANSM enforcement intensity would require recalibration. Practitioners should keep alternative scenarios live as adolescent eligibility expansion and endoscopic alternative reimbursement decisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Bariatric Medical Chairs Market
Bariatric Surgery
Mexico Bariatric Surgery Market
Bariatric Surgery
China Bariatric Surgery Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Devices Market
Bariatric Surgery
Bariatric Surgery Devices Market
Bariatric Surgery
United Kingdom Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
Bariatric Lifts Market
Bariatric Surgery
UAE Bariatric Surgery Market
Bariatric Surgery
Bariatric Patient Room Market
Bariatric Surgery
Global Bariatric Walking Aids Market
Bariatric Surgery
Canada Bariatric Surgery Market
Bariatric Surgery
Spain Bariatric Surgery Market
Bariatric Surgery
Chile Bariatric Surgery Market
Bariatric Surgery
Bariatric Walkers Market