
 RFID Blood Refrigerators and Freezers Market | 2026-2036
RFID Blood Refrigerators and Freezers Market Size, Share, and Industry Trends Forecast 2026-2036
RFID Blood Refrigerators and Freezers Market Intelligence
China is fragmenting the RFID blood refrigerator supply base as domestic manufacturers scale cold chain output for Asia-Pacific hospital networks. Helmer Scientific leverages its North American service infrastructure to sustain long-term contracts with regional blood centers. Thermo Fisher Scientific anchors its position through deep R&D investment in ultra-low temperature telemetry systems. B Medical Systems competes aggressively on energy efficiency ratings across European procurement tenders.
RFID blood refrigerators and freezers are temperature-controlled storage systems integrating radio-frequency identification tags, antenna arrays, and cloud-connected monitoring software to track individual blood unit location, temperature history, and expiration status in real time. These systems maintain precise thermal envelopes between two degrees Celsius and negative eighty degrees Celsius while logging chain-of-custody data required for patient safety protocols. Refrigerators dominate current procurement volumes among hospitals and blood banks due to higher platelet and red cell inventory turnover, while ultra-low temperature freezers capture concentrated margin pools from rare plasma and cryoprecipitate storage in research laboratories. RFID active systems lead technology adoption where real-time alerts justify premium hardware costs, though passive systems extend into cost-sensitive diagnostic centers through simpler gateway installations.
FDA 21 CFR Part 11 electronic record requirements and EU MDR traceability mandates shape product development roadmaps by forcing validated software architectures and audit-ready temperature logs. Health Canada and Japan's PMDA impose parallel cold chain documentation standards that manufacturers must navigate for market access across major jurisdictions. Stakeholders should monitor evolving interoperability standards between RFID blood tracking platforms and hospital enterprise resource planning systems to avoid stranded equipment investments.
Market Dynamics
Hospital blood banks are consolidating vendor relationships around integrated cold chain platforms that unify temperature telemetry, RFID tracking, and enterprise resource planning connectivity into single procurement contracts. This consolidation favors manufacturers with validated software architectures capable of satisfying FDA 21 CFR Part 11 and EU MDR audit requirements without custom integration work.
Growth Catalysts
- FDA 21 CFR Part 11 compliance mandates:Electronic record validation requirements are forcing blood centers to replace legacy manual logging systems with automated RFID-enabled cold storage, creating replacement demand across US hospital networks.
- Platelet inventory turnover velocity:Higher transfusion volumes among aging populations in Germany and Japan are expanding refrigerator procurement for short-shelf-life blood components.
- Ultra-low temperature telemetry:Research laboratories storing cryoprecipitate and rare plasma are adopting active RFID systems for real-time alerts during freezer door events.
Market Restraints
- Stainless steel and semiconductor input volatility:Refrigeration compressor controllers and RFID reader chipsets face supply concentration risks from East Asian foundry capacity.
- Passive RFID range limitations:Metal-dense hospital environments degrade signal reliability, forcing redundant antenna installations that inflate hardware costs.
- EU MDR conformity assessment timelines:Extended notified body review periods for software-validated medical devices delay product launches by 12-18 months.
Strategic Opportunities
- Diagnostic center gateway installations:Smaller blood testing facilities in India represent underpenetrated demand for simplified passive RFID systems without full cold chain telemetry.
- ISO 13485 certification acceleration:Medical device quality management standardization is opening tender access for qualified suppliers across Middle Eastern hospital privatization programs.
- Cloud-native ERP convergence:RFID blood tracking platforms are hybridizing with SAP and Oracle health system modules to create unified inventory visibility.
Industry Challenges
- Biomedical engineering talent scarcity:Hospitals lack personnel capable of calibrating RFID antenna arrays and resolving electromagnetic interference in retrofit installations.
- Legacy LIS integration complexity:Blood bank laboratory information systems require custom middleware development to ingest RFID timestamp data without workflow disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RFID Blood Refrigerators and Freezers Market |
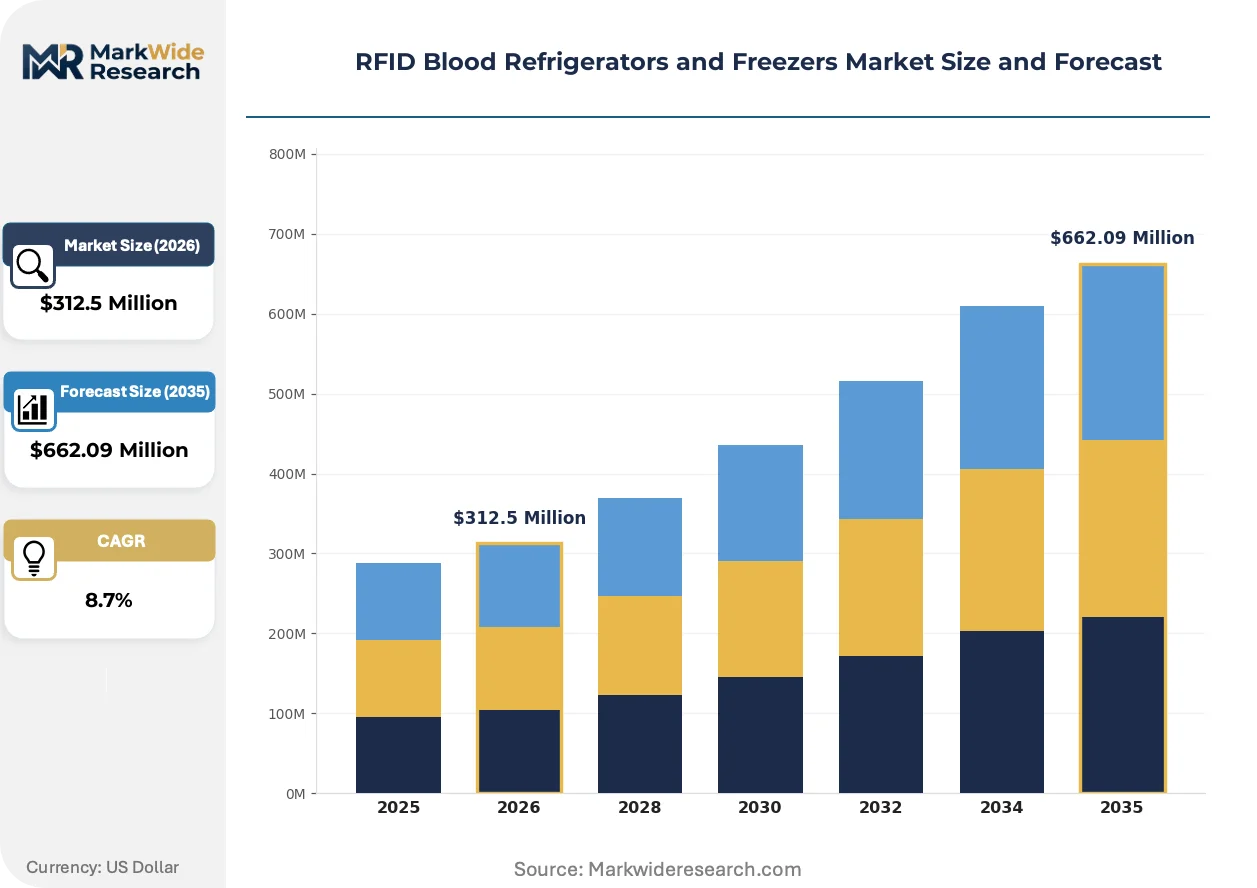
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Freezers, Combination Units, Ultra-Low Temperature Freezers Technology: RFID Active Systems, RFID Passive Systems, Wireless Monitoring, Smart Sensors End User: Hospitals, Blood Banks, Research Laboratories, Diagnostic Centers Installation: On-premise, Mobile Units, Centralized Systems, Modular Installations |
| Companies Covered | Helmer Scientific, Thermo Fisher Scientific, B Medical Systems, Angelantoni Life Science, Haier Biomedical, PHC Holdings Corporation, Philips, Terso Solutions, Arctiko A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RFID Blood Refrigerators and Freezers Market Strategic Shifts & Innovations
RFID blood cold chain infrastructure is converging with hospital digital transformation programs, embedding storage equipment within broader enterprise asset management architectures rather than operating as isolated temperature monitoring silos.
Active RFID sensor networks are hybridizing with Bluetooth Low Energy beacons to create redundant location tracking for high-value plasma units. Regional blood centers in Texas and California are piloting these dual-protocol installations to eliminate signal dead zones during emergency inventory relocations. The technology is hybridizing hardware procurement decisions by forcing buyers to evaluate interoperability with existing real-time location system investments rather than selecting cold storage on thermal performance alone.
EU MDR traceability mandates are compressing software development roadmaps for European market access. Manufacturers must deploy validated electronic record architectures with audit-ready temperature logs and chain-of-custody documentation. Blood bank operators in France and the Netherlands are prioritizing vendors with pre-certified quality management systems to accelerate procurement timelines.
Consolidated procurement through group purchasing organizations is displacing standalone equipment tenders among US hospital networks. Blood centers affiliated with multi-state health systems are negotiating enterprise-wide cold storage contracts that bundle RFID-enabled refrigerators, freezers, and multi-year service agreements. This concentration is most visible in the Southeast, where regional purchasing cooperatives dominate capital equipment allocation for transfusion services.
RFID Blood Refrigerators and Freezers Market Segmentation
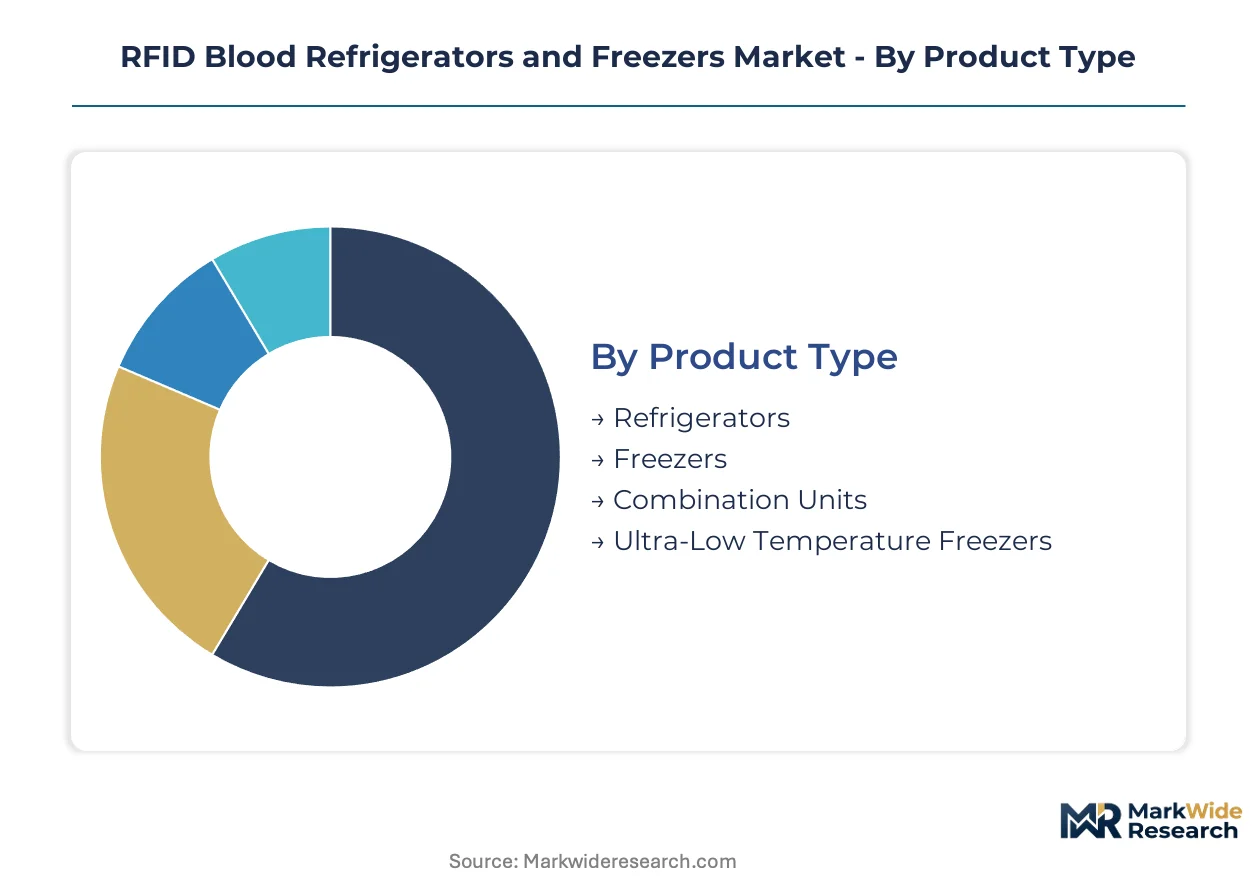
Segmentation in RFID blood cold chain equipment reveals divergent procurement rhythms across product lifecycles and technology maturity curves. Hospital capital committees weight inventory velocity against compliance architecture when allocating budgets across refrigerator and freezer categories.
Product Type:
Cycle times vary dramatically from platelet refrigerators turning inventory every five days to plasma freezers holding units for months or years.
- Refrigerators:These units maintain two to six degrees Celsius for red blood cells and platelets with shelf lives under forty-two days. Hospital blood banks in the United States and Germany prioritize these for highest-turnover components, driving procurement volume through replacement of legacy manual-logging units under FDA and EU MDR compliance pressure.
- Freezers:Standard plasma freezers operate at negative thirty degrees Celsius for frozen components with multi-year stability. Blood centers concentrate expansion here for rare plasma inventory buffering, though lower turnover extends replacement cycles versus refrigerator fleets.
- Combination Units:Dual-temperature cabinets serving mixed component storage in smaller facilities.
- Ultra-Low Temperature Freezers:Cryogenic systems at negative eighty degrees Celsius for cryoprecipitate and research specimens.
Refrigerators dominate installed base. Ultra-low temperature freezers are where expansion concentrates for research laboratory and rare plasma applications.
Technology:
Cost tiers separate premium active systems from gateway-dependent passive installations across hospital network budget strata.
- RFID Active Systems:Battery-powered tags transmit real-time location and temperature data continuously through mesh networks. Research laboratories storing high-value cryoprecipitate in Texas and California health systems justify premium hardware costs through elimination of cold chain excursion risks during emergency inventory relocations.
- RFID Passive Systems:Reader-activated tags without onboard power reduce per-unit hardware expense for diagnostic centers. India's expanding blood testing facility network adopts these for simplified gateway installations without full telemetry infrastructure.
- Wireless Monitoring:Wi-Fi or cellular-connected temperature loggers without RFID location tracking.
- Smart Sensors:Integrated environmental probes with cloud connectivity for predictive maintenance alerts.
RFID active systems anchor premium hospital contracts. RFID passive systems are climbing the fastest in diagnostic center penetration.
End User:
Application criticality shapes validation requirements from transfusion-ready patient safety to research-grade specimen preservation.
- Hospitals:Transfusion services demand validated software architectures satisfying FDA 21 CFR Part 11 and EU MDR audit trails for every unit administered to patients. Southeast US health systems are consolidating procurement through regional purchasing cooperatives for enterprise-wide cold storage standardization.
- Blood Banks:Regional collection centers require chain-of-custody documentation from donation through distribution.
- Research Laboratories:Academic and pharmaceutical facilities storing cryoprecipitate for clinical trials prioritize ultra-low temperature telemetry with redundant alert pathways.
- Diagnostic Centers:Smaller testing facilities prioritize capital efficiency over comprehensive cold chain documentation.
Hospitals command the largest equipment budgets. Research laboratories are gaining share fastest in ultra-low temperature freezer procurement.
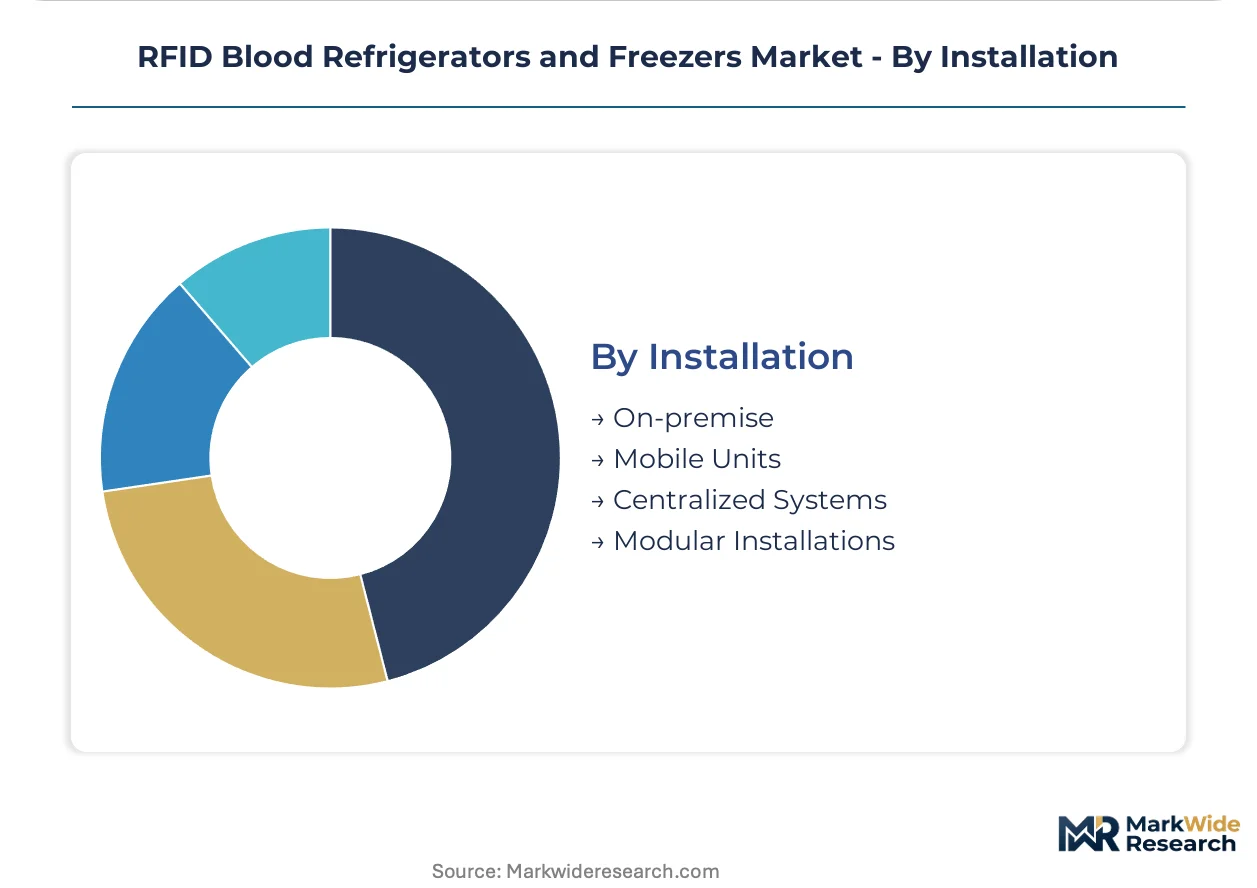
Installation:
Volume concentration favors fixed infrastructure while mobility addresses emergency response and field collection scenarios.
- On-premise:Permanent installations in hospital transfusion services and blood bank processing facilities constitute the procurement majority. France and Netherlands operators prioritize vendors with pre-certified quality management systems to accelerate deployment timelines under compressed EU MDR software validation schedules.
- Mobile Units:Vehicle-mounted or portable systems for blood drives and emergency response.
- Centralized Systems:Hub-and-spoke architectures serving multi-site health networks from single processing locations.
- Modular Installations:Scalable cabinet configurations for facilities anticipating inventory growth.
On-premise installations anchor the revenue base. Modular installations are expanding most quickly among multi-state health systems planning capacity flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes compliance-driven replacement cycles for FDA-validated systems, while Germany and Japan emphasize precision engineering for aging-population transfusion volumes. China scales domestic manufacturing for cost-sensitive hospital networks.
United States
Regional blood centers in Texas and California pilot dual-protocol RFID installations combining active sensors with Bluetooth beacons for emergency inventory relocation. FDA 21 CFR Part 11 mandates force automated cold chain upgrades across Southeast health systems consolidating procurement through regional purchasing cooperatives. Helmer Scientific leverages its North American service infrastructure to sustain long-term contracts with these multi-state networks.
Germany
Hospital blood banks expand refrigerator procurement for platelet inventory turnover driven by higher transfusion volumes among elderly populations. EU MDR conformity assessment timelines compress software validation roadmaps, favoring vendors with pre-certified quality management systems. B Medical Systems competes aggressively on energy efficiency ratings across federal-state procurement tenders in Baden-Württemberg and Bavaria.
Japan
PMDA cold chain documentation standards parallel FDA requirements, tightening equipment specifications for transfusion safety. Research laboratories in Tokyo and Osaka prioritize ultra-low temperature telemetry for cryoprecipitate storage in clinical trial applications. Thermo Fisher Scientific anchors its position through deep R&D investment in ultra-low temperature telemetry systems serving these academic medical centers.
China
Domestic manufacturers scale cold chain output for Asia-Pacific hospital networks, fragmenting the supply base with cost-competitive alternatives. Haier Biomedical exemplifies this expansion from Qingdao manufacturing clusters into provincial hospital procurement. The country's national pharmaceutical regulator accelerates medical device quality management standardization, opening tender access for ISO 13485-certified suppliers across Middle Eastern hospital privatization programs.
India
Diagnostic centers in Maharashtra and Karnataka represent underpenetrated demand for simplified passive RFID systems without full telemetry infrastructure. CDSCO regulatory alignment with international cold chain standards lags, creating procurement friction for imported equipment. Smaller blood testing facilities prioritize capital efficiency over comprehensive documentation, favoring gateway-dependent passive installations from regional distributors.
RFID Blood Refrigerators and Freezers Market Key Industry Players
Capability concentration sits with precision-engineering specialists; scale advantage sits with diversified life science conglomerates. The market structures around three tiers: North American service-anchored incumbents, European energy-efficiency specialists, and Asia-Pacific cost-optimized fabricators. Strategic archetypes include compliance-validated platform providers, modular cold chain integrators, and component-scale suppliers. Competitive moves center on enterprise contract consolidation and ISO 13485 certification acceleration for Middle Eastern tender access.
Among North American service-anchored incumbents, Helmer Scientific occupies a position exemplifying long-term contract sustainability through regional blood center relationships. Thermo Fisher Scientific represents the diversified conglomerate archetype with deep R&D positioning in ultra-low temperature telemetry. B Medical Systems sits within the European energy-efficiency specialist tier, competing on ratings across procurement tenders. Haier Biomedical anchors the Asia-Pacific cost-optimized fabricator segment, scaling domestic output for hospital network expansion.
| Leading Market Players |
|---|
| Helmer Scientific |
| Thermo Fisher Scientific |
| B Medical Systems |
| Angelantoni Life Science |
| Haier Biomedical |
| PHC Holdings Corporation |
| Philips |
| Terso Solutions |
| Arctiko A/S |
| Others |
Cost & Logistics Intelligence
Semiconductor foundry concentration in East Asia determines both pricing tier spreads and supply chain shape across RFID blood cold chain equipment. Tariff exposure on refrigeration compressor controllers and RFID reader chipsets widens the gap between premium active systems and cost-optimized passive installations, forcing buyers to weigh validated software architectures against hardware cost compression.
Pricing Analysis
North American hospital networks pay premiums of thirty to fifty percent above Indian diagnostic centers for equivalent thermal capacity, reflecting FDA validation costs and service-attach bundling. Three-tier pricing structure across premium, standard, and economy levels separates active RFID systems with real-time telemetry from gateway-dependent passive installations and basic temperature loggers. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers are scaling output for Asia-Pacific procurement. Blood banks in Germany and Japan demonstrate the least price sensitivity, prioritizing EU MDR pre-certification and energy efficiency ratings over capital expenditure minimization.
Supply Chain Analysis
Stainless steel feedstock from China, compressor controllers from South Korea, and RFID chipsets from Taiwan anchor upstream procurement for most manufacturers. Component sourcing draws from East Asian foundry capacity that faces single-source vulnerability for advanced telemetry chipsets used in ultra-low temperature freezers. Distribution runs through regional blood center service networks in the United States, federal-state procurement tenders in Germany, and hospital group purchasing organizations in Japan. Logistics chokepoints at major port complexes create lead time volatility for European and North American assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RFID blood cold chain equipment functions as a service-attach opportunity where multi-year validation contracts and preventive maintenance subscriptions expand faster than hardware replacement cycles. Recurring revenue from software updates and audit-ready temperature log retention is displacing standalone equipment tenders among consolidated health systems.
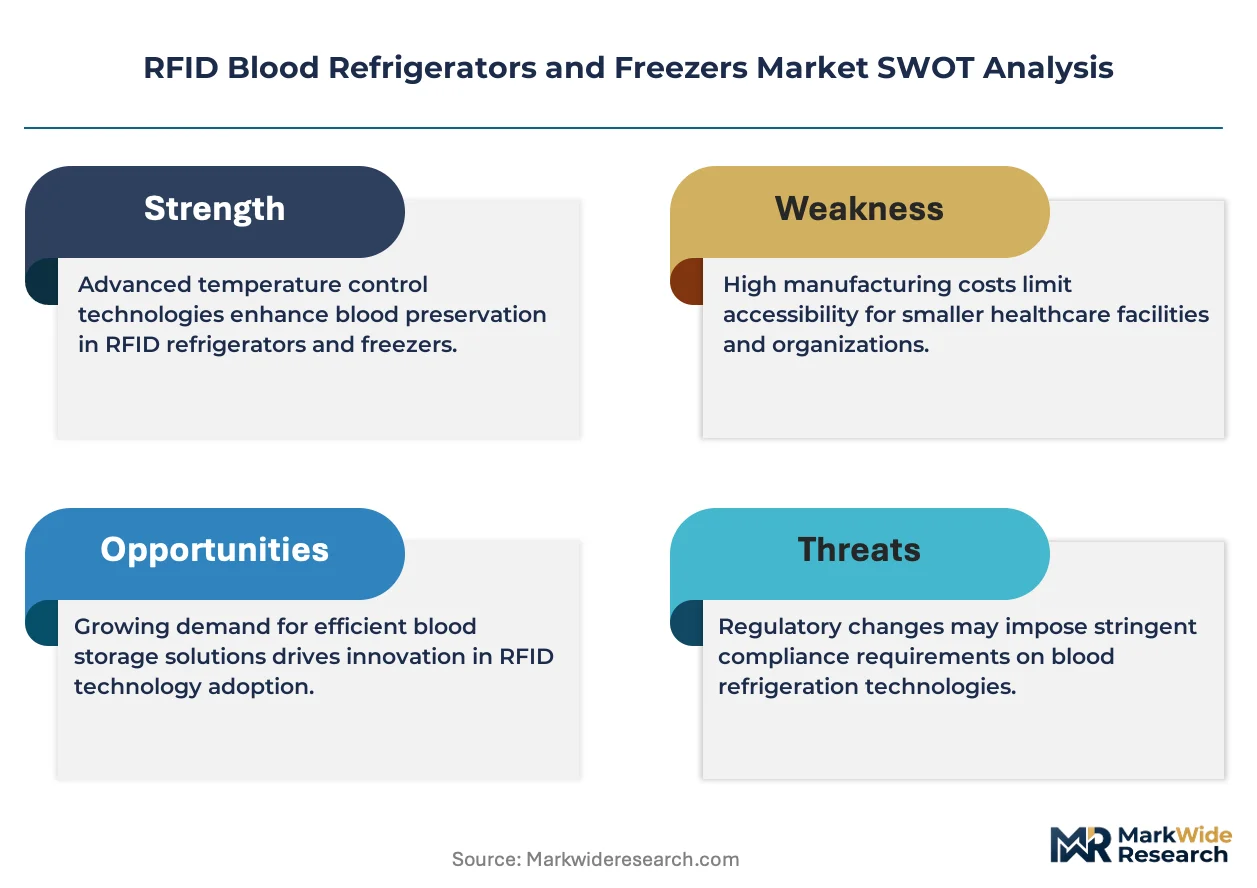
For Market Incumbents: Pre-empt domestic Chinese cost competition by embedding cloud-native ERP connectivity into standard product configurations, eliminating the integration work that currently justifies premium pricing. Accelerate ISO 13485 certification for Middle Eastern tender access before regional hospital privatization programs mature. Vertical integration into refrigeration compressor controller production reduces exposure to South Korean foundry concentration risks. For New Entrants and Emerging Players: Diagnostic centers in Maharashtra and Karnataka represent the most penetrable entry point, as these facilities prioritize capital efficiency over comprehensive cold chain documentation and currently rely on regional distributors for gateway-dependent passive systems. Smaller blood testing facilities across Southeast Asia offer parallel white-space expansion for simplified RFID installations without full telemetry infrastructure. A direct-to-laboratory sales model bypassing traditional hospital procurement committees accelerates initial reference site acquisition. For Investors and Strategic Acquirers: The market sits at a compliance-driven replacement phase that favors validated software platform providers with pre-certified quality management systems. Long-term viability over the next decade hinges on convergence with hospital digital transformation programs rather than isolated temperature monitoring equipment. Acquisition targets should demonstrate existing SAP or Oracle health system module integrations. The signal to watch is group purchasing organization consolidation velocity in the Southeast United States, as enterprise-wide contract bundling either accelerates incumbent scale advantages or creates entry points for modular cold chain integrators.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native ERP Integration | SAP and Oracle health system module convergence creates unified inventory visibility for hospital networks. |
| ISO 13485 Certification Acceleration | Medical device quality management standardization opens tender access across Middle Eastern hospital privatization programs. |
| Dual-Protocol Sensor Deployment | Active RFID hybridization with Bluetooth Low Energy beacons eliminates signal dead zones during emergency inventory relocations in Texas and California health systems. |
| Energy Efficiency Rating Competition | Federal-state procurement tenders in Baden-Württemberg and Bavaria prioritize vendors with superior ratings for platelet refrigerator contracts. |
| Service Infrastructure Expansion | North American regional blood center relationships sustain long-term contracts through preventive maintenance bundling and validation support. |
Research Approach
A standing panel of hospital blood bank directors, biomedical engineers, GPO contracts managers, and cold chain validation specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR notified body databases, hospital procurement contract registries, and medical device trade flow records. Bottom-up unit economics and top-down market sizing triangulation ensured cross-verification of volume and value estimates.
Scenario-bracketing around regulatory approval timelines, semiconductor supply volatility, and health system consolidation velocity framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user application, installation configuration, and regional regulatory cluster. CAGRs were derived from installed base turnover analysis and replacement cycle compression under FDA and EU MDR compliance pressure. Forecast inputs incorporated blood component inventory velocity data and cold chain excursion risk valuation from research laboratory applications.
Practitioners should monitor EU MDR notified body review period extensions, East Asian foundry capacity allocation shifts, and group purchasing organization contract consolidation for early signals of forecast revision. Cross-checking against hospital capital expenditure surveys and blood bank operational benchmarking studies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Global Optometry Equipment Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Global Medical Power Supply Market
Medical Equipment
North America Medical Device Reprocessing Market
Medical Equipment
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Healthcare Simulators Market
Medical Equipment
Terminal Sterilization Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
Contact Type Liquid Handling Workstation Market
Medical Equipment
Global Steam Autoclaves Market
Medical Equipment
Hybrid Operating Room Market
Medical Equipment
Europe Medical Automation Market