
 Medical Ethylene Oxide Sterilization Equipment Market | 2026-2036
Medical Ethylene Oxide Sterilization Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Ethylene Oxide Sterilization Equipment Market Insights
Direct sales and service partnerships between equipment makers and hospital procurement consortiums is reconfiguring how sterilization systems reach end users. Steris leverages its installed base of sterilizers to sustain long-term service contracts across integrated delivery networks. Getinge Group anchors its position through geographic dominance in European healthcare infrastructure. Hangzhou Riches Engineering Co., LTD competes on manufacturing scale for chamber sterilizers serving Asia-Pacific pharmaceutical exporters.
Medical ethylene oxide sterilization equipment encompasses enclosed chamber systems that deliver precise concentrations of EtO gas, typically between 450-1200 mg/L, at controlled temperature and humidity levels to achieve sterility assurance levels of 10^-6 on moisture- and heat-sensitive medical products. These systems serve as critical infrastructure for terminal sterilization of polymer-based implants, electronic medical devices, and custom procedure kits that cannot withstand steam or radiation methods. Batch sterilizers dominate current installed capacity due to their flexibility across load configurations, while automated technology segments capture expanding margin pools as pharmaceutical companies pursue validated, reproducible cycles with reduced operator exposure. Vacuum sterilizer architectures lead in high-throughput hospital settings where rapid chamber turnaround supports surgical schedule density.
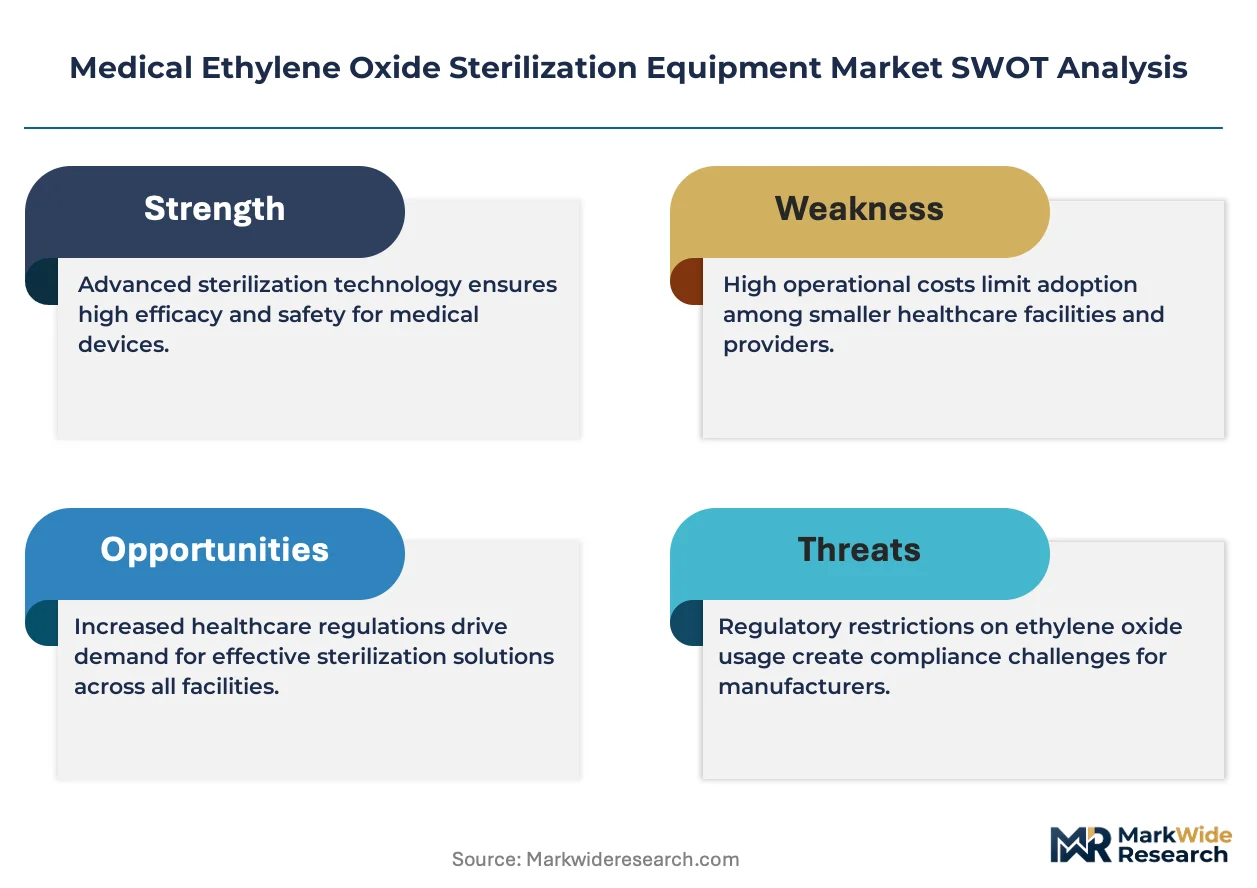
FDA enforcement of updated EtO emission limits shapes equipment design requirements, while EPA ambient air standards drive abatement system retrofits and replacement demand across existing installations. ISO 11135 validation protocols govern cycle development and biological indicator placement, creating compliance barriers that favor established suppliers with documented quality systems. Stakeholders must monitor evolving state-level EtO restrictions and assess whether advanced hybrid technologies can satisfy both sterility outcomes and tightening occupational exposure thresholds without displacing proven gas-based methods.
Market Dynamics
EPA emissions enforcement is forcing hospital systems and contract sterilizers to accelerate equipment replacement cycles while retrofitting abatement infrastructure on existing EtO chambers.
Growth Catalysts
- ISO 11135 validation protocols:Biomedical manufacturers in Germany and Japan require documented quality systems that favor established equipment suppliers with proven cycle development capabilities.
- In-house sterilization expansion:Hospital procurement consortiums across North America are consolidating sterilization capacity to reduce dependency on third-party logistics.
- Precision polymer implants:Moisture- and heat-sensitive cardiac and orthopedic devices require terminal EtO sterilization that steam and radiation methods cannot achieve.
Market Restraints
- EtO gas supply concentration:Industrial gas production clusters in the US Gulf Coast create vulnerability to weather-related supply disruptions.
- EPA ambient air standards:Tightening federal emissions limits impose capital-intensive abatement retrofits on existing vacuum sterilizer installations.
- Peracetic acid vapor systems:Alternative low-temperature sterilization methods are capturing select loads from EtO in outpatient surgical settings.
Strategic Opportunities
- Automated batch sterilizers:Pharmaceutical exporters in India require validated, reproducible cycles with reduced operator exposure to meet EU MDR import requirements.
- Service contract unbundling:Independent service organizations are capturing maintenance revenue from legacy installed bases as hospital capital budgets tighten.
- Hybrid sterilization technologies:Convergence of nitrogen dioxide and vaporized hydrogen peroxide systems creates white space for equipment makers with multi-modal platforms.
Industry Challenges
- Biological indicator validation:ISO 11135 compliance requires specialized microbiology expertise that sterilization departments struggle to retain.
- Legacy chamber integration:New abatement systems must interface with 20-year-old vacuum architectures without disrupting surgical schedule density.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Ethylene Oxide Sterilization Equipment Market |
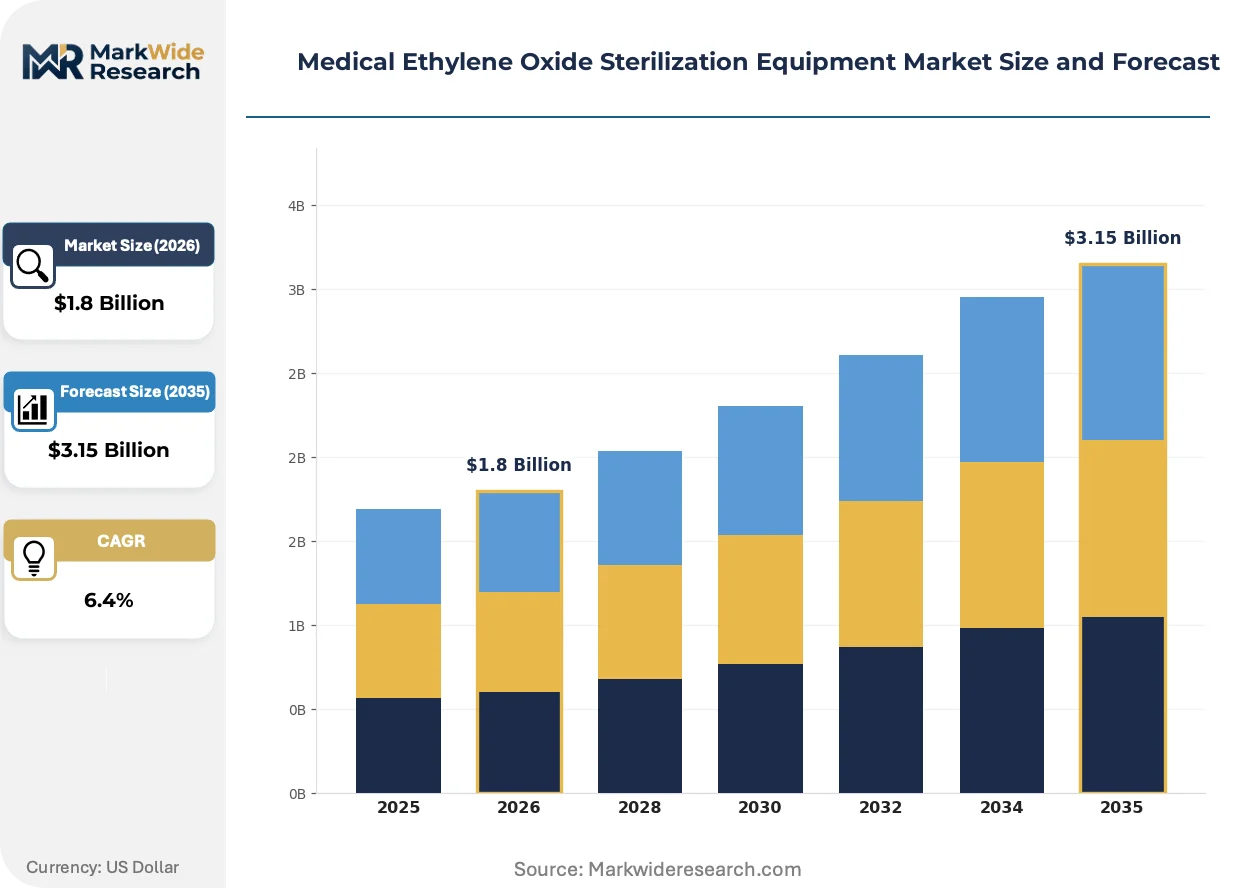
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Sterilizers, Continuous Sterilizers, Vacuum Sterilizers, Chamber Sterilizers End User: Hospitals, Clinics, Laboratories, Pharmaceutical Companies Technology: Conventional, Advanced, Hybrid, Automated Application: Medical Devices, Pharmaceuticals, Laboratory Equipment, Others |
| Companies Covered | Steris, Getinge Group, Hangzhou Riches Engineering Co., LTD, 3M, Shinva Medical Instrument, Belimed, Andersen Sterilizers, Advanced Sterilization Products, MMM Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Ethylene Oxide Sterilization Equipment Market Trends and Innovations
Equipment architecture is migrating toward automated, closed-loop systems that reduce cycle variability and operator exposure while compressing turnaround times in high-throughput settings.
Vacuum sterilizer technology is migrating from manual load configuration toward robotic handling systems integrated with hospital enterprise resource planning platforms. Academic medical centers in the United States are piloting these configurations to support same-day surgical instrument turnover. The shift is compressing labor costs per cycle while raising the technical barrier for mid-tier equipment suppliers.
FDA enforcement of updated EtO emission limits is reshaping equipment design requirements and accelerating abatement system retrofits across existing installations. Sterilization facilities must now demonstrate real-time emissions monitoring capabilities that previous-generation chambers lacked. Contract sterilizers in high-density manufacturing corridors are responding by consolidating loads and extending chamber utilization rates.
Hospital procurement groups are consolidating vendor relationships and demanding outcome-based service agreements that bundle equipment, consumables, and validation support. Integrated delivery networks are displacing standalone purchasing decisions previously made at individual facility level. This concentration is most visible in the Northeastern United States where health system mergers have reduced supplier touchpoints by half.
Medical Ethylene Oxide Sterilization Equipment Market Segmentation
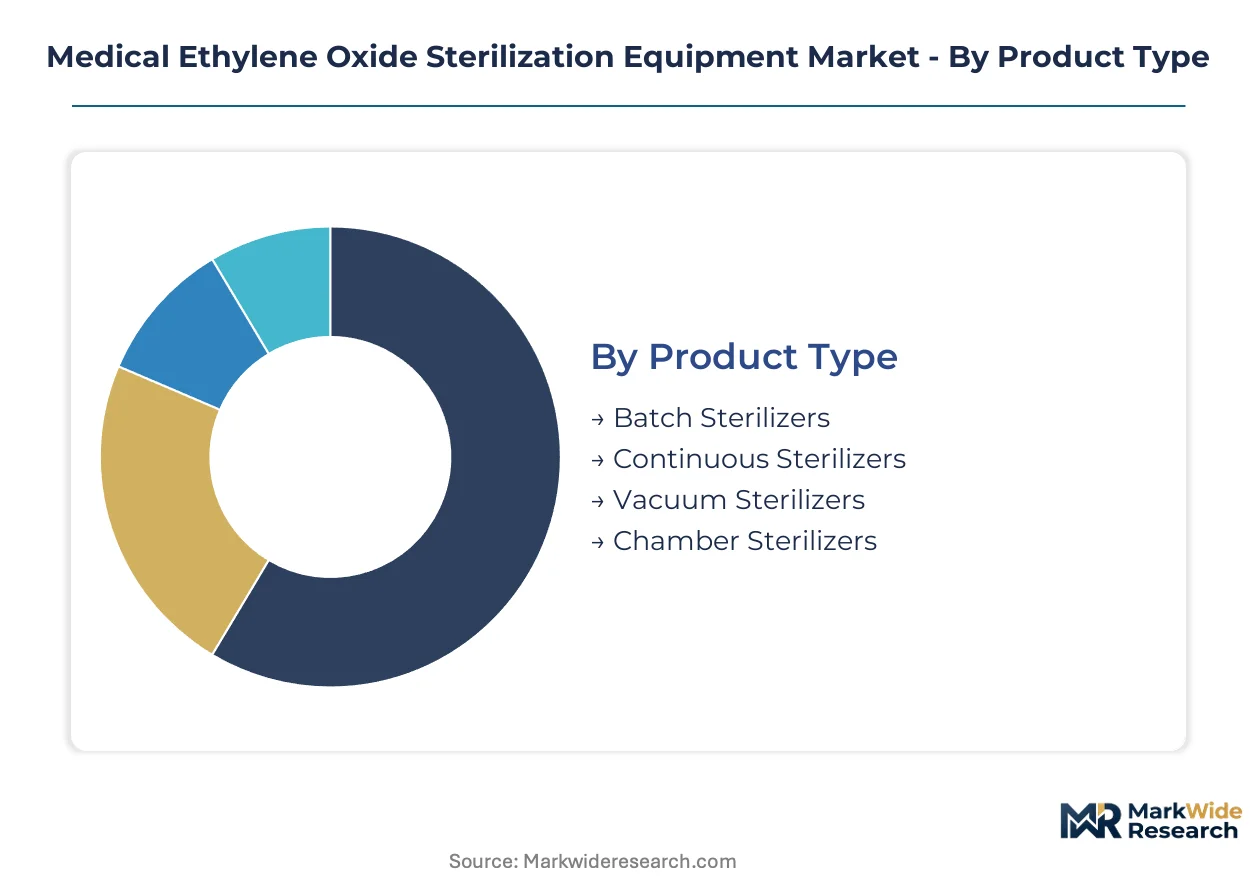
Equipment segmentation in the Medical Ethylene Oxide Sterilization Equipment Market reveals how sterilization architecture maps to throughput requirements, regulatory validation burdens, and capital deployment strategies across healthcare and pharmaceutical value chains. Understanding these divisions exposes where margin pools concentrate and which technology transitions will reshape competitive positioning.
Product Type:
Equipment architecture divides primarily by chamber configuration and load-handling methodology, with each design carrying distinct capital intensity, cycle flexibility, and emissions abatement requirements.
- Batch Sterilizers:Enclosed chamber systems process discrete load configurations with cycle parameters adjustable per product type, serving contract sterilizers handling diverse medical device portfolios. Demand concentrates in Germany and Japan where precision polymer implants require validated, product-specific cycles that continuous systems cannot accommodate. ISO 11135 documentation requirements favor established suppliers with proven cycle development libraries.
- Vacuum Sterilizers:These architectures employ pressure differential technology to accelerate gas penetration and aeration phases, compressing turnaround times for high-throughput hospital settings. North American health systems expanding in-house capacity prioritize these systems to support surgical schedule density without outsourcing dependency.
- Continuous Sterilizers:Conveyor-fed tunnel configurations process high-volume single-product streams with minimal operator intervention.
- Chamber Sterilizers:Modular cabinet designs serve mid-scale pharmaceutical exporters with standardized load patterns.
Batch Sterilizers hold installed capacity. Vacuum Sterilizers is rotating up the share rankings.
End User:
Customer type determines purchasing authority, service contract structures, and regulatory exposure profiles across the sterilization value chain.
- Hospitals:Integrated delivery networks in the United States are consolidating procurement decisions previously made at individual facility level, demanding bundled equipment-service-validation agreements. EPA emissions enforcement is accelerating replacement cycles across aging installed bases while tightening capital budgets.
- Pharmaceutical Companies:Exporters to EU MDR jurisdictions require documented sterilization validation with biological indicator placement protocols that automated systems reduce. Indian pharmaceutical manufacturers are expanding EtO capacity to capture contract sterilization revenue from European device makers facing domestic emissions constraints.
- Clinics:Outpatient surgical centers favor compact chamber systems with minimal facility infrastructure requirements.
- Laboratories:Research sterilization demands flexible cycle parameters for experimental load configurations.
Hospitals command procurement volume concentration. Pharmaceutical Companies is expanding most quickly as vertical integration accelerates.
Technology:
Technology tier reflects automation depth, emissions control integration, and operator exposure reduction capabilities that determine compliance posture and labor economics.
- Automated:Closed-loop systems integrate robotic load handling with real-time cycle monitoring and enterprise resource planning connectivity, compressing labor costs per cycle while satisfying FDA emissions documentation requirements. Academic medical centers in the United States pilot these configurations for same-day surgical instrument turnover.
- Hybrid:Multi-modal platforms combine EtO with nitrogen dioxide or vaporized hydrogen peroxide capability, creating flexibility as occupational exposure thresholds tighten without displacing proven gas-based methods for moisture-sensitive loads.
- Conventional:Manual configuration systems dominate legacy installed bases requiring abatement retrofits.
- Advanced:Next-generation architectures incorporate predictive maintenance and emissions analytics.
Conventional systems retain legacy footprint. Automated is gaining share fastest on replacement demand.
Application:
Application scope determines sterility assurance level requirements, biological indicator validation complexity, and alternative sterilization method substitutability.
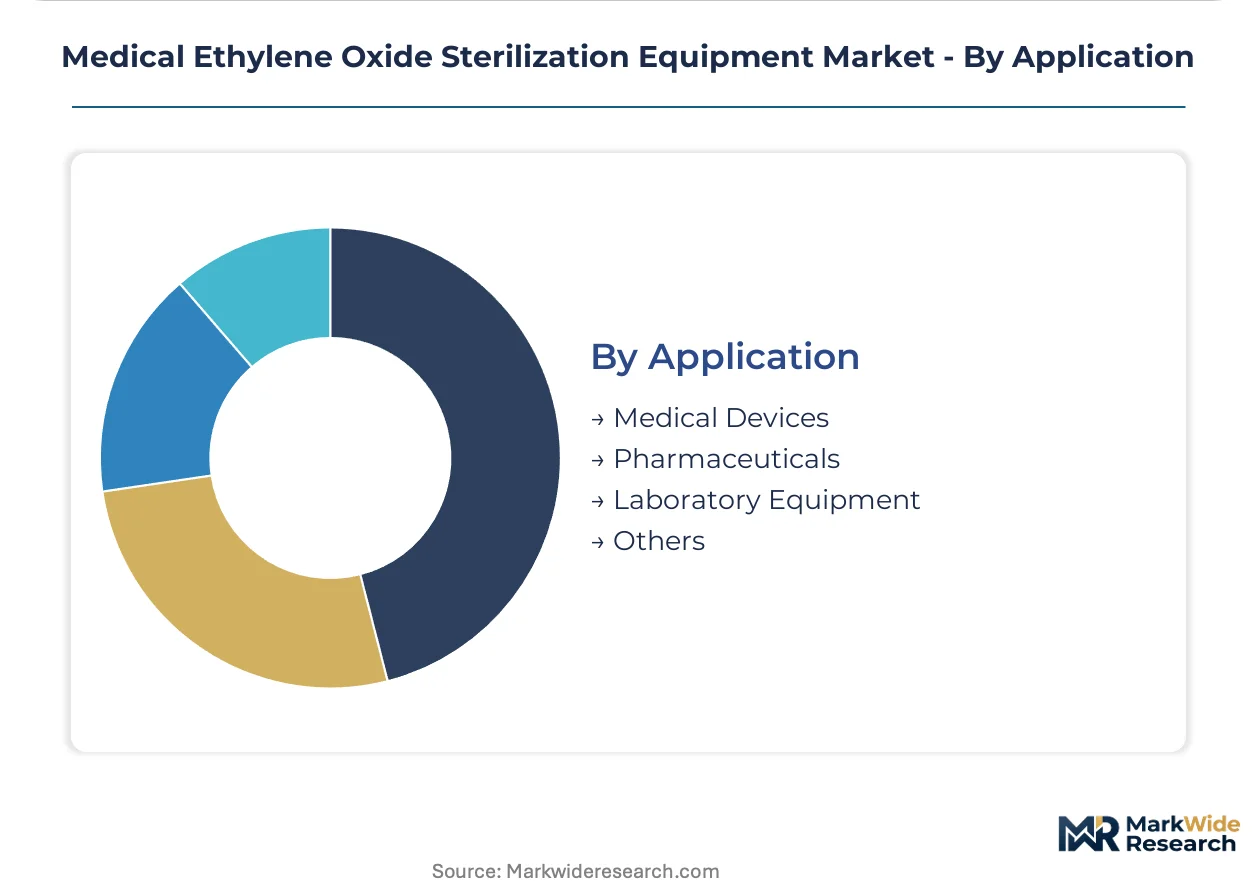
- Medical Devices:Polymer-based cardiac and orthopedic implants require terminal EtO sterilization achieving 10^-6 sterility assurance levels that steam and radiation methods cannot deliver. Precision manufacturing clusters in Germany and Japan anchor demand for validated sterilization infrastructure supporting export qualification.
- Pharmaceuticals:Parenteral drug packaging and combination products require documented cycle reproducibility with reduced operator exposure to satisfy EU MDR and FDA quality system regulations.
- Laboratory Equipment:Research-grade sterilization demands flexible validation protocols for non-standard load configurations.
- Others:Specialty applications include aerospace components and food packaging requiring customized cycle development.
Medical Devices anchors revenue concentration. Pharmaceuticals is climbing the fastest on biologics packaging expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of updated EtO emission limits is accelerating equipment replacement cycles across the United States while tightening occupational exposure thresholds reshape sterilization infrastructure investment patterns worldwide.
United States
Hospital procurement consortiums in the Northeast and Midwest are consolidating vendor relationships to reduce outsourcing dependency on contract sterilizers. FDA emission documentation requirements now mandate real-time monitoring capabilities that legacy vacuum chambers lack. Academic medical centers in Boston and Philadelphia pilot robotic load-handling configurations to compress same-day surgical instrument turnaround.
Germany
Precision polymer implant manufacturers in Baden-Württemberg and Bavaria require validated EtO cycles that ISO 11135 protocols govern with strict biological indicator placement standards. EU MDR import requirements from Asian pharmaceutical exporters sustain demand for documented sterilization infrastructure. The Tübingen and Freiburg medical device clusters anchor European terminal sterilization capacity for cardiac and orthopedic implants.
Japan
PMDA quality system regulations enforce sterility assurance levels of 10^-6 on moisture-sensitive electronic medical devices that steam methods cannot achieve. Manufacturing clusters in Osaka and Tokyo sustain captive sterilization capacity to protect export qualification for polymer-based implants. METI industrial policy supports equipment modernization to maintain precision device manufacturing competitiveness against Korean and Chinese rivals.
India
Pharmaceutical exporters in Maharashtra and Gujarat are expanding EtO capacity to capture contract sterilization revenue from European device makers facing domestic emissions constraints. CDSCO documentation requirements for parenteral drug packaging drive investment in automated batch systems with reduced operator exposure. The Mumbai-Pune corridor concentrates validated sterilization infrastructure serving EU MDR-compliant export markets.
China
NMPA medical device registration rules require terminal sterilization validation for polymer implants that radiation damages or steam degrades. Manufacturing scale in Jiangsu and Zhejiang provinces sustains chamber sterilizer demand from domestic device makers and multinational subsidiaries. Shanghai and Suzhou medical device parks anchor precision sterilization infrastructure serving both domestic consumption and export qualification.
Medical Ethylene Oxide Sterilization Equipment Market Competitive Landscape
On the supply side, the industry is consolidating around integrated equipment-service platforms that capture long-term maintenance revenue from hospital capital budgets. Three archetypes dominate competitive positioning: multinational healthcare conglomerates with installed base leverage, regional engineering specialists serving pharmaceutical export corridors, and mid-scale fabricators competing on manufacturing scale for standardized chamber configurations. Dominant competitive moves include geographic expansion through distribution partnerships and portfolio diversification into hybrid multi-modal sterilization platforms.
Among the established multinational tier, Steris and Getinge Group occupy positions defined by service contract density across integrated delivery networks, while Hangzhou Riches Engineering Co., LTD exemplifies the Asia-Pacific manufacturing-scale archetype serving chamber sterilizer demand from pharmaceutical exporters. Shinva Medical Instrument and Belimed represent regional healthcare infrastructure specialists with geographic concentration in their respective domestic markets. These five named entities collectively illustrate how competitive positioning stratifies across global conglomerates, regional champions, and manufacturing-scale specialists.
| Leading Market Players |
|---|
| Steris |
| Getinge Group |
| Hangzhou Riches Engineering Co., LTD |
| 3M |
| Shinva Medical Instrument |
| Belimed |
| Andersen Sterilizers |
| Advanced Sterilization Products |
| MMM Group |
| Others |
Pricing and Supply Chain Analysis
EPA emissions enforcement vulnerability concentrates pricing power among equipment suppliers with documented abatement integration capabilities, widening spreads between ISO 11135-validated premium systems and conventional chamber configurations while forcing hospital procurement consortiums toward bundled service contracts that internalize compliance cost uncertainty.
Pricing Analysis
Certification level (ISO 11135/FDA-grade) creates the primary spread between equipment tiers, with validated cycle development libraries and real-time emissions monitoring capabilities commanding substantial premiums over conventional manual configurations. Three-tier pricing structure across premium automated, standard vacuum, and economy chamber levels reflects differential compliance posture and operator exposure reduction features. Cost compression in mid-tier segments is intensifying because independent service organizations unbundle maintenance revenue from legacy installed bases. Pharmaceutical exporters exhibit lowest price sensitivity due to EU MDR documentation requirements, while outpatient surgical centers face acute capital constraints.
Supply Chain Analysis
Export control regimes restricting advanced abatement technology flows to certain manufacturing corridors constrain supply elasticity for EPA-compliant systems. Component fabrication concentrates in Germany, Japan, and the United States, with precision gas delivery systems and vacuum pump assemblies drawing from specialized industrial gas equipment suppliers. Stainless steel chamber fabrication, control system electronics, and emissions monitoring sensors constitute critical input dependencies. Single-source vulnerability runs through EPA-certified abatement system integrators with limited qualified vendor pools. Distribution runs through direct sales organizations and hospital procurement consortiums with consolidated vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network mergers that have halved supplier touchpoints in the Northeastern United States, fragmenting purchasing authority previously held at individual facility level.
For Market Incumbents: Build regulatory compliance moats by deepening ISO 11135 validation service capabilities and securing exclusive abatement retrofit contracts across aging vacuum sterilizer installed bases. Peracetic acid vapor systems threaten select outpatient loads; counter by embedding automated EtO configurations with robotic handling into enterprise resource planning platforms at academic medical centers. For New Entrants and Emerging Players: Build out automated batch sterilizer capacity serving Indian pharmaceutical exporters facing EU MDR import documentation requirements. Hybrid multi-modal platforms combining nitrogen dioxide capability represent the most penetrable white space as occupational exposure thresholds tighten. Pursue outcome-based service agreements that bundle equipment, consumables, and validation support to displace fragmented procurement decisions. For Investors and Strategic Acquirers: Regional engineering specialists with geographic concentration in European healthcare infrastructure offer compelling acquisition profiles given their validated sterilization infrastructure relationships with precision polymer implant manufacturers. Long-term viability hinges on regulatory enforcement durability rather than technology substitution. Monitor EPA state-level EtO restriction expansion as the critical inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Batch Sterilizer Deployment | Pharmaceutical exporters in India require validated cycles with reduced operator exposure for EU MDR compliance. |
| Abatement System Retrofit Programs | EPA emissions enforcement mandates real-time monitoring capabilities that legacy vacuum chambers lack. |
| Hybrid Multi-Modal Platform Development | Convergence of nitrogen dioxide and vaporized hydrogen peroxide creates flexibility without displacing proven EtO methods. |
| Service Contract Unbundling | Independent service organizations capture maintenance revenue as hospital capital budgets tighten. |
| Robotic Load Handling Integration | Academic medical centers pilot ERP-connected configurations to compress same-day surgical instrument turnaround. |
Research Methodology
The analysis maps batch sterilizer, vacuum sterilizer, and automated technology segments, each validated through sterilization department directors, biomedical engineers, hospital procurement consortium managers, and GPO contracts specialists. Primary fieldwork combined structured interviews with secondary validation from FDA 510(k) filings, EPA emissions compliance databases, ISO 11135 registration records, and hospital capital expenditure disclosures. Bottom-up equipment shipment tracking and top-down healthcare infrastructure investment analysis provided triangulation across the projection horizon.
The forecast framework holds EPA enforcement trajectory and EU MDR documentation requirements fixed while varying hospital in-house sterilization expansion rates and pharmaceutical export corridor development. Segmentation dimensions modeled include equipment architecture, end-user type, automation technology tier, and application scope across the analysis window. CAGRs derive from sterilizer replacement cycle analysis and validated capacity expansion announcements. Biological indicator validation complexity and emissions abatement integration timelines constitute industry-specific forecast inputs.
Practitioners should monitor state-level EtO restriction adoption patterns and hybrid sterilization technology efficacy signals for early revision triggers. Forecasts reflect assumptions regarding regulatory enforcement durability and alternative method substitution limits. Material shifts in EPA ambient air standard stringency or breakthrough vaporized hydrogen peroxide penetration in moisture-sensitive loads would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Urodynamics Equipment and Disposables Market
Medical Equipment
Automated Dialysis Concentrated Production Systems Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Operating Table Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
North America Durable Medical Equipment Market
Medical Equipment
Chile Radiotherapy Market
Medical Equipment
Manufacturing on Demand for Medical Market
Medical Equipment
Global Countertop Platelet Incubator Market
Medical Equipment
CO2 Medical Laser Systems Market
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
South Africa Radiotherapy Market
Medical Equipment
PMMA Healthcare Market
Medical Equipment
Medical Physics Market
Medical Equipment
Apheresis Equipment Market