
 Advanced Wound Therapy Devices Market | 2026-2036
Advanced Wound Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Wound Therapy Devices Market Analysis
CE marking under the EU Medical Device Regulation is bifurcating competitive access between established manufacturers and newer entrants lacking notified body relationships. Mölnlycke Health Care AB leverages its Scandinavian manufacturing footprint to sustain premium positioning across European hospital networks. Smith & Nephew PLC anchors its portfolio through specialized negative pressure systems that dominate ambulatory surgical center contracts in North America.
Advanced wound therapy devices encompass electromechanical systems, bioactive dressings, and energy-based modalities engineered to accelerate healing through controlled moisture balance, negative pressure application, or cellular stimulation at wound beds. These technologies serve primarily to reduce infection rates, shorten hospitalization duration, and enable outpatient management of complex wounds including diabetic foot ulcers and post-surgical dehiscence. Negative pressure wound therapy systems capture the deepest margin pools given capital equipment attachment and recurring canister revenues, while hydrocolloid dressings compete on volume throughput in long-term care settings where cost-per-change economics govern procurement. Electrotherapy and ultrasound therapy segments attract R&D concentration from device firms seeking differentiation beyond commodity dressing markets.
FDA 510(k) pathways and EU MDR conformity assessments shape product development cycles, with the former emphasizing predicate equivalence and the latter demanding clinical evidence portfolios that extend regulatory timelines. The EPA regulates antimicrobial claims embedded in advanced dressings, constraining formulation choices for manufacturers targeting infected wound indications. Stakeholders must monitor evolving reimbursement thresholds from CMS and parallel national health technology assessment bodies, as coverage determinations increasingly predicate market access on demonstrated cost-effectiveness against standard-of-care comparators.
Market Dynamics
Medicare reimbursement reforms in the United States are compressing hospital procurement cycles for advanced wound therapies while simultaneously expanding coverage for home-based negative pressure systems, fundamentally restructuring where and how these devices generate revenue.
Growth Catalysts
- Post-acute migration:Home healthcare providers are scaling portable negative pressure procurement as CMS reimbursement shifts care outside institutional settings.
- EU MDR compression:CE marking pathways under the Medical Device Regulation are shortening development timelines for biologic-synthetic hybrid dressings with established notified body relationships.
- Antimicrobial integration:EPA-registered silver-ion and PHMB formulations embedded in advanced dressings are capturing infected wound indications previously managed with systemic antibiotics.
Market Restraints
- Silicone supply concentration:Medical-grade silicone feedstock for hydrocolloid and foam dressing substrates faces pricing volatility from concentrated Asian petrochemical suppliers.
- FDA predicate divergence:510(k) equivalence requirements for novel electrotherapy modalities create regulatory friction when no suitable predicate device exists in the database.
- Conventional gauze persistence:Cost-per-change economics in long-term care facilities sustain commodity dressing protocols despite demonstrated clinical superiority of advanced alternatives.
Strategic Opportunities
- Rural home health penetration:Underserved counties in the United States present white space for remote monitoring-integrated negative pressure systems with telehealth connectivity.
- Diabetic foot ulcer protocols:Emerging application of ultrasound therapy combined with bioactive dressings is displacing debridement-only standards in podiatric surgery centers.
- VA contract consolidation:Department of Veterans Affairs centralized procurement mandates create volume concentration opportunities for manufacturers with federal supply schedule positioning.
Industry Challenges
- Bioelectronic manufacturing scale-up:Printed circuit and flexible electrode production for electrotherapy patches requires capital-intensive cleanroom expansion that strains mid-cap device firms.
- Interoperability certification:Integration complexity with electronic health record systems delays hospital system adoption of connected wound monitoring devices pending HL7 FHIR compliance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Wound Therapy Devices Market |
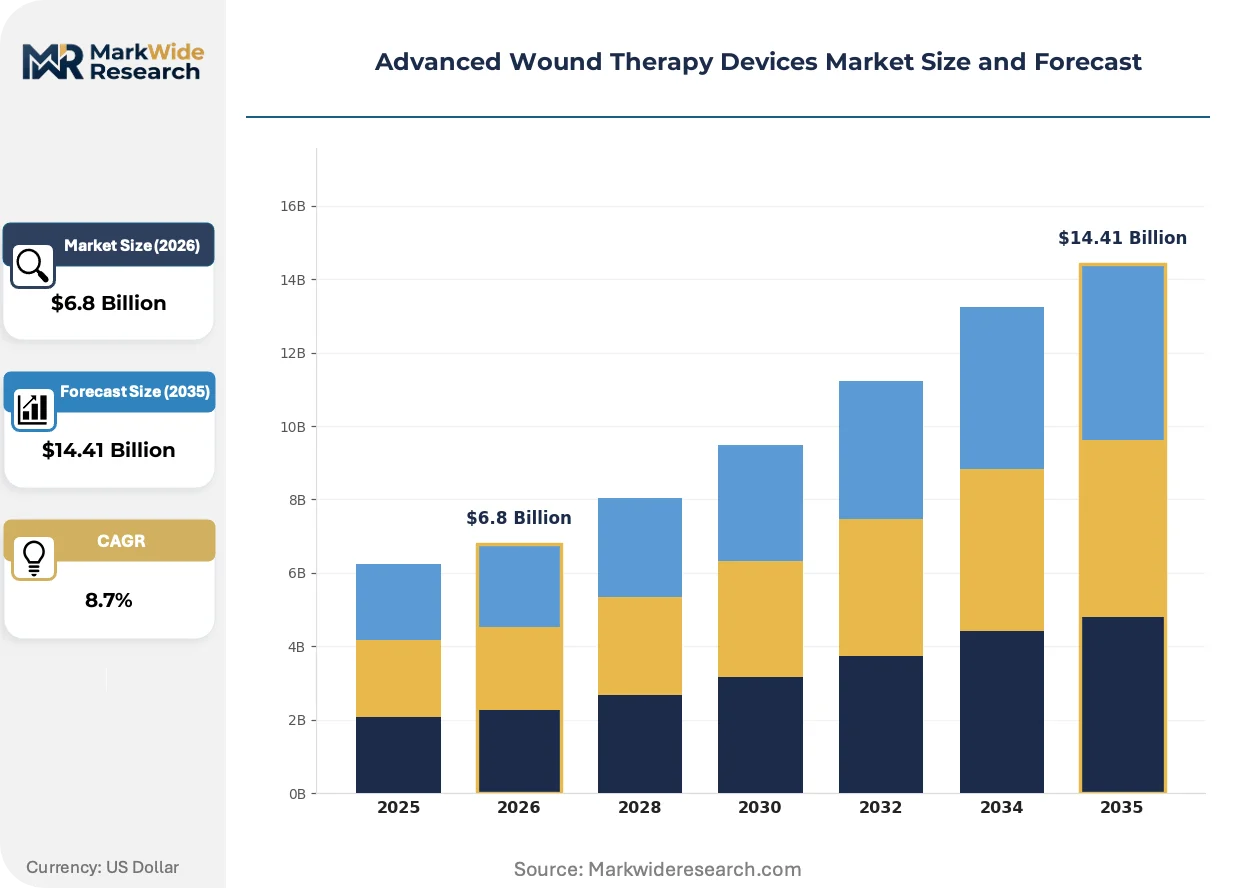
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Negative Pressure Wound Therapy, Hydrocolloid Dressings, Foam Dressings, Alginate Dressings End User: Hospitals, Home Healthcare, Long-Term Care Facilities, Ambulatory Surgical Centers Application: Chronic Wounds, Surgical Wounds, Ulcers, Burn Care Technology: Electrotherapy, Ultrasound Therapy, Biologics, Traditional Dressings |
| Companies Covered | Mölnlycke Health Care AB, Medtronic PLC, Smith & Nephew PLC, B. Braun Melsungen AG, Medline Industries, Inc., ConvaTec Group PLC, 3M, Integra LifeSciences, Coloplast A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Wound Therapy Devices Market Emerging Trajectories
Convergence of bioactive materials with connected monitoring hardware is fragmenting traditional dressing categories while compressing the window between clinical evidence generation and reimbursement coverage decisions.
Smart dressings with embedded pH and temperature sensors are decomposing the distinction between passive wound coverage and active therapeutic intervention. Acute care hospitals in Germany and the United States are piloting these systems for post-surgical monitoring, reducing nursing assessment frequency while capturing infection onset earlier than visual inspection protocols permit.
EU MDR clinical evidence requirements are extending conformity assessment timelines for novel wound therapy devices, favoring manufacturers with existing predicate portfolios over de novo entrants. The regulation's emphasis on post-market surveillance is shifting R&D investment toward real-world evidence collection infrastructure rather than purely pre-market clinical trials.
Hospital purchasing cooperatives are consolidating vendor rosters for advanced wound care, displacing fragmented regional distributor networks with direct manufacturer agreements tied to outcome guarantees. This concentration is most visible in the United States, where integrated delivery networks in Texas and Florida are negotiating total-cost-of-care contracts spanning negative pressure systems through bioactive dressings.
Advanced Wound Therapy Devices Market Segmentation
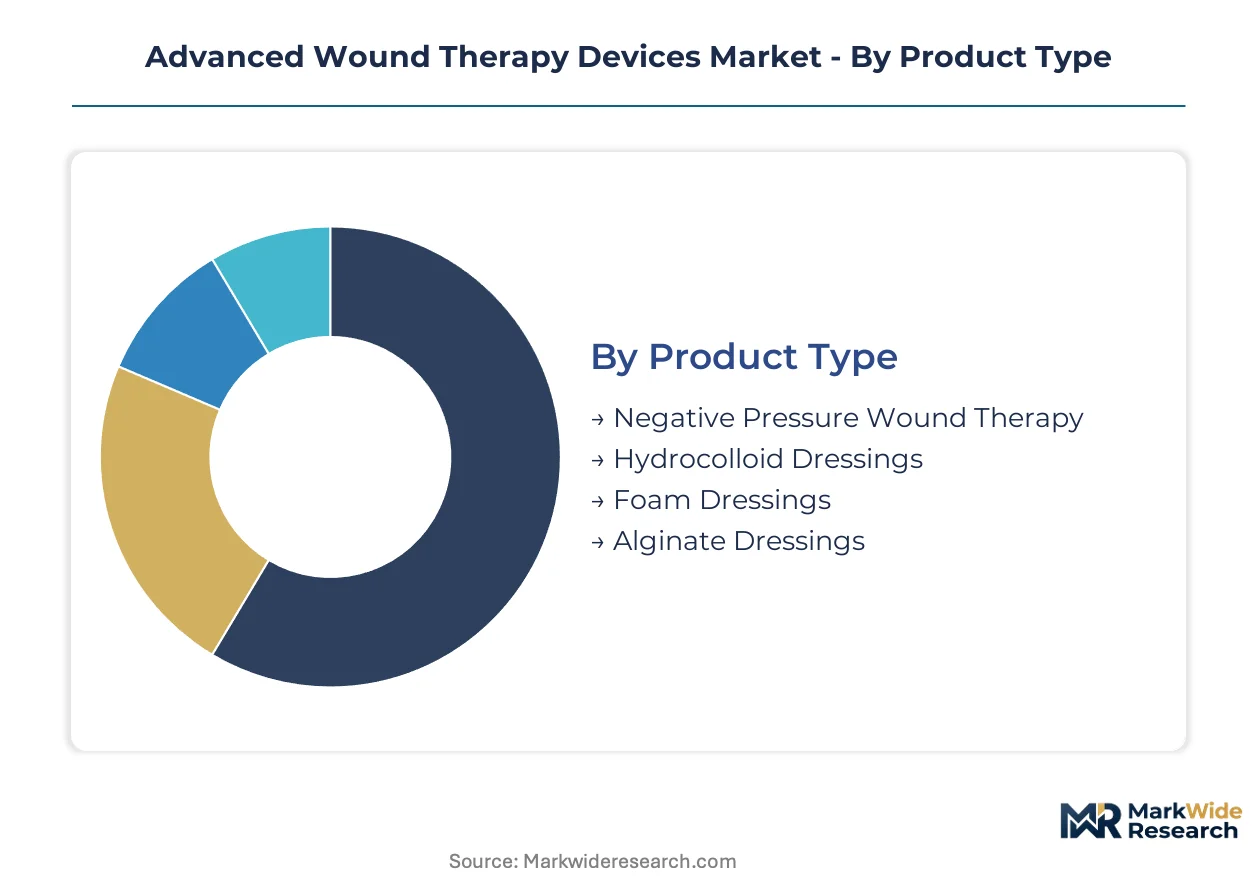
Segmentation in advanced wound therapy devices reveals distinct margin architectures and substitution vulnerabilities across product categories. Each dimension exposes divergent competitive pressures, reimbursement pathways, and end-user procurement behaviors that determine commercial positioning.
Product Type:
Substitution pressure from conventional gauze and commodity dressings weighs heaviest on segments lacking capital equipment lock-in or bioactive differentiation.
- Negative Pressure Wound Therapy:Electromechanical systems apply sub-atmospheric pressure through sealed foam or gauze interfaces to accelerate granulation tissue formation. Demand concentrates in United States ambulatory surgical centers where CMS reimbursement for portable units enables post-discharge revenue capture.
- Hydrocolloid Dressings:Gel-forming polymers like carboxymethylcellulose create moist healing environments for partial-thickness wounds. Long-term care facilities in Germany and Japan drive volume procurement through cost-per-change contracting that favors standardized application protocols over clinical complexity.
- Foam Dressings:Hydrophilic polyurethane matrices manage exudate in moderately draining wounds.
- Alginate Dressings:Calcium-sodium fiber dressings derived from brown seaweed address heavily exuding wound beds.
Negative Pressure Wound Therapy retains volume leadership; Hydrocolloid Dressings hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive institutional purchasers from price-sensitive decentralized settings.
- Hospitals:Integrated delivery networks negotiate enterprise contracts spanning multiple product categories with outcome guarantee clauses. United States hospital systems in Texas and Florida are consolidating vendor rosters through total-cost-of-care agreements that displace fragmented regional distributors.
- Home Healthcare:Portable negative pressure systems and simplified dressing protocols enable post-acute migration outside institutional walls. Medicare reimbursement reforms are compressing procurement cycles while expanding coverage for connected monitoring devices with telehealth integration.
- Long-Term Care Facilities:Nursing homes and skilled nursing facilities prioritize cost-per-change economics over clinical sophistication.
- Ambulatory Surgical Centers:Freestanding surgical facilities demand rapid-turnover dressing solutions with minimal nursing intervention.
Hospitals command absolute revenue share; Home Healthcare is climbing the fastest as reimbursement shifts site of care.
Application:
Application segmentation tracks wound etiology complexity and corresponding reimbursement intensity across clinical pathways.
- Chronic Wounds:Diabetic foot ulcers, venous leg ulcers, and pressure injuries require sustained therapeutic intervention over extended healing timelines. Podiatric surgery centers in the United States are adopting ultrasound therapy combined with bioactive dressings to displace debridement-only standards.
- Surgical Wounds:Post-operative incision management spans clean closed wounds to dehisced or infected sites requiring advanced intervention. Acute care hospitals in Germany pilot smart dressings with embedded pH sensors to reduce nursing assessment frequency while capturing infection onset earlier than visual inspection.
- Ulcers:Neuropathic and ischemic ulcers in diabetic populations drive specialized protocol development.
- Burn Care:Thermal and chemical injuries require biologic and synthetic skin substitutes with antimicrobial integration.
Chronic Wounds retains volume leadership; Surgical Wounds holds the steepest expansion curve.
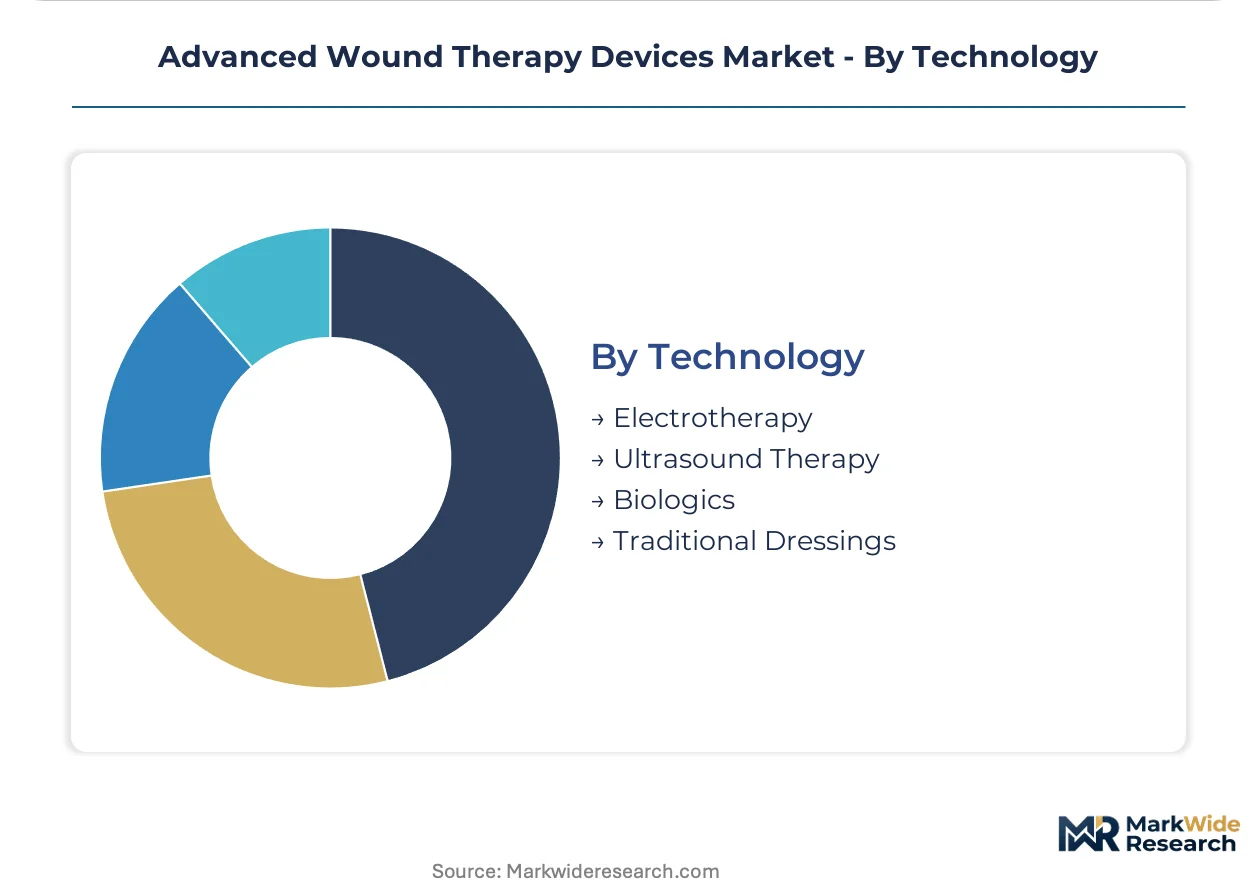
Technology:
Technology segmentation distinguishes electromechanical and energy-based modalities from passive material solutions.
- Electrotherapy:Low-frequency electrical stimulation promotes cellular migration and angiogenesis at wound beds. FDA 510(k) predicate divergence creates regulatory friction for novel modalities when no suitable predicate device exists in the database, extending development timelines for mid-cap device firms.
- Ultrasound Therapy:Low-intensity pulsed ultrasound accelerates healing through mechanotransduction and microstreaming effects. Bioelectronic manufacturing scale-up requires capital-intensive cleanroom expansion for printed circuit and flexible electrode production that strains mid-cap device firms.
- Biologics:Growth factors, skin substitutes, and cellular therapies command premium pricing in recalcitrant wound indications.
- Traditional Dressings:Gauze and basic non-adherent materials persist in cost-constrained settings despite clinical inferiority.
Traditional Dressings retains volume leadership; Ultrasound Therapy is gaining share fastest through podiatric protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement reforms in the United States are accelerating post-acute care migration toward home settings, while EU MDR compliance timelines reshape competitive access across European markets. FDA 510(k) pathways and EPA antimicrobial registration frameworks create distinct regulatory thresholds that fragment market entry strategies by geography.
United States
CMS reimbursement expansion for portable negative pressure systems drives procurement volume through home healthcare agencies and ambulatory surgical centers. FDA 510(k) predicate equivalence requirements compress development timelines for electromechanical devices with established clearance pathways. Hospital purchasing cooperatives in Texas and Florida consolidate vendor rosters through total-cost-of-care contracts that displace fragmented regional distributors.
Germany
Acute care hospitals pilot smart dressings with embedded pH sensors to reduce nursing assessment frequency while capturing infection onset earlier than visual inspection protocols. EU MDR clinical evidence requirements extend conformity assessment timelines for novel wound therapy devices, favoring manufacturers with existing predicate portfolios. Medical technology clusters in Bavaria and Baden-Württemberg concentrate R&D investment toward real-world evidence collection infrastructure.
United Kingdom
NHS England integrated care systems negotiate enterprise contracts spanning multiple product categories with outcome guarantee clauses that favor established manufacturers. MHRA post-Brexit regulatory alignment with EU MDR maintains CE marking recognition while preserving national divergence capacity. London and Southeast England health technology assessment bodies increasingly predicate market access on demonstrated cost-effectiveness against standard-of-care comparators.
Japan
PMDA accelerated approval pathways for combination device-biologic products compress development timelines for wound care innovators with domestic manufacturing partnerships. METI subsidies for medical device export capability expansion support premium positioning in Southeast Asian markets. Osaka-based medical device clusters concentrate production of hydrocolloid and foam dressing substrates for regional supply.
India
CDSCO medical device rules classification for negative pressure wound therapy systems creates distinct regulatory thresholds that favor multinational joint ventures over pure imports. PLI scheme incentives for domestic manufacturing of advanced medical electronics attract mid-cap device firms seeking cost-competitive production bases. Medical device parks in Gujarat and Karnataka concentrate assembly operations for export-oriented wound dressing production.
Advanced Wound Therapy Devices Market Vendor Landscape
Listed leaders compete with private specialists across capital equipment and consumable segments, creating tiered market access where scale advantages in negative pressure systems contrast with regional agility in dressing portfolios. Publicly traded manufacturers anchor enterprise contracts through integrated delivery networks, while private specialists capture niche indications through specialized formulation expertise. Three archetypes dominate: diversified medtech conglomerates with wound care divisions, pure-play wound management specialists, and regional dressing manufacturers with cost-optimized production. Competitive moves concentrate on M&A for technology access and vertical integration into medical-grade silicone feedstock to secure substrate supply.
Within the diversified medtech tier, Medtronic PLC and Smith & Nephew PLC exemplify scale-driven positioning through electromechanical system portfolios and ambulatory care channel dominance. Mölnlycke Health Care AB represents Scandinavian manufacturing-based premium positioning across European hospital networks. Among pure-play specialists, ConvaTec Group PLC and Coloplast A/S occupy positions defined by chronic care protocol integration and direct-to-institutional contracting relationships. 3M anchors the materials science archetype through substrate technology licensing and diversified adhesive platform applications.
| Leading Market Players |
|---|
| Mölnlycke Health Care AB |
| Medtronic PLC |
| Smith & Nephew PLC |
| B. Braun Melsungen AG |
| Medline Industries, Inc. |
| ConvaTec Group PLC |
| 3M |
| Integra LifeSciences |
| Coloplast A/S |
| Others |
Supply Flow & Price Mechanics
Capital equipment utilization rates at negative pressure wound therapy manufacturers in the United States and Germany determine minimum viable production scales that sustain premium pricing tiers while squeezing mid-tier competitors on margin coverage. These scale thresholds concentrate supply among electromechanical specialists with established FDA 510(k) portfolios, compressing price floors for portable systems as home healthcare procurement volumes expand.
Pricing Analysis
Certification level (FDA-grade vs. CE-marked vs. non-certified) creates the primary spread between premium electromechanical systems and commodity dressing alternatives. Three-tier pricing structure across capital equipment, advanced consumables, and basic dressings governs procurement contracts, with Medicare reimbursement intensity determining which tier dominates volume. Cost compression in hydrocolloid segments is intensifying because long-term care facilities negotiate consolidated purchasing agreements. Hospital integrated delivery networks exhibit lowest price sensitivity due to outcome-guarantee contracting, while rural home health agencies face acute budget constraints.
Supply Chain Analysis
Just-in-time inventory strategies dominate foam and hydrocolloid dressing procurement from contract manufacturers, whereas negative pressure system assemblers maintain strategic stockpiles of medical-grade silicone substrates against petrochemical volatility. Supply concentrates in Malaysia, Germany, and the United States for polyurethane foam matrices; China, Japan, and South Korea for printed circuit assemblies; and Thailand, India, and Belgium for alginate fiber processing. Single-source vulnerability in medical-grade silicone feedstock from concentrated Asian petrochemical suppliers threatens dressing substrate availability. Distribution runs through hospital purchasing cooperatives and group purchasing organizations that consolidate vendor rosters under total-cost-of-care agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of notified body relationships for EU MDR conformity assessments and FDA predicate device portfolios concentrates competitive advantage among established manufacturers, leaving capability gaps for novel electrotherapy and ultrasound modalities.
For Market Incumbents: Compound regulatory moats by deepening backward integration into medical-grade silicone substrate production and expanding real-world evidence collection infrastructure for post-market surveillance compliance. Electromechanical system commoditization from portable negative pressure entrants threatens premium positioning; defend through software companion development for remote monitoring integration and telehealth connectivity. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for predicate-equivalent portable negative pressure systems offer the most penetrable entry point for home healthcare reimbursement capture. Target rural counties in the United States with telehealth-integrated devices that satisfy CMS coverage expansion criteria. Go-to-market through direct contracting with home health agencies bypasses hospital purchasing cooperative consolidation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among negative pressure system manufacturers with locked-in canister consumable streams and hospital system service contracts. Long-term viability favors electromechanical specialists with software-enabled monitoring platforms over pure-play dressing manufacturers facing commodity substitution. Watch for Department of Veterans Affairs centralized procurement mandate awards as inflection indicators for federal supply schedule positioning strength.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Predicate equivalence accelerates clearance for portable negative pressure systems targeting CMS reimbursement expansion. |
| CE Marking Pathway | Notified body relationships under EU MDR compress development timelines for biologic-synthetic hybrid dressing innovators. |
| Hospital System Partnership | Integrated delivery networks in Texas and Florida consolidate vendor rosters through outcome-guarantee contracting. |
| Software Companion Development | HL7 FHIR compliance enables EHR integration for connected wound monitoring devices in acute care pilots. |
| Reimbursement Strategy | Medicare coverage determination alignment determines market access velocity for home-based negative pressure procurement. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with wound care clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body guidance documents. Bottom-up triangulation across product category volume estimates and top-down reconciliation against end-user expenditure patterns ensured consistency.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, end-user setting, wound etiology application, and technology modality including electromechanical, energy-based, and passive material solutions. CAGRs were derived from regression analysis of historical procurement trends and reimbursement intensity shifts. Forecast inputs incorporated Medicare site-of-care migration patterns and EU MDR compliance timeline compression effects.
The analysis sits within stated boundaries; outcomes outside sustained Medicare reimbursement expansion for home-based therapies or prolonged EU MDR notified body backlogs would require recalibration. Forecasts reflect assumptions regarding regulatory pathway efficiency and antimicrobial claim EPA registration stability. Revision becomes warranted when silicone feedstock pricing volatility crosses thresholds that compress mid-tier dressing margins below viable production economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
Wound Drainage Devices Market
Wound Care
Global Negative Pressure Wound Therapy (NPWT) Devices Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
South Korea Wound Care Management Market
Wound Care
Wound Closure Devices Market
Wound Care
Europe Compression Bandages Market
Wound Care
Wound Closure Market
Wound Care
Europe Wound Care Market
Wound Care
Japan Wound Care Management Devices Market
Wound Care
Wound Evacuators Market
Wound Care
Advanced Wound Dressings Market
Wound Care
Australia Wound Care Management Devices Market
Wound Care
Autologous Wound Patches Market
Wound Care
Maggot Debridement Market
Wound Care
Wound Healing Supplement Market