
 Global Venous Stents Market | 2026-2036
Global Venous Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Venous Stents Market Foresight
EU MDR is expanding the cost-of-entry calculus for venous stent manufacturers seeking CE marking in European markets. Boston Scientific Corporation leverages its broad interventional portfolio to sustain regulatory compliance across multiple jurisdictions. Medtronic plc anchors its venous franchise through deep vascular surgery relationships and integrated catheter-stent systems. Cook Medical differentiates via specialized venous expertise built over decades in complex iliocaval interventions.
Venous stents are laser-cut or braided metallic scaffolds, typically constructed from nitinol or cobalt-chromium alloys, designed to resist external compression and restore luminal patency in low-flow, high-compliance venous segments. Self-expanding stents dominate procedural volume due to their conformability against venous wall irregularities, while covered stents capture concentrated margin pools in cases requiring exclusion of thrombotic material or fistula management. The therapy area segmentation reveals chronic venous insufficiency and May-Thurner syndrome as the fastest-growing addressable populations, driven by expanded screening and minimally invasive treatment adoption.
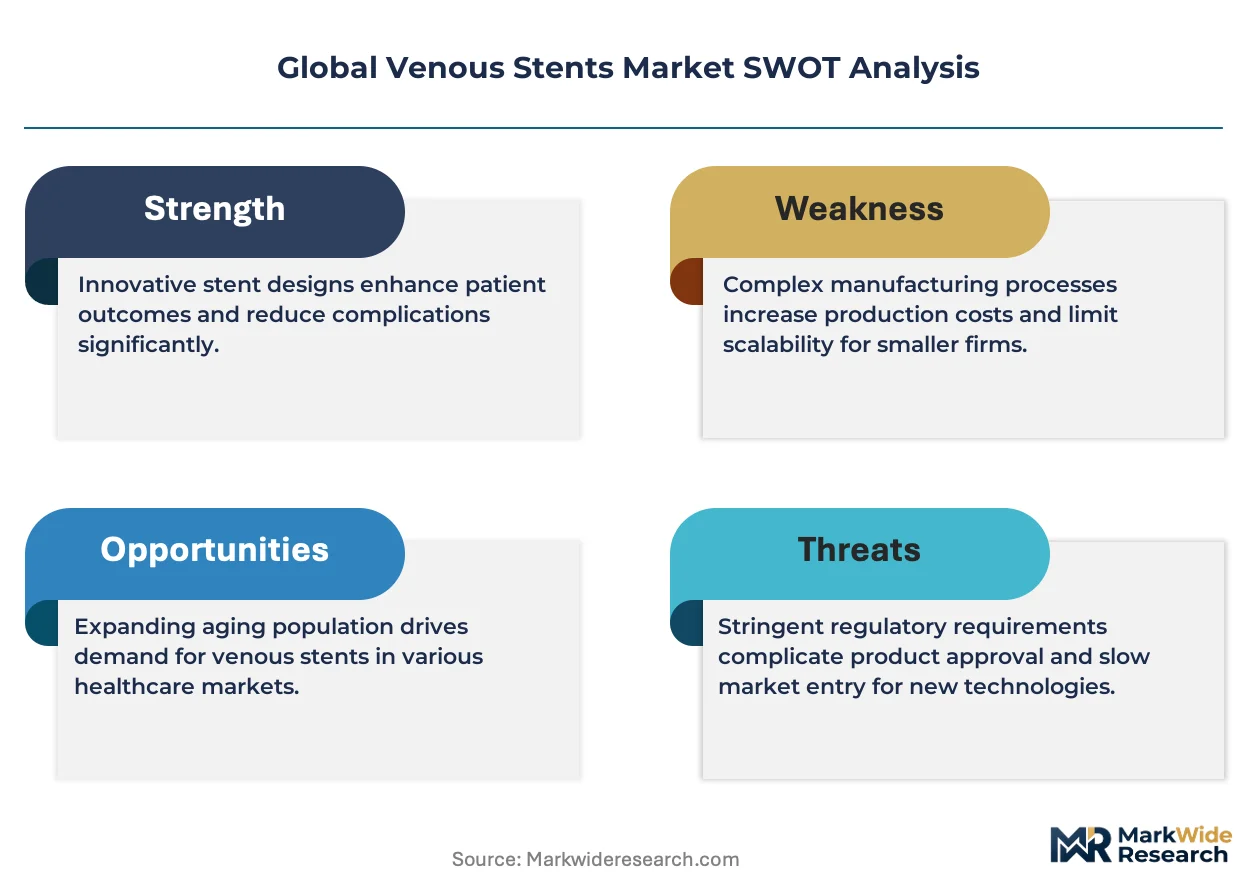
FDA premarket approval requirements, EU MDR technical documentation mandates, and Japan PMDA quality management system inspections collectively shape product development timelines and clinical evidence thresholds for market access. The FDA's emphasis on dedicated venous stent trials with patency endpoints is forcing manufacturers to invest in indication-specific evidence generation rather than relying on arterial stent data extrapolation. Stakeholders must monitor evolving reimbursement decisions for venous interventions across Medicare, national health systems, and private payers to anticipate volume shifts.
Market Dynamics
EU MDR technical documentation mandates are compressing product development timelines and forcing venous stent manufacturers to rebuild clinical evidence packages from arterial stent extrapolation toward dedicated venous patency trials. This regulatory inflection is reshaping competitive economics across European markets.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway accelerates commercial timelines for novel stent geometries targeting May-Thurner syndrome and chronic venous insufficiency, compressing review periods for predicate device innovators.
- Metropolitan Hospital Cluster Expansion:Interventional radiology suite investments in São Paulo and Mumbai concentrate procedural volume where chronic venous disease burden is rising fastest among working-age populations.
- Nitinol Alloy Conformability:Self-expanding scaffold designs resist external compression in low-flow venous segments, enabling same-day discharge protocols that reduce total episode costs.
Market Restraints
- EU MDR Cost Escalation:The regulation expands cost-of-entry calculus for CE marking through enhanced clinical evaluation requirements and notified body capacity constraints.
- Nitinol Raw Material Concentration:Supply of nickel-titanium shape-memory alloy concentrates among specialty metallurgical suppliers, creating input cost volatility for laser-cut stent manufacturers.
- Reimbursement Uncertainty:Medicare coverage determinations for venous interventions remain inconsistent across MAC jurisdictions, creating volume forecasting friction for hospital purchasers.
Strategic Opportunities
- Brazilian Public Hospital Modernization:SUS system investments in interventional radiology create procurement windows for venous stent suppliers targeting Latin America's largest addressable population.
- Covered Stent Fistula Management:Exclusion of thrombotic material in dialysis access maintenance represents an emerging application with concentrated margin pools.
- Integrated Catheter-Stent Systems:Convergence of delivery platform engineering with scaffold design enables single-procedure venous recanalization workflows.
Industry Challenges
- Venous-Specific Trial Design Expertise:Clinical affairs teams lack experience designing patency endpoint studies for low-flow vascular beds, extending regulatory submission preparation timelines.
- Legacy ERP Integration:EU MDR unique device identification requirements force supply chain system reconfigurations that disrupt batch release workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Venous Stents Market |
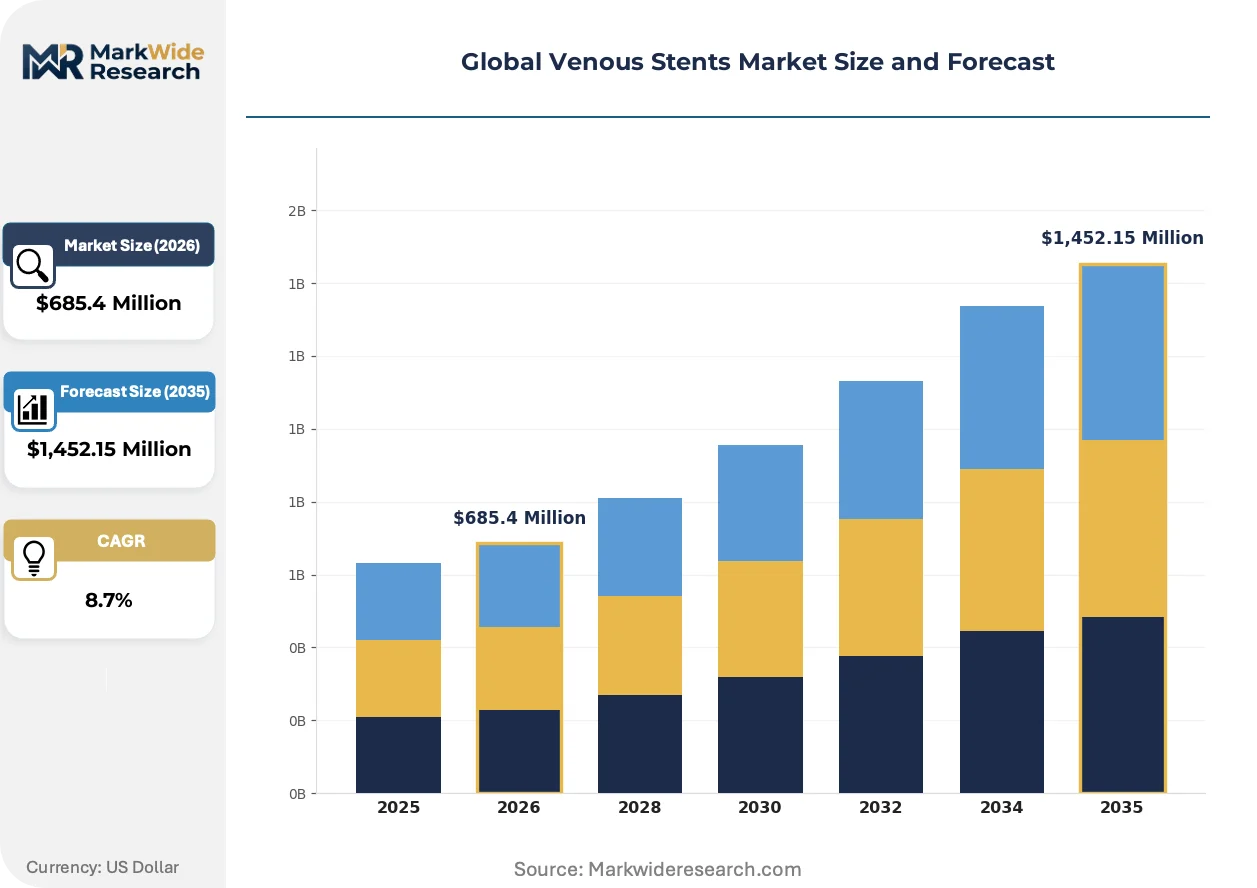
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Expanding Stents, Balloon-Expandable Stents, Covered Stents, Drug-Eluting Stents Therapy Area: Deep Vein Thrombosis, Chronic Venous Insufficiency, May-Thurner Syndrome, Superior Vena Cava Syndrome, Other Venous Disorders End User: Cardiology Centers, Vascular Surgery Units, Diagnostic Laboratories, Specialized Clinics Distribution Channel: Direct Sales, Medical Distributors, Online Pharmacies, Hospitals Procurement, Third-Party Logistics |
| Companies Covered | Boston Scientific Corporation, Medtronic plc, Cook Medical, Becton, Dickinson and Company, W. L. Gore & Associates, Abbott Laboratories, Bentley InnoMed GmbH, Optimed Medizinische Instrumente GmbH, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Venous Stents Market Shifts & Advancements
Bioresorbable scaffold research and drug-eluting surface engineering are converging to redefine durability expectations in venous interventions. These material science advances promise to compress revision procedure rates.
Laser-cut nitinol stents with helical strut geometries are electrifying venous wall apposition in tortuous iliac and femoral segments. Academic medical centers in Germany and the United States are adopting these designs for complex chronic venous insufficiency cases. The technology is electrifying competitive positioning around conformability metrics that arterial-derived scaffolds cannot match.
Japan PMDA quality management system inspections are tightening documentation requirements for foreign manufacturers seeking market access. The policy shift forces dedicated venous stent trials with Japanese patient cohorts rather than bridging from US or European data. Small-to-mid cap manufacturers are responding by partnering with domestic distributors to navigate QMS certification timelines.
Hospital value analysis committees are consolidating purchasing authority for interventional devices previously acquired through individual physician preference. Integrated delivery networks in the United States are replacing fragmented procurement with standardized vendor contracts across cath lab portfolios. This concentration is most visible in metropolitan clusters where health system consolidation has advanced furthest.
Global Venous Stents Market Segmentation
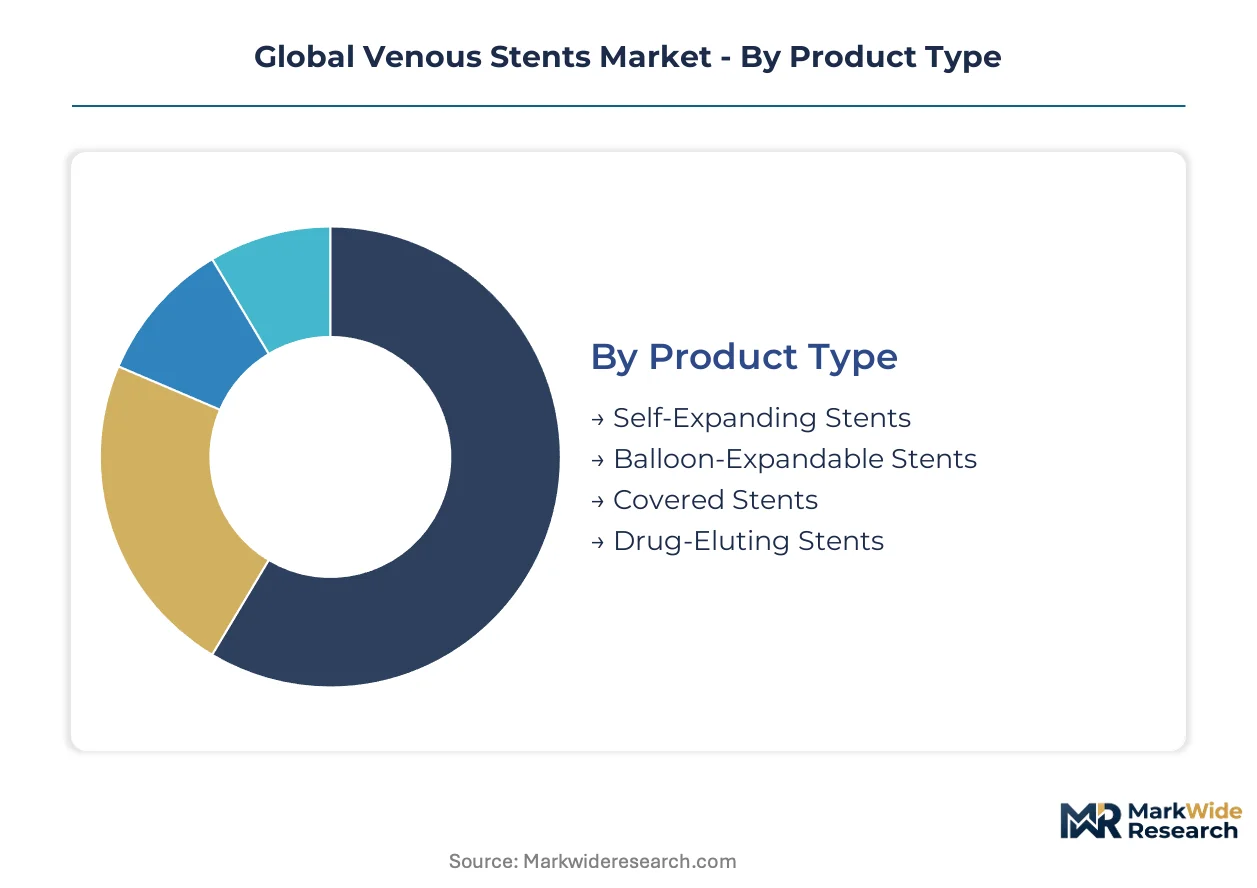
Venous stent segmentation reveals distinct procurement patterns across acute intervention versus chronic disease management pathways. Product design specifications diverge sharply between self-expanding conformable scaffolds for tortuous venous anatomy and covered configurations for thrombotic exclusion. Understanding these segment boundaries enables targeted evidence generation and reimbursement positioning.
Product Type:
Customization intensity varies from standardized laser-cut nitinol platforms to highly engineered covered configurations with proprietary polymer formulations.
- Self-Expanding Stents:Nitinol shape-memory alloys provide radial force against external compression in low-flow venous segments. Demand concentrates in German and US hospital clusters where same-day discharge protocols reduce total episode costs for chronic venous insufficiency interventions.
- Covered Stents:Expanded polytetrafluoroethylene or polyester membranes exclude thrombotic material and seal fistula communications. Metropolitan hospital clusters in São Paulo and Mumbai prioritize these configurations for dialysis access maintenance where margin pools concentrate.
- Balloon-Expandable Stents:Stainless steel or cobalt-chromium platforms deliver precise diameter control in calcified venous segments. Applications remain limited to central venous obstructions.
- Drug-Eluting Stents:Sirolimus or paclitaxel coatings target neointimal hyperplasia in recurrent stenosis cases. Clinical evidence requirements from FDA and PMDA constrain commercial timelines.
Leading the category by volume: Self-Expanding Stents. Growing fastest: Covered Stents.
Therapy Area:
Procedure volume scales with disease prevalence screening infrastructure and interventional radiology suite availability across hospital systems.
- Chronic Venous Insufficiency:Progressive venous hypertension drives limb swelling and ulceration in working-age populations. German academic medical centers and US integrated delivery networks are expanding dedicated venous programs with specialized stent inventories.
- May-Thurner Syndrome:Left common iliac vein compression by the right common iliac artery predominantly affects women. FDA breakthrough device designation pathways are accelerating commercial access for novel stent geometries targeting this indication.
- Deep Vein Thrombosis:Acute thrombotic occlusion requires pharmacomechanical intervention with optional stent placement for underlying anatomic lesions. Procedure volumes track anticoagulation therapy failure rates.
- Superior Vena Cava Syndrome:Malignant obstruction demands rapid palliative stenting with covered configurations. Cancer center procurement drives concentrated demand.
- Other Venous Disorders:Nutcracker syndrome, pelvic congestion, and rare congenital anomalies comprise heterogeneous indications with limited dedicated device development.
Volume leadership resides with Chronic Venous Insufficiency. Steepest expansion trajectory belongs to May-Thurner Syndrome.
End User:
Site-of-care economics shape stent selection criteria from capital-intensive catheterization laboratories to outpatient procedural suites.
- Vascular Surgery Units:Operating room-based interventions combine open and endovascular techniques. Deep relationships with manufacturers anchor procurement loyalty for integrated catheter-stent systems.
- Cardiology Centers:Existing arterial intervention infrastructure repurposes for venous procedures with additional training requirements. Volume growth depends on cross-specialty credentialing pathways.
- Specialized Clinics:Ambulatory surgical centers focus on select chronic venous insufficiency cases with streamlined reimbursement. Device selection prioritizes cost efficiency over technology sophistication.
- Diagnostic Laboratories:Imaging-confirmed disease identification triggers referral pathways rather than direct intervention. Influence on stent selection is indirect through physician network relationships.
Procurement concentration: Vascular Surgery Units. Fastest volume migration: Cardiology Centers.
Distribution Channel:
Supply chain configuration determines inventory carrying costs and emergency procedure responsiveness across hospital networks.
- Direct Sales:Manufacturer field inventory programs support high-volume academic medical centers with consignment arrangements. Boston Scientific and Medtronic deploy dedicated venous specialists to major metropolitan clusters.
- Medical Distributors:Regional warehouses buffer smaller hospitals from minimum order quantities and extended lead times. Brazilian and Indian markets rely heavily on distributor networks for geographic coverage.
- Hospitals Procurement:Value analysis committees consolidate purchasing authority across integrated delivery networks in the United States. Standardized vendor contracts replace individual physician preference.
- Third-Party Logistics:Temperature-controlled transport and serialization tracking satisfy EU MDR unique device identification requirements.
- Online Pharmacies:Limited relevance for implantable devices due to regulatory restrictions on direct-to-patient distribution.
Dominant channel by revenue: Direct Sales. Expanding most quickly: Hospitals Procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement in Germany and the United States concentrates demand for venous stents, while metropolitan clusters in India and Brazil generate the fastest procedural volume expansion for chronic venous disease interventions.
United States
Integrated delivery networks in metropolitan hospital clusters drive consolidated purchasing for interventional radiology suites. FDA breakthrough device designation pathways compress commercial timelines for novel stent geometries. Academic medical centers in Boston and Houston anchor clinical evidence generation for May-Thurner syndrome indications.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia expand dedicated venous programs with specialized stent inventories. EU MDR technical documentation mandates reshape clinical evaluation requirements for CE marking renewal. Frankfurt and Munich hospital clusters prioritize same-day discharge protocols for chronic venous insufficiency interventions.
Brazil
São Paulo metropolitan hospital clusters concentrate procedural volume where chronic venous disease burden rises fastest among working-age populations. ANVISA regulatory pathways govern market access for imported stent systems. Public hospital modernization through SUS system investments creates procurement windows for interventional radiology equipment.
India
Mumbai and Delhi-NCR hospital clusters drive demand as chronic venous disease screening infrastructure expands. CDSCO medical device regulations require local clinical trials for stent registration beyond predicate device pathways. Private hospital chains in Maharashtra and Karnataka invest in interventional radiology suites for venous procedures.
Japan
PMDA quality management system inspections tighten documentation requirements for foreign manufacturers seeking market access. Dedicated venous stent trials with Japanese patient cohorts replace bridging from US or European data. Tokyo and Osaka academic medical centers adopt self-expanding nitinol designs for complex iliac vein interventions.
Global Venous Stents Market Competitive Landscape
United States producers anchor the premium-tier segment; German specialists hold engineering-intensive niches. The vendor base concentrates around diversified interventional portfolios and dedicated venous expertise. Three archetypes dominate: diversified medtech conglomerates with broad regulatory compliance infrastructure, mid-cap specialists with decades of venous intervention focus, and integrated catheter-stent system engineers. Competitive moves center on EU MDR evidence package rebuilding and metropolitan hospital cluster direct sales deployment.
Within the diversified conglomerate tier, Boston Scientific Corporation and Medtronic plc occupy positions sustained by multi-jurisdictional regulatory compliance and deep vascular surgery relationships. Cook Medical exemplifies the specialized venous expertise archetype built through decades of complex iliacaval intervention focus. These three anchors represent distinct strategic postures: broad portfolio leverage, integrated system convergence, and indication-specific depth.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic plc |
| Cook Medical |
| Becton, Dickinson and Company |
| W. L. Gore & Associates |
| Abbott Laboratories |
| Bentley InnoMed GmbH |
| Optimed Medizinische Instrumente GmbH |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
Self-expanding nitinol stents and covered polymer-membrane configurations diverge sharply in both pricing architecture and sourcing complexity, with the former drawing from standardized laser-cut platforms and the latter resting on specialized membrane lamination processes that concentrate manufacturing expertise among German and US suppliers.
Pricing Analysis
Volume leadership sits with self-expanding nitinol platforms while margin concentration belongs to covered configurations for dialysis access and thrombotic exclusion. Price differentiation hinges on CE marking tier under EU MDR and FDA breakthrough designation status, with premium tiers commanding substantial markups for dedicated venous trial evidence. Cost compression in standard nitinol segments is intensifying because Brazilian and Indian procurement consolidation favors commoditized specifications. Public hospital systems in São Paulo and Mumbai exhibit the highest price sensitivity, whereas German academic medical centers prioritize conformability metrics over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with specialty nickel-titanium shape-memory alloy suppliers concentrated in the United States, Germany, and Japan. Nitinol feedstock, expanded polytetrafluoroethylene membranes, and cobalt-chromium tubing constitute critical input dependencies. Tariff exposure on precision metallurgical imports from Asia threatens margin stability for laser-cut manufacturers. Distribution runs through manufacturer field inventory programs for high-volume academic centers, with regional distributors buffering smaller hospitals in Brazil and India from minimum order constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The venous stents market is transitioning from arterial-derived predicate devices toward indication-specific scaffold geometries, with helical strut nitinol designs displacing legacy platforms in complex iliac and femoral interventions.
For Market Incumbents: Acquire dedicated venous trial datasets to preempt EU MDR evidence package requirements. Deepen catheter-stent system integration to defend against mid-cap specialists with decades of iliocaval expertise. Anchor procurement loyalty through consignment inventory programs at metropolitan hospital clusters in Germany and the United States. For New Entrants and Emerging Players: Capture SUS modernization procurement windows in São Paulo before diversified conglomerates deploy dedicated venous specialists. Target Brazilian public hospital clusters where chronic venous disease burden rises fastest among working-age populations. Partner with domestic distributors to navigate ANVISA regulatory pathways and bypass direct QMS certification timelines. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap venous specialists given FDA breakthrough designation acceleration for May-Thurner syndrome indications. Long-term viability centers on indication-specific evidence generation capability over arterial stent data extrapolation. Watch Medicare coverage determination consistency across MAC jurisdictions as the inflection signal for volume forecasting reliability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pathway | Compresses commercial timelines for novel stent geometries targeting May-Thurner syndrome indications. |
| EU MDR Technical Documentation Rebuild | Forces transition from arterial predicate data toward dedicated venous patency trials for CE marking. |
| Metropolitan Hospital Cluster Direct Sales | Deploys field inventory consignment at academic medical centers in Boston, Houston, and Munich. |
| Integrated Catheter-Stent System Development | Enables single-procedure venous recanalization workflows for chronic venous insufficiency cases. |
| Brazilian SUS Procurement Engagement | Captures modernization investment windows in São Paulo interventional radiology suite expansion. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, GPO contracts managers, and biomedical engineers underwrites the qualitative findings in this study. Primary fieldwork with interventional radiologists, vascular surgeons, and regulatory affairs leads at device manufacturers combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation summaries, and hospital procurement databases. Bottom-up procedure volume modeling and top-down market sizing triangulate demand estimates across the analysis window.
Comparable-period anchoring to historical venous intervention volumes and stent placement rates informed the projection framework. Segmentation dimensions span product type, therapy area, end-user site of care, and distribution channel configuration. CAGRs were derived from procedure volume elasticity to screening infrastructure expansion and interventional radiology suite investment cycles. Forecast inputs incorporate EU MDR transition timelines and Medicare coverage determination patterns without specific year attribution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nitinol raw material supply concentration and reimbursement policy shifts across national health systems. Deviation in FDA breakthrough designation review velocity or notified body capacity constraints under EU MDR would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
Medical Bionic Implants and Exoskeletons Market
Medical Devices
Spine Surgery Robots Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
Europe Breast Implant Market
Medical Devices
Global Digital Therapeutic Devices Market
Medical Devices
Prescription Goggles Market
Medical Devices
Global Medical Device Labeling Market
Medical Devices
Asia-Pacific Ultrasound Devices Market
Medical Devices
Pocket Otoscope Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Laser BPH Devices Market
Medical Devices
Thoracolumbar Spine Devices Market
Medical Devices
North America Electroencephalography Devices Market
Medical Devices
Cyberknife Market