
 Medical Oxygen Gas Cylinder Market | 2026-2036
Medical Oxygen Gas Cylinder Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Oxygen Gas Cylinder Market Intelligence
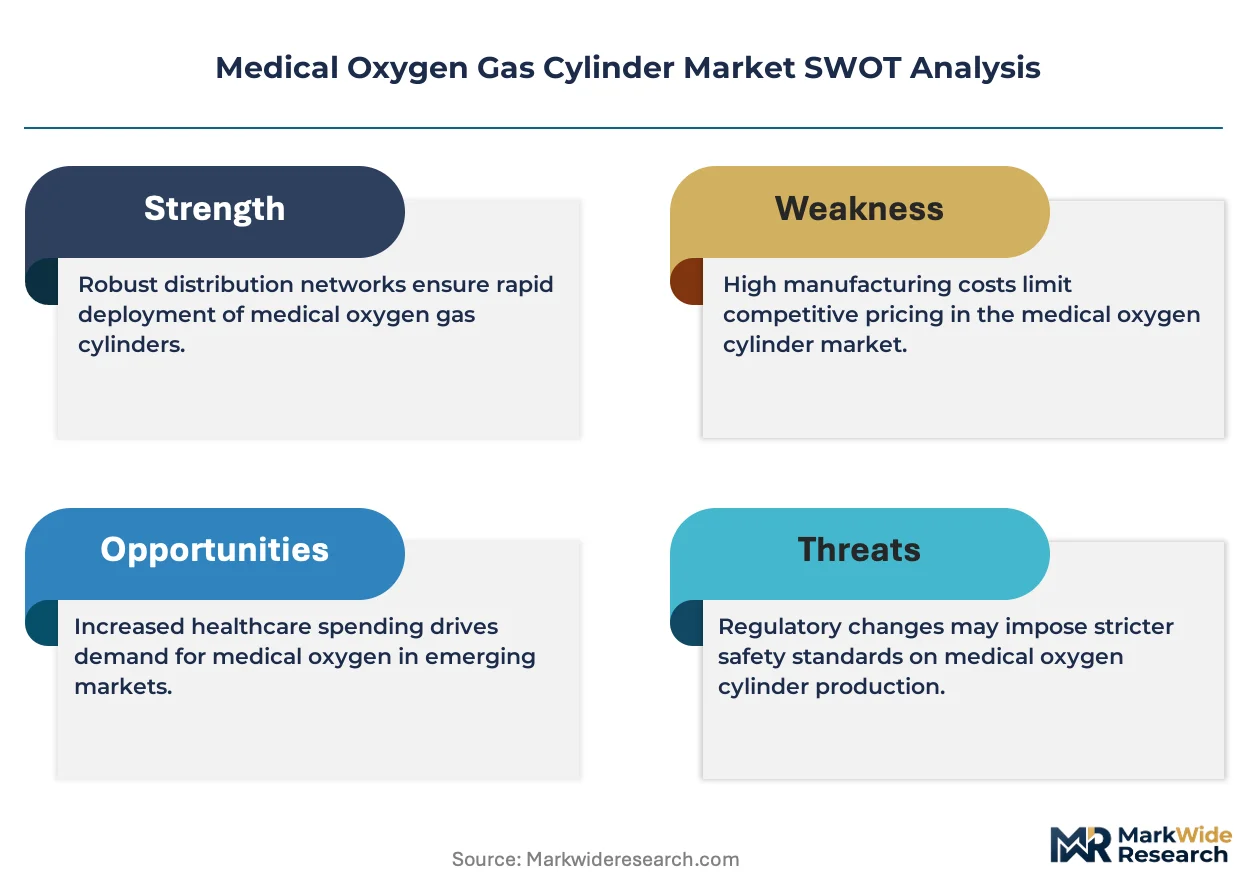
Multi-source procurement for medical oxygen gas cylinders is broadening across hospital systems and home care distributors seeking supply chain resilience. Linde plc leverages its integrated gas production and cylinder distribution network to sustain delivery reliability across fragmented regional markets. Faber Industrie anchors European manufacturing scale through specialized high-pressure seamless cylinder production. Catalina Cylinders differentiates via precision aluminum extrusion capabilities that serve portable oxygen demand in North American home care channels.
A medical oxygen gas cylinder is a pressurized vessel constructed from aluminum alloy, carbon steel, or composite materials, designed to store and dispense oxygen at pressures typically ranging from 2,000 to 3,000 psi for therapeutic respiratory support. Fabrication methods include seamless extrusion, deep drawing, and filament winding for composite overwrap designs, with each process dictating weight-to-capacity ratios critical for patient mobility and clinical throughput. Portable cylinders now capture the fastest-expanding margin pool as home care and ambulance services prioritize lightweight designs that extend patient ambulation time, while stationary cylinders retain dominant volume share in hospital bulk storage installations where capacity and durability outweigh mobility requirements. Liquid oxygen containers serve a narrower but structurally defended niche in high-consumption clinical settings where vaporization systems reduce refill frequency.
The FDA enforces container integrity and labeling standards under 21 CFR Part 868 that govern oxygen cylinder material certification and pressure testing protocols, while ISO 9809 and ISO 7866 define international manufacturing benchmarks for seamless steel and aluminum cylinders that shape export market access. India's BIS certification requirements and CDSCO medical device rules add compliance layers for imported cylinder assemblies entering one of the fastest-expanding procurement jurisdictions. Stakeholders must monitor evolving composite material approvals and transport safety regulations as cylinder lightweighting trends accelerate across home care and emergency service applications.
Market Dynamics
The migration of oxygen therapy from acute care facilities into residential settings is compressing demand patterns and forcing manufacturers to reconfigure product portfolios around portability and patient self-management capabilities.
Growth Catalysts
- India's PLI scheme for medical devices:Domestic production incentives are drawing fresh manufacturing investment into high-pressure seamless cylinder fabrication, reducing import dependency for rural health infrastructure expansion.
- Home care services:Post-acute respiratory patients now receive extended oxygen therapy outside hospital walls, creating sustained replacement demand for lightweight portable units.
- Composite overwrap technology:Filament-wound carbon fiber cylinders are cutting vessel weight by half versus aluminum equivalents, enabling longer ambulation times for chronic obstructive pulmonary disease patients.
Market Restraints
- High-grade aluminum alloy supply concentration:Aerospace and automotive sectors compete for the same 6061-T6 and 7068-T6511 extrusion feedstock, creating input cost volatility for cylinder manufacturers.
- Liquid oxygen systems:Bulk vaporization installations in high-consumption hospitals present a durable substitute threat for gaseous cylinder storage, particularly where refill logistics prove cumbersome.
- ISO 9809 testing protocols:International pressure vessel certification requires destructive hydrostatic testing that extends production cycles and limits rapid scaling for new market entrants.
Strategic Opportunities
- Rural India:Underpenetrated district hospital networks and ASHA worker deployment programs represent untapped procurement volume for portable cylinder units with integrated flow regulators.
- Drone-enabled emergency delivery:Last-mile distribution partnerships with aerial logistics providers could bypass road infrastructure gaps in mountainous and flood-prone regions.
- FDA composite material approvals:Anticipated updates to 21 CFR Part 868 for fiber-reinforced pressure vessels would unlock premium pricing for next-generation lightweight designs in North American home care channels.
Industry Challenges
- Composite pressure vessel engineering talent:Filament winding process optimization and finite element analysis for burst prediction require specialized expertise that remains concentrated in aerospace supply chains.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of FDA 510(k), BIS IS 7285, and CE marking under MDR creates sequential approval bottlenecks that delay product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Oxygen Gas Cylinder Market |
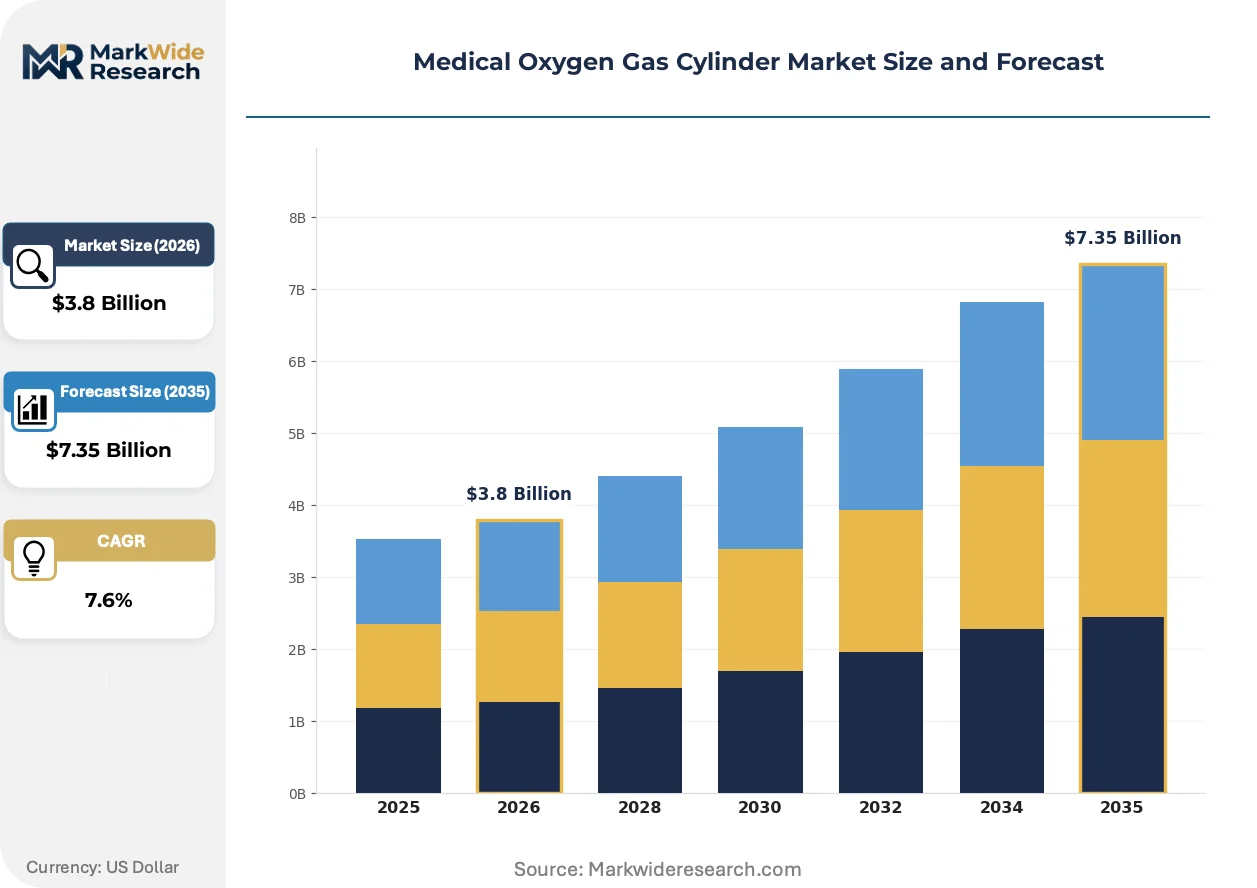
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Cylinder, Stationary Cylinder, Liquid Oxygen Containers, Bulk Tanks Application: Home Care, Hospitals, Emergency Services, Industrial End User: Healthcare Providers, Individuals, Ambulance Services, Research Facilities Delivery Mode: Duty-Cycle, Continuous-Flow, Pulse-Dose, Variable-Flow |
| Companies Covered | Catalina Cylinders, Faber Industrie, Linde plc, AMS Composite Cylinders, Chart Industries, Air Liquide, Worthington Industries, Taiyo Nippon Sanso Corporation, Luxfer Gas Cylinders, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Oxygen Gas Cylinder Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory modernization are converging to redefine cylinder performance standards, while patient mobility requirements are redrawing competitive boundaries between portable and stationary product categories.
Filament-wound carbon fiber composite cylinders are electrifying the portable oxygen segment by slashing vessel weight while maintaining 3,000 psi operating pressure. Ambulance services and home care distributors in Germany and Japan are accelerating procurement of these units to extend patient transport range. The technology is electrifying margin structures by commanding 40-60% price premiums over aluminum equivalents while compressing replacement cycles through improved patient compliance.
REACH regulation amendments governing persistent organic pollutants are tightening restrictions on certain epoxy resin systems used in composite overwrap manufacturing. European cylinder fabricators must reformulate matrix materials or source alternative chemistries to maintain CE marking validity. High-pressure seamless steel cylinder exporters targeting EU medical device markets face the most acute compliance pressure, with reformulation timelines extending through 2027.
Subscription-based cylinder exchange programs are displacing traditional capital purchase models in North American home care channels. Durable medical equipment suppliers now bundle delivery, maintenance, and refill logistics into per-patient monthly fees, unbundling hardware ownership from therapeutic service provision. This restructuring is most visible in Florida and Texas, where large respiratory therapy networks are consolidating procurement decisions across hundreds of branch locations.
Medical Oxygen Gas Cylinder Market Segmentation
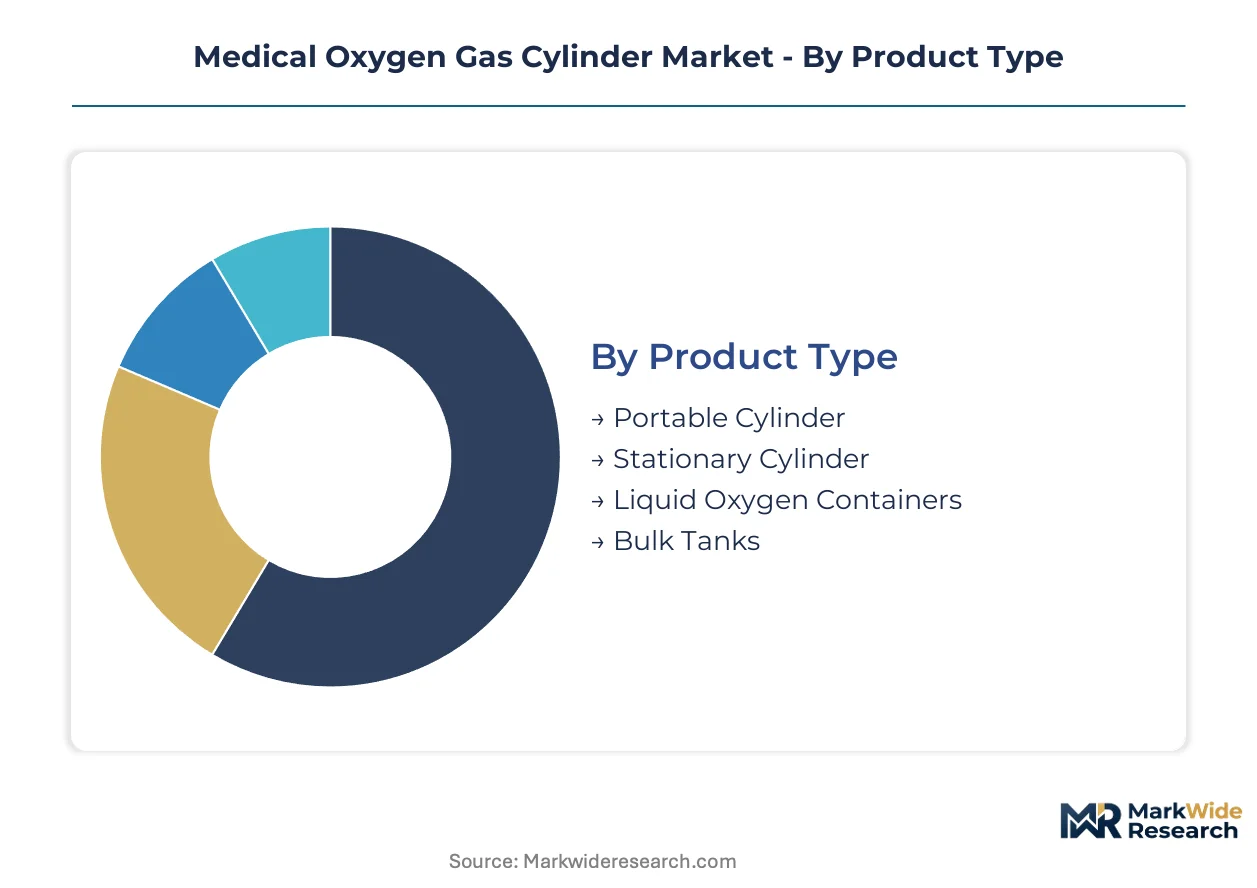
Segmentation in the medical oxygen gas cylinder market reveals how patient mobility requirements, care settings, and oxygen delivery protocols create distinct procurement patterns across manufacturers. Each dimension shapes material selection, pressure specifications, and regulatory compliance pathways differently.
Product Type:
Buyers differentiate by weight-to-capacity ratios and refill logistics rather than oxygen chemistry alone.
- Portable Cylinder:Aluminum alloy or composite vessels weighing 3-6 pounds store oxygen at 2,000-3,000 psi for patient ambulation. Demand concentrates in North American home care channels where Medicare reimbursement favors lightweight designs that extend daily activity windows for COPD patients.
- Stationary Cylinder:Large-capacity steel or aluminum units provide continuous flow for bedridden patients. Hospital bulk storage installations in India and Germany prioritize these units where capacity and durability outweigh mobility requirements.
- Liquid Oxygen Containers:Vacuum-insulated vessels store oxygen in cryogenic liquid form at -183°C, reducing refill frequency for high-consumption clinical settings.
- Bulk Tanks:Centralized storage systems serve multi-bed hospital wards and industrial gas distribution hubs with vaporization capabilities.
Volume sits with stationary cylinders; growth tilts toward portable units.
Application:
Procurement scale and reimbursement pathways diverge sharply between institutional buyers and dispersed residential settings.
- Home Care:Post-acute respiratory patients receive extended oxygen therapy outside hospital walls, creating sustained replacement demand for lightweight portable units with integrated flow regulators.
- Hospitals:Acute care facilities require both portable units for patient transport and stationary cylinders for ward-level backup, with procurement decisions centralized through group purchasing organizations.
- Emergency Services:Ambulance fleets and first responder units prioritize rapid cylinder exchange protocols and ruggedized valve designs for field reliability.
- Industrial:Welding, cutting, and metal fabrication operations consume medical-grade oxygen for precision applications, though this segment faces substitution from on-site oxygen generation systems.
Hospital procurement dominates current volume; home care applications are climbing the fastest.
End User:
Purchasing authority and technical specification knowledge vary dramatically across buyer types.
- Healthcare Providers:Hospital systems and clinics leverage volume contracts to negotiate cylinder lease arrangements and consolidated maintenance services.
- Individuals:Medicare and private insurance reimbursement shapes direct-to-patient sales for home oxygen therapy, with copayment structures influencing aluminum versus composite material selection.
- Ambulance Services:Fleet operators prioritize rapid-fill valve designs and standardized mounting brackets across vehicle platforms to minimize turnaround times.
- Research Facilities:Laboratories and biotechnology operations require ultra-high-purity oxygen delivery with specialized contamination controls for cell culture and analytical applications.
Healthcare providers command the largest procurement volumes; individual purchases show the steepest expansion trajectory.
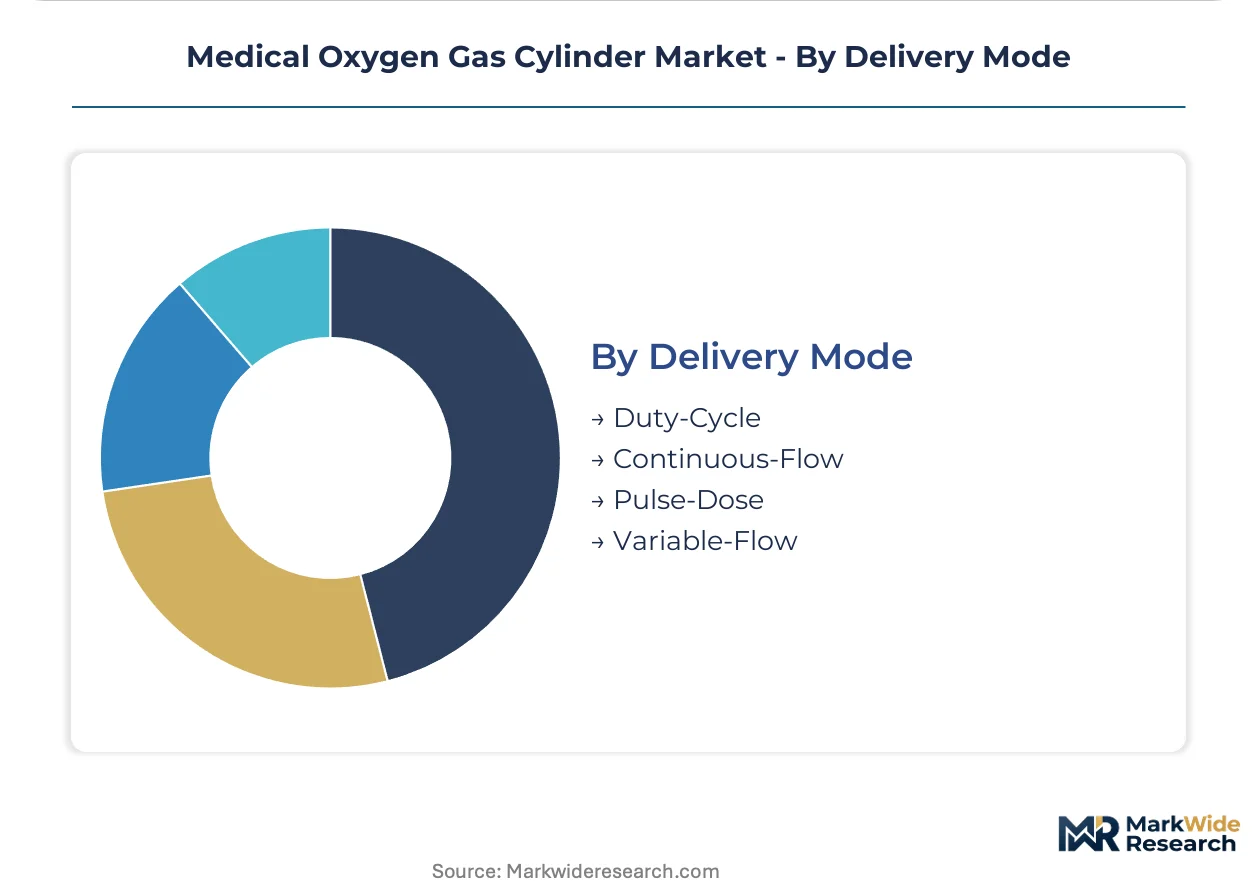
Delivery Mode:
Oxygen conservation technology determines cylinder size requirements and refill frequency for chronic patients.
- Duty-Cycle:Intermittent delivery synchronized with inhalation phases extends cylinder duration by 3-5x versus continuous flow, enabling smaller portable units for active patients.
- Continuous-Flow:Uninterrupted oxygen delivery at fixed liter-per-minute rates remains standard for stationary bedside applications and severe hypoxemia cases.
- Pulse-Dose:Electronic sensors trigger oxygen release at the start of inhalation, conserving gas for ambulatory patients with moderate respiratory insufficiency.
- Variable-Flow:Automated adjustment based on activity detection or SpO2 feedback optimizes conservation across sleep, rest, and exertion states.
Continuous-flow systems retain dominant installed base; pulse-dose configurations gain share fastest in portable applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-grade aluminum extrusion feedstock from South Korean and Chinese smelters underpins cylinder manufacturing across major demand centers. The report tracks procurement intensity across five national markets where oxygen therapy infrastructure is expanding fastest.
United States
Medicare reimbursement for portable oxygen concentrators and cylinders drives home care procurement volume. FDA maintains 21 CFR Part 868 standards for pressure vessel integrity and labeling. Manufacturing clusters in Ohio and Pennsylvania produce seamless aluminum cylinders for domestic distribution and Canadian export markets.
Germany
Ambulance fleet modernization and aging demographics sustain demand for lightweight composite transport cylinders. REACH amendments on epoxy resin systems force reformulation of composite overwrap matrix materials by 2027. Industrial gas specialists in Bavaria and North Rhine-Westphalia coordinate filament-wound cylinder production for EU medical device markets.
India
Rural health infrastructure expansion under the National Health Mission creates procurement pull for portable units with integrated flow regulators. The PLI scheme for medical devices draws investment into high-pressure seamless cylinder fabrication. Manufacturing activity concentrates in Gujarat and Maharashtra where domestic aluminum rolling capacity supports vertical integration.
Japan
Hyper-aged population demographics and home oxygen therapy reimbursement sustain replacement demand for compact portable designs. METI oversees industrial gas safety standards alignment with ISO 9809 protocols. Precision cylinder fabricators in the Chubu region supply filament-wound units for ambulance and emergency service applications.
Brazil
Universal health system expansion into Amazonian municipalities drives demand for ruggedized portable cylinders suited to riverine transport. ANVISA regulates medical gas container certification parallel to ISO 7866 benchmarks. São Paulo-based distributors coordinate last-mile logistics for hospital systems across the Southeast region.
Medical Oxygen Gas Cylinder Market Key Industry Players
Global majors compete with regional champions across integrated gas production versus specialized cylinder fabrication. The market structure splits between consolidated industrial gas conglomerates with captive cylinder operations and fragmented regional metal-forming specialists. Three archetypes dominate: integrated gas-cylinder conglomerates, precision aluminum extrusion specialists, and composite overwrap technology licensors. Capacity expansion and strategic partnerships represent the dominant competitive moves as players position for home care segment growth.
Among integrated gas-cylinder conglomerates, Linde plc and Air Liquide exemplify the vertical control archetype spanning production through distribution. Precision aluminum fabricators include Catalina Cylinders, which occupies a position serving North American portable oxygen demand. Faber Industrie represents European-scale seamless cylinder specialization for high-pressure medical applications.
| Leading Market Players |
|---|
| Catalina Cylinders |
| Faber Industrie |
| Linde plc |
| AMS Composite Cylinders |
| Chart Industries |
| Air Liquide |
| Worthington Industries |
| Taiyo Nippon Sanso Corporation |
| Luxfer Gas Cylinders |
| Others |
Cost & Logistics Intelligence
Medicare reimbursement pressure for portable oxygen therapy in the United States is compressing hardware margins and forcing manufacturers to unbundle cylinder ownership from refill logistics, which in turn fragments pricing power across durable medical equipment distributors and gas supply networks.
Pricing Analysis
Warranty and preventive maintenance bundling now separates premium cylinder offerings from transactional commodity sales. Three-tier pricing structure across premium, standard, and economy levels reflects material certification grades and after-sales service inclusion. Cost compression in aluminum alloy feedstock tiers is intensifying because aerospace demand competes for 6061-T6 extrusion supply. Hospital group purchasing organizations exhibit lowest price sensitivity due to volume leverage, while individual Medicare beneficiaries face highest out-of-pocket exposure driving economy tier selection.
Supply Chain Analysis
Reverse logistics for cylinder refurbishment and hydrostatic re-certification creates closed-loop material recovery flows that extend vessel service life. Manufacturing concentration centers on China, India, and Germany for seamless extrusion and filament winding operations. Raw material dependencies draw from South Korean aluminum smelters, Japanese carbon fiber producers, and German epoxy resin formulators. Single-source vulnerability in aerospace-grade alloy supply presents structural risk during commodity demand spikes. Distribution runs through regional gas distributors with localized filling station networks rather than direct manufacturer-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized composite pressure vessel engineering talent scarcity props pricing for filament-wound cylinder manufacturers, creating durable margin protection against aluminum commodity volatility.
For Market Incumbents: Cement market position by deepening backward integration into high-pressure seamless cylinder fabrication in Gujarat and Maharashtra production clusters. Acquire specialized filament winding engineering capabilities from aerospace supply chain spinouts before talent scarcity intensifies. Defend against liquid oxygen system substitution by emphasizing rapid cylinder exchange logistics for rural hospital networks. For New Entrants and Emerging Players: India's PLI scheme for medical devices opens a window for domestic fabrication entrants to capture procurement share from import-dependent district hospital networks. Target underpenetrated ASHA worker deployment programs with lightweight portable units featuring integrated flow regulators. Pursue drone-enabled emergency delivery partnerships as a differentiated last-mile go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with precision aluminum extrusion specialists given FDA's anticipated composite material approvals under 21 CFR Part 868. Long-term viability hinges on certification breadth spanning FDA 510(k), BIS IS 7285, and CE marking under MDR. Monitor BIS certification timeline compression as an inflection signal for import substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Regulatory Submission | FDA 510(k) pathway for carbon fiber overwrap designs unlocks premium home care pricing tiers. |
| Domestic Manufacturing Scale-Up | India's PLI scheme incentives reduce import dependency for rural health infrastructure procurement. |
| Drone Delivery Partnership | Aerial logistics alliances bypass road infrastructure gaps in flood-prone and mountainous regions. |
| Subscription Service Model | Per-patient monthly fees unbundle hardware ownership from therapeutic service provision. |
| REACH Compliance Reformulation | Epoxy resin matrix alternatives preserve CE marking validity for EU medical device markets. |
Research Approach
Independent corroboration across hospital procurement managers, biomedical engineers, GPO contracts specialists, and filament winding process engineers underwrites the qualitative findings. Primary interviews with clinicians and durable medical equipment distributors combined with secondary validation from FDA 510(k) filings, BIS certification records, CMS Medicare reimbursement databases, and customs trade data establish demand-side ground truth. Bottom-up patient population modeling and top-down industrial gas production triangulation cross-validate volume estimates.
Rate-of-change decomposition separates volume effects from pricing mix shifts across the projection horizon. Segmentation dimensions modeled include product type, application setting, end-user purchasing authority, and delivery mode conservation technology. CAGRs derive from patient population epidemiology, reimbursement trajectory assumptions, and material substitution elasticity. Industry-specific inputs incorporate PLI scheme disbursement pacing and FDA composite approval timeline scenarios.
The model assumes a particular technology adoption path; alternative pathways for filament-wound carbon fiber cylinders would alter the outlook if aerospace demand spikes divert engineering talent or if liquid oxygen vaporization systems achieve cost parity in high-consumption settings. Practitioners should monitor BIS certification processing delays and REACH epoxy resin restriction implementation for early signals of supply chain reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Surgical Table Market
Medical Equipment
Medical Thawing Systems Market
Medical Equipment
Medical Cart Battery Market
Medical Equipment
Ultrasound Equipment Market
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
Medical Ultrasonic Baths Market
Medical Equipment
Urodynamics Equipment and Disposables Market
Medical Equipment
Home Medical Equipment Market
Medical Equipment
Spinal Surgery Tables Market
Medical Equipment
X-Ray Machine Manufacturing Market
Medical Equipment
India Massage Equipment Market
Medical Equipment
Cell Washer Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
Mortuary Refrigerator Market
Medical Equipment
Centrifuge Market
Medical Equipment
Global Medical Device Reprocessing Market