
 Auditory Brainstem Response Analyzers Market | 2026-2036
Auditory Brainstem Response Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Auditory Brainstem Response Analyzers Market Outlook
Software-defined signal processing subscriptions is restructuring how manufacturers monetize auditory brainstem response platforms. Natus Medical leverages integrated hardware-software bundles to sustain recurring revenue from hospital systems. Interacoustics anchors its position through specialized calibration services that lock audiology clinics into long-term contracts.
An auditory brainstem response analyzer is a neurophysiological instrument that delivers calibrated acoustic stimuli through insert earphones or bone conduction transducers while recording evoked neural potentials via scalp electrodes, with typical stimulus rates of 11-83 Hz and analysis windows spanning 10-15 milliseconds post-stimulus to objectively assess auditory pathway integrity. These devices serve primarily to detect sensorineural hearing loss in non-verbal patients and to identify retrocochlear pathologies such as vestibular schwannomas. Portable systems now lead unit shipments due to point-of-care migration, while software algorithms command disproportionate margin pools as clinicians prioritize automated waveform interpretation over raw data acquisition. Desktop systems retain dominance in research institutions where multi-modal evoked potential integration remains essential.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape validation protocols and delay market entry for novel electrode configurations. The EU AI Act introduces additional conformity scrutiny for machine-learning-based waveform classifiers, compelling manufacturers to maintain exhaustive algorithm training datasets. Stakeholders must monitor how regulatory divergence between FDA and notified body interpretations of clinical evidence standards affects platform development roadmaps and geographic launch sequencing.
Market Dynamics
Software-defined architectures are compressing hardware replacement cycles while subscription-based waveform analysis services extract recurring revenue from capital-constrained audiology departments. This shift redistributes margin pools from device manufacturers to algorithm vendors and restructures procurement relationships across hospital systems.
Growth Catalysts
- Newborn hearing mandates:Universal screening legislation in the United States, Germany, and Japan creates predictable replacement demand as installed bases age beyond calibration-validated service intervals.
- EU MDR technical documentation:Stricter clinical evidence requirements for electrode configurations accelerate consolidation toward established manufacturers with robust quality management systems.
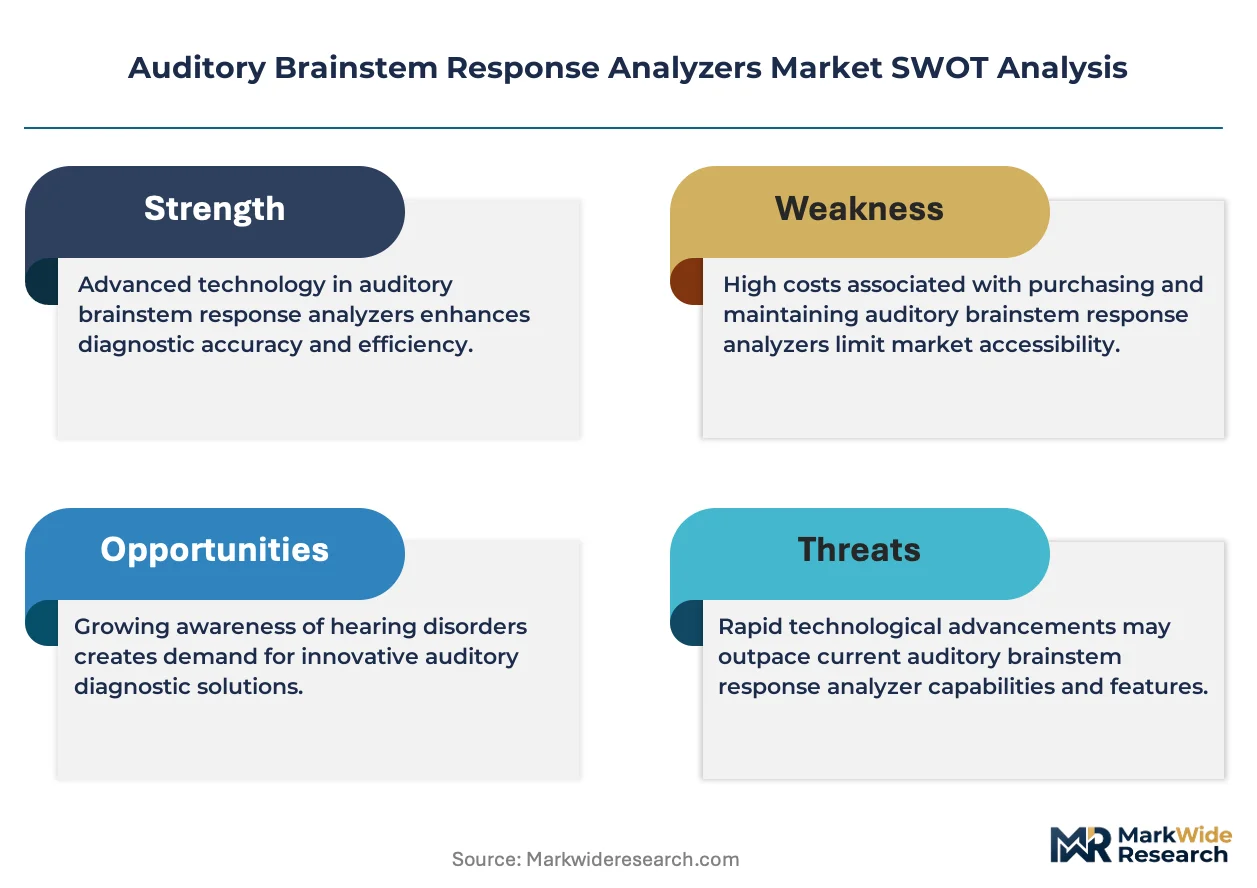
- Portable platform miniaturization:Lithium-polymer battery advances and low-power DSP chips enable point-of-care deployment outside traditional sound-booth environments.
Market Restraints
- Electrode supply concentration:Silver-silver chloride sensor manufacturing clusters in Southeast Asia expose procurement to logistics volatility and tariff exposure.
- FDA 510(k) pathway friction:Novel stimulus paradigms face extended review timelines compared to predicate device clearances, delaying feature differentiation.
- Alternative screening modalities:Otoacoustic emission analyzers compete for pediatric screening budgets with faster test protocols and lower per-exam labor requirements.
Strategic Opportunities
- Rural clinic penetration:Tele-audiology integration allows remote waveform interpretation from tertiary centers, opening underserved markets in Australia and Canada.
- EU AI Act compliance services:Machine-learning classifier validation creates adjacent revenue streams for manufacturers with exhaustive training datasets.
- Geriatric cognitive assessment convergence:ABR latency measures correlate with neurodegenerative progression, positioning devices within dementia screening protocols.
Industry Challenges
- Electrophysiologist training scarcity:Waveform interpretation requires specialized neurophysiology expertise that residency programs inadequately produce.
- Legacy EMR integration complexity:Proprietary data formats from installed base systems resist seamless HL7 FHIR connectivity without middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auditory Brainstem Response Analyzers Market |
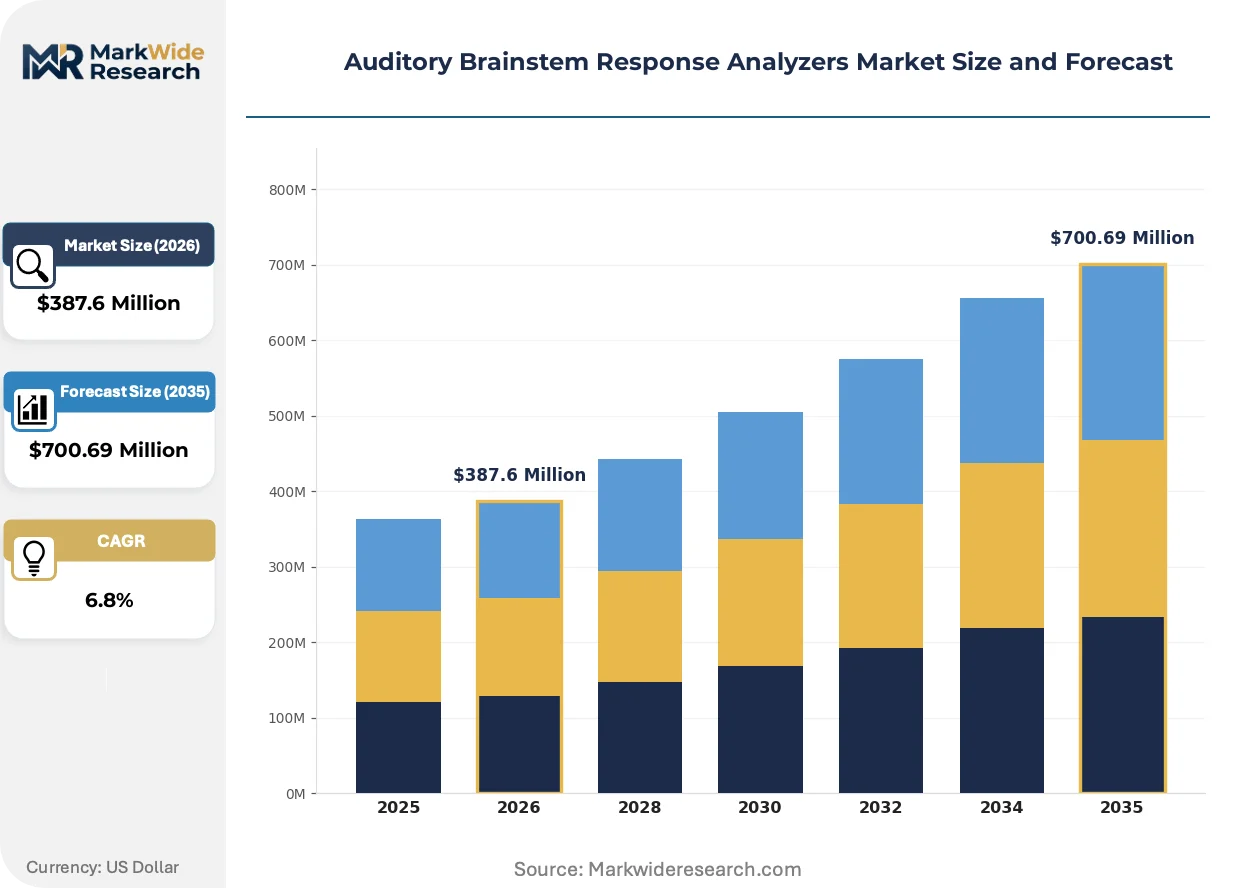
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Desktop Systems, Integrated Systems, Wireless Systems End User: Hospitals, Diagnostic Labs, Research Institutions, Audiology Clinics Technology: Electroencephalography, Evoked Potentials, Signal Processing, Software Algorithms Application: Hearing Assessment, Neurological Disorders, Clinical Research, Pediatric Screening |
| Companies Covered | Natus Medical, Interacoustics, Otometrics, Vivosonic, Intelligent Hearing Systems, MAICO Diagnostics, Grason-Stadler, Medtronic, Path Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auditory Brainstem Response Analyzers Market Strategic Shifts
Signal processing architectures are migrating from dedicated hardware to cloud-resident algorithms, compressing device BOM costs while elevating software subscription attach rates. This transformation redefines competitive moats around data assets rather than transducer engineering.
Machine-learning waveform classification is converging with automated artifact rejection to reduce skilled interpreter dependence. Community health centers in India and Brazil adopt these systems to extend screening coverage without specialist staffing. The technology is converging with telemedicine platforms to enable asynchronous diagnosis from low-resource settings.
The EU AI Act introduces conformity assessment obligations for clinical decision-support algorithms that exceed traditional medical device software scrutiny. Manufacturers must maintain algorithm training documentation spanning development, validation, and post-market surveillance. Pediatric screening programs in France and the Netherlands face extended procurement timelines as notified bodies interpret evidence standards.
Hospital procurement committees now unbundle hardware acquisition from software licensing and calibration service contracts. Audiology departments negotiate multi-vendor support agreements rather than single-source captive relationships. This pattern concentrates in German university hospital systems where centralized purchasing authority overrides departmental brand preferences.
Auditory Brainstem Response Analyzers Market Segmentation
Segmentation in the auditory brainstem response analyzer market reveals distinct procurement patterns across clinical and research settings. Product architecture, end-user workflow requirements, and signal processing sophistication drive purchasing decisions more than unit price alone.
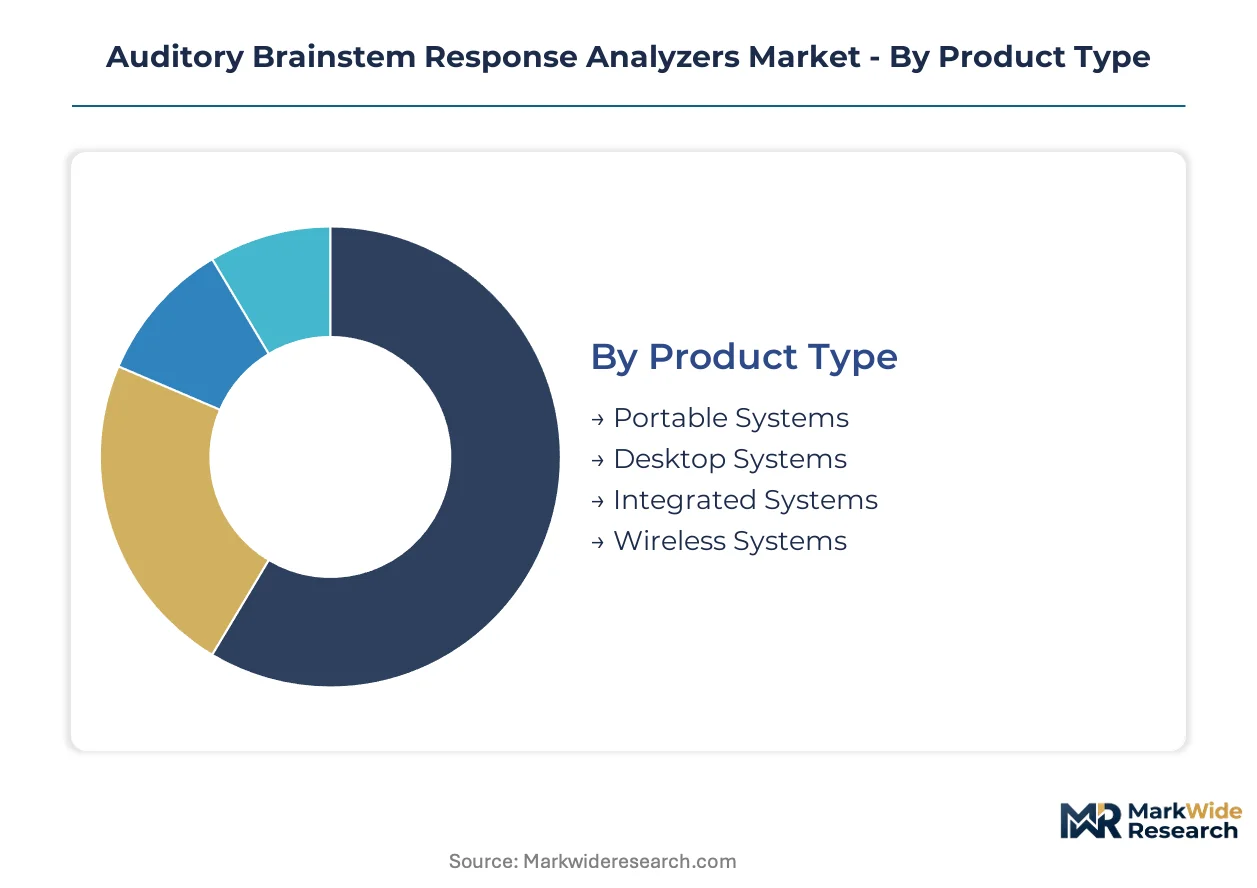
Product Type:
Capital intensity varies sharply across form factors, with integrated systems demanding the highest upfront investment for multi-modal capability.
- Portable Systems:Lithium-polymer battery architectures and low-power DSP chips enable deployment outside sound-booth environments. Demand concentrates in community health centers across India and Brazil where specialist staffing is scarce and point-of-care screening protocols are expanding.
- Desktop Systems:Multi-channel amplifiers and shielded Faraday enclosures support research-grade signal fidelity. Research institutions in Germany and Japan dominate procurement for multi-modal evoked potential integration protocols.
- Integrated Systems:Combine ABR with otoacoustic emission and tympanometry modules in unified hardware stacks.
- Wireless Systems:Bluetooth-enabled electrode arrays reduce cable artifact and enable patient mobility during extended recording sessions.
Most installed capacity flows through desktop systems in research institutions. Expansion is steepest in portable systems.
End User:
Procurement authority and workflow integration requirements shape vendor selection across four institutional categories.
- Hospitals:Pediatric departments with universal newborn hearing screening mandates drive replacement cycles. United States hospital systems prioritize FDA 510(k) cleared platforms with automated waveform interpretation to reduce electrophysiologist staffing burdens.
- Diagnostic Labs:High-throughput operations demand batch processing capabilities and HL7 FHIR connectivity for health information system integration.
- Research Institutions:Require raw data export and customizable stimulus paradigms for protocol development.
- Audiology Clinics:Independent practices favor subscription-based software models to preserve capital for facility expansion.
Hospital procurement committees command the largest transaction values. Audiology clinics are gaining share fastest through tele-audiology network participation.
Technology:
Margin pools are migrating from transducer hardware toward algorithmic differentiation and software-defined architectures.
- Electroencephalography:Scalp electrode arrays with silver-silver chloride sensors capture microvolt-scale neural potentials. Manufacturing concentration in Southeast Asia exposes supply chains to logistics volatility and tariff exposure.
- Evoked Potentials:Time-locked averaging protocols isolate auditory pathway responses from background cortical activity. Clinical demand in Japan focuses on retrocochlear pathology detection for vestibular schwannoma screening.
- Signal Processing:Digital filtering and artifact rejection algorithms reduce skilled interpreter dependence.
- Software Algorithms:Machine-learning waveform classifiers face EU AI Act conformity assessment obligations that exceed traditional medical device scrutiny.
Electroencephalography hardware commands the largest installed base. Software algorithms are climbing the fastest as clinicians prioritize automated interpretation.
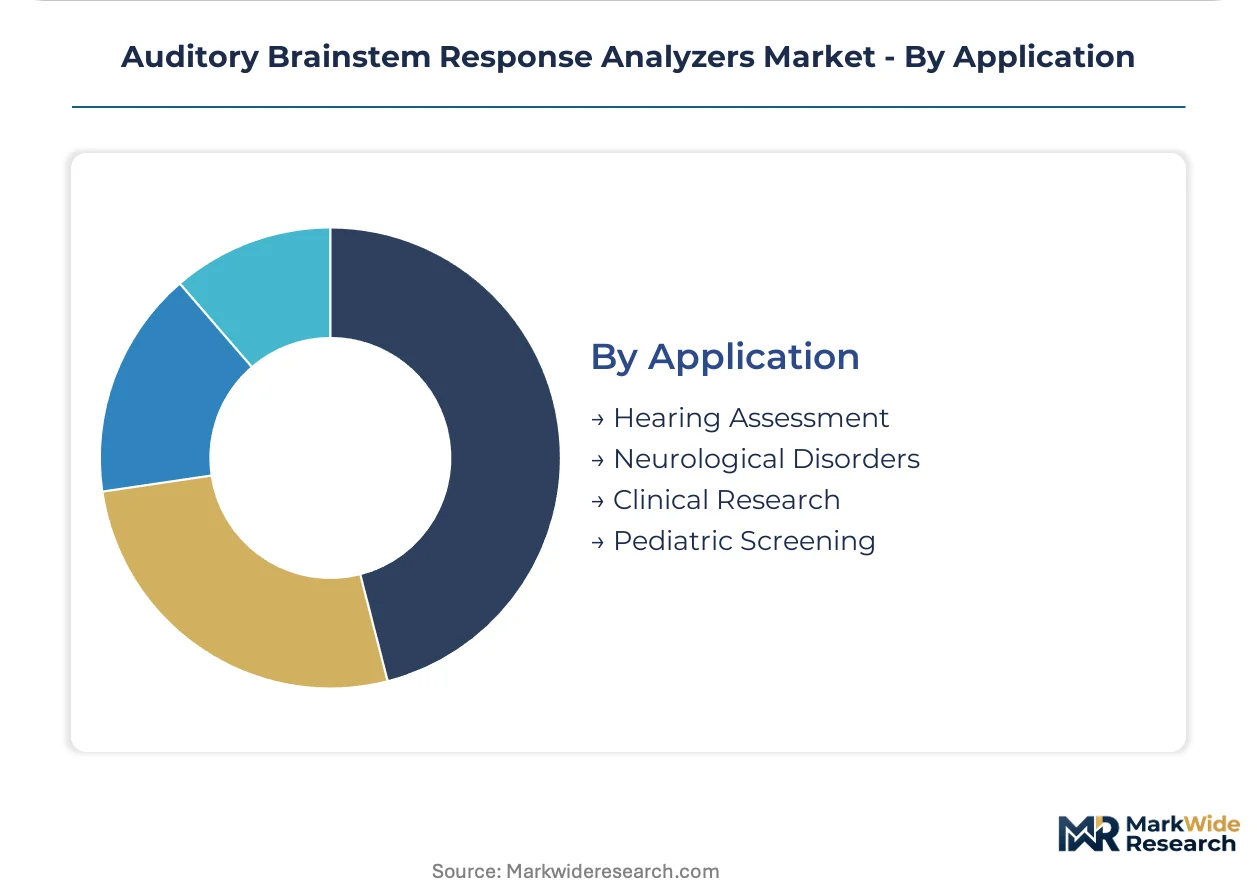
Application:
Clinical utility and reimbursement pathways determine adoption velocity across diagnostic categories.
- Hearing Assessment:Objective threshold estimation for non-verbal patients remains the core clinical indication. Pediatric screening programs in Germany and the Netherlands extend procurement timelines as notified bodies interpret EU MDR evidence standards.
- Neurological Disorders:ABR latency measures correlate with neurodegenerative progression, positioning devices within dementia screening protocols for geriatric populations in Japan.
- Clinical Research:Pharmaceutical trials for ototoxicity monitoring require validated equipment and audit trails.
- Pediatric Screening:Universal newborn hearing mandates in the United States create predictable replacement demand as installed bases age beyond calibration-validated service intervals.
Hearing assessment absorbs the majority of installed systems. Neurological disorder applications are expanding most quickly through convergence with cognitive assessment protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States exhibit contrasting procurement velocities, with German hospital systems extending replacement cycles under centralized purchasing authority while American pediatric departments accelerate turnover driven by newborn hearing mandate compliance pressures.
United States
FDA 510(k) clearance pathways shape vendor selection for hospital audiology departments prioritizing automated waveform interpretation capabilities. The Early Hearing Detection and Intervention program mandates universal newborn screening across all states. Massachusetts and California medical device clusters concentrate software algorithm development for machine-learning classifier platforms.
Germany
University hospital systems in Bavaria and North Rhine-Westphalia command centralized procurement authority that overrides departmental brand preferences. EU MDR technical documentation requirements extend validation timelines for novel electrode configurations. The Berlin-Brandenburg region hosts specialized calibration service providers that lock clinics into long-term maintenance contracts.
Japan
Retrocochlear pathology detection for vestibular schwannoma screening drives clinical demand in metropolitan Tokyo and Osaka. PMDA regulatory frameworks align with international standards while maintaining distinct post-market surveillance obligations. The Kansai region concentrates research-grade desktop system installations for multi-modal evoked potential integration protocols.
India
Community health centers in Maharashtra and Karnataka adopt portable platforms to extend screening coverage without specialist staffing. The national pharmaceutical regulator oversees medical device quality standards alongside CDSCO jurisdiction. Tamil Nadu manufacturing clusters produce silver-silver chloride electrodes serving domestic procurement and regional export markets.
Australia
Tele-audiology integration enables remote waveform interpretation from tertiary centers in Sydney and Melbourne to rural clinics in Queensland and Western Australia. The Therapeutic Goods Administration maintains alignment with FDA and EU MDR standards for streamlined market entry. New South Wales pediatric screening programs drive replacement demand as installed bases age beyond calibration-validated service intervals.
Auditory Brainstem Response Analyzers Market Competitive Environment
Top-tier vendors anchor the premium hardware-software bundle segment, while mid-tier specialists compete on portable platform miniaturization and regional calibration service networks. The vendor base stratifies across three tiers: multinational medical device conglomerates with integrated audiology portfolios, specialized diagnostic equipment manufacturers with dedicated evoked potential expertise, and regional assemblers serving price-sensitive procurement committees. Two dominant competitive moves define current positioning: subscription-based waveform analysis services that extract recurring revenue from capital-constrained departments, and strategic partnerships with telemedicine platforms to enable asynchronous diagnosis from low-resource settings.
Within the specialized diagnostic tier, Natus Medical and Interacoustics exemplify contrasting monetization architectures. Natus Medical leverages integrated hardware-software bundles to sustain recurring revenue from hospital systems, while Interacoustics anchors its position through specialized calibration services that lock audiology clinics into long-term contracts. MAICO Diagnostics occupies a position within the mid-tier portable segment, representing the specialist manufacturer archetype focused on point-of-care deployment outside traditional sound-booth environments.
| Leading Market Players |
|---|
| Natus Medical |
| Interacoustics |
| Otometrics |
| Vivosonic |
| Intelligent Hearing Systems |
| MAICO Diagnostics |
| Grason-Stadler |
| Medtronic |
| Path Medical |
| Others |
Value Chain & Pricing Dynamics
Silver spot price volatility on the London Bullion Market Association index cascades through electrode manufacturing costs, compressing margins for mid-tier portable system assemblers while amplifying pricing power for integrated hardware-software bundle providers serving hospital audiology departments.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for silver-silver chloride electrode components, forcing recalibration of three-tier pricing structure across premium, standard, and economy levels. Premium tiers anchor on FDA 510(k) clearance and automated waveform interpretation algorithms, while economy positioning relies on stripped hardware without software subscriptions. Cost compression in the mid-tier intensifies because otoacoustic emission analyzers compete for pediatric screening budgets. Community health centers in India and Brazil exhibit highest price sensitivity; German university hospital systems demonstrate lowest sensitivity due to centralized procurement authority overriding departmental preferences.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore coordinate hub-and-spoke patterns for electrode arrays and DSP chip modules. Manufacturing concentrates in Malaysia, Thailand, and China for silver-silver chloride sensors, with Germany and Japan hosting final system integration. Raw material flows draw from Chilean silver mining, Taiwanese semiconductor foundries, and Japanese lithium-polymer cell producers. Single-source vulnerability in Southeast Asian electrode manufacturing exposes procurement to logistics volatility and tariff exposure. Distribution runs through audiology equipment specialists and hospital GPO contracts rather than open-channel retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on software subscription attach rates displacing transactional hardware sales, with algorithm vendors capturing value pools that device manufacturers previously controlled.
For Market Incumbents: Lock in electrophysiologist training scarcity through proprietary certification programs that bind hospital audiology departments to ecosystem-dependent workflows. Deepen backward integration into electrode manufacturing to insulate margin structures from silver price volatility and Southeast Asian logistics disruptions. Counter emerging portable platform entrants by embedding calibration services into multi-year enterprise agreements. For New Entrants and Emerging Players: Begin with tele-audiology-enabled portable systems targeting rural clinics in Australia and Canada where tertiary center waveform interpretation resolves specialist staffing gaps. Community health centers in Maharashtra and Karnataka represent the most penetrable geography given national screening expansion without local electrophysiology expertise. Pursue software-first positioning with asynchronous diagnostic platforms rather than competing on transducer hardware specifications. For Investors and Strategic Acquirers: Asymmetric upside sits with algorithm vendors possessing exhaustive training datasets for EU AI Act compliance services. Five-to-ten year viability favors manufacturers with hospital system recurring revenue architectures over transactional device sellers. Signal to watch: notified body interpretation divergence between FDA and EU MDR evidence standards accelerating geographic launch sequencing advantages for dual-certified platforms.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Service Development | Machine-learning classifier validation creates adjacent revenue streams for manufacturers with documented algorithm training datasets. |
| Tele-audiology Platform Integration | Remote waveform interpretation from tertiary centers opens underserved rural markets in Australia and Canada. |
| Backward Integration into Electrode Manufacturing | In-house production of silver-silver chloride sensors reduces exposure to Southeast Asian logistics volatility and tariff risk. |
| Software Subscription Model Transition | Recurring revenue from automated waveform analysis services extracts value from capital-constrained audiology departments. |
| Hospital System Partnership Expansion | Multi-year enterprise agreements with pediatric departments lock in replacement cycles under newborn hearing mandate compliance. |
Study Parameters
Bottom-up hospital audiology department modeling reconciled against top-down medical device manufacturer shipment tracking forms the analytical core of this study. Primary interviews with clinical audiologists, hospital purchasing committee chairs, biomedical equipment engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and national newborn hearing screening program reports. Triangulation across these sources resolves discrepancies between stated demand and actual installation patterns.
Historical trendline analysis of replacement cycles under calibration-validated service intervals informs the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, end-user institution type, signal processing technology tier, and clinical application area. CAGRs derive from installed base aging curves and procurement authority concentration patterns. Forecast inputs incorporate EU AI Act implementation timelines and lithium-polymer battery cost trajectories.
Several conditions sit outside the modeled scope, including unforeseen regulatory divergence between FDA and PMDA interpretations, commodity price shocks exceeding historical volatility bands, and disruptive alternative screening modality breakthroughs. Forecasts reflect documented assumptions regarding mandate compliance stickiness and software attach rate progression. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Platelet Agitator Market
Medical Equipment
Automated Dialysis Concentrated Production Systems Market
Medical Equipment
Faecal Extraction System Market
Medical Equipment
Global Capnography Equipment Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
MRI Transport Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Marijuana Drying and Curing Equipment Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
Cath Lab Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Medical Equipment Reimbursement Market