
 Medical Thawing Systems Market | 2026-2036
Medical Thawing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Thawing Systems Market Analysis
Hospital procurement channels are reshaping vendor relationships across the medical thawing systems landscape. Thermo Fisher Scientific leverages its life sciences distribution network to sustain instrument placement in academic medical centers. Cardinal Health competes through integrated supply contracts that bundle thawing equipment with blood management programs. Sartorius AG specializes in bioprocessing-adjacent thawing solutions, anchoring its position in cell therapy manufacturing workflows.
Medical thawing systems encompass electromechanical devices designed to warm frozen biological specimens—typically blood components, stem cells, or tissues—from cryogenic temperatures to infusion-ready states, with critical functional parameters including temperature uniformity within ±0.5°C and thaw completion alarms to prevent thermal damage. These systems serve primary commercial purposes in clinical transfusion medicine, regenerative medicine manufacturing, and assisted reproductive technology laboratories where viability preservation directly impacts patient outcomes. Water bath systems dominate installed base volumes due to established clinical familiarity and lower capital thresholds, while dry heat technology captures expanding margin pools in cell therapy applications where contamination risk disqualifies aqueous methods. Rapid thawing protocols lead technology adoption in emergency transfusion settings, whereas controlled rate thawing commands premium positioning in fertility clinics where oocyte and embryo viability sensitivity necessitates precise thermal profiling.
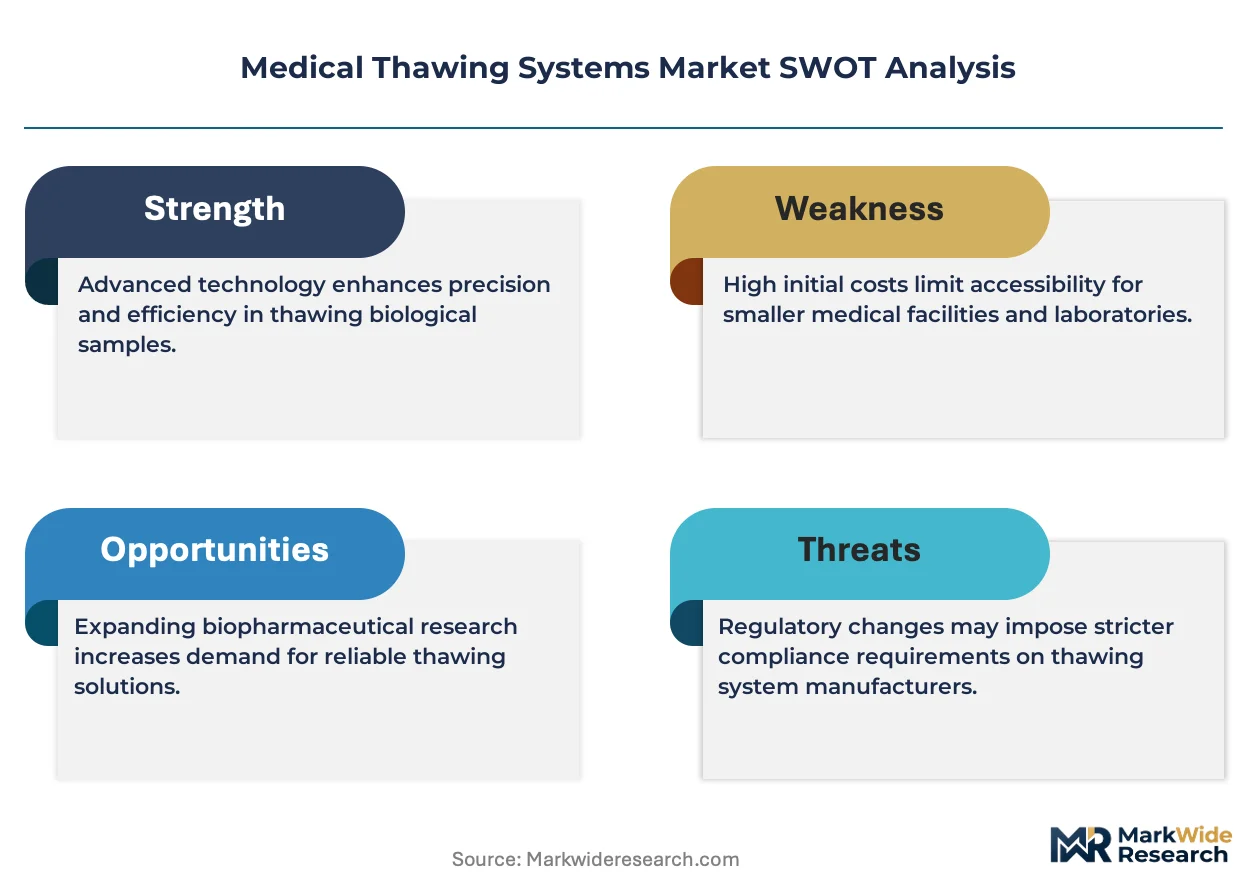
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development roadmaps, compelling manufacturers to invest in clinical validation studies and post-market surveillance infrastructure. ISO 13485 quality management certification functions as a baseline market access filter, with notified body scrutiny intensifying for software-controlled thawing algorithms. Blood banks, fertility clinics, and cell therapy manufacturers must evaluate vendor regulatory dossier completeness alongside thermal performance specifications when qualifying new platform acquisitions.
Market Dynamics
Cell therapy manufacturing scale-up is compressing validation timelines and forcing thawing system vendors to integrate closed-system architectures that eliminate open-water-bath contamination vectors entirely.
Growth Catalysts
- EU MDR Annex I technical documentation:Post-market surveillance mandates for Class IIa medical devices are accelerating replacement cycles in European fertility clinics and blood centers.
- Cryopreservation volume expansion:Cord blood banks in the United States, Germany, and Japan are adding controlled-rate thawing capacity to handle rising stem cell inventory.
- ISO 13485:2016 quality management:Certification requirements for software-controlled thermal algorithms are filtering out non-compliant vendors from hospital procurement shortlists.
Market Restraints
- Stainless steel and electronic component costs:Input price volatility for precision temperature sensors and medical-grade enclosures compresses gross margins for mid-tier equipment manufacturers.
- Water bath contamination liability:Persistent Legionella and biofilm risks in aqueous thawing methods drive liability insurance premiums upward for hospital risk managers.
- FDA 510(k) clearance timelines:Average review durations for novel thawing algorithms extend commercialization cycles by twelve to eighteen months versus predicate device pathways.
Strategic Opportunities
- India CDSCO medical device registration:Streamlined import licensing for Class B devices creates first-mover positioning in emerging cell therapy manufacturing hubs.
- Closed-system dry heat convergence:Integration of infrared warming with disposable containment sets addresses contamination-sensitive bioprocessing applications.
- Group purchasing organization channel expansion:Consolidated procurement contracts through Cardinal Health and Medline Industries bypass traditional capital equipment sales cycles.
Industry Challenges
- Thermal validation engineering talent scarcity:Specialized expertise in cryobiology heat transfer modeling commands premium compensation and constrains R&D throughput.
- Legacy LIS/EMR integration complexity:Thaw completion alarm data streams require HL7 FHIR compliance investments that strain smaller vendor development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Thawing Systems Market |
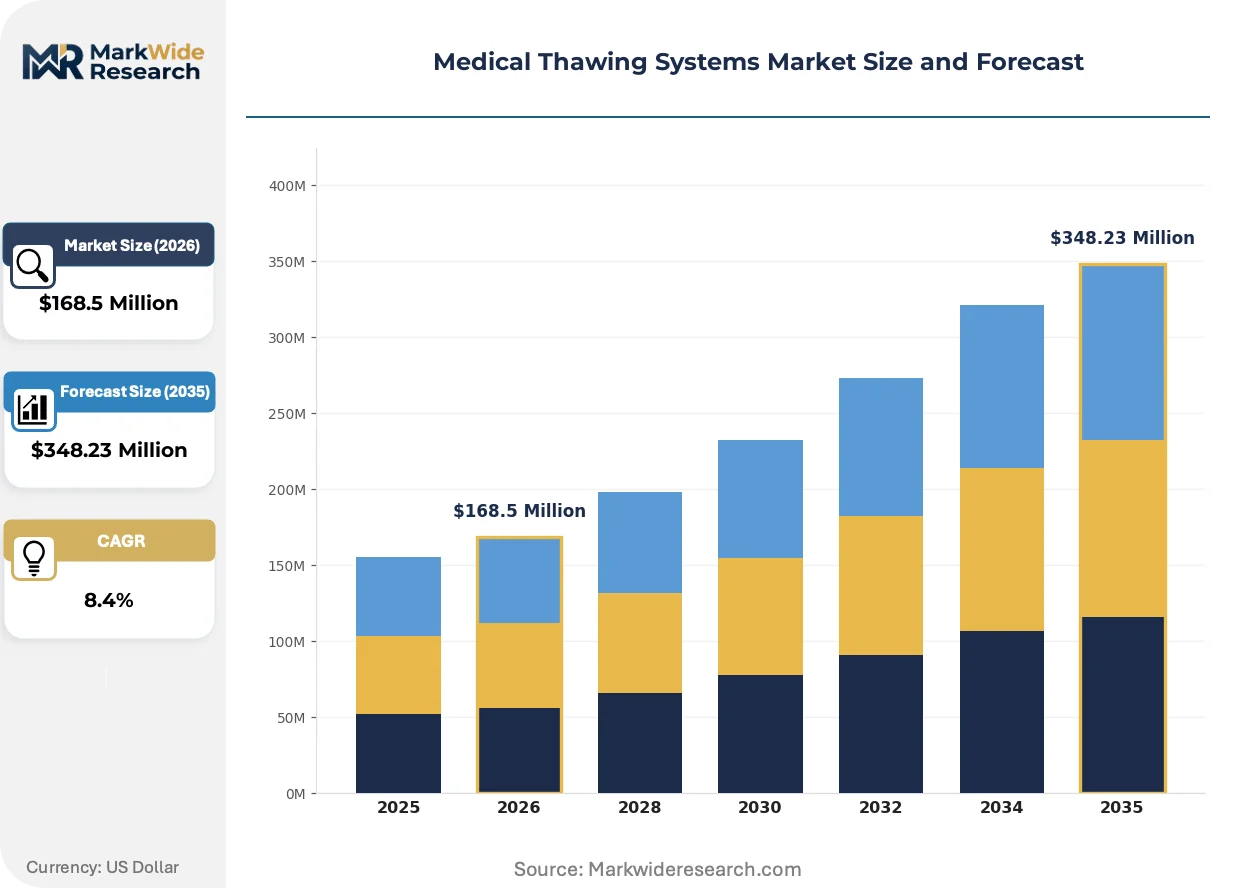
| Market Size in 2026 | $168.5 Million |
| Market Size in 2035 | $348.23 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Bath, Microwave, Dry Heat, Other Technology: Rapid Thawing, Controlled Rate Thawing, Passive Thawing, Others End User: Hospitals, Blood Banks, Research Laboratories, Fertility Clinics Application: Tissue Preservation, Blood Component Storage, Cell Therapy, Regenerative Medicine |
| Companies Covered | Helmer Scientific, Boekel Scientific, Sartorius AG, Sarstedt AG & Co. KG, Barkey GmbH & Co. KG, Cardinal Health, Thermo Fisher Scientific, General Electric, BioLife Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Thawing Systems Market Emerging Trajectories
Dry heat technology architectures are displacing aqueous methods across contamination-sensitive applications while regulatory software validation requirements harden. Vendor R&D roadmaps now prioritize closed-system designs that eliminate open-water handling entirely.
Programmable infrared warming platforms are migrating from niche fertility clinic applications to mainstream cell therapy manufacturing workflows. Bioprocessing contract manufacturers in the United States and Germany are specifying these systems for GMP-compliant thawing of cryopreserved cell banks. The technology is migrating from premium positioning toward standard equipment tier as contamination risk tolerance drops across the industry.
FDA software validation guidance for medical device thermal control algorithms is tightening documentation requirements for predicate device 510(k) submissions. Manufacturers must now submit failure mode and effects analysis for algorithm edge cases previously exempted. Blood bank instrument procurement committees are extending vendor qualification timelines to verify compliance depth.
Hospital capital equipment buying committees are unbundling thawing system purchases from integrated blood management contracts. Standalone instrument procurement allows technical specification prioritization over bundled pricing discounts. This pattern concentrates in academic medical centers where clinical engineering departments retain independent evaluation authority.
Medical Thawing Systems Market Segmentation
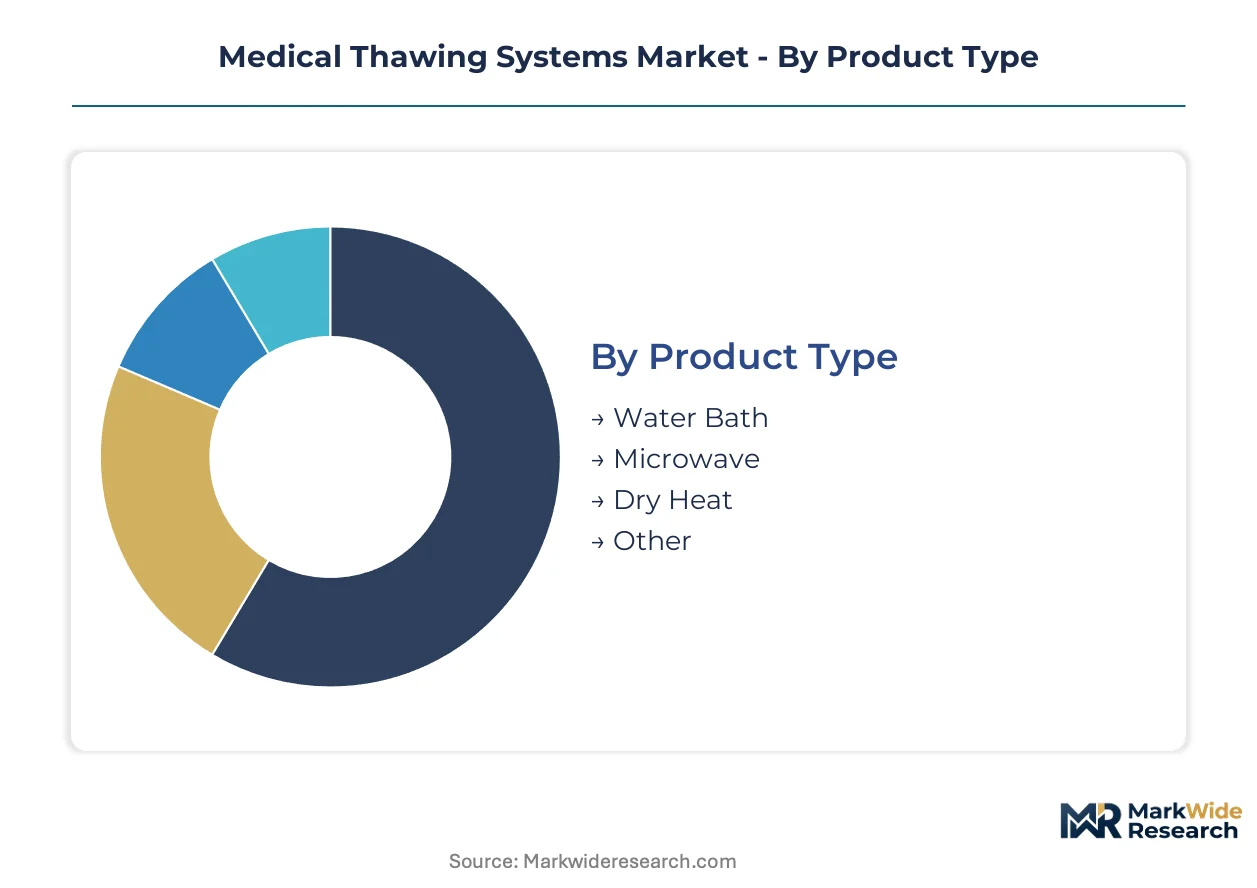
Segmentation in medical thawing systems reveals how thermal technology choices map to contamination risk tolerance, regulatory validation requirements, and end-use workflow constraints. Understanding these divides exposes where margin pools concentrate and where replacement cycles accelerate.
Product Type:
Cost tier stratification in product architecture separates established aqueous methods from emerging dry heat platforms that command premium positioning.
- Water Bath:Stainless steel vessels with circulating heated water maintain temperature uniformity through direct thermal conduction. Blood banks in the United States and Germany retain this technology for high-volume plasma thawing where capital constraints outweigh contamination concerns.
- Dry Heat:Infrared or conductive warming elements eliminate aqueous contamination vectors entirely. Cell therapy manufacturers in Japan specify these systems for GMP-compliant stem cell thawing where biofilm risk disqualifies water-based methods.
- Microwave:Electromagnetic heating delivers rapid energy transfer for emergency transfusion protocols. Trauma centers deploy these units for massive hemorrhage response where thaw speed determines clinical outcome.
- Other:Hybrid thermal architectures and experimental warming modalities serve niche research applications with non-standard specimen formats.
Water Bath holds installed capacity. Dry Heat is rotating up the share rankings.
Technology:
Application sensitivity determines whether speed or precision governs thermal protocol selection.
- Controlled Rate Thawing:Programmable algorithms execute precise temperature ramps with ±0.5°C uniformity to preserve cellular membrane integrity. Fertility clinics in Germany depend on this technology for oocyte and embryo viability where thermal shock causes irreversible damage.
- Rapid Thawing:High-power thermal delivery achieves infusion-ready states within minutes for emergency clinical scenarios. Hospital emergency departments prioritize these protocols for trauma-induced coagulopathy management.
- Passive Thawing:Ambient temperature equilibration serves low-resource settings and non-critical research workflows where equipment investment is prohibitive.
- Others:Experimental thermal modulation techniques including ultrasonic and dielectric warming remain confined to academic research environments.
Controlled Rate Thawing commands the premium tier. Rapid Thawing is expanding most quickly into emergency medicine infrastructure.
End User:
Customer type segmentation aligns procurement authority with clinical workflow complexity and regulatory scrutiny intensity.
- Blood Banks:High-throughput facilities processing thousands of units annually require validated thawing protocols for plasma, cryoprecipitate, and platelet components. Cord blood banks in the United States are adding controlled-rate capacity to handle expanding stem cell inventory volumes.
- Hospitals:Integrated health systems balance emergency transfusion readiness with blood management program standardization. Academic medical centers maintain independent clinical engineering evaluation authority for capital equipment selection.
- Fertility Clinics:Specialized reproductive medicine laboratories demand precision thermal control for gamete and embryo preservation. EU MDR Annex I documentation requirements are accelerating replacement cycles in European fertility centers.
- Research Laboratories:Academic and commercial research settings tolerate higher protocol variability for experimental cell banking and tissue engineering applications.
Blood Banks anchor volume demand. Fertility Clinics are climbing the fastest in per-unit value contribution.
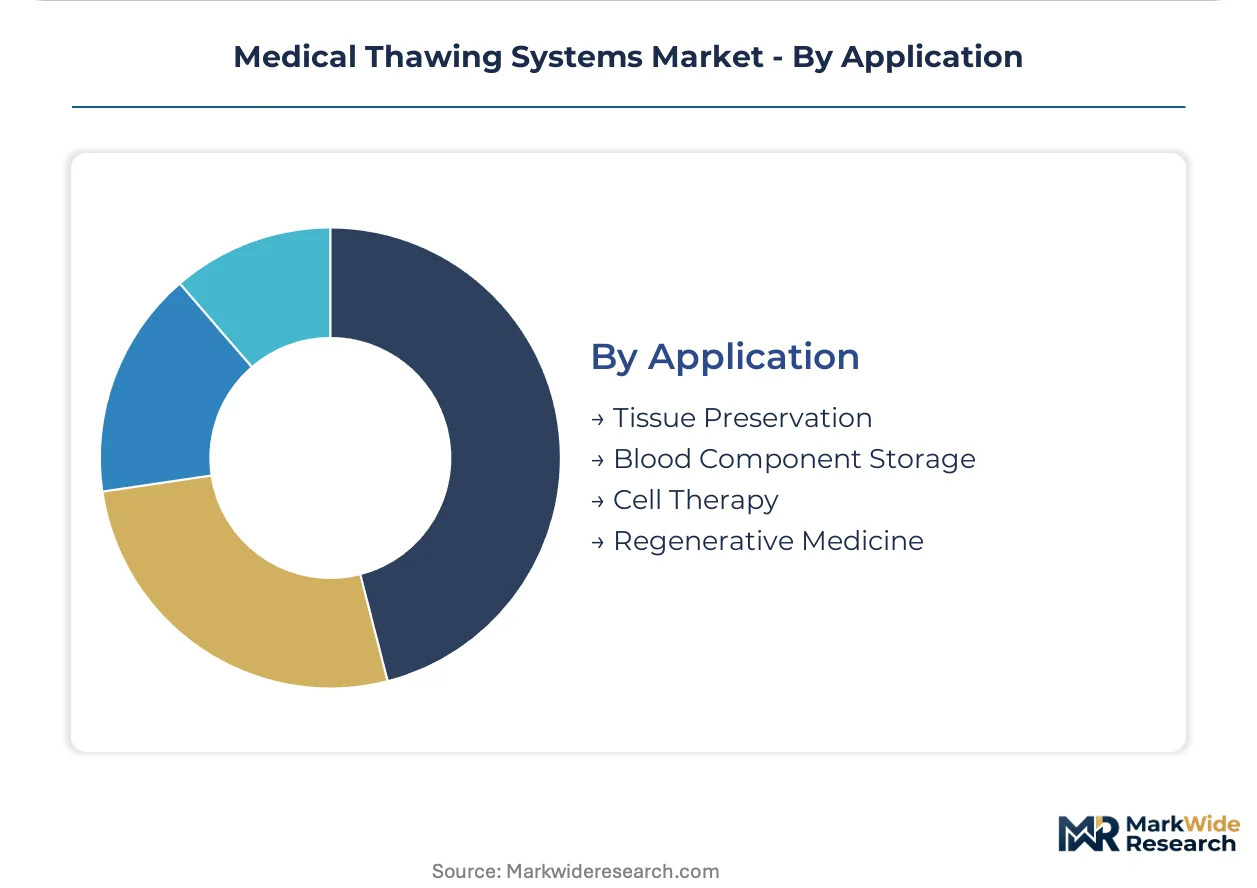
Application:
Volume scale and viability sensitivity create divergent equipment specifications across therapeutic domains.
- Cell Therapy:Manufacturing workflows for CAR-T and stem cell products mandate closed-system thawing to maintain GMP compliance. Contract manufacturers in Germany and the United States specify dry heat platforms with disposable containment sets.
- Blood Component Storage:Plasma and cryoprecipitate thawing for transfusion medicine represents the largest installed base by unit volume. Validation requirements from FDA and EU MDR shape procurement committee evaluation criteria.
- Regenerative Medicine:Tissue engineering and biobanking applications require scalable thawing protocols for cryopreserved cell banks. Bioprocessing facilities prioritize contamination elimination over capital cost minimization.
- Tissue Preservation:Solid organ and tissue graft thawing protocols serve specialized transplant centers with lower throughput requirements than blood banking operations.
Blood Component Storage maintains the broadest footprint. Cell Therapy is gaining share fastest as manufacturing capacity scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance timelines and EU MDR technical documentation obligations are compressing procurement cycles in mature markets while India's CDSCO streamlines import licensing for Class B devices.
United States
Cord blood banks in Texas and California are expanding controlled-rate thawing capacity to handle rising stem cell inventory volumes. FDA software validation guidance for thermal control algorithms tightens documentation requirements for predicate device submissions. Academic medical centers in Boston and the San Francisco Bay Area maintain independent clinical engineering authority for capital equipment selection.
Germany
Fertility clinics in Bavaria and Baden-Württemberg are accelerating replacement cycles under EU MDR Annex I post-market surveillance mandates. The country's national pharmaceutical regulator enforces ISO 13485 certification for software-controlled thawing systems entering hospital procurement channels. Bioprocessing contract manufacturers in the Rhine-Main cluster specify dry heat platforms with disposable containment sets for GMP-compliant workflows.
Japan
Cell therapy manufacturers in the Kanto region around Tokyo specify dry heat systems for contamination-sensitive stem cell thawing protocols. METI industrial standards shape thermal performance specifications for domestic equipment procurement. Osaka-based regenerative medicine facilities are adding closed-system thawing capacity as manufacturing scales for export markets.
India
Emerging cell therapy manufacturing hubs in Maharashtra and Telangana are qualifying imported thawing equipment under streamlined CDSCO Class B device registration. The national pharmaceutical regulator's import licensing reforms create first-mover positioning for controlled-rate systems. Biotech clusters in Bangalore and Hyderabad are building cryopreservation infrastructure for contract research organizations.
United Kingdom
Fertility clinics in London and the Southeast are extending vendor qualification timelines to verify EU MDR compliance depth for replacement equipment. The Medicines and Healthcare products Regulatory Agency maintains alignment with EU technical documentation standards post-Brexit. Research laboratories in Cambridge and Oxford tolerate higher protocol variability for experimental cell banking applications.
Medical Thawing Systems Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Diversified life sciences conglomerates with distribution networks compete against specialized bioprocessing equipment fabricators and regional precision thermal engineering shops. Strategic archetypes include integrated supply contract bundlers, closed-system dry heat specialists, and validation-heavy regulatory compliance enablers. Dominant competitive moves encompass portfolio diversification into adjacent cryopreservation workflows and geographic expansion through distributor partnerships in emerging manufacturing hubs.
Among Germany-based precision thermal engineering specialists, Sartorius AG and Barkey GmbH & Co. KG exemplify the closed-system dry heat archetype, occupying positions in contamination-sensitive bioprocessing applications. Thermo Fisher Scientific represents the diversified life sciences conglomerate tier, leveraging distribution infrastructure to sustain instrument placement. Cardinal Health sits within the integrated supply contract segment, bundling thawing equipment with blood management programs to bypass traditional capital equipment sales cycles.
| Leading Market Players |
|---|
| Helmer Scientific |
| Boekel Scientific |
| Sartorius AG |
| Sarstedt AG & Co. KG |
| Barkey GmbH & Co. KG |
| Cardinal Health |
| Thermo Fisher Scientific |
| General Electric |
| BioLife Solutions |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Antwerp freight corridor's container rate volatility compresses margins for precision temperature sensor shipments from German fabricators to United States blood bank distributors, concentrating pricing power among ISO 13485-certified vendors while forcing mid-tier manufacturers toward standard-grade positioning.
Pricing Analysis
Certification level (ISO 13485/FDA 510(k)/CE-marked) creates the primary spread between premium dry heat systems and economy water bath alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects thermal uniformity precision, software validation depth, and after-sales service bundling. Cost compression in the standard tier is intensifying because stainless steel input volatility and electronic component shortages squeeze mid-tier manufacturers. Blood banks exhibit highest price sensitivity due to capital budget constraints, while cell therapy manufacturers show lowest sensitivity given GMP compliance imperatives.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for hospital procurement committees, straining working capital for smaller precision thermal engineering shops. Component sourcing concentrates in Germany, Japan, and the United States for medical-grade temperature sensors, infrared warming elements, and software control modules. Supply chain risk centers on single-source vulnerability for FDA-validated thermal algorithms, where predicate device documentation creates switching costs. Distribution runs through group purchasing organizations and integrated supply contracts that bundle thawing equipment with blood management programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation through Cardinal Health and Medline Industries has shifted buyer power toward integrated supply contracts, fragmenting standalone instrument vendors and compressing their pricing autonomy.
For Market Incumbents: Insulate installed base positions by deepening ISO 13485 certification moats and embedding software companion tools that lock in hospital EMR integration. Threat from closed-system dry heat specialists demands defensive capacity addition in Japan's Kanto region where cell therapy manufacturing scales fastest. Channel control through exclusive GPO contracts represents the critical defensive lever.
For New Entrants and Emerging Players: India's Maharashtra and Telangana biotech clusters represent the most penetrable entry point, where streamlined CDSCO Class B registration creates first-mover positioning ahead of established vendor qualification. Secondary white-space targets include United Kingdom fertility clinics extending vendor timelines post-Brexit regulatory alignment. Go-to-market angle should emphasize rapid ISO 13485 certification completion to bypass procurement committee filters.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life sciences conglomerates seeking to divest non-core thermal equipment portfolios. Long-term viability frames around cell therapy manufacturing scale-up rather than blood banking replacement cycles. Signal to watch: FDA software validation guidance tightening for algorithm edge cases, which would accelerate replacement demand and validate premium positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Dry Heat Platform Launch | Eliminates aqueous contamination vectors for GMP-compliant cell therapy workflows in Germany and Japan. |
| FDA 510(k) Software Validation Investment | Accelerates predicate device pathways for thermal control algorithms amid tightening documentation requirements. |
| Group Purchasing Organization Channel Expansion | Bypasses traditional capital equipment sales cycles through Cardinal Health and Medline integrated supply contracts. |
| ISO 13485 Certification Acceleration | Filters non-compliant vendors from hospital procurement shortlists across United States and European markets. |
| India CDSCO Registration First-Mover Positioning | Captures emerging cell therapy manufacturing hubs in Maharashtra and Telangana ahead of established competition. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with blood bank operations directors, fertility clinic laboratory managers, cell therapy manufacturing heads, hospital biomedical engineers, and group purchasing organization contract specialists. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, ISO 13485 certification registries, hospital procurement committee records, and GPO contract disclosure documents. Bottom-up unit demand modeling triangulated against top-down market sizing from equipment shipment tracking and installed base analysis.
Calibration against historical replacement cycle data and regulatory implementation timelines anchored volume projections across the analysis window. Segmentation dimensions modeled include product architecture (water bath, dry heat, microwave), technology protocol (controlled rate, rapid thawing), end-user type (blood bank, hospital, fertility clinic, research laboratory), and application workflow (cell therapy manufacturing, blood component storage, regenerative medicine). CAGRs were derived from equipment placement trajectories and cryopreservation volume expansion curves, with cryobiology heat transfer engineering talent scarcity and stainless steel input cost volatility incorporated as scenario variables.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure budgets, freight corridor container rates, or precision sensor component pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation pacing and cell therapy manufacturing scale-up. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Gas Analyzer Market
Medical Equipment
Medical Equipment Calibration Services Market
Medical Equipment
Global Surgical Table Market
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
Faecal Extraction System Market
Medical Equipment
Cell Culture Incubator Market
Medical Equipment
Floor-Standing Platelet Agitator Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Global Medical Lighting Technologies Market
Medical Equipment
Birthing Beds Market
Medical Equipment
Global Medical Equipment Calibration Market
Medical Equipment
Medical Fluid Bags Market
Medical Equipment
Stereotactic Biopsy Tables Market
Medical Equipment
Global Intraoperative Radiation Therapy Market
Medical Equipment
Global Mobile Operating Tables Market
Medical Equipment
Diathermy Equipment Market