
 Global Smart Hospital Bed Market | 2026-2036
Global Smart Hospital Bed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Hospital Bed Market Intelligence
Beds equipped with integrated patient monitoring and automated fall prevention systems are rotating the market toward higher-value configurations. Stryker Corporation leverages its extensive hospital network to drive adoption of its connected bed platforms. Hill-Rom Holdings Inc. specializes in patient support systems and workflow solutions that integrate with electronic health records. Getinge AB competes through its focus on equipment for intensive care and surgical environments, where advanced monitoring is critical.
A smart hospital bed is a medical device embedded with sensors and wireless connectivity to monitor patient vitals, movement, and bed status in real time. These systems utilize IoT-enabled features to transmit data to a central nursing station or electronic health record system. Their primary purpose is to enhance patient safety and optimize clinical workflows. Within the technology segment, sensor integration and wireless connectivity are becoming standard, while intensive care units and rehabilitation centers lead adoption across applications.
Regulatory frameworks from bodies like the FDA in the United States and the CE marking process under the MDR in Europe define market access. These authorities mandate stringent requirements for device safety, electrical standards, and data security. For manufacturers, future success will depend on navigating these complex compliance landscapes while proving tangible improvements in patient outcomes and hospital operational efficiency.
Market Dynamics
The central force shaping the market is the reclassification of the hospital bed from a piece of furniture into a critical data-generating node within a hospital's digital ecosystem. This shift is driven by the integration of IoT sensors that enable real-time patient monitoring and workflow automation.
Growth Catalysts
- Patient Safety Mandates:Hospital initiatives to reduce preventable adverse events, such as patient falls and pressure ulcers, create direct demand for beds with automated monitoring and alert systems, aligning with value-based care models.
- Wireless Infrastructure Maturation:The standardization and deployment of robust in-hospital wireless networks, including Wi-Fi 6, provide the reliable, high-bandwidth connectivity essential for streaming real-time patient data from IoT-enabled beds to central nursing stations.
- Demographic Pressures:Aging populations in developed economies, particularly in Germany and Japan, increase the volume of patients requiring intensive or long-term care, driving investment in technologies that enhance monitoring efficiency in high-acuity settings.
Market Restraints
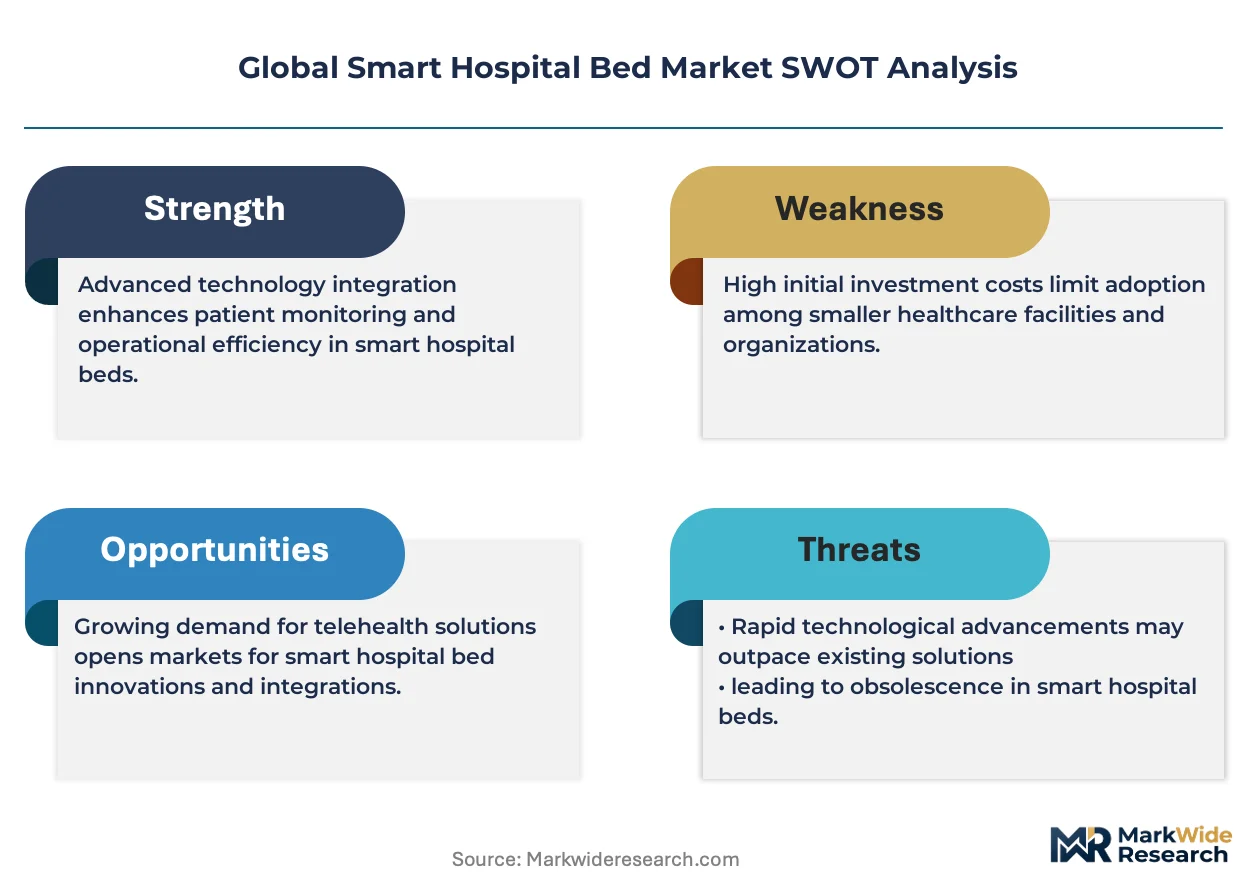
- High Capital Expenditure:The significant upfront cost of smart beds compared to traditional hospital beds represents a substantial capital investment, limiting adoption in smaller hospitals or healthcare systems with constrained budgets.
- EHR Integration Complexity:Achieving seamless data flow between smart beds and a hospital's existing Electronic Health Record system presents a major technical and logistical barrier, often requiring custom integration and creating interoperability challenges.
- Data Security and Privacy Risks:The wireless transmission of sensitive patient health information raises significant cybersecurity concerns, requiring robust data encryption and compliance with regulations like HIPAA in the United States and GDPR in Europe.
Strategic Opportunities
- Expansion into Home Healthcare:Adapting smart bed technology for the home care market presents an opportunity to manage high-risk patients remotely, supporting the trend of shifting care from hospitals to lower-cost settings.
- Predictive Analytics Integration:Incorporating artificial intelligence and machine learning algorithms to analyze data from bed sensors can enable predictive alerts for events like patient falls or the onset of sepsis, offering a higher value proposition.
- Untapped Emerging Markets:Healthcare infrastructure modernization projects in countries like Brazil and India offer significant long-term growth potential for smart bed manufacturers as new hospitals are built and existing ones are upgraded.
Industry Challenges
- Clinical Staff Training Gap:The effective use of smart beds requires nurses and clinical staff to be trained on new software interfaces and data interpretation, creating a need for extensive education and posing an operational challenge during implementation.
- Interoperability Standardization:The absence of a universally adopted data standard for medical device communication hinders the plug-and-play integration of smart beds from different manufacturers into a unified hospital IT platform.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Hospital Bed Market |
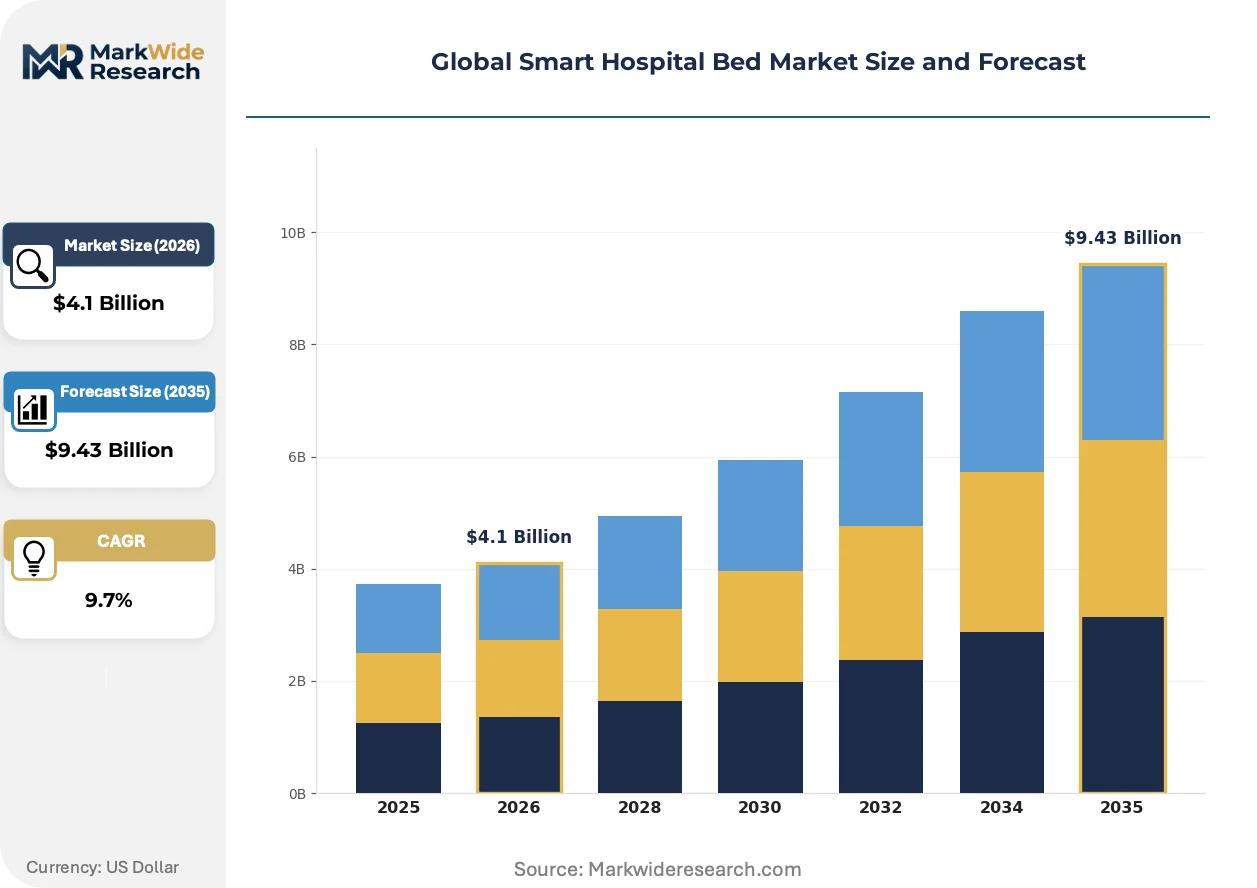
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $9.43 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Beds, Manual Beds, Semi-Electric Beds, Pediatric Beds, Bariatric Beds Technology: Sensor Integration, Wireless Connectivity, Remote Control Systems, Automated Positioning, IoT-enabled Features Application: Intensive Care Units, Rehabilitation Centers, Elderly Care Facilities, Maternity Wards, Emergency Rooms End User: Hospitals, Nursing Homes, Ambulatory Surgical Centers, Home Healthcare, Specialty Clinics |
| Companies Covered | Stryker Corporation, Hill-Rom Holdings Inc., Getinge AB, Paramount Bed Co., Ltd., Arjo AB, Invacare Corporation, Sleep Number Corporation, GE Healthcare, LINET spol. s r.o., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Hospital Bed Market Strategic Shifts & Innovations
The evolution of the smart bed is defined by its transition from a passive mechanical device to an active, intelligent platform for clinical data acquisition. This transformation is driven by advancements in sensing technology, stricter regulatory demands for software, and new procurement behaviors from hospital systems.
Non-contact sensing technologies are becoming a key feature in next-generation smart beds. These systems use embedded radar or load-cell-based ballistocardiography to monitor a patient's heart rate, respiratory rate, and movement without any physical contact. High-acuity environments like intensive care units are the earliest adopters. This passive monitoring capability is displacing the need for certain wearable biosensors and reducing the frequency of manual vital sign checks.
Stricter regulatory frameworks, particularly the European Union's Medical Device Regulation (MDR), are elevating the requirements for software validation and cybersecurity. The MDR mandates more rigorous clinical evidence and post-market surveillance for devices with software components, including smart beds. This particularly affects the software-as-a-medical-device (SaMD) elements, compelling manufacturers to invest heavily in robust quality management and data security protocols to achieve and maintain CE marking.
Subscription-based acquisition models are gaining traction among large hospital networks, challenging the traditional one-time capital equipment purchase. This approach bundles the hardware, software updates, maintenance, and data services into a predictable operational expense, allowing facilities to access the latest technology without a massive upfront investment. This procurement shift is most visible in the United States, where it helps hospitals manage technology obsolescence and align expenditures with operational budgets.
Global Smart Hospital Bed Market Segmentation
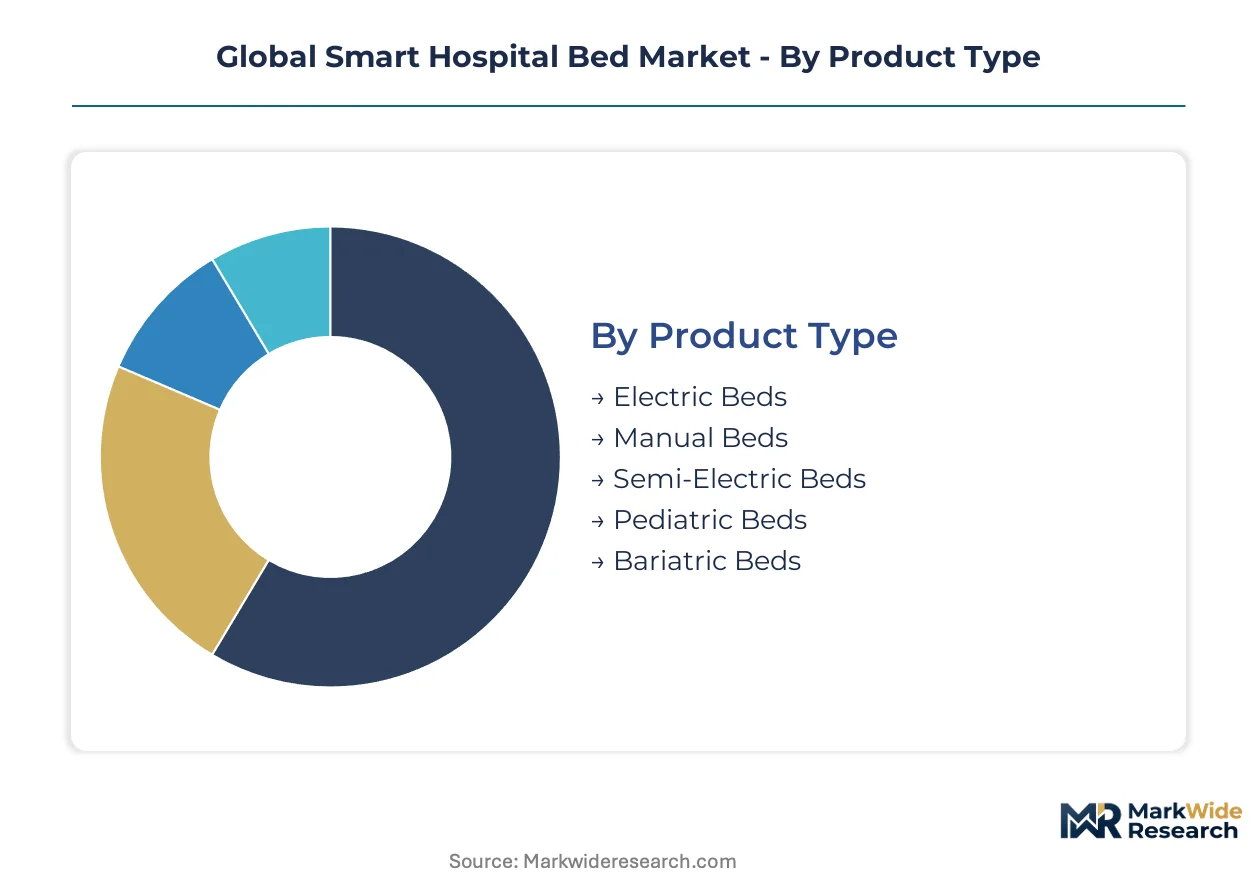
The segmentation of the global smart hospital bed market highlights how diverse product configurations and technological integrations cater to specific clinical needs and patient demographics. Understanding these segments is critical for manufacturers to align product development with evolving healthcare priorities and regional market dynamics.
Product Type:
The product type segmentation reveals distinct adoption patterns across different healthcare systems globally, influenced by economic development and regulatory priorities.
- Electric Beds:These beds offer motorized adjustments for height, backrest, and leg rest, enhancing patient comfort and caregiver ergonomics. Demand concentrates in developed healthcare systems like the United States and Germany, driven by stringent patient safety protocols and workflow efficiency goals.
- Bariatric Beds:Designed with reinforced frames and wider platforms, these beds accommodate heavier patients safely and comfortably. Hospitals in Western economies, particularly in the United States and the United Kingdom, show high demand due to rising obesity rates and the specialized care required for bariatric patients.
- Manual Beds:These beds require manual adjustment of features, representing a cost-effective option for basic patient care.
- Semi-Electric Beds:Offering a hybrid of manual and electric controls, these beds balance cost and functionality for various care settings.
- Pediatric Beds:Specifically designed for younger patients, these beds incorporate safety features and adaptable sizes for pediatric care environments.
Electric Beds commands the established base. The steepest expansion runs through Bariatric Beds.
Technology:
Technology advancements are often tailored to specific clinical applications, driving specialized demand within hospital environments.
- Sensor Integration:This involves embedding sensors within the bed to monitor patient vitals, movement, and bed exit status in real time. Intensive care units and high-acuity settings globally, including those in Germany and Canada, drive demand for continuous monitoring and early intervention capabilities.
- IoT-enabled Features:These features enable wireless data transmission, cloud connectivity, and integration with hospital IT systems for advanced analytics and remote management. Large hospital networks in the United States and Japan increasingly adopt these features for workflow optimization and data-driven clinical insights.
- Wireless Connectivity:This allows seamless data exchange between the bed and central monitoring stations or electronic health records.
- Remote Control Systems:These systems provide caregivers with convenient control over bed functions, improving patient positioning and comfort.
- Automated Positioning:Beds with automated positioning can adjust based on pre-set parameters or patient needs, reducing manual effort.
Innovation in IoT-enabled Features drives new product development, while Sensor Integration forms the foundational layer.
Application:
Different end-user settings prioritize smart bed features based on their patient demographics and operational models.
- Intensive Care Units:These units utilize smart beds for critical patient monitoring, automated fall prevention alerts, and pressure ulcer management. Hospitals in Germany prioritize these applications for patient safety in high-acuity settings.
- Rehabilitation Centers:Smart beds in these facilities aid in patient repositioning, mobility assistance, and progress tracking during recovery. Facilities in Japan heavily invest in these technologies to support an aging population with long-term recovery needs.
- Elderly Care Facilities:These facilities use smart beds for resident monitoring, fall detection, and enhanced comfort.
- Maternity Wards:Smart beds here focus on patient comfort, ease of access for new mothers, and basic monitoring.
- Emergency Rooms:Smart beds in ERs facilitate rapid patient assessment, comfortable positioning, and efficient patient transfer.
The largest share of demand originates from Intensive Care Units, with Rehabilitation Centers demonstrating significant expansion.
End User:
The end-user landscape presents varied margin opportunities, with some segments valuing advanced features more highly than others.
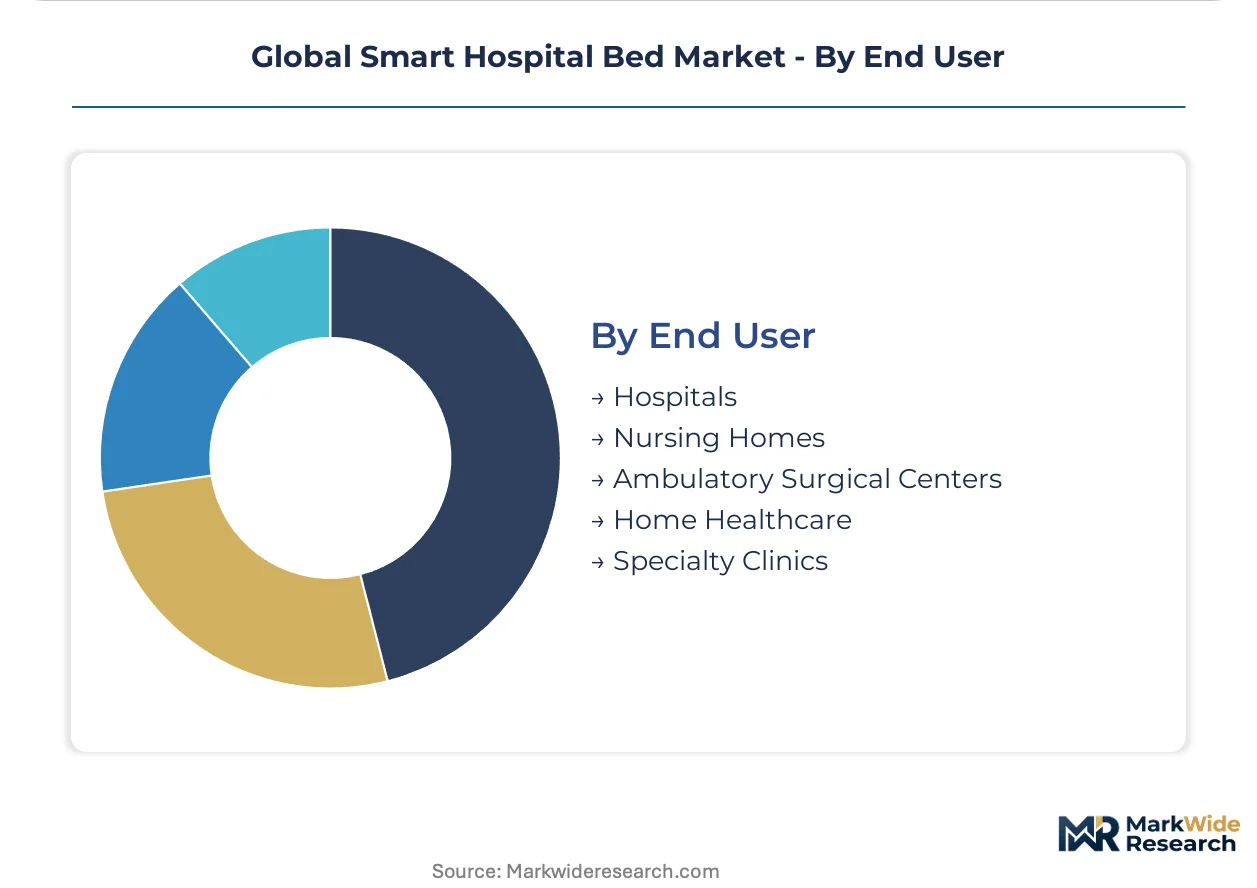
- Hospitals:These institutions represent the largest end-user segment, deploying smart beds across various departments for comprehensive patient care and workflow integration. Large hospital networks in the United States drive demand for enterprise-wide solutions focusing on operational efficiency and data integration.
- Home Healthcare:This segment involves deploying smart beds in residential settings for remote patient monitoring and support. Aging populations in developed economies like Canada and the UK drive demand for technologies that enable care outside traditional institutional settings.
- Nursing Homes:These facilities adopt smart beds for resident safety, fall prevention, and improved care efficiency.
- Ambulatory Surgical Centers:Smart beds in ASCs focus on pre-operative and post-operative patient comfort and monitoring.
- Specialty Clinics:These clinics use smart beds for specific patient populations requiring specialized positioning or monitoring.
Traditional institutional settings still dominate demand, but emerging care models are shifting focus towards Home Healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global smart hospital bed market exhibits a concentrated supply base, with established manufacturers often originating from regions with advanced healthcare infrastructure. These entities drive innovation and set industry standards for connected medical devices. This concentration influences market dynamics across various geographies.
United States
Demand for smart beds is high due to stringent patient safety mandates and the push for workflow efficiency in large hospital networks. HIPAA regulations govern data security for these IoT-enabled devices, necessitating robust cybersecurity measures. Silicon Valley and Boston's biotech hubs are centers for health tech innovation, influencing smart bed development.
Germany
Intensive care units in Germany prioritize smart beds for critical patient monitoring and fall prevention, aligning with strict patient safety protocols. The CE marking process under the MDR mandates rigorous safety and performance standards for medical devices like smart beds. Medical technology clusters in Bavaria and North Rhine-Westphalia are key innovation areas for advanced hospital equipment.
Japan
Aging populations in Japan drive demand for smart beds in rehabilitation centers and elderly care facilities, supporting long-term recovery needs. PMDA regulations ensure the safety and efficacy of medical devices, including those with advanced monitoring capabilities. Tokyo and Osaka's medical device industry clusters are developing AI-integrated smart bed solutions.
Canada
Home healthcare initiatives in Canada increase the need for smart beds that enable remote patient monitoring and support for an aging demographic. Health Canada regulates medical devices, ensuring compliance with safety and quality standards for technologies used in both institutional and home settings. Toronto and Montreal are developing health tech ecosystems that foster smart bed adoption.
India
Healthcare infrastructure modernization projects in India present significant long-term growth potential for smart bed manufacturers. The CDSCO oversees medical device regulations, ensuring market access for advanced hospital equipment. Bengaluru and Hyderabad are emerging as medical technology hubs, attracting investment in smart hospital solutions.
Global Smart Hospital Bed Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the global smart hospital bed market. The market exhibits a tiered structure, with established medical equipment manufacturers dominating the high-value segments. Innovators specializing in IoT and AI integration represent a distinct archetype, while regional players often compete on price and localized service. Dominant competitive moves include strategic partnerships for technology integration and continuous portfolio diversification to address varied clinical needs.
Established medical technology providers exemplify market leadership through extensive hospital networks and integrated product offerings, often spanning multiple care environments. Stryker Corporation leverages its broad hospital reach to drive adoption of connected bed platforms, representing a scale-driven approach that emphasizes comprehensive solutions. Hill-Rom Holdings Inc. occupies a position as a specialist in patient support systems, integrating workflow solutions directly with electronic health records for enhanced clinical efficiency. Swedish-based Getinge AB focuses on equipment for intensive care and surgical environments, where advanced monitoring capabilities are critical for patient outcomes and safety.
| Leading Market Players |
|---|
| Stryker Corporation |
| Hill-Rom Holdings Inc. |
| Getinge AB |
| Paramount Bed Co., Ltd. |
| Arjo AB |
| Invacare Corporation |
| Sleep Number Corporation |
| GE Healthcare |
| LINET spol. s r.o. |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized IoT sensors and integrated circuit boards significantly influence smart bed manufacturers' pricing power, shaping the overall supply chain structure. This dependency impacts final product costs.
Pricing Analysis
CE marking under the MDR dictates the pricing tier structure for smart hospital beds in Europe, emphasizing compliance and safety. The market increasingly adopts subscription-based acquisition models, bundling hardware, software updates, and maintenance. Price differentiation stems from certification levels and advanced integrated features like non-contact sensing; this also contributes to pricing pressure from high R&D investment for regulatory compliance. Smaller hospitals exhibit higher price sensitivity compared to large hospital networks.
Supply Chain Analysis
China and Taiwan anchor the supply of critical electronic components, including IoT sensors and wireless modules, for smart hospital beds. Germany contributes specialized mechanical components and precision engineering for advanced bed frames. The supply chain draws from medical-grade plastics and metals; single-source vulnerability for highly specialized non-contact sensing technology presents a structural risk. Distribution runs primarily through direct sales channels to large hospital networks and Group Purchasing Organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart hospital bed market represents a high-growth disruption, driven by the integration of IoT sensors transforming beds into critical data-generating nodes. This technological inflection enhances patient safety and optimizes clinical workflows.
For Market Incumbents: Shield existing market share by deepening integration with hospital Electronic Health Record systems and expanding subscription-based service offerings. Invest heavily in non-contact sensing technology R&D to counter emerging specialized IoT players. Leverage extensive hospital networks and GPO relationships to secure long-term procurement contracts. Prioritize robust cybersecurity measures to mitigate data privacy risks under HIPAA and GDPR, a key competitive differentiator.
For New Entrants and Emerging Players: Differentiate on predictive analytics integration, leveraging AI/ML algorithms for early detection of adverse patient events like falls or sepsis. Target the underpenetrated home healthcare market with adaptable, cost-effective smart bed solutions for remote monitoring. Focus on software-as-a-medical-device (SaMD) elements to offer high-value data insights, aligning with value-based care models. Partner with smaller, budget-constrained hospitals in emerging markets seeking advanced, but scalable, technology.
For Investors and Strategic Acquirers: Long-term, this sits as a technology-driven healthcare transformation play because smart beds are becoming essential infrastructure for digital hospitals. Target acquisition profiles include specialized firms in AI/ML-powered predictive analytics and non-contact sensing technologies. Focus on companies with robust regulatory compliance frameworks, particularly for SaMD elements. The signal to watch is the widespread adoption of standardized interoperability protocols, which will unlock greater data utility and market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures long-term procurement agreements and enhances product integration within clinical workflows. |
| Software Companion Development | Expands data analytics capabilities and enables predictive insights for patient safety. |
| CE Marking Pathway Acceleration | Ensures market access and regulatory compliance for advanced medical device features in Europe. |
| Non-Contact Sensing R&D | Drives technological leadership and reduces the need for traditional wearable patient monitors. |
| Home Healthcare Adaptation | Unlocks new market segments and supports remote patient monitoring for aging populations. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings like FDA and EMA submissions, hospital procurement databases, and medical device registries. Primary insights stem from interviews with clinicians, hospital purchasing committees, biomedical engineers, and Group Purchasing Organization contracts managers. This approach ensures robust data validation. Bottom-up and top-down triangulation methods further refine market size and growth estimates.
Segmentation dimensions modeled include product type, technology, application, end-user, and regional healthcare spending. The analytical framework projects market growth across the analysis window, deriving compound annual growth rates (CAGRs) from historical trends and future projections. Forecast inputs incorporate hospital bed occupancy rates and healthcare IT infrastructure investment. This methodology provides a granular outlook on market evolution.
Material uncertainties — rapid technological obsolescence, unforeseen regulatory shifts, and major global health crises — sit outside the modeled envelope. Forecasts reflect assumptions regarding market dynamics and macroeconomic stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Clinical Chairs Market
Medical Furniture
Hospital Beds Market
Medical Furniture
Global Chemotherapy Chairs Market
Medical Furniture
Medical Mattress Market
Medical Furniture
Asia-Pacific Hospital Furniture Market
Medical Furniture
Medical Walker Market
Medical Furniture
Medicine Cabinets Market
Medical Furniture
Healthcare Smart Beds Market
Medical Furniture
Electrical Hospital Beds Market
Medical Furniture
Global Medical Furniture Market
Medical Furniture
North America Hospital Furniture Market
Medical Furniture
Europe Hospital Furniture Market
Medical Furniture
Hospital Bed Management Systems Market
Medical Furniture
Healthcare Flooring Market
Medical Furniture
Hospital Furniture Market
Medical Furniture
Asia-Pacific Hospital Bed Market