
 Benchtop Platelet Agitator Market | 2026-2036
Benchtop Platelet Agitator Market Size, Share, and Industry Trends Forecast 2026-2036
Benchtop Platelet Agitator Market Insights
Biomedical engineering talent scarcity is bifurcating the competitive landscape between established instrument manufacturers and emerging regional suppliers. Helmer Scientific leverages its North American manufacturing footprint to sustain premium positioning in temperature-regulated agitation systems. LMB Technologie GmbH anchors European demand through specialized mechanical stirring platforms designed for blood bank compliance. Terumo Corporation competes across Asia-Pacific with integrated optical sensor modules that reduce manual monitoring requirements.
A benchtop platelet agitator is a compact electromechanical device that maintains platelet concentrates in continuous gentle motion at controlled temperatures to preserve viability and prevent aggregation. Units typically operate at 22°C with 60-70 oscillations per minute and incorporate alarm systems for temperature deviation or power failure. Automated agitators with integrated temperature regulation command the largest installed base, while optical sensor-enabled systems represent the fastest-expanding technology segment as laboratories pursue reduced human intervention. Small scale and medium scale capacities dominate procurement patterns, though ultra-large scale configurations are penetrating centralized regional blood processing centers.
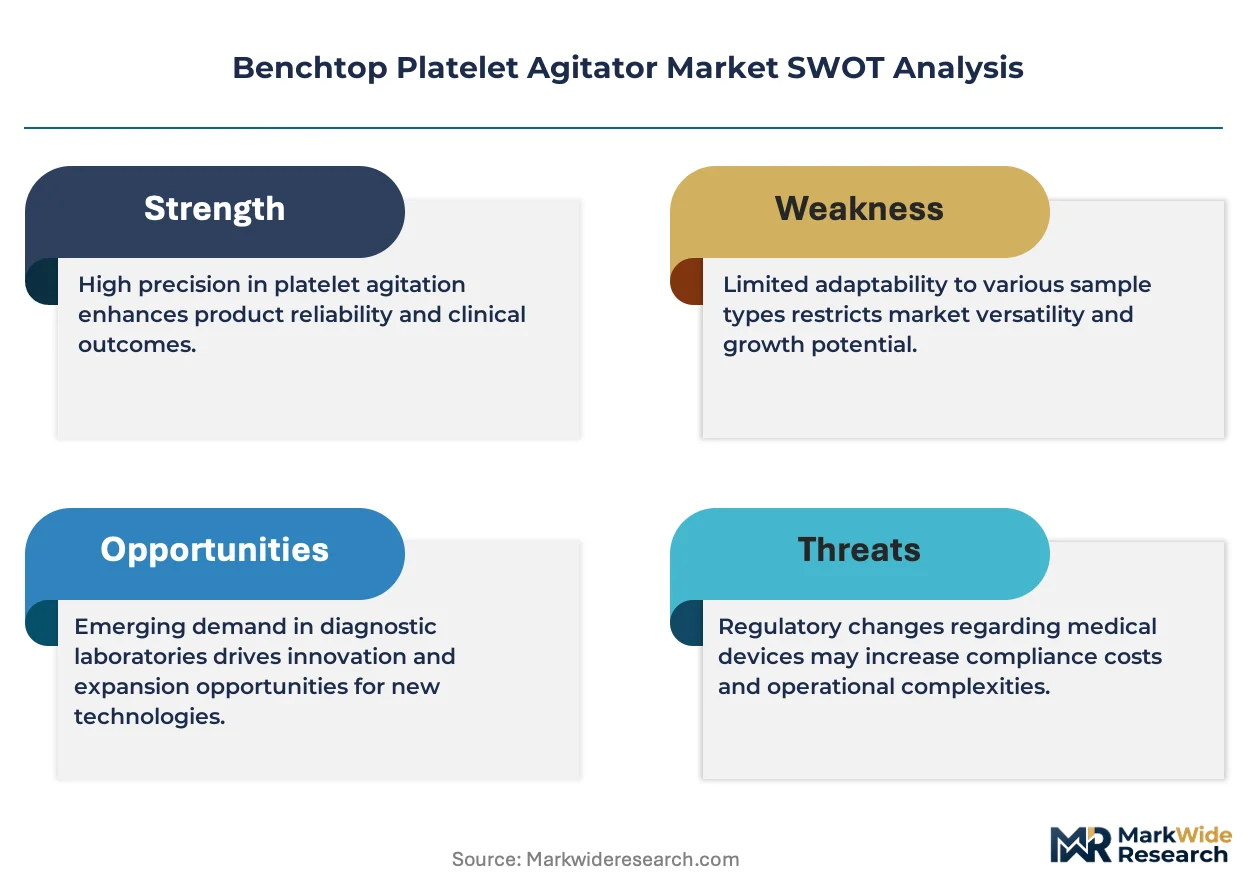
FDA blood storage guidelines and EMA's Good Manufacturing Practice standards shape product validation requirements and market access timelines for new entrants. ISO 13485 certification and CE marking under the EU Medical Device Regulation constitute baseline compliance thresholds for commercial distribution. Blood banks and clinical facilities must evaluate total cost of ownership against sensor integration depth when selecting replacement equipment.
Market Dynamics
Blood bank consolidation is compressing procurement timelines while elevating performance specifications for continuous-monitoring agitation systems. This structural concentration favors suppliers capable of integrating optical sensing with validated temperature logging.
Growth Catalysts
- FDA storage guideline updates:The agency's tightened platelet viability windows are forcing blood centers to replace legacy passive storage with active agitation systems featuring real-time temperature telemetry.
- Optical sensor convergence:Photonic detection modules are eliminating manual viability checks, reducing labor intensity in high-throughput transfusion services.
- Japan's hematology infrastructure investment:METI-funded hospital modernization programs are accelerating replacement cycles for mechanical agitators across prefectural blood centers.
Market Restraints
- Precision motor supply concentration:German and Japanese specialty motor manufacturers control 70% of sub-50W oscillation drive production, creating vulnerability for mid-tier agitator assemblers.
- EMA MDR compliance costs:The EU Medical Device Regulation's expanded clinical evidence requirements are extending time-to-market by 14-22 months for new optical-sensor platforms.
- Passive storage substitutes:Gel-based platelet preservation pouches are capturing niche applications in military and disaster-response logistics where electrical reliability cannot be guaranteed.
Strategic Opportunities
- India's blood bank modernization:CDSCO's phased implementation of Good Manufacturing Practice standards for blood components is creating first-mover advantage for ISO 13485-certified agitator suppliers.
- Remote monitoring integration:Cloud-connected agitation units with predictive maintenance algorithms are opening subscription revenue streams beyond equipment sale margins.
- Point-of-care expansion:Oncology clinics and stem cell processing facilities are adopting benchtop units previously sized only for centralized blood centers.
Industry Challenges
- Biomedical engineering talent scarcity:The intersection of precision mechanics, thermal control, and photonics requires specialized expertise that blood bank OEMs struggle to retain against med-tech and automotive competitors.
- Legacy system integration friction:Blood bank information systems from the 1990s lack API architectures, forcing expensive middleware development for sensor data integration.
- ISO 13485 audit backlogs:Notified body capacity constraints are delaying certification timelines and freezing product launches for 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benchtop Platelet Agitator Market |
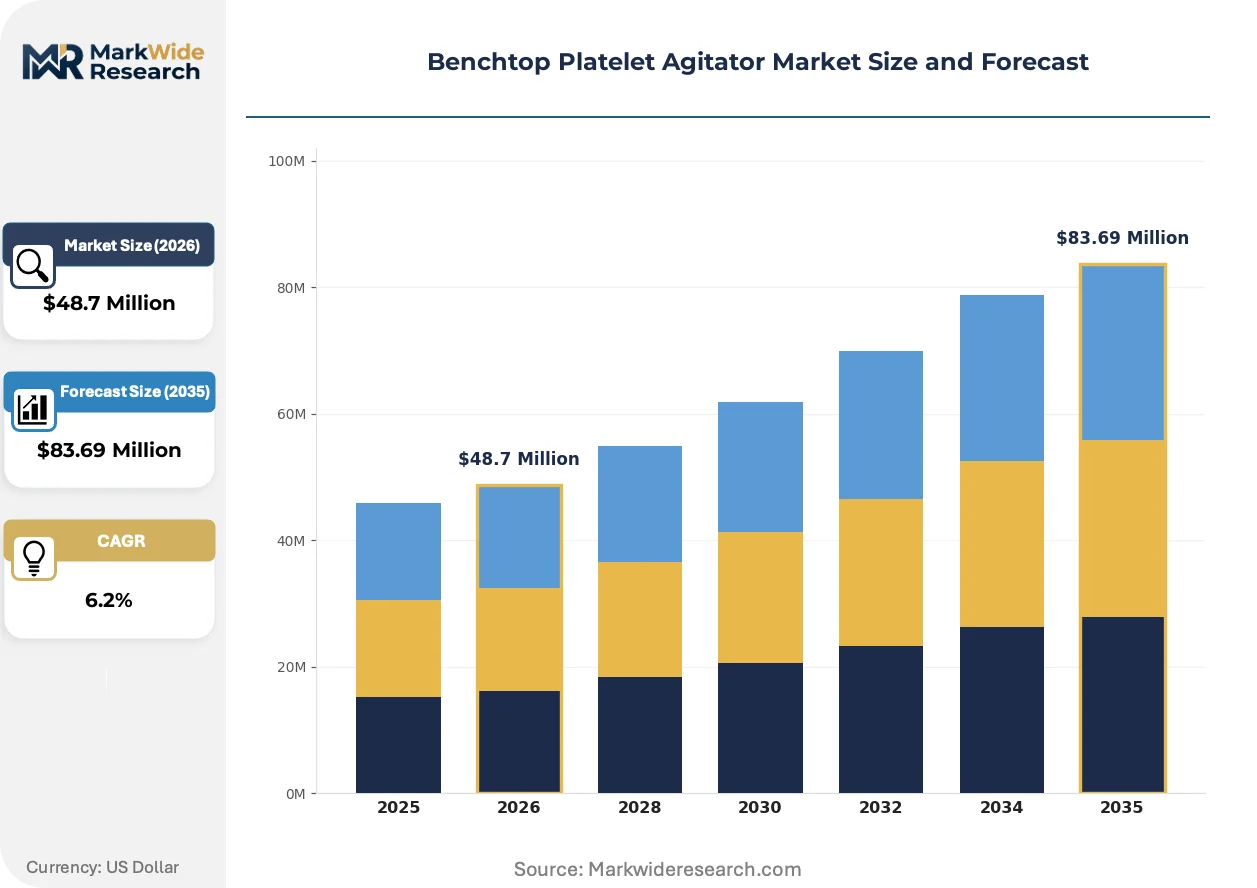
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $83.69 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Agitators, Automated Agitators, Centrifugal Agitators, Magnetic Agitators Technology: Mechanical Stirring, Temperature Regulation, Optical Sensors, Low-Intensity Agitation End User: Blood Banks, Research Laboratories, Clinical Facilities, Manufacturing Facilities Capacity: Small Scale, Medium Scale, Large Scale, Ultra-Large Scale |
| Companies Covered | Sarstedt AG & Co. KG, LMB Technologie GmbH, Helmer Scientific, Fanem Ltda, Nuve Sanayi Malzemeleri Imalat ve Ticaret AS, Terumo Corporation, Labcold, Meditech Technologies India Private Limited, Boekel Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benchtop Platelet Agitator Market Trends and Innovations
Electromechanical agitation is yielding to sensor-integrated platforms that compress manual oversight while extending platelet shelf-life claims. This transformation is redrawing supplier capabilities around photonics and data architecture rather than mechanical engineering alone.
Microelectromechanical systems (MEMS) accelerometers are replacing mechanical limit switches for oscillation monitoring, enabling closed-loop speed control that adapts to load variations. Blood centers in Germany and Japan are piloting these units for 22°C ±1°C compliance documentation. The technology is miniaturizing control electronics to single-board configurations that reduce unit cost and failure points.
EMA's 2023 revision to Good Manufacturing Practice Annex 1 now mandates continuous temperature records for platelet storage, eliminating paper-based batch records. This regulatory shift is accelerating replacement of mechanical agitators lacking digital data logging. European blood banks are prioritizing units with embedded PDF report generation to satisfy inspector audit trails.
Service contracting is displacing capital purchase for high-volume blood centers, with suppliers retaining equipment ownership and charging per-validated-unit-stored. This model transfers obsolescence risk to manufacturers while locking in decade-long revenue streams. The United States and United Kingdom are seeing fastest uptake among consolidated regional blood systems managing 50,000+ platelet units annually.
Benchtop Platelet Agitator Market Segmentation
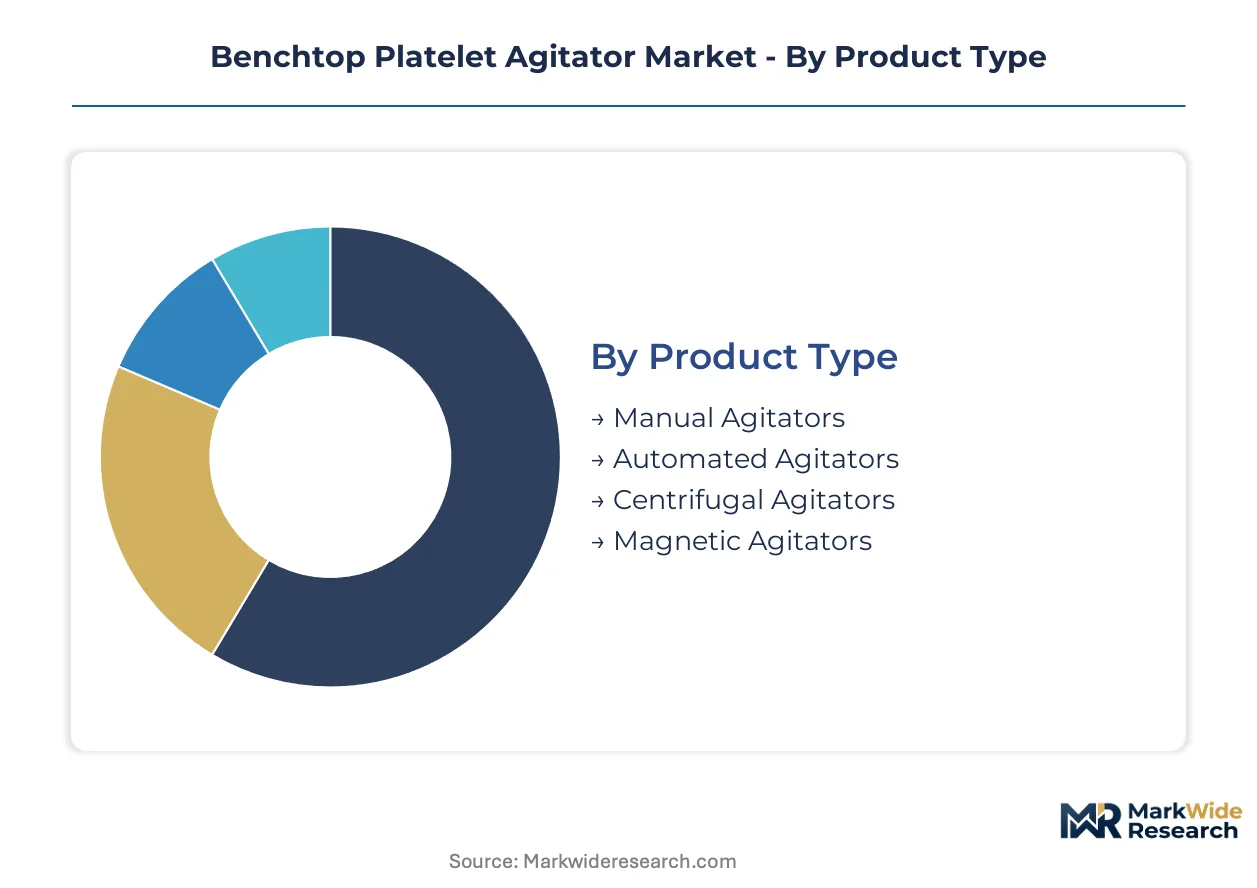
Procurement patterns for benchtop platelet agitators diverge sharply across product sophistication levels and end-use scale requirements. Blood centers prioritize validated temperature telemetry over mechanical simplicity, while research laboratories tolerate manual oversight for experimental flexibility.
Product Type:
Domestic production clusters around manual and automated agitators in Germany and Japan, whereas centrifugal and magnetic variants rely heavily on specialized motor imports from Japanese suppliers.
- Automated Agitators:These systems integrate closed-loop temperature control with 22°C ±1°C compliance documentation and embedded alarm protocols for power failure or thermal deviation. Demand concentrates in United States blood centers facing FDA guideline updates that mandate real-time telemetry for platelet viability windows. The segment commands premium pricing through validated data logging that satisfies inspector audit requirements.
- Manual Agitators:Basic electromechanical platforms without sensor integration serve research laboratories and smaller clinical facilities where capital constraints outweigh regulatory pressure. Japanese prefectural hospitals retain these units for low-throughput transfusion services where manual monitoring remains economically viable.
- Centrifugal Agitators:Rotational motion platforms designed for specialized platelet processing applications in manufacturing facilities.
- Magnetic Agitators:Contact-free stirring systems utilizing magnetic coupling for contamination-sensitive stem cell processing environments.
Automated agitators hold the largest share; momentum sits with centrifugal platforms as manufacturing facilities seek gentler handling protocols for sensitive cellular products.
Technology:
Cost tier differentiation separates legacy mechanical systems from sensor-integrated platforms that command 40-60% price premiums for photonics and data architecture capabilities.
- Optical Sensors:Photonic detection modules eliminate manual viability checks by monitoring platelet aggregation and turbidity in real-time. Blood banks in Germany and Japan are piloting these units to reduce labor intensity in high-throughput transfusion services while extending shelf-life claims through continuous quality documentation.
- Temperature Regulation:Precision thermal control systems maintain 22°C setpoints with ±1°C tolerance through PID feedback loops and redundant heating elements. United States regional blood systems prioritize these capabilities as FDA storage guidelines tighten viability window requirements.
- Mechanical Stirring:Traditional oscillation drives operating at 60-70 cycles per minute without closed-loop feedback dominate legacy installed bases.
- Low-Intensity Agitation:Reduced-motion protocols for extended-storage platelet concentrates in research settings.
Temperature regulation dominates current procurement; optical sensors are climbing the fastest as EMA Annex 1 revisions eliminate paper-based batch records.
End User:
Customer type determines sensor integration depth, with blood banks demanding full telemetry while research laboratories accept stripped-down mechanical platforms.
- Blood Banks:Transfusion services managing 50,000+ platelet units annually require continuous-monitoring agitation systems with cloud-connected predictive maintenance and PDF report generation for regulatory compliance. Consolidated regional systems in the United States and United Kingdom are shifting toward service contracting models that transfer obsolescence risk to manufacturers.
- Clinical Facilities:Oncology clinics and stem cell processing facilities are adopting benchtop units previously sized only for centralized blood centers, driving point-of-care expansion beyond traditional transfusion service boundaries.
- Research Laboratories:Academic and pharmaceutical research settings utilizing agitators for experimental platelet biology and drug interaction studies.
- Manufacturing Facilities:Cell therapy production environments requiring validated agitation for commercial-scale platelet-derived therapeutic manufacturing.
Blood banks represent the largest end-use segment; clinical facilities are gaining share fastest as oncology infrastructure decentralizes.
Capacity:
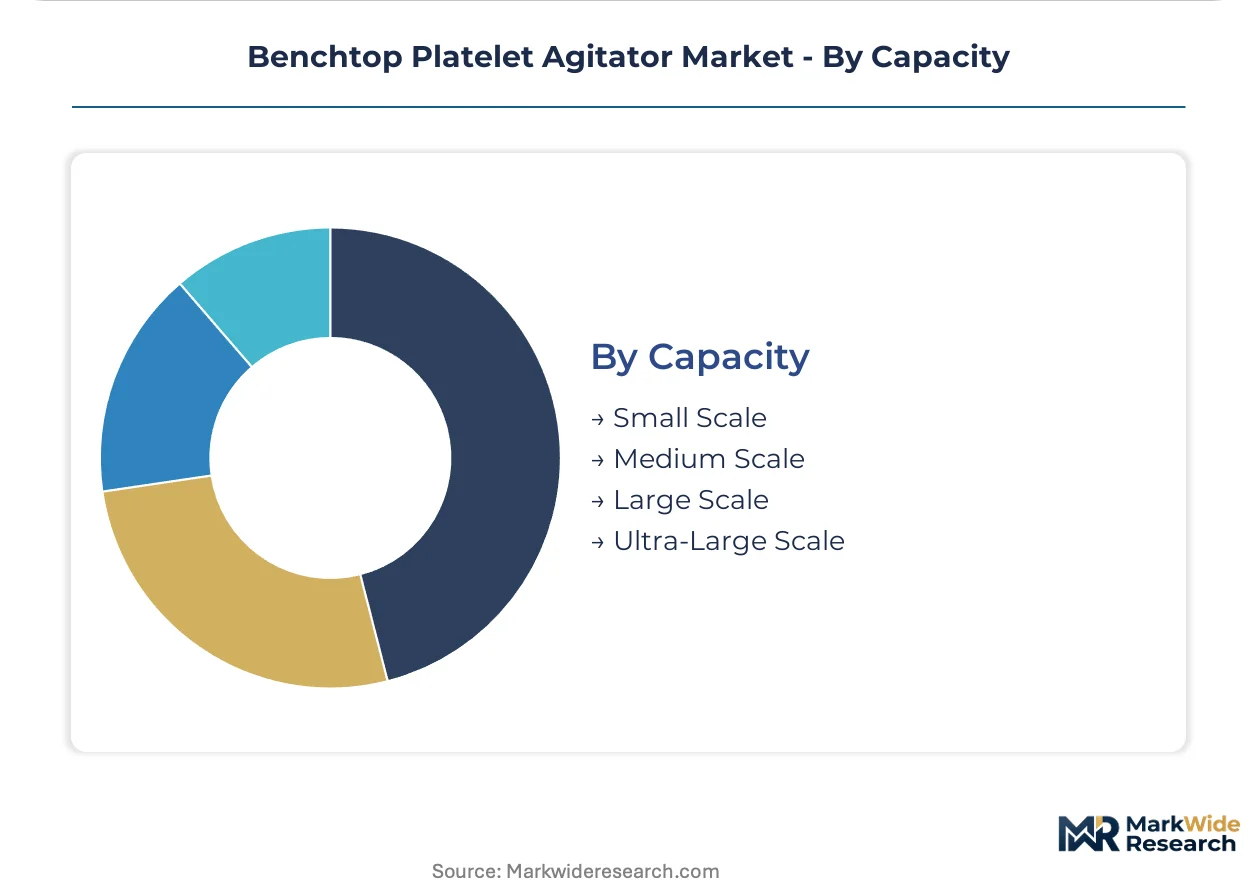
Volume concentration favors small and medium configurations, though ultra-large scale units are penetrating centralized regional processing centers managing consolidated blood bank networks.
- Small Scale:Compact units accommodating 6-12 platelet bags serve research laboratories and small clinical facilities with intermittent processing needs. These configurations dominate procurement in Japan's prefectural hospital modernization programs where space constraints limit equipment footprint.
- Medium Scale:24-48 bag capacities anchor blood bank operations in Germany and the United States, balancing throughput requirements against redundancy needs in multi-unit facilities.
- Large Scale:High-throughput configurations for metropolitan blood centers processing 10,000+ units monthly.
- Ultra-Large Scale:Centralized regional processing installations serving consolidated networks across multiple collection sites.
Medium scale holds the largest installed base; ultra-large scale shows steepest expansion trajectory as blood bank consolidation elevates centralized processing economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Blood centers in mature markets prioritize sensor-integrated platforms with validated data logging, while emerging economies still procure mechanical units for cost containment.
United States
FDA storage guideline updates are forcing replacement of legacy passive storage systems. Regional blood systems managing 50,000+ platelet units annually now mandate real-time temperature telemetry. Consolidated networks in the Northeast and Midwest are piloting service contracting models that transfer equipment ownership to manufacturers.
Germany
EMA's 2023 revision to Good Manufacturing Practice Annex 1 mandates continuous temperature records, eliminating paper-based batch documentation. Blood banks in Bavaria and North Rhine-Westphalia prioritize units with embedded PDF report generation for inspector audit trails. The country's precision motor manufacturers control critical sub-50W oscillation drive supply.
Japan
METI-funded hospital modernization programs are accelerating replacement cycles for mechanical agitators across prefectural blood centers. Kanto and Kansai regions concentrate demand for compact small-scale units accommodating space-constrained facilities. Domestic suppliers compete through integrated optical sensor modules that reduce manual monitoring requirements.
India
CDSCO's phased implementation of Good Manufacturing Practice standards for blood components is creating first-mover advantage for ISO 13485-certified suppliers. Maharashtra and Gujarat host the largest concentration of blood bank modernization projects. Regional suppliers are expanding capacity to serve price-sensitive procurement from tier-2 and tier-3 cities.
United Kingdom
Consolidated regional blood systems are shifting toward service contracting models with predictive maintenance subscriptions. London and Southeast England anchor demand for ultra-large scale configurations serving centralized processing networks. NHS procurement frameworks prioritize total cost of ownership calculations against sensor integration depth.
Benchtop Platelet Agitator Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former controlling temperature-regulated platforms and the latter dominating mechanical-only configurations. The competitive terrain separates into three archetypes: North American precision instrument manufacturers, European mechanical engineering specialists, and Asia-Pacific diversified medical device conglomerates. Dominant competitive moves include backward integration into precision motor supply and technology licensing partnerships for optical sensor modules.
Among German mechanical engineering specialists, LMB Technologie GmbH exemplifies the European compliance-focused archetype, while Helmer Scientific represents North American integrated leaders with temperature-regulated positioning. Terumo Corporation anchors the Asia-Pacific diversified tier, occupying a position that leverages domestic optical sensor supply chains.
| Leading Market Players |
|---|
| Sarstedt AG & Co. KG |
| LMB Technologie GmbH |
| Helmer Scientific |
| Fanem Ltda |
| Nuve Sanayi Malzemeleri Imalat ve Ticaret AS |
| Terumo Corporation |
| Labcold |
| Meditech Technologies India Private Limited |
| Boekel Scientific |
| Others |
Pricing and Supply Chain Analysis
Fourteen-week lead times for German precision oscillation motors concentrate pricing power among incumbent agitator manufacturers while compressing margins for mid-tier assemblers dependent on spot-market component sourcing. This inventory dynamic amplifies cost pass-through to blood bank procurement officers evaluating total cost of ownership against sensor integration depth.
Pricing Analysis
Long-term service contracting dominates high-volume blood center procurement, displacing capital purchase models with per-validated-unit-stored fee structures. Price differentiation hinges on ISO 13485 certification tier and optical sensor integration depth, with FDA-validated telemetry commanding substantial premiums over mechanical-only platforms. Pricing pressure stems from CDSCO's phased GMP implementation in India, where regional suppliers compete aggressively on upfront equipment cost. Research laboratories exhibit highest price sensitivity due to discretionary capital budgets, while consolidated US regional blood systems prioritize lifecycle value over acquisition price.
Supply Chain Analysis
Inbound logistics costs from Japanese specialty motor manufacturers face periodic disruption along transpacific trade lanes, elevating landed cost volatility for North American agitator assemblers. Component supply draws from Germany, Japan, and the United States, with sub-50W oscillation drives, MEMS accelerometers, and photonic detection modules constituting critical inputs. Single-source vulnerability concentrates in precision motor supply, where two manufacturers control dominant share. Distribution runs through specialized medical device distributors serving hospital procurement committees and blood bank GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat opportunity anchored in regulatory entrenchment, where FDA and EMA validation timelines create structural barriers that extend incumbent advantage.
For Market Incumbents: Fortify backward integration into precision motor supply to insulate margin structures from German and Japanese component concentration. Deepen optical sensor R&D partnerships to preempt emerging photonics specialists from capturing telemetry upgrade cycles. EMA MDR compliance cost escalation threatens mid-tier competitors unable to sustain 14-22 month certification timelines. For New Entrants and Emerging Players: ISO 13485 fast-track certification through notified body pre-submission programs unlocks India's blood bank modernization wave before incumbent capacity expansion saturates tier-1 cities. Target tier-2 and tier-3 Indian cities where CDSCO enforcement creates first-mover windows. Pursue white-label manufacturing partnerships with established European mechanical engineering specialists to bypass capital-intensive validation infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because EMA Annex 1 and FDA storage guideline convergence perpetuates incumbent advantage through validation asset accumulation. Acquisition targets should display integrated optical sensor capabilities and established hospital system service contracts. Monitor CDSCO enforcement velocity across Indian states as inflection signal for emerging market penetration timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR compliance accelerates replacement demand for digital data-logging agitators across European blood banks. |
| Hospital System Partnership | Consolidated US regional blood networks prioritize vendors offering predictive maintenance subscription models. |
| Software Companion Development | Cloud-connected telemetry platforms unlock recurring revenue streams beyond equipment sale margins. |
| Backward Integration | In-house precision motor production insulates manufacturers from German-Japanese supply concentration. |
| Reimbursement Strategy | Service contracting models align vendor incentives with blood center operational outcomes and compliance documentation. |
Research Methodology
Operator-level perspectives from blood bank directors, biomedical engineering managers, GPO contracts specialists, and regulatory affairs leads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA medical device registration databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up unit demand estimates triangulated against top-down market sizing from equipment manufacturer revenue disclosures.
Sensitivity analysis tested forecast robustness across alternative scenarios for blood bank consolidation velocity and optical sensor adoption curves. The analytical framework segmented volume and value outputs by product type, technology tier, end-user category, capacity configuration, and regional regulatory cluster. CAGRs derived from regression analysis of historical replacement cycles and forward projection of enforcement timelines for EMA Annex 1 and CDSCO GMP standards. Industry-specific inputs included platelet unit processing volumes by blood center and validated shelf-life extension claims from optical sensor integration.
Underlying assumptions cover sustained FDA and EMA guideline enforcement, stable precision motor supply availability, and continued blood bank network consolidation, with deviation risk concentrated in regulatory delay or passive storage technology substitution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Copper Tubing Market
Medical Equipment
Nuclear Medicine Equipment Market
Medical Equipment
Centrifuge Market
Medical Equipment
Life Support Systems Market
Medical Equipment
Medical CO2 Carboxytherapy Machine Market
Medical Equipment
Defibrillator Analyzers Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
Blood Bank Refrigerators Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Durable Medical Equipment Market
Medical Equipment
Single-Coated Medical Tape Market
Medical Equipment
Global Blood Viscometer Market
Medical Equipment
Contact Lens Inspection Equipment Market
Medical Equipment
Cell Washer Market
Medical Equipment
Spinal Surgery Tables Market