
 Clinical Microscopes Market | 2026-2036
Clinical Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Microscopes Market Analysis
The EU Medical Device Regulation is realigning procurement criteria for clinical microscopy equipment across European healthcare systems. Nikon Corporation leverages its century-old optics heritage to sustain premium positioning in fluorescence imaging systems. Leica Microsystems anchors its competitive stance through backward integration into precision glass engineering and captive supply of specialized objective lenses.
Clinical microscopes are precision optical instruments employing compound lens arrays with numerical apertures typically ranging from 0.1 to 1.4, designed to magnify cellular and tissue structures for diagnostic visualization in medical settings. Their primary commercial purpose centers on enabling pathologists and laboratory technicians to identify morphological abnormalities for disease diagnosis. Compound microscopes occupy the largest installed base across hospital laboratories, though digital microscopes represent the fastest-expanding category as telepathology networks multiply. End user demand fragments across pathology labs and diagnostic centers, with the latter segment capturing disproportionate margin pools through high-throughput screening contracts.
FDA 510(k) clearance pathways and EU MDR conformity assessments govern market access for clinical microscopy devices sold in the United States and Europe, with ISO 13485 quality management certification serving as a baseline expectation for supplier qualification. The EPA regulates mercury-containing fluorescence lamp disposal, nudging manufacturers toward LED illumination architectures. Stakeholders must monitor how artificial intelligence-enabled image analysis modules reshape regulatory classification boundaries and reimbursement frameworks for automated diagnostic workflows.
Market Dynamics
The EU MDR conformity assessment timeline is compressing procurement cycles for clinical microscopy equipment, forcing hospitals and diagnostic centers to front-load capital expenditure decisions before certification deadlines. Pathology labs face a structural pivot toward integrated digital-fluorescence platforms that satisfy both diagnostic accuracy mandates and emerging telemedicine infrastructure requirements.
Growth Catalysts
- Telepathology Network Expansion:Healthcare systems in Germany, France, and the Netherlands are deploying remote diagnostic infrastructure that requires digital microscope compatibility. This creates pull-through demand for whole-slide imaging systems.
- EU MDR Certification Windows:The Medical Device Regulation's phased implementation deadlines are accelerating replacement cycles for legacy equipment. Labs must upgrade to MDR-compliant devices to maintain operational authorization.
- LED Illumination Architectures:Solid-state lighting is displacing mercury-vapor fluorescence sources, eliminating hazardous waste disposal costs and reducing downtime for lamp replacement in high-throughput screening environments.
Market Restraints
- Precision Optics Supply Concentration:Germany's Wetzlar-Jena corridor controls captive production of specialized objective lenses. Any disruption to this geographic cluster propagates through global equipment lead times.
- EU MDR Notified Body Capacity:Bottlenecked conformity assessment timelines extend product launch windows by 12-24 months. Manufacturers face working capital strain from inventory holding costs during regulatory review.
- Digital Pathology Reimbursement Gaps:Medicare and commercial payors in the United States lack consistent coding for remote diagnostic interpretation. This suppresses return-on-investment calculations for telepathology infrastructure.
Strategic Opportunities
- India Diagnostic Center Buildout:The country's PLI scheme for medical device manufacturing is attracting contract assembly investment. Domestic production can bypass import duty structures that inflate landed costs for fully-built systems.
- AI-Enabled Image Analysis Convergence:Machine learning algorithms for cytological screening are integrating directly into microscope control software. This creates new revenue streams through software licensing rather than hardware-only sales.
- Subscription Service Models:Equipment-as-a-service contracts with bundled maintenance and reagent supply are penetrating private pathology networks. This shifts capital expenditure to operational budgets for mid-sized diagnostic chains.
Industry Challenges
- Fluorescence Microscopy Specialist Shortage:Pathology residency programs emphasize conventional brightfield techniques. Labs struggle to recruit technicians proficient in immunofluorescence protocol optimization and quantitative image analysis.
- Legacy System Integration Complexity:Hospital IT departments face interoperability failures when connecting new digital microscopes to existing laboratory information systems. DICOM compliance gaps require custom middleware development.
- Mercury Lamp Phase-Out Transition:EPA hazardous waste regulations are forcing simultaneous replacement of illumination subsystems across installed bases. Service organizations lack trained field engineers to execute retrofit programs at required velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Microscopes Market |
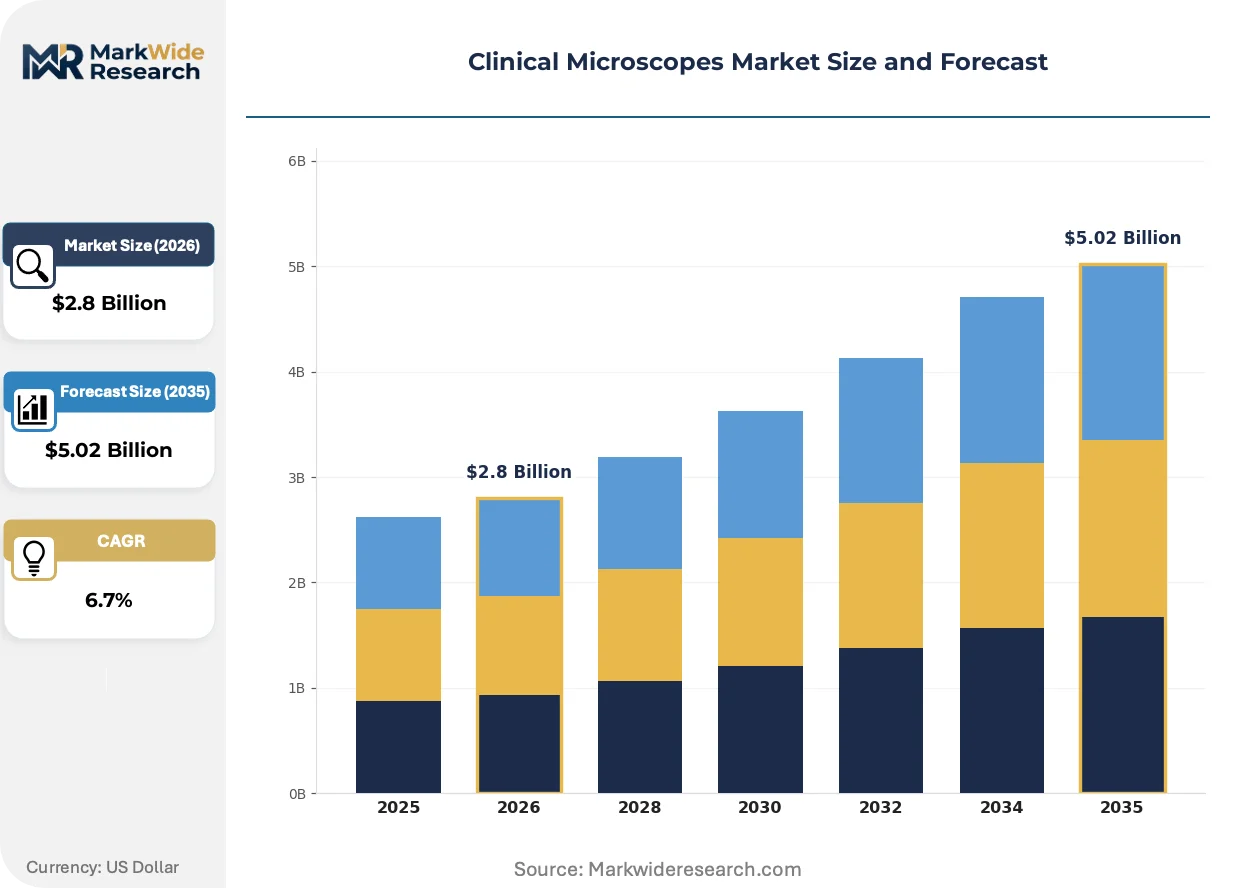
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compound Microscopes, Digital Microscopes, Stereo Microscopes, Confocal Microscopes End User: Hospitals, Pathology Labs, Research Institutions, Diagnostic Centers Application: Hematology, Histology, Cytology, Microbiology Technology: Optical, Electron, Fluorescence, Phase Contrast |
| Companies Covered | Nikon Corporation, Keyence Corporation, Leica Microsystems, Motic, Meiji Techno, Olympus Corporation, Thermo Fisher Scientific, Accu-Scope, Carl Zeiss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Microscopes Market Emerging Trajectories
Computational microscopy is merging optical hardware with algorithmic image reconstruction, compressing the tradeoff between resolution depth and field of view. This convergence is redrawing competitive boundaries between traditional optics manufacturers and software-native entrants.
Confocal laser scanning microscopy is automating z-stack acquisition and deconvolution processing in oncology pathology workflows. Major cancer centers in the United States are standardizing on these platforms for three-dimensional tissue reconstruction. The technology is automating previously manual focal plane selection, reducing per-slide technician time and enabling overnight batch processing.
The EPA's mercury lamp disposal regulations under the Resource Conservation and Recovery Act are mandating LED retrofit or full system replacement by 2027. Equipment manufacturers are redesigning fluorescence illuminator modules to accommodate solid-state emitters with equivalent spectral output. Academic medical centers with large installed bases face the steepest compliance costs and are negotiating volume transition contracts with suppliers.
Consolidated purchasing through group purchasing organizations is concentrating buying power among multi-hospital systems in the United States. Independent pathology practices are losing price negotiation leverage and are migrating toward cooperative procurement networks. This pattern is most pronounced in Texas and Florida, where private equity-backed diagnostic rollups dominate regional markets.
Clinical Microscopes Market Segmentation
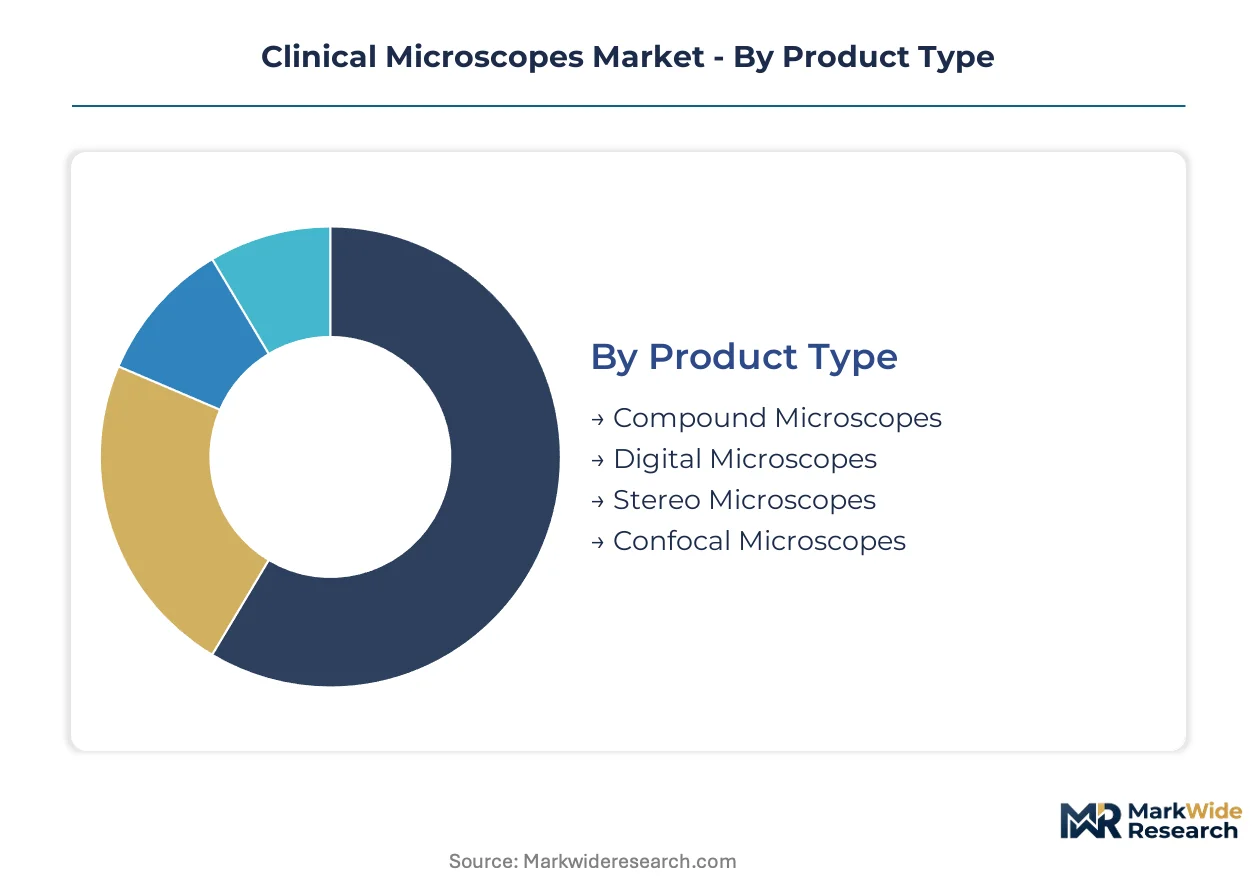
Clinical microscope procurement decisions fragment across distinct technical specifications, end-use workflows, and diagnostic protocols. Each segmentation dimension captures different margin pools and replacement cycle dynamics that shape supplier positioning.
Product Type:
Standalone benchtop systems dominate pathology infrastructure, while embedded modules integrate into automated laboratory workflows and telepathology networks.
- Compound Microscopes:Multi-lens optical systems with rotating nosepieces housing 4-6 objective lenses deliver magnification ranges from 40x to 1000x. Hospital laboratories in Germany and the United States deploy these as foundational diagnostic workstations for routine tissue examination. Demand concentrates in high-throughput screening environments where technician familiarity and maintenance simplicity outweigh advanced feature requirements.
- Digital Microscopes:Integrated camera sensors and network connectivity enable whole-slide image capture for remote consultation and AI-assisted analysis. Diagnostic centers in the Netherlands and France are prioritizing these platforms to satisfy telemedicine infrastructure mandates and reduce specialist travel burdens between regional facilities.
- Stereo Microscopes:Lower-magnification binocular systems serve surgical pathology and gross specimen examination. Research institutions utilize these for dissection and tissue preparation workflows preceding detailed microscopic analysis.
- Confocal Microscopes:Laser scanning architectures with pinhole apertures eliminate out-of-focus light for three-dimensional tissue reconstruction. Major cancer centers in the United States standardize on these platforms for oncology pathology requiring subcellular resolution.
Volume placements concentrate in compound microscopes; the faster expansion belongs to digital microscopes.
End User:
Capital allocation patterns diverge between institutions with diagnostic revenue models versus those dependent on grant funding or fixed reimbursement schedules.
- Hospitals:Integrated health systems with captive pathology departments prioritize interoperability with existing laboratory information systems and electronic health record platforms. Procurement committees emphasize FDA 510(k) clearance status and vendor service network density.
- Pathology Labs:Independent reference laboratories and hospital-affiliated units drive fluorescence microscopy adoption for immunohistochemistry and specialized staining protocols. These facilities face acute technician recruitment challenges for advanced imaging modalities.
- Research Institutions:Academic medical centers and university laboratories demand configurable systems with open software architectures for custom algorithm development. Funding cycles from NIH and European Research Council grants dictate replacement timing rather than regulatory compliance deadlines.
- Diagnostic Centers:High-throughput screening facilities in India's tier-1 cities and Brazil's São Paulo corridor capture disproportionate margin pools through volume contracts with national health programs. These operators prioritize throughput metrics and reagent cost optimization over optical performance specifications.
Diagnostic centers generate the steepest unit economics; research institutions impose the longest sales cycles.
Application:
Workflow standardization varies significantly across diagnostic disciplines, with some applications demanding quantitative image analysis while others rely on qualitative morphological assessment.
- Hematology:Blood cell morphology examination requires consistent illumination calibration and standardized magnification protocols. Automated cell counters have displaced manual microscopy in high-volume screening, though confirmatory smear review sustains demand for skilled technician workstations.
- Histology:Thin-section tissue analysis from biopsies and surgical specimens represents the foundational workload of hospital pathology departments. Paraffin embedding and microtomy preparation steps precede microscopic examination, creating integrated workflow dependencies.
- Cytology:Pap smear and liquid-based cytology screening for cervical cancer detection drives standardized platform requirements. National screening programs in the United Kingdom and Australia specify equipment configurations to ensure inter-laboratory consistency.
- Microbiology:Culture examination and Gram staining protocols demand oil immersion objectives and consistent heat-fixed specimen preparation. Clinical laboratories face regulatory pressure to reduce turnaround times for bloodstream infection diagnosis.
Histology commands the largest installed base; cytology faces the strongest automation displacement pressure.
Technology:
Illumination source selection and image formation physics determine capital cost tiers and operational expenditure profiles across technology categories.
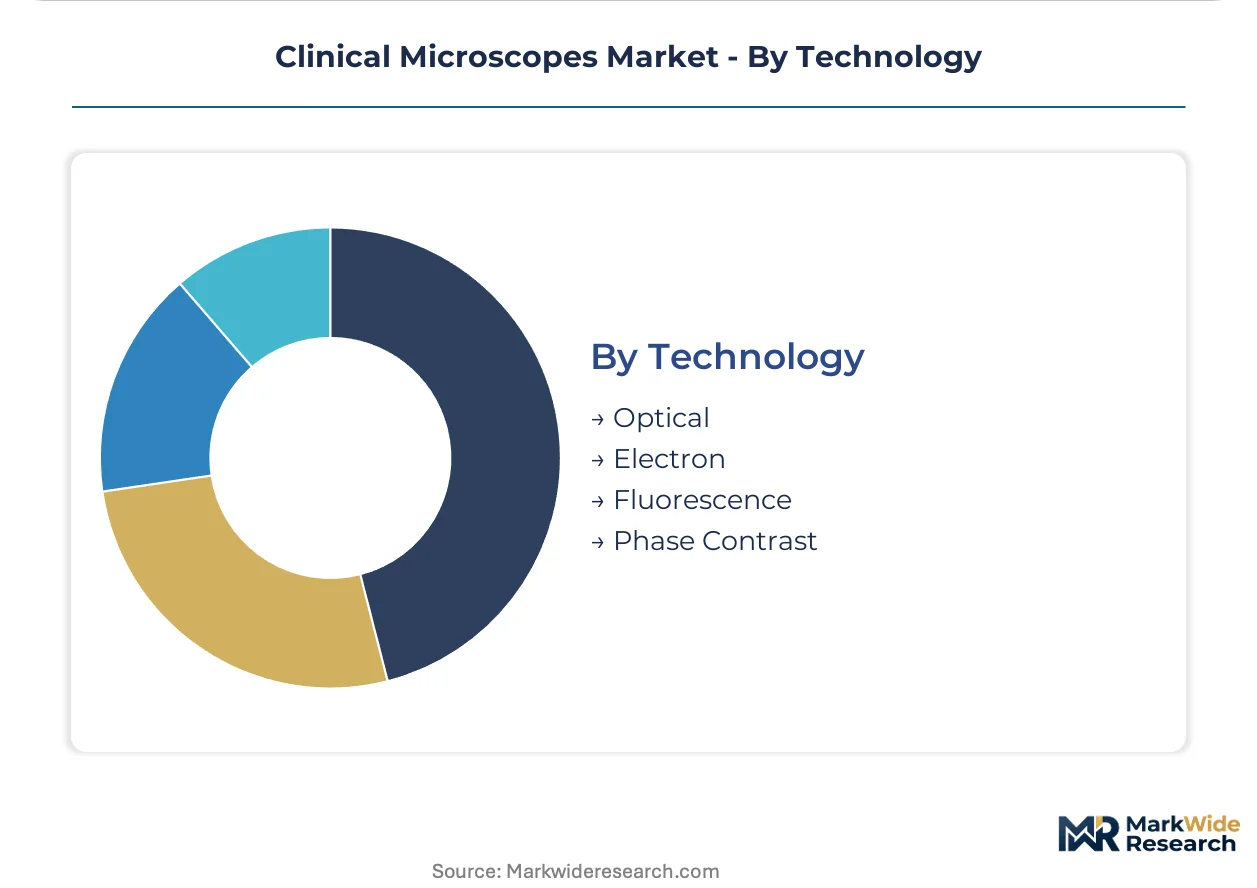
- Optical:Conventional brightfield microscopy using transmitted visible light remains the default configuration for routine diagnostic work. LED retrofit modules are displacing halogen illumination to satisfy EPA hazardous waste regulations and reduce energy consumption.
- Electron:Transmission and scanning electron microscopes serve ultrastructural pathology and research applications requiring nanometer-scale resolution. These systems demand specialized facilities with vibration isolation and electromagnetic shielding that constrain placement options.
- Fluorescence:Mercury vapor and LED-excited fluorophore visualization enables immunofluorescence and FISH protocols for oncology and infectious disease diagnosis. EU MDR compliance deadlines are accelerating replacement of legacy mercury lamp systems ahead of regulatory phase-out dates.
- Phase Contrast:Unstained live cell observation using refractive index differences serves microbiology and cell culture applications. Research laboratories utilize these systems for time-lapse imaging where chemical fixation would compromise specimen viability.
Optical technology maintains volume dominance; fluorescence platforms climb the fastest on diagnostic protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wetzlar and Jena anchor global precision optics manufacturing for clinical microscopy, with Germany's central corridor supplying specialized objective lenses to equipment assemblers worldwide. This geographic concentration shapes procurement lead times and certification workflows across three continents.
United States
Major cancer centers in Texas and Florida are standardizing on confocal laser scanning platforms for three-dimensional tissue reconstruction. FDA 510(k) clearance pathways govern market access for fluorescence imaging systems. The EPA's Resource Conservation and Recovery Act mandates mercury lamp phase-out by 2027, forcing academic medical centers in Boston and California to negotiate volume transition contracts with suppliers.
Germany
Pathology labs in Bavaria and North Rhine-Westphalia face compressed procurement cycles ahead of EU MDR certification deadlines. The Medical Device Regulation's conformity assessment requirements are accelerating replacement of legacy equipment. The Wetzlar-Jena corridor maintains captive production of specialized objective lenses, with any disruption propagating through global equipment lead times.
India
Diagnostic centers in Maharashtra and Karnataka are expanding high-throughput screening capacity for national health program contracts. The PLI scheme for medical device manufacturing is attracting contract assembly investment to bypass import duty structures. Domestic production clusters in Gujarat and Tamil Nadu are scaling to serve tier-1 city demand for compound and digital microscope platforms.
Netherlands
Healthcare systems are deploying remote diagnostic infrastructure requiring digital microscope compatibility for telepathology networks. EU MDR compliance deadlines are front-loading capital expenditure decisions before certification windows close. Amsterdam and Rotterdam medical centers are prioritizing whole-slide imaging systems to reduce specialist travel burdens between regional facilities.
Japan
Research institutions in the Kanto and Kansai regions demand configurable systems with open software architectures for custom algorithm development. PMDA regulatory frameworks align with international standards for optical diagnostic equipment. Tokyo and Osaka academic medical centers are integrating computational microscopy platforms that merge optical hardware with algorithmic image reconstruction.
Clinical Microscopes Market Vendor Landscape
The competitive structure tilts toward heritage optics specialists with century-old precision engineering capabilities. The vendor base separates into three tiers: integrated conglomerates with diversified life science portfolios, pure-play microscopy specialists with captive lens manufacturing, and emerging digital-native entrants leveraging computational imaging software. Consolidation pressure is intensifying through M&A activity targeting fluorescence imaging capabilities and strategic partnerships for AI-enabled image analysis modules.
Among heritage optics specialists, Nikon Corporation and Leica Microsystems exemplify the premium-tier positioning sustained through backward integration into precision glass engineering. Olympus Corporation occupies a position bridging optical heritage with digital pathology platform development. These three anchors represent divergent strategic responses to the convergence of hardware and software in diagnostic workflows.
| Leading Market Players |
|---|
| Nikon Corporation |
| Keyence Corporation |
| Leica Microsystems |
| Motic |
| Meiji Techno |
| Olympus Corporation |
| Thermo Fisher Scientific |
| Accu-Scope |
| Carl Zeiss |
| Others |
Supply Flow & Price Mechanics
EU MDR certification deadlines are compressing procurement timelines and forcing diagnostic centers to front-load capital expenditure decisions, which concentrates buying power among multi-hospital systems and amplifies price negotiation leverage for volume contracts. This demand-side consolidation is reshaping how equipment manufacturers structure pricing tiers and supply allocation priorities across regional markets.
Pricing Analysis
Throughput-based pricing anchors equipment valuation, with diagnostic centers in India and Brazil capturing steeper discounts through high-volume screening contracts than research institutions purchasing single units. Three-tier pricing structure across premium, standard, and economy levels separates MDR-compliant fluorescence systems from legacy brightfield configurations and entry-level compound microscopes. Cost compression in the mid-tier is intensifying because LED retrofit modules are commoditizing illumination subsystems. Independent pathology practices exhibit the highest price sensitivity as GPOs consolidate purchasing power among integrated health systems.
Supply Chain Analysis
Freight costs for specialized objective lenses from Germany's Wetzlar-Jena corridor represent a material landed cost component for equipment assemblers in India and the United States. Supply concentrates in Germany for precision glass engineering, Japan for optical coatings, and China for electronic camera modules. The supply chain draws from rare-earth elements for fluorescence filter coatings, high-grade borosilicate glass for objective lens substrates, and semiconductor sensors for digital imaging. Single-source vulnerability in Germany's optics cluster propagates through global equipment lead times. Distribution runs through authorized dealer networks serving hospital procurement committees and direct contracts with national health programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR conformity assessment timeline creates a cost-of-compliance barrier that favors heritage optics specialists with established notified body relationships and captive certification resources, effectively moating premium-tier positioning against emerging entrants lacking regulatory infrastructure.
For Market Incumbents: Deepen backward integration into precision glass engineering to secure captive supply of specialized objective lenses against supply concentration risk in Germany's Wetzlar-Jena corridor. Expand service organization capacity for LED retrofit programs ahead of EPA mercury lamp phase-out deadlines. Software-native entrants with computational imaging platforms represent the primary substitution threat requiring defensive R&D investment in AI-enabled image analysis modules. For New Entrants and Emerging Players: Capture white-space opportunity in India's diagnostic center buildout by establishing contract assembly operations under the PLI scheme to bypass import duty structures. Target mid-sized pathology chains in Texas and Florida with subscription service models that shift capital expenditure to operational budgets. Partner with telepathology network operators for pull-through demand of whole-slide imaging systems. For Investors and Strategic Acquirers: The window for entry favors heritage optics specialists with established notified body relationships and captive lens manufacturing capabilities. Long-term viability hinges on convergence between hardware and software in diagnostic workflows. Target acquisition archetype: pure-play microscopy specialists with fluorescence imaging capabilities and FDA 510(k) clearance portfolios. Monitor AI-enabled image analysis regulatory classification shifts as inflection indicator for automated diagnostic workflow reimbursement frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Investment | Accelerates product launch timelines by securing notified body capacity ahead of competitor bottlenecks. |
| LED Illumination Module Development | Eliminates hazardous waste disposal costs and satisfies EPA Resource Conservation and Recovery Act mandates. |
| Telepathology Network Partnership | Creates pull-through demand for whole-slide imaging systems in Netherlands and German healthcare infrastructure. |
| AI-Enabled Image Analysis Integration | Opens software licensing revenue streams beyond hardware-only sales in cytological screening workflows. |
| India PLI Scheme Manufacturing Localization | Bypasses import duty structures inflating landed costs for fully-built systems in Maharashtra diagnostic centers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital procurement managers, pathology lab directors, biomedical engineers, and GPO contracts managers. FDA 510(k) databases, EU MDR notified body registers, EPA hazardous waste compliance records, and hospital procurement databases furnished validation benchmarks. Bottom-up equipment shipment tracking and top-down healthcare capital expenditure surveys were triangulated against import-export statistics.
Granularity-level modeling captured product type, end user, application, and technology dimensions at the country level across the analysis window. CAGRs were derived from weighted average of historical trajectory and forward-looking protocol adoption curves. Forecast inputs incorporated telepathology network deployment timelines, EU MDR certification deadline phasing, and LED illumination retrofit velocity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AI-enabled diagnostic workflow reimbursement decisions and precision optics supply chain disruption scenarios. Forecasts reflect documented assumptions about regulatory compliance timelines and technology substitution rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Cryopreservation Systems Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
Medical Computer Carts Market
Medical Equipment
Medical Pediatric Bed Market
Medical Equipment
Medical Oxygen Systems Market
Medical Equipment
Contact Type Liquid Handling Workstation Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
North America Medical Carts Market
Medical Equipment
Medical Whirlpool Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Terminal Sterilization Market
Medical Equipment
Autoclaves Market
Medical Equipment
Medical Thawing Systems Market
Medical Equipment
Equine Operating Tables Market
Medical Equipment
Global Medical Vacuum System Market