
 North America Radiotherapy Market | 2026-2036
North America Radiotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Radiotherapy Market Insights
Medical physicist staffing is rotating toward proton therapy and MR-linac platforms, creating a credential bottleneck that slows clinic expansion in the United States and Canada. Varian Medical Systems Inc. dominates linear accelerator installations across major hospital networks. Elekta AB leverages its Unity MR-linac platform to compete in the high-margin adaptive therapy segment. Siemens Healthineers AG anchors its position through integrated imaging-radiotherapy workflows.
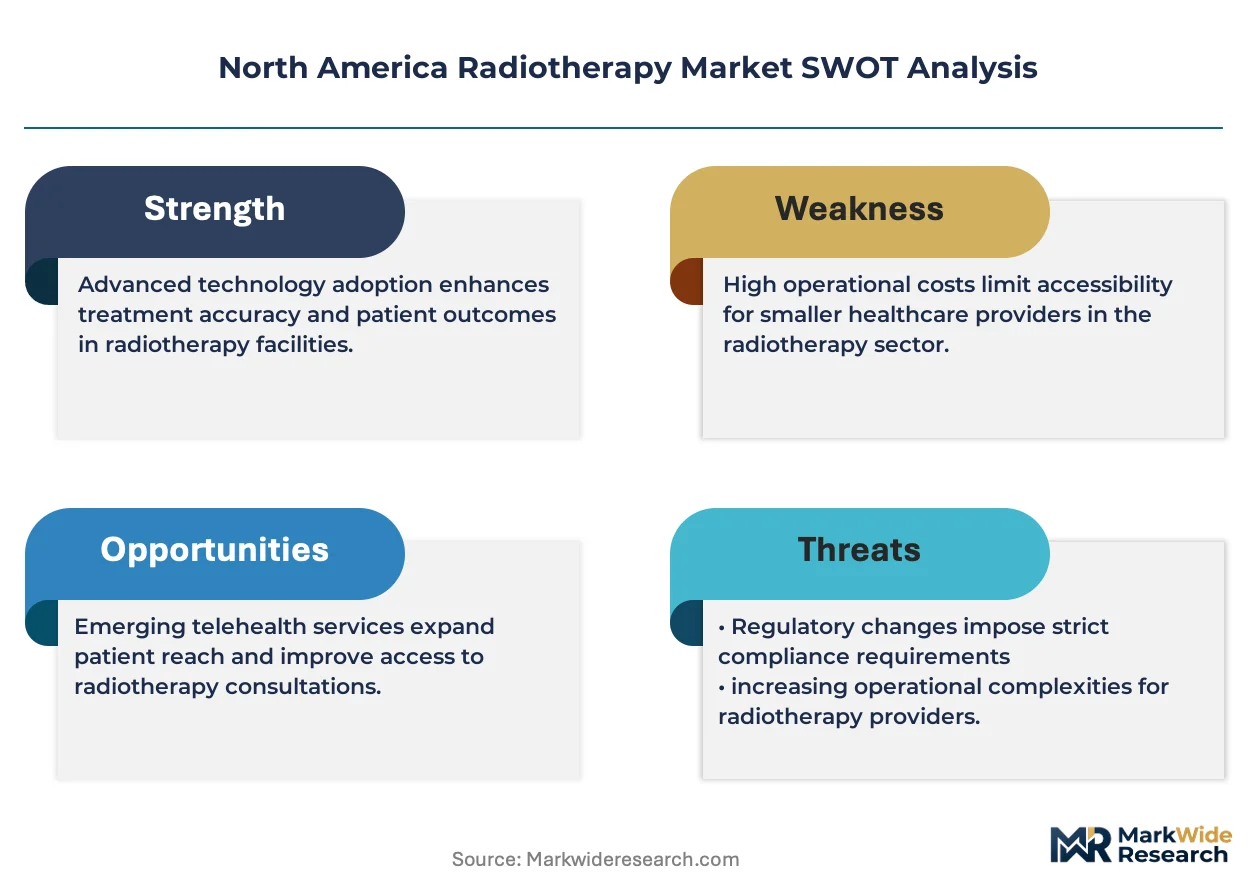
Radiotherapy deploys ionizing radiation—photon, proton, or electron beams calibrated to 6-15 MV energies—to destroy malignant cells while sparing healthy tissue through beam shaping and fractionation protocols. Its primary purpose is curative and palliative cancer treatment delivered in 20-40 fractional sessions. External Beam Therapy occupies the largest installed base across North American hospitals, though Proton Beam Therapy captures disproportionate margin pools due to capital intensity and limited site availability. Intensity-Modulated Radiation Therapy sustains volume leadership among photon modalities, while Stereotactic Radio Surgery grows fastest in specialized clinics treating brain and spinal lesions.
FDA 510(k) and PMA pathways govern device clearance, while NRC regulations control radioactive source handling and shielding standards for cobalt and cesium-based systems. State-level certificate-of-need laws in New York, Illinois, and California constrain linear accelerator proliferation, protecting incumbent utilization rates. Stakeholders must monitor CMS reimbursement rate negotiations for proton therapy, as coverage determinations will dictate capital commitment timelines for health system executives.
Market Dynamics
Proton beam therapy infrastructure expansion is compressing the competitive window for photon-based systems across the United States and Canada, as health system capital committees prioritize single-fraction precision capabilities over conventional linac fleets.
Growth Catalysts
- Adaptive radiotherapy software:FDA 510(k) clearance pathways for AI-driven treatment planning are shortening deployment cycles at academic medical centers in the northeastern United States.
- Certificate-of-need reform:Legislative pressure in Illinois and California is loosening restrictions on linear accelerator proliferation, enabling network expansion.
- MR-linac platform convergence:Real-time magnetic resonance guidance during beam delivery is attracting radiation oncology departments seeking margin reduction.
Market Restraints
- Medical physicist scarcity:Proton therapy and MR-linac credentialing requirements are creating a staffing bottleneck that constrains clinic expansion timelines.
- Capital intensity concentration:Proton therapy centers require $150-200 million upfront investment, limiting deployment to major metropolitan hospital networks.
- NRC radioactive source regulations:Stringent shielding and handling protocols for cobalt-60 and cesium-137 systems are extending decommissioning timelines for legacy equipment.
Strategic Opportunities
- Southern Ontario referral networks:Academic medical centers in Toronto and Hamilton are anchoring proton therapy catchment zones that extend into upstate New York and Michigan.
- CMS proton therapy coverage:National coverage determination negotiations for pediatric and central nervous system indications are creating reimbursement tailwinds.
- Artificial intelligence integration:Machine learning-based contouring and dose optimization are converging with cloud-based treatment planning to enable decentralized quality assurance.
Industry Challenges
- Fractionation protocol standardization:Variability in hypofractionation regimens across proton and photon platforms complicates multi-site clinical trial enrollment.
- Legacy linac integration:Retrofitting Varian and Elekta installed bases with adaptive software modules requires substantial downtime and retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Radiotherapy Market |
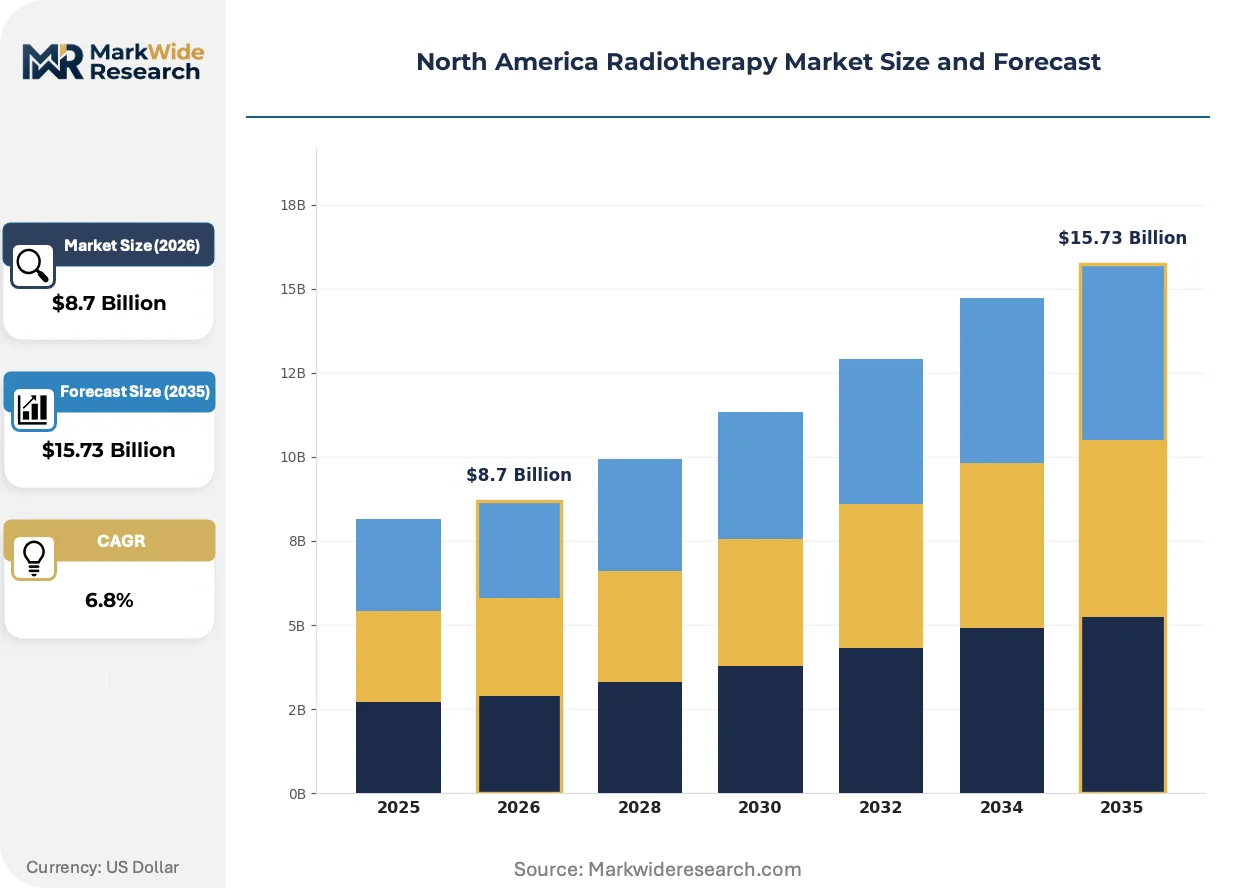
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
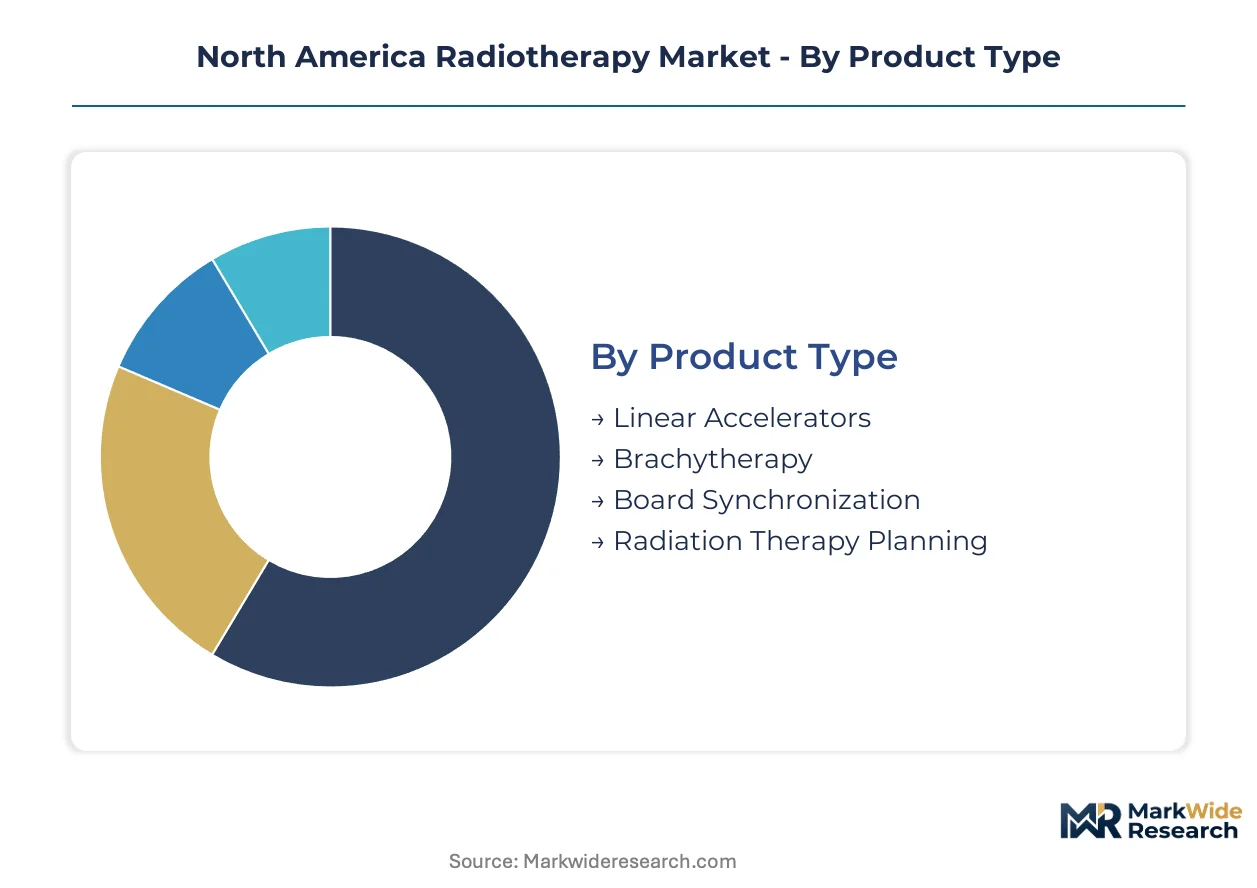
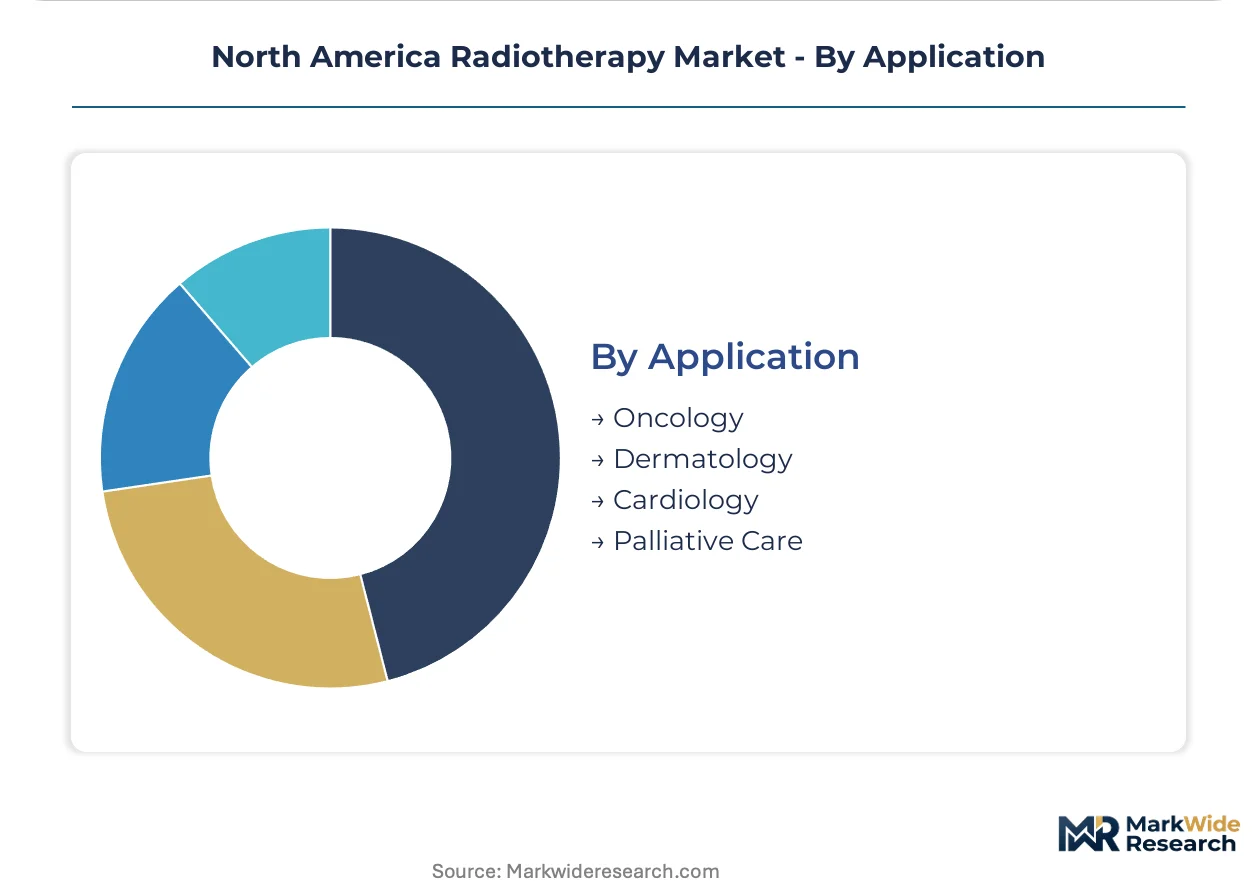
| Segmentation | Product Type: Linear Accelerators, Brachytherapy, Board Synchronization, Radiation Therapy Planning Technology: External Beam Therapy, Intensity-Modulated Radiation Therapy, Stereotactic Radio Surgery, Proton Beam Therapy End User: Hospitals, Oncology Centers, Research Institutions, Specialized Clinics Application: Oncology, Dermatology, Cardiology, Palliative Care |
| Companies Covered | Siemens Healthineers AG, Elekta AB, Accuray Incorporated, Varian Medical Systems Inc., IBA Worldwide, ViewRay Technologies, Inc., GE Healthcare, Becton Dickinson and Co., Canon Medical Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Radiotherapy Market Trends and Innovations
Real-time imaging guidance and automated treatment adaptation are collapsing the latency between simulation and beam delivery, compressing patient throughput timelines while elevating precision requirements for clinical staff.
Flash radiotherapy is decomposing conventional fractionation paradigms by delivering ultra-high dose rates in single or few-fraction regimens. Research consortia at MD Anderson and Massachusetts General Hospital are validating tissue-sparing mechanisms in preclinical models. This modality is decomposing the economic logic of 30-40 session treatment courses that have sustained photon linac utilization rates for decades.
FDA breakthrough device designation pathways for adaptive radiotherapy software are accelerating premarket review timelines for algorithms that adjust treatment plans between fractions. This regulatory flexibility is compressing time-to-revenue for developers while elevating post-market surveillance obligations. The PMA supplement process for hardware-software integration is most affected, with vendors restructuring quality management systems to accommodate iterative deployment.
Health system procurement committees are consolidating vendor relationships through enterprise-wide linear accelerator standardization. Independent community oncology practices in Texas and Florida are losing negotiating leverage as regional hospital networks centralize purchasing through shared services organizations. This concentration is most visible in the southeastern United States, where HCA and Tenet facilities are enforcing single-platform policies across radiation oncology departments.
North America Radiotherapy Market Segmentation
Radiotherapy equipment procurement channels diverge sharply across product categories, with capital-intensive proton systems flowing through academic medical center committees while linear accelerators penetrate community hospital networks through group purchasing organizations.
Product Type:
Capital equipment and software modules follow distinct distribution pathways, with hardware sales concentrated through direct manufacturer relationships and planning software increasingly delivered via cloud-based subscription models.
- Linear Accelerators:Photon delivery systems generating 6-15 MV beams constitute the dominant installed base across hospital radiation oncology departments. Demand concentrates in the northeastern United States and southern Ontario where certificate-of-need restrictions have historically constrained proliferation, protecting incumbent utilization rates while creating pent-up replacement demand.
- Brachytherapy:Radioactive source-based internal radiation systems utilizing iridium-192 and cesium-137 isotopes serve gynecologic and prostate indications. Deployment clusters in comprehensive cancer centers across Texas and Florida where high patient volumes justify dedicated suites and specialized physics staffing.
- Board Synchronization:Immobilization and respiratory tracking devices enable sub-millimeter precision during fraction delivery. Adoption accelerates in stereotactic programs at Massachusetts General Hospital and MD Anderson where motion management is non-negotiable.
- Radiation Therapy Planning:Software platforms for dose calculation and beam optimization are migrating to cloud architectures with AI-driven contouring modules. FDA 510(k) clearance pathways for adaptive algorithms are shortening sales cycles at academic centers.
Linear accelerators dominate installed base. Radiation therapy planning software is where expansion concentrates.
Technology:
Clinical adoption patterns separate established photon modalities from emerging precision platforms, with reimbursement differentials determining where health systems allocate capital committee attention.
- External Beam Therapy:Conventional photon delivery from cobalt-60 units and basic linear accelerators retains volume leadership across community oncology practices. NRC radioactive source regulations and state-level certificate-of-need laws in Illinois and California constrain fleet expansion, extending legacy equipment lifecycles.
- Intensity-Modulated Radiation Therapy:Computer-controlled multileaf collimator systems modulate beam intensity to conform dose distributions to tumor geometry. IMRT sustains treatment volume leadership among photon modalities as community hospitals prioritize proven reimbursement pathways over unproven proton economics.
- Stereotactic Radio Surgery:High-dose single-fraction or hypofractionated delivery to cranial and spinal lesions demands sub-millimeter targeting precision. Growth accelerates in specialized neurosurgery clinics treating brain metastases across the northeastern United States.
- Proton Beam Therapy:Charged particle systems exploiting the Bragg peak effect spare distal tissue beyond the target volume. Capital intensity of $150-200 million per center limits deployment to major metropolitan hospital networks in Houston, Boston, and Toronto.
Intensity-modulated radiation therapy commands treatment volume leadership. Proton beam therapy is climbing the fastest as academic medical centers compete for referral dominance.
End User:
Procurement authority and reimbursement sophistication create distinct customer tiers, with integrated delivery networks centralizing purchasing while independent practices lose negotiating leverage.
- Hospitals:Integrated health systems with radiation oncology departments embedded in comprehensive cancer centers anchor proton therapy and MR-linac adoption. HCA and Tenet facilities in the southeastern United States enforce single-platform standardization policies across their networks.
- Oncology Centers:Freestanding community practices concentrate photon linac utilization in Texas and Florida where population growth outpaces hospital capacity. Consolidation into regional networks is eroding independent negotiating power.
- Research Institutions:Academic medical centers at MD Anderson, Memorial Sloan Kettering, and Massachusetts General Hospital validate flash radiotherapy and adaptive software in preclinical and early clinical protocols.
- Specialized Clinics:Brain and spine-focused practices deploy stereotactic platforms for metastasis and functional neurosurgery. Credentialing bottlenecks for medical physicists constrain expansion timelines.
Hospitals anchor capital equipment procurement. Specialized clinics are gaining share fastest as precision indications fragment the treatment landscape.
Application:
Clinical indication breadth determines equipment utilization rates and reimbursement stability, with oncology commanding dedicated capital while other applications share multi-purpose systems.
- Oncology:Curative and palliative cancer treatment across solid tumors and hematologic malignancies consumes the overwhelming majority of beam time. CMS reimbursement rate negotiations for proton therapy indications dictate capital commitment timelines for health system executives.
- Dermatology:Superficial electron and orthovoltage applications for non-melanoma skin lesions operate at the margins of radiation oncology department schedules. Dermatology practices in sun-belt states deploy dedicated superficial units.
- Cardiology:Emerging ventricular tachycardia ablation and coronary restenosis prevention applications remain investigational, with cardiac radiosurgery programs limited to Cleveland Clinic and a handful of academic centers.
- Palliative Care:Pain and symptom management for bone metastases and superior vena cava syndrome sustains linac throughput during curative case lulls. Community hospitals rely on palliative volume to justify equipment depreciation.
Oncology dominates installed base utilization. Cardiology represents the steepest expansion trajectory as electrophysiology-radiation oncology collaboration protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways anchor equipment deployment velocity across the United States, while Health Canada regulatory timelines shape adoption cadence in Canadian provinces. State-level certificate-of-need laws in New York, Illinois, and California create sub-regional friction that fragments procurement patterns.
United States
Academic medical centers in Houston, Boston, and Philadelphia anchor proton therapy capital commitments exceeding $150 million per facility. CMS reimbursement rate negotiations for pediatric and central nervous system indications dictate health system executive commitment timelines. The northeastern corridor from Massachusetts to Maryland concentrates MR-linac adoption where certificate-of-need restrictions have historically suppressed linear accelerator proliferation.
Canada
Health Canada and the Canadian Nuclear Safety Commission govern radioactive source handling and shielding standards for cobalt-based systems. Southern Ontario referral networks centered on Toronto and Hamilton extend proton therapy catchment zones into upstate New York and Michigan. Provincial health authorities in Quebec and British Columbia are evaluating MR-linac procurement against existing photon fleet utilization rates.
Mexico
The Federal Commission for the Protection against Sanitary Risk (COFEPRIS) regulates medical device importation and clinical trial protocols for adaptive radiotherapy software. Private hospital networks in Mexico City and Monterrey concentrate linear accelerator installations serving medical tourism flows from the United States. Northern border states are integrating cross-border referral pathways with Texas oncology centers.
North America Radiotherapy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North America radiotherapy equipment landscape. Siemens Healthineers AG, Varian Medical Systems Inc., and Elekta AB dominate linear accelerator and integrated imaging-workflow installations through direct hospital network relationships. Specialist vendors concentrate in proton beam therapy gantries, MR-linac platforms, and adaptive planning software modules. Competitive dynamics center on enterprise-wide standardization mandates from integrated delivery networks and FDA 510(k) clearance velocity for AI-driven treatment planning algorithms.
Among Germany-based diversified health technology conglomerates, Siemens Healthineers AG exemplifies the integrated imaging-radiotherapy workflow archetype. Swedish precision therapy specialist Elekta AB occupies a position within the MR-linac and adaptive therapy segment. California-based Varian Medical Systems Inc. anchors the linear accelerator installed base tier across major United States hospital networks.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Elekta AB |
| Accuray Incorporated |
| Varian Medical Systems Inc. |
| IBA Worldwide |
| ViewRay Technologies, Inc. |
| GE Healthcare |
| Becton Dickinson and Co. |
| Canon Medical Systems Corporation |
| Others |
Pricing and Supply Chain Analysis
Capital intensity at proton therapy centers creates scale thresholds that concentrate supply among three integrated manufacturers while elevating price floors for precision platforms above commodity photon systems. This scale dynamic compresses margins for mid-tier linear accelerator vendors as hospital networks consolidate purchasing through shared services organizations across the southeastern United States.
Pricing Analysis
Geographic price spreads separate northeastern academic medical centers paying premium rates for MR-linac platforms from community hospitals in Texas and Florida negotiating standard-tier photon system bundles. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity, with FDA 510(k) clearance tier commanding 15-20% premiums over CE-marked equivalents. Pricing pressure stems from CMS reimbursement uncertainty for proton therapy indications, eroding capital committee confidence. Independent oncology practices exhibit highest price sensitivity, while integrated delivery networks leverage volume commitments for preferential terms.
Supply Chain Analysis
Isotope supply chokepoints for cobalt-60 and cesium-137 sources tether North American brachytherapy deployment to Canadian and South African reactor schedules. Superconducting magnet fabrication for proton gantries draws from Germany and Japan, while multileaf collimator assemblies source from Switzerland and the United States. Tariff exposure on Chinese-sourced rare earth elements for permanent magnet linac components creates margin vulnerability. Distribution runs through direct manufacturer relationships for capital equipment, with software modules increasingly delivered via cloud subscription.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as HCA and Tenet enforce single-platform standardization across radiation oncology departments, fragmenting independent practice negotiating leverage and reshaping procurement dynamics.
For Market Incumbents: Compound installed base advantages by retrofitting legacy Varian and Elekta fleets with adaptive software modules, locking in switching costs before proton therapy margins compress. Accelerate FDA 510(k) clearance velocity for AI-driven contouring algorithms to preempt emerging software entrants. Prioritize vertical integration into medical physicist training pipelines to alleviate credential bottlenecks constraining clinic expansion timelines. For New Entrants and Emerging Players: Differentiate on flash radiotherapy preclinical validation, targeting research institution partnerships at MD Anderson and Massachusetts General Hospital as credibility anchors. Penetrate the southern Ontario referral network where proton therapy catchment zones extend underserved upstate New York demand. Pursue cloud-native treatment planning software with subscription pricing to bypass capital equipment procurement cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors adaptive software specialists over hardware-dependent proton therapy developers as fractionation protocols shift toward ultra-high dose rate regimens. Five-to-ten year viability hinges on reimbursement tailwinds for pediatric and central nervous system indications. Monitor CMS national coverage determination negotiations as the decisive inflection signal for capital commitment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Proton Therapy Center Partnership | Academic medical center alliances in Houston and Boston anchor referral dominance for pediatric indications. |
| Adaptive Software FDA Submission | 510(k) clearance for AI-driven replanning algorithms compresses time-to-revenue at northeastern hospitals. |
| Medical Physicist Training Pipeline | Credential bottlenecks for proton and MR-linac platforms constrain competitor expansion timelines. |
| Cloud Treatment Planning Migration | Subscription architectures bypass hospital capital committee approval cycles for software procurement. |
| Certificate-of-Need Reform Engagement | Legislative pressure in Illinois and California unlocks pent-up linear accelerator replacement demand. |
Research Methodology
Desk research of FDA 510(k) and PMA filing databases, CMS reimbursement determinations, and state certificate-of-need statutes preceded structured interviews with radiation oncology department chairs, medical physicists, hospital procurement officers, and GPO contracts managers. Secondary validation drew from NRC regulatory filings, Health Canada device approvals, and proton therapy consortium research publications. Bottom-up equipment installation tracking and top-down health system capital expenditure analysis were triangulated against vendor shipment disclosures.
Variance decomposition across technology adoption curves, reimbursement policy scenarios, and regulatory clearance timelines shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, technology modality, end-user category, and application indication, with geographic regulatory clusters treated as distinct adoption environments. CAGRs were derived from installed base replacement cycles and penetration rate assumptions for emerging platforms, incorporating medical physicist supply constraints as a capacity ceiling input.
The analysis sits within stated boundaries; outcomes outside sustained CMS proton therapy coverage or accelerated FDA software clearance pathways would require recalibration. Forecasts reflect documented assumptions regarding health system capital commitment behavior and regulatory timeline stability. Practitioners should keep alternative scenarios live as reimbursement negotiations and certificate-of-need legislative developments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Asia-Pacific Nuclear Medicine Equipment Market
Medical Equipment
Mercury Thermometer Market
Medical Equipment
US Durable Medical Equipment Market
Medical Equipment
Thermal Cycler Market
Medical Equipment
MRI Transport Market
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
Autoclaves Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Global Bone Densitometer Market
Medical Equipment
Dialysis Equipment Market
Medical Equipment
Faecal Extraction System Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Bench-Top Dental Autoclaves Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Animal Operating Table Market
Medical Equipment
Electrophysiology Equipment and Recording Systems Market